From Capture-Ready to Capture-Committed: Decarbonizing Natural Gas with CCS
Key Takeaways
- Data centers are driving surging demand for new, firm electricity supply, accelerating natural gas-fired power generation.
- Carbon capture and storage (CCS) offers a practical way to balance long-term climate commitments with the need for new electricity generation in the near term.
- New natural gas-fired power plants must be capture-committed, not just capture-ready, potentially delivering power in 18 months and decarbonized power 18-24 months later.
- Capture-committed plants integrate planning and finance for the CO₂ capture, transport, and storage value chain from the start.
- Relae believes early investment in engineering, infrastructure, and community engagement is essential to meet capture commitments.
A New Era of Electricity Demand and Climate Pressure
The US and much of the developed world are experiencing profound growth in electricity demand. Two main forces are driving this trend: (1) the push to electrify existing uses, such as vehicles and heating, to improve energy security, enhance system efficiency, and reduce air pollution; and (2) the growth of energy-intensive sectors like manufacturing, telecommunications, and AI data centers.
Among these drivers, AI is creating unique demands that catalyze specific investments in electric power generation. Astonishing AI data center buildout, led by a handful of large technology firms (sometimes called “hyperscalers”) and their utility and construction partners, is accelerating energy consumption. These firms prioritize speed. When asked for their top five criteria for bringing new AI infrastructure online, one executive responded: “Speed, speed, speed, cost, and carbon emissions.”
Data centers require reliable, always-on power (referred to as “firm power”). This differs from other use cases, such as residential or commercial, which do not need the same amount of power across all hours. While hyperscalers and their partners are investing in renewables, nuclear, and geothermal energy at a remarkable pace, renewable resources alone do not yet meet the exploding demand for firm power.
Natural Gas Provides Firm Power but Drives Emissions Higher
The mismatch between data center power needs and variable renewable generation is fueling a boom in natural gas-fired power generation. The pipeline of new natural gas-fired power plants is enormous. Plants under construction in 2025 would, by themselves, add roughly 25 million tonnes of greenhouse gases each year to the air and oceans. The full suite of plants in planning is at least 10 times larger. Existing gas plants are also being used more and staying online longer.
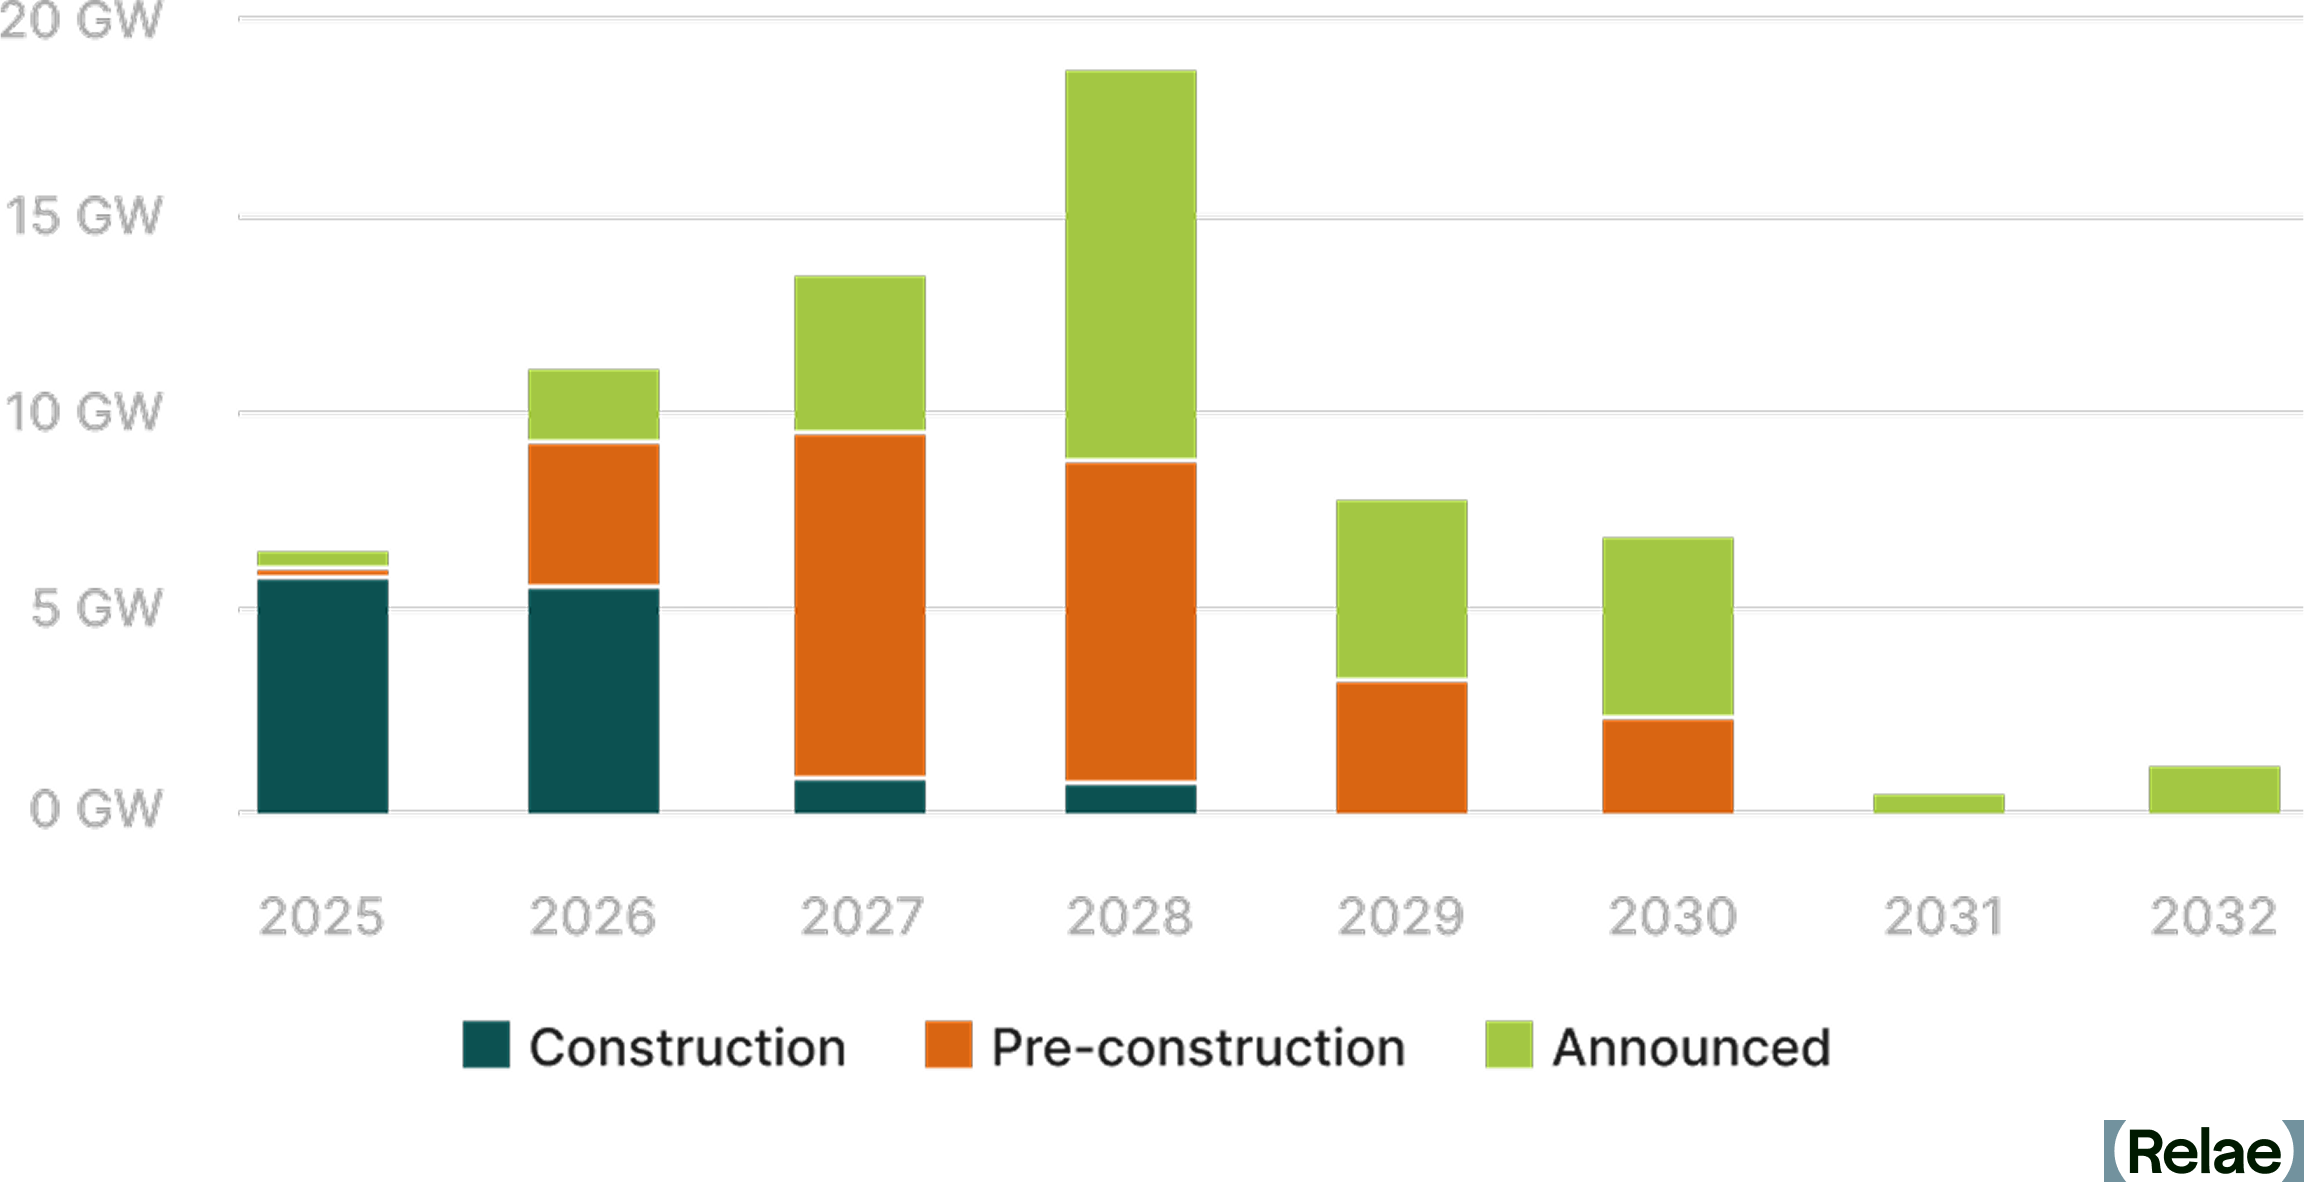
This rapid buildout is creating tension with corporate climate goals. Hyperscalers remain seriously committed to reducing emissions, but their ability to hit those targets is undermined by the need to procure new, large-scale electricity generation quickly.
Carbon Capture Aligns with Data Center Energy Demands
Carbon capture and storage is one way to bridge the gap. Data centers operate continuously and may have the ability to shift or curtail load. This demand profile suits the duty cycles of natural gas turbines and CCS facilities well. The potential to reduce direct emissions is profound: today’s CCS technology can capture 95% or more of CO₂ emissions at competitive costs in many markets.
This has led to a resurging interest in the concept of capture-ready gas power generation. New natural gas power plants can be built and brought online in 18 months. In a capture-ready plant, the developers integrate the necessary interfaces and reserve additional land, water, and energy to enable a carbon capture project to be built at a future date. In favorable locations, carbon capture can be added to a capture-ready plant in 18-24 months.
However, past experience shows that capture-ready plants rarely deliver. The ambition and commitment of the developers were contingent on policy and market signals that were either too small or never materialized. While the base plant may have made economic sense in terms of energy value for investment, it does not appear anyone was willing to pay the climate premium for CCS.
As David Hawkins of the Natural Resource Defense Council famously said, “If your plant is capture ready, my driveway is Ferrari ready.” To bring David’s humorous analogy back to the specifics here: don’t build a new driveway without at least a downpayment on the car.
How to Build Capture-Committed Power Plants for CCS
A better approach is building capture-committed plants, namely facilities that integrate CCS from the start. To be capture-committed, project developers must:
- Identify geologic storage for the many millions of metric tons of CO2 that these plants will produce each year over the next 20-30 years.
- Plan reliable CO₂ transportation from power generation to geologic storage by pipeline, rail, barge, or truck.
- Engage credible vendors of carbon capture technology that serve their needs and fit their goals.
- Fund front-end engineering design (FEED) studies.
- Arrange, or help to arrange, financing for the construction, commissioning, and operation of all necessary components in the CO₂ capture, transportation, and storage value chain.
- Ensure natural gas supply has near-zero fugitive methane emissions.
- Partner with local and frontline stakeholders to incorporate community impact into project planning, design, and financing.
Capture-committed plants send strong market signals. They help build the permitting pathways and develop the workforce, infrastructure, and community acceptance needed to avoid extra expense and delays. Done well, early commitments and investments will likely create repeatable models that reduce build times and costs.
A Path Toward Power That’s Clean Firm and Future-Ready
Eventually more carbon-free power in the form of renewables, nuclear, and geothermal energy will be deployed to serve national and international electric load growth for all types of electrification. Over time, these resources will likely displace natural gas. Until then, hundreds of millions of tons of CO₂ will be emitted each year unless commitments are made to take tangible action now.
Capture-committed natural gas-fired plants offer a pragmatic solution. With the right planning, financing, and community engagement, they can provide reliable power without locking in emissions, and they can deliver enormous benefits compared to uncontrolled operation. Federal and state governments can accelerate this transition by honoring and increasing CCS grants, supporting shared infrastructure, and streamlining permitting for CCS plants as they have for other clean energy supplies. These investments will enable the construction of cleaner, more resilient power infrastructure for the industries driving demand, from AI data centers to heavy industry.
[cta]
Frequently Asked Questions
What is the difference between a capture-ready and a capture-committed power plant?
A capture-ready plant creates an option to add carbon capture in the future, whereas a capture-committed plant treats capture as part of the project from day one. In a capture-ready plant, developers install the right interfaces and reserve extra land, water, and energy, but nothing obligates them to build the capture project, ever. A capture-committed developer secures options for CO₂ transportation and geologic storage, relationships with capture equipment vendors, funding for engineering studies, and financing across the full value chain before the base plant comes online.
Why have capture-ready plants historically failed to add carbon capture?
Nobody was willing to pay the climate premium. Capture-ready developers built plants that made economic sense on energy value alone, then waited for policy and market signals to justify carbon capture. Those signals were either too weak or never arrived, so the option went unexercised and no capture project was ever designed. The base plant runs uncontrolled for decades while the reserved land sits empty. David Hawkins of the Natural Resources Defense Council captured the problem well: "If your plant is capture ready, my driveway is Ferrari ready." Preserving an option costs very little. Exercising it costs a great deal, and capture-ready facilities rarely came with the funding to do so.
If renewables, nuclear, and geothermal will eventually displace gas, why invest in CCS for gas plants now?
Because greenhouse gas emissions happen in the meantime. Gas plants being built today will operate for 20 to 30 years, long before carbon-free resources scale enough to displace them. Left uncontrolled, they will emit hundreds of millions of tons of CO₂ over that span. Capture on those plants avoids most of it. Today's technology can capture 95% or more of CO₂ emissions at competitive costs in many markets.
What can federal and state governments do to accelerate capture-committed projects?
Three kinds of support matter most: funding, infrastructure, and permitting. Governments should honor and extend existing CCS incentives. Developers make capture commitments years before any revenue arrives, so uncertainty in government funding undermines the confidence these projects require. Governments should also support shared CO₂ transport and storage infrastructure. Common pipelines, rail terminals, and storage hubs make it easier for developers to secure physical CO2 offtake. Finally, permitting for CCS should be streamlined the way it has been for other clean energy supplies. Permitting delay is a leading cause of cost overruns, and a capture-committed plant should be able to pursue capture and storage with the same intensity and speed as electricity generation.
Power & Energy
Relae provides independent advisory for large corporate buyers, power providers, and infrastructure investors making high-stakes decisions about clean firm power, grid constraints, data center energy optimization, and long-term investment strategy. Our insights help you evaluate solutions that can be deployed reliably, responsibly, and affordably, so you can navigate an evolving energy landscape with confidence.
Carbon Capture for Natural Gas-Fired Power Generation


Julio Friedmann, PhD
Julio Friedmann, PhD

Dr. Friedmann is one of the most widely known and authoritative experts in the US on carbon removal (CO₂ drawdown from the air and oceans), CO₂ conversion and use (carbon-to-value), hydrogen, industrial decarbonization, green manufacturing, and carbon capture and sequestration.He served as Principal Deputy Assistant Secretary for the Office of Fossil Energy at the Department of Energy during the Obama Administration, where he was responsible for DOE's R&D program in advanced fossil energy systems, carbon capture, and storage (CCS), CO₂ utilization, and advanced power generation. More recently, he was a Senior Research Scholar at the Center on Global Energy Policy at Columbia. He has held positions at Lawrence Livermore National Laboratory, including Chief Energy Technologist.
Greenman Award (Lifetime achievement in CCS), International Energy Agency: IEA
A.J. Simon
A.J. Simon
,
A.J. Simon is a mechanical engineer and energy systems expert, whose passion for efficiency and insatiable curiosity has led to a 25+ year career spanning industry, academia and the US Department of Energy.
Prior to joining Relae, he managed the Energy Group at Lawrence Livermore National Lab where he led assessments of technologies as diverse as nuclear energy, carbon capture and removal, the energy-water nexus, hydrogen fuel, building energy efficiency, and soldier-portable power.
From 2003 to 2008, he helped to manage a large portfolio of university-led clean energy research at Stanford's Global Climate and Energy Project. From 2001 to 2003, he developed combustion and emissions control technologies for General Electric's diesel and gas turbine product lines.
Oppenheimer Science and Energy Fellow, Department of Energy (2018)
Secretary’s Honor Award, Department of Energy (2016)
Scientific Editor for Science & Technology Review, Lawrence Livermore National Laboratory (2013)
Centennial Teaching Assistant, Stanford University (2000)
What to Read Next
Top Questions on FERC's Co-Location Compliance Order for PJM, Answered
Key Takeaways
- On April 16, 2026, two weeks before the Department of Energy’s (DOE) April 30 deadline for action on the Large Load Proceeding, FERC, the Federal Energy Regulatory Commission, provided a significant update:
- FERC issued its compliance order on PJM's Bring Your Own Generation (BYOG) tariff; the order approved four interconnection paths, rejected two PJM proposals, and directed PJM to refile by May 18.
- FERC's June 2026 order settled a key question around enforcement mechanisms for co-located projects. FERC rejected PJM's Two-Strike proposal (which would have terminated contracts on second violation), allowing only penalties and suspension from the three new transmission services, materially reducing developer downside risk.
- Notably, BYOG arrangements built on the rejected elements of the compliance filing face restructuring risk before that refile. For deals that clear it, however, energization could begin as early as this summer.
- These proceedings reflect the underlying industry concerns about speed, reliability, and cost equity, shifting the risks and costs of new generation from ratepayers to the large loads, such as data centers, themselves.
- Developers, investors, and project teams can use quantitative grid and load modeling to navigate these risks successfully, converting regulatory exposure into priced engineering decisions.
A New Rulebook for Bring Your Own Generation in PJM
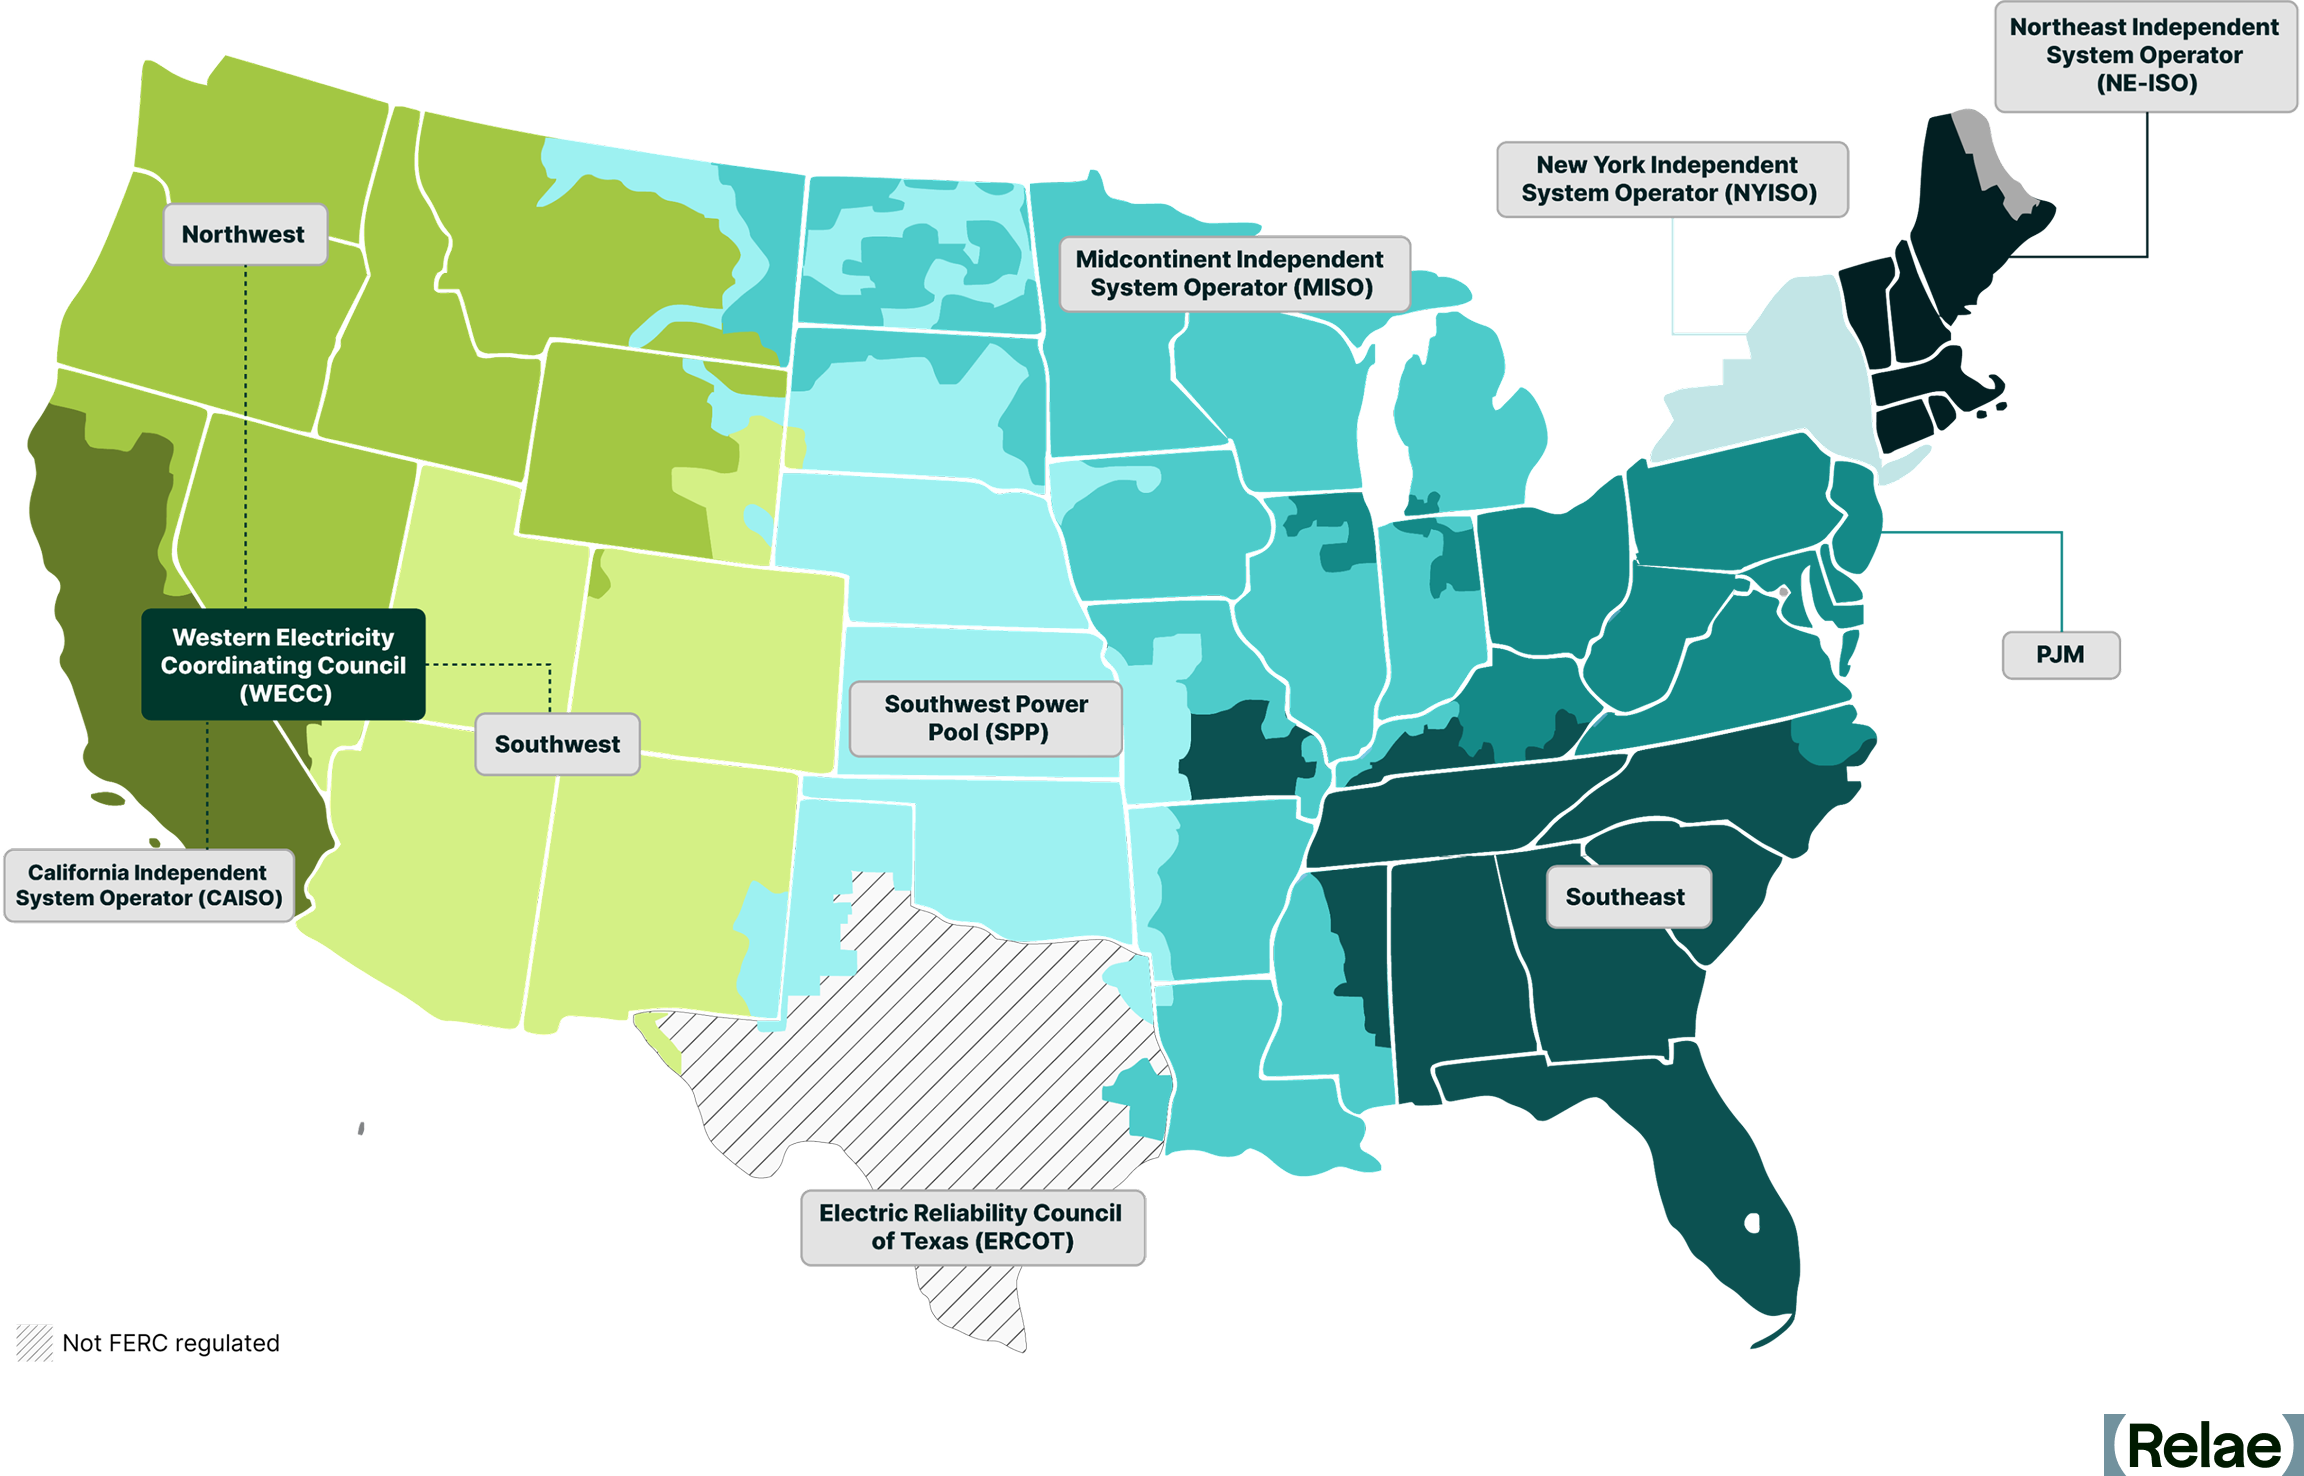
PJM Interconnection (PJM) hosts the highest concentration of data center load growth in the US, managing regional transmission across 13 states in the Eastern US, and commercial operation dates for new generation projects in its current interconnection queue stretch into the early 2030s. Bring Your Own Generation (BYOG) has become the fastest speed-to-power path around that bottleneck.
BYOG allows large loads, such as data centers, to draw power directly from a co-located generation source connected to the bulk power grid, enabling developers to avoid lengthy interconnection queues and costly transmission upgrades, while drawing limited to no power from the bulk power grid.
The Federal Energy Regulatory Commission’s (FERC) April 16 order is now the rulebook that governs the tariffs that facilitate these BYOG arrangements. Any deal built on the paths FERC closed off must now find a way to align with one of the four approved mechanics before PJM's May 18 compliance refile. Deals that clear the refile could begin to energize as early as this summer.
Below are the top questions the Relae power advisory team is fielding most from hyperscalers, large commercial power buyers, and power producers navigating the mechanics of PJM’s BYOG tariff and the engineering realities of running a co-located project.
What Is Co-Location?
Co-location refers to a power generation facility sited in close proximity to a large load, such as a data center, that interconnects directly to the bulk power grid. The generator serves that load contractually via a power purchase agreement (PPA), with power flowing through the meter.
BYOG is the predominant co-location model in PJM. Under a typical BYOG arrangement, on-site generation covers the majority of the data center's load (~90%), with only a small residual portion (~10%) supplied from the grid. Each co-located project effectively functions as its own mini-grid, with explicit operational obligations that are less forgiving than standard transmission service (NITS).
Why Did FERC Keep Behind-the-Meter (BTM) and Co-Location Separate?
While BTM and co-location may look similar, they sit in different regulatory buckets. That said, the line between them is less clear-cut than it once was. FERC found existing BTM rules inadequate to address the grid impacts of large co-located loads and directed PJM to treat co-location as a distinct framework.
At the same time, BTM rules, including how tariffs and distribution charges are applied, remain under revision in a separate PJM proceeding. The two tracks moving in parallel have contributed to the conflation of the frameworks in industry discussion.
How Does Co-Location Differ from BTM Generation?
- Co-location, as this order defines it, is a bulk grid-interconnected arrangement. The host generator remains on the same interstate grid, maintains its interconnection service agreement, and continues exporting power to the grid. The co-located load connects through an approved interconnection mechanic and takes transmission service under a PJM tariff product.
- BTM is a distinct arrangement. The generator sits on the consumer's side of the utility meter and serves the load through a private line, without an interconnection agreement. The load may typically have a grid connection; however, in some circumstances, the generation may be fully off-grid or islanded. By setting a megawatt (MW) threshold for BTM, larger loads with co-located generation may no longer net out their load to reduce transmission and grid charges. FERC's jurisdiction over a BTM arrangement is narrower, and the tariff mechanics that apply to co-location do not apply in the same way.
FERC's rejection of PJM's proposed BTM rule changes illustrates this distinction. The commission is keeping the two categories separate on purpose. Ultimately, FERC’s intention seems to signal that large loads co-located with generation may not be adequately reflected in grid and transmission upgrade costs when these assets are behind the meter. Historically, BTM assets were exempt from these costs because their relatively insignificant power contributions had no meaningful financial impact on the bulk power grid.
That said, the BTM track is still moving. PJM's BTM application rules, including the netting-off mechanism that lets BTM loads avoid utility tariffs, remain under review in parallel proceedings.
For developers, regulatory clarity on co-location and BTM is increasingly critical. In April 2025, FERC upheld its rejection of the Talen-Amazon Susquehanna nuclear BTM interconnection agreement proposal, declining to rehear arguments on the initial decision. To many experts, the split ruling signaled that the structure of PJM’s interconnection service agreement (ISA) is inadequate for large loads operating behind the meter.
However, in the initial challenge to the Talen-Amazon proposal, utility companies argued that the arrangement would unjustifiably shift transmission costs to other PJM customers. Ultimately, in June 2025, Talen Energy entered into a 1,920 MW, front-of-the-meter power purchase agreement with Amazon Web Services, which does not require FERC’s approval.
FERC Has Always Regulated Generators, Not Loads. What Changed?
The April 16 order lands inside a larger jurisdictional shift. FERC does not typically regulate load interconnection; its authority sits with the bulk power grid. Under Orders 888 and 2003, FERC has regulated how generators connect to that system (with standardized study deposits, readiness requirements, and withdrawal penalties) while load interconnection has historically been regulated at the distribution level under state jurisdiction.
That generation-only approach to FERC regulation worked for three decades. Now, the scale of AI data centers and other large loads creates interstate impacts that state-level load regulation cannot fully address. Generation co-location breaks the pattern by routing the load through a FERC-regulated generator interconnection agreement rather than a state-regulated load-serving entity, pulling it into federal jurisdiction.
In December 2025, FERC declared PJM's existing interconnection rules (tariff) unjust and unreasonable in the PJM Co-Location Order and directed PJM to revise the tariff. The April 16 order is FERC's review of that rewrite.
As FERC Commissioner David Rosner wrote in his concurrence to the December 2025 PJM Co-Location Order: "We are trying to meet surging demand while upholding two fundamental values that underpin the electric industry in our country: first, that all customers have a right to receive electric service on a timely basis, and second, that electric service should be reliable and affordable for all customers. Given the scale of new large loads putting demand on our grid today, it is clear that fostering both of these values requires intervention."
Which Four Interconnection Mechanics Did FERC Approve?
The April 16 order (Docket ER26-1088-000, 195 FERC ¶ 61,030) approves four ways for a data center to plug into the PJM grid. Each solves a different bottleneck: available capacity, queue position, study timing, or pre-studied capacity. All four rely on existing PJM and FERC tariff mechanics rather than new constructs, a deliberate choice to reduce legal exposure and speed up adoption.
- Sub-full-capacity interconnection service (available capacity). The data center co-locates with an existing host generator, and interconnects at less than the host generator's full capacity, using the portion of the existing interconnection rights the generator does not need.
- Request acceleration at Decision Points I and II (queue position). Co-located load applications can move ahead of the standard queue at defined checkpoints, subject to PJM's study results. Co-located loads place less demand on the bulk power grid than new large loads without co-located generation, justifying the accelerated treatment. To qualify, projects must demonstrate there will be no significant network updates required or network impact, among other readiness milestones.
- Provisional Interconnection Service, or PIS (study timing). Interim interconnection services are provided during the full study, giving developers a bridge to early operations.
- Surplus Interconnection Service, or SIS (pre-studied capacity). Use of unused capacity at an already-studied generator’s interconnection point, without triggering a new full study.
The four mechanics are different ways of answering the same operational question—how a co-located data center plugs into the grid without triggering a multi-year re-study of the host generator's interconnection—enabling faster speed-to-power.
Which Generators Gain Most From Surplus Interconnection Service?
SIS is the most commercially interesting of the four mechanics for existing generator owners because it monetizes previously stranded capacity.
The generators that benefit most include:
- Retiring or derated thermal units with unused megawatts of interconnection rights at high-value points (for example, retiring coal plants in PJM's eastern and mid-Atlantic footprint).
- Existing nuclear and large thermal plants near concentrated load growth, particularly in Dominion, American Electric Power (AEP), and ComEd territory (the Northern Virginia, Columbus, and Chicago metro zones), where PJM load is most concentrated.
- Storage-paired assets where the underlying generator has capacity headroom that the storage does not fully use (for example, solar-plus-storage or gas-plus-storage sites where the battery sits below the full interconnection rights).
For illustration, a host generator running at roughly 85% of its interconnection rights with a forced outage rate near 5% has material surplus capacity (10%) available to a co-located load, depending on how PJM studies the combined profile.
Owners of underutilized interconnection rights now have an approved tariff path to extract value from them by attracting data centers to co-locate with these generators.
What Transmission Service Does a Co-Located Load Receive?
Connecting to the bulk power grid and taking service from it are two separate decisions. PJM's default transmission service for any load on the system is the Network Integration Transmission Service (NITS), the standard contract for firm power year-round. NITS commits PJM to serve a customer’s full load at any and all times, meaning that PJM may need to wait for generation and/or transmission upgrades before offering it to a large load.
Recently, PJM reopened its generation interconnection queue after pausing to study its backlog of proposed projects. With 800 proposed projects representing approximately 220 GW in new capacity in 2026, this growth signals progress, but it does not address the underlying permitting and financing challenges that have prevented projects already in the queue from being built.
The BYOG mechanics are variations that waive or defer parts of NITS for faster speed-to-power. PJM delivers the resulting service through three tariff product types:
- Firm contract demand: The co-located load holds firm transmission service (consistent with most aspects of NITS) and operates like any other firm load on the system. Availability is site-specific, depending on the point of interconnection. Unlike other NITS customers, entities contracting firm contract demand transmission on behalf of co-located loads cannot exceed the contracted demand level, and loads would be subject to a penalty if they withdraw additional energy beyond the contracted demand capacity.
- Non-firm contract demand: The load accepts interruption risk in exchange for faster interconnection or lower-cost service, making it better suited to loads with operational flexibility. It is available at more interconnection points than firm service, but power delivery is subject to curtailment based on real-time grid conditions. This service intends to provide brief and intermittent energy access from the bulk power grid, during available periods, under unanticipated circumstances, such as downtime for the co-located generator.
- Interim NITS: A bridge product that provides firm service on an interim basis while the co-located generator is still under construction. The load energizes early; once the generator and any transmission upgrades are complete, the project transitions to a standard NITS arrangement, and the generator can participate in the broader PJM market. However, while the load pays the NITS rate, the load is subject to curtailment under system emergency conditions, posing reliability challenges.
In practice, a 1,000 MW data center co-located with a 900 MW on-site generator would request 100 MW from PJM under one of these three products.
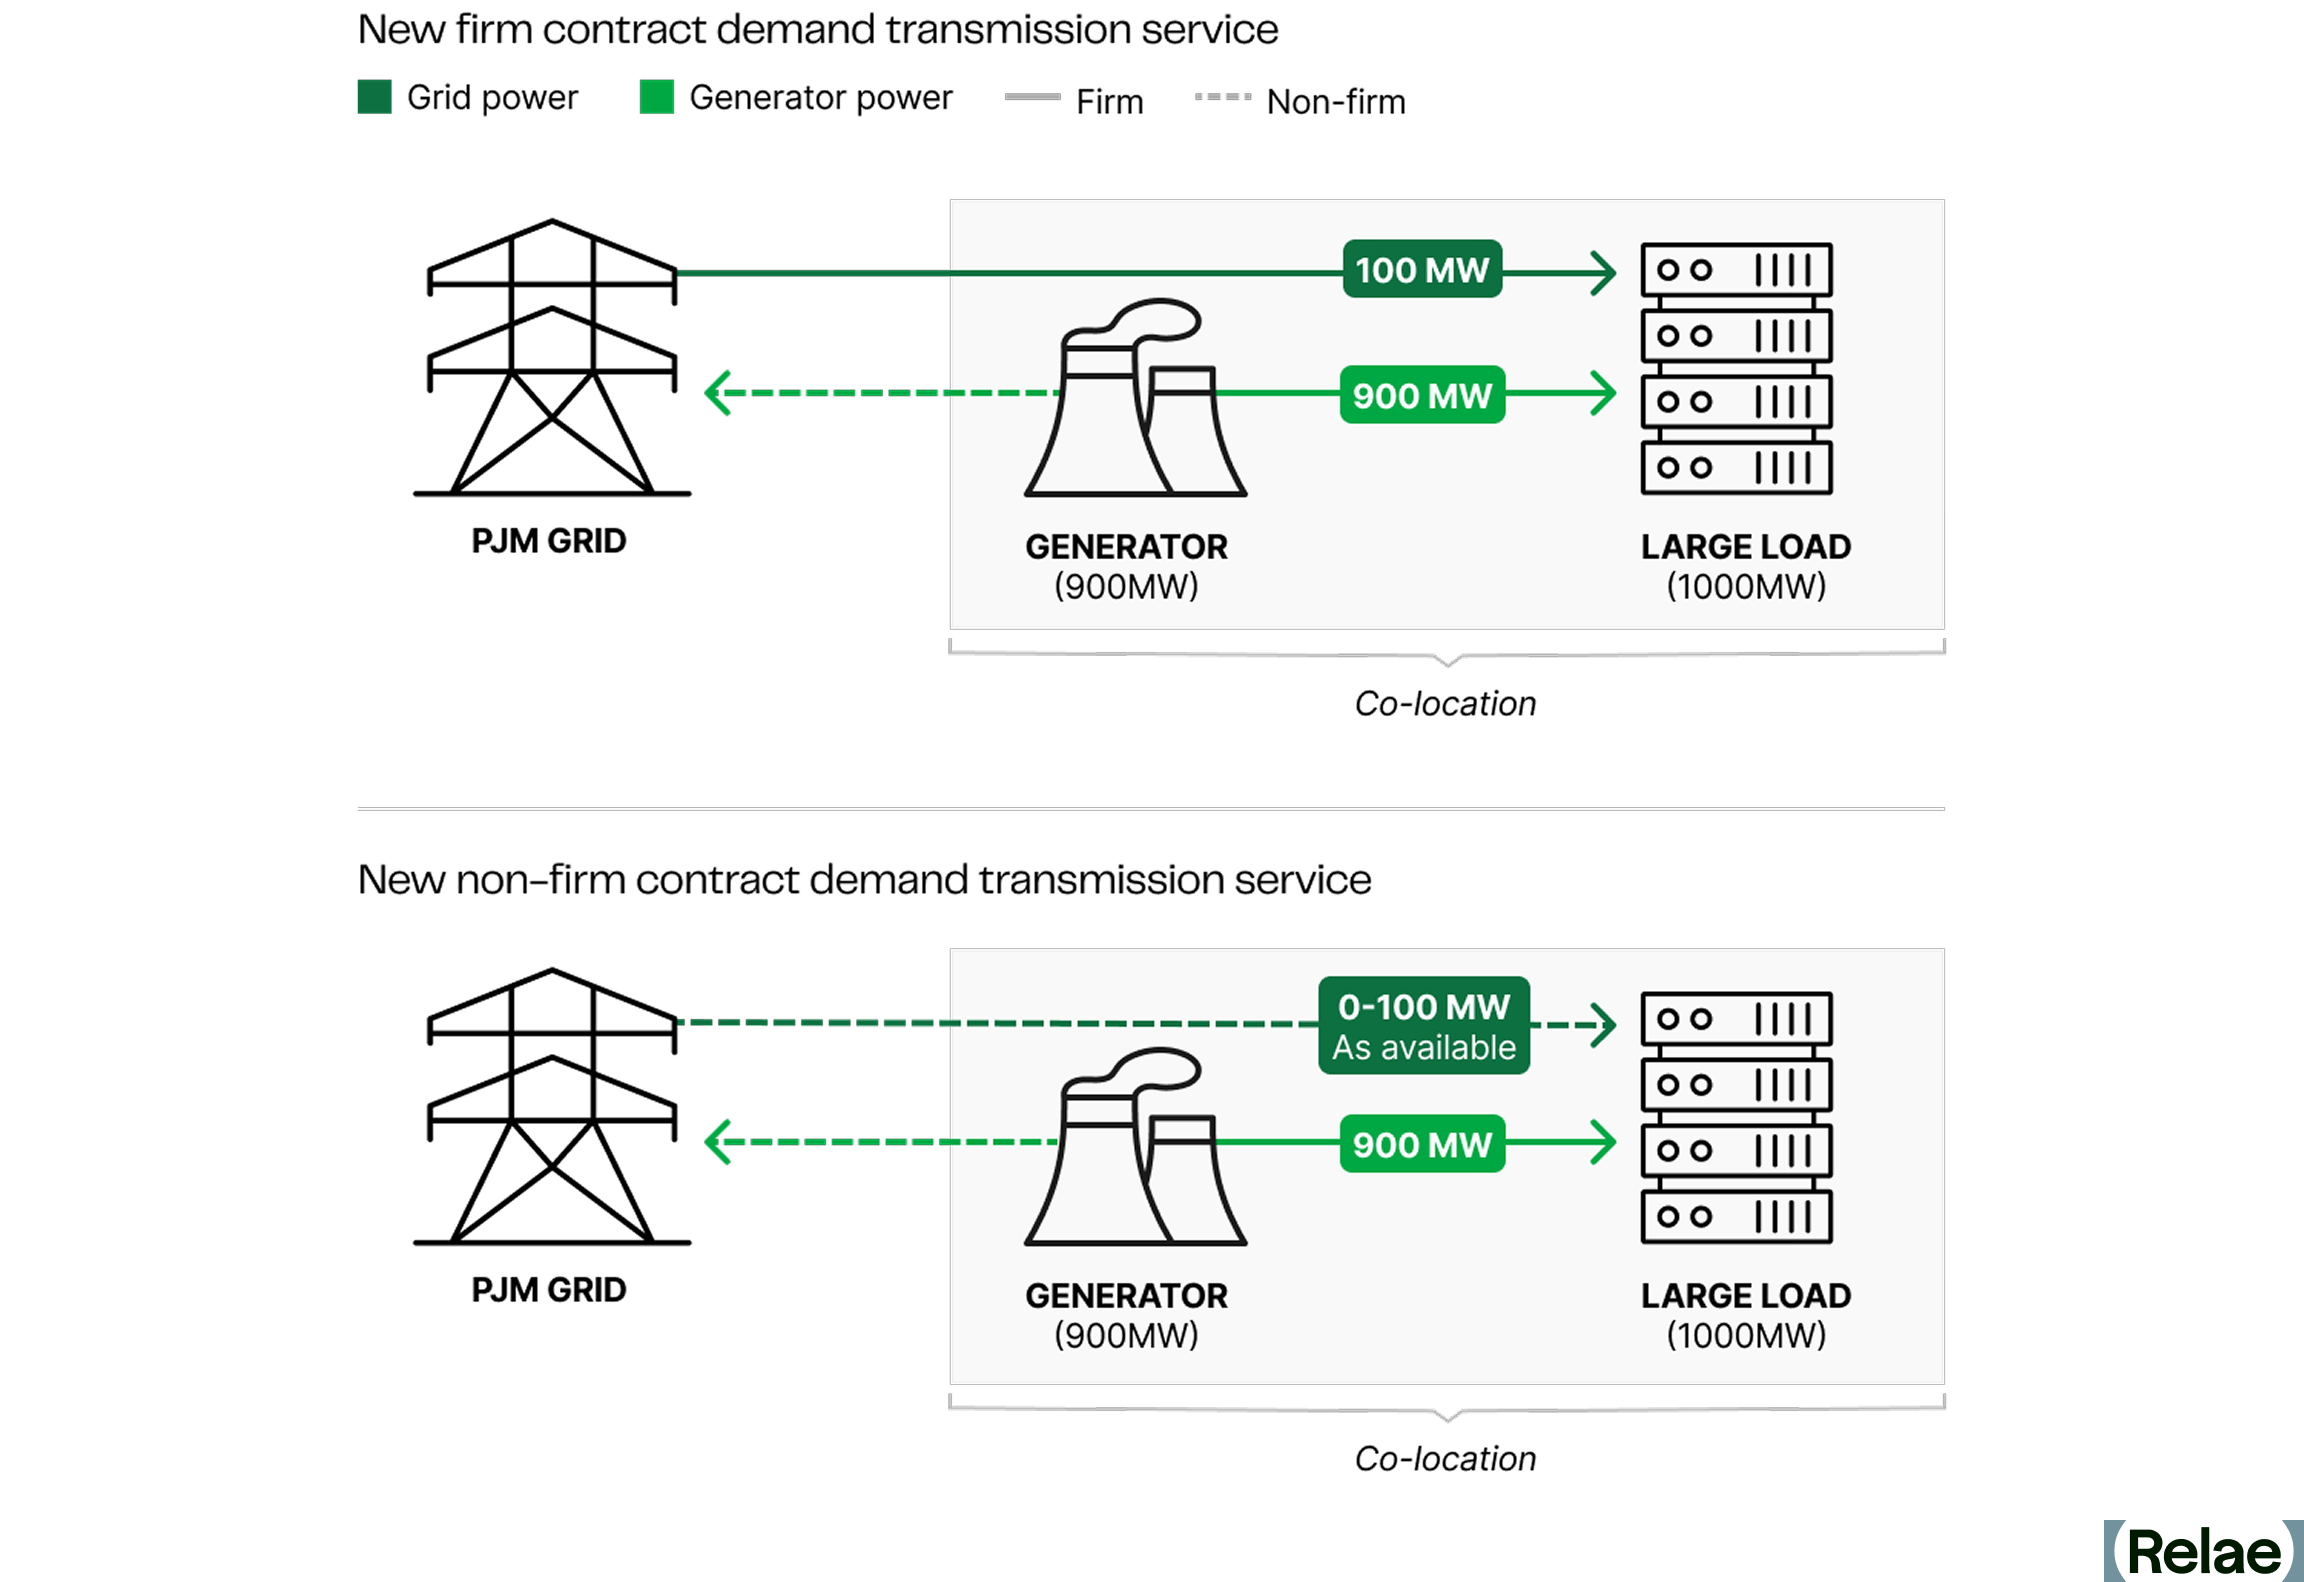
The interconnection mechanic (how the load connects) and the tariff product (what service the load receives) are two distinct decisions. For example, in the case of an interim NITS, a data center and co-located load could connect through a Provisional Interconnection Service (PIS). Other co-located loads may connect by submitting a request for acceleration at Decision Points I and II to secure firm contract demand service. The connection mechanism and tariff will vary based on each co-located load’s unique characteristics and project configuration.
For clients evaluating specific sites, the right path depends on how much of the host generator's interconnection capacity is available, how sensitive the load is to interruption, and how fast the site needs to energize. Grid modeling allows project teams to quantitatively assess their risk exposure before committing to a tariff product.
Which Two PJM Proposals Did FERC Reject?
Two elements of PJM's original filing did not make it through the April 16 order.
- Point of Change in Ownership substitution: PJM proposed swapping in "Point of Change in Ownership" for FERC’s mandated term "Point of Interconnection" in the definition of Co-Located Load. FERC rejected the swap as an unexplained deviation from the Co-Location Order's definition and because it could let transmission owners delay or effectively veto the Point of Change in Ownership location, creating uncertainty for co-located projects.
- BTM application-rule changes: PJM tried to fold changes to its BTM application rules into this same compliance package. FERC rejected that on the ground the changes did not fall within the scope of the initial order. BTM remains a separate regulatory track; the April 16 order does not settle it.
Project configurations built on either rejected proposal need restructuring before PJM's May 18 refile.
The order also directs PJM to add the PIS definition to the Open Access Transmission Tariff (OATT), Part I, section 1 (paragraph 26), and flags items in paragraph 29, including assessment of the reliability of co-located loads paired with electric storage, as out of scope.
These determinations should not be seen as FERC rejecting these tariff changes, but rather deeming them outside the scope of the order. They are open questions that belong in a separate docket. The direction to include PIS while declining to address issues not included in the compliance proceeding demonstrates FERC’s focus on speed-to-power, clarifying the rules for new co-located generators to connect to the grid more quickly.
What Is the Two-Strike Reliability Rule, and Why Does it Matter?
The rules for violating a co-location interconnection service agreement are still being developed, but FERC has urged PJM to issue robust protections to maintain reliability and cost allocation equity.
For both firm and non-firm contract demand transmission service, PJM will apply a penalty rate to transmission service customers who withdraw more energy from the grid than was contracted. The precise design of these rates for unreserved use is scheduled for a paper hearing this spring; however, developers should cautiously size and appropriately model load and generation sizes, as the penalties for jeopardizing PJM’s reliability are not limited to rates.
While penalty rate design for unreserved use is underway, PJM proposed a strict Two-Strike reliability rule for co-located projects. If a co-located customer failed to adequately implement automated loadshedding or generator tripping mechanisms during unusual grid conditions, PJM has previewed severe consequences:
- First strike: a 120-day operational pause for review.
- Second strike: termination of the transmission service contract and return to the NITS interconnection waitlist.
The entire purpose of pursuing a co-located large load configuration is to ensure speed-to-power while maintaining reliability. In a June 2026 order, FERC conceded that there are legitimate reliability concerns with co-located generation misoperation; however, PJM’s proposal to disqualify customers with multiple misoperations is unnecessarily strict. FERC ultimately agreed PJM has the authority to charge penalties to and temporarily suspend services for customers that fail to shed load or curtail, but cannot disqualify customers for misoperation. Data centers will need to rigorously model and design their co-located load and generator facilities with the understanding that multiple reliability violations could strand billion-dollar assets for multiple years.
Which BYOG Deals Need Restructuring Before the May 18 Refile?
Any deal built around the Point of Change in Ownership substitution or the BTM application-rule changes that FERC rejected needs restructuring.
In addition, co-located projects that relied on one of the four approved mechanics, but used PJM tariff language from the original December filing, may also need re-papering against the language PJM submits in its forthcoming May 18 compliance filing. Until PJM files that package and FERC accepts it, the operative document is the April 16 order itself.
Counterparties should confirm that operational controls, curtailment rights, and dispute mechanisms in the contract align with the proposed Two-Strike regime and the approved mechanics the project uses.
What Does Grid Modeling Reveal for a Co-Located Project?
Non-firm service is the lowest-cost tariff product for the portion of load the co-located generator does not serve, but availability depends on real-time grid conditions. Grid modeling is how developers size that exposure before signing.
Take the same 1,000 MW data center paired with a 900 MW on-site generator, contracting 100 MW of non-firm service for the residual load. Grid modeling might show non-firm power dropping out in roughly 15% of hours during the summer peak.
If the on-site generator also carries a 5% forced outage rate, the developer faces a meaningful probability of a compound event: grid supply drops out at the same moment the on-site unit trips offline.
In that window, the data center has three options, none of them free:
- Curtail load.
- Shift the load to another site.
- Draw more from the grid than the contract allows, which triggers a Two-Strike violation.
Grid modeling converts that risk into decisions the developer can price. A developer can test whether adding 50 MW of battery storage, contracting 150 MW of firm service instead of 100 MW of non-firm, or adding a smaller backup generator delivers the best risk-adjusted return.
Scope 2 Emissions Explained: Tracking, Reporting, and Reducing Impact
Key Takeaways
- Scope 2 emissions (indirect emissions from energy use) are increasingly critical to address. With surging electricity demand, especially from data centers, scope 2 is a growing share of corporate emissions and a priority for decarbonization.
- Approaches to scope 2 accounting are evolving—and formal changes are now on the table. Both location-based and market-based methods remain accepted under the Greenhouse Gas Protocol. Still, the Protocol's recently closed public consultation proposes more granular approaches, including 24/7 power and carbon matching, that would better reflect the realities of modern power markets.
- Proven decarbonization levers, such as reducing energy use, entering power purchase agreements, procuring green tariffs, and buying high-quality renewable energy certificates, are already available and impactful. Decarbonization, not just measurement, must be the goal. Companies don’t need to wait to decarbonize.
Accounting for Indirect Emissions From Energy Use
As businesses and organizations strive to reduce their environmental impact, carbon accounting has become an essential tool for tracking and managing greenhouse gas (GHG) emissions. Carbon accounting helps organizations measure, report, and mitigate their emissions across various activities. A key framework for categorizing these emissions is the Greenhouse Gas Protocol (GHG Protocol), which classifies emissions into three scopes:
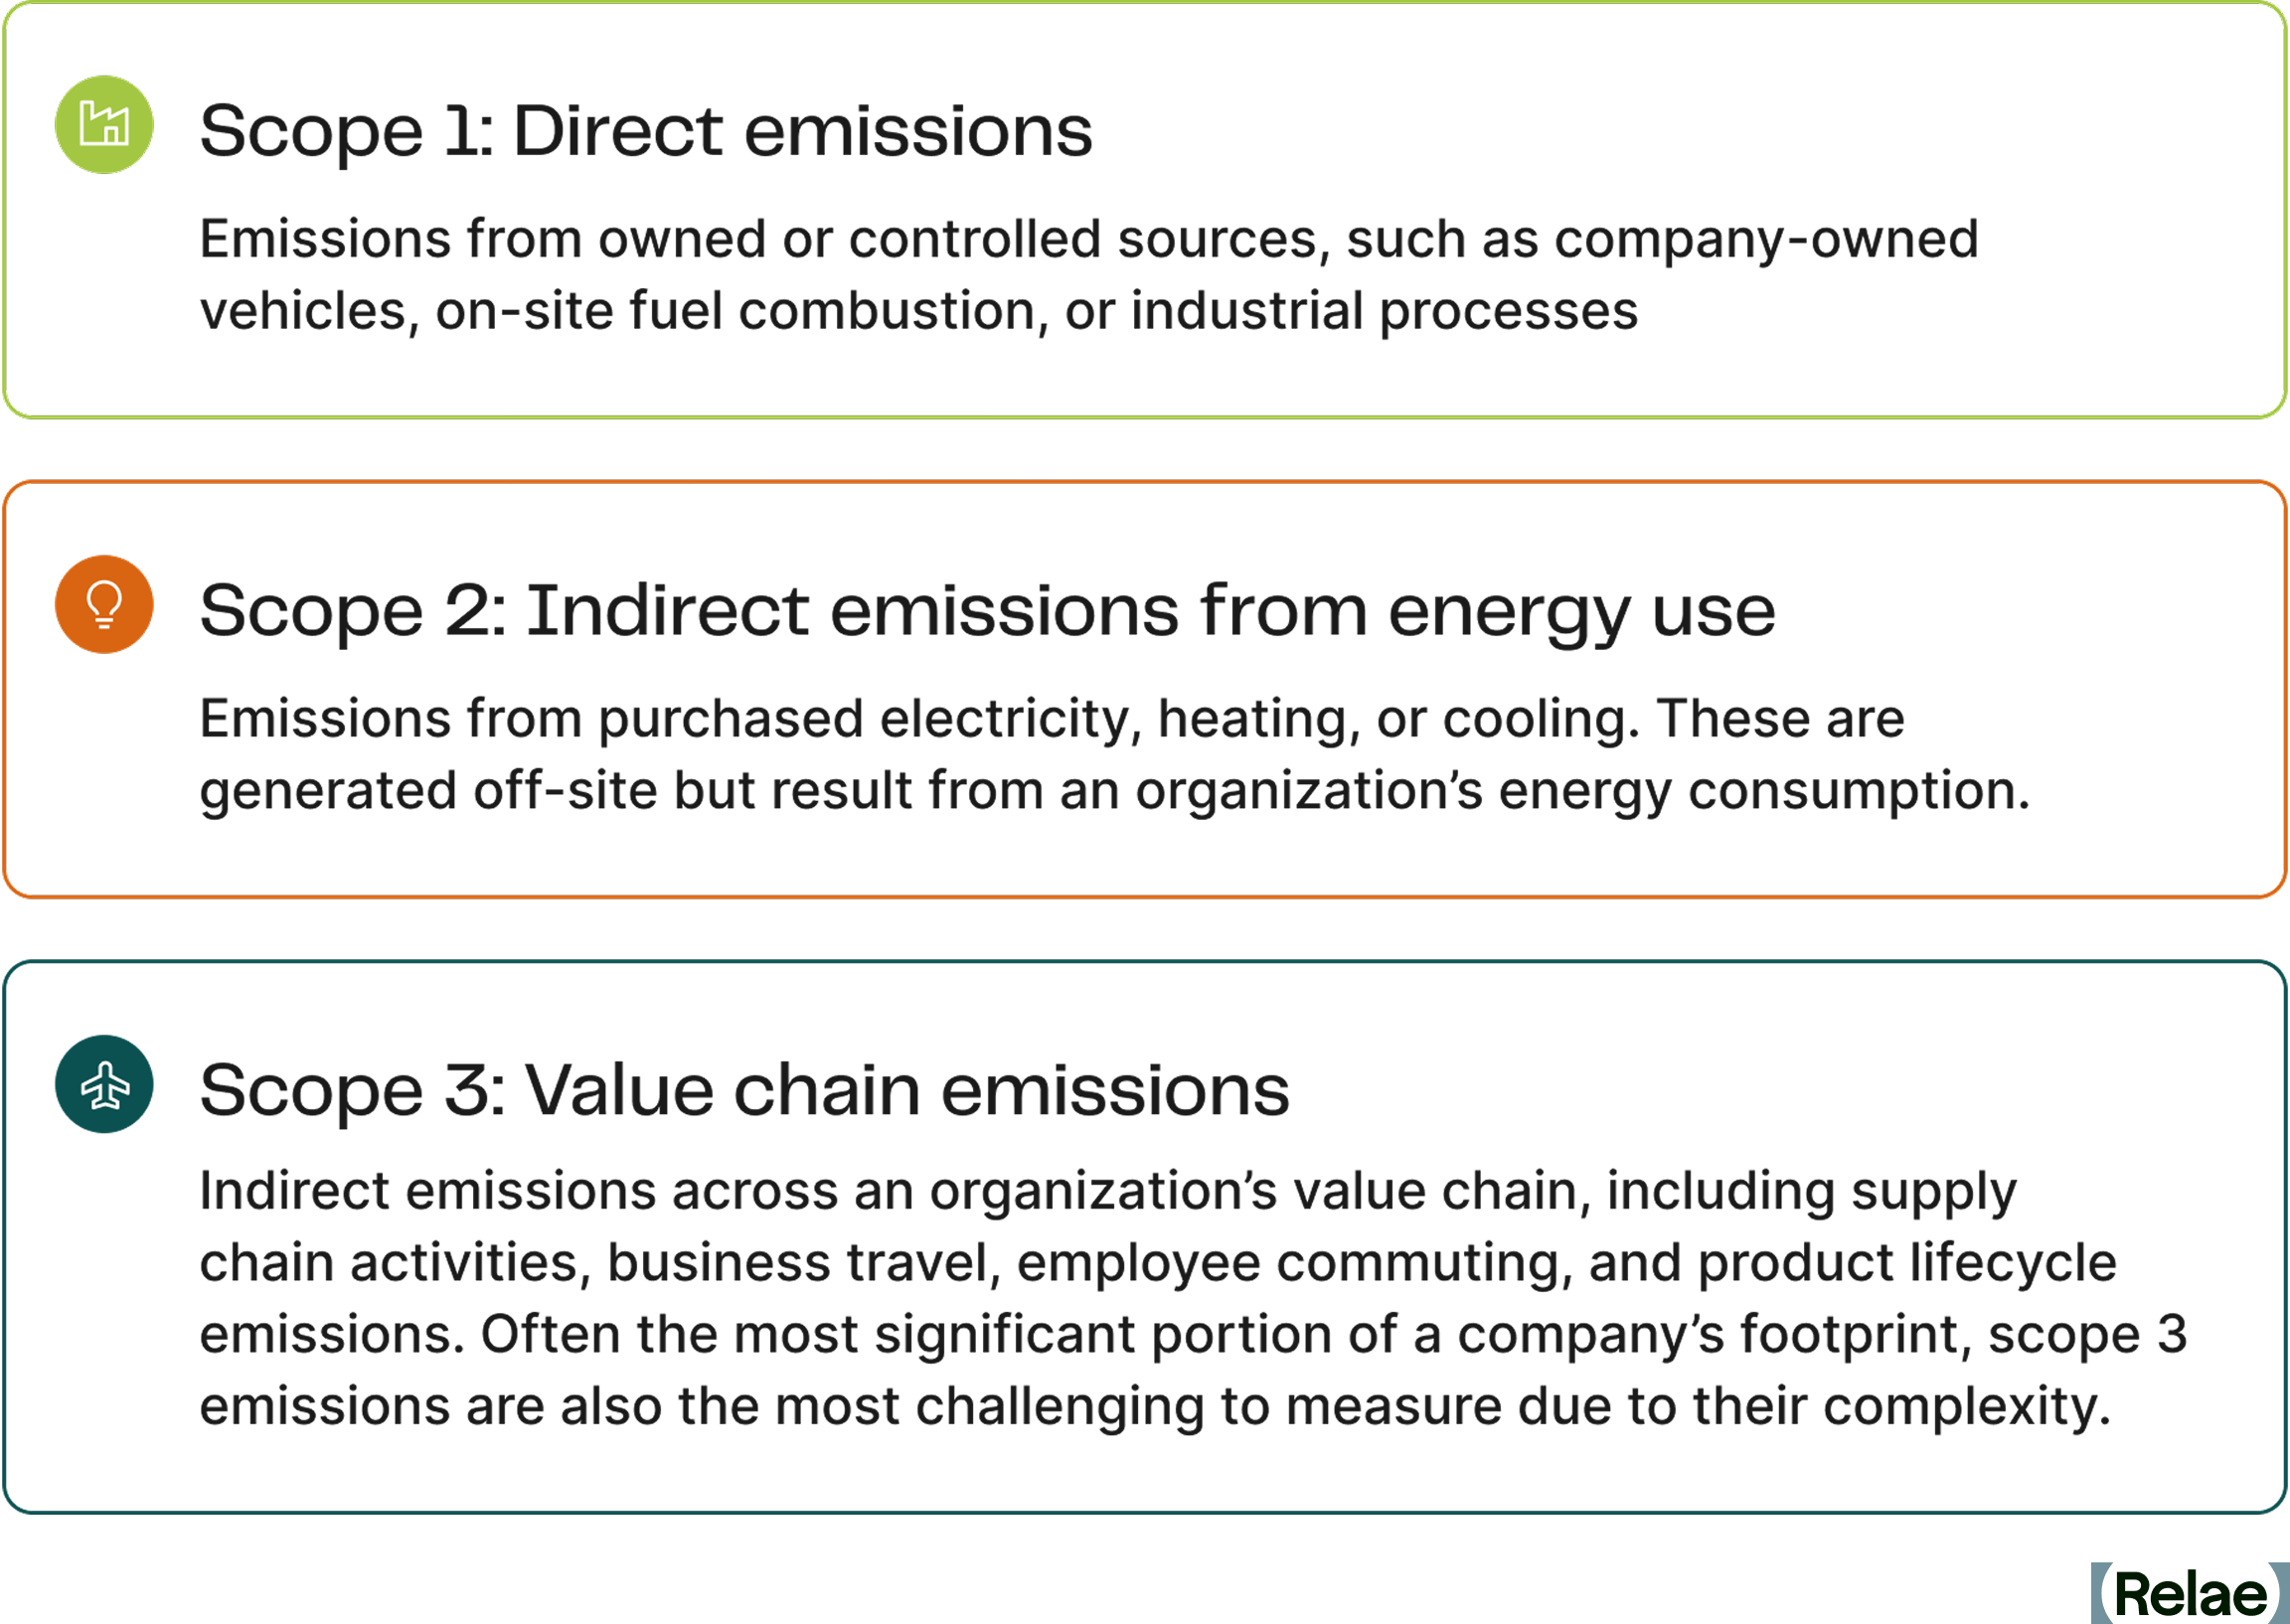
Each scope presents unique challenges and opportunities for reduction. Among them, scope 2 emissions are particularly significant because they stem from purchased energy, which is often generated using fossil fuels. However, numerous reduction mechanisms exist today to help organizations eliminate these emissions, such as improving energy efficiency in order to use less energy, and transitioning to renewable energy sources through market-based mechanisms. Understanding scope 2 emissions is crucial for businesses looking to contribute meaningfully to the global energy transition and achieve sustainability goals.
What Are Scope 2 Emissions?
Scope 2 emissions refer to indirect GHG emissions associated with the consumption of purchased energy. Unlike scope 1 emissions, which result from direct fuel combustion, scope 2 emissions arise from the generation of electricity, steam, heat, or cooling that a company procures from external sources.
The primary sources of scope 2 emissions include:
Purchased electricity: When businesses buy electricity from a utility provider, the emissions from power plants that generate this electricity are classified under scope 2.
Purchased heat, steam, and cooling: Some companies purchase heat, steam, or cooling services instead of generating them on-site. These services often come from centralized facilities that may rely on fossil fuels, thereby contributing to scope 2 emissions.
What sets scope 2 emissions apart from other scopes is the presence of market-based mechanisms that offer multiple pathways for organizations to reduce their carbon footprint. Unlike scope 1, where emissions reductions often require technological shifts or operational changes, scope 2 reductions can be achieved through strategic procurement decisions. The transition to renewable energy sources is an essential component of sustainability strategies, setting the stage for a broader energy transition across industries and economies.
How Are Scope 2 Emissions Measured Today?
The GHG Protocol currently outlines two primary approaches for calculating scope 2 emissions: the location-based method and the market-based method.
Location-Based Method
The location-based method calculates emissions for electricity consumption based on the average emissions intensity of the grid where the energy consumption occurs. This approach is mandatory under various reporting frameworks and does not take into account a company’s procurement choices.
- Relies on grid averages: Emissions are calculated based on regional grid emissions factors rather than specific energy purchases.
- Time-delayed data: Since grid emissions factors are typically updated annually, this method may not reflect real-time energy sourcing changes.
- Limited control: Companies using this method have less direct influence over their reported emissions, as they depend on the overall energy mix of their region.
Market-Based Method
The market-based method, on the other hand, reflects an organization’s actual procurement decisions and energy-sourcing strategies. It accounts for specific contracts, such as power purchase agreements (PPAs), renewable energy credits (RECs), and green tariffs, which allow businesses to claim lower emissions from their purchased electricity.
- Reflects company choices: Emissions calculations take into account contractual agreements for renewable energy purchases.
- Mechanism for electricity transition: Encourages organizations to invest in low-carbon electricity options and actively support the transition to renewables.
- Multiple reduction options: Companies can reduce their scope 2 emissions through a portfolio of mechanisms like PPAs, RECs, and green tariffs, making this method a flexible and strategic tool for decarbonization.
While market-based mechanisms provide flexibility in reducing scope 2 emissions, they also highlight the need for more precise and updated carbon accounting methodologies. For example, some decarbonization strategies, such as time-shifting energy consumption to better match renewable generation, are not accounted for under these methods. This and other limitations mean that the traditional methods outlined in the GHG Protocol are increasingly seen as outdated in an era of rapid changes in energy generation and grid dynamics. As a result, the market is shifting toward more advanced power emission accounting methodologies that provide a more accurate reflection of emissions associated with electricity use.
Proposed Changes to the GHG Protocol Scope 2 Guidance
The current GHG Protocol Scope 2 Guidance provides a market-based instrument methodology, originally designed in the early 2000s, that allows US-based companies to procure renewable energy at any point within a year from anywhere in North America and apply it to any of its annual electricity consumption within that same year. This methodology, as written, allows for a potentially significant mismatch of “emissions caused” (by consuming electricity) versus “emissions avoided” (by generating renewable electricity) in that it does not account for any of the realities of electric grids and generators, which vary significantly over different regions, seasons, and time of day.
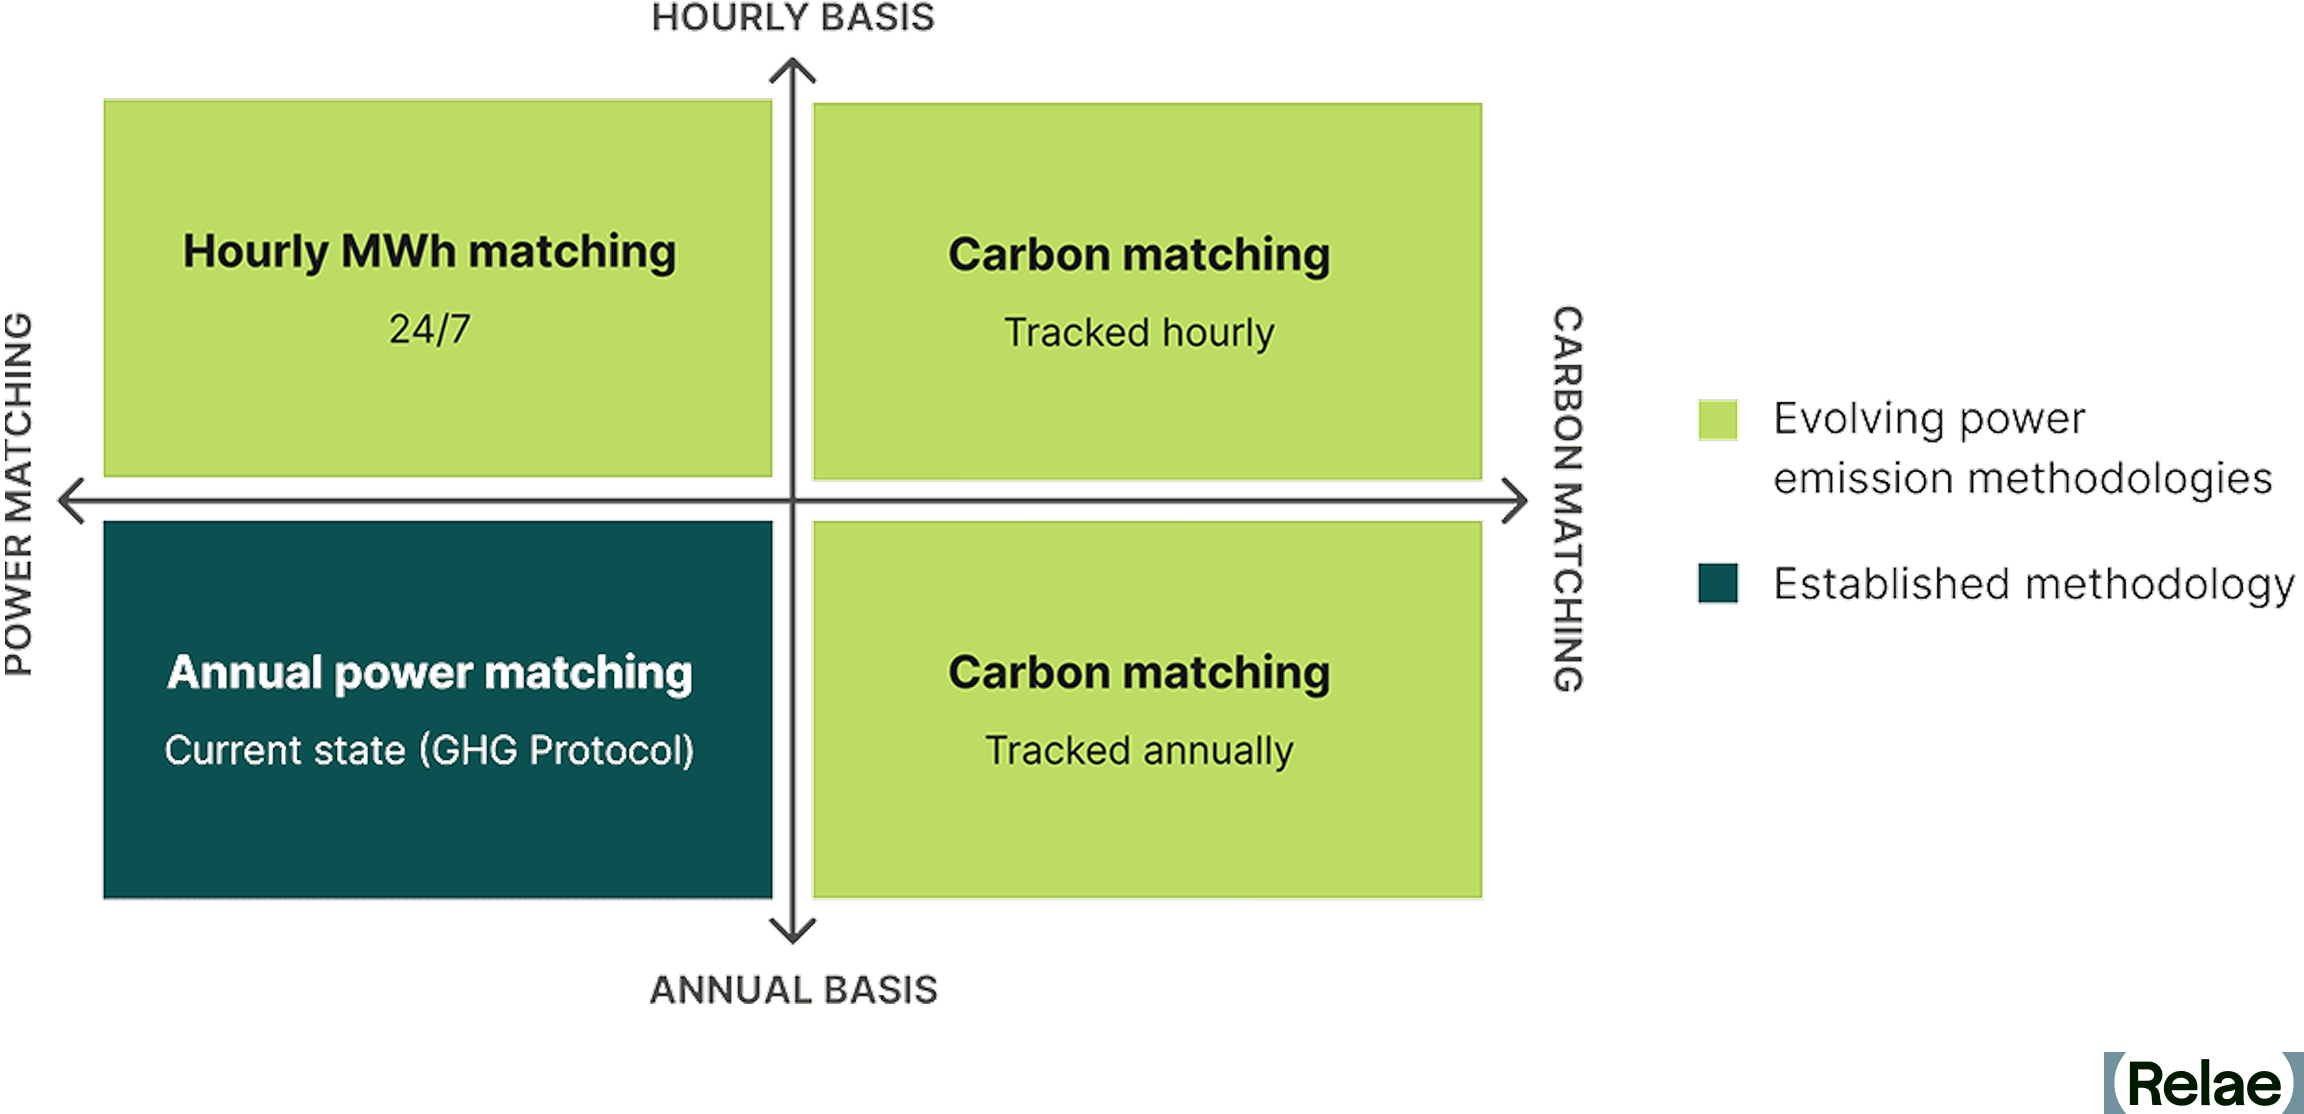
In response to this, the GHG Protocol Scope 2 Guidance is currently undergoing a revision process, which will include how emissions associated with electricity consumption are calculated. A focus of the revision process is on how to better account for the real emissions associated with a corporate’s electricity consumption, and more impactful ways of mitigating them through market-based instruments and other approaches. Advanced power emission accounting methodologies, such as 24/7 power matching and carbon matching, are being explored as ways to better represent the GHG emissions associated with electricity consumption.
- 24/7 power matching emphasizes matching electricity consumption with an equivalent amount of renewable energy production on an hourly basis.
- Carbon matching emphasizes measuring the emissions impact of incremental electricity consumption or production at a specific time.
These emerging methodologies propose a shift toward more granular temporal and region-specific matching, which could require companies to rethink their emissions reporting approach and explore more advanced tracking tools. They may also introduce new strategies beyond market-based instruments for reducing scope 2 emissions, such as time-shifting energy consumption.
As power grids continue to decarbonize and new digital tools emerge, businesses will need to adapt to these evolving methodologies to remain compliant, enhance sustainability strategies, and achieve meaningful reductions in emissions. Companies that proactively integrate advanced power emission tracking into their carbon accounting strategies will be better positioned to lead in the transition to a low-carbon economy.
How to Reduce Scope 2 Emissions
The GHG Protocol provides multiple mechanisms for reducing scope 2 emissions, allowing organizations to shift their energy consumption toward lower-carbon alternatives. These include:
- Reducing energy consumption: Improving energy efficiency in operations can significantly lower electricity use. In some cases, this involves capital investments in more energy-efficient equipment, but in other cases, it can be based on operational changes such as reducing unnecessary lighting, HVAC, and other services during non-working hours. (Electrification efforts, such as shifting from fossil fuel-powered systems to electric alternatives, may actually increase scope 2 emissions, but this can ultimately reduce overall emissions by correspondingly decreasing scope 1 emissions and allowing for renewable energy procurement.)
- RECs: Companies can purchase unbundled RECs (emissions “attributes” separated from the actual electricity product) to offset emissions associated with purchased electricity. While there has been criticism of RECs due to their significant range in quality, high-quality RECs are available, which may include ensuring regional matching, financial additionality, on-line date additionality, or tighter temporal generation to consumption matching. The use of high-quality unbundled RECs is the most accessible and realistic option for most smaller-scale companies to address scope 2 emissions.
- On-site generation and co-location: Installing on-site renewable energy generation, such as solar panels, allows companies to directly offset their electricity consumption from the grid. In some commercial settings, such as companies using leased real estate or co-located data centers, partnering with facilities that prioritize renewable energy procurement can help reduce scope 2 emissions for the facility owner while the facility occupant reduces scope 3 emissions.
- PPAs: Entering into long-term contracts with renewable energy providers ensures companies receive electricity from clean energy sources while supporting the expansion of renewable generation capacity. PPAs are available with standardized contract terms, and some service providers will aggregate demand from multiple smaller companies to reach the minimum required amount for typical PPA contracts. Hedging products are also available to reduce market risks.
- Green tariffs: Many utilities offer green tariffs that enable businesses to purchase renewable energy directly through their electricity provider, often at a premium but with lower emissions impact. For many smaller companies, this is a more viable approach than a PPA with a single renewable generator.
By adopting a combination of these strategies, businesses can significantly lower their scope 2 emissions while aligning with broader sustainability goals and regulatory requirements. The path to decarbonization requires proactive investment in cleaner energy sources, efficient consumption practices, and leveraging market-based instruments to drive the transition toward a low-carbon future.
Why Does Reducing Scope 2 Emissions Matter?
Reducing scope 2 emissions is the underpinning of decarbonizing the power sector and enabling the global energy transition. In 2025, S&P reported that corporate buyers added 15.2 GW of renewable capacity in the US, up from 9.1 GW in 2024, illustrating the growing impact of the corporate sector on the electricity grid. Cleaner grids translate to lower emissions for all energy users. Organizations that actively reduce their scope 2 emissions can contribute to decreasing demand for fossil fuel-based electricity and accelerate the deployment of renewable energy infrastructure.
For companies that own and operate data centers, this transition is especially important. AI data centers consume large amounts of electricity, and their reliance on purchased power makes them a significant source of scope 2 emissions. Since many businesses rely on third-party data center services, reducing emissions from these facilities also helps lower scope 3 emissions across industries. Corporates can influence data centers by requiring that they have a clear and explicit low-emission power strategy in place before procurement.
Beyond direct corporate benefits, reducing scope 2 emissions has a tangible long-term impact on power grids. Increased investment in renewable energy procurement sends a strong market signal, encouraging utilities and developers to expand clean energy projects. As more companies commit to sourcing renewable energy, the overall mix of grid power shifts, making low-carbon electricity more accessible and reducing reliance on fossil fuel-based generation. Ultimately, widespread corporate action in scope 2 emissions reduction supports the broader decarbonization of power markets and strengthens global climate commitments.
Frequently Asked Questions
Will RECs (renewable energy certificates) still count toward scope 2 reductions under the GHG Protocol's proposed changes?
Under the current Scope 2 Guidance, yes—RECs remain a valid market-based instrument. The proposals from the GHG Protocol's recent consultation range from retaining market-based accounting with stricter quality criteria to restructuring how instrument-based claims are reported altogether, and nothing is final until the revised standard is published. What's clear is that scrutiny is rising, particularly for unbundled RECs with weak temporal or geographic connection to a company's actual consumption, so prioritizing high-quality RECs now is the best way to future-proof a procurement strategy.
How would the proposed hourly and regional matching requirements affect companies that rely on unbundled RECs today?
Hourly (24/7) and regional matching would require renewable generation claims to line up much more closely with when and where a company actually consumes electricity. Companies relying on annually matched, unbundled RECs sourced from distant grids would likely see their reported market-based emissions rise under such requirements. The practical preparation is to start collecting more granular (ideally hourly) consumption data and shift toward RECs and contracts with tighter regional and temporal matching.
What's the practical difference between location-based and market-based scope 2 accounting, and will that distinction survive the GHG Protocol's revision?
The location-based method calculates emissions using the average emissions intensity of the local grid, regardless of procurement choices, while the market-based method reflects a company's actual contracts, such as PPAs, RECs, and green tariffs. The consultation explored options from strengthening the criteria for market-based claims to reporting emissions and market instruments in separate, complementary statements. Both concepts will exist in some form, but companies should expect the requirements behind market-based claims to tighten.
When is the new Scope 2 Guidance expected to take effect, and what should companies do now to prepare?
Per the GHG Protocol's July 2026 development plan, a draft of the revised consolidated Corporate Standard is expected for public consultation in 2027, with a final published standard currently estimated for late 2028, and adoption timelines will follow publication. Companies should take action now. Energy efficiency, PPAs, green tariffs, and high-quality RECs reduce real emissions under any accounting regime. Building hourly consumption tracking and auditing the quality of existing REC portfolios now will make any future transition smoother.
The New Geothermal Energy: How EGS Unlocks Clean, Firm Power at Scale
Key Takeaways
- Enhanced geothermal systems (EGS) overcome traditional geothermal energy limitations by engineering subsurface conditions rather than searching for them, enabling widespread deployment of clean firm renewable power.
- Induced seismicity from high-pressure injection has caused major EGS project cancellations, but advanced approaches like Sage Geosystems’ gravity-assisted fracturing mitigate this risk by avoiding overpressures and directing fractures downward away from fault zones.
- Sage’s $97 million Series B financing, co-led by Ormat Technologies and Carbon Direct Capital, will fund the first commercial EGS facility at an existing Ormat plant—accelerating the transition from innovation to grid-scale deployment.
- For hyperscalers racing to power AI infrastructure, EGS offers a credible path to firm, 24/7 low-carbon power at scale.
Geothermal Energy: The Heat (And Pressure) Is On
For decades, geothermal energy has occupied a compelling yet narrow place in the clean energy landscape. It offers what the grid increasingly needs— firm, renewable, low-carbon power—yet has remained constrained by limited siting flexibility, high upfront resource risk, and persistent concerns around induced seismicity.
Enhanced geothermal systems (EGS) change that equation. Instead of searching for ideal subsurface conditions, EGS engineers them directly. In doing so, EGS rewrites the rules of where geothermal energy can be deployed and how far it can scale, with the potential to transform this historically niche resource into a widely deployable form of clean firm power.
One such solution, Sage Geosystems, uses a pressure-managed EGS approach to extract geothermal energy from engineered subsurface reservoirs, while explicitly addressing the seismicity risks that have constrained earlier projects.
How EGS Scales Geothermal Energy
Conventional geothermal power relies on a narrow set of subsurface conditions: sufficiently high temperatures, naturally occurring fluid, and enough permeability to circulate fluid through hot rock. In practice, those conditions coexist in only a few places—nearly all US commercial geothermal power generation is concentrated in California, Nevada, and a handful of sites across Utah and Hawaii.
EGS reduces this constraint by engineering permeability and fluid access rather than relying on their natural presence. While fluid access and permeability are harder to find, heat is not: the Earth’s natural geothermal gradient ensures that hot rock exists almost everywhere at sufficient depth.
By reducing the number of variables that must be discovered rather than designed, EGS expands siting flexibility and lowers the resource risk that has historically constrained geothermal development. The Department of Energy (DOE) estimates this approach could unlock more than 5,500 GW annually of US resource potential, which, when converted to electric power, is roughly comparable to the total installed power capacity of the US today.
One remaining challenge has been induced seismicity. When you inject pressurized water into rock and create fractures, you are adding lubrication to geological systems that have been static for millions of years. If those fractures propagate into existing fault zones, the faults can slip, producing earthquakes. Projects in Basel, Switzerland (2006) and Pohang, South Korea (2017) triggered magnitude 3.4 and 5.4 events, respectively, both leading to project cancellations and regulatory backlash that set the industry back years.
Sage's approach to EGS is designed to address this risk directly. Rather than relying on high-pressure hydraulic stimulation, Sage uses a gravity-assisted fracturing approach that helps avoid the high overpressures that can drive fault slip. Further, its approach biases fracture growth downward and away from shallow, critically stressed fault systems. By understanding causes and conditions, Sage aims to work with the subsurface, not against it.
This is not a minor technical detail. It is the difference between a technology that can scale with community acceptance and one that faces opposition at every site. For a hyperscaler evaluating geothermal offtake agreements, seismicity risk translates directly into permitting risk, timeline risk, and reputational risk.
The Clean Firm Power Gap Driving EGS Adoption
To understand why this matters, start with the problem hyperscalers are trying to solve. Solar and wind have scaled dramatically, but they face a structural limitation: they do not generate power when the sun is not shining or the wind is not blowing. Batteries help bridge short gaps, but current technology cannot economically cover multi-day periods of low renewable output. Nuclear provides firm generation, but faces permitting timelines that extend well past 2030.
This creates what might be called the 'clean firm power gap'—the difference between what hyperscalers need (24/7, low-carbon, scalable to gigawatts) and what current markets can supply. A single large AI training cluster can consume more than 100 MW continuously. Meta, Google, and Microsoft are planning data center campuses that will require gigawatts of capacity. The gap between demand and available clean firm power supply is widening, not narrowing.
Geothermal energy aligns closely with this need. Unlike solar or wind, geothermal power plants run continuously, with capacity factors that routinely exceed 90%. And unlike nuclear, geothermal projects can, in principle, be permitted and built on shorter timelines. The challenge has never been performance, rather availability: with the emergence of EGS, geothermal power is expanding where clean firm power can realistically be built, arriving at a moment when the grid’s need for dependable, low-carbon supply has never been greater.
Sage Raises $97 Million to Deploy Geothermal at Ormat Site
Sage Geosystems announced $97 million in Series B financing co-led by Ormat Technologies, the world's largest geothermal operator, and Carbon Direct Capital, a leading energy investing firm. Ormat will host Sage's first commercial facility at an existing Ormat plant.
The investment signals that EGS has become investable to the industry built to scale it. For Ormat, the logic is clear: conventional geothermal is constrained by resource availability. EGS expands the addressable market, but requires the subsurface capabilities that conventional operators don't typically possess by Sage does.
Why the Partnership Structure Works
EGS proposes that the fastest way to scalable power is to eliminate the resource risks that beset conventional geothermal projects. These risks do not simply disappear: they are transferred into subsurface and remain unproven at scale. Conventional operators locate naturally permeable reservoirs. EGS requires creating permeability in crystalline rock and managing induced seismicity risks that don't exist in hydrothermal systems. Sage is actively addressing the seismicity problem that ended projects in Basel and Pohang. Ormat brings everything else: turbines, plant operations, grid expertise, and six decades of operational knowledge.
Building at an existing Ormat site provides another advantage: established subsurface characterization, proven geological stability, and grid infrastructure already in place. For a first commercial deployment, this de-risks demonstration in ways greenfield sites cannot.
Both companies move faster together because the technical capabilities required to make EGS work don't naturally exist within a single organization.
What Hyperscaler Demand Means for the Power Sector
Meta's 150 MW power purchase agreement with Sage—announced in August 2024, with delivery planned for sites east of the Rocky Mountains—adds another dimension to this story. Hyperscalers have concluded that waiting for clean firm power technologies to mature before signing contracts means those technologies may not be available when needed. So they are becoming anchor customers, providing the revenue certainty that enables projects to secure financing.
For geothermal power specifically, this demand signal is transformative. Contracted offtake from creditworthy counterparties changes project economics fundamentally. It lowers the cost of capital, enables debt financing, and de-risks the investment case for additional capacity. The hyperscaler model has already accelerated deployment in solar, wind, and battery storage. Its application to geothermal power may prove similarly catalytic.
The Final Constraint
EGS is not a silver bullet, but it is beginning to look like a credible answer to a growing-problem: how to deliver clean firm power at scale, in more places, and on timelines that match accelerating demand. Advances in subsurface engineering are reducing the resource and seismicity risks that once confined geothermal to a narrow footprint, while partnerships with incumbent operators are showing how those advances can be integrated into existing energy infrastructure.
At the same time, hyperscalers are reshaping the market by signaling demand early, underwriting first deployments, and pulling technologies forward rather than waiting for them to mature on their own. That combination of technical progress, industrial adoption, and committed buyers is what turns promising concepts into deployable systems.
Whether EGS ultimately fulfills its potential will depend on repeatable and continued performance under real-world conditions. But the recent alignment of science, incumbents, and demand suggests EGS is moving beyond possibility and into a phase where the final constraint is no longer what the Earth can provide, but what the energy system is prepared to build.
Frequently Asked Questions
What is an enhanced geothermal system?
An enhanced geothermal system, or EGS, produces geothermal energy by engineering underground conditions needed to circulate fluid through hot rock. Unlike conventional geothermal projects, which depend on naturally occurring heat, fluids, and permeability occurring together, EGS can create or enhance permeability and fluid circulation, greatly expanding the locations where geothermal power may be developed.
Why is EGS important for data centers and AI infrastructure?
AI and data centers require large amounts of electricity around the clock, creating demand for power sources that are both low-carbon and firmly available. EGS could provide high capacity factor (greater than 90%), 24/7 clean electricity in more locations than conventional geothermal, making it a potentially valuable complement to intermittent renewable resources.
What is induced seismicity, and how are new EGS technologies addressing it?
Induced seismicity refers to earthquakes caused by changes in underground pressures or stresses caused by human activities. Earlier EGS projects demonstrated that high-pressure fluid injection can activate existing faults and in some cases triggered noticeable earthquakes and intense public backlash. New EGS approaches are being designed to better control reservoir pressure, fracture development, and proximity to faults, reducing seismicity risk while maintaining the fluid circulation needed to extract geothermal energy.
Can EGS be deployed anywhere?
EGS substantially expands geothermal’s geographic potential, but it does not make every location equally suitable. Projects still depend on factors including underground temperature, how deep they need to drill to access that temperature, water availability, seismic risk, and whether the rocks are of type suitable to hold and sustain engineered fracture networks.
From Capture-Ready to Capture-Committed: Decarbonizing Natural Gas with CCS
Key Takeaways
- Data centers are driving surging demand for new, firm electricity supply, accelerating natural gas-fired power generation.
- Carbon capture and storage (CCS) offers a practical way to balance long-term climate commitments with the need for new electricity generation in the near term.
- New natural gas-fired power plants must be capture-committed, not just capture-ready, potentially delivering power in 18 months and decarbonized power 18-24 months later.
- Capture-committed plants integrate planning and finance for the CO₂ capture, transport, and storage value chain from the start.
- Relae believes early investment in engineering, infrastructure, and community engagement is essential to meet capture commitments.
A New Era of Electricity Demand and Climate Pressure
The US and much of the developed world are experiencing profound growth in electricity demand. Two main forces are driving this trend: (1) the push to electrify existing uses, such as vehicles and heating, to improve energy security, enhance system efficiency, and reduce air pollution; and (2) the growth of energy-intensive sectors like manufacturing, telecommunications, and AI data centers.
Among these drivers, AI is creating unique demands that catalyze specific investments in electric power generation. Astonishing AI data center buildout, led by a handful of large technology firms (sometimes called “hyperscalers”) and their utility and construction partners, is accelerating energy consumption. These firms prioritize speed. When asked for their top five criteria for bringing new AI infrastructure online, one executive responded: “Speed, speed, speed, cost, and carbon emissions.”
Data centers require reliable, always-on power (referred to as “firm power”). This differs from other use cases, such as residential or commercial, which do not need the same amount of power across all hours. While hyperscalers and their partners are investing in renewables, nuclear, and geothermal energy at a remarkable pace, renewable resources alone do not yet meet the exploding demand for firm power.
Natural Gas Provides Firm Power but Drives Emissions Higher
The mismatch between data center power needs and variable renewable generation is fueling a boom in natural gas-fired power generation. The pipeline of new natural gas-fired power plants is enormous. Plants under construction in 2025 would, by themselves, add roughly 25 million tonnes of greenhouse gases each year to the air and oceans. The full suite of plants in planning is at least 10 times larger. Existing gas plants are also being used more and staying online longer.
This rapid buildout is creating tension with corporate climate goals. Hyperscalers remain seriously committed to reducing emissions, but their ability to hit those targets is undermined by the need to procure new, large-scale electricity generation quickly.
Carbon Capture Aligns with Data Center Energy Demands
Carbon capture and storage is one way to bridge the gap. Data centers operate continuously and may have the ability to shift or curtail load. This demand profile suits the duty cycles of natural gas turbines and CCS facilities well. The potential to reduce direct emissions is profound: today’s CCS technology can capture 95% or more of CO₂ emissions at competitive costs in many markets.
This has led to a resurging interest in the concept of capture-ready gas power generation. New natural gas power plants can be built and brought online in 18 months. In a capture-ready plant, the developers integrate the necessary interfaces and reserve additional land, water, and energy to enable a carbon capture project to be built at a future date. In favorable locations, carbon capture can be added to a capture-ready plant in 18-24 months.
However, past experience shows that capture-ready plants rarely deliver. The ambition and commitment of the developers were contingent on policy and market signals that were either too small or never materialized. While the base plant may have made economic sense in terms of energy value for investment, it does not appear anyone was willing to pay the climate premium for CCS.
As David Hawkins of the Natural Resource Defense Council famously said, “If your plant is capture ready, my driveway is Ferrari ready.” To bring David’s humorous analogy back to the specifics here: don’t build a new driveway without at least a downpayment on the car.
How to Build Capture-Committed Power Plants for CCS
A better approach is building capture-committed plants, namely facilities that integrate CCS from the start. To be capture-committed, project developers must:
- Identify geologic storage for the many millions of metric tons of CO2 that these plants will produce each year over the next 20-30 years.
- Plan reliable CO₂ transportation from power generation to geologic storage by pipeline, rail, barge, or truck.
- Engage credible vendors of carbon capture technology that serve their needs and fit their goals.
- Fund front-end engineering design (FEED) studies.
- Arrange, or help to arrange, financing for the construction, commissioning, and operation of all necessary components in the CO₂ capture, transportation, and storage value chain.
- Ensure natural gas supply has near-zero fugitive methane emissions.
- Partner with local and frontline stakeholders to incorporate community impact into project planning, design, and financing.
Capture-committed plants send strong market signals. They help build the permitting pathways and develop the workforce, infrastructure, and community acceptance needed to avoid extra expense and delays. Done well, early commitments and investments will likely create repeatable models that reduce build times and costs.
A Path Toward Power That’s Clean Firm and Future-Ready
Eventually more carbon-free power in the form of renewables, nuclear, and geothermal energy will be deployed to serve national and international electric load growth for all types of electrification. Over time, these resources will likely displace natural gas. Until then, hundreds of millions of tons of CO₂ will be emitted each year unless commitments are made to take tangible action now.
Capture-committed natural gas-fired plants offer a pragmatic solution. With the right planning, financing, and community engagement, they can provide reliable power without locking in emissions, and they can deliver enormous benefits compared to uncontrolled operation. Federal and state governments can accelerate this transition by honoring and increasing CCS grants, supporting shared infrastructure, and streamlining permitting for CCS plants as they have for other clean energy supplies. These investments will enable the construction of cleaner, more resilient power infrastructure for the industries driving demand, from AI data centers to heavy industry.
[cta]
Frequently Asked Questions
What is the difference between a capture-ready and a capture-committed power plant?
A capture-ready plant creates an option to add carbon capture in the future, whereas a capture-committed plant treats capture as part of the project from day one. In a capture-ready plant, developers install the right interfaces and reserve extra land, water, and energy, but nothing obligates them to build the capture project, ever. A capture-committed developer secures options for CO₂ transportation and geologic storage, relationships with capture equipment vendors, funding for engineering studies, and financing across the full value chain before the base plant comes online.
Why have capture-ready plants historically failed to add carbon capture?
Nobody was willing to pay the climate premium. Capture-ready developers built plants that made economic sense on energy value alone, then waited for policy and market signals to justify carbon capture. Those signals were either too weak or never arrived, so the option went unexercised and no capture project was ever designed. The base plant runs uncontrolled for decades while the reserved land sits empty. David Hawkins of the Natural Resources Defense Council captured the problem well: "If your plant is capture ready, my driveway is Ferrari ready." Preserving an option costs very little. Exercising it costs a great deal, and capture-ready facilities rarely came with the funding to do so.
If renewables, nuclear, and geothermal will eventually displace gas, why invest in CCS for gas plants now?
Because greenhouse gas emissions happen in the meantime. Gas plants being built today will operate for 20 to 30 years, long before carbon-free resources scale enough to displace them. Left uncontrolled, they will emit hundreds of millions of tons of CO₂ over that span. Capture on those plants avoids most of it. Today's technology can capture 95% or more of CO₂ emissions at competitive costs in many markets.
What can federal and state governments do to accelerate capture-committed projects?
Three kinds of support matter most: funding, infrastructure, and permitting. Governments should honor and extend existing CCS incentives. Developers make capture commitments years before any revenue arrives, so uncertainty in government funding undermines the confidence these projects require. Governments should also support shared CO₂ transport and storage infrastructure. Common pipelines, rail terminals, and storage hubs make it easier for developers to secure physical CO2 offtake. Finally, permitting for CCS should be streamlined the way it has been for other clean energy supplies. Permitting delay is a leading cause of cost overruns, and a capture-committed plant should be able to pursue capture and storage with the same intensity and speed as electricity generation.
The AI Bubble Debate Misses the Point: The Bottleneck Is Physical
Key Takeaways
- Agentic inference has changed the economics of AI. Tokens are becoming units of work and the economic driver is now the work produced, not token generation. Per-token costs are falling and the willingness to pay for work produced is rising; these two trends compound. This tailwind enhances AI economics and has spillover impacts on all layers of the AI stack.
- The AI infrastructure question has shifted from whether demand will show up to whether the physical stack can scale quickly enough. That stack includes power generation, grid capacity, interconnection, compute, memory, networking, cooling, siting, and community acceptance.
- Carbon Direct Capital and Relae (formerly Carbon Direct Inc.) have a differentiated view because the two entities work across both sides of the constraint: Relae advises hyperscalers and energy buyers on power and grid bottlenecks, while Carbon Direct Capital invests in the technologies that relieve those bottlenecks.
- Carbon Direct Capital sees better risk-adjusted returns investing in the physical foundations of AI, including clean firm power, energy system efficiency, data center efficiency, and inference-optimized compute, rather than chasing late-stage AI application valuations.
A Better Question Than "Is AI a Bubble?"
The most important development in AI economics is agentic AI turning tokens into work, a shift that reframes the bubble debate which dominated investor conversations, sell-side notes, and Chief Information Officer surveys through early 2026. Hyperscalers spent approximately US$380 billion on capital expenditure (capex) in 2025 and have guided to approximately US$720 billion of capex in 2026.¹ Carbon Direct Capital and Relae have worked together to build project-level models for both training and inference facilities to demystify the numbers and understand financial and technical sensitivities. The core finding was that the assets could be bankable using standard assumptions and that the binding constraints were physical, not financial. That conclusion has been reinforced in recent months by new developments.
Concretely, AI is moving from single prompts and answers to multi-step workflows that plan, reason, call tools, verify outputs, and keep state. This shift to inference is the structural successor to training in the initial AI capex cycle; it changes power requirements, time to power, and compute architectures all at once. Goldman Sachs estimates that agentic AI could drive a 24-fold increase, relative to a 2026 baseline, to roughly 120 quadrillion tokens per month globally by 2030 as per-token costs continue to fall. SemiAnalysis makes the same point from another angle: the value of frontier tokens has risen as agentic workflows become useful, while hardware and software improvements have reduced the cost of producing each token.
This does not mean every AI company is attractive, every data center project works, or every valuation is justified. It means the easy bubble framing is missing the more investable question. If token demand is compounding and the unit value of work produced is rising, the scarce resource is not abstract enthusiasm. It is the physical infrastructure required to turn that demand into work produced.
The Data Center Model Still Matters, But the Box is not a Black Box
Our internal modeling for an illustrative 167-megawatt inference data center using Nvidia Blackwell graphics processing unit (GPU) servers suggests the potential for high-teens percent equity returns under a defined set of assumptions.² We built a bottom-up underwriting, beginning with the number of users served per inference data center, assuming approximately how many tokens they will demand daily, and translating that token demand into compute needed based on industry-standard quantization and utilization rates. We then inferred the number of GPUs and servers needed to achieve the desired compute, which ultimately drove the total invested capital and power demand based on assumed thermal power designs and power usage effectiveness (PUE). On the revenue side, we used GPU-as-a-service rental rates as one proxy for the market value of compute capacity. A hyperscaler would not rent scarce compute externally if it had higher-value internal demand for that same capacity. As we will detail below, GPU rental prices have been steadily increasing on the back of inflecting inference demand.
This model is not the entire argument; it is the starting point. An important lesson is that power cost alone does not break data center economics. Electricity is slightly over 10% of total costs in our model: a 50% increase in power price reduces equity-level returns by less than 2%. Access to power, speed of interconnection, and equipment availability matter more. In other words, the economics of the model facility are workable, but only if the facility can be built and powered on the timeline customers need.
That is where most AI commentary remains too superficial. It treats the data center as a black box: capex goes in, tokens come out. That misses the bottlenecks inside and around the box. AI racks are moving far beyond traditional cloud power density. Cooling is shifting from air to liquid and two-phase systems. Networking and high-bandwidth memory become binding constraints in inference architectures. Grid interconnection queue wait times stretch to years. Communities can and do block projects. The technical, physical, and political constraints are increasingly the drivers of potential returns.
Inference Makes the Constraint Structural
While training is episodic, inference is recurring. A training run can be delayed, accelerated, or redesigned. Inference happens every time a user asks a question, a developer runs an agent, a business automates a workflow, or an application calls a model in the background. Agentic inference multiplies that load because one user action can become many model calls, validation loops, and memory reads; industry benchmarks show that agentic systems consume 5–30 times more tokens than a standard chat interaction.
Inference demand is also resilient in both directions. If efficiency gains lower the cost per token, more workflows become economic and total token consumption rises - the classic Jevons Paradox. However, token prices do not necessarily need to fall for inference spend to grow. As the economic unit shifts from tokens generated to work produced, customers may pay more per token when an agent delivers work produced that is worth more than the inference cost. Regardless of token price, tokens must all route through the same physical bottlenecks and we are seeing an increase in inference demand.
The architecture of inference is also changing. Some workloads will prioritize low-latency answers. Others, especially agentic work without a human waiting on every token, will prioritize memory, state, context, and cost per completed task. That means the AI infrastructure stack will become more heterogeneous, not less: XPUs (specialized AI accelerator chips), custom silicon, photonics, memory hierarchies, and edge or regional deployment models will all matter. The pricing data shows demand for more AI infrastructure overall: on-demand GPU rental capacity is effectively sold out across all chip generations in early 2026, with one-year Hopper H100 contract pricing rising 15–20% month-on-month through March 2026 and Blackwell B200 rental rates up 23% in March alone. When rental rates rise into a wave of new chip supply, supply is not catching up to demand.
Power Is Not One Constraint, It Is Several
Saying "AI is power constrained" is true, but not specific enough. The real problem has several layers. First, data centers need more electricity than many local grids can deliver on hyperscalers' timelines. Crucially, some grids can supply sufficient power but not continuously for 8,760 hours per year, conflicting with traditional assumptions about service reliability and leading to novel strategies around flexibility and intermittent self-supply. Second, the grid must be able to absorb large, fast-moving computational loads without creating reliability risks. Third, customers need energy procurement strategies that satisfy cost, reliability, climate, and public-acceptance requirements. Fourth, projects must get built in real communities, through real interconnection processes and real permitting fights. Power is not simply a commodity to purchase. It is an infrastructure development problem.
This is where Relae is directly relevant. Relae has assembled a team of scientific, engineering, and market experts to support a paying power and energy advisory practice serving hyperscalers, energy buyers, and power producers. Its work answers the questions customers are asking before the market prices them: how to get more capacity out of existing physical grid infrastructure; how to assess the costs and value of load flexibility through advanced modeling capabilities; how to make clean firm generation bankable; how to reduce data center energy intensity; how to validate "bring your own power" and "bring your own compute" structures; and how to build projects that communities will accept.
In the last twelve months alone, Relae has supported hyperscalers on bankability assessments for next-generation geothermal, scoped load-flexibility programs for multi-hundred-megawatt, single-customer sites, and modeled the carbon and reliability profile of "bring your own power" configurations against grid-tied baselines. Carbon Direct Capital leverages our network of technical experts at Relae, including power engineers, geologists, and electrochemists, to conduct credible technical diligence and to gain insights into early stage market trends and emerging preferences.
What Carbon Direct Capital Is Investing Behind
Our investment focus follows the bottlenecks. On the power side, we are investing in technologies that can deliver reliable power on AI timelines. Sage Geosystems is a next-generation geothermal platform with hyperscaler buy-in; Carbon Direct Capital co-led its US$97 million Series B with Ormat Technologies. We could not have made this investment without the deep expertise of the Relae research team which analyzed Sage's technical results to date to help underwrite future project feasibility. ION Clean Energy is a company that retrofits carbon capture technology onto natural gas combined cycle plants to create "blue electrons"; Relae is in active dialogue with multiple large power users on this topic. Carbon Direct Capital is also actively evaluating the enabling picks and shovels around geothermal, nuclear, fuel cells, and more.
On the data center efficiency side, we are investing in technologies that reduce the amount of power required for a unit of AI work. While it is encouraging to see incremental annual gains in chip efficiency, these are scaling far more slowly than compute demand, driving the need for more innovative technological solutions. As one example, a team at Relae helped us understand the fundamental energy consumption requirements of a standard complementary metal-oxide-semiconductor (CMOS) chip, and the potential of all-optical computing as an alternative. This led to Carbon Direct Capital investing in Neurophos, a photonic compute company targeting step-function gains in energy efficiency per chip that are beyond those achievable by existing GPUs. Carbon Direct Capital joined the company's US$110 million Series A alongside Gates Frontier, Microsoft's M12, Aramco Ventures, Bosch Ventures, and others. More broadly, we are studying other layers of the data center technology stack including networking, memory, cooling, and inference-optimized architectures because the next phase of AI infrastructure will not be solved by simply buying more of yesterday's hardware.
The Bear Case Deserves to Be Taken Seriously
There are real risks to the AI boom: Hyperscaler free cash flow can compress if capex grows faster than revenue. Model efficiency gains can reduce the amount of compute required for a given task. Training demand may be more episodic than the market assumes. Local opposition can slow or cancel data center and power projects. Some new data center capacity could become expensive cloud infrastructure competing on price if AI revenue disappoints.
Those risks are why Carbon Direct Capital frames this as an investment in constraints, not in AI enthusiasm. If efficiency improves, inference use cases expand and the bottleneck shifts to deployment, memory, power, and cost per unit of work produced. If training demand slows, inference and enterprise agents still require recurring capacity. If local grids cannot absorb load, technologies that unlock power, reduce energy intensity, or improve flexibility become more valuable. If some AI applications or model developers fail, the upstream physical bottlenecks remain for the rest.
The Investment Conclusion
The AI infrastructure opportunity sits at the intersection of frontier technology risk, project-finance economics, and energy-system engineering. Underwriting this opportunity well requires addressing all three at once; Carbon Direct Capital is built to do just that. The technical team at Relae has a pulse on emerging stakeholder preferences and scientific breakthroughs, understands novel technologies deeply, and is highly experienced in conducting detailed technical diligence to ensure that projects are viable and scalable. Carbon Direct Capital combines these market and technical insights with our commercial underwriting to facilitate new investments. We are not picking AI winners. We are not picking pure energy assets. We are investing in the companies and technologies that have to exist for AI to sustainably scale.
Frequently Asked Questions
Is the AI capex boom a bubble? While valuations vary, token demand and physical infrastructure needs are real and compounding. The correct question to ask is not whether AI is a bubble, but what the binding constraints are. Our modeling shows that constraints are physical, not financial.
What are the real constraints on AI infrastructure growth right now? AI infrastructure growth is constrained by power availability, grid capacity, and interconnection speed, not capital availability.
Why does inference matter more than training for long-term AI power demand? Inference is recurring and grows with AI usage, it is not episodic like training runs.
What is Carbon Direct Capital investing in, and why? We are investing in clean firm power, energy system efficiency, data center efficiency, and inference-optimized compute—the physical bottlenecks rather than application-layer valuations.
Disclaimer
Carbon Direct Capital Management LLC is an investment adviser registered with the US Securities and Exchange Commission (SEC). Registration as an investment adviser does not imply any particular level of skill or training. Additional information about Carbon Direct Capital Management LLC, including our Form ADV Part 2A Brochure, is available on the SEC's website at adviserinfo.sec.gov.
This content is provided for informational purposes only and should not be construed as or relied upon as investment, legal, tax, or other advice. You should consult your own advisers regarding legal, business, tax, and other matters related to any investment. Any projections, estimates, forecasts, targets, prospects, or opinions expressed are subject to change without notice and may differ from opinions expressed by other employees of Carbon Direct Capital Management LLC, its affiliates, investors, portfolio companies and other individuals, groups or entities. Certain information contained herein may have been obtained from third-party sources believed to be reliable; however, Carbon Direct Capital Management LLC makes no representations about the accuracy or completeness of any such information or its appropriateness for any given situation. Any investments or portfolio companies mentioned are not representative of all investments made by funds managed by Carbon Direct Capital Management LLC, and there can be no assurance that any investment will be profitable or that future investments will have similar characteristics or results. Past performance is not indicative of future results. The content speaks only as of the date indicated. This content does not constitute an offer to sell or a solicitation of an offer to buy any security. Any such offering will be made only pursuant to formal offering documents.
AI Scale and Climate Commitments: A 2026 Outlook
The AI and Climate Execution Challenge
Data center energy capacity in the US is projected to increase from 25 GW to 120 GW by 2030—a fivefold increase. Hyperscalers are projected to invest $7 trillion globally in data center infrastructure through 2030, with approximately $2.8 trillion invested in the US.
While 2025 was defined by a 'scale at all costs' scramble for compute, in 2026, the new mandate is responsible scale: reconciling voracious power demands with aggressive net-zero commitments and rising energy costs.
Grid constraints determine the geography and velocity of growth, forcing companies into complex trade-offs between speed-to-market and “clean, firm” power, which can take years to develop. Evolving carbon accounting rules are shifting procurement strategies and infrastructure choices at this trillion-dollar scale, creating a “carbon debt”—embodied emissions that will stay on the books for decades. In 2026, the competitive advantage likely belongs to those who integrate power, hardware, and climate strategy from day one.
Powering AI: Grid Reliability, Constraints, and Interconnection
Grid infrastructure faces reliability challenges from aging systems and capacity constraints. Interconnection queues stretch three to five years for renewables, while large electrical load interconnection lacks consistent standards.
Federal Regulatory Response
The federal government is moving to standardize these processes, with a critical decision point in 2026. For companies planning data center deployments in 2026, understanding these regulatory shifts is likely essential to realistic timeline and site selection planning.
On October 30, 2025, the US Department of Energy (DOE) leveraged Section 403(a) of the DOE Organization Act to direct the Federal Energy Regulatory Commission (FERC) to issue a rulemaking to “ensure efficient, timely, and non-discriminatory load interconnections” for large (>20 MW) electrical loads.
By April 30, 2026, FERC is expected to issue a final rule on large electrical load interconnections for grid operators, providing federal regulations for approval pathways, timelines, and rates.
Public comments on DOE’s advanced notice of proposed rulemaking were due on December 5, 2025, and grid operators, utilities, NGOs, and customers submitted over 150 comments reflecting a wide range of perspectives.
While federal standardization should reduce procedural uncertainty, it doesn't create new grid capacity. Even with clearer approval pathways, the underlying supply-demand mismatch remains a primary gating factor for growth.
Bridging the Supply-Demand Gap
Data center energy demand is surging, but new clean electricity generation takes years to build. This mismatch between accelerating demand and slow-building supply is forcing the industry to pursue solutions on two timelines: near-term load flexibility strategies that unlock existing capacity, and long-term generation investments that build new power supply.
Load Flexibility: Near-Term Grid Access
Load flexibility is emerging as a possible path to faster grid connection. Oracle, NVIDIA, Emerald AI, and Salt River Project's joint research demonstrated 25% power reduction during peak hours through workload tiering. The demonstration shows that if data centers reduce consumption during peak times (roughly 1% of the year), it unlocks 126 GW of currently constrained capacity that could be available now.
Large power loads increasingly face incentives or mandates to demonstrate flexibility as part of interconnection agreements, making this an access requirement, not an optional efficiency measure. For example, Senate Bill 6 in Texas mandates that data centers and other large loads must reduce their consumption during certain grid peak times. Many other state legislatures are passing legislation that will impact data centers.
Storage has shifted from smoothing renewables to enabling multiple strategies: making intermittent renewables firmer, providing grid reliability services, and supporting 24/7 matching. Storage may emerge as a solution to allow data centers to reduce grid consumption during peak hours while maintaining operations.
Relae helps clients design load flexibility strategies under evolving regulatory frameworks: evaluating behind-the-meter generation options, sizing storage for peak reduction scenarios, and structuring interconnection configurations that preserve optionality across accounting methodologies.
Clean Firm Power: Long-Term Generation
Hyperscalers remain committed to clean, firm generation that’s reliable: power that's both low-carbon and dispatchable 24/7. Natural gas with carbon capture and storage (CCS) is emerging as a critical bridge technology. Google's 400 MW CCS power agreement with Broadwing, expected online in 2029, demonstrates commercial demand at scale.
In our analysis evaluating CCS pathways, commercial viability depends on rigorous assessment of permitting timelines, capital and operating costs, storage geology, vendor compatibility, and 45Q tax credit optimization. Execution has been most prevalent where technology intersects with regulatory approval and storage access.
Hyperscalers are also investing across geothermal, nuclear, including Small Modular Reactors (SMR), hydrogen, and fusion. Long-duration energy storage has also been an area of focus. Each has different risk profiles and opportunities across technical maturity, permitting, commercial viability, emission accounting methodology, dispatchability, and political support.
Evaluating these pathways requires multi-dimensional frameworks. Each technology faces distinct challenges: SMRs struggle with execution complexity, geothermal with extended development periods, and hydrogen with production-dependent carbon intensity. Tax credit eligibility (particularly 45Q for CCS and 45V for hydrogen) significantly impacts project economics.
Both power generation and data center Infrastructure site selection require integrating environmental and social vulnerability data to avoid community conflicts that delay or stop projects.
Power Accounting Rules Determine Clean Energy Procurement
The Greenhouse Gas (GHG) Protocol extended the public consultation period for proposed scope 2 guidance changes to January 31, 2026. The results will determine clean energy procurement strategies and the carbon value of load flexibility for the next decade.
The proposed shift in electricity emissions accounting could increase clean energy procurement costs for buyers. The accounting methodological debates matter for hyperscalers: 24×7 energy matching versus carbon matching. The issues of deliverability (being located in the same grid region) and additionality (being new, rather than repurposed, generation) are also hotly debated.
These different frameworks strongly influence whether natural gas with CCS, nuclear, geothermal, or battery-backed renewables are considered optimal for a site, and whether load flexibility has carbon value.
Companies need to model scenarios across advanced power emissions methodologies, evaluating portfolio costs and carbon performance before final standards are published in 2027. Companies are also signing forward renewable energy certificate contracts (RECs) and structuring power purchase agreements (PPAs) now to preserve optionality across scenarios.
AI Infrastructure Emissions at Scale
Data center construction creates substantial scope 3 emissions, and their relative importance depends on grid carbon intensity. For facilities powered by average-carbon grids, scope 2 operational emissions dominate. But for data centers powered by very low-carbon electricity (renewables or nuclear), scope 3 embodied emissions can represent 40% of total lifetime greenhouse gas emissions.
In AI data centers, IT equipment drives the majority of embodied emissions. Chips and memory account for 67%, followed by structural materials at 17%, with server power supplies, aluminum, and other components comprising the final 16%.
Direct procurement of low-carbon materials faces constraints: limited supply, geographic concentration, and contracting complexity. Environmental Attribute Credits (EACs) provide an interim pathway by decoupling environmental benefits from physical materials, but require rigorous quality standards and verification to ensure real emissions reductions.
Our high-quality EAC criteria, developed with Microsoft, establish standards that separate market-making from greenwashing. Levelized Cost of Carbon Abatement frameworks make materials decisions comparable to power decisions, treating infrastructure decarbonization as portfolio optimization, not separate workstreams.
Carbon Removal: Addressing Residual Emissions
Complete supply chain decarbonization by 2030 isn't feasible. Despite aggressive efforts to procure clean power and reduce construction emissions, residual emissions will remain significant. For hyperscalers with net-zero commitments, carbon dioxide removal (CDR) has shifted from an optional component to a structural necessity. Microsoft remains the world's largest CDR buyer, and Google increased purchases 14-fold from 2023 to 2024.
CDR credit quality varies widely. Companies must apply science-based principles to evaluate credits. Our Criteria for High-Quality CDR, developed in collaboration with Microsoft, establishes six science-based principles for evaluating credits—critical as emerging hyperscaler and other corporate demand high-integrity supply.
AI and Climate: Looking Ahead
The window for strategic maneuvering is narrow. The AI infrastructure buildout is happening now, and the decisions made in 2026 will impact a company’s cost structure and carbon profile for years.
Companies treating power, infrastructure, and decarbonization as separate workstreams will face compounding constraints. The winners of the AI era will be those who integrate power, infrastructure, and carbon strategy into a single, cohesive system.