Steel Decarbonization: How EACs Scale Low-Carbon Production by 2030
Key Takeaways
- Decarbonizing steel is key to meeting ambitious climate targets in the face of rapidly expanding AI infrastructure as well as broader infrastructure growth.
- The gap between corporate climate ambitions and near-term commercial reality is widening. Despite strong demand signals from hyperscalers and other major buyers, leading producers have recently canceled or delayed flagship green steel projects, citing high energy costs, slow hydrogen market development, and unfavorable policy environments.
- Bridging this gap requires significant capital investment and supporting mechanisms to scale low-carbon technologies. Environmental attribute certificates offer an effective mechanism to channel capital toward transformative, low-carbon steel projects, supporting technology scale-up, as well as providing a way for buyers to meet their emissions reduction targets.
- To protect the credibility of environmental attribute certificates as a market mechanism for decarbonization, projects should seek to meet rigorous quality criteria such as additionality, verifiability, and catalytic impact.
Forging New Climate Ambitions for Steel Production
Decarbonizing steel production is essential to meet global climate targets. Steel production accounts for approximately 7–9% of global CO2 emissions. This is driven chiefly by coal-based primary steelmaking, which still accounts for the majority of global production. Globally, at least 1.8 billion tonnes of crude steel were produced in 2025 to serve a broad array of industries including real estate, infrastructure, automotive, and data center construction.
As hyperscalers race to build the infrastructure underpinning the AI revolution, steel demand for data center construction, and associated energy infrastructure, is increasing. While the relative share of data center demand for steel versus global steel demand is small, the need for approximately 20,000 tonnes of steel per data center has a material impact on hyperscaler’s public climate commitments. Microsoft, Meta, and other large technology companies have set ambitious 2030 climate targets that include their scope 3 emissions. The embodied carbon of the steel used to build their data centers sits squarely in scope 3.
Hyperscaler’s climate commitments have generated sector-specific demand for decarbonized steel, presenting an opportunity to affect steel decarbonization more broadly. Despite this demand, the supply of low-carbon steel remains limited. The industry faces significant scale-up challenges due to the diffuse nature of demand and the nascent market. Catalyzing growth in decarbonized steel production will require market innovations and new production pathways designed to overcome these challenges. Credible environmental attribute certificates can help bridge the gap between today’s market and tomorrow’s low-carbon steel sector.
What is an Environmental Attribute Certificate?
An environmental attribute certificate (EAC) represents the environmental attributes of a product that can be unbundled and transacted separately from the underlying physical commodity. The most widely used EACs today are renewable energy certificates (RECs), which track the environmental attributes of renewable electricity. The same concept can also be applied to steel and iron, as well as to materials such as cement and concrete.
In a book and claim model, a steel producer can implement a verified emissions reduction intervention, quantify the resulting lowered carbon intensity per tonne of steel produced, and convert that into tradeable certificates. Buyers can then purchase those certificates to support the deployment of low-carbon steelmaking capacity in cases where direct procurement of low-carbon steel is currently impractical due to geographic, contracting, or scheduling incompatibilities.
EACs are distinct from carbon credits. They do not represent emissions reduced or avoided relative to a counterfactual; they represent the intrinsic carbon intensity of the material produced, measured through a life cycle assessment.
Decarbonizing Steel Requires Significant Capital and Infrastructure Deployment
Steel Production Today
Steel is currently made via three main production routes. About 71% of the world’s steel is produced through the blast furnace–basic oxygen furnace (BF-BOF) route, which emits an average of 2.33 tonnes of carbon dioxide (tCO2) per tonne of crude steel. A further 24% is produced using scrap-based electric arc furnaces (EAFs), which emit 0.68 tCO2 per tonne on average—far lower, but still dependent on the carbon intensity of grid electricity. The remaining roughly 5% uses direct reduced iron combined with an EAF (DRI-EAF), typically using natural gas, emitting 1.37 tCO₂ per tonne on average.
While increasing scrap-based production is a critical decarbonization lever, scrap availability is limited. Primary steel production, which uses iron ore as the main feedstock rather than recycled scrap, will remain necessary at large volumes through 2050. This makes it essential to decarbonize ore-based pathways, especially ironmaking: the step where iron ore is reduced to iron and where most emissions occur.
Decarbonizing ore-based steel production requires one of three fundamental interventions: (1) replacing coal and natural gas with low-carbon fuels such as hydrogen or bio-coke, (2) electrifying ironmaking directly, or (3) capturing and storing the CO2 generated from fossil-fuel-based processes. All three involve significant capital expenditure and dependencies on infrastructure that is not yet in place at the necessary scale. As a result, the energy and cost challenge is substantial.
Low-Carbon Steel: Emerging Pathways
A range of transformative technological pathways are currently in development to overcome these barriers, offering the potential to deliver deep decarbonization to the steel industry exceeding 90% by 2050:
- Hydrogen-based DRI-EAF: Using green hydrogen instead of natural gas within the DRI process provides a pathway to significantly lower the carbon intensity of ironmaking. Producers such as Stegra are deploying commercial-scale facilities designed to utilize 100% green hydrogen to reduce iron ore.
- Electrifying ironmaking:
- Molten oxide electrolysis: Boston Metal is commercializing a process that uses electricity to directly convert iron ore to molten metal through electrolysis at high temperature, eliminating the need for hydrogen or carbon reductants entirely.
- Low-temperature electrowinning: Colorado-based startup Electra uses renewable electricity to extract iron from ore via an aqueous electrochemical process that operates at near-ambient temperature.
- Carbon capture and storage (CCS): For blast furnaces and DRI plants with long remaining lifetimes, retrofitting with CCS technology can significantly reduce emissions. With new high-emitting capacity still being built, and assets expected to operate for decades, integrating CCS will be essential to avoid long-term carbon lock-in and to decarbonize these facilities over time. To date, commercial-scale deployment remains limited. The Al Reyadah facility at Emirates Steel is the only project currently capturing CO2 from a DRI process at scale, though a handful of other large-scale projects have entered the development pipeline.
Progress and Setbacks: A Mixed Picture
The past year sent contradictory signals about the pace of steel decarbonization. On the demand side, technology companies with ambitious climate targets are actively signaling their intent to procure near-zero steel and support its development.
In September 2025, Microsoft and Stegra announced a landmark agreement that combines a physical supply deal for low-carbon steel with a separate EAC purchase agreement. Around the same time, Meta announced an agreement with Electra to purchase EACs tied to the startup’s clean iron production, becoming one of the first buyers to use the EAC model for an entirely novel, pre-commercial ironmaking technology. Nucor, the largest US steelmaker, also entered into a physical iron purchase agreement with Electra.
Despite these demand signals, the industry has experienced significant setbacks. A series of low-carbon steel project cancellations and delays has raised questions about the pace and viability of the steel transition, especially due to the high costs associated with green hydrogen production.
At present, the green premium for most low-carbon steel remains too high for buyers. A combination of sustained policy support, long-term demand signals from buyers willing to pay more, and scaling of supporting industries, such as green hydrogen production, is necessary for the low-carbon steel industry to be successful in the long run.
How EACs Can Bridge the Funding Gap in Steel
EACs unbundle low-carbon steel attributes from the physical material, reducing the friction between buyers who are willing to pay a green premium and geographic or logistical constraints that may inhibit physical offtake. Buyers, such as hyperscalers procuring conventional steel for data center construction in locations where low-carbon steel is not yet available, can purchase these certificates to support the development of low-carbon capacity, attribute lower-carbon production to their steel use via a market-based mechanism, and advance toward their scope 3 targets.
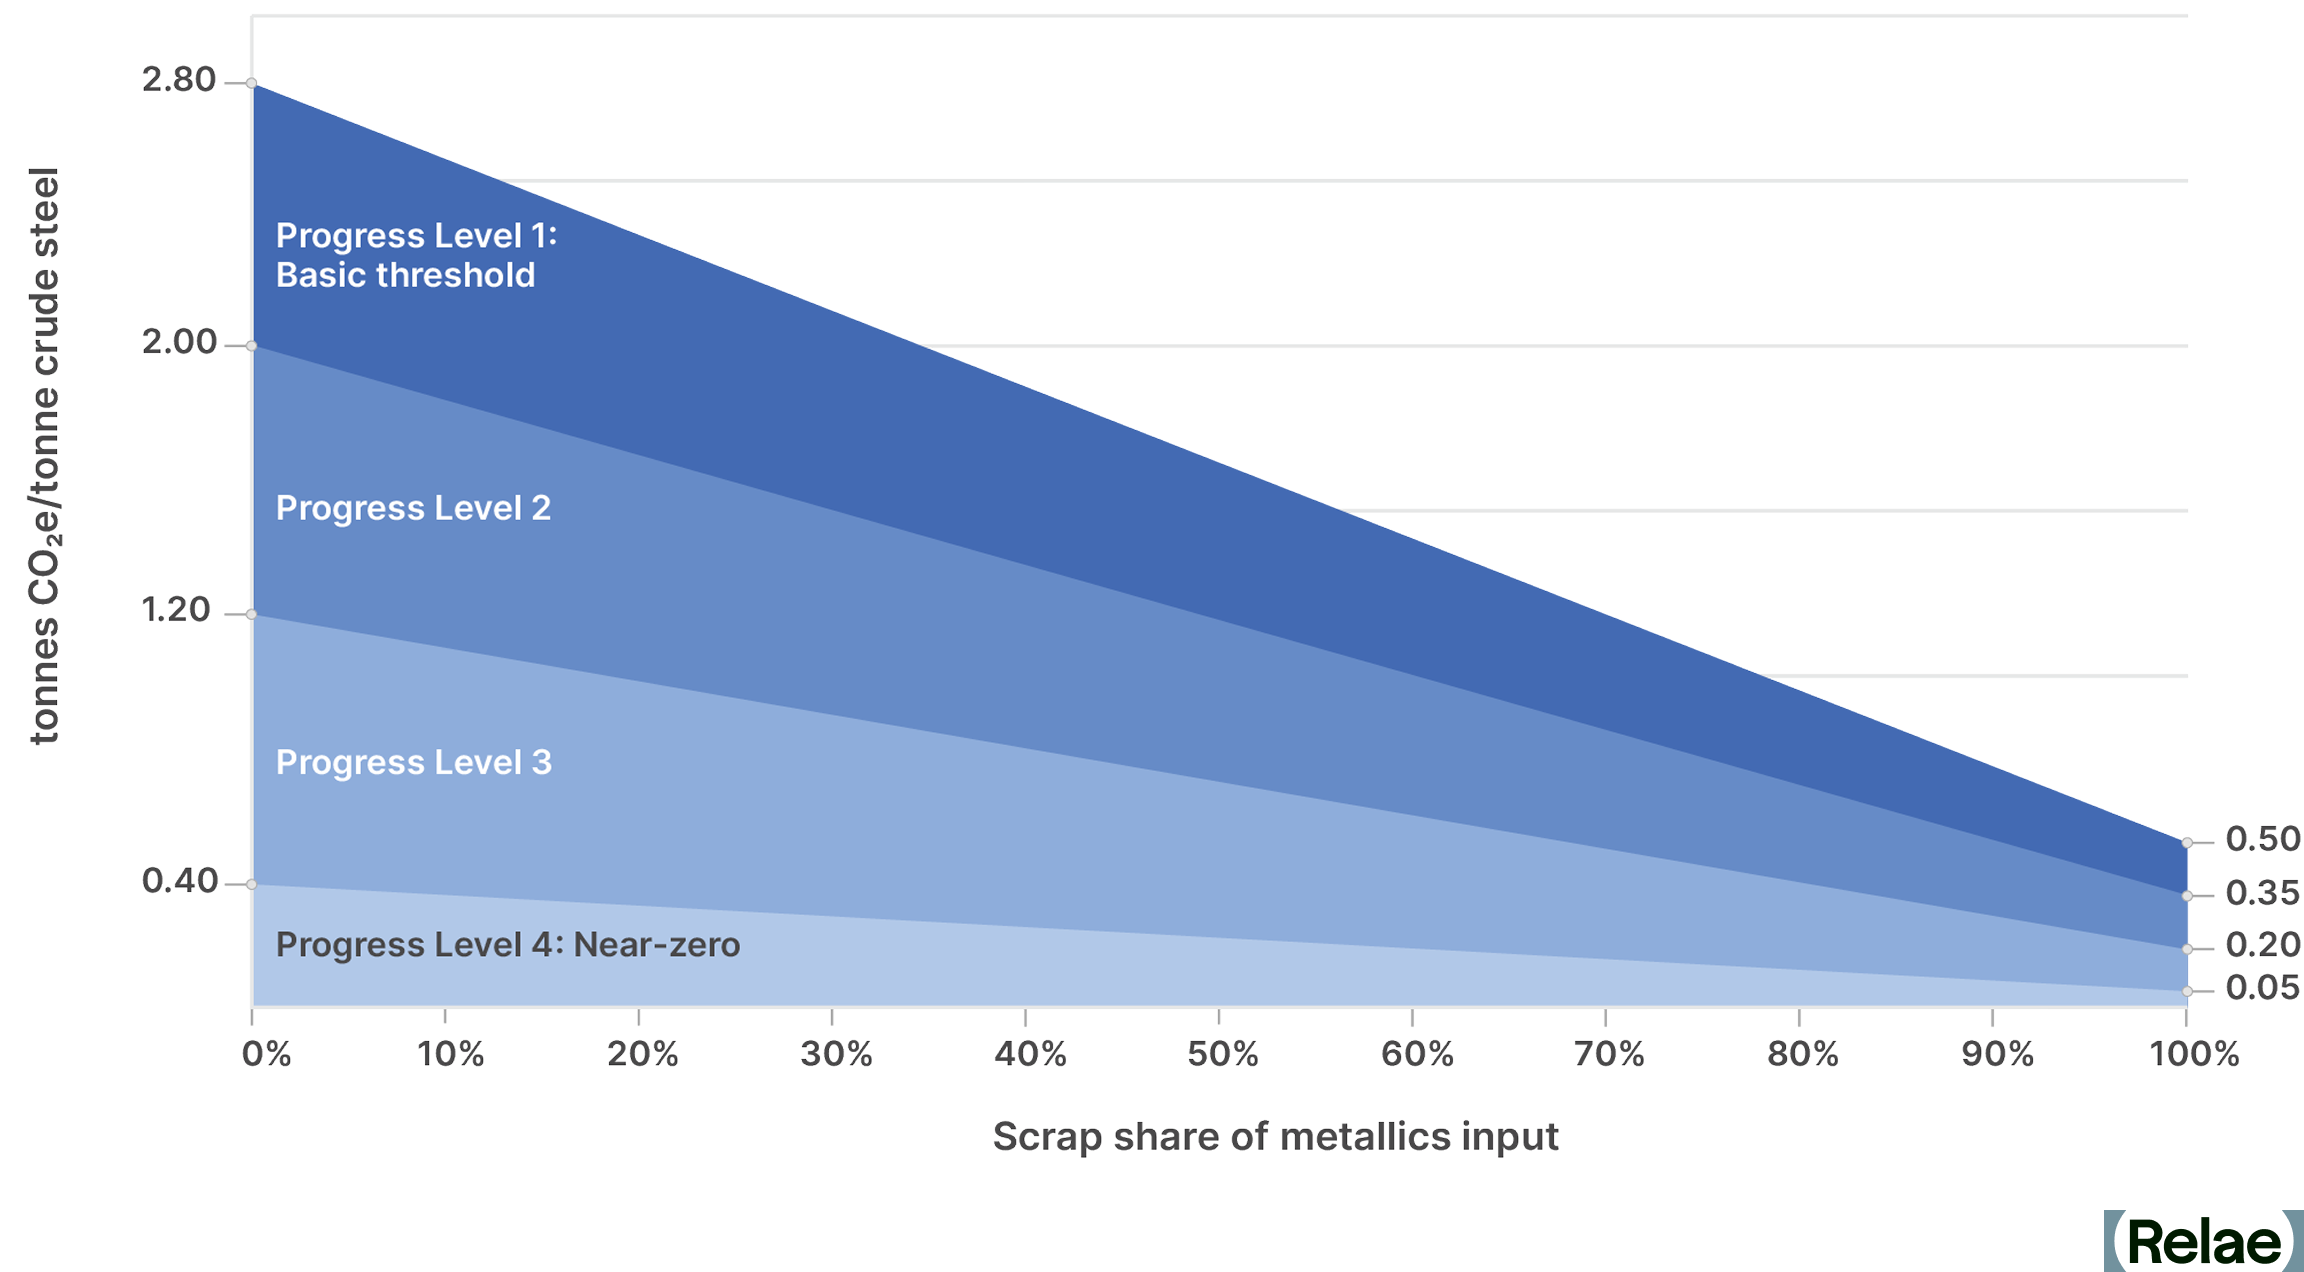
A primary objective of the Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors, jointly developed by Relae (formerly Carbon Direct) and Microsoft, is to establish high-integrity standards for the EAC market in these sectors. For steel EACs, that means demonstrating significant emissions reduction performance by reaching at least Progress Level 2 in the ResponsibleSteel Decarbonization Progress Levels framework, and aiming to achieve Progress Level 3 by 2030. ResponsibleSteel’s scrap-variable benchmark provides a technology-neutral mechanism to evaluate emissions reduction performance by accounting for the specific proportion of scrap used.
EACs for steel are designed to be catalytic. Rather than supporting incremental improvements that are already becoming cost-competitive, they should target transformative capital changes, such as replacing BF-BOF routes with DRI-EAF, adopting low-carbon hydrogen in DRI processes, or deploying novel ironmaking technologies. Multi-year purchase agreements are particularly powerful because they provide the investment certainty that first-of-a-kind projects need to access capital at a lower cost.
What this Means for Buyers and Suppliers of Low-Carbon Steel
Whether you are producing or procuring steel, EACs are only one part of a broader decarbonization strategy. For buyers with significant emissions from steel, and other building materials such as cement and concrete, EACs can be a powerful tool to help advance scope 3 reduction goals where supply for physical low-carbon materials is limited. Suppliers can complement commercialization strategies for low-carbon materials by using EACs to monetize emissions reductions, generate additional revenue to support decarbonization investments, and help scale markets for low-carbon materials. Navigating the steel market requires decisions at the intersection of technical feasibility, greenhouse gas accounting, and capital strategy. Key considerations include:
- Greenhouse gas accounting and reportability: Cradle-to-gate emissions for steel production must be tracked using life cycle assessments and should strive for interoperability with environmental product declarations (EPDs). EAC transactions must be reported transparently, especially given the absence of formal market standards at this stage.
- Additionality and catalytic impact: EAC purchases must demonstrably support projects that would not proceed without financial support from the EAC market mechanism, and projects should have a credible pathway toward the near-zero (Progress Level 4) threshold on the ResponsibleSteel framework.
- Avoiding double counting: EAC buyers must verify that the environmental attributes they purchase are not also being claimed by the physical product buyer via an EPD.
FAQs
What is an environmental attribute certificate (EAC) for steel?
An EAC represents the environmental attributes of low-carbon steel, unbundled from the physical material itself, so a producer can quantify a verified reduction in carbon intensity per tonne and sell that value as a separate, tradeable certificate. Buyers can purchase EACs to support low-carbon steel production while still working toward their own emissions targets.
How is an EAC different from a carbon credit?
An EAC reflects the intrinsic carbon intensity of the material itself, measured through a life cycle assessment. That's different from a carbon credit, which represents carbon dioxide actively avoided, reduced or removed from the atmosphere relative to a baseline.
How are AI data centers impacting the demand for low-carbon steel?
Data centers use roughly 20,000 tonnes of steel each, and as hyperscalers build out AI infrastructure, that steel use counts toward their scope 3 emissions and public climate targets. That's turned data center construction into a meaningful driver of demand for low-carbon steel, even though supply remains limited.
What makes an EAC credible enough to count toward a company's emissions goals?
A credible steel EAC needs to meet criteria like additionality (the project wouldn't happen without the EAC revenue), verifiability through life cycle assessment, and catalytic impact toward transformative technology rather than incremental gains. Relae (formerly Carbon Direct) and Microsoft jointly developed criteria for high-quality EACs in the steel and concrete sectors, which set a threshold of at least Progress Level 2 on the ResponsibleSteel Decarbonization framework today, rising to Progress Level 3 by 2030.
Can a producer sell an EAC and also get credit for the physical steel elsewhere?
No. EAC producers need to confirm the environmental attributes they're selling aren't also being claimed by whoever buys the physical steel through an environmental product declaration; otherwise the same emissions reduction gets counted twice.
Environmental Markets
Relae guides buyers, investors, producers, and project developers through the market instruments designed to mitigate environmental impacts. Our work combines science-based quality criteria, project-level diligence, market and policy intelligence, and commercial execution to help you make defensible decisions, capture green premiums, and finance the clean energy transition.
Criteria for High-Quality Environmental Attribute Certificates


David Lluis Madrid
David Lluis Madrid

<p>David helps clients understand more about the most impactful and cost-effective carbon reduction and removal actions they could take.</p><p>Prior to joining Relae, David was the lead research analyst on carbon capture, utilization and storage at BloombergNEF, where he wrote the company’s CCS market outlooks and specific research pieces on direct air capture, CO₂-to-fuels and CO₂ capture cost drivers.</p>
<p>Imperial Excellence Scholarship</p>
John Dees, PhD
John Dees, PhD
,
Dr. Dees leads Relae's scientific advisory practice for the transportation fuel and industrial commodity sectors. He brings interdisciplinary expertise to the bioeconomy and bioenergy systems, bridging industrial ecology, economics, and climate policy to drive decarbonization. As a researcher, Dr. Dees explored the role of biomass as both an energy feedstock and a substrate for carbon removal (BiCRS), integrating technoeconomic analysis and life cycle assessment with market-enabling policy. His work has been featured in leading academic journals, including Environmental Science and Technology, Green Chemistry, and ES&T Water. Over a two-year collaboration with the Energy Systems team at Lawrence Livermore National Laboratory, Dr. Dees was a lead contributor to the US DRIVE Net-Zero Carbon Fuels Technical Analysis, evaluating the potential for ethanol decarbonization and the climate impacts of sustainable aviation fuels (SAF). At Relae, he directs an interdisciplinary team to provide strategic guidance at the intersection of transport fuels and heavy industry. He has spearheaded the development of industry-standard resources, including the Sustainable Aviation Fuel Primer and the Criteria for High-Quality Environmental Attribute Certificates for the steel and concrete sectors.
Graduate Fellow (2015-2020), NSF; Udall Scholar (2014), Udall Foundation
What to Read Next
The 2026 Criteria: Designing and Delivering High-Quality Carbon Removal
Key Takeaways
- High-quality carbon dioxide removal (CDR) projects require robust project management and oversight to deliver credits on time and at the promised volume; delivery risk is a distinct concern that quality standards alone don't catch.
- The sixth edition of the Criteria for High-Quality Carbon Dioxide Removal is the first to provide an approach to evaluating both credit quality and delivery risk, adding a new delivery risk appendix built around the TECOP framework: technical, economic, commercial, organizational, and political risk.
- The 2026 Criteria provides a framework for developers, investors, and buyers to evaluate both project quality and delivery risk.
- This year's update draws on 170 new diligence reports from 2025 and the input of more than 60 subject matter experts, building on a foundation of six years of lessons from professional diligence across hundreds of real-world CDR projects.
The Criteria Create a Shared Standard for Credit Quality
Relae (formerly Carbon Direct) first launched the Criteria for High-Quality Carbon Dioxide Removal (the Criteria) in collaboration with Microsoft in 2021 to help rapidly and justly scale the development of high-quality carbon dioxide removal (CDR) credits. The market didn't yet have a shared definition of what "high-quality" meant, so we laid out transparent, science-based benchmarks that gave developers, investors, and buyers a common foundation to work from. Every year since, we have gone back and sharpened those benchmarks so that they keep pace with the quickly evolving industry.
But a shared definition of quality doesn't guarantee the delivery of credits as planned. The 2026 edition is the first to tackle that gap directly, pairing the Criteria's quality benchmarks with a new framework for evaluating delivery risk.
The Six Principles of High-Quality Carbon Removal
The Criteria defines six science-based principles that apply across engineered, hybrid, and nature-based CDR approaches:
- Social harms, benefits, and environmental justice: The extent to which the project prevents new social harms to people and communities, reduces existing harms, and provides meaningful benefits distribution.
- Environmental harms and benefits: The extent to which the project minimizes and mitigates environmental harms, as well as provides environmental benefits.
- Additionality and baselines: The evidence that the project’s carbon removal would not have occurred without carbon finance.
- Measurement, monitoring, reporting, and verification (MMRV): The ability to accurately quantify carbon removal in a repeatable and verifiable way, and to develop a plan for long-term monitoring of the project.
- Durability: The likelihood that removed carbon remains stored over time, with mechanisms in place to mitigate reversal risk.
- Leakage: The extent to which project activities cause increased emissions elsewhere.
These principles provide a consistent foundation for carbon removal procurement, evaluation, and project benchmarking.
[cta]
Supporting the Delivery of High-Quality CDR Credits
"Projects must work better operationally and be more commercial. Quality and delivery risk shape a project's risk profile at every point in its life, and this edition of the Criteria is the first to give buyers a way to judge both at once." Dr. Julio Friedmann, Chief Scientist, Relae
Designing projects to meet high-quality CDR criteria is only part of the challenge. Effective project planning, management, and execution are also essential to ensure that high-quality CDR tonnes successfully reach the market as planned. As discussed in CDR 2.0: Five Pillars of Successful Project Deployment and Delivery, managing delivery risk requires developers, investors, and buyers to understand the risks that can affect project success and align on how these risks are assessed and mitigated.
To support this alignment, the 2026 Criteria introduced a new Delivery Risk Appendix, which establishes a common framework and language for identifying and evaluating key delivery risks for the first time. Drawing on our broader observations of the carbon removal market and established approaches to project risk management, the appendix highlights common delivery risks across two broad CDR project types: open systems and closed systems. It organizes these risks into five categories: technical, economic, commercial, organizational, and political factors, also known as the TECOP framework.
The TECOP Framework for CDR Delivery Risk
- Technical delivery risks are associated with the technical feasibility of the project design, implementation, and long-term operation of the project
- Economic delivery risks are associated with the project’s financing structure, financial modeling assumptions, and expenditure profile
- Commercial delivery risk reflects the extent to which a project's purchase agreements, supply arrangements, and key contractual relationships are secured or well-advanced.
- Organizational delivery risks center on the project developer's capacity and capability to successfully plan, execute, and manage a project of the appropriate size and complexity.
- Political delivery risks are associated with governance, policies, and potential changes in regulatory environments, as well as the local communities’ perception of and willingness to participate in projects.
New Additions to the 2026 Criteria
Since publishing the 2025 Criteria, Relae has conducted an additional 170 diligence reports across established and emerging CDR pathways, ranging from reforestation and enhanced rock weathering (ERW) to direct air capture (DAC). To date, less than 10% of all 900+ projects the team has reviewed have met the bar for high-quality. These diligence efforts, together with insights from market analysis and ongoing synthesis of the latest scientific and technical literature, have deepened our understanding of how CDR project quality has evolved over the past year.
The 2026 Criteria leverage these insights and the expertise of more than 60 subject matter experts to reflect advances across the CDR industry and address key weaknesses that remain in the market across all pathways.
A few of the most significant updates to the Criteria include:
Addition of Direct Counterparty Considerations: Direct counterparties are the organizations that developers partner with, and are structurally dependent on, to generate credits. This can include:
- Primary feedstock providers (e.g., mines, biomass providers, tree nurseries)
- Major implementing partners (e.g., local implementation partners, base facilities, transportation and storage providers, major product offtakers)
- Land owners that make up a significant proportion of project land
To reflect the key role that direct counterparties play in high-quality credit generation, developers must conduct diligence and disclose on their direct counterparties to demonstrate that they are not causing social or environmental harm.
Increased Rigor for Enhanced Rock Weathering Projects: Over the past year, ERW’s presence in the CDR market has grown substantially, and so too has the market’s understanding of the corresponding scientific and technical rigor required to deliver high-quality tonnes. The 2026 Criteria raised the bar for how ERW projects:
- Measure and prove their carbon removal claims
- Mitigate risks related to potentially toxic elements (PTEs)
- Incorporate more sophisticated farmer protections and benefits
Projects now have to back up their numbers with multiple physical field measurements, not just computer models; and they must now track and account for every significant loss pathway, from plants taking up minerals to carbon escaping from rivers and oceans.
Use of Dynamic Baselines for ARR Projects: ARR projects are increasingly using dynamic baselines to provide a more accurate reflection of the counterfactual scenario (e.g., what would have happened in the absence of the project). This is reflected in the 2026 Criteria with a requirement that ARR projects, with the exception of agroforestry projects, use dynamic baselines with statistically matched controls.
What’s Next?
The 2026 Criteria create a clear, science-driven framework for both designing and delivering measurable, just, and durable carbon removal. However, the Criteria cannot ensure high-quality tonnes reach the market on its own; good criteria do not replace robust diligence. To put these criteria into practice, we encourage developers, standard-setting bodies, buyers, investors, and policymakers to consider how the Criteria can be used to inform their role in enabling the carbon market to deliver high-quality tonnes and to engage in deep diligence and ongoing monitoring over the life of a project.
This edition of the Criteria reflects what we have learned over the past year, but our work is not done. We will continue to update it so that it remains a living document that evolves with the science and the market. To do so effectively, it must be a collaborative effort; we welcome input from carbon market actors, academia, and communities.
Frequently Asked Questions
Who publishes the Criteria for High-Quality Carbon Dioxide Removal, and how often is it updated?
Relae (formerly Carbon Direct) first published the Criteria for High-Quality Carbon Dioxide Removal with Microsoft in 2021 and have updated it every year since. The 2026 edition reflects six years of lessons from real-world project diligence and advances in climate science.
What are the six principles of the Criteria for High-Quality Carbon Dioxide Removal?
The Criteria define six science-based principles that apply across all CDR pathways: social harms, benefits, and environmental justice; environmental harms and benefits; additionality and baselines; measurement, monitoring, reporting, and verification (MMRV); durability; and leakage.
What CDR pathways does the Criteria cover?
The Criteria include pathway-specific criteria across nine CDR pathways: afforestation, reforestation, and revegetation (ARR); mangrove forestation; improved forest management (IFM); soil carbon; enhanced rock weathering (ERW) in croplands; biomass carbon removal and storage (BiCRS); abiotic marine CDR; carbon mineralization; and direct air capture (DAC).
What is delivery risk in carbon removal?
Delivery risk is the likelihood that a project generates credits on the timeline and at the quantity committed to buyers. It's a distinct concern from credit quality: even a high-quality project can fail to deliver as planned because of technical, economic, commercial, organizational, or political risk, the five categories the Criteria's TECOP framework evaluates. The 2026 Criteria's new Delivery Risk Appendix gives developers, investors, and buyers a shared benchmark for identifying and managing these risks before they derail a project.
What's the relationship between carbon removal credit quality and delivery risk?
Credit quality and delivery risk are distinct but interrelated. A project that fails to deliver credits as planned reduces the availability of high-quality CDR tonnes in the market, and weaknesses in credit quality can themselves increase delivery risk by creating buyer uncertainty or limiting access to project financing. The 2026 Criteria provides a framework for evaluating both quality and delivery risk.
The Sustainable Aviation Fuel Cost Premium Is Permanent
Key Takeaways
- Sustainable aviation fuel (SAF) will not reach price parity with fossil jet fuel under any realistic near-term scenario. The cost premium is structural—rooted in the chemistry of feedstocks—not a temporary artifact of early-stage markets.
- Neither airlines nor corporate buyers are purchasing SAF for its energy content. Both are buying sustainability claims: airlines for regulatory compliance and scope 1 credentials, corporates for scope 3 emissions reporting and social license to operate. The fuel is incidental to both transactions.
- Corporate offtakes can play a genuine role in building the SAF industry, but only if they create capacity that would not otherwise exist. Additionality is not a technicality; it is the entire value proposition.
- High-integrity SAF procurement requires evaluating not just carbon reduction, but feedstock sourcing, leakage, and social and environmental harms. The newly released Criteria for High-Quality Low Carbon Fuels from Relae (formerly Carbon Direct) provides a framework for doing this rigorously.
A Major Deal Illustrates How the SAF Market Really Works
On June 5, 2026, Google and American Airlines announced a three-year agreement under which Google will purchase sustainable aviation fuel (SAF) certificates (SAFc) associated with 35 million gallons of SAF. American will take physical delivery of the fuel at Chicago O'Hare. Google receives the emissions attributes. The arrangement relies on book-and-claim accounting, in which the physical fuel and the environmental attribute are legally separated and transferred to different parties.
The deal is a window into how the SAF market works, and what every company in the value chain needs to understand before entering it.
The SAF Cost Premium Is Structural, Not a Market Inefficiency
There is a persistent hope in the aviation industry that SAF will eventually reach price parity with fossil jet fuel. This will not happen, at least not through any mechanism that currently exists or is credibly in development.
The economics are the product of thermodynamics. Petroleum is pre-deoxygenated; over millions of years, heat and pressure stripped oxygen from biological material, concentrating energy into the hydrocarbons we pump out of the ground today. Bio-based SAF feedstocks, e.g., vegetable oils, agricultural residues, and other biomass, are oxygen-rich (carbohydrates, not hydrocarbons). Power-to-liquid e-fuels start from captured CO₂, which is fully oxidized.
Either way, every SAF production pathway must pay an energy debt to remove or chemically reduce that oxygen, in the form of hydrogen deoxygenation, energy inputs, and processing costs. This is not a manufacturing inefficiency that scale will solve. It is a constraint baked into the feedstocks themselves.
The numbers reflect this. According to the European Union Aviation Safety Agency (EASA), the average market price of SAF in 2025 was approximately €1,925 per tonne, roughly three times the €640 per tonne average for conventional jet fuel.
The cheapest pathway, hydroprocessed esters and fatty acids (HEFA), produced from waste oils like used cooking oil or tallow, represents almost all current SAF supply and sits at the lower end of the SAF cost range. Costlier cellulosic and e-fuel pathways push it higher. EASA estimates 2025 production costs for power-to-liquid e-fuels at €7,520 per tonne, more than ten times the cost of conventional kerosene. While these costs can and will come down, none are expected to approach price parity.
The feedstock ceiling compounds this. HEFA from waste oils is the cheapest SAF pathway, but waste oil supply is finite and competes with renewable diesel, which typically offers better margins for producers. As mandates push SAF volumes beyond what HEFA can supply, the industry must move to cellulosic biomass or power-to-liquid pathways, at progressively higher cost. Scaling the SAF industry does not automatically bring prices down. In the near term, it pushes them up.
Policy Determines Who Absorbs the Cost
If price parity is not coming, the cost premium lands somewhere. Two policy philosophies have emerged to answer that question.
Europe has largely adopted the polluter-pays principle: SAF mandates place the cost burden on fuel suppliers and, by extension, on airlines and their passengers. The EU's ReFuelEU Aviation regulation and the UK's SAF mandate both carry steep penalties for non-compliance. As Relae has documented, in the UK, those penalties range from three to 13 times the cost of compliance, depending on the obligation type and year, signaling that regulators are serious about pushing aviation toward sustainable fuels.
The United States approached the problem differently, leaning on taxpayer subsidies.The Inflation Reduction Act (IRA) 45Z Clean Fuel Production Credit and its predecessor, the 40B Sustainable Aviation Fuel Credit sought to socialize much of the cost premium. The appeal of this approach was that it made SAF economics viable without raising ticket prices. Its vulnerability was political: when the IRA's incentive landscape was revised, the project pipelines that had formed around those credits evaporated quickly. US taxpayer-funded support proved politically less durable than the UK and EU’s mandated compliance obligations.
Neither model works in isolation. Mandates without bankable project finance generate demand signals but no new supply. Incentives without policy durability attract project interest but cannot get facilities to final investment decisions. The deals that have actually moved capital combine a stable policy floor, whether mandate or incentive, with long-term private commitments that provide the revenue certainty project finance requires.
The Google-American Airlines deal illustrates the incentives-plus-private-commitment structure. The deal explicitly credits the Illinois SAF tax credit as the enabling policy lever. HEFA SAF of this type is eligible to generate Renewable Fuel Standard credits (RINs), and fuel produced from 2025 onward qualifies for the IRA's 45Z Clean Fuel Production Credit. This stack provides additional floor economics. The corporate offtake completes the structure by delivering the revenue certainty that volatile policy credits alone cannot. Remove any one of those elements and the deal's economics likely do not hold.
Nobody in this Market Is Buying SAF for its Energy Content
This is the key to understanding how the SAF market works. Neither airlines nor corporate buyers purchase SAF for its energy content. Airports have kerosene. Airlines do not need SAF to keep planes in the air. Corporate buyers, like Google, have minimal operational use for aviation fuel at all. While recent global disruptions in crude oil supply have highlighted SAF in the context of energy security, the industry as it exists today does not represent a realistic hedge against conventional fuel volatility.
What all parties are buying is the sustainability attribute attached to the fuel. For airlines, the relevant claim is a scope 1 emissions reduction: the right to report lower lifecycle carbon intensity for their flight operations. For corporate buyers, the relevant claim is a scope 3 reduction, a documented abatement of the emissions associated with their employees' business travel. Book-and-claim accounting makes this architecture explicit: it legally severs the physical fuel from the environmental attribute, allowing each to be transferred to the party that values it. The fuel is the delivery mechanism for the claim.
This distinction matters for assessing the market. Airlines operate on among the lowest margins of any major industry. They cannot absorb the cost premium voluntarily without fundamentally compromising their finances. They participate in SAF markets when required to by mandate, or when a corporate partner subsidizes the premium by purchasing certificates downstream. The cost premium does not disappear; it shifts. Understanding where it lands is the starting point for any serious procurement decision.
Corporate climate programs have finite budgets. SAF competes with renewable electricity procurement, fleet electrification, CO2 removal, and supply chain decarbonization for the same dollars. Buyers who want their sustainability claims to match the actual sources of their emissions (rather than offsetting aviation with unrelated activities elsewhere) have a genuine reason to prefer SAF.
A SAF Claim Is Only as Strong as the Quality Behind it
SAF buyers and sellers trade sustainability claims. The quality of those claims is the entire value proposition, and the reputational liability travels with them. The companies with the greatest willingness to pay for SAF certificates tend to be those with the most brand exposure: high-profile technology companies, professional services firms, and financial institutions. These are also the companies most likely to face scrutiny from regulators, NGOs, and investors if a claim does not hold up. Buying a certificate does not protect a company from that scrutiny. It transfers the liability along with the attribute.
That means a rigorous buyer needs to answer at least three distinct questions before relying on a SAF claim.
- Does this fuel actually reduce lifecycle emissions?
SAF's climate case rests on a carbon cycle argument: the feedstock absorbs CO₂ from the atmosphere as it grows, so when that carbon is released during combustion, the net addition to the atmosphere is theoretically near zero. But that logic holds only if upstream production is clean, and it often is not.
Indirect land use change (when demand for a feedstock crop displaces food agriculture elsewhere, triggering clearing of forests or grasslands) can generate substantial emissions elsewhere in the global land and food system, eroding or eliminating the lifecycle benefit. Even waste-based feedstocks are not automatically clean: used cooking oil and tallow have existing market uses, and diverting them without careful accounting can displace those uses, alter commodity markets, and create emissions leakage elsewhere.
- Is the purchase additional?
Additionality asks whether the procurement caused SAF to exist that otherwise would not have. This is a harder question than it appears, especially in markets where multiple policy support mechanisms are already active. For the Google-American Airlines deal, one critical variable for financial additionality—the SAFc price—has not been disclosed. If Illinois credits and federal RINs already cover most of the HEFA cost premium, then the question of what Google's purchase actually caused to happen is genuinely open. However, American Airlines has stated publicly that the long-term nature of the agreement enabled them to secure a new SAF offtake with Valero Marketing and Supply Company. The supply arrangement that may not have been bankable on the basis of volatile RIN markets and changeable policy alone. That is a real additionality argument. But it requires transparency to evaluate. The undisclosed SAF credit price is a current market liability, not just in this deal, but across the voluntary SAF market broadly.
Long-term offtakes do something that policy credits cannot: they provide stable, bankable revenue certainty. RIN prices fluctuate. Tax credits change with administrations. Neither can reliably anchor a final investment decision at the project level. A multi-year, creditworthy offtake agreement can. This is the distinctive and genuinely valuable role that corporate buyers play in this market: not paying the cost premium per gallon, but reducing the financial risk premium that keeps capital on the sidelines.
- Is the full supply chain sound?
Carbon claims are not the only dimension of sustainability that matters to a buyer's reputation. Companies making claims about their SAF procurement are implicitly making claims about their supply chains. That means labor practices, community impacts, Indigenous rights, feedstock sourcing integrity, and market leakage from displaced uses all fall within the scope of what a rigorous buyer should evaluate. A SAF supply chain that displaces food crops, harms a proximate community, or causes deforestation through indirect land use change creates a reputational problem that no certificate can fix.
What High-Integrity SAF Procurement Looks Like
The voluntary SAF market is still early, and the transparency it requires does not yet exist consistently. Relae recently released the Criteria for High-Quality Low Carbon Fuels, a comprehensive, publicly available framework designed to help close that gap.
The criteria address six principles across the full supply chain: carbon accounting, additionality, feedstock sourcing, leakage, environmental harms, and social harms and environmental justice. They are designed as a practical reference for what a credible SAF claim requires, and where existing certifications may leave gaps that require additional diligence.
At the transaction level, five questions should have clear answers before any buyer signs an offtake:
- Is the certificate linked to a specific project or supply agreement?
- Is that project financially dependent on the offtake, after accounting for all policy support already in the stack?
- Is the lifecycle emissions profile documented across the full well-to-wheel boundary, including indirect effects?
- Are the feedstock sourcing and supply chain risks assessed and disclosed?
- Has the producer evaluated leakage and community impacts?
The Google-American Airlines deal demonstrates what serious voluntary SAF procurement can look like. The Criteria for High-Quality Low Carbon Fuels provides the framework buyers need to evaluate deals like this one rigorously.
How SAF Mandates in the EU and UK Are Reshaping Aviation Fuel Markets
Key Takeaways
- SAF and e-SAF mandates are reshaping the aviation fuel market. The EU and UK impose steep non-compliance penalties, turning regulatory requirements into a strategic lever for those who act early.
- Non-compliance is costly. Penalties run roughly 3 times the cost of compliance in the EU and from about 2 to 13 times in the UK, making long-term planning essential to mitigate risk.
- e-SAF producers have a unique opportunity. Mandates and penalties are shifting the economics of aviation fuel, making e-SAF more attractive despite historically high production costs.
How SAF Compliance Stacks Up
Airlines and fuel suppliers operating in Europe and the UK face growing economic uncertainty due to stringent mandates requiring the adoption of sustainable aviation fuels (SAF) with carve-outs for SAF produced from renewable hydrogen, also known as Power-to-Liquids (PtL) or e-SAF.1 These mandates, aimed at reducing aviation emissions, carry steep penalties (up to 13 times the cost of compliance) for fuel suppliers who fail to meet required quotas. While this creates cost uncertainty for airlines and passengers, it opens a strategic opportunity for e-SAF producers. These producers are challenged by high production costs relative to other SAF on the market and a limited set of buyers that can afford the premium on a voluntary basis.
This piece explores the cost implications for aviation being shaped by these EU and UK SAF mandates and outlines how airlines and suppliers can respond strategically to minimize risk and maximize opportunities. By understanding these dynamics, industry stakeholders can turn regulatory compliance into a source of competitive advantage.
Understanding SAF Mandates in the EU and UK
The EU Commission’s ReFuelEU Aviation regulation, part of the European Green Deal, sets binding targets for aviation sustainability. Beginning in 2025, ReFuelEU mandated that aviation fuel suppliers offer a minimum percentage of SAF and e-SAF at EU airports. By 2030, suppliers must blend at least 6% SAF, including 1.2% e-SAF. To discourage tankering practices (carrying excess fuel for return trips, increasing emissions), ReFuelEU Aviation requires airline operators to refuel at least 90% of their annual aviation fuel needs at a given EU airport before departure.
In parallel, the UK Department for Transport (DfT) mandates a higher SAF blend of 10% by 2030 and places greater emphasis on reducing reliance on hydrogenated esters and fatty acids (HEFA) SAF fuels, which face eventual limitations on feedstock supply. HEFA’s allowable share will decline annually from 100% in 2025 to 42% in 2040. The UK also includes a sub-mandate specifically for PtL SAF.
The Real Cost of Falling Behind on SAF Mandates
The financial impact of these mandates is significant. Each year, the European Union Aviation Safety Agency (EASA) publishes regulatory reference prices for SAF, e-SAF, and conventional jet fuel (CJF) that anchor non-compliance penalties in the EU, most recently the 2025 Aviation Fuels Reference Prices for ReFuelEU Aviation. Using these reference prices for current-year costs and projected production costs or prices for SAF, e-SAF, and CJF from 2030–2050, the following analysis compares EU and UK compliance versus non-compliance penalties, converting all figures to US$/gallon.2
The price gap between SAF and fossil jet fuels remains wide. In 2025, SAF is approximately three times the price of CJF, while e-SAF is nearly twelve times more expensive. Projections indicate this price gap narrows by 2030, but far more for SAF than for e-SAF. The projected price of SAF in 2030 is US$5.46/gallon, more than double the estimated US$2.41/gallon for CJF. The price difference is even greater for e-SAF: with no traded e-SAF market yet, projected 2030 prices span US$5.70/gallon to US$33.00/gallon, with a central estimate around US$18/gallon, or roughly seven times the price of CJF.
Estimated Jet Fuel Prices 2025-2050 (US$/Gallon)
Source: European Union Aviation Safety Agency. 2025 Aviation Fuels Reference Prices for ReFuelEU Aviation. (link); UK Department for Transport. SAF Mandate: Final-stage Cost Benefit Analysis. (link); EUROCONTROL. Aviation Outlook 2050: Main Report. (link)
The mandates carry strict penalties for non-compliance. Penalties for non-compliance in the EU are set at a minimum of two times the price difference between SAF and CJF per gallon of unmet obligation. Additionally, fuel suppliers must supply any unmet fuel obligations in subsequent reporting periods, which pushes the cost of non-compliance in the EU to three times the cost of compliance.
In the UK, penalties work differently: fuel suppliers must pay a fixed buy-out price per megajoule (MJ) of unmet obligation, which translates to US$24.64/gallon of unmet SAF obligation and US$26.08/gallon of unmet e-SAF obligation.3 Because the buy-out is fixed while compliance costs vary, UK penalties range from about 2 times the cost of compliance for e-SAF to 13 times for SAF in later years. The intent is clear: regulators are serious about pushing aviation towards sustainable fuels.
Cost-Comparison of Compliance vs Non-Compliance (US$/Gallon)
Note: The cost of compliance under both mandates is calculated as the price premium of SAF/e-SAF over CJF per ton, using region-specific SAF prices: the EU SAF price reflects HEFA-based supply (ReFuelEU imposes no HEFA cap), while the UK SAF price is a weighted average of HEFA and higher-cost advanced pathways based on the UK's declining HEFA cap. The e-SAF (PtL) price is the same in both regions.
Cost-Comparison of Complicance vs Non-Compliance (US$/Gallon)
e-SAF Has a Policy-Driven Market Opportunity
These price differentials present risk and opportunity. Airlines and fuel suppliers that fall short of compliance will face steep penalties. Those who comply strategically, can mitigate those risks and benefit from financial incentives that help offset higher fuel costs.
Incentive structures support SAF and e-SAF production. For example, the EU’s Emissions Trading System (ETS) has allocated allowances to offset SAF costs, especially for renewable fuels of non-biological origin (or e-SAF). Similarly, the UK offers tradable certificates and has now legislated a Revenue Certainty Mechanism (Sustainable Aviation Fuel Act 2026) that will guarantee SAF producers a set strike price through contracts-for-difference-style agreements, funded by a levy on fuel suppliers, with the first allocation round expected in 2027. The UK’s ETS also provides an indirect incentive as SAF use by airlines lowers compliance costs through reducing required allowances.
Strategic Recommendations for Airlines and Suppliers
To navigate this shifting landscape, airlines and fuel suppliers must think strategically about procurement and compliance, potentially including:
- Proactive procurement: Airlines and fuel suppliers should prioritize securing long-term contracts with SAF and e-SAF producers. Early engagement can help ensure access to limited supply and stable pricing.
- Leverage incentive programs: Actively participate in available incentive schemes, such as the EU ETS and UK tradable certificates, to minimize compliance costs.
- Invest in e-SAF production: Consider strategic investments or partnerships in e-SAF production to align sustainability goals with regulatory requirements and financial incentives.
- Plan for volatility: Develop robust risk mitigation plans, using flexible procurement strategies and financial instruments to buffer against supply chain disruptions and price swings.
Turning Mandates into Market Momentum
As 2030 approaches, the pressure on airlines and fuel suppliers to comply with SAF mandates will intensify. Those who proactively respond to and embrace the mandates can transform regulatory requirements into strategic opportunities. Rather than viewing mandates as burdens, forward-looking stakeholders can use them to drive sustainable innovation and long-term resilience.
The EU and UK mandates for SAF and e-SAF represent an emerging shift in aviation fuel markets. Stakeholders that act now, by engaging with incentives and investing in sustainable fuel solutions, will emerge as industry leaders. Now is the time for airlines, fuel suppliers, and e-SAF producers to act decisively, transforming regulatory compliance from a costly obligation into a clear competitive advantage.
Frequently Asked Questions
What happens if an airline or fuel supplier misses its SAF mandate quota?
Fuel suppliers—the obligated parties—pay a penalty on every unmet tonne: in the EU, twice the price gap between SAF and jet fuel, plus supplying the shortfall in a later period; in the UK, a fixed buy-out price (£0.137/MJ for SAF, £0.145/MJ for e-SAF). Combined, non-compliance runs roughly 3 times the cost of complying in the EU and from about 2 to 13 times in the UK.
What is e-SAF, and how is it different from other SAF?
e-SAF, also called Power-to-Liquid (PtL) fuel, is made from renewable or low-carbon electricity, hydrogen, and captured CO₂ rather than biomass feedstocks. It costs more to produce than conventional SAF today, but both the EU (from 2030) and UK (from 2028) mandates carve out a specific, growing sub-quota for it.
What is the UK's Revenue Certainty Mechanism?
It is a UK government scheme, modeled on the Contracts for Difference structure used in the power sector, that guarantees SAF producers a set strike price for up to 10 years, funded by a levy on aviation fuel suppliers. It became law through the Sustainable Aviation Fuel Act 2026, and the first contract allocation round is expected in 2027.
Is the EU considering changes to its SAF mandate timeline?
The EU has scheduled a formal review of ReFuelEU Aviation for 2027, following calls from airline groups to delay the 2030 e-SAF sub-target. No delay has been adopted, and the European Commission has said it remains "fully committed" to both the SAF and e-SAF mandates and that the 2027 review will evaluate the regulation rather than revise it.
Can corporate buyers still claim SAF benefits from fuel used to meet these mandates?
No, mandated volumes are claimed in the compliance market, so to avoid additionality concerns, voluntary corporate scope 3 claims (typically made through SAF certificates and book-and-claim) must come from supply beyond what the mandates require. As mandate demand grows, the pool available to voluntary buyers tightens, which is why early procurement locks in both supply and price.
Decarbonizing Concrete and Steel with Environmental Attribute Certificates
Key Takeaways
- Concrete and steel contribute 13% of global CO2 emissions. These materials represent substantial scope 3 emissions for companies that are building new infrastructure, including data centers.
- Low-emission alternatives and production technologies are nascent and not yet widely deployed.
- Environmental attribute certificates (EACs) are an innovative solution that can stimulate manufacturing of sustainable commodity materials and overcome market barriers to direct physical procurement.
- Relae (formerly Carbon Direct) and Microsoft developed criteria to guide Microsoft’s high-quality EAC procurement, accelerate decarbonization, and catalyze market expansion for decarbonized materials across supply chains.
- These criteria cover seven key areas: qualifying conditions, social harms and benefits, environmental harms and benefits, additionality and baselines, catalytic impact, verifiability, and leakage.
A Vision for Low-Carbon Concrete and Steel
Concrete and steel are essential for modern construction, but are carbon-intensive. Combined, they account for approximately 13% of global carbon dioxide (CO2) emissions. As the demand for data centers and infrastructure development continues to grow, so do the embodied emissions from concrete and steel. There is an urgent need to decarbonize these sectors so that construction of new facilities remains consistent with climate commitments.
However, the markets for low-carbon concrete and steel are still in their infancy. Market barriers such as low production volumes, contracting complexity, geographic concentration of supplies, and long-distance transportation limit buyers’ ability to directly procure low-carbon building materials. As buyers and sellers overcome these barriers, the market for low-carbon building materials will mature, giving producers the confidence to invest in new manufacturing facilities and giving buyers access to decarbonized materials directly in their supply chain.
Environmental attribute certificates (EACs) represent the sustainability attributes of a material commodity, unbundled and transacted separately from the physical commodity. EACs are transacted at a price that reflects the additional cost of sustainably producing the material. While barriers to direct procurement of low-carbon materials persist, EACs can serve as a powerful tool to signal demand for low-carbon concrete and steel, catalyze market expansion, and accelerate decarbonization.
[cta]
Microsoft’s Approach to Emissions from Building Materials
To address embodied emissions and help achieve its ambitious 2030 carbon-negative goal, Microsoft aims to deeply reduce its scope 3 emissions, including from building materials, by more than half compared to a 2020 baseline. In 2023, scope 3 emissions made up over 96% of Microsoft’s total greenhouse gas footprint. To meet its 2030 target, Microsoft is focusing on addressing supply-chain emissions related to data center construction and the embodied carbon of the commodity materials used to build them. Microsoft is already working to decarbonize its building material supply chain using the following three tactics:
- Reduce the need for concrete and steel through innovative building design or the use of lower-carbon alternatives, such as sustainably sourced mass timber.
- Directly engage with suppliers to procure low-carbon alternatives to conventional concrete and steel.
- Invest in and help pilot new low-carbon production pathways.
EACs represent a fourth approach to decarbonization that can both reduce emissions and catalyze industry growth. Taken together with Microsoft’s design, procurement, and investment tactics, these actions underpin a comprehensive strategy for long-term decarbonization of the built environment.
High-Quality EACs Support Decarbonization
EACs offer a virtual, market-driven solution to decarbonize the built environment by allowing companies to support low-carbon material production when physical supply chain barriers impede direct procurement. EACs for concrete and steel function similarly to other market-based decarbonization mechanisms such as sustainable aviation fuel (SAF) certificates in the aviation sector and renewable energy certificates (RECs) in the energy sector.
These mechanisms work by decoupling the environmental benefits of low-carbon production from the physical materials themselves. EACs allow companies to claim the environmental benefits of physical low-carbon concrete or steel production, even if they do not directly or physically source those materials. EACs provide a verified claim that a purchaser has procured a product with lower emissions, enabling companies to meet climate targets and demonstrate their commitment to sustainability.
Due to their virtual nature, which limits physical oversight of the supply chain, EACs also exacerbate risks such as double counting, greenwashing, fraud, social harms, and environmental harms. Therefore, adhering to transparent, rigorous criteria is foundational to mitigating these risks.
New Criteria to Guide Procurement of High-Quality EACs
To support the integrity and effectiveness of EACs in these sectors, Relae and Microsoft have co-developed Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors. These robust criteria serve as a public resource for companies seeking credible and impactful EAC procurement pathways for low-carbon concrete and steel.
The criteria address seven key areas:
- Qualifying conditions: EACs must complement, not displace, direct procurement and represent significant emissions reductions.
- Social harms and benefits: EACs must not further social harms and should promote community engagement and social benefits such as meaningful workforce development opportunities and community climate resilience.
- Environmental harms and benefits: EACs must not perpetuate environmental harm, but instead should mitigate risks and, ideally, provide additional environmental benefits.
- Additionality and baselines: Projects funded by EACs must drive real, meaningful emissions reductions in terms of financial, regulatory, and common practice additionality.
- Catalytic impact: Prioritize transformative technologies with sector-wide decarbonization potential.
- Verifiability: Set a high bar for documentation, transparency, and independent auditing.
- Leakage: Address risks of emissions displacement to support net-positive outcomes.
These criteria provide a robust framework for companies and stakeholders to evaluate and implement commodity EACs effectively, supporting impactful change. They balance rigor with flexibility and acknowledge the nascent state of the markets for low-carbon concrete and steel. Sectoral decarbonization will advance over time, shifting the thresholds for what is considered significant, additional, and catalytic in EAC transactions. This science-driven framework can adapt to advancements in policy, industry practices, and technological readiness, ensuring EACs remain a relevant and impactful tool for years to come.
Sector-Specific Insights
In addition to providing overarching criteria and guidance on procuring EACs for the built environment, Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors also provides insights into the unique challenges and opportunities of decarbonizing concrete and steel.
Decarbonizing Concrete
EACs can support innovative decarbonization strategies for concrete, such as producing alternatives to clinker and cement, adopting supplementary cementitious materials (SCMs), and reducing emissions from cement kilns through electrification or integrating carbon capture and storage (CCS). Performance-based standards and evolving building codes may also unlock new opportunities for low-carbon concrete.
The Global Cement and Concrete Association (GCCA) publishes a rating system, Low Carbon Concrete (or Cement) Ratings, which defines eight separate low-carbon grades (AA through G). These grades correspond to the depth of decarbonization and are based on a sliding scale related to the material’s compressive strength. When developing these criteria, Microsoft considered grades AA through D to be eligible for consideration in its EAC procurements.
Decarbonizing Steel
EACs can support transformative technologies for decarbonizing steel, like direct reduced iron (DRI) with electric arc furnaces (EAF) powered by green or blue hydrogen. This support can enable the steel sector to move beyond incremental improvements and focus on capital-intensive solutions that have the potential to reshape the industry.
ResponsibleSteel, an independent standards and certification organization with membership that is broadly representative of the steel industry, publishes decarbonization progress levels, with four separate grades (PL1–PL4). These grades correspond to the depth of decarbonization and are based on a sliding scale related to the fraction of recycled scrap use in the steel manufacturing process. When developing these criteria, Microsoft included levels PL2 through PL4 for consideration in its EAC procurements.
A Blueprint for EAC Market Development
Relae and Microsoft crafted Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors as a public resource that can help shape the future of the commodity EAC market.
These criteria are designed to:
- Communicate intent: Communicate Microsoft's intent to support the decarbonization and scaling of physical commodity supply chains where they have been previously limited.
- Guide decision-making: Serve as a public guide for Microsoft's decision-making process, explaining the rationale behind pursuing or declining specific EAC pathways.
- Set high-integrity standards: Maintain high integrity for EACs at an early stage, ensuring they are used to enable future physical procurement by supporting market development.
- Stimulate partnership opportunities: Encourage potential partnerships and purchasing pipelines by clearly describing criteria for high-quality EACs.
- Publicly share detailed thinking: Build on previous work and publicly share detailed thinking, aiming to stimulate market development and guide procurement decisions.
Practical Recommendations for Implementing EACs
Whether you are a supplier, buyer, policymaker, or sustainability advocate, these new criteria offer actionable insights to help you navigate the complexities of EACs in the built environment. From setting significance thresholds to ensuring verifiability to avoiding double counting, the criteria provide clear guidance to maximize the impact of EAC-supported projects.
Beyond the technical aspects of EACs, these criteria aim to address their broader social and environmental implications. The criteria focus on the importance of community engagement, transparency, and equitable distribution of benefits in EAC project planning, ensuring that decarbonization efforts contribute to a more sustainable and just economy. The criteria are backed by extensive research, stakeholder consultations, and industry expertise.
[cta]
Frequently Asked Questions
What is an environmental attribute certificate (EAC), and how does it differ from buying low-carbon concrete or steel directly?
An environmental attribute certificate represents the sustainability attributes of a commodity material such as concrete or steel, unbundled from the physical material and transacted separately from it. Direct procurement means a buyer purchases low-carbon concrete or steel and takes physical delivery of it for a specific project. An EAC purchase instead allows a buyer to fund and claim the environmental benefit of sustainably produced materials that are sold as typical commodities, and apply that benefit against conventional commodities in their own supply chain. EACs are priced to reflect the additional cost of producing the material sustainably, which sends a demand signal to producers. This makes EACs useful where market barriers—limited production volumes, geographic concentration of supply, or long-distance transportation—prevent buyers from sourcing low-carbon materials directly.
How do EACs for concrete and steel compare to renewable energy certificates (RECs) or sustainable aviation fuel (SAF) certificates?
Environmental attribute certificates for concrete and steel share a structure with renewable energy certificates and sustainable aviation fuel certificates: each decouples the environmental benefit of low-carbon production from the physical product, letting a buyer fund and claim that benefit without taking physical delivery. There are two key differences. First, conventional RECs represent electricity with a zero-emissions footprint, while every tonne of concrete or steel behind an EAC still carries embodied emissions — the certificate demonstrates reduction against a baseline, not a zero-emission product. Second, REC and SAF markets are established, while EACs for concrete and steel are nascent. Both differences are why rigorous criteria matter: quantifying the reduction credibly is harder, and the virtual structure carries risks of double counting, greenwashing, and fraud.
Will EACs let companies claim emissions reductions without actually reducing their built environment climate footprint?
An EAC purchase does not change the materials in a buyer's own buildings; it funds lower-emission production elsewhere in the market. Credible EAC frameworks therefore require that certificates complement rather than displace direct procurement, that they represent significant reductions against a defensible baseline, and that the funded project would not have proceeded without EAC revenue. The criteria published by Relae and Microsoft enable buyers to address these requirements directly in their procurement processes - addressing the climate and reputational risks of low-quality certificates. Used this way, EACs become an additional tool to address emissions from the built environment, supplementing design changes, direct procurement, and investment in new production pathways.
Who should use these criteria?
Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors, co-developed by Relae and Microsoft, is a public resource intended for four audiences. Buyers pursuing scope 3 reductions can use it to evaluate whether a given certificate represents a credible, additional emissions reduction. Suppliers and project developers can use it to understand what purchasers of high-quality certificates look for before bringing a project to market. Policymakers and standards bodies can draw on it while shaping rules for an emerging market. Sustainability practitioners and advocates can use it as a reference point for assessing claims made about low-carbon concrete and steel. The criteria are designed to evolve as these sectors decarbonize, and users may adapt them to meet their own levels of capability and ambition.
Decarbonizing Cement and Concrete: Are Their Emissions Set in Stone?
Key Takeaways
- Cement is the key ingredient in concrete and is responsible for more than 80% of concrete’s emissions. Cement’s GHG emissions are the primary technical challenge in decarbonizing an industry that accounts for over 8% of annual global greenhouse gas emissions.
- The global market for low-carbon concrete is constrained by the slow deployment of breakthrough technologies, yet demand from major buyers such as hyperscalers, developers, and infrastructure investors is accelerating. This mismatch between demand and supply is creating a new market mechanism: environmental attribute certificates (EACs) for building materials.
- EACs represent the climate benefits of low-carbon materials and can be traded separately from the physical product. These certificates, when backed by robust technical diligence, offer a near-term funding mechanism to accelerate decarbonization across the cement and concrete supply chain.
The AI Boom Meets an Industrial Reality
As the market for AI infrastructure expands, data center construction is accelerating—and with it, demand for concrete, one of the most carbon-intensive materials in the built environment. For both builders and material suppliers, the embodied carbon of cement and concrete is under a microscope due to its significant climate impact. Hyperscalers, like Microsoft and Meta, have 2030 targets that far outpace the concrete industry’s readiness to provide near-term low-emissions materials.
This piece explores why cement and concrete decarbonization is so challenging and how credible, high-quality EACs can help bridge the ambition gap.
Cement and Concrete: An Important Distinction
These two terms are often used interchangeably, but they are not the same—and the distinction matters for decarbonization strategy. Cement is the reactive ingredient in concrete, acting like an egg in a cake batter. Concrete itself is a blend of cement, aggregates (like sand and gravel), and water (the batter overall). While concrete is widely used and often seen as the emissions culprit, it is actually cement—just 15% of the mix by volume—that is responsible for more than 80% of concrete’s lifecycle carbon emissions.
Why Is Concrete so Hard to Decarbonize?
Concrete is the second most-used material on Earth after water. Despite emitting only ~0.13 kg of CO₂ per kilogram, its sheer scale gives it an outsized climate impact—contributing around 8% of global CO₂ emissions. Yet decarbonization has been slow, held back by technical, structural, and accounting challenges across a complex supply chain.
The Supply Chain Behind Concrete’s Carbon Footprint
To understand why decarbonizing concrete is so difficult, it’s essential to understand how it’s made and what drives its emissions. Three factors explain much of the difficulty:
- Cement is made in an emissions-intensive process. Cement is produced by heating limestone to extreme temperatures (~1450 °C) to create clinker, a reactive material that binds sand and aggregates into concrete. This energy and carbon-intensive process is where the majority of the emissions occur.
- Concrete is made to order. Concrete is a blend of cement, aggregate, and water. It is made to order at local batch plants and poured on-site or used in precast molds, with mix designs tailored to specific compressive strength and durability requirements.
- The supply chain is decentralized and performance-driven. Because concrete mixtures must meet application-specific performance requirements, low-carbon innovations are limited to those that do not decrease product quality and performance at any point in the value chain.
This layered supply chain, from kiln to batch plant to job site, means decarbonization strategies must be compatible with local infrastructure, material availability, and performance needs. There is no single lever to pull.
Clinker Is the Main Emissions Driver
Clinker production alone accounts for the majority of cement’s emissions, due to the chemical process (calcination) that converts limestone into lime and releases CO2. Not only does calcination directly produce CO2, but the combustion of fossil fuels used to heat the kiln adds to the emissions of the overall process.
Low-Carbon Concrete Technology: Invented, Not Yet Deployed
Six promising technologies are in development to address cement and concrete emissions, including:
- Carbon Capture and Storage (CCS): CCS can be retrofitted to capture the fuel and process emissions from clinker production, delivering nearly complete decarbonization of the cement manufacturing process. CCS can be combined with electrification or fuel switching to deliver deeper decarbonization
- Supplementary cementitous materials (SCMs): SCMs offer two key benefits: they can partially replace conventional cement in concrete mixtures, and certain SCMs react with CO₂ from industrial or atmospheric sources to enable durable carbon storage.
- Electrification: Electrifying kiln heating systems can reduce emissions from fossil fuel combustion during clinker production. When powered by low-carbon electricity, this approach lowers the carbon intensity of cement manufacturing while maintaining the high temperatures required for clinker formation.
- Fuel Switching: Natural gas, biomass, and renewable natural gas are low carbon-intensity fuels that can replace the higher-emitting coal and refuse derived fuel that usually drive the clinker production process. Unlike electrification, some alternative fuels can be used as 'drop-in' replacements in existing equipment.
- Synthetic and recycled aggregates: Alternatives to traditional gravel and crushed stone, made from waste materials or industrial byproducts, which can lower emissions and reduce resource extraction.
- CO2 curing: A process where concrete is cured with captured CO2 instead of air, helping lock carbon into the material and partially offsetting upstream process emissions.
Each solution faces deployment challenges, from raw material availability and geographic constraints to cost, performance certification, and integration with legacy infrastructure.
Few decarbonization strategies have reached industrial scale today, but these strategies are being piloted and demonstrated, and given targeted support, some have the potential to significantly decarbonize the future of the industry.
The Gap Between Targets and Real Market Capacity
Hyperscalers, utilities, real estate developers, and other large organizations with ambitious scope 3 targets are looking to significantly reduce the embodied carbon throughout their supply chain. However, the current supply of deeply decarbonized cement and concrete is insufficient to support these targets through direct procurement alone; the low-carbon material simply does not exist at the required volume or in the right geographies. In some cases, pilot plants produce too little material to meet large-scale demand, while projects capable of larger volumes may not yet be located in regions where interested buyers are concentrated.
In this context, EACs offer a flexible mechanism to fund innovation and bridge the gap. By unbundling climate attributes from physical materials, near-term obstacles, such as geographic availability, can be overcome while channeling capital toward scalable and catalytic solutions.
When backed by rigorous life cycle assessments and high-quality, transparent traceability standards, EACs can provide the financial bridge for truly innovative suppliers to invest in the capital solutions required to decarbonize cement and concrete. EACs can serve a catalytic role to support scalable strategies and help ensure that first-of-a-kind facilities are built, and direct procurement of low-carbon concrete is increasingly feasible in the years to come.
How Environmental Attribute Certificates Work in Cement and Concrete Markets
EACs translate emissions reductions from low-carbon cement and concrete production into climate attributes that can be purchased separately from the physical material. Instead of requiring buyers to procure low-carbon concrete directly from a specific supplier site, EACs allow the climate benefit associated with that production to be transacted independently through a book and claim model.
In practice, a producer implements a verified emissions reduction intervention, such as reducing clinker content through supplementary cementitious materials, installing carbon capture at a kiln, or deploying alternative cement chemistries. The resulting emissions reductions are quantified through life cycle assessment and product-level disclosures such as Environmental Product Declarations. Verified reductions can then be converted into certificates representing the climate benefit of that lower-emissions production.
Buyers can purchase these certificates to support the deployment of low-carbon cement and concrete technologies while making progress toward embodied carbon reduction targets. In this way, EACs provide an early demand signal and a revenue stream that can help producers finance capital-intensive decarbonization investments across the cement and concrete supply chain.
What This Means for Suppliers and Buyers
Whether you are procuring concrete or producing it, EACs are only one part of a broader decarbonization strategy. Navigating this space requires decisions at the intersection of technical feasibility, GHG accounting, and capital strategy. Key considerations include:
- GHG accounting and reportability: Life cycle assessments, Environmental Product Declarations, and other product-level attributes must be tracked and transacted with high integrity. Buyers should report their EAC activities responsibly, especially in the current absence of formal standards and guidance.
- Procurement alignment: EAC buyers must ensure purchased certificates reflect equivalent performance grade materials to what was directly procured for structural applications.
- Monetization pathways: Book-and-claim EAC models offer producers a way to fund capital-intensive decarbonization upgrades while giving buyers a credible way to meet interim scope 3 goals. EAC transactions can take many forms and should be designed thoughtfully to minimize risks such as double counting.
Frequently Asked Questions
What is low-carbon cement, and how does it work?
Low-carbon cement reduces emissions by replacing traditional clinker with supplementary cementitious materials (SCMs), switching to cleaner fuels, electrifying kilns, or capturing CO₂ at the point of production. Because cement is responsible for more than 80% of concrete's lifecycle emissions, interventions targeting clinker production deliver the greatest climate impact. Most approaches are technically proven at smaller scales but have not yet reached the industrial volumes needed to meet mainstream demand.
How do EACs for cement and concrete compare to direct procurement of low-carbon materials?
Direct procurement means physically buying low-carbon concrete from a supplier, which requires that product to exist at conditions that often can not be met today. EACs decouple the climate benefit from the physical material, allowing buyers to fund verified emissions reductions across the supply chain even when direct sourcing isn't feasible. Both approaches can count toward scope 3 targets, but EACs offer more flexibility in the near term while the low-carbon materials market matures.
Is low-carbon concrete proven and available at scale today?
The core technologies for decarbonizing cement and concrete are technically demonstrated, but most have not reached commercial scale. Supply is geographically concentrated and insufficient to meet the volume demands of large buyers like hyperscalers, utilities, and real estate developers. This gap between technical readiness and market availability is precisely what makes EACs a valuable bridging mechanism right now.
What should a company look for when evaluating EACs for cement and concrete?
High-quality EACs should be backed by rigorous life cycle assessments and transparent traceability standards that tie the certificate to a specific, verifiable emissions reduction intervention. Buyers should also confirm that the certificates represent materials with equivalent performance grades to what they are directly procuring for structural applications, and that accounting practices minimize risks like double counting. Working with a technically credible advisor to evaluate EAC quality is essential, since the market currently lacks formal standards and guidance.
How Relae Can Help Decarbonize Cement and Concrete
Decarbonizing cement and concrete is both a technical and a strategic challenge. Relae brings integrated expertise across geochemistry, life cycle assessment, carbon accounting, and industrial decarbonization strategy to help buyers and producers navigate the complex path to decarbonization. Relae works directly with producers developing low-carbon cement and concrete technologies and with global buyers seeking credible pathways to address embodied emissions in construction. Our team combines industrial decarbonization engineering, geochemical expertise, and carbon accounting to evaluate emerging EAC frameworks and ensure they deliver real climate impact.
- EAC advisory for buyers: Relae helps buyers procure high-quality EACs through criteria development and in-depth technical diligence of EAC offerings across a range of low-carbon commodities, supporting purchased certificates that reflect genuine, verifiable climate impact.
- EAC advisory for suppliers: Relae helps producers design high-quality EAC interventions and assess potential EAC claims throughout the supply chain, informed by technical assessment, book-and-claim systems, and market landscaping.
- For both: Relae’s levelized cost of carbon abatement tooling provides custom modeling to assess trade-offs across cement and concrete decarbonization pathways, helping ensure that every dollar of climate spend goes further.
Independent Project Assurance Is Likely Your Best-Returning Spend
Key Takeaways
- The decision to fund a project is determined by a holistic review of project development maturity. This applies across capital-intensive projects, including low-carbon power generation, carbon capture and storage (CCS) solutions, sustainable aviation fuel (SAF), and broader transition infrastructure build-out. Both technical and commercial workstreams must be developed in parallel to avoid project failure.
- Early scope decisions, such as site selection, core technology selection, and nameplate capacity, are cheap to make but become exponentially disruptive and costly to reverse.
- Independent challenge and verification is tangible evidence of a disciplined, well-managed capital development process.
Bridging the Gap from Announcement to Delivery
Among project developers, a perception often persists: seeking external review signals a project in distress. In capital budgeting discussions, subjecting engineering scope and commercial assumptions to third-party interrogation can be misconstrued as a vote of no confidence in the primary delivery team.
In reality, the reverse is true. Across complex infrastructure, independent challenge is the disciplined stage-gate practice that protects capital by reconciling technical reality with commercial terms before designs are locked.
Independent Challenge Is a Sign of Strength, Not Doubt
Across capital projects, and in particular within emerging low-carbon industrial infrastructure, the gap between announced projects and delivered assets remains stark. Data from the Mission Possible Partnership’s Global Project Tracker reveals that fewer than 17% of announced commercial-scale clean industrial facilities worldwide have reached Final Investment Decision (FID) or commercial operations, leaving more than 800 major decarbonization projects stalled in front-end development.
The causes of developmental paralysis are multifaceted. While macroeconomic interest rate shifts and global supply chain disruptions sit largely outside a developer's control, project definition and developmental discipline remain entirely manageable. Even amid external volatility, a project designed with resilience will have a far greater likelihood of success.
Independent review and assurance directly strengthen a project’s chance of success and overall value. Large global project delivery organizations have applied this discipline for decades by deploying independent teams to evaluate project readiness at every stage gate. For teams lacking a dedicated internal oversight organization, or those deploying first-of-a-kind facilities, third-party independent review provides the necessary rigor to facilitate project success.
Relae’s (formerly Carbon Direct) work with Stockholm Exergi is a clear example: independent assurance helped build funder and regulator confidence in a first-of-a-kind carbon removal facility with no direct precedent to benchmark against.
Why Projects Stall Between Announcement and FID
Low-carbon infrastructure and net-zero industrial projects carry unique risks compared to the repeat delivery of established designs. Exciting new developments run a higher risk of falling victim to optimism bias or compressing development timelines to meet public announcement milestones.
It is a natural human tendency for project champions to focus on the upside during early development. However, early momentum must be balanced with processes that reintroduce industrial lessons, supply-chain realities, and operational resilience.
Front-End Loading (FEL) is a well-evidenced approach for improving capital project outcomes. Decades of benchmarking by Independent Project Analysis (IPA) show that approximately two-thirds of industrial megaprojects suffer capital cost overruns or schedule slippage of 25% or more, or encounter severe operational problems lasting more than two years post-startup. This pattern is repeating in low-carbon infrastructure: IPA’s analysis of 12 completed low-carbon projects found average cost escalation of 31% and schedule slip of almost 50%. Rigorous front-end definition remains the single strongest predictor of whether a project will achieve its cost and schedule targets.
As highlighted in the CDR 2.0: Five Pillars of Successful Project Deployment and Delivery report published by Relae, projects falter when developers push ahead without stress-testing the full delivery framework. Stage gate reviews are the mechanisms that evaluate the total project concept and underlying business case. They are most effective when executed as independent cold-eye evaluations prior to each funding gate, identifying and mitigating vulnerabilities long before final investment decisions are reached.
What Funders Need to See at Each Gate
Different stages of project development rely on distinct capital sources, each requiring specific proof points before deploying funds.
Before FEED Funding: Justifying the Engineering Spend
Front-End Engineering Design (FEED) is a major financial commitment, typically costing between 2% and 4% of total project capital cost. The funders backing this stage are usually the developer’s own balance sheet equity, strategic partners, or public grant programs. Before allocating millions of dollars to detailed engineering, these funders need confidence on the fundamentals:
- A technically sound process concept, confirmed utility balances, and an energy integration scheme that fits the site.
- Secured site control, clear zoning pathways, and no environmental fatal flaws that could derail permitting.
- Documented availability of required feedstocks, water and power, paired with demonstrable interest from target off-takers.
Before FID: Proving Bankability and Commercial Closure
As a project approaches FID, the funding audience shifts to conservative commercial lenders, infrastructure funds, and binding offtake counterparties. These capital providers are not underwriting strategic vision; they are underwriting long-term operational cash flows and debt service. Depending on the project and financing structure, capital providers may require:
- A high-confidence capital cost estimate (AACE Class 2 or Class 3) backed by frozen Piping and Instrumentation Diagrams (P&IDs), firm equipment quotes, and a realistic execution schedule with clear critical paths.
- Bankable engineering, procurement, and construction (EPC) structures that clearly allocate risk, include performance guarantees and enforceable liquidated damages.
- Fully executed, binding offtake and feedstock agreements, along with non-appealable permits and completed utility interconnection agreements, with remaining conditions clearly understood.
- An objective, third-party challenge review that assesses operational viability and distinguishes an executable engineering plan from an aspirational concept.
Commercial and Technical Co-Development: The Stage-Gate Method in Practice
A project rarely fails because of an isolated mechanical issue or a purely commercial misstep; failure happens when technical decisions and commercial terms are negotiated in silos and decisions are made without understanding of the wider implications.
We see this disconnect play out in several ways, including:
- Sizing capacity before testing market demand: An engineering team may size a facility to maximize thermodynamic efficiency and economies of scale, only for the commercial team to discover buyers will only commit to half that volume. The developer is left with an oversized, unbankable design requiring fundamental rework.
- Setting product specifications before negotiating offtake: Process engineers frequently design systems around standard vendor packages. However, when downstream transport, processing, or storage networks enforce strict purity standards, the facility faces costly equipment redesigns. This issue has materialized directly within European CCS networks. Open-access offshore storage operators, such as Norway's Northern Lights project, established strict cross-border CO2 specifications requiring tighter moisture and impurity thresholds than originally designed for.
- Locking Electrical Loads Prior to Interconnection Verification: As detailed in Relae’s analysis of physical infrastructure bottlenecks, scale is rarely constrained by capital availability; it is dictated by electrical transmission queues, substation headroom, and 24/7 firm power availability. Freezing electrical demand before verifying utility interconnection timelines risks stranding engineering work on an asset that cannot connect to the grid.
How Relae Stress Tests Projects at Each Gate
Independent reviews at each stage-gate improve success rates by stress-testing assumptions before presenting to lenders, infrastructure investors, or corporate buyers. Relae reviews projects across five categories using the TECOP framework:
- Technical: Verifying technology readiness levels (TRL), mass and energy balances, plot plan constructability, and operational availability under real-world conditions.
- Economic: Capex benchmarking, operating contingency adequacy, utility tariff sensitivities, and financial model cash-flow resilience.
- Commercial: Offtake agreement structures, feedstock contracts, contracting boundaries, EPC contract structures, and counterparty creditworthiness.
- Organizational: Owner's team capabilities, internal stage-gate governance, contractor oversight mechanisms, and execution capabilities.
- Political: Statutory permitting status, regulatory durability, carbon market policy exposure, and local community social license.
The TECOP framework is relevant for evaluating delivery risk across all project types, see more in Relae’s Criteria for High-Quality Carbon Dioxide Removal, Delivery Risk Appendix.
What makes this approach effective is sitting on both sides of the table. Having completed over 250 deep-dive technology reviews, 900+ project evaluations, and advised on more than $6 billion in industrial project finance, Relae has extensive experience evaluating the considerations important to institutional funders and buyers.
The Value of Early Independent Project AssuranceIncorporating independent review should be standard practice for modern infrastructure delivery. Because funders will perform their own rigorous diligence regardless, conducting an independent evaluation early enables developers to address vulnerabilities proactively and present a more resilient business case.
Commissioning an independent team for a cold-eye review during early project formation can be a cost-effective way to identify potential risks before they become expensive to address. Catching an unworkable process assumption, an oversized capacity plan, or a misaligned commercial interface during pre-FEED costs a tiny fraction of what it takes to fix those issues during construction
Ultimately, independent challenge is not an admission of doubt, but the disciplined stage-gate practice that protects capital by reconciling technical reality with commercial terms before designs are locked, signaling to partners, and your future funders that your project is built to deliver.
To dive deeper into the frameworks that support successful projects, read Relae's white paper: CDR 2.0: Five Pillars of Successful Project Deployment and Delivery and take a look at project assurance in action through our Stockholm Exergi Case Study.
Frequently Asked Questions
What is independent project assurance?
Independent project assurance is a structured review of a capital project by a team that sits outside the project’s delivery organization. Reviewers test the engineering scope, cost estimate, schedule, commercial agreements and permitting position against what funders will require at the next stage gate. The developer receives a clear list of gaps, risks and proposed mitigations prior to presenting the project to lenders, investors or buyers.
When should a developer commission an independent project review?
Periodically throughout the project development process - at a minimum before each major funding gate, but smaller reviews are also beneficial at earlier stages when key concept and technology decisions are being made. A review before Front-End Engineering Design (FEED) tests whether the process concept, site and supply of feedstock, water and power justify the engineering spend. A review before Final Investment Decision (FID) tests whether the cost estimate, EPC structure and binding agreements will satisfy lenders. Site, technology and capacity decisions are cheap to change in pre-FEED and expensive to reverse once detailed engineering starts.
What does an independent project review assess?
Relae structures its reviews around the TECOP framework, which covers five risk areas: technical (technology readiness, mass and energy balances, constructability), economic (capex benchmarking, contingency, financial model resilience), commercial (offtake, feedstock and EPC contracts), organizational (owner’s team capability and stage-gate governance) and political (permitting, regulatory durability and social license). Reviewers also check that technical and commercial decisions are aligned, because projects often fail where the two are developed in silos.
How does an independent project review differ from lender due diligence?
An independent project review applies a holistic approach identifying not only gaps, but also opportunities to add value and strengthen the business case. Lender and investor due diligence is often purely looking at risks and gaps, prior to committing capital. Lender diligence protects the funder and reports its findings at a point when changes are costly and can delay financial close. A developer-commissioned review takes place earlier, so the project team can fix weaknesses in scope, cost or contracts before funders see them.