
Research, Analysis, & Point of View
Original insights from the Relae team on the forces reshaping power systems, GHG emissions, environmental markets, nature, and the capital and policies behind them.
In-Depth Research
Criteria for High-Quality Carbon Dioxide Removal
Criteria for High-Quality Low Carbon Fuels
Carbon Capture for Gas-Fired Power Generation
Blogs
The New Nasdaq Issuance Calendar Advances Transparency in the Carbon Removal Market
Key Takeaways
- The Nasdaq Carbon Issuance Calendar, a new data platform, provides carbon removal buyers and suppliers with standardized information on future offtake availability, indicative pricing, and project maturity. The platform was developed in collaboration with Relae, formerly Carbon Direct.
- The Carbon Issuance Calendar addresses the fragmentation and transparency problems of the voluntary carbon market by centralizing standardized project data and embedding our scientific diligence framework, built over 900 project reviews, giving buyers delivery-risk insight that no registry or marketplace offers today.
- The Carbon Issuance Calendar is an important early step, not the whole journey: it shows buyers what durable tonnes exist and allows them to compare projects with apples-to-apples data.
- Buyers can move from the Carbon Issuance Calendar into technical diligence, contracting, and project assurance with Relae’s advisory team. Suppliers can register to connect with buyers who are ready to engage.
Carbon Removal Project Data Has a Visibility Problem
If you're sourcing durable carbon removal credits, you may run into a familiar wall: project data scattered across dozens of developer websites, presented in inconsistent formats, with no easy way to compare one project against another. If you're a project developer, you face the mirror image of that problem: fielding individual requests for proposals, with no central place to showcase your available tonnes.
Get this wrong, and buyers may end up counting on carbon removal that never shows up - the delivery risk bugbear.
Between 2022 and 2024, high-durability engineered carbon removal made up just 2 percent of all carbon credit issuances. They remain in short supply, particularly the high-quality supply corporate buyers need. The gap is set to widen: our 2026 State of the Voluntary Carbon Market report found that more than 80% of the 2030 high-durability carbon removal projects are at risk of stalling and failing without additional offtake and financing commitments.
The Nasdaq Carbon Issuance Calendar, developed by Nasdaq in collaboration with Relae, offers an important first step toward addressing this information gap.
What Is the Nasdaq Carbon Issuance Calendar?
The Carbon Issuance Calendar is a centralized, accessible dashboard where carbon removal buyers and suppliers view standardized project data: future credit availability, indicative pricing, and project delivery status, all in one place.
The Nasdaq Carbon Issuance Calendar combines structured, developer-provided project data with project maturity assessment informed by Relae’s assessment framework and technical diligence. This helps users understand future CDR availability, indicative pricing, and potential project delivery risk through a single platform.
This expertise didn't appear overnight. It comes from sitting across the table with developers, stress-testing their science, mapping their delivery timelines against reality, and helping them show up to buyers as credible partners. The result is a track record that gives the framework embedded in the Carbon Issuance Calendar its depth. It's a starting point, built for buyers and suppliers to find each other on the basis of consistent, comparable information, using international class financial and information infrastructure.
How Buyers Should Use the Nasdaq Carbon Issuance Calendar
Today, if you're trying to procure durable carbon removal credits, you have no single place to start. You have to visit individual developer sites, request information through scattered channels, and compare projects that present data in entirely different formats before diligence has even begun. In many cases, you are comparing apples to oranges - different kinds of CDR projects with different durabilities, risks, and overall quality.
The Carbon Issuance Calendar provides a central starting point. You can view future credit availability, compare indicative pricing across projects, and begin assessing options without contacting each supplier one by one.
More importantly, the Carbon Issuance Calendar frames the data. Our scientists developed a delivery-oriented lens, built from reviewing over 900 carbon removal projects, drawing on the same rigor behind our Criteria for High-Quality Carbon Dioxide Removal, which we develop annually with Microsoft.
How Suppliers Reach Buyers Through the Carbon Issuance Calendar
If you're a project developer, the Nasdaq Carbon Issuance Calendar tackles visibility, one of the most persistent barriers to market access. You can list available tonnes, display indicative pricing, and reach a global audience of corporate and financial buyers at no cost.
The timing matters. Many first-of-a-kind engineered carbon removal projects are preparing to break ground and need bankable offtake agreements to secure financing before they can do so (a key aspect of CDR 2.0). Our analysis of approximately 140 high-durability carbon removal project developers found scale-up plans for 30 million tonnes of supply per year. Reaching that potential will take real demand: committed forward offtake, increased project equity investment, and access to lending.
Register now: you'll be positioned to connect to buyers actively looking to engage.
How Does the Carbon Issuance Calendar Differ From a Carbon Credit Registry or Carbon Removal Marketplace?
The Carbon Issuance Calendar solves a distinct, early-stage problem. It gives buyers and suppliers a centralized place to find each other and compare options against standardized information, something neither a registry nor a marketplace is built to do.
For a closer look at how registries differ and what you should weigh when navigating them, read our Navigating Carbon Credit Registries report.
Scientific Diligence Turns Visibility Into Confidence
Standardized data tells you what exists. Scientific diligence tells you what's worth pursuing.
Relae’s scientists do that work every day. Our experts apply rigorous pathway-specific criteria to live projects, evaluating delivery risk and status, and identifying where questions remain is the core of what we bring to the carbon removal market.
The Carbon Issuance Calendar puts an accessible version of that expertise at the top of the procurement funnel. It’s for everyone in the market - you don't need to be a carbon removal scientist to use it. This snapshot allows you to compare projects against each other, giving you a meaningful starting point before deeper diligence begins.
Want to go deeper on a specific project? Relae’s technical diligence team picks up right where the Carbon Issuance Calendar leaves off.
What Carbon Removal Projects Are on the Carbon Issuance Calendar Today?
The Carbon Issuance Calendar currently features engineered and hybrid carbon removal projects: direct air capture, biochar, enhanced rock weathering, and bioenergy with carbon capture and storage. These high-durability pathways offer permanence on the order of hundreds to thousands of years.
Many of these projects are at an inflection point: they’re ready to scale but dependent on committed offtake to unlock financing. The Calendar serves their needs, and the buyer’s needs, together.
Nature-based carbon removals have their own criteria and market dynamics. They may appear in a separate segment of the Carbon Issuance Calendar down the line.
From the Carbon Issuance Calendar to Completed Carbon Removal Procurement
If you're building or refining a carbon removal procurement strategy, the Carbon Issuance Calendar is the right place to start.
From there, you can choose to work with the Relae advisory team to support every later stage: technical diligence on specific projects, contracting and negotiation support, ongoing project assurance, and access to curated carbon credit sourcing. The Carbon Issuance Calendar surfaces the market; we help you navigate it, connecting you with the right developers, on the right terms, with the scientific confidence to move forward.
Moving from commitment to delivery takes structural change across the market, too—our CDR 2.0 white paper lays out the five pillars we see as essential to getting engineered and hybrid carbon removal projects built and delivering.
Independent Project Assurance Is Likely Your Best-Returning Spend
Key Takeaways
- The decision to fund a project is determined by a holistic review of project development maturity. This applies across capital-intensive projects, including low-carbon power generation, carbon capture and storage (CCS) solutions, sustainable aviation fuel (SAF), and broader transition infrastructure build-out. Both technical and commercial workstreams must be developed in parallel to avoid project failure.
- Early scope decisions, such as site selection, core technology selection, and nameplate capacity, are cheap to make but become exponentially disruptive and costly to reverse.
- Independent challenge and verification is tangible evidence of a disciplined, well-managed capital development process.
Bridging the Gap from Announcement to Delivery
Among project developers, a perception often persists: seeking external review signals a project in distress. In capital budgeting discussions, subjecting engineering scope and commercial assumptions to third-party interrogation can be misconstrued as a vote of no confidence in the primary delivery team.
In reality, the reverse is true. Across complex infrastructure, independent challenge is the disciplined stage-gate practice that protects capital by reconciling technical reality with commercial terms before designs are locked.
Independent Challenge Is a Sign of Strength, Not Doubt
Across capital projects, and in particular within emerging low-carbon industrial infrastructure, the gap between announced projects and delivered assets remains stark. Data from the Mission Possible Partnership’s Global Project Tracker reveals that fewer than 17% of announced commercial-scale clean industrial facilities worldwide have reached Final Investment Decision (FID) or commercial operations, leaving more than 800 major decarbonization projects stalled in front-end development.
The causes of developmental paralysis are multifaceted. While macroeconomic interest rate shifts and global supply chain disruptions sit largely outside a developer's control, project definition and developmental discipline remain entirely manageable. Even amid external volatility, a project designed with resilience will have a far greater likelihood of success.
Independent review and assurance directly strengthen a project’s chance of success and overall value. Large global project delivery organizations have applied this discipline for decades by deploying independent teams to evaluate project readiness at every stage gate. For teams lacking a dedicated internal oversight organization, or those deploying first-of-a-kind facilities, third-party independent review provides the necessary rigor to facilitate project success.
Relae’s (formerly Carbon Direct) work with Stockholm Exergi is a clear example: independent assurance helped build funder and regulator confidence in a first-of-a-kind carbon removal facility with no direct precedent to benchmark against.
Why Projects Stall Between Announcement and FID
Low-carbon infrastructure and net-zero industrial projects carry unique risks compared to the repeat delivery of established designs. Exciting new developments run a higher risk of falling victim to optimism bias or compressing development timelines to meet public announcement milestones.
It is a natural human tendency for project champions to focus on the upside during early development. However, early momentum must be balanced with processes that reintroduce industrial lessons, supply-chain realities, and operational resilience.
Front-End Loading (FEL) is a well-evidenced approach for improving capital project outcomes. Decades of benchmarking by Independent Project Analysis (IPA) show that approximately two-thirds of industrial megaprojects suffer capital cost overruns or schedule slippage of 25% or more, or encounter severe operational problems lasting more than two years post-startup. This pattern is repeating in low-carbon infrastructure: IPA’s analysis of 12 completed low-carbon projects found average cost escalation of 31% and schedule slip of almost 50%. Rigorous front-end definition remains the single strongest predictor of whether a project will achieve its cost and schedule targets.
As highlighted in the CDR 2.0: Five Pillars of Successful Project Deployment and Delivery report published by Relae, projects falter when developers push ahead without stress-testing the full delivery framework. Stage gate reviews are the mechanisms that evaluate the total project concept and underlying business case. They are most effective when executed as independent cold-eye evaluations prior to each funding gate, identifying and mitigating vulnerabilities long before final investment decisions are reached.
What Funders Need to See at Each Gate
Different stages of project development rely on distinct capital sources, each requiring specific proof points before deploying funds.
Before FEED Funding: Justifying the Engineering Spend
Front-End Engineering Design (FEED) is a major financial commitment, typically costing between 2% and 4% of total project capital cost. The funders backing this stage are usually the developer’s own balance sheet equity, strategic partners, or public grant programs. Before allocating millions of dollars to detailed engineering, these funders need confidence on the fundamentals:
- A technically sound process concept, confirmed utility balances, and an energy integration scheme that fits the site.
- Secured site control, clear zoning pathways, and no environmental fatal flaws that could derail permitting.
- Documented availability of required feedstocks, water and power, paired with demonstrable interest from target off-takers.
Before FID: Proving Bankability and Commercial Closure
As a project approaches FID, the funding audience shifts to conservative commercial lenders, infrastructure funds, and binding offtake counterparties. These capital providers are not underwriting strategic vision; they are underwriting long-term operational cash flows and debt service. Depending on the project and financing structure, capital providers may require:
- A high-confidence capital cost estimate (AACE Class 2 or Class 3) backed by frozen Piping and Instrumentation Diagrams (P&IDs), firm equipment quotes, and a realistic execution schedule with clear critical paths.
- Bankable engineering, procurement, and construction (EPC) structures that clearly allocate risk, include performance guarantees and enforceable liquidated damages.
- Fully executed, binding offtake and feedstock agreements, along with non-appealable permits and completed utility interconnection agreements, with remaining conditions clearly understood.
- An objective, third-party challenge review that assesses operational viability and distinguishes an executable engineering plan from an aspirational concept.
Commercial and Technical Co-Development: The Stage-Gate Method in Practice
A project rarely fails because of an isolated mechanical issue or a purely commercial misstep; failure happens when technical decisions and commercial terms are negotiated in silos and decisions are made without understanding of the wider implications.
We see this disconnect play out in several ways, including:
- Sizing capacity before testing market demand: An engineering team may size a facility to maximize thermodynamic efficiency and economies of scale, only for the commercial team to discover buyers will only commit to half that volume. The developer is left with an oversized, unbankable design requiring fundamental rework.
- Setting product specifications before negotiating offtake: Process engineers frequently design systems around standard vendor packages. However, when downstream transport, processing, or storage networks enforce strict purity standards, the facility faces costly equipment redesigns. This issue has materialized directly within European CCS networks. Open-access offshore storage operators, such as Norway's Northern Lights project, established strict cross-border CO2 specifications requiring tighter moisture and impurity thresholds than originally designed for.
- Locking Electrical Loads Prior to Interconnection Verification: As detailed in Relae’s analysis of physical infrastructure bottlenecks, scale is rarely constrained by capital availability; it is dictated by electrical transmission queues, substation headroom, and 24/7 firm power availability. Freezing electrical demand before verifying utility interconnection timelines risks stranding engineering work on an asset that cannot connect to the grid.
How Relae Stress Tests Projects at Each Gate
Independent reviews at each stage-gate improve success rates by stress-testing assumptions before presenting to lenders, infrastructure investors, or corporate buyers. Relae reviews projects across five categories using the TECOP framework:
- Technical: Verifying technology readiness levels (TRL), mass and energy balances, plot plan constructability, and operational availability under real-world conditions.
- Economic: Capex benchmarking, operating contingency adequacy, utility tariff sensitivities, and financial model cash-flow resilience.
- Commercial: Offtake agreement structures, feedstock contracts, contracting boundaries, EPC contract structures, and counterparty creditworthiness.
- Organizational: Owner's team capabilities, internal stage-gate governance, contractor oversight mechanisms, and execution capabilities.
- Political: Statutory permitting status, regulatory durability, carbon market policy exposure, and local community social license.
The TECOP framework is relevant for evaluating delivery risk across all project types, see more in Relae’s Criteria for High-Quality Carbon Dioxide Removal, Delivery Risk Appendix.
What makes this approach effective is sitting on both sides of the table. Having completed over 250 deep-dive technology reviews, 900+ project evaluations, and advised on more than $6 billion in industrial project finance, Relae has extensive experience evaluating the considerations important to institutional funders and buyers.
The Value of Early Independent Project AssuranceIncorporating independent review should be standard practice for modern infrastructure delivery. Because funders will perform their own rigorous diligence regardless, conducting an independent evaluation early enables developers to address vulnerabilities proactively and present a more resilient business case.
Commissioning an independent team for a cold-eye review during early project formation can be a cost-effective way to identify potential risks before they become expensive to address. Catching an unworkable process assumption, an oversized capacity plan, or a misaligned commercial interface during pre-FEED costs a tiny fraction of what it takes to fix those issues during construction
Ultimately, independent challenge is not an admission of doubt, but the disciplined stage-gate practice that protects capital by reconciling technical reality with commercial terms before designs are locked, signaling to partners, and your future funders that your project is built to deliver.
To dive deeper into the frameworks that support successful projects, read Relae's white paper: CDR 2.0: Five Pillars of Successful Project Deployment and Delivery and take a look at project assurance in action through our Stockholm Exergi Case Study.
Frequently Asked Questions
What is independent project assurance?
Independent project assurance is a structured review of a capital project by a team that sits outside the project’s delivery organization. Reviewers test the engineering scope, cost estimate, schedule, commercial agreements and permitting position against what funders will require at the next stage gate. The developer receives a clear list of gaps, risks and proposed mitigations prior to presenting the project to lenders, investors or buyers.
When should a developer commission an independent project review?
Periodically throughout the project development process - at a minimum before each major funding gate, but smaller reviews are also beneficial at earlier stages when key concept and technology decisions are being made. A review before Front-End Engineering Design (FEED) tests whether the process concept, site and supply of feedstock, water and power justify the engineering spend. A review before Final Investment Decision (FID) tests whether the cost estimate, EPC structure and binding agreements will satisfy lenders. Site, technology and capacity decisions are cheap to change in pre-FEED and expensive to reverse once detailed engineering starts.
What does an independent project review assess?
Relae structures its reviews around the TECOP framework, which covers five risk areas: technical (technology readiness, mass and energy balances, constructability), economic (capex benchmarking, contingency, financial model resilience), commercial (offtake, feedstock and EPC contracts), organizational (owner’s team capability and stage-gate governance) and political (permitting, regulatory durability and social license). Reviewers also check that technical and commercial decisions are aligned, because projects often fail where the two are developed in silos.
How does an independent project review differ from lender due diligence?
An independent project review applies a holistic approach identifying not only gaps, but also opportunities to add value and strengthen the business case. Lender and investor due diligence is often purely looking at risks and gaps, prior to committing capital. Lender diligence protects the funder and reports its findings at a point when changes are costly and can delay financial close. A developer-commissioned review takes place earlier, so the project team can fix weaknesses in scope, cost or contracts before funders see them.
Introducing the Diligence Collection: High-Quality Carbon Removal, Vetted
Key Takeaways
- Relae (formerly Carbon Direct) has conducted over 900 comprehensive, rigorous reviews of carbon removal (CDR) projects around the world. But fewer than 10% meet our standard for high-quality. In today’s market, scientifically-credible CDR supply is scarce.
- To identify high-quality projects, buyers and investors previously had to commission numerous deep diligences, which often made it a lengthy and complex process, not well-suited to most market participants.
- The Diligence Collection changes that paradigm by giving you direct access to existing comprehensive analysis on a curated set of high-quality CDR projects. The hard work of identifying high-quality projects is already done, allowing you to move faster, spend less, and procure with more confidence.
Relae Sets the Bar for High-Quality CDR
Since 2020, every year Relae has released an updated version of the Criteria for High-Quality Carbon Dioxide Removal in collaboration with Microsoft. The Criteria set the standard for scientific rigor across nine CDR pathways and across six technical dimensions. Using this standard, the Relae team has conducted diligence on over 900 CDR projects across 63 countries. Our diligence has been used for over 50% of all tonnes contracted through announced CDR offtake agreements worldwide, including diligence for the majority of tonnes from Microsoft’s announced offtakes. This gives Relae a uniquely deep understanding of the CDR market; and importantly, it has highlighted that high-quality projects in the voluntary carbon market are scarce.
Quality Is the Central Challenge in CDR Procurement
Only 10% of the projects that Relae has assessed meet our high-quality criteria. This means that without rigorous, scientific assessment, buyers and investors run real risk of exposing themselves to delivery shortfalls, financial loss, and reputational damage.
This presents a series of challenges to buyers and investors interested in procuring or investing in CDR. Conducting diligence on CDR projects is time-intensive, complex, and requires deep expertise. Building the internal capacity to rigorously evaluate a wide variety of CDR projects isn’t practical for most actors. But conducting the in-depth diligence required to procure or invest confidently requires real commitment, especially when a significant proportion of the projects diligenced may not be high-quality. Finding the needle in the CDR haystack isn’t easy.
The Case for Curated CDR
The Diligence Collection directly addresses these challenges by providing self-serve access to diligence on a curated set of high-quality CDR projects vetted by Relae. Every project has already been evaluated against the Criteria for High-Quality Carbon Dioxide Removal, the science-based benchmark jointly established by Relae in collaboration with Microsoft. The Collection includes projects reviewed on behalf of Microsoft and other major buyers, and more broadly reflects our diligence work across the market.
With the Diligence Collection, you're not starting from scratch. Instead, you're starting from a shortlist of some of the highest-quality CDR opportunities available, with robust scientific diligence to back them up. The bottleneck that's slowed procurement for so many organizations is no longer a concern.
The Collection offers two levels of diligence, matched to the level of scrutiny your commitment warrants:
- Desk review: An executive-level assessment using available project documentation, enough to make an informed shortlisting decision or purchase.
- Deep diligence: A comprehensive technical evaluation covering project design, operational risk, technology assessment, policy landscape, and community impacts, reflecting the same methodology that's informed the procurement programs of Microsoft and other major buyers.
Both tiers include the option to commission an updated evaluation as your needs evolve.
What Rigorous CDR Diligence Involves
The depth of Relae’s diligence sets the Diligence Collection apart. Our desk review process involves conducting detailed assessments to evaluate projects against 6 quality principles: social harms, benefits, and environmental justice; environmental harms and benefits; additionality and baselines; measurement, monitoring, reporting, and verification; durability; and leakage. The result is a comprehensive report that assesses projects against these criteria, highlighting the project's overall quality, strengths, and weaknesses in a clear, succinct way that supports decision-making.
Many of our reports dig even deeper. Our deep diligences assess both a project’s quality and its delivery risk. To evaluate delivery risk, we assess projects across 5 elements: technologic, economic, commercial, operational, and political. Deep diligence is conducted over 3-4 months, which includes weekly back-and-forth with the supplier and a site visit to understand all of the nuances of the project and validate developer claims on the ground. The resulting report not only documents a project's strengths and weaknesses, but also outlines risk mitigation measures and recommends improvements over time.
Broader Access, Stronger Market
Forward offtake demand in the CDR market has historically concentrated among a handful of large buyers, and as our 2026 State of the Voluntary Carbon Market report notes, diversifying that pool is essential to enabling the next generation of CDR supply. The Diligence Collection is built to support exactly that. By making the scientific rigor behind the world's largest CDR transactions available through a self-service platform, it opens credible procurement to organizations at any stage of purchasing. More buyers accessing high-quality, de-risked projects means more capital flowing to suppliers, more projects able to scale, and a more resilient market that doesn't depend on a small number of actors to function.
High-quality CDR supply is scarce, and the best projects are in high demand. The Diligence Collection gives you the foundation to act efficiently and with confidence, without starting from zero.
[cta]
Frequently Asked Questions
Who Can Access the Relae Diligence Collection?
The Diligence Collection is available to approved subscribers, including CDR buyers and investors seeking to more efficiently evaluate carbon removal projects. To preserve the independence and integrity of the Collection and protect proprietary diligence insights, access is not available to project developers or rating agencies.
How Is the Relae Diligence Collection Different From a Rating Agency or Market Intelligence Platform?
Most rating platforms optimize for quantity; we optimize for quality. Our process includes pathway-specific risk assessments and, in many cases, site visits from our in-house scientists, engineers, and technical experts—the same multidisciplinary team and judgment behind our own portfolio decisions and the procurement programs we support directly. The Collection also includes projects diligenced before they've received external ratings, giving you visibility into promising opportunities at the pre-commercialization stage.
Does Inclusion in the Relae Diligence Collection Mean Relae Endorses a Project?
Inclusion means a project was evaluated through our scientific diligence process and, at the time of review, met our Criteria for High-Quality Carbon Dioxide Removal. It reflects a positive diligence outcome based on the information available during the review and the project's stage of development at that time. As projects and market conditions evolve, we recommend considering whether updated diligence or additional evaluation is appropriate for your specific procurement or investment objectives.
Can I Request Diligence on a Project That Isn't Already in the Collection?
Yes. You can commission us to diligence a specific project based on your procurement or investment priorities. Whether it's later added to the Diligence Collection depends on a few factors beyond just meeting our quality bar, including consent from you as the commissioning buyer and approval from the project developer.
The Six Policy Responses States Used to Legislate Data Centers in 2026
Key Takeaways
- Community opposition to data center development has become a national conversation, and state legislatures are now responding with a broad spectrum of policy responses to address constituent concerns.
- Relae’s policy experts have identified six broad categories of policy responses: tax incentives, disclosure requirements, transparency rules, cost allocation, incentive clawbacks, and moratoria. In 2026, incentive bills are stalling while disclosure, cost allocation, and clawback bills are advancing.
- The shifting action of state legislatures across these categories can guide developers on the relative political openness or opposition to data center developments across the United States, and should inform site selection and investment decisions.
- Every state legislature will be back in session in 2027, including major data-center markets like North Dakota, Nevada, and Texas that sat out 2026, so this picture will keep changing.
Which States Are Getting Harder to Build In
Community concerns have translated into opposition, delaying, derailing, or altogether denying projects. Local debates over land, water, and electricity prices have moved into statehouses as a result.
If you're trying to figure out "Which states are becoming harder (or easier) to site a data center in, and why?", the state legislature is where that answer is being written. Last year, we tracked the initial wave of state bills on data centers. This year, the volume of bills has grown. The policy categories we used last year still broadly hold, but the distribution of emphasis across these categories has shifted significantly.
Relae’s policy experts reviewed the bills introduced in 2026 legislative sessions related to data centers and identified six categories of policy responses available to a state: tax incentives (“reward it”), disclosure requirements (“review it”), transparency rules (“reveal it”), cost allocation (“shape it”), incentive clawbacks (“revoke it”), and moratoria (“stop it”). These categories do contain some overlap, but together they show a range of what legislatures are trying.
Each response answers at least one of three questions local communities have been posing for over a year now: Who bears the costs of new generation, transmission, and other grid upgrades? What are constituents entitled to know about data center developments in their region? Who decides whether a project goes forward?
For each policy response, we selected at least one representative bill that is either most consequential financially or most impactful to developer timelines. Notably, states with significant data center development pressure, such as North Dakota, Nevada, and Texas, did not have regular sessions in 2026, meaning the scope of policy responses reflected here is not exhaustive.
Six State Policy Responses to Watch for Data Center Siting and Investment
Which policy response a state reaches for, and how that bill fares in the legislative process, signals how politically open or resistant it currently is to new data center development. That political landscape should directly inform data center site selection and investment decisions - and it’s changing quickly.
1. Reward It: Data Center Tax Incentives and Subsidies
These bills try to attract data centers by giving them a financial reason to locate in a state. We call this response "reward it." It typically means property tax exemptions, sales tax breaks on equipment, or reduced utility taxes, usually in exchange for a minimum investment and a job-creation commitment.
West Virginia Senate Bill 623, the “West Virginia-Powered Data Center Incentive Act,” would have exempted data center equipment from property taxes and cut business taxes for the utilities supplying power to the data center. To qualify, a data center would have needed to invest at least $50 million, create 50 jobs, and run on coal-generated electricity for at least 80% of its operational capacity. The bill died in committee without a vote, which is emblematic of how this category of bills fared in 2026.
Relative to the approximately 50 bills introduced (and 9 passed) in 2025 that provided tax incentives for data centers, this category declined significantly in the 2026 session. Part of the drop off could also be a product of the current tax laws of many states, which already include substantial tax incentives for data centers.
For developers, this is the category to watch shrink: fewer states are actively competing to hand out new incentives, so existing programs may be close to the extent of what's on offer going forward.
2. Review It: Data Center Disclosure Requirements
Under what we call the "review it" response, these bills require specific information to be shared with regulators or grid operators before or while the project is built, usually about power demand, interconnection plans, or backup generation.
Pennsylvania House Bill 1834, the “Data Center Act,” would direct the state’s Public Utility Commission (PUC) to oversee commercial data centers with a peak demand of 25 megawatts or greater. It would require disclosure of information relating to interconnection requests as well as planned backup generation. It would also fast-track interconnection for facilities that bring incremental clean firm resources. That disclosure helps grid planners in PJM spot duplicate projects in their interconnection queue, while also helping state leaders to understand if projects in the state are in jeopardy of being lured elsewhere. The House passed the bill 104-95, and is awaiting action in the Senate.
This category, which also includes bills that require disclosure of information around environmental impacts and power or water usage, has grown in 2026. Pennsylvania has been at the center of many discussions around data centers and utility affordability this year. Governor Josh Shapiro's initiative on utility affordability identifies data center load as the pressure point while a wider discussion evolves in PJM over capacity costs.
3. Reveal It: Data Center Transparency Rules and NDA Bans
This is a new category in 2026. We call it the "reveal it" response: bills that stop public officials from signing non-disclosure agreements about data center projects. The goal is to inform residents about who is behind a proposed facility and how much power it will use.
Ohio House Bill 695 would bar county commissioners, township trustees, village mayors, and council members from entering into nondisclosure agreements (NDAs) related to their official duties. It directly targets the NDAs that have kept local officials from telling residents who is behind a proposed project or how much power it would consume. The Ohio legislature is in session until December 17, and the bill is still awaiting action in committee. A similar bill in Pennsylvania, House Bill 2359, would tie NDA prohibitions to a data center sales tax exemption. That bill has passed the House and is also currently pending in the Senate. Separately, in August, Gov. Shapiro banned NDA use outright on any data center project the state oversees.
4. Shape It: Data Center Cost Allocation and Ratepayer Protection
These bills aim to allocate more of the grid infrastructure costs associated with upgrades to the data center. New power lines, substations, and other transmission costs fall on the data center, not on everyone else's electric bill, under what we call the "shape it" response.
California Senate Bill 886, the California Technology Innovation and Ratepayer Protection Act, was signed into law by Governor Gavin Newsom on September 21, 2026, as part of a seven-bill data center package. It passed the Senate 28-10 and the Assembly 49-7. It requires the California PUC to establish or update electricity tariffs by January 1, 2028, for data centers entering new transmission-level interconnection agreements on or after January 1, 2027. Under it, developers bear the cost of transmission upgrades and face a 10-year early termination fee if they back out or fail to reach capacity. This is a strong template for keeping the costs of serving large loads from impacting retail ratepayers, and similar bills should be expected in other states in 2027.
5. Revoke It: Data Center Incentive Clawbacks
These bills take back or narrow tax breaks a state already granted (the "revoke it" response), usually once lawmakers start weighing what those incentives are actually costing the state against what they bought.
Washington Senate Bill 6231, signed into law by Governor Bob Ferguson in April, will remove the sales tax exemption for replacing or refurbishing existing server equipment. The category of bills revoking previous tax incentives for data center development and operation has grown substantially as more states are starting to reconsider the large incentives they put into place at the beginning of the data center boom. Over 50 bills in more than 20 states have sought to restrict data center incentives in 2026, including New Jersey Senate Bill S4390, which was signed into law in August.
6. Stop It: Data Center Development Moratoria
These bills seek to temporarily restrict certain new data center development outright (the "stop it" response), usually for a fixed period while the state studies the impact on the grid, water use, or electricity rates.
New York Senate Bill S10642/Assembly Bill A11560, the Responsible Data Center Development Act, would impose a permit moratorium on data centers of 20 megawatts or more. It passed the legislature on June 4th and is awaiting action by Governor Kathy Hochul. If signed into law, it would be the first moratorium enacted through a legislature. Separately, Governor Hochul has issued an executive order to establish a temporary moratorium on data centers, though her order only applies to facilities of 50 megawatts or more.
This category did not exist a year ago within state legislatures, but as public concern about data centers has grown, several moratorium bills have been introduced. Maine’s LD 307 passed through the state legislature and would have done the same, but was vetoed by Governor Janet Mills in April. In Texas, Governor Greg Abbott has issued orders to state agencies to halt data center approvals in ERCOT until audits can be completed, and in September, he expanded the pause to also cover a review of environmental permits.
It is important to note that many of the moratoria put in place at the state level, whether through the legislature or via executive action, are temporary, usually one year in duration. Often, the moratoria being considered include a plan to study the impacts of data centers on communities and whether utility rates may rise.
What to Watch in 2027
The most consequential policies in 2026 didn’t come through legislatures. They came from executive action by the governors of New York and Texas, which went further than any legislature with respect to their financial and commercial impact. The outcome of the 2026 midterm elections will shape the appetite of both the legislative and executive branches for additional action. In addition, every state legislature will be in session in early 2027, including North Dakota, Nevada, and Texas, which all sat out 2026, so we expect significant policy developments to continue at the state level next year.
In legislatures, the pattern across all six policy responses points in the same direction: recent legislative activity suggests that some states are moving from attracting data center development through incentives toward imposing additional conditions, oversight requirements, or restrictions on new development. Fewer bills providing new incentives for data centers are being introduced or are stalling in legislatures, while bills on cost allocation, disclosure, incentive reduction, and permitting are advancing more successfully.
Map Your State's Regulatory Risk
Site selection and investment decisions increasingly hinge on which of these six responses a state is pulling, and how fast that can change. Talk to our Policy Advisory Team about what a state's current and pending legislation means for a specific project or portfolio.
Beyond Backup Generators: Hydrogen as Baseload Power for AI Infrastructure
Key Takeaways
- Speed to operation is the value proposition. While grid interconnection can take 3-5 years in constrained regions, hydrogen fuel cell systems can be deployed in a fraction of that time—a large advantage for operators racing to meet data center capacity demands.
- Hydrogen is moving beyond backup. Fuel cells could supply 6-15% of incremental data center power, functioning as primary or near-primary power rather than emergency standby.
- Higher fuel costs can be rational. When the alternative is a multi-year wait for grid power and the development loss that comes with it, paying a premium for hydrogen is better than falling behind.
The Grid Can’t Keep Up With Data Centers
The data center infrastructure buildout is moving at a pace the US power grid was never designed to accommodate. Cleanview tracks about 63 GW of operating US data center capacity and another 392 GW in planning, roughly six times what exists today. Developers in high-demand corridors—Northern Virginia, Central Texas, Phoenix—are finding that the grid can't deliver new capacity fast enough.
Interconnection queues now stretch 3-5 years in many regions, and that’s before accounting for permitting, transmission upgrades, and substation buildouts. For operators that need power online faster than the grid can deliver it, this timeline gap is a fundamental constraint on the business.
This mismatch between AI deployment, generator bottlenecks, and grid timelines is why hydrogen is entering the conversation as a viable power option for a growing subset of data center deployments, alongside natural gas with carbon capture, geothermal, and long-duration energy storage.
Hydrogen Fuel Cells: From Standby to Primary Power
For most of its history in data centers, hydrogen has been discussed as a cleaner replacement for diesel backup generators. That framing undersells the opportunity.
The shift happening now is more fundamental: hydrogen fuel cells are being evaluated as primary or near-primary power sources for behind-the-meter and facilities that can’t wait for grid connection. Notably, many modern fuel cell systems—including solid oxide fuel cells—can run on natural gas today and transition to hydrogen as clean supply becomes available. Bloom Energy's 2024 deal with American Electric Power to provide up to 1 GW of fuel cells for data center power illustrates this approach: the systems will initially run on natural gas, with the capability to switch to 100% hydrogen in the future.
Furthermore, fuel cell systems are modular, can be deployed incrementally as load grows, and provide continuous power output. This is a promising path, and one that will scale only as fast as the fuel cell supply chain can keep up. Unlike solar or wind, fuel cells aren’t weather-dependent. Running on hydrogen, they produce zero direct emissions at the point of use. Running on natural gas, they still emit CO2, but their higher efficiency gives them a lower carbon intensity than a comparable gas turbine.
Goldman Sachs estimates that fuel cells could supply 6-15% of incremental data center power (the estimate doesn't specify fuel mix, though most near-term deployments would run primarily on natural gas). This is a meaningful share of new capacity, driven largely by operators who face years-long waits for both grid connections and new gas turbines. Bloom Energy, whose fuel cell products serve data center applications, has been a notable outlier in an otherwise struggling hydrogen sector, with its stock rising sharply on strong revenue performance and growing investor enthusiasm around data center power demand.
Speed to power depends on the fuel. Solid oxide fuel cells run on pipeline natural gas today, so operators do not wait for a hydrogen supply chain. Bloom states it can deliver onsite power for an entire data center in as little as 90 days, with the ability to add modules as load grows under certain circumstances. In all but a few select locations, hydrogen comes later when the same systems switch fuels as clean supply scales. Projects that need hydrogen from day one face additional challenges. Limited hydrogen availability and supporting infrastructure across much of the US can undermine the potential speed advantage of hydrogen-dependent projects. Nevertheless, locations with suitable hydrogen supply and supporting infrastructure may offer viable near-term opportunities.
The Hydrogen Premium: When Paying More Makes Sense
Hydrogen-generated power is more expensive than other forms of electricity generation in most markets. The logistics penalty (including compression, transport, and storage) can push hydrogen from $4/kg at the production site to $8-16/kg delivered, making the economics look unfavorable on a simple $/MWh comparison. In practical terms, hydrogen at $4-6/kg translates to roughly $120-180/MWh on an energy-content basis (LHV). At a fuel cell electrical efficiency of around 50%—typical for solid oxide systems—the effective cost of electricity rises to approximately $240-360/MWh for co-located production, compared to $40-60/MWh for natural gas fuel cells, $51-129/MWh for gas combined cycle, and $144-276/MWh for gas peakers. Operators can improve hydrogen economics by co-locating with production, avoiding the logistics penalty that can double or quadruple delivered costs.
While expensive, this cost comparison misses the central point. The relevant question is not whether hydrogen is cheaper than grid power, but whether it is better than having no access to power at all.
For an operator with signed contracts and a 100 MW facility sitting idle during a multi-year interconnection queue, the opportunity cost is substantial. At average US wholesale colocation rates (~$196/kW/month - a record high), a facility of that size represents roughly $235 million per year in potential revenue—meaning even a single year of delay can outweigh years of hydrogen fuel premiums.
The Inflation Reduction Act’s 45V Production Tax Credit further compresses the gap, offering up to $3/kg for clean hydrogen production—but projects must begin construction by December 31, 2027, to qualify. That deadline adds urgency to what’s already a time-sensitive calculus.
Reframing the Cost Debate for Speed-to-Power
The debate about whether hydrogen is cost-competitive with grid power misses the strategic challenge facing data center operators today: the fastest path to reliable, clean power. Hydrogen can play a consequential role in that timeline in some markets.
Assessing that requires modeling the full picture: grid interconnection timelines, hydrogen supply chain costs at a specific location, the 45V credit’s impact on project economics, and how hydrogen compares to batteries and other bridging technologies for a data center’s particular load profile.
Relae’s advisory team helps data center operators and technology companies evaluate these tradeoffs with rigorous, independent analysis. If speed to operation is a factor in your energy planning, let’s talk.
Frequently Asked Questions
How much faster is hydrogen fuel cell deployment than waiting for grid interconnection?
Grid interconnection in constrained regions can take 3-5 years once permitting, transmission upgrades, and substation buildouts are factored in. Fuel cell systems, especially those that start on natural gas and then transition to hydrogen, can be deployed in a fraction of that time. They are modular and can be installed and scaled incrementally as a facility’s load grows, though the pace depends on equipment and fuel supply.
If hydrogen costs more than grid power, why would an operator choose it?
For an operator with a 100 MW facility sitting idle during a multi-year interconnection queue, the lost revenue—roughly $235 million a year at average US wholesale colocation rates—can outweigh years of hydrogen’s fuel premium. That makes the higher cost a rational tradeoff against a multi-year wait for grid power, not just an expensive alternative to it.
Do hydrogen fuel cell systems have to run on pure hydrogen from day one?
No. Many modern fuel cell systems, including solid oxide fuel cells, can run on natural gas today and transition to hydrogen as clean supply becomes available. Bloom Energy’s up to 1 GW agreement with American Electric Power follows this model: the systems start on natural gas, with the capability to switch to 100% hydrogen as the hydrogen supply chain matures.
Data Centers Need a New Approach to Community Benefits
Key Takeaways
- Community Benefits Agreements (CBAs) have existed for two decades, and the data center buildout is exposing where the legacy model breaks.
- Across 46 cancelled or stalled US data center projects that Relae analyzed, late-stage benefits packages may be insufficient to change outcomes. Process, transparency, and proof of delivery did.
- The next generation of CBAs, especially for data centers, needs to be meaningful in scope and community voice, measurable in delivery and outcomes, and durable across political and generational divides.
Communities Are Rejecting the Legacy Benefits Model
In a white paper published earlier this year, Relae documented 46 US data center projects that were cancelled, stalled, or withdrawn between January 2024 and May 2026. Together, these projects represent more than US$170 billion in announced investment associated with projects canceled, stalled, or withdrawn following community opposition. Developers led with projects that included reactive communications and limited benefits packages negotiated under the pressure of rapid development timelines and local permitting and approval processes.
[stat]
Across these cases, local communities expressed concerns ranging from environmental and natural resource concerns to electricity rate impacts, to the lack of transparency and accountable development approaches. Even more importantly, communities do not clearly see how AI-driven data center development directly benefits them and advances their priorities and local social and economic goals.
The legacy community benefits models that data center developers are deploying were designed for a different kind of project, in a different political context. The public and local communities are demanding a new model to meet the current moment.
What Is a Community Benefits Agreement? A Brief History of CBAs
Community Benefits Agreements, or CBAs, have been a feature of US infrastructure development for twenty years. The foundational practitioner manual was published by Julian Gross, Greg LeRoy, and Madeline Janis-Aparicio in 2005, and the Partnership for Working Families coalition has carried the practice forward since.
The frame has expanded. Just Transition principles from labor and climate justice coalitions, the former federal Justice40 Initiative, and contemporary CBA templates from civil rights organizations like the NAACP have pushed the field toward binding equity commitments, durable community ownership stakes, and, where Indigenous or culturally significant sites are implicated, free prior and informed consent. These frameworks moved the field forward.
Relae examined CBAs across 40 US climate and clean energy projects in our prior white paper, Codifying Community Benefits in US Climate and Clean Energy Projects. Our analysis found that developers now routinely integrate multiple benefit types, including fiscal, workforce, infrastructure, environmental, and procedural commitments. CBAs for climate and clean energy projects have evolved, and this has brought many improvements, even though imperfections remain. The absence of a shared standard for defining and monitoring those benefits can leave outcomes uneven and often inequitable across host communities. Some efforts attempted to create a unified structure. For example, the Department of Energy had a Community Benefits Plan requirement on every Bipartisan Infrastructure Law and Inflation Reduction Act application, weighted at twenty percent of technical review.
Even still, these models were subject to political whims and did not advance localized and community-driven benefits. The gap now is in the timing, verification, and enforcement layer that turns those commitments into outcomes.
Community Data Center Opposition Is Breaking the Old CBA Model
Data center capital is arriving faster than any wave of large-load infrastructure since the shale gas boom. BCG estimates hyperscalers will spend US$1.8 trillion on data center-related capex in the US between 2024 and 2030. According to Dell'Oro Group, the four largest US cloud providers (Amazon, Microsoft, Google, and Meta) spent over US$340 billion in 2025 alone, with Amazon leading at $125 billion. Communities are responding faster, too. According to both Data Center Watch and Relae's own Data Center Cancellations Tracker, the opposition wave documented is mobilizing in weeks, not months.
Data center opposition in the US is bipartisan. It spans red and blue counties, every region, and multiple grid operators, with nearly two-thirds of the blocked investment sitting in counties that voted for Donald Trump in 2024.
By the time a developer reaches a public hearing with strong local community organization, the path of the project is largely set. Late-stage benefits packages that are offered as contractual agreements to side-step community concerns are proving to be ineffective. Communities read them as concessions, not commitments. Good Jobs First has now turned that critique on the data center sector, warning that hyperscale developers risk using the CBA label to whitewash bad deals.
What Makes a Community Benefits Agreement Actually Work?
The next generation of community benefits needs to pass three tests: meaningful, measurable, and durable.
1. Meaningful. Benefits should be calibrated to the host community's burden and vulnerability profile and be developed in collaboration with local community leaders and community-based organizations. Developers should draw on best-in-class methods in environmental justice analyses to help develop strong and responsible community engagement plans to involve residents and impacted communities in data center design decisions. Communities most exposed to siting harm must be at the table on equal footing with adjacent jurisdictions.
2. Measurable. For developers to be accountable to local communities, benefits frameworks need to include metrics for tracking and verifying both investment and outcomes. SMART (specific, measurable, attainable, relevant, and time-bound) milestones, independent monitoring, and secured financial obligations should be the default, not the exception. Historically, DOE's Community Benefits Plan requirements provided an example of incorporating measurable community commitments into federal funding applications. Although these federal requirements have since been rescinded, their emphasis on specific milestones and accountability offers lessons for voluntary community benefits frameworks and have set a usable floor, with at least one specific, measurable, achievable, realistic, and time-bound milestone per budget period. RMI's analysis shows how that floor translates to project-level design. The same logic applies to data centers. If a commitment cannot be measured by the community, it is not a commitment.
3. Durable. Benefits have to survive political winds and local electoral politics. Any benefits that a developer delivers should also be intergenerational in scale, or at least be scaled to the planned lifecycle operations of the data center itself. A CBA built only on conversations negotiated in a closed room will not hold. Durable benefits are written with enforcement mechanisms, conditional triggers, and modification rights that the community can exercise. The strongest form of durability is community ownership, in the shape of revenue share, community trust structures, or potential co-ownership of infrastructure or assets like battery storage or renewable energy generation. Microsoft's Community-First AI Infrastructure framework is a useful industry signal, but voluntary frameworks do not substitute for instruments the community can enforce.
Where Developers and Capital Partners Go From Here
The cancellation surge is a structural feature of the current data center siting environment. The patterns are legible enough to act on now. Three moves matter most.
1. Engage early, and well before site selection. Genuine engagement means naming the end user on the application, opening pre-application discussions to the public, and treating disclosure as a siting strategy rather than a legal afterthought.
2. Calibrate benefits to the host community, not to a template. Pre-siting analysis of demographic, environmental, and infrastructure indicators tells a developer whether drinking-water investment, energy burden protection, noise mitigation, or air-quality remediation will land as a real benefit for that community. Likewise, community involvement and voice in benefits design are equally important to shape calibrated and meaningful benefits. The same investment delivers very different value across communities.
3. Build verification into the instrument from day one. SMART milestones, independent monitoring, secured financial obligations, and modification rights the community can exercise belong in the agreement at signing, not bolted on later. Capital partners should expect to see these structures in their own diligence. A commitment without measurement is a promise, and communities are no longer accepting promises.
The Next Generation of Community Benefits Is Being Written Now
The next generation of community benefits is being designed right now, across municipal halls, civic coalitions, capital diligence checklists, and developer playbooks. The frameworks that will work are the ones that pass three tests: meaningful in scope and community voice, measurable in delivery and outcomes, and durable across political and generational divides.
Relae's Responsible Development team works with developers, capital partners, and host communities to build these frameworks from the ground up. Pre-siting community intelligence, burden-calibrated benefits design, and the verification scaffolding that converts commitments into outcomes.
The shift from reactive to proactive community engagement puts the focus on whether developers are willing to advance the capital to develop meaningful, measurable, and durable community benefits.
[cta]
Frequently Asked Questions
Why do data centers need community benefits agreements?
Communities opposing data center projects cite concerns ranging from environmental and rate impacts to a lack of transparency, and often don’t see how the project benefits them directly. Across 46 cancelled or stalled US data center projects Relae analyzed, representing more than US$170 billion in blocked investment, late-stage benefits offered under pressure didn’t change outcomes. A community benefits agreement lets developers deliver benefits proactively and make them verifiable, rather than reactively once opposition has organized.
What’s the difference between a legacy community benefits agreement and a next-generation one?
Legacy CBAs were often negotiated with specific legal and formal entities like County Commissions or City Councils and had narrow focuses on workforce or economic development. Oftentimes, these tools were offered as concessions through negotiation, rather than commitments, which is why communities are rejecting them. A next-generation community benefits agreement is meaningful, measurable, and durable from the start, with benefits calibrated to the host community rather than bolted on later.
Who should be involved in negotiating a community benefits agreement for a data center?
Benefits should be developed with local community leaders and community-based organizations, with the most affected communities at the table on equal footing with adjacent jurisdictions. Developers, capital partners, and host communities all have a role in building the SMART milestones and independent monitoring that turn those commitments into outcomes.
Low-Carbon Fuel Certification: How Market Rules Shape the Value of a Fuel
Key Takeaways
- The revenue stack for a given fuel is set by the rules that govern the market for low-carbon fuels: regulations, certification schemes, certificate registries, and corporate accounting frameworks.
- Regulators and buyers reward characteristics beyond regulatory eligibility and carbon intensity, such as reportability, broader sustainability, and advanced technology.
- Relae helps producers with commercial strategy relating to feedstock, production pathway, and certification, which impact access to markets.
The Route to Market Is a Strategic Choice
Low-carbon fuels (LCFs), such as sustainable aviation fuel (SAF) and renewable natural gas (RNG), will cost more to make than their fossil equivalents for the foreseeable future. Projects narrow that gap through some combination of regulatory-market value, sales of environmental attribute certificates (EACs) to voluntary buyers, and financial incentives such as the 45Z Clean Fuel Production Credit.
Regulatory programs are pulling investment into new facilities and novel production routes, and voluntary reporting frameworks are moving toward allowing companies to count fuel certificates in their emissions inventories. What the revenue stack for a given fuel looks like is set by the rules that govern the market for LCFs: regulations, certification schemes, certificate registries, and corporate accounting frameworks.
In voluntary markets, the certification scheme, certificate registry, and reporting framework determine the official carbon intensity (CI) of the fuel, the number of certificates generated, and how buyers can use them to make claims.
In regulatory programs across Europe and North America, the rules determine how the fuel is classified, and whether its feedstock receives premium value, is capped, or is excluded altogether. Producers who understand how their market entry decisions impact value will be better positioned now and going forward.
What Is Carbon Intensity?
A fuel’s CI measures the life cycle greenhouse gas emissions per unit of fuel, usually expressed in grams of carbon dioxide-equivalent per megajoule (gCO2e/MJ). It covers feedstock production, conversion, transport, and use. Each program defines its own methodology for calculating it, which is why the same batch of fuel can carry a different CI depending on which program’s rules apply.
EACs Carry a Fuel’s Value to Market
An LCF EAC records characteristics of a batch of fuel separately from the fuel itself, such as whether it qualifies for a given program, the CI, or its feedstock. The certificate can travel with the fuel (bundled) or be sold on its own (unbundled):
Bundled EACs
In most regulatory markets, an obligated party purchases the fuel and its certificate together. These buyers are mainly fuel suppliers, as under the California Low Carbon Fuel Standard (LCFS), and airlines, as under the EU Emissions Trading System and the Carbon Offsetting and Reduction Scheme for International Aviation (CORSIA). They need both the physical fuel and the EAC that proves the fuel is eligible.
Unbundled EACs (Book-and-Claim)
Often in the voluntary market, the fuel is consumed wherever it can be delivered. The EAC is sold separately to whoever wants to claim its attributes, a system called book-and-claim. This matters because most companies have no control over the fuel burned in their supply chains: a company that ships freight cannot choose the fuel its carriers use, but it can buy EACs with a certified CI and claim the associated emissions reduction.
In both markets, the characteristics the EAC carries determine the regulatory and voluntary value in a fuel’s revenue stack.
Three Layers of Rules Determine the Value of an EAC
An LCF producer chooses the feedstock, production pathway, and markets to sell into. How those choices translate to the value of a fuel’s EAC is determined by three layers of rules that govern the LCF market (Table 1).
Table 1. The three layers of rules that set an LCF EAC’s value. Examples are illustrative and not exhaustive. ISCC = International Sustainability and Carbon Certification; RSB = Roundtable on Sustainable Biomaterials; SAFc = sustainable aviation fuel certificate; RED III = Renewable Energy Directive; GHG = greenhouse gas; SABA = Sustainable Aviation Buyers Alliance. Source: Relae.
Where the Rules Disagree: Three Feedstock and Pathway Examples
The result is that the same batch of fuel can carry a different CI, or a different classification, depending on which rules it is subject to. Three examples below demonstrate how production pathway decisions can impact a fuel’s value:
- Manure-based RNG ⇨ avoided emissions. The three layers treat avoided emissions differently. At the regulatory program and voluntary standard layer, ISCC PLUS follows the EU Renewable Energy Directive (RED III) in crediting methane emissions avoided through improved manure management, but CORSIA does not. At the registry and accounting layer, the Greenhouse Gas (GHG) Protocol’s draft Action and Market Instruments (AMI) Standard and the AIM Platform have proposed separating avoided emissions from a fuel’s direct life cycle emissions and reporting the two on different statements, and whether negative CI values from avoided emissions are accepted at all depends on the registry where the EACs are listed.
- Crop-based feedstocks ⇨ indirect land use change (iLUC). Regulators don’t agree on how to incorporate iLUC, either. Under the LCFS, modeled iLUC emissions for all crop-based fuels are positive. Under CORSIA, they can be positive or negative. Under RED III, iLUC is excluded from the CI, though separate rules restrict feedstocks deemed high-risk for iLUC. And because modeling and assumptions keep evolving, iLUC values are also subject to change over time.
- Synthetic fuel ⇨ e-SAF mandates. Regulatory programs also differ on what counts as a given category of fuel. ReFuelEU Aviation and the UK SAF Mandate both reserve a share of their mandates for e-SAF, but define it differently. The EU requires the fuel to qualify as a renewable fuel of non-biological origin (RFNBO). The UK sets its own power-to-liquid criteria, including which electricity sources it accepts. The same e-SAF can therefore count toward one sub-mandate and not the other.
Beyond Eligibility: EAC Characteristics the Market Rewards
In regulatory markets, an EAC’s value depends first on whether the fuel is eligible and how it is classified. In voluntary markets, value depends on the fuel’s CI and the number of certificates issued. Both regulators and voluntary buyers also reward characteristics beyond that baseline, and those characteristics can impact a fuel’s revenue stack:
- Voluntary reportability. The value of an EAC depends on how a buyer can report it, today and in the future. The GHG Protocol is still finalizing its rules for fuel certificates and what a buyer can claim. Certificates that fit cleanly within those rules may command a premium.
- Breadth of sustainability criteria. Some buyers screen EACs against criteria beyond emissions savings. The Sustainable Aviation Buyers Alliance (SABA) explicitly prefers advanced feedstocks and certification schemes with stronger social and environmental safeguards. Regulations set a minimum bar, but voluntary markets have no single standard for a high-quality EAC. The Relae Criteria for High-Quality Low Carbon Fuels consolidate these characteristics into one framework, and can show producers how their fuel and certification choices measure up against it.
- Advanced feedstocks and technologies. Fuel from novel pathways typically costs more than fuel from established ones, and some buyers are willing to pay that premium: early buyers want to support technologies that need offtake to reach commercial scale, and others want to diversify supply ahead of expected constraints on hydroprocessed esters and fatty acids (HEFA) SAF.¹ Regulators reward the same pathways directly through e-SAF sub-mandates and financial incentives, such as the UK Revenue Certainty Mechanism.
Where Should Producers Start?
How each program treats a feedstock, how each methodology calculates CI, and what each set of buyers will pay for are inputs to the feedstock, production pathway, and offtake decisions themselves. Once those decisions are made and contracts are signed, the route to market is largely fixed. Producers should weigh the routes open to them against three questions before committing:
- How will my feedstock, production pathway, and certification affect access to markets?
- How do I position my product within overlapping voluntary and regulatory markets?
- Who are my buyers and what do they require or prefer?
A sound strategy must consider the complex interactions between voluntary and regulatory markets, certification schemes and registries, and buyer preferences.
The landscape continues to evolve, with new national certification programs and regulations for LCFs emerging across the globe and accounting frameworks shifting. The policy experts, scientists, engineers, and economists at Relae help producers understand how each certification route affects the value of their fuel in the markets they want to enter, choose feedstocks and pathways with that in mind, and make sure the claims behind their EACs are high-quality and hold up to buyer and registry scrutiny as the rules evolve.
Frequently Asked Questions
What is the difference between a bundled and an unbundled EAC?
A bundled EAC is sold with the physical fuel, usually to an obligated party under a regulatory program such as the LCFS or ReFuelEU Aviation. An unbundled EAC is sold separately from the fuel through book-and-claim, so a buyer can claim its attributes without taking delivery of or consuming the fuel.
What is the difference between a regulation, a certification scheme, a registry, and a corporate accounting framework?
A regulation or voluntary standard sets the CI methodology and decides whether certain feedstocks are rewarded, capped, or excluded. A certification scheme verifies that a batch of fuel meets that methodology. A registry issues and tracks the certificates and can apply additional rules on CI, while corporate accounting frameworks determine what a voluntary buyer can claim.
Why can the same fuel have more than one carbon intensity?
Each regulatory program and voluntary standard sets its own CI methodology, and registries can add rules of their own. Manure-based RNG is one example: RED III and ISCC PLUS credit avoided methane emissions, CORSIA does not, and some registries cap CI at zero. The same batch can therefore carry different CIs depending on where it is certified and what market it is sold into.
How does carbon intensity affect LCFS credits?
Under the LCFS, the number of credits a fuel generates depends on how far its certified CI falls below the program’s fossil fuel benchmark for that year. Credit price is set by the market, so a lower CI increases the credits a producer has to sell, and the program’s rules decide the CI of the fuel.
Battery Storage Economics: Do the Numbers Still Pencil in Today’s Market?
Key Takeaways
- Batteries have competed away the revenue that financed their first wave. In Texas, ancillary prices have fallen about 90% since 2023, and price spikes driving arbitrage revenue are becoming ever less frequent.
- The business has moved from trading energy to selling capacity. In Texas, tolls work as private capacity contracts, and resource adequacy payments make up roughly 70% of battery revenue in California. Project economics increasingly pencil on a fixed $/kW-month basis rather than price spikes.
- Long-term contracts help shift the risk, but they don’t fully close the gap. Under a 15-year toll, a new battery needs about 22% less revenue, but that is still nearly three times what Texas batteries earned in the market in 2025.
- Buildout now depends on who will pay for capacity. Merchant revenue alone no longer covers a new battery, so growth hinges on how many buyers will sign capacity contracts worth nearly three times what Texas batteries earn in the market.
Battery Revenues Are Falling While Deployments Keep Rising
US developers are expected to install about 24 GW of utility-scale battery storage energy systems (BESS) in 2026, about 60% more than the record 15 GW added in 2025, according to the EIA. Yet in Texas, where batteries earn most of their money in the market, a typical battery earned roughly 85% less in 2025 than in 2023.
Is this unjustified overbuilding by an industry that has grown too fast? Some battery executives argue this is not overbuilding, because merchant revenue earned in wholesale markets is no longer the business. In their view, falling merchant revenue matters less because longer-term offtake contracts, such as 15-year tolls with utilities and large power buyers, make lower revenue financeable. As a result, today’s installations bank on batteries being paid as capacity assets rather than as pure energy arbitrageurs.
We tested those claims against market data from Texas (ERCOT) and California (CAISO) between 2022 and 2026. Our core finding is that project economics in both markets are increasingly reliant on fixed $/kW-month earnings rather than arbitrage revenue.
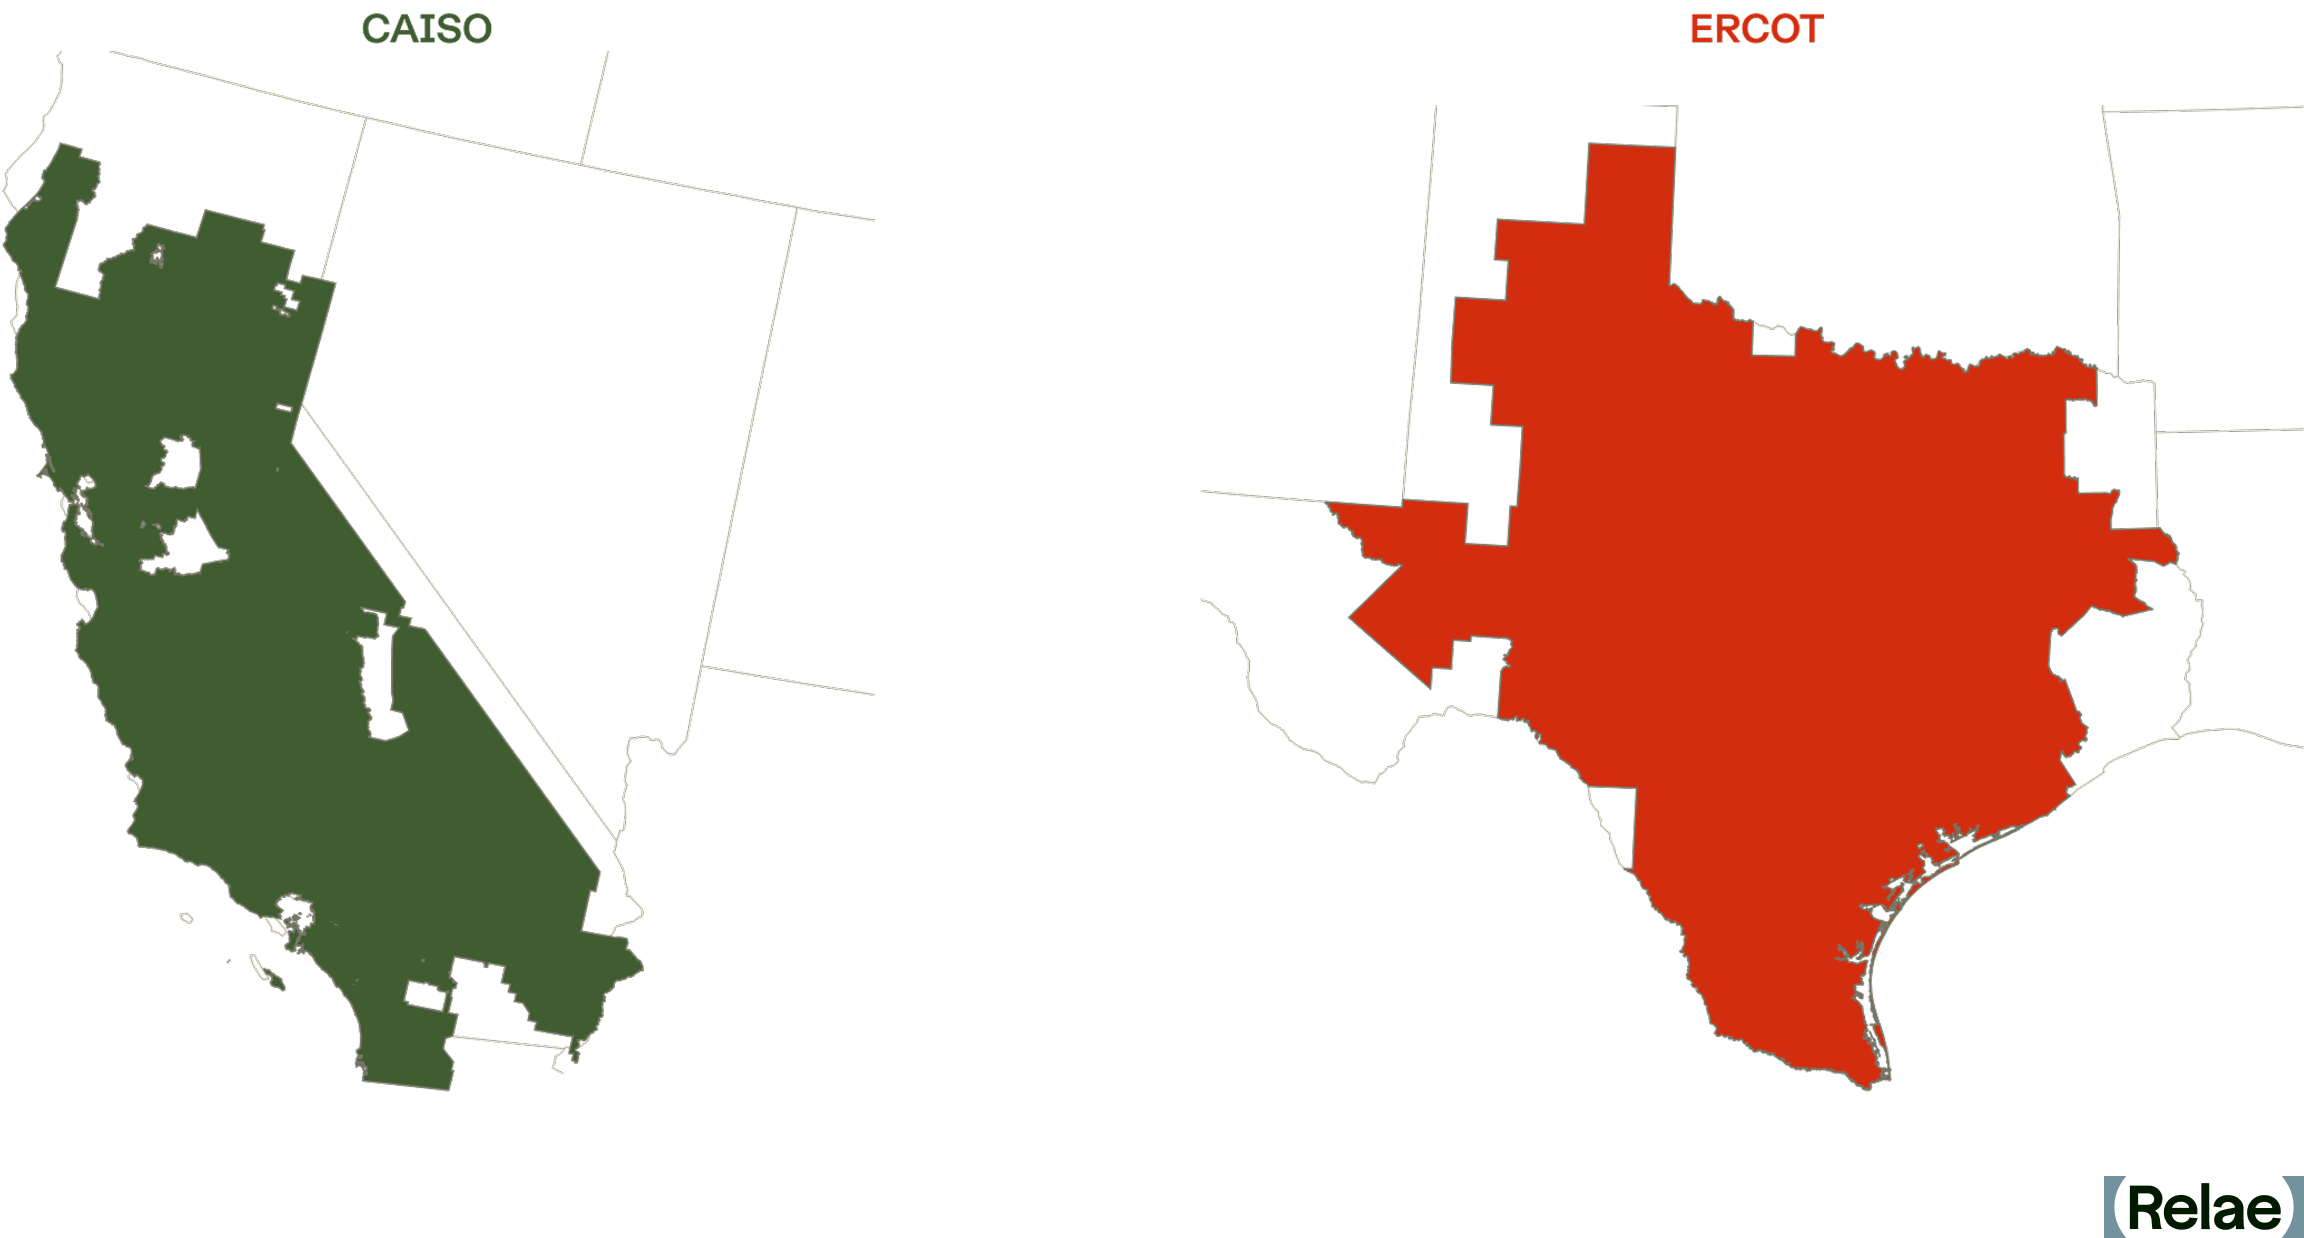
How Does a Grid Battery Make Money?
A battery has three ways to earn:
- Energy arbitrage (merchant: paid per MWh traded, hour-by-hour): charging when power is cheap and discharging when it is expensive. Its value depends on the daily spread between the highest- and lowest- priced hours.
- Ancillary services (merchant: paid per MW held in reserve, bought a day ahead): payments for standing ready to keep the grid stable, such as frequency regulation and reserves, whether or not the battery is called on to deliver energy.
- Capacity contracts (contracted: fixed $/kW-month for many years): a utility or large buyer pays a fixed monthly fee, often called a toll, for the right to use the battery, and takes on the market risk itself. It is the most stable of the three.
Texas batteries earned almost entirely from the first two. California batteries have earned from all three, and as market revenue has fallen, resource adequacy (RA) contracts–the mechanism through which load-serving entities meet the state’s capacity requirements–have become their main source of income.
That additional revenue stream is crucial in CAISO, making up roughly 70% of battery revenue by 2025, as net market revenue declined from $103/kW-year in 2022 to under $40/kW-year in 2025. Outcomes differ, too: California still curtails large amounts of midday solar despite its growing battery fleet, while ERCOT’s batteries have flattened price peaks.
How Texas Batteries Lost Their Merchant Revenue
Ancillary services filled up first. In 2022-23, ancillary services supplied more than 80% of Texas batteries’ revenue. But these markets are small and fixed in size. ERCOT buys about 3 GW of the fast reserves batteries excel at, and 6–8 GW of ancillary services in total.
The battery fleet passed the first mark in mid-2023 and the second in spring 2024; it is now about 19 GW of registered capacity. Average ancillary services prices fell 85-95% between 2023 and 2025, and ERCOT's day-ahead ancillary services spending fell from about $1.5 billion to $174 million. California’s ancillary markets saturated even earlier: batteries already won about 70% of its regulation-up procurement in 2022, and about 90% since 2024. Its ancillary services spending, much smaller than ERCOT’s to begin with, fell by about 60%, from $237 million in 2022 to $95 million in 2025.
Price spikes disappeared, too. ERCOT's average daily spread between its four highest- and four lowest-priced hours fell from $163/MWh in 2023 to $48/MWh in 2025, even as natural gas prices rose. Yet the typical day, adjusted for gas prices, looks much as it did in 2022. What vanished is scarcity: hours when real-time prices topped $1,000/MWh fell from about 60 in 2023 to 2 in 2025.
Batteries discharge into exactly those hours, and there are now enough of them to flatten the peaks. Controlling for gas prices, renewables, and demand, each additional gigawatt of batteries is associated with a 9% narrower daily spread.
Merchant revenue collapsed. Texas batteries earned about $193 per kW-year in 2023 and only about $29 in 2025, according to Modo Energy’s fleet index. California batteries’ market revenue fell from about $80 to under $40 per kW-year, before resource adequacy payments. Merchant revenue alone is no longer enough to finance a new battery in either market.
Costs fell too, but not by as much: NLR’s benchmark installed cost for a four-hour system fell about a third from its 2022 peak to 2024, from roughly $517 to $334 per kWh in 2024 dollars. Costs then turned up again: Lazard’s levelized cost of storage rose in 2026, to near the top of its range since 2020, as tariffs cut access to cheaper Chinese cells and new foreign-entity-of-concern (FEOC) rules pushed buyers toward other suppliers.
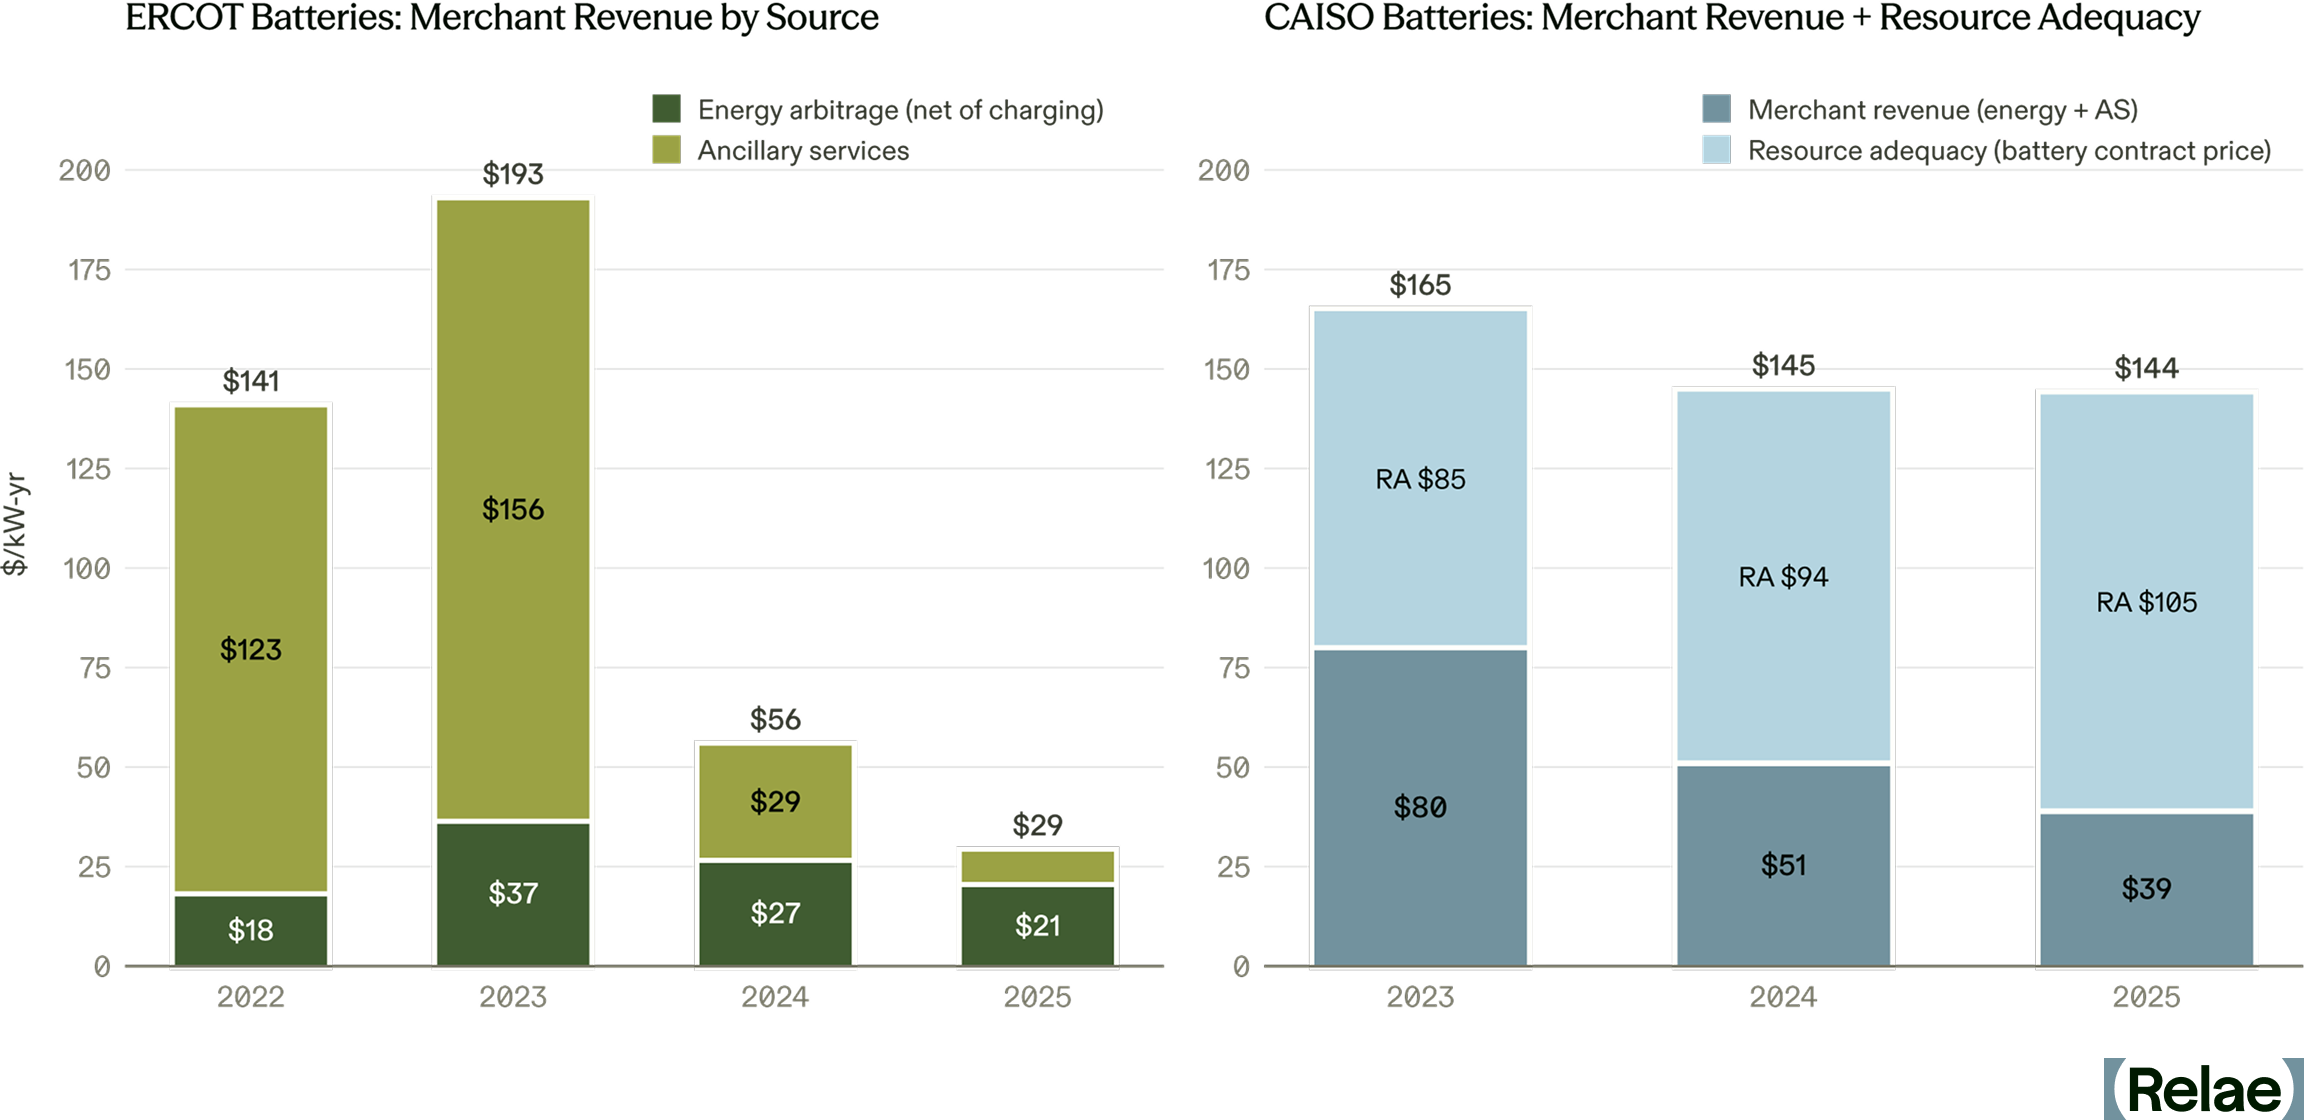
The Battery Business Has Moved From Energy to Capacity
As merchant revenue declines, storage developers are increasingly turning to capacity contracts to support revenue requirements. This has an important advantage: contracted cash flow can carry more debt at a lower cost. Under illustrative financing assumptions, moving a battery coming online in 2028 from merchant to a 15-year toll lowers its cost of capital from about 12.6% to 7.2%.
Using NLR’s projected installed capital costs for 2028, that cuts the annual revenue a two-hour system needs to break even by about 22%, from $105 to $82 per kW-year ($64-101 across NLR’s low- and high- cost cases). However, that is still nearly three times what Texas batteries earned in the market in 2025. Given this gap, new BESS installations might appear to be uneconomic.
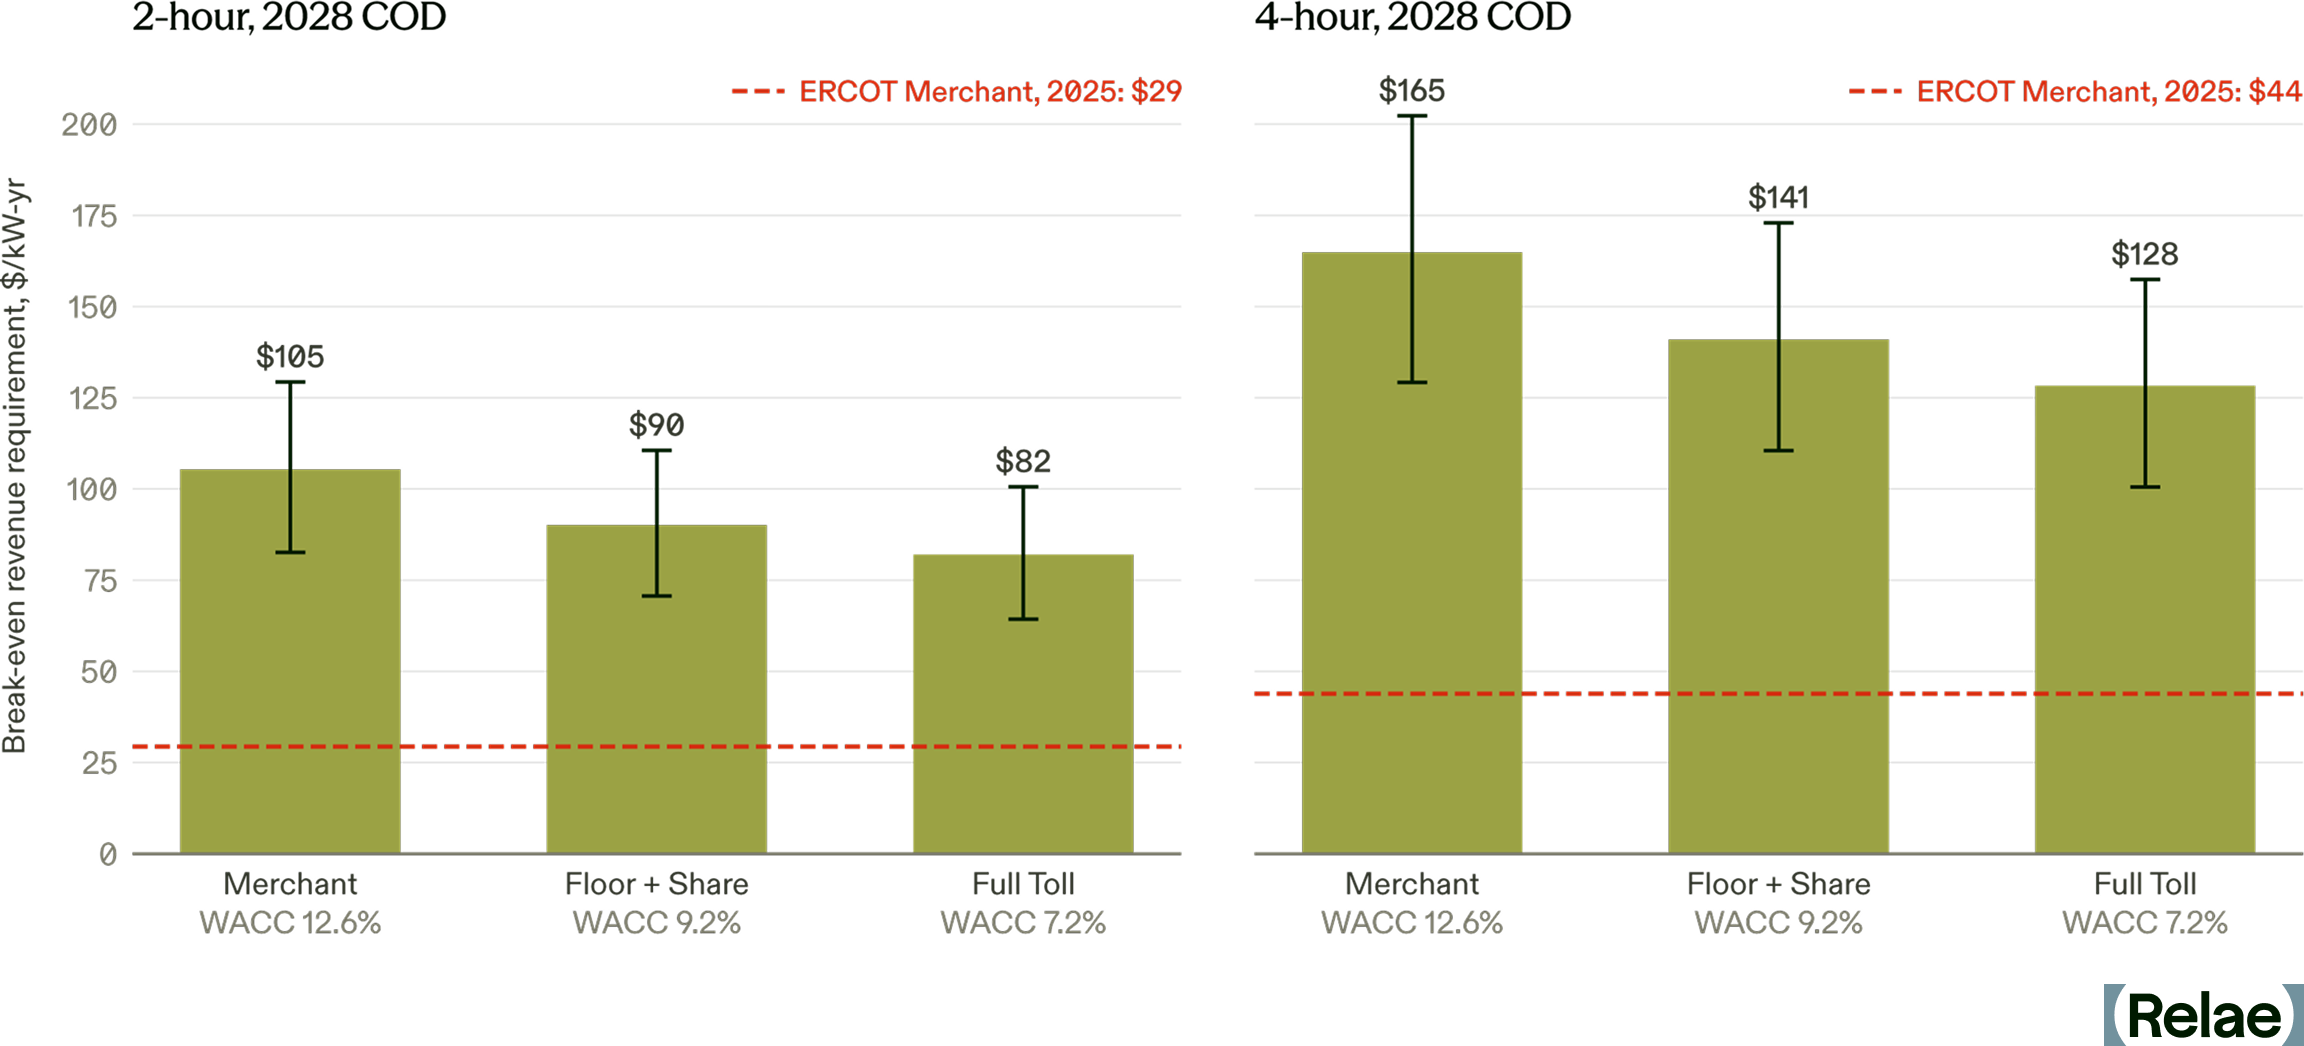
Why Are Developers Still Building BESS?
However, new BESS installations continue to be built. This is partly because many battery storage projects coming online now were financed on 2022-23 revenue (the average project can take over four years from entering the interconnection queue to operation), and partly because new contracts, such as tolls, are priced on capacity, not energy: the supplier is obligated to keep certain amounts of capacity available over a given time period, independent of energy delivery.
In Texas (which has no capacity market), such tolls are, in effect, private capacity contracts. In California, resource adequacy already plays that role: batteries’ RA contracts averaged about $9 per kW-month in early 2025.
An owner needs roughly $7 per kW-month for a two-hour battery (about $11 for four hours) to break even, in line with the roughly $7 per kW-month cap on a 20-year battery storage agreement Austin Energy approved in May 2026. By contrast, the energy and ancillary revenue an offtaker could capture by dispatching it is about $2.50–3.50 per kW-month. The difference is what buyers pay for firm capacity: insurance against scarcity events like Winter Storm Uri, capacity to meet their own load obligations, or a hedge against scarcity returning as demand grows.
The Next Battery Wave Depends on Who Pays for Reliability
Batteries have done what they were built to do: absorb volatility and steady the grid. In doing so, they competed away the revenue that financed the first wave. At today’s prices, merchant revenue no longer covers a new battery. The build continues on projects financed in 2022–23 and on capacity contracts worth nearly three times what Texas batteries earn in the market. Whether the buildout continues depends on how many buyers will pay that premium.
Deployment continues to grow in both markets. ERCOT registered about 4.2 GW of new batteries in January to July 2026, against 2.8 GW a year earlier. But the pace is slowing: Texas’s fleet grew about 50% in 2025 after nearly doubling in 2024, and interconnection queues are thinning: ERCOT battery applications fell by half in the second half of 2025.
Wholesale markets financed the first boom. The next wave depends on buyers who value reliability, including utilities, retailers, and large loads such as data centers, and on how cheaply that risk can be priced and capitalized. Data centers in particular put a high value on firm power: research inferring their willingness to pay from cloud computing prices puts it at up to $13,600 per MWh for frontier AI chips on guaranteed service, far above ERCOT’s $5,000 per MWh price cap.
For developers and investors, the question is no longer how much the market will pay, but who will sign, and for how long. For more on how interconnection queues shape how many storage projects get built and how queue wait times vary by technology, see Relae’s interconnection research.
Relae’s Power & Energy advisory team helps developers, investors, and large energy buyers understand and price the value of storage. This includes behind-the-meter modeling, resource portfolio optimization, and interconnection queue analysis.
Frequently Asked Questions
Why are battery storage revenues falling if deployment keeps growing?
Batteries have become victims of their own success. They earned most of their early revenue from two sources: ancillary services and high wholesale market prices. Texas now has more batteries than ancillary services the grid needs, so those prices have collapsed. And because batteries discharge during the most expensive hours, there are now enough of them to flatten the price spikes that used to pay the most.
What is a battery tolling agreement?
A toll is a long-term contract in which a utility or large buyer pays a battery owner a fixed monthly fee for the right to direct how the battery is used. The buyer keeps whatever the battery earns in the market and takes on the risk if that falls short. The owner gets a steady income it can borrow against.
Who is signing these contracts?
Mostly utilities, retailers and power traders, who need capacity to serve their customers or want protection against price spikes. In California, utilities sign capacity contracts with batteries to meet the state’s resource adequacy requirements. Large loads such as data centers place a high value on reliable power, but few have signed contracts with grid batteries so far; most of their battery deals are for on-site power.
Will battery storage buildout slow down?
Not yet. Texas is still adding more batteries each year, largely projects that were planned and financed when revenues were higher. But the pipeline behind them is thinning: new battery applications in ERCOT’s interconnection queue halved in the second half of 2025. Whether buildout holds up depends on how many buyers will pay for capacity at a premium to what the market pays today.