The New Geothermal Energy: How EGS Unlocks Clean, Firm Power at Scale
Key Takeaways
- Enhanced geothermal systems (EGS) overcome traditional geothermal energy limitations by engineering subsurface conditions rather than searching for them, enabling widespread deployment of clean firm renewable power.
- Induced seismicity from high-pressure injection has caused major EGS project cancellations, but advanced approaches like Sage Geosystems’ gravity-assisted fracturing mitigate this risk by avoiding overpressures and directing fractures downward away from fault zones.
- Sage’s $97 million Series B financing, co-led by Ormat Technologies and Carbon Direct Capital, will fund the first commercial EGS facility at an existing Ormat plant—accelerating the transition from innovation to grid-scale deployment.
- For hyperscalers racing to power AI infrastructure, EGS offers a credible path to firm, 24/7 low-carbon power at scale.
Geothermal Energy: The Heat (And Pressure) Is On
For decades, geothermal energy has occupied a compelling yet narrow place in the clean energy landscape. It offers what the grid increasingly needs— firm, renewable, low-carbon power—yet has remained constrained by limited siting flexibility, high upfront resource risk, and persistent concerns around induced seismicity.
Enhanced geothermal systems (EGS) change that equation. Instead of searching for ideal subsurface conditions, EGS engineers them directly. In doing so, EGS rewrites the rules of where geothermal energy can be deployed and how far it can scale, with the potential to transform this historically niche resource into a widely deployable form of clean firm power.
One such solution, Sage Geosystems, uses a pressure-managed EGS approach to extract geothermal energy from engineered subsurface reservoirs, while explicitly addressing the seismicity risks that have constrained earlier projects.
How EGS Scales Geothermal Energy
Conventional geothermal power relies on a narrow set of subsurface conditions: sufficiently high temperatures, naturally occurring fluid, and enough permeability to circulate fluid through hot rock. In practice, those conditions coexist in only a few places—nearly all US commercial geothermal power generation is concentrated in California, Nevada, and a handful of sites across Utah and Hawaii.
EGS reduces this constraint by engineering permeability and fluid access rather than relying on their natural presence. While fluid access and permeability are harder to find, heat is not: the Earth’s natural geothermal gradient ensures that hot rock exists almost everywhere at sufficient depth.
By reducing the number of variables that must be discovered rather than designed, EGS expands siting flexibility and lowers the resource risk that has historically constrained geothermal development. The Department of Energy (DOE) estimates this approach could unlock more than 5,500 GW annually of US resource potential, which, when converted to electric power, is roughly comparable to the total installed power capacity of the US today.
One remaining challenge has been induced seismicity. When you inject pressurized water into rock and create fractures, you are adding lubrication to geological systems that have been static for millions of years. If those fractures propagate into existing fault zones, the faults can slip, producing earthquakes. Projects in Basel, Switzerland (2006) and Pohang, South Korea (2017) triggered magnitude 3.4 and 5.4 events, respectively, both leading to project cancellations and regulatory backlash that set the industry back years.
Sage's approach to EGS is designed to address this risk directly. Rather than relying on high-pressure hydraulic stimulation, Sage uses a gravity-assisted fracturing approach that helps avoid the high overpressures that can drive fault slip. Further, its approach biases fracture growth downward and away from shallow, critically stressed fault systems. By understanding causes and conditions, Sage aims to work with the subsurface, not against it.
This is not a minor technical detail. It is the difference between a technology that can scale with community acceptance and one that faces opposition at every site. For a hyperscaler evaluating geothermal offtake agreements, seismicity risk translates directly into permitting risk, timeline risk, and reputational risk.
The Clean Firm Power Gap Driving EGS Adoption
To understand why this matters, start with the problem hyperscalers are trying to solve. Solar and wind have scaled dramatically, but they face a structural limitation: they do not generate power when the sun is not shining or the wind is not blowing. Batteries help bridge short gaps, but current technology cannot economically cover multi-day periods of low renewable output. Nuclear provides firm generation, but faces permitting timelines that extend well past 2030.
This creates what might be called the 'clean firm power gap'—the difference between what hyperscalers need (24/7, low-carbon, scalable to gigawatts) and what current markets can supply. A single large AI training cluster can consume more than 100 MW continuously. Meta, Google, and Microsoft are planning data center campuses that will require gigawatts of capacity. The gap between demand and available clean firm power supply is widening, not narrowing.
Geothermal energy aligns closely with this need. Unlike solar or wind, geothermal power plants run continuously, with capacity factors that routinely exceed 90%. And unlike nuclear, geothermal projects can, in principle, be permitted and built on shorter timelines. The challenge has never been performance, rather availability: with the emergence of EGS, geothermal power is expanding where clean firm power can realistically be built, arriving at a moment when the grid’s need for dependable, low-carbon supply has never been greater.
Sage Raises $97 Million to Deploy Geothermal at Ormat Site
Sage Geosystems announced $97 million in Series B financing co-led by Ormat Technologies, the world's largest geothermal operator, and Carbon Direct Capital, a leading energy investing firm. Ormat will host Sage's first commercial facility at an existing Ormat plant.
The investment signals that EGS has become investable to the industry built to scale it. For Ormat, the logic is clear: conventional geothermal is constrained by resource availability. EGS expands the addressable market, but requires the subsurface capabilities that conventional operators don't typically possess by Sage does.
Why the Partnership Structure Works
EGS proposes that the fastest way to scalable power is to eliminate the resource risks that beset conventional geothermal projects. These risks do not simply disappear: they are transferred into subsurface and remain unproven at scale. Conventional operators locate naturally permeable reservoirs. EGS requires creating permeability in crystalline rock and managing induced seismicity risks that don't exist in hydrothermal systems. Sage is actively addressing the seismicity problem that ended projects in Basel and Pohang. Ormat brings everything else: turbines, plant operations, grid expertise, and six decades of operational knowledge.
Building at an existing Ormat site provides another advantage: established subsurface characterization, proven geological stability, and grid infrastructure already in place. For a first commercial deployment, this de-risks demonstration in ways greenfield sites cannot.
Both companies move faster together because the technical capabilities required to make EGS work don't naturally exist within a single organization.
What Hyperscaler Demand Means for the Power Sector
Meta's 150 MW power purchase agreement with Sage—announced in August 2024, with delivery planned for sites east of the Rocky Mountains—adds another dimension to this story. Hyperscalers have concluded that waiting for clean firm power technologies to mature before signing contracts means those technologies may not be available when needed. So they are becoming anchor customers, providing the revenue certainty that enables projects to secure financing.
For geothermal power specifically, this demand signal is transformative. Contracted offtake from creditworthy counterparties changes project economics fundamentally. It lowers the cost of capital, enables debt financing, and de-risks the investment case for additional capacity. The hyperscaler model has already accelerated deployment in solar, wind, and battery storage. Its application to geothermal power may prove similarly catalytic.
The Final Constraint
EGS is not a silver bullet, but it is beginning to look like a credible answer to a growing-problem: how to deliver clean firm power at scale, in more places, and on timelines that match accelerating demand. Advances in subsurface engineering are reducing the resource and seismicity risks that once confined geothermal to a narrow footprint, while partnerships with incumbent operators are showing how those advances can be integrated into existing energy infrastructure.
At the same time, hyperscalers are reshaping the market by signaling demand early, underwriting first deployments, and pulling technologies forward rather than waiting for them to mature on their own. That combination of technical progress, industrial adoption, and committed buyers is what turns promising concepts into deployable systems.
Whether EGS ultimately fulfills its potential will depend on repeatable and continued performance under real-world conditions. But the recent alignment of science, incumbents, and demand suggests EGS is moving beyond possibility and into a phase where the final constraint is no longer what the Earth can provide, but what the energy system is prepared to build.
Frequently Asked Questions
What is an enhanced geothermal system?
An enhanced geothermal system, or EGS, produces geothermal energy by engineering underground conditions needed to circulate fluid through hot rock. Unlike conventional geothermal projects, which depend on naturally occurring heat, fluids, and permeability occurring together, EGS can create or enhance permeability and fluid circulation, greatly expanding the locations where geothermal power may be developed.
Why is EGS important for data centers and AI infrastructure?
AI and data centers require large amounts of electricity around the clock, creating demand for power sources that are both low-carbon and firmly available. EGS could provide high capacity factor (greater than 90%), 24/7 clean electricity in more locations than conventional geothermal, making it a potentially valuable complement to intermittent renewable resources.
What is induced seismicity, and how are new EGS technologies addressing it?
Induced seismicity refers to earthquakes caused by changes in underground pressures or stresses caused by human activities. Earlier EGS projects demonstrated that high-pressure fluid injection can activate existing faults and in some cases triggered noticeable earthquakes and intense public backlash. New EGS approaches are being designed to better control reservoir pressure, fracture development, and proximity to faults, reducing seismicity risk while maintaining the fluid circulation needed to extract geothermal energy.
Can EGS be deployed anywhere?
EGS substantially expands geothermal’s geographic potential, but it does not make every location equally suitable. Projects still depend on factors including underground temperature, how deep they need to drill to access that temperature, water availability, seismic risk, and whether the rocks are of type suitable to hold and sustain engineered fracture networks.
Power & Energy
Relae provides independent advisory for large corporate buyers, power providers, and infrastructure investors making high-stakes decisions about clean firm power, grid constraints, data center energy optimization, and long-term investment strategy. Our insights help you evaluate solutions that can be deployed reliably, responsibly, and affordably, so you can navigate an evolving energy landscape with confidence.
Ready to Navigate What Comes Next?


Peter Psarras, PhD
Peter Psarras, PhD
,

Dr. Peter Psarras is a chemical engineer and carbon management expert with over 15 years of experience in lifecycle and techno-economic assessment of engineered systems. Prior to joining Relae, he was a Research Professor at the University of Pennsylvania in Chemical Engineering and Energy Policy where he led research on carbon capture, utilization and storage, direct air capture and carbon mineralization. His work operated at the interface of process engineering, energy policy, and real-world deployment constraints across the entire value chain. He previously held postdoctoral appointments at Stanford University and the Colorado School of Mines, where he conducted research on geospatial deployment optimization of carbon management systems. He received his PhD from Cleveland State University, where his research focused on catalyst development for CO₂-based synthetic fuels. His career spans scales from the molecular-level to system-wide deployment, providing a foundation for navigating the complexities of real-world carbon management.
What to Read Next
How to Reduce Grid-Wide Emissions for Carbon Capture and Storage
Key Takeaways
- The opportunity: Clean, firm power is a strategic priority for large electricity buyers. Natural gas-fired generation equipped with carbon capture and storage (CCS) is emerging as a key tool in meeting this demand. The existing gas-fired power fleet in the US should be assessed to identify plants well-positioned for carbon capture retrofits that would benefit grid decarbonization.
- The challenge: The climate benefits of CCS-equipped natural gas plants depend entirely on how often they actually run. Adding carbon capture technology increases the cost to operate the equipment. These higher running costs can make the plant less competitive in auctions where the grid operator picks the cheapest power first. Without mechanisms to keep these plants running continuously, they may be outbid by cheaper, higher-polluting plants, causing grid-wide emissions to stay the same or even increase.
- The solution: Hyperscalers and other large energy buyers are creating a robust market for clean, firm power. By paying a "clean, firm premium" through long-term offtake agreements, these buyers can offset the higher operational costs of CCS, ensuring these plants are continuously utilized. This corporate leadership not only maximizes the grid-wide climate impact of each retrofit but also provides an important hedge against policy volatility, securing the investment case for clean innovation even when the future of subsidies like the 45Q tax credit is uncertain.
We Need Clean, Firm Power Now
The market signals for clean, firm power are clear. Meta’s nuclear energy projects and Microsoft’s Crane Clean Energy Center demonstrate growing interest in reliable, low-carbon electricity to support the rapid expansion of AI. Similar commitments by Google and Meta to advanced geothermal power also illustrate this trend.
One of the near-term options to meet this demand is natural gas with carbon capture and storage (CCS). As explored by Relae (formerly Carbon Direct), retrofitting existing gas facilities offers a path to reliable baseload power with low direct emissions, leveraging existing infrastructure to bypass the years-long delays typical of new grid interconnections.
Recent initiatives from Google and Calpine are already working to prove this concept at scale. This type of corporate leadership is driving the market; over the last decade, voluntary corporate procurement led to more than 40% of new clean energy capacity in the US. Further, recent procurement decisions illustrate that these players are willing to pay a “clean, firm premium” to secure round-the-clock, low-emissions sources of power.
Why Systems-Level Analysis Matters for CCS
While news of corporate procurements often makes headlines, recent analysis finds the number of supply contracts for natural gas power with CCS may outpace the number of secured offtake agreements. Without a power purchase agreement (PPA) to ensure competitive operation, or strong policy support, a generator may need to operate as a “merchant plant” in power markets, competing solely on cost.
A power plant’s ultimate climate impact is determined primarily by how it is positioned in the market, not just its facility-level technology.
How Power Markets Determine Which Plants Run
Understanding the potential of CCS to deliver clean, firm power and grid-wide decarbonization requires looking beyond the technology performance at a single facility. A retrofitted plant does not operate in isolation; its impact depends on how it interacts with the broader power market’s merit order.
The merit order is the ranking system in competitive power markets where the grid operator dispatches the cheapest offers first. Since carbon capture units are energy-intensive, the retrofitted natural gas plant incurs higher operating costs. This cost increase can inadvertently price the lower-emitting plant out of the market. Without mechanisms to ensure continuous utilization, the CCS plant is potentially outbid by cheaper, more carbon-intensive resources. This creates a risk of increased overall grid emissions.
To illustrate this dynamic, we’re sharing the results of our detailed grid modeling analyses of the Electric Reliability Council of Texas (ERCOT), which serves most of Texas, and the Southwest Power Pool (SPP), which covers parts of 14 states across the central US. Our analysis highlights the value of corporate “clean, firm premiums” in achieving maximum climate benefit and mitigating policy risk present in government subsidy support.
This type of systems-level grid modeling is necessary in understanding how facility-level reductions translate into real climate benefits. Support to incentivize continuous operation, such as corporate offtake agreements or the 45Q tax credit, is key to ensuring that retrofitting a gas power plant with CCS reduces overall grid emissions.
Offtake Agreements and Policy Support as Solutions
Power offtake from CCS retrofitted gas plants can meaningfully reduce system-level emissions. By directly matching electricity demand with the supply of power, large energy buyers – the offtakers – ensure the power plant is effectively utilized. This type of arrangement helps ensure any changes to reduce emissions intensity at the facility level translate into broader emissions reductions on the grid.
For these offtakers, the decision to pay a premium for clean power is driven by the goal of additionality – ensuring their procurement has a measurable, additional emissions reduction impact. Beyond physical energy, buyers secure Energy Attribute Certificates (EACs) for CCS, which serve as the verified proof of low-carbon generation required to satisfy corporate zero-emissions targets. As seen in the recent Google and Calpine agreement, these certificates allow buyers to claim the specific climate benefit of the CCS retrofit, justifying a premium over standard wholesale market rates to secure firm, clean delivery.
In the absence of offtake agreements, policy frameworks like the 45Q tax credit (up to $85 per ton of CO2 sequestered) serve a similar function by offsetting production costs.
However, access to this credit is not a guarantee and carries operational hurdles. To unlock the full credit value, facilities must meet stringent prevailing wage and apprenticeship requirements. Furthermore, the credit is limited to a 12-year window once the facility is placed in service, and requires construction to commence by 2033.
Beyond these eligibility requirements, the long-term outlook for 45Q involves inherent uncertainty. Recent regulatory shifts, including potential changes to the Greenhouse Gas Reporting Program (GHGRP), pose risks to the verification mechanisms required to substantiate captured tons.
Corporate offtake agreements offer a crucial private-sector complement to this landscape; they provide a stable revenue model independent of policy cycles, ensuring the investment case remains robust over the full life of the asset.
Understanding the Merit Order in Power Markets
Most US power plants operate in competitive deregulated markets, where grid operators dispatch generators based on their marginal cost of production – the cost of generating one additional unit of electricity. The operator ranks these offers from lowest to highest price, creating the "merit order.”
In these auctions, the cheapest resources (typically renewables and base load) are dispatched first. Progressively more expensive units (gas and peaking plants) are called upon until demand is met. The price of the final, most expensive unit required sets the market-clearing price received by all generators in that period.
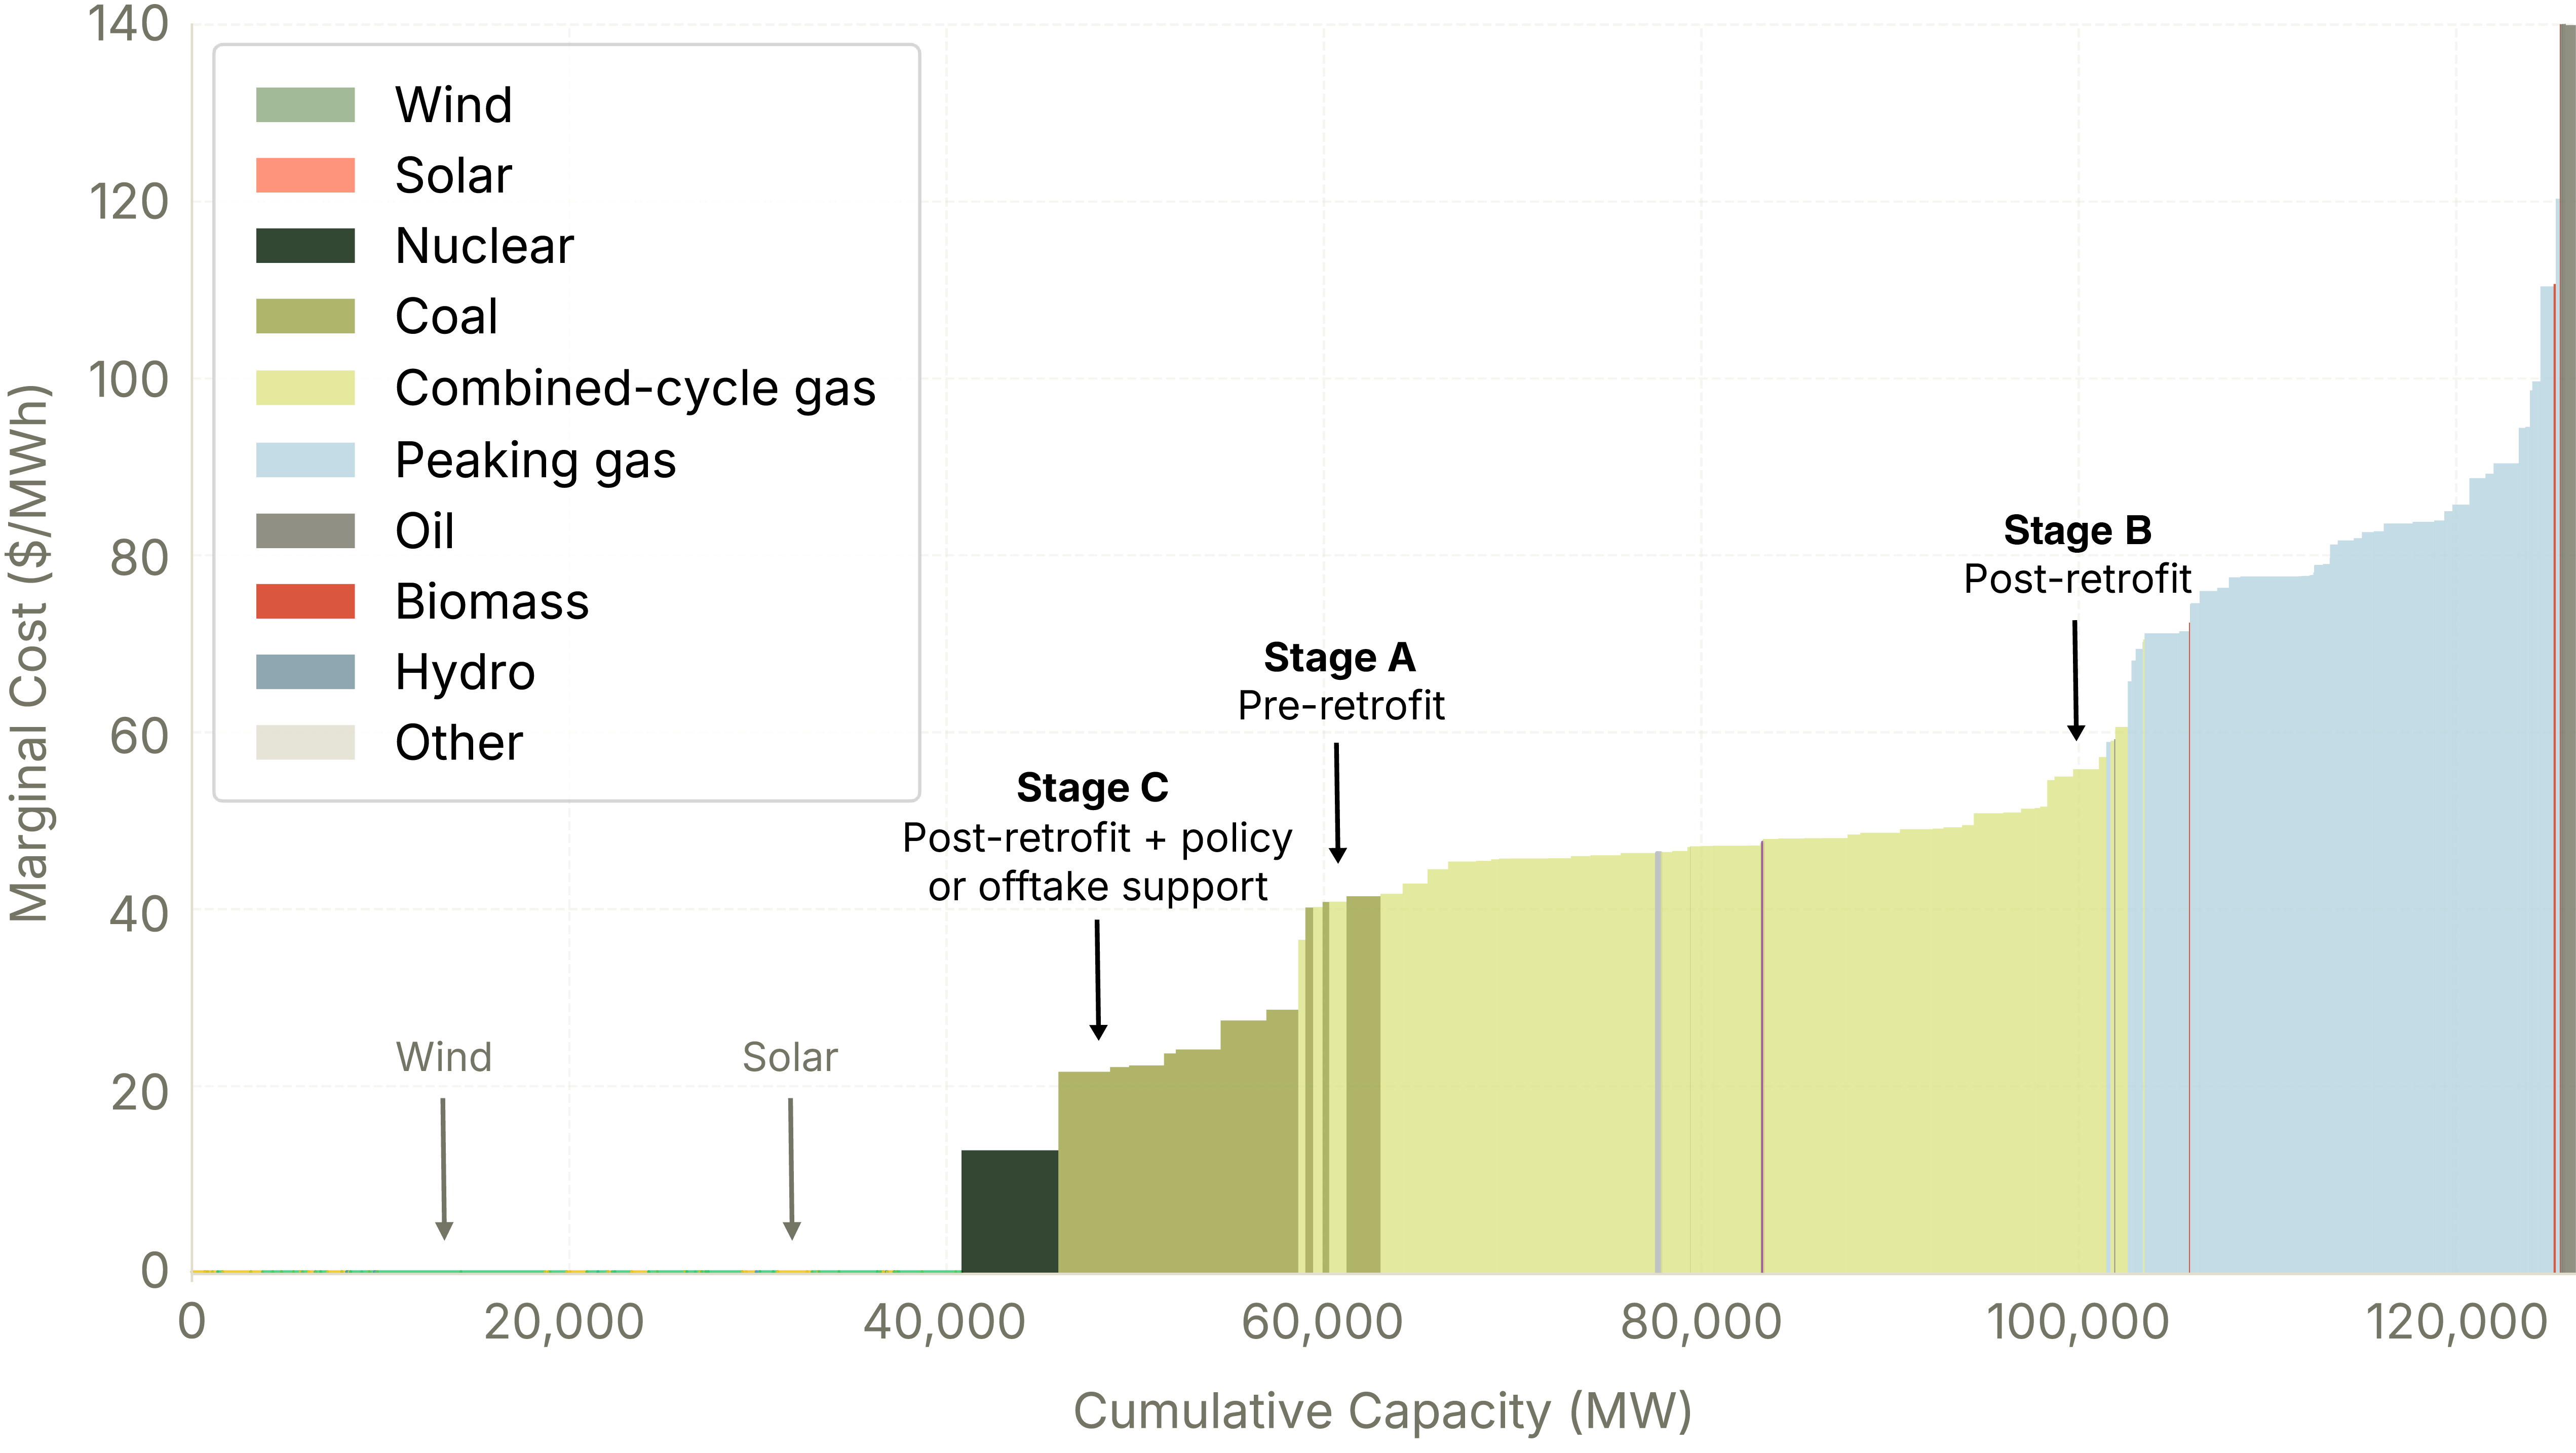
The Figure below shows an example generation merit order in the ERCOT energy market.
Case Study: How Support Structures Influence Dispatch
The merit order figure illustrates a hypothetical scenario for a natural gas generator, showing how its market position changes based on technical and policy variables:
- Pre-Retrofit (Stage A): The plant operates with standard marginal costs, sitting competitively in the middle of the supply stack.
- Post-Retrofit (Stage B): Retrofitting with CCS introduces higher operating costs due to the energy-intensive nature of carbon capture. Without external support, the plant’s marginal cost increases (A to B), making it less competitive. The retrofitted plant may be utilized less while cheaper units are dispatched to meet demand.
- Post-Retrofit + policy or offtake support (Stage C): Financial support, whether through the 45Q tax credit (approx. $33/MWh1) or a corporate offtake agreement, can effectively offset the plant’s higher operational costs (B to C). This effect restores the plant’s competitiveness, ensuring it dispatches consistently.
Testing This With Grid Modeling
At Relae, we apply state-of-the-art grid analysis tools to answer these and more complex analytical questions related to the future energy system. Our custom modeling framework has been used to simulate clean power strategies, assess data center demand response programs, and understand how procurement decisions today impact the future energy system.
While the theoretical impact of a CCS retrofit, a PPA agreement, and the 45Q tax credit on a plant’s dispatch is clear, it’s important to put the theory to the test by modeling their effects on system-wide emissions.
Our Modeling Approach
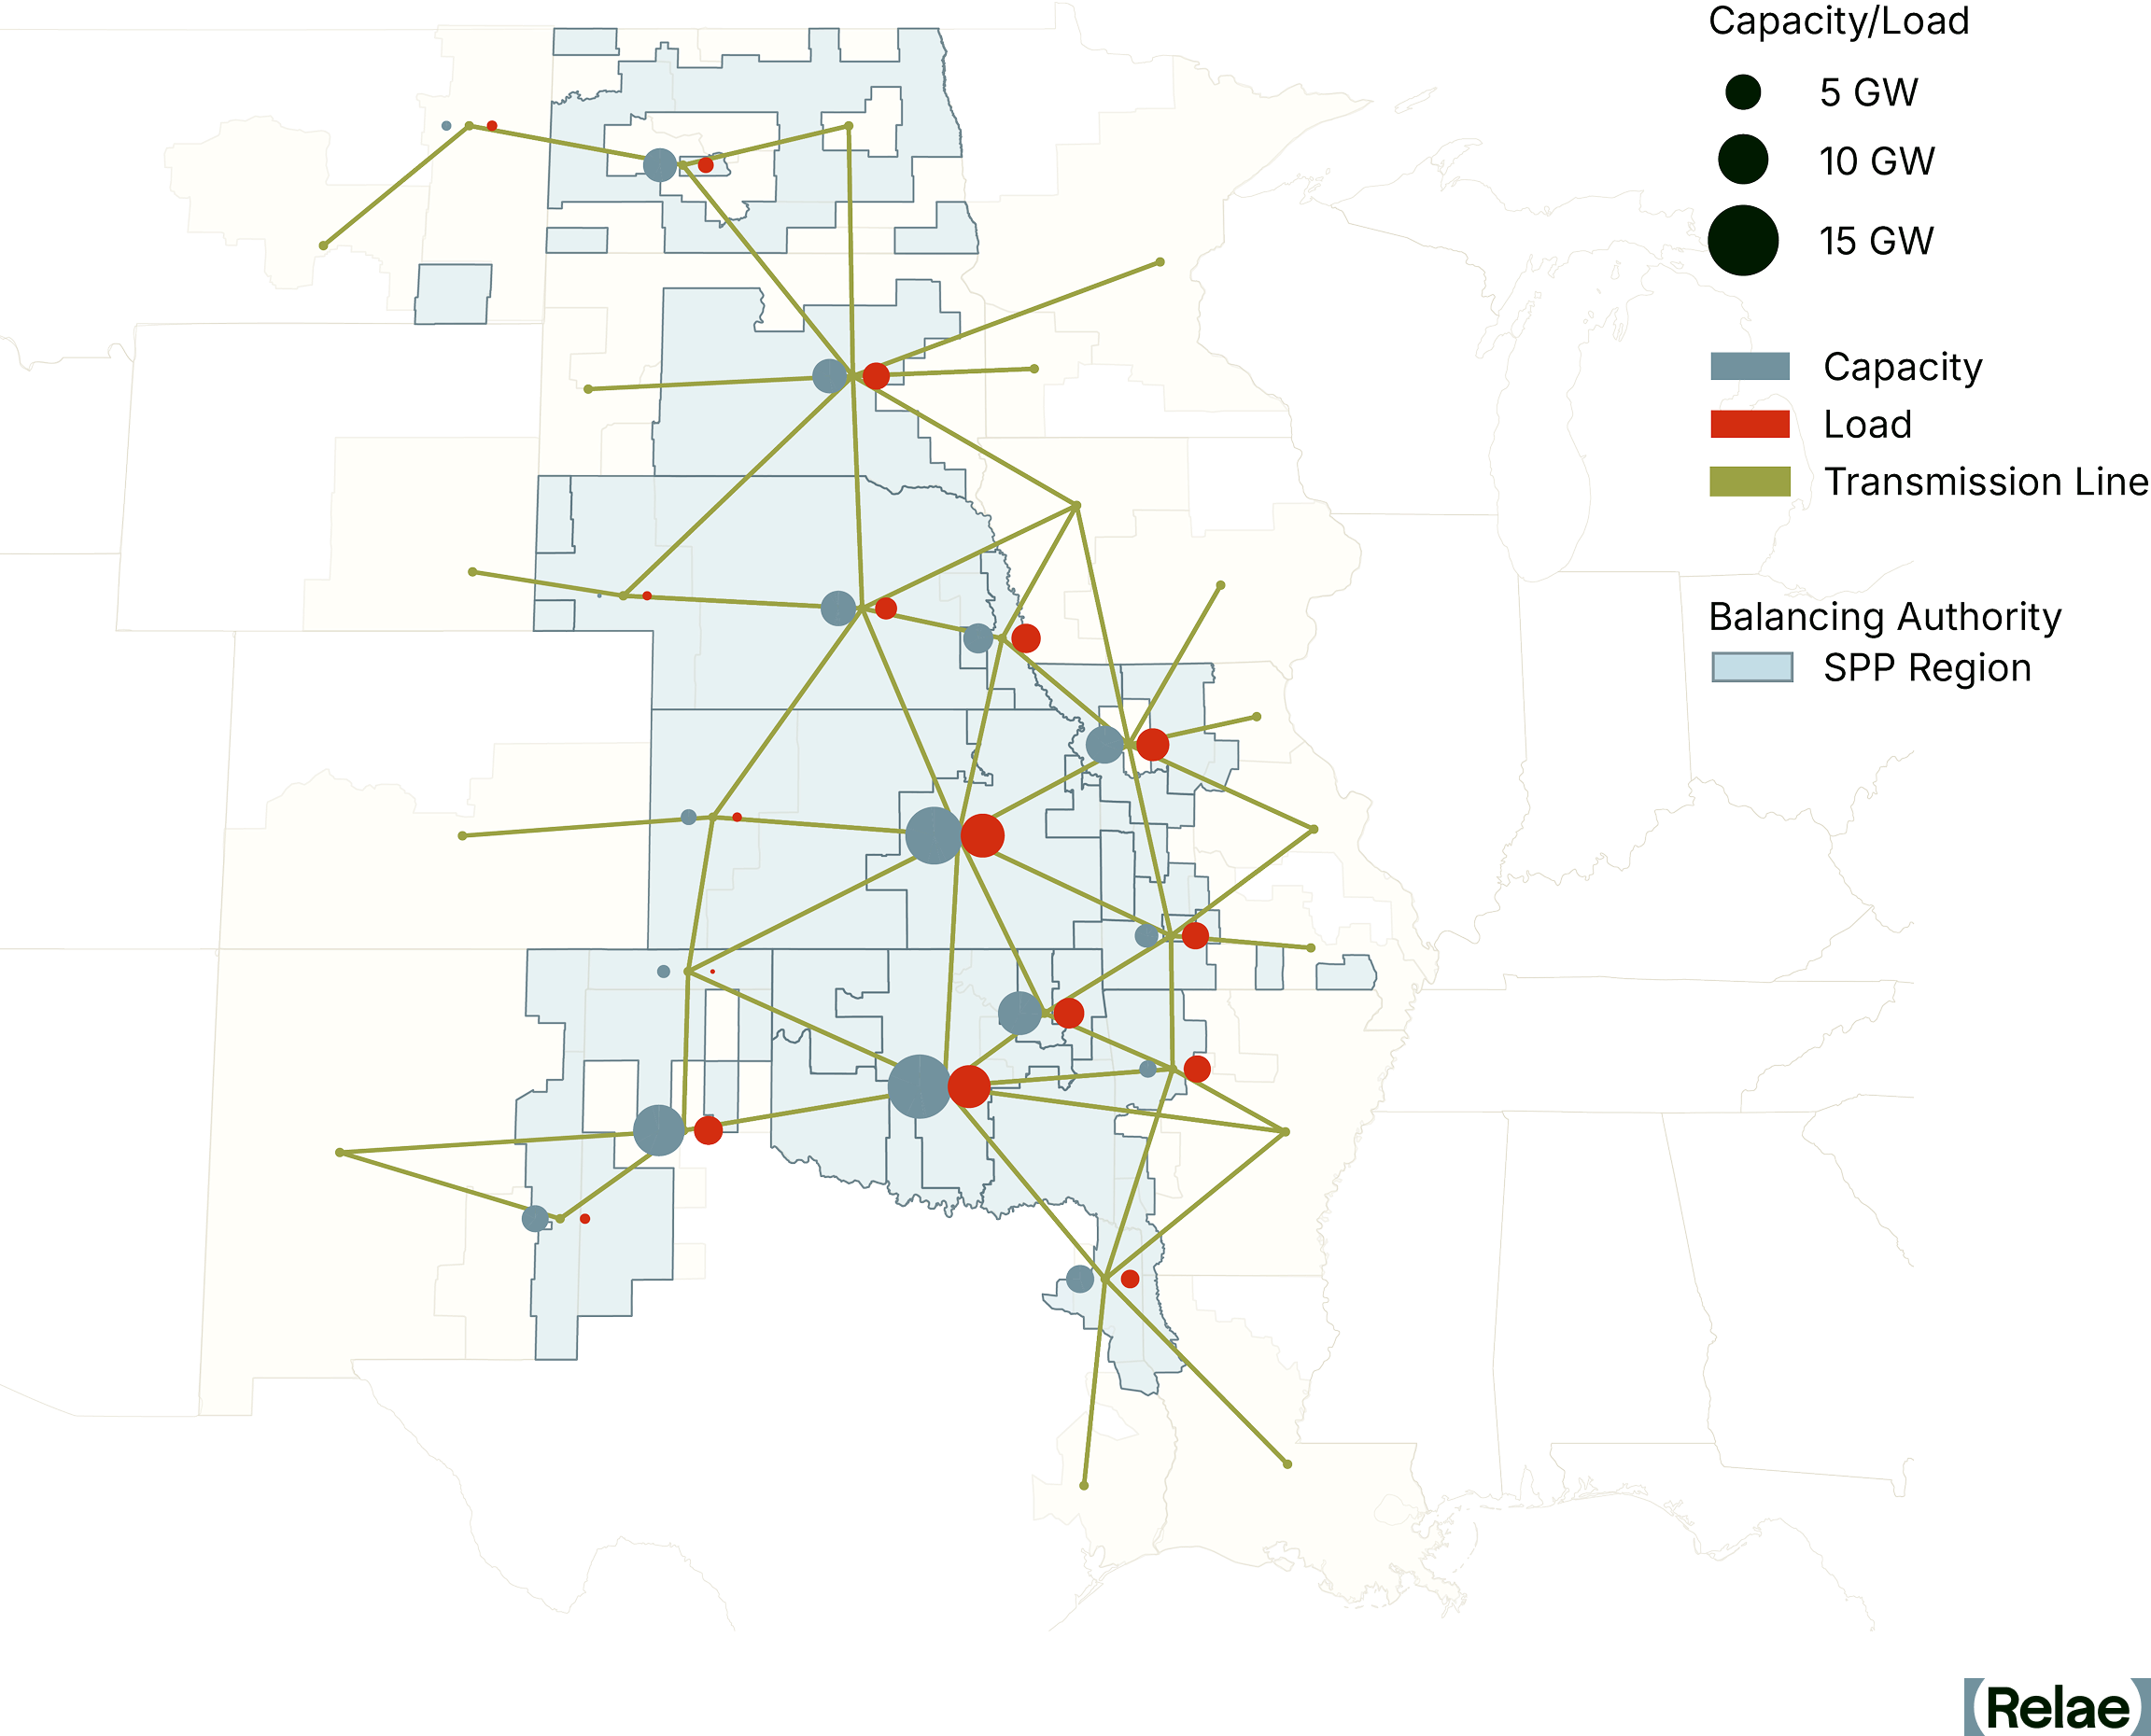
Because each grid region has distinct power plants and load requirements, they must be modeled separately. For this analysis, we chose to model the ERCOT and SPP power markets to determine the region-specific, grid-wide emissions impact of hypothetical CCS retrofits of natural gas power plants.
As part of this modeling, we:
- Deployed detailed hourly simulation: We used our custom PyPSA-USA grid model to produce a set of hourly simulations of the ERCOT and SPP electricity markets.2
- Identified suitable retrofits: We identified suitable combined cycle gas power plants for a CCS retrofit in each of the markets, based on key commercial and operational criteria, including size, age, generation profile, and proximity to CO2 transport/storage.
- Modeled plant and energy assumptions: To reflect the retrofit, we adjusted generator cost and energy use for the identified plants (up to 1.4 GW capacity), fitting all combustion turbines with capture and requiring each plant to consume 20% more fuel per unit of electricity produced to power CCS.3
- Carried out comparative scenario analysis: We simulated several scenarios, including (1) pre-retrofit, business-as-usual, (2) post-retrofit, with and without a PPA, and (3) post-retrofit, with and without the 45Q tax credit, to isolate the impact of different procurement agreements and policy landscapes on grid-wide emissions.
What Our Analysis Reveals
Results of this analysis reveal how CCS deployment in the power grid interacts with market economics and the role mechanisms that drive high utilization of CCS retrofit plants can have in ensuring system-wide emissions reductions:
CCS With a Firm Offtake Agreement Can Significantly Reduce Grid-Wide Emissions
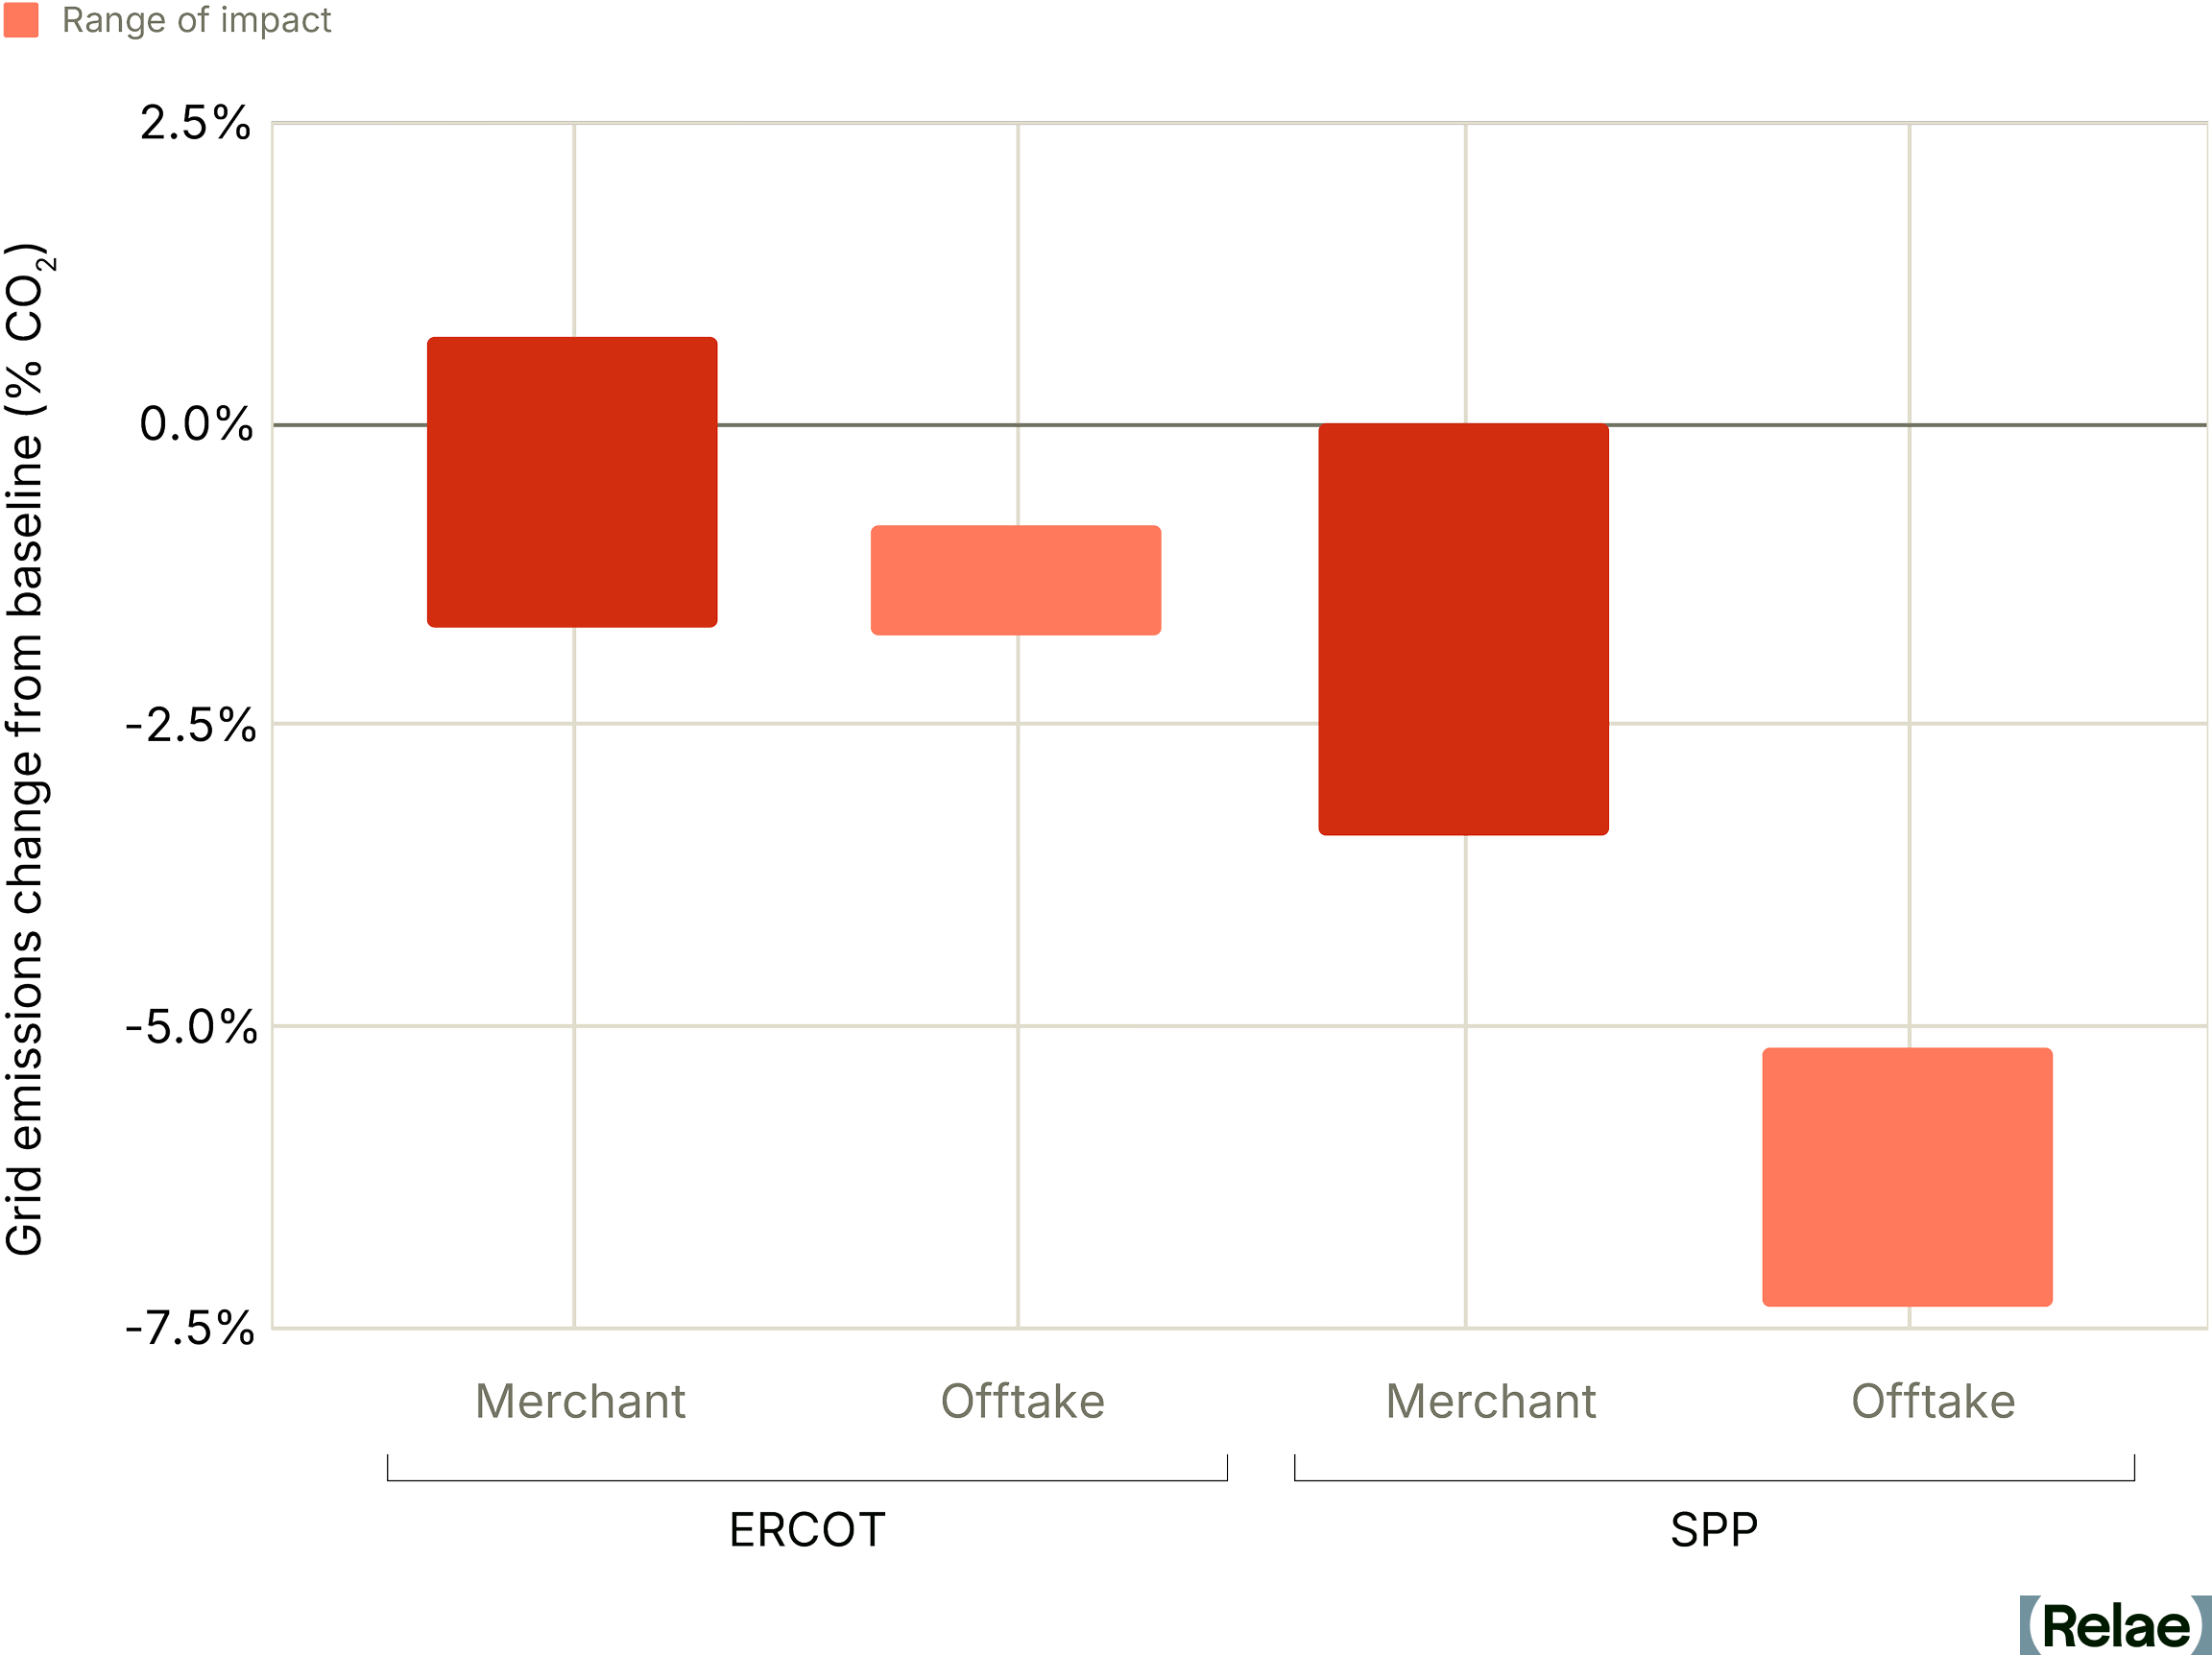
Pairing a retrofitted plant with a dedicated offtaker can drive meaningful emissions reductions in both ERCOT and SPP compared to business-as-usual (-0.8% to -1.7% CO2 in ERCOT; -5.2% to -7.3% CO2 in SPP). Under these arrangements, system-wide emissions fall because the PPA acts as an operational anchor, ensuring the retrofitted plant maintains high utilization rates despite its higher running costs. Ensuring the plant stays utilized prevents the grid from reverting to more carbon-intensive generation to fill the gap.
Our analysis finds the value of the operational “clean, firm premium” for natural gas with CCS power is up to $60 per MWh. This value varies by hour, region and scenario but results generally align with our previous estimate of a $30 per MWh value associated with this type of generation. Other estimates put this value between $19 and $72 per MWh.
CCS Without an Offtake Agreement Can Reduce Emissions, But Is More Reliant on Policy Support
Without a dedicated offtake agreement or policy support, retrofitting natural gas plants with CCS runs the risk of a small increase in grid emissions (+0.7% CO2 in ERCOT; -0.0% CO2 in SPP). System-wide emissions are higher because other power plants displace the plants with carbon capture. The higher operational costs of CCS mean the CCS plants have a less competitive place in the merit order and run for fewer hours in the year.
The story changes with the application of 45Q, and grid-wide emissions are lower for both ERCOT and SPP (-1.7% CO2 in ERCOT; -3.4% CO2 in SPP). Access to the 45Q tax credit improves each CCS plant’s position in the merit order, meaning that it runs for more hours and successfully displaces higher-emitting generation with clean, firm power.
The Path Forward for Clean, Firm Power
Our analysis illustrates that in competitive power markets, the overall carbon emissions impact of natural gas generation with CCS cannot be measured solely at the power plant level. While clean, firm power remains a strategic priority for large electricity buyers, and CCS is a key tool to meet this demand, the overall climate value of a successful retrofit is linked to the availability of offtake agreements and the plant’s position in the merit order.
A systems-level perspective captures what facility-level analysis misses: how market dynamics determine the true climate impact of decarbonization investments. Support mechanisms for the continuous operation of low-carbon power plants, like PPAs and the 45Q tax credit, are important tools that ensure clean, firm power reaches the grid, effectively bridging the competitiveness gap.
Frequently Asked Questions
How can companies ensure CCS retrofits actually reduce grid-wide emissions?
By securing the plant’s dispatch through a long-term offtake agreement, or by utilizing a policy incentive like 45Q. Relae’s modeling found that offtake agreements have a substantial impact on the emissions reduction potential of CCS retrofits.
Why would the dispatch decisions of one power plant affect others?
Power plants dispatch according to marginal cost, and grid stability requires that total supply remain constant at any given moment. So, if one large plant suddenly dispatches less (say, because its operating costs have increased), other potentially dirtier plants may ramp up to fill the gap, increasing total system emissions.
Inside NERC’s Level 3 Alert on Data Center Loads
Key Takeaways
- On May 4, 2026, the North American Electric Reliability Corporation (NERC) issued a rare Level 3 “Essential Actions” Alert in response to repeated events in which 1,000+ megawatts (MW) of computation load dropped off the bulk power system in seconds, leading to major grid stability issues.
- The pattern has since escalated: on July 22, 2026, a transmission fault in Ashburn, Virginia took more than 3 GW of data center load offline in seconds—roughly 3% of PJM demand at the time.
- NERC also published Reliability Guidelines that push the same concerns into long-term planning, explicitly recommending resource adequacy models that capture firm vs. flexible load, behind-the-meter resources, and AI training operating windows.
- For transmission operators and balancing authorities, the releases compel new scrutiny of how computational loads affect stability and resource adequacy. For hyperscalers and other large loads, those assessments now sit on the critical path: if operators cannot show through advanced modeling that they can integrate the new loads, interconnection and buildout plans stall.
- Meeting the bar takes advanced grid modeling at multiple time and spatial scales, from sub-second stability through long-horizon capacity and resource adequacy, to evaluate the role of large load portfolios considering demand response, storage, and co-located generation.
Why Grid Frequency Matters for Large Loads
When we turn on the lights or charge our phones, it’s easy to forget that electricity travels through the power grid as alternating current. Sixty times a second—far faster than our eyes can see—the flow of electricity alternates back and forth along the wires making up both the transmission and distribution parts of the North American grid.
Power generation equipment and most large industrial loads are designed to work with this 60 Hertz (Hz) alternating flow and must be synchronized precisely to this rhythm to function. Grid synchronization is so important that it can even have geopolitical implications.
For some electrical equipment, getting out of sync with the grid’s frequency can lead to malfunctions or even physical damage and destruction. That’s why grid-connected equipment is protected by circuits that automatically disconnect from the grid (“trip offline”) if the grid frequency begins to deviate by even one percent. For minor equipment, this is easily managed. However, when large amounts of generation or load trip offline quickly, it can lead to rapidly cascading grid blackouts affecting tens of millions of people with costs in the billions.
Grid operators pay extremely careful attention to factors that could cause grid frequency to deviate. The grid’s frequency stays near 60 Hz only when total power generation and consumption (load) are closely balanced. If load suddenly drops below generation, physical rotating generators like gas turbines can begin to speed up, making grid frequency rise.
This becomes particularly dangerous when large grid-connected loads all trip offline simultaneously because of minor frequency deviations or other factors. If these loads are large enough, they can trigger a cascading sequence of rising frequency and further equipment and generator trips, potentially causing a complete “grid collapse” blackout. The North American grid may be getting closer to this scenario.
What Triggered NERC’s Highest-Urgency Alert
Data center load drops are now a documented grid stability threat. On May 4, 2026, NERC issued a rare Level 3 “Essential Actions” Alert—its highest-urgency notification—in response to a pattern of customer-initiated load reductions in which 1,000+ MW of computational load (data centers) dropped off the bulk power system (tripped offline) in seconds. These were “customer-initiated” because protection circuits at data centers detected problems with grid-supplied power and automatically disconnected to protect their sensitive computing equipment from electrical damage.
Paired with a new Reliability Guideline on emerging large loads, the alert highlights the urgent need to better understand the potential for these events to cause grid instability or even blackouts. Together, these two documents reset the bar for the detailed grid modeling and planning needed for any utility, independent system operator (ISO), or hyperscaler with material data-center growth in its footprint.
Customer-Initiated Load Reductions
A customer-initiated load reduction (CILR) is an event in which a large load, most often a data center, AI training facility, or crypto miner, abruptly and without warning reduces or disconnects its electricity draw from the grid in response to a frequency or voltage disturbance that the grid’s internal protection circuits interpret as unsafe.
Compute-based loads like AI data centers are particularly sensitive to changes in the expected voltage and frequency from grid-supplied power, and their automated electrical protection systems tend to react more quickly and at smaller deviations than conventional industrial, commercial, and residential loads.
NERC has documented multiple events of 1,000+ MW since 2022, with reductions occurring in seconds, much faster than real-time operators can respond. This makes these events a significant risk to grid frequency stability that is distinct from more traditional load loss events that occur at a smaller scale or over slower timescales, allowing grid operators to take action to compensate.
How the Alert Reshapes Grid Interconnection
For utilities and ISOs, the alert and guideline raise the standard of evidence required to connect computational loads safely to the grid. Modeling assessments now sit on the critical path for large load interconnection decisions, and the same studies will increasingly inform reserve margin, transmission, and dispatch program designs.
For hyperscalers and other large loads, the consequence is direct. Plans that assume firm service without supporting analysis will face longer queues and tougher interconnection conditions. Buildout timelines now depend on whether utilities and ISOs can show, through stability and resource adequacy modeling, that the system can absorb the load and respond safely to its disturbances.
For storage developers, particularly long-duration and fast-responding assets, these events elevate the reliability value of rapid response and load-shifting resources. The same grid modeling improvements that capture flexible load behavior also surface storage's full reliability contribution.
For flexibility platforms, the same modeling work that satisfies NERC's expectations unlocks faster, cheaper interconnection. Demand response, large-load shifting, and co-located dispatch coordination are now both technical and commercial enablers.
A Higher Bar for Power Analysis
These pressures point to a higher bar for power analysis at multiple time and spatial scales, for utilities and the large loads they serve.
At sub-second to second timescales, electromagnetic transient (EMT) models capture fast electrical switching and the uninterruptible power supply behavior that determines whether a data center stays connected during a disturbance (“rides through”). The alert asks for these models to be more detailed, validated against actual equipment, and shared between large loads, transmission owners, and planners.
At seconds-to-minutes, dynamic stability simulation covers system frequency response, voltage recovery, and oscillation behavior after disturbances. NERC now expects annual stability studies and explicit load drop contingencies in planning files.
At hours-to-years, capacity expansion and production cost modeling determine whether the system has enough resources, in the right places, with the right flexibility, to keep up with computational load growth. NERC’s May 2026 Large Loads Reliability Guideline is most explicit at this scale, calling for resource adequacy studies that represent firm and flexible load components, behind-the-meter resources, AI training operating windows, and probabilistic scenarios across many weather, load, and outage combinations on a network-aware footprint.
Rising to the Challenge
Since the alert was issued, its expectations have begun hardening into rules. Registered entities were required to report to NERC on their progress against the seven Essential Actions by August 3, 2026, and on July 16, 2026, FERC directed NERC to go further: to develop mandatory reliability standards for computational loads and revise its registration criteria, with the first standards and Rules of Procedure changes due December 31, 2026 and a second-phase work plan due March 1, 2027. NERC's Large Loads Action Plan anticipates new "Computational Load Owner" and "Computational Load Operator" registered entity types alongside the first three computational load standards.
The practical consequence is that the modeling described above is no longer only good planning practice: utilities, ISOs, hyperscalers, and other large loads should expect the data-sharing, study, and commissioning expectations in the alert to return as auditable requirements, and should build the capability before the compliance deadline rather than after it.
Frequently Asked Questions
What is a NERC Level 3 Alert, and what does it require?
A Level 3 “Essential Actions” Alert is the most urgent of NERC's three alert levels, reserved for risks that need immediate, documented industry response. The May 4, 2026 alert directed registered entities to take seven essential actions on computational load—covering modeling, system studies, commissioning, protection, fault recording, and direct operational communication with large load operators. Written responses were due to NERC by August 3, 2026.
Why do data centers disconnect from the grid during minor disturbances?
Data centers run voltage- and frequency-sensitive computing equipment protected by automatic transfer systems that switch to on-site UPS or backup generation the moment grid power looks abnormal. Those protection settings trip faster, and at smaller deviations, than conventional industrial loads, so a fault lasting milliseconds can move a gigawatt of demand off the system in seconds. Because the shift is customer-initiated, grid operators get no warning and no time to rebalance.
How does the alert change interconnection for hyperscalers and other large loads?
Modeling assessments now sit on the critical path for large load interconnection. A plan that assumes firm service without stability and resource adequacy analysis behind it will face longer queues and tougher interconnection conditions, because the utility or ISO has to be able to show the system can absorb the load and respond safely to its disturbances. In practice, buildout timelines are now tied to someone else's study queue.
What modeling do utilities and large loads need to meet NERC's expectations?
Electromagnetic transient (EMT) models validated against actual equipment for sub-second ride-through behavior; dynamic stability simulation with explicit load-drop contingencies for seconds-to-minutes frequency and voltage response; and capacity expansion and probabilistic resource adequacy modeling that separates firm from flexible load, represents behind-the-meter resources, and reflects AI training operating windows. The paired Reliability Guideline is most explicit about the last of these.
Why AI Data Centers Are Being Blocked: A Project-Level Examination
Key Takeaways
- Community opposition has blocked, withdrawn, or stalled more than $170 billion in announced AI data center investment across 20 US states since January 2024. The pace is accelerating: 6 cancellations in 2024, 25 in 2025, and more than 20 additional cancellations by May 15, 2026.
- Data center opposition is bipartisan. It spans red and blue counties, every region, and multiple grid operators, with nearly two-thirds of the blocked investment sitting in counties that voted for Donald Trump in 2024.
- Process and transparency, more than resource concerns alone, drive the fastest and most durable opposition. How a developer runs the engagement process shapes both community sentiment and the project’s ultimate success.
How Many AI Data Center Projects Have Been Cancelled?
Between January 1, 2024, and May 15, 2026, community opposition blocked, withdrew, or stalled 46 announced AI data center projects across 20 US states, representing more than $170 billion in announced investment. These values are disclosed or derived for 35 of the 46 projects; the remaining 11 carry no public figure.
[stat]
The pace of successful opposition has accelerated sharply. Cancellations rose from 6 in 2024 to 25 in 2025. The first five months of 2026 added more than 20 additional cancellations, the fastest stretch on record.
Virginia leads the state count with 11 blocked projects, followed by Indiana with 7 and Texas with 5. Together, those three states account for roughly half of all cancellations in the dataset. The PJM grid region carries the largest single share of blocked investment at $70 billion across 13 projects, followed by MISO at $37 billion.
Is Opposition to Data Centers Bipartisan?
Yes. The opposition wave crosses party lines on every measure we examined. Republican-leaning counties hosted 28 of the 46 projects (61%), Democratic-leaning counties hosted 16 (35%), and 2 fell within five points.
Weighted by announced investment, about two-thirds of blocked dollars sat in Republican-voting counties. Strong Republican counties (those Trump won by more than 15 points) account for $99 billion across 23 projects. Strong Democratic counties account for $29 billion across 9 projects. The remaining $44 billion spans Lean Republican, Tossup, and Lean Democratic counties.
Why Are Communities Opposing Data Centers?
Communities raise a consistent set of concerns across the country: water demand, electricity rates, air quality where developers propose gas co-generation, rural character, and a lack of transparency in the development process.
Across the seven cases that we studied in depth, process, and transparency concerns were the most consistently cited factors associated with opposition. Non-disclosure agreements between developers and local officials, ownership structures in which the ultimate end-user was not publicly identified, and closed-door pre-application negotiations produce opposition faster and more durably than any other concern.
The pattern holds across very different communities: a diffuse civic mobilization in rural Georgia, an NGO water coalition in a Texas college town, a conservation coalition anchored by the Southern Environmental Law Center in Southside, Virginia, and an institutional civic organization with legal-expert and celebrity support in northern Virginia. Each produced the same outcome, and each flagged process and transparency as a dominant or top-three concern in the public record.
By the time a project reaches its first public hearing against organized community opposition, the political path of the project is largely set. Late-stage benefits packages consistently fail to reverse that trajectory. Communities read them as concessions, not commitments.
Assess Community Opposition Risk Before You Site
Community opposition is now a structural feature of the AI data center siting environment. The patterns are clear enough to act on now. Relae's Community Impacts team helps developers and capital partners implement responsible development standards through pre-siting community intelligence, calibration of benefits design to specific community contexts, and building the verification scaffolding that turns commitments into outcomes.
[cta]
Frequently Asked Questions
Which states are banning data centers in the US?
The first statewide moratoriums on data centers have arrived. In July 2026, Governor Hochul signed the country's first statewide moratorium, an executive order pausing state environmental permits for up to one year for new data centers of 50 MW or more. Texas followed weeks later, halting approvals of new data center grid connections until state regulators audit their power, water, tax, and ownership details. This is a snapshot from August 2026, and we will likely see additional changes in the months ahead.
The local picture is more developed. Individual municipalities and counties have adopted moratoria and zoning ordinance amendments that block or restrict data centers within their jurisdictions. The City of Peculiar, Missouri, removed data centers from its light-industrial zoning entirely. Monroe County, Georgia, and Jones County, Georgia, both adopted moratoria after project denials in 2025. Cassville Township, Wisconsin, and San Marcos, Texas adopted zoning and code amendments in 2026. State legislatures in Virginia, Indiana, Texas, and Missouri have taken up data center siting, ratepayer, and permitting legislation, though most bills remain in progress rather than enacted.
How much data center investment has been blocked in the US?
More than $170 billion in announced AI data center investment has been blocked, withdrawn, or stalled by community opposition across 46 projects and 20 US states between January 1, 2024 and May 15, 2026.
Relae arrived at this figure from data on 35 of the 46 projects; 11 have no publicly disclosed investment value. The pace has accelerated sharply: 6 cancellations in 2024, 25 in 2025, and more than 20 additional cancellations in the first five months of 2026 alone. Virginia leads the state count with 11 projects. The PJM grid region carries the largest single share of blocked capacity at $70 billion across 13 projects.
What causes a data center project to be cancelled by community opposition?
As of August 2026, communities cite a consistent set of concerns across cancelled projects: water demand, grid strain and residential rate impacts, air quality where developers propose gas-fired co-generation, rural character and farmland conversion, and lack of transparency in the development process.
In the seven cases we studied in depth, process and transparency were together the most consistent driver of opposition. Non-disclosure agreements between developers and local officials, shell LLC ownership structures that conceal the end-user, and closed-door pre-application negotiations produce faster and more durable opposition than any single resource concern. Late-stage benefits packages consistently fail once that transparency-driven frame has formed.
Dynamic Line Rating: The Fastest Gigawatt Is the One You Already Have
Key Takeaways
- Power demand is outrunning buildout. Meeting large load growth requires more than new generation; it requires faster interconnection and congestion relief on existing transmission lines.
- Dynamic line rating (DLR) is available today, deploys in months, and enables faster speed-to-power. On the right thermally congested lines, DLR can unlock more capacity at a fraction of new infrastructure cost. In one utility demonstration, 5% to 10% of additional capacity was enough to clear most of the congestion on the lines studied.
- DLR has been held back by weak incentives, but that is changing. Utilities earn a regulated return on capital they invest in new assets, which favors building new infrastructure over lower-cost solutions like DLR. Load growth and new Federal Energy Regulatory Commission (FERC) mandates are starting to shift the calculus.
The Grid Cannot Expand Fast Enough for AI Demand, But It Can Carry More
Power demand is booming as data centers scale across the US grid, and current grid infrastructure cannot supply it. This constraint is physical, not financial. Meeting this demand requires a significant amount of power generation and infrastructure upgrades. More than 2 terawatts of generation and storage sit in interconnection queues, roughly 1.5x the total installed generation capacity in the US.
Regional markets are working to accelerate generation buildouts, but connecting that generation to the transmission network remains expensive and slow to match speed-to-power needs. New high-voltage lines take years to permit, cost between $2 million and $6 million per mile to build, and major projects routinely take five to ten years from identification to energization. For example, PJM Interconnection LLC (PJM) identified the Doubs–Goose Creek 500 kilovolt (kV) corridor as a bottleneck feeding Data Center Alley in 2023 and set June 2027 as the date a fix was needed. Dominion Energy's published schedule for its portion of that rebuild anticipates a completion date of 2031.
A number of studies1,2 show there is headroom in the bulk transmission system. Grid-enhancing technologies, such as dynamic line rating (DLR), can convert part of that headroom into capacity today while new generation and transmission are being built. DLR lets suitable transmission lines increase their carrying capacity in real time, unlocking that headroom at a fraction of the cost of a buildout. Realizing that value is a targeting exercise with a key question: On which thermally limited lines can DLR actually relieve congestion?
What Is Dynamic Line Rating?
Dynamic line rating is a method for calculating a transmission line's real-time carrying capacity using live weather and conductor-temperature data. It lets grid operators safely carry more power whenever weather conditions allow.
Most transmission lines operate under a static rating: a fixed, conservative limit on current, set for worst-case weather and held all year. The limit is based on temperature, because pushing too much current can overheat the conductor wire. Metal conductors expand as they heat, which can make them sag and touch trees or other obstacles, causing short circuits or fires. Real conditions almost always cool a conductor better than the worst-case assumption a static rating is built on. That means the line can carry more current while staying at the same maximum conductor temperature, and therefore within the same sag and clearance envelope. That headroom is exactly what DLR captures: instead of leaving it on the table, DLR recalculates the line's rating in real time so operators can use the extra capacity safely.
Beyond a static rating is the ambient-adjusted rating (AAR), which many utilities have begun adopting. An AAR recalculates the rating from forecast ambient air temperature, typically hourly and out to several days. DLR goes further, adding wind speed and direction, solar heating, and in some deployments the conductor's measured temperature.
DLR technologies rest on a heat-balance algorithm: how fast a line heats up (from electric current and sunshine) versus how fast it cools off (from wind and cold air). The calculations are standardized in IEEE 738 in North America and CIGRE 601 internationally. The data feeding those calculations can come from line-mounted sensors, weather models, or both, depending on a tradeoff between per-span accuracy and the cost of installing sensors along every span.
Even so, DLR remains limited in the US, and AAR has been slow to arrive. FERC's Order 881 required the transmission providers it regulates to adopt AAR by July 2025, but FERC has granted numerous extensions. PJM became the first to fully implement AAR in March 2026, while Midcontinent Independent System Operator (MISO) and New York Independent System Operator (NYISO) are not expected until 2028.
The Near-Term Value of DLR: Reducing Grid Congestion
DLR's value is immediate. It can be installed in months, not years, so a currently congested line can start carrying more power the moment conditions allow, reducing congestion right away. When cheaper generation is available upstream of that line, DLR cuts costs directly, because grid operators no longer need to dispatch pricier generation downstream of the congestion to supply load. That means DLR can reduce congestion costs in the current delivery year, compared to a transmission line rebuild that sits in a decade-long queue.
Over a longer horizon, utility planners can build that headroom into long-term capacity models. This is important, because current capacity-expansion and integrated resource plan (IRP) models still run on static or seasonal ratings, and typically leave out the potential gains from grid-enhancing technologies like DLR.
NERC's large loads white paper and FERC's RM26-4 rulemaking both raise the issue of how utilities can absorb multi-hundred-megawatt data center requests without a decade-long transmission build. Solutions like DLR are one of the few tools that can compress that timeline.
The hardware itself is cheap: sensors and data management cost a small fraction of any physical upgrade. That means the economics comes down to identifying the lines that benefit most from DLR. This is particularly important because on most US grids, congestion concentrates on a small number of lines that repeatedly reach their limits. On those lines, DLR can cut congestion costs directly and defer costlier upgrades, while its potential on other lines may be far lower. As a result, identifying those high-potential, thermally congested lines is essential.
Proven DLR Examples in the Industry
Real deployments show DLR can reduce a meaningful share of transmission congestion costs, with extra carrying capacity above the static rating running roughly 5% to 30%, depending on how often that capacity is available. In Oncor's ERCOT demonstration, 5% of additional capacity would have relieved up to 60% of congestion on the target lines, and 10% would have practically eliminated it. PPL Electric in Pennsylvania/PJM reports annual customer savings of $23 million after deploying DLR across its initial three lines. The DLR installation cost about $250,000, against a rebuild alternative that would have cost about $50 million and taken far longer.
The contrast abroad is instructive. Austria's grid operator, APG, recorded about $13 million a year in congestion savings across roughly 15% of its network. While these savings are real, it's important to recognize that these results come from single, well-chosen, badly congested lines.
The UK's National Grid began with a two-year DLR trial on a single 275 kV circuit in 2022, expanded to more than 275 kilometers of its network by 2025, with estimated consumer savings of about $26 million a year. In April 2026, National Grid signed a five-year contract covering 585 kilometers more, with most installations due by 2028 and potential savings of up to $66 million. Each expansion followed measured results from the stage before it.
Where the Headroom Is: Screening PJM's Data Center Alley
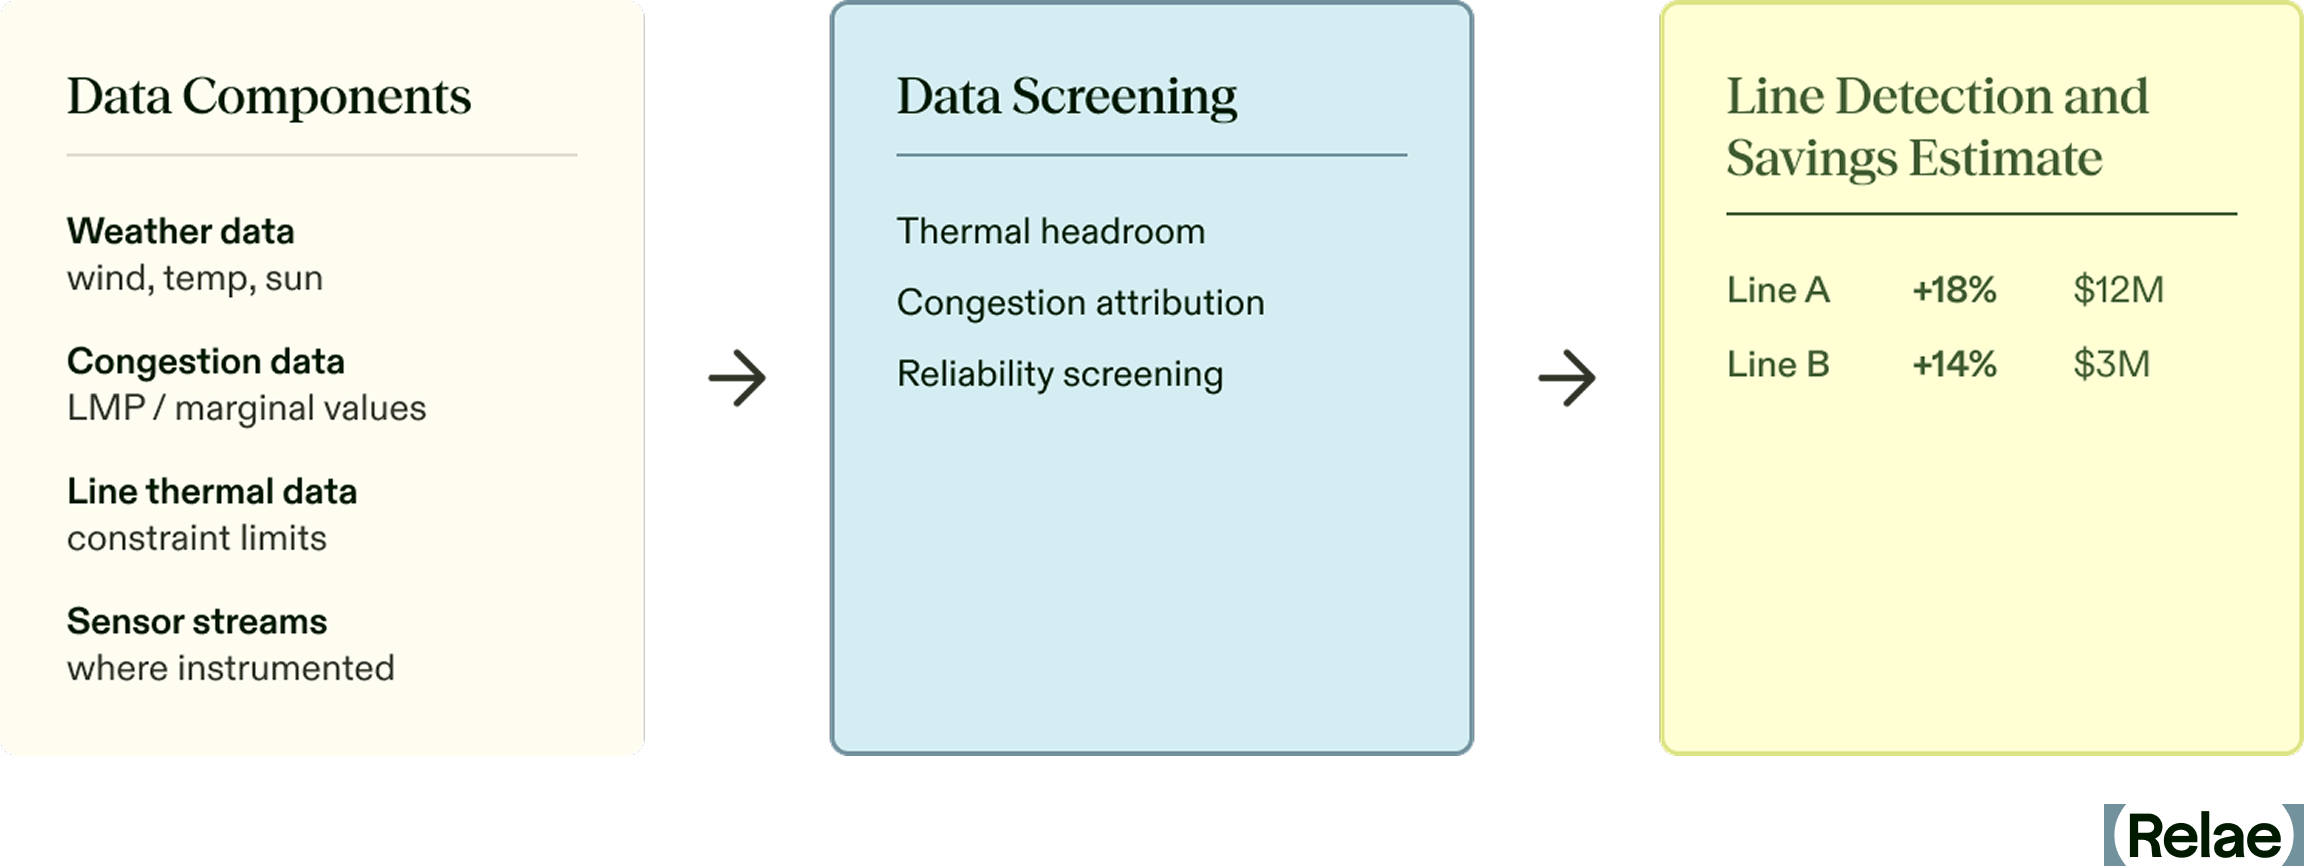
To illustrate the congestion savings from DLR, Relae screened PJM's five-minute real-time market record for every binding transmission constraint in 2025. For each one, we captured the shadow price, the marginal value of relaxing that constraint.3
Our analysis focused on thermal constraints, and then identified lines that bind frequently, in conditions milder than the worst case their static rating was set for, which is when a conductor's true rating sits above its static assumption. For the lines that we identified, congestion costs were added over the binding hours to set a bound on the savings that could result from DLR. That full amount would not necessarily be realized in practice, because the shadow price values only the next megawatt freed, and relieving one line can shift the constraint to the next. However, it serves as a useful estimate for the scale of savings that could be achieved.
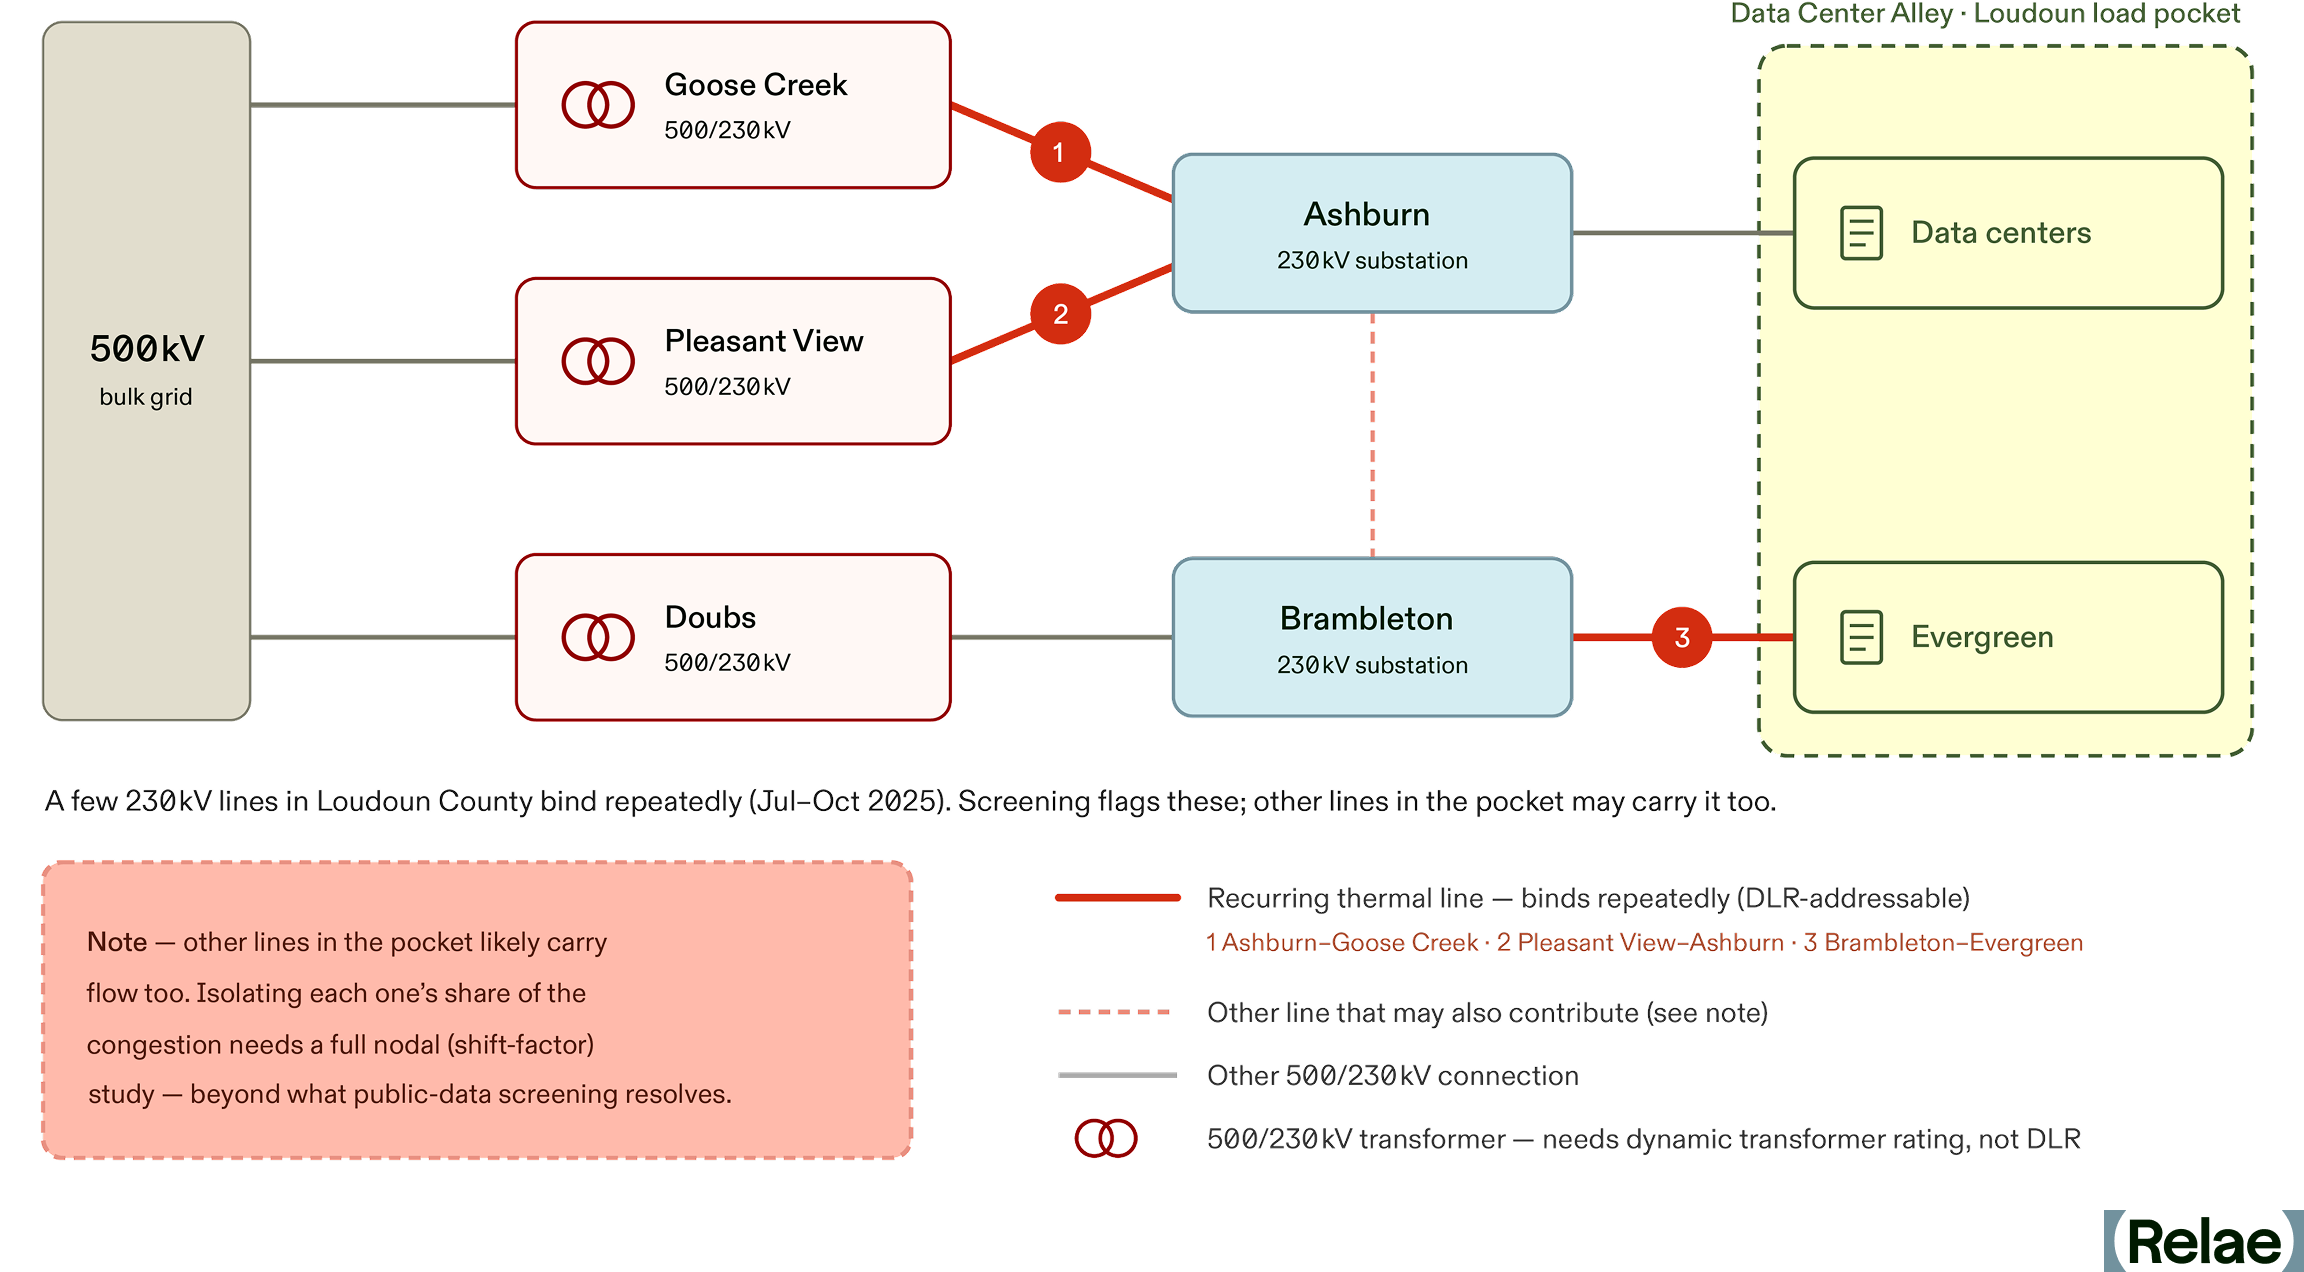
We ran the analysis on the Dominion (DOM) zone in PJM, home to Data Center Alley in Loudoun County, Virginia. Figure 2 shows a high-level section of the grid. The 500 kV bulk grid steps down through transformers to the 230 kV substations feeding the data centers, with the lines that experience recurring congestion highlighted. A handful of those 230 kV lines showed up as binding thermal constraints again and again.
The congestion in DOM isn't constant, and it concentrates in particular months and within the day in particular hours. Figure 3 shows three transmission lines within the DOM zone and the number of hours each was thermally congested in each hour-of-day slot over 2025. Binding concentrates in the warm months and, within the day, from late morning through early evening.
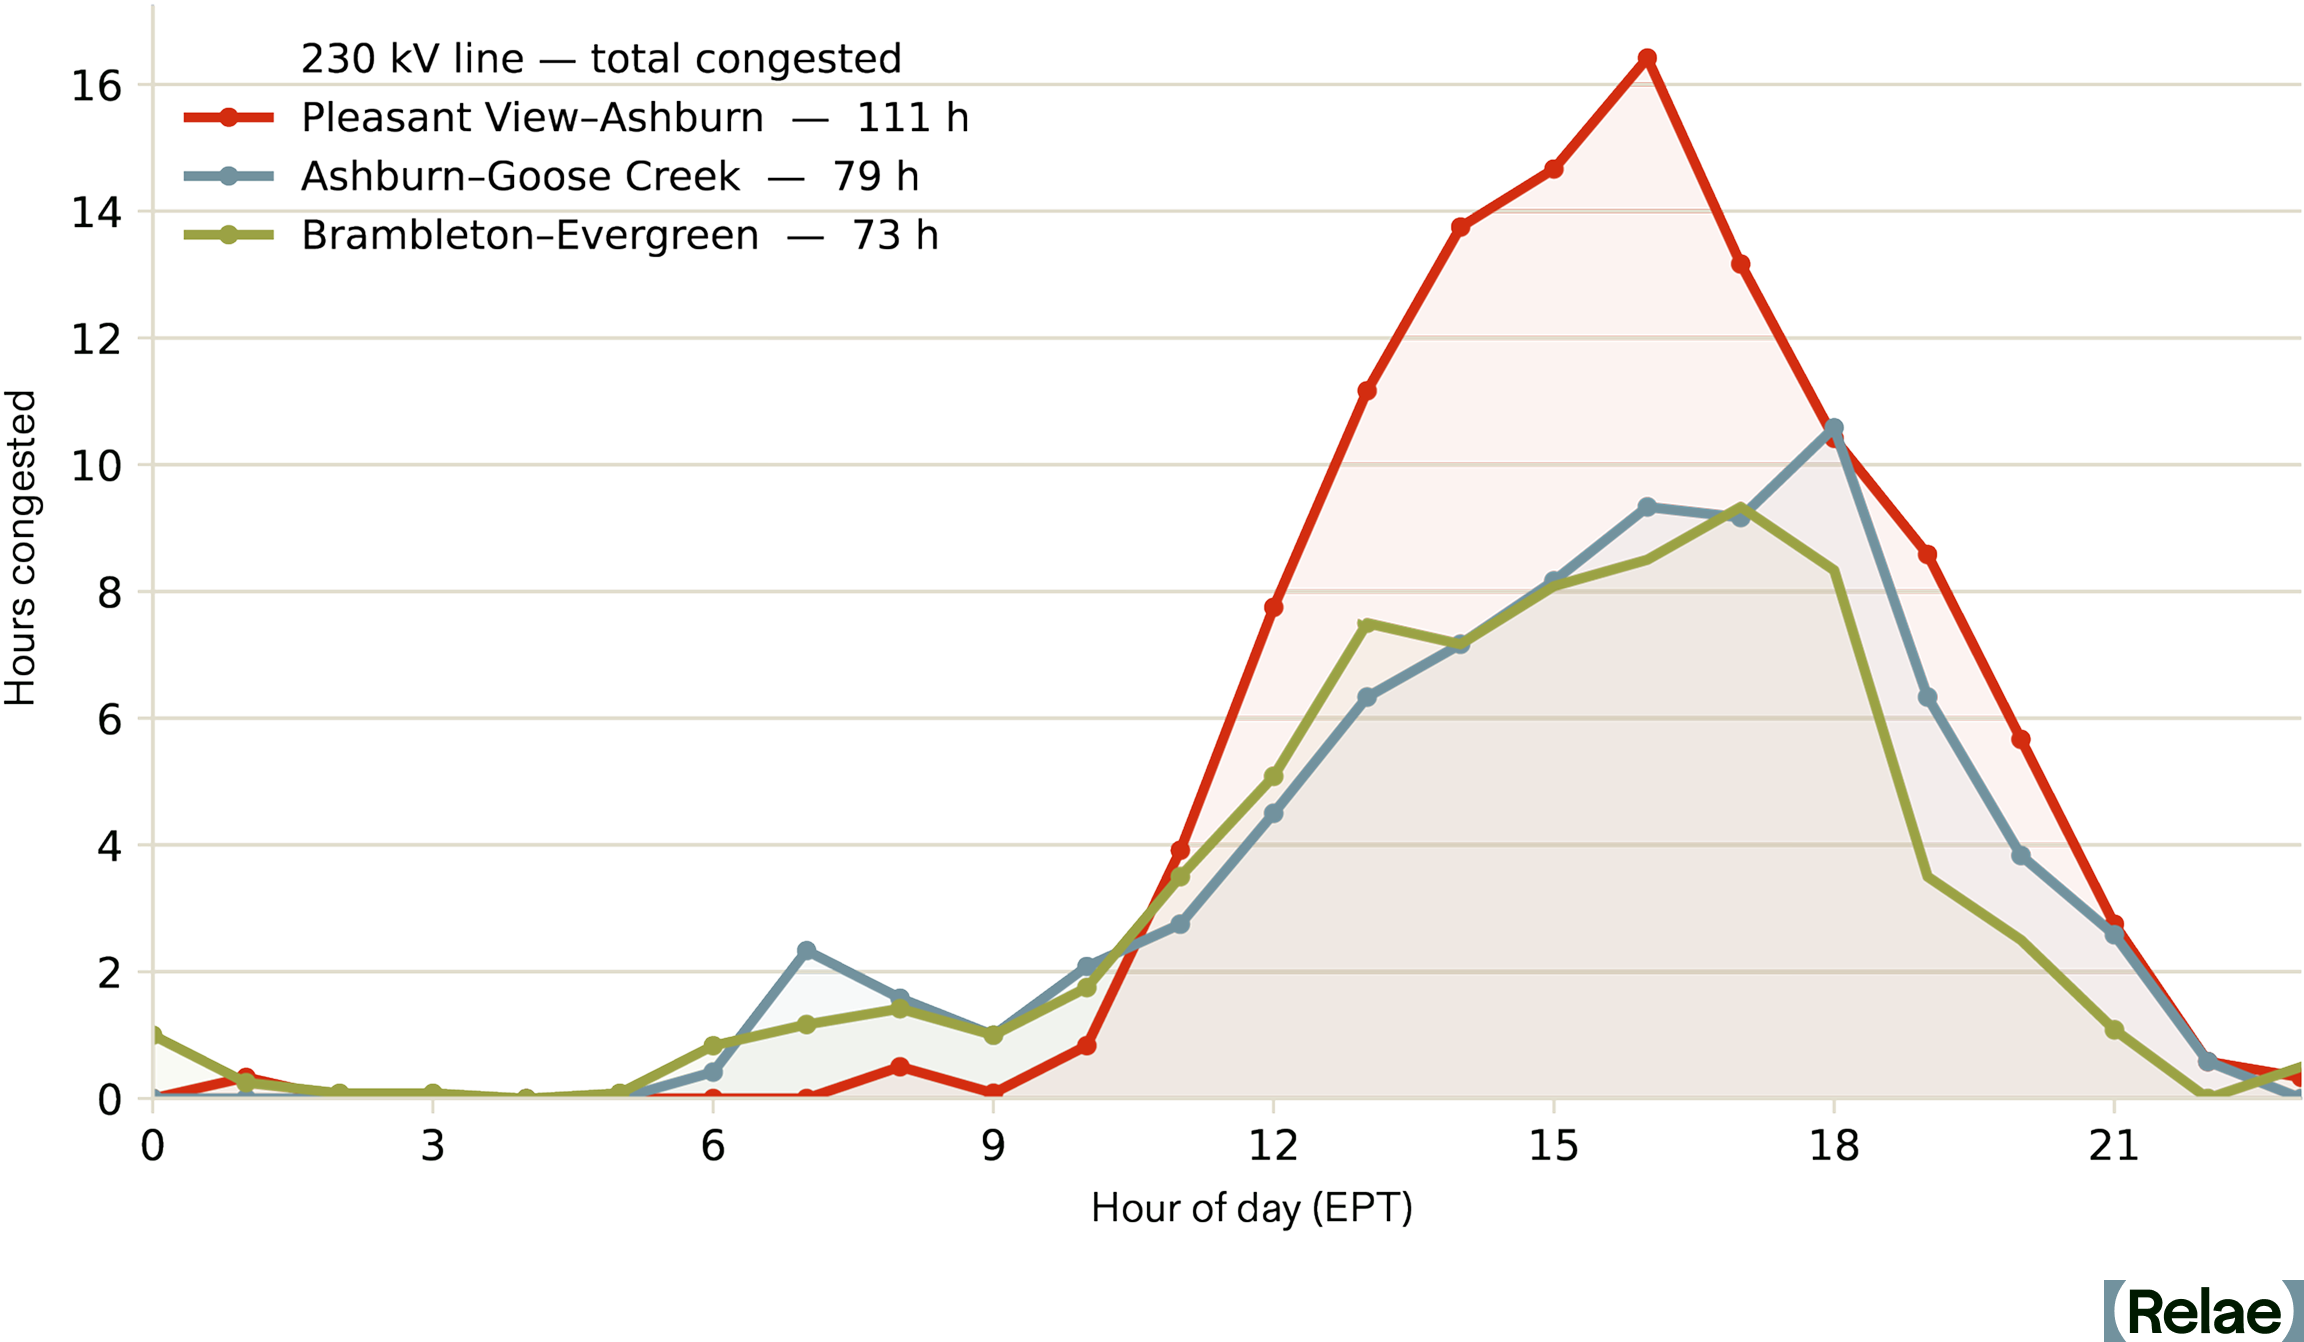
At first glance, this period looks like the wrong window for DLR. The local weather record says otherwise. These periods turn out to be some of the windiest hours of the day, not the stillest. Median wind speed at Dulles ran about 3.5 m/s, above the 0.6 m/s crossflow a static rating conventionally assumes, with fewer than 5% of observations falling below that threshold. Median ambient temperature in those hours was about 26°C, against the 35–40°C a static summer rating is typically built for. Across all three lines, the large majority of congested hours coincided with weather that would have supported a materially higher rating.
Valuing just one megawatt of DLR relief at each five-minute shadow price, the estimated savings are worth roughly $300,000 in this three-line example across about 263 line-hours.4
Because the value concentrates on a handful of thermally limited, heavily congested lines, and because the operational case has to be made line by line, capturing the opportunity is fundamentally an analytics problem: find the right lines, and prove the savings.

What Does It Take to Scale DLR?
DLR is cheap and effective, but two things stand between it and broader adoption: incentives and advanced grid analytics.
The utility cost-of-service model recovers investment in generation and transmission assets and earns its profit as a regulated return on the capital deployed. Because rates recover capital rather than power delivered, utilities have a stronger incentive to build or upgrade lines than to move more power across the ones they already own. That bias toward capital investment over optimization is why a mature technology has stayed niche in the US for years. Regulators have started to look more closely at this, but the main federal rule still mandates the milder AAR, not DLR, and leaves the return model untouched.
Contingency analysis compounds the problem. Current models are built around fixed line limits. A rating that changes hour to hour adds real modeling work, and more importantly, the system still has to hold under worst-case contingencies. So while operators already forecast weather daily for wind and solar, the harder step is trusting a forecast enough to commit a transmission limit against it. That takes significant predictive analytics built into system planning, not bolted on after.5
How Policy Is Starting to Shift the Calculus
Policy is starting to move the incentive problem. FERC's Order 881 made AAR the minimum for the transmission providers it regulates (effective July 2025, with several operators on extended timelines) and required markets to be capable of accepting dynamic ratings. PJM has started to implement this: PPL Electric has run sensor-based DLR on nine congested lines since 2022, feeding PJM's day-ahead markets.
Order 1920, FERC's first long-term transmission-planning overhaul in more than a decade, now requires planners to formally evaluate grid-enhancing technologies like DLR against conventional builds. It stops short of mandating deployment, but it forces a comparison utilities used to skip. That comparison is now written into filed tariff processes (PJM filed its plan in December 2025). Those first cycles only began in 2026, and the order allows up to three years to reach a selection, so the results are still pending.
A shared-savings incentive, letting a utility keep a slice of the congestion savings it creates, has been proposed to FERC and championed in the Advancing GETs Act, but it isn't yet a rule, so the core misalignment stands. DOE's GRIP program has funded grid-enhancing deployments, and by early 2026, 16 states had some form of advanced transmission technology requirement, with Colorado adding its Grid Optimization Act in April 2026.
The newest pressure is coming from the demand side. Through 2025–26, FERC began overhauling how large loads connect to the grid, and while none of it touches the utility's return on capital, it changes who sees the costs. FERC issued show-cause orders directing all six grid operators to justify or reform their large-load rules. This tees up consideration of alternative transmission technologies in study processes and greater transparency into costs.
And the rules are moving toward making the large load pay for the upgrades its connection requires. Pennsylvania's model large-load tariff, for example, recommends utilities charge data centers for the upgrades their interconnection makes necessary. It also instructs utilities to let those customers self-construct certain upgrades, including some affecting the wider grid. That combination is what matters. The party paying the bill now has a reason to ask whether a cheaper fix exists and, in at least one state, a route to build it. We have not yet seen a DLR deployment selected this way, because these frameworks are only months old, but the cost gap between a DLR fix and a rebuild is becoming visible to the party who pays the difference.
How Relae Helps Find the Value of DLR
Through our Power, Data, and Innovation practice, Relae combines transmission congestion data, line-level thermal constraints, and short-term weather forecasts into a single view of where dynamic ratings would actually pay. The output is a short list of candidate lines, each with a modeled capacity uplift and an estimated dollar value, turning a vague “DLR is promising” into a priced, line-by-line decision. It is the transmission-side complement to our work on the interconnection queue and demand-side flexibility. All three are ways of closing the gap between demand and delivered capacity faster than new construction allows.
Understanding the Carbon Footprint of AI and How to Reduce It
Key Takeaways
- AI's carbon footprint has two distinct parts: embodied emissions from building data centers and operational emissions from running them, both accelerating as global data center electricity use is set to double by 2030, and AI-focused use to triple.
- Managing that footprint will require deliberately steering technology architecture, power sourcing, and materials choices, instead of leaving them to react to demand after the fact.
- Eight concrete strategies, from smarter chip design to firm clean power and carbon removal, can cut AI's footprint today, without waiting on new regulation.
- US data centers used 4% of the USA's total electricity in 2024, and are projected to use as much as 15% by 2030.
Introduction
The rapid growth of artificial intelligence (AI), particularly large-language models (LLM) and generative AI, has taken many by surprise. This surge has led to escalating electricity demands at data centers and raised concerns about the strain on the power grid. It has also sparked the construction of new, larger data centers, resulting in growing embodied emissions tied to building and maintaining AI physical infrastructure.
Managing the risks of increased greenhouse gas (GHG) emissions from AI requires investment, expertise, and new approaches to building and operating many aspects of AI operation and supply chains. The immediate task is to understand these risks, gather the necessary information, and to avoid poor outcomes by proactively managing construction, operation, and emissions associated with the growth in AI. In parallel to that work, it's important to recognize that AI can itself be a real force to reduce emissions incrementally and dramatically across a wide range of sectors.
What Is the Carbon Footprint of AI?
The carbon footprint of AI consists of two main parts: "embodied" emissions that come from manufacturing IT equipment and constructing data centers, and "operational" emissions that come from electricity consumed by servers, memory and networking equipment as they perform AI-related calculations. Both of these aspects of emissions are growing as more data centers are built and existing data centers increase their share of power-hungry AI applications like generative LLM searches, AI agents, and AI image generation.
Understanding Electricity Demand for Data Centers
Today, the electricity demand from AI-specific applications is estimated to be less than 1% of global electricity use. To understand this number, it helps to start with the electricity consumed by the 12,000+ data centers worldwide, which was about 1.5% of global electricity consumption in 2024. (This excludes another 0.4% from cryptocurrency mining.) However, most of the computation at these data centers is not AI; instead, it's more conventional applications like e-commerce, video streaming, social media, and online gaming.
The amount of AI-based computation at data centers is hard to determine, but AI-dedicated accelerated servers consumed about one third of overall data center electricity in 2025, or roughly 0.5% of global electricity. Notably, this is projected to grow at 30% annually, much faster than conventional (non-AI) data center electricity use. However, that electricity use results in a relatively small share of greenhouse gas emissions: about 0.5% of global fuel combustion emissions, with AI data centers representing only a small portion of that value.
Still, the demand for AI applications is rapidly growing, and this is likely to drive up the electricity used by data centers and the associated greenhouse gas emissions. The most important implications of this trend are in the US, which hosts about half the world's data centers. Currently, data centers use about 4% of US electricity, but projections for the future range from a low of 9.5% to a high of 15.3% in 2030.
[cta]
How Electricity Sources Impact Data Center Emissions
A large increase in electricity use doesn't necessarily result in a similarly large increase in greenhouse gas emissions. Currently, a significant portion of the electricity powering data centers comes from zero-carbon sources such as wind and solar. This is partly because of large, corporate power-purchase agreements (PPAs) signed by leading data center operators, particularly Amazon, Meta and Google.
US technology companies have been buying renewable energy for years. Global corporate clean energy procurement hit a record 62 GW in 2024, then fell to 55.9 GW in 2025, the first annual decline in nearly a decade, as elevated power prices and policy uncertainty made even large buyers more selective. Meta, Amazon, Google, and Microsoft still accounted for roughly 49% of global clean energy procurement in 2025, with Meta and Amazon alone securing 20.4 GW combined, including 4.7 GW of nuclear power.
The use of low-carbon power means that the net emissions from these data centers is smaller than the electricity consumption numbers might suggest. Of course, a crucial consideration is whether this low-carbon power is truly "additional," meaning that it is being added to the grid and not simply taken away from other uses. Data center operators are also expanding beyond their traditional wind and solar PPAs by exploring novel approaches to try to meet this standard, including geothermal projects in the US and Taiwan.
However, the projected electricity demand from AI applications at data centers will be difficult to meet entirely with low-carbon power, at least in the near term. Despite installing over 43.2 GW of wind, solar and battery projects in the US in 2025, these generators face a long wait for interconnection approval in many parts of the country. Geothermal and hydro power, which offer steady ("baseload") low-carbon electricity, remain constrained in the near term. And the interest in scaling up nuclear power, from restarting full-scale reactors to novel small modular reactors (SMRs), faces significant regulatory, cost, and supply chain hurdles.
One important source of low-carbon electricity that has not received enough attention is natural gas-fired power equipped with carbon capture and storage (CCS). This technology has the potential to significantly reduce emissions from existing power plants and enable new projects to achieve near-zero emissions.
The Role of Embodied Emissions in Data Center Construction
Embodied emissions include all emissions associated with the extraction, production, transportation, construction, and disposal of materials used in construction.
The embodied emissions from constructing data centers are substantial, and include concrete, steel, and IT hardware. Scope 3 GHG emissions for data centers—which include embodied emissions—range from approximately one-third to two-thirds of overall lifetime emissions. At Microsoft, Scope 3 emissions made up about 86% of the company's total FY2025 footprint and grew roughly 12% year over year, with capital goods driving most of that increase. In FY2024, capital goods alone accounted for about 41% of Microsoft's Scope 3 emissions, and purchased goods and services (including IT hardware) accounted for another 34%. In response, Microsoft has started using wood in some data center construction to reduce this impact. While using wood offers a partial solution, it cannot fully offset the emissions of even a single facility, and wood supply chains remain limited.
Major data center operators are working hard to address this challenge, including emphasizing the need for standardized emissions measurements and disclosures for key building materials. Ultimately, achieving deeper decarbonization will require further action to address both operational and embodied emissions.
Eight Strategies to Reduce the Carbon Footprint of AI
1. Adapt Technology Architecture
Efficiency is the foundational strategy in any clean energy approach. As such, chipmakers are developing ways to cut energy use from the outset, such as incorporating more memory directly onto computer chips or hard-wiring basic calculations. These innovations have already reduced energy consumption in new computer chips substantially, in some cases a 96% improvement. Examples of this include NVIDIA's Blackwell platform and the company's newer Rubin platform, launched in 2026, continues that trajectory. Likewise, servers are being designed with new architectures that minimize internal data transfers, delivering additional efficiencies. Even more efficiency gains may be possible with emerging technologies like photonic computing.
2. Optimize Training Geography
There are also significant opportunities to manage AI's energy use through time and space optimization. For example, a large portion of the energy consumption for LLMs occurs during the training phase, prior to a model's deployment for inference. Because these training tasks are not location-dependent, they can be carried out in regions with abundant, low-cost, low-carbon electricity, as part of broader efforts to dynamically move computing tasks to reduce emissions, known as carbon-aware computing. Additionally, server requests for generative AI tasks, like ChatGPT searches, can potentially be routed through systems powered by low-carbon electricity. Although this may add only a few milliseconds of latency, it could substantially reduce emissions from computing operations.
3. Select Appropriately-Sized Models
Not all generative AI tasks, like ChatGPT queries, are equal in terms of energy demand. Leading AI companies are increasingly focusing on using smaller, more efficient AI models to perform these tasks, achieving nearly equivalent quality for far less energy consumption. A notable recent test of that idea came in January 2025, when China's DeepSeek released a model with competitive performance that was trained using less powerful chips and far fewer computing hours than its established rivals. Similarly, many AI applications, such as digital twinning and satellite-based pattern recognition, consume far less electricity than generative LLMs, because of their specialized, relatively efficient models. This can even save energy compared to non-AI approaches: for example, some of the most advanced AI-driven weather prediction models require far less energy than traditional weather simulations, running on a laptop rather than a supercomputer.
4. Address Fugitive Methane Emissions
As data center operators increasingly plan on using natural gas for new electricity supply, reducing upstream emissions from gas production and transmission will be crucial. In the U.S., the Environmental Protection Agency (EPA) 2024 Methane Rule was designed to cut these non-carbon dioxide greenhouse gas emissions by approximately 80%. However, Congress repealed the rule's methane fee in 2025 and barred the EPA from collecting it until 2034. The EPA has since extended compliance deadlines and loosened flare and vent-gas requirements, with litigation over those changes still ongoing. Meanwhile, tools from companies like Kayrros and organizations like Carbon Mapper help detect methane leaks and attribute them to specific operators. The best actors in the industry emit minimal methane, less than 0.5% of what is produced. This standard is achievable for nearly all gas producers.
5. Use Carbon Capture on Power Plants
For both new and existing natural gas-fired power plants, carbon capture and storage technology offers the potential for generating firm, low-carbon power. While many plants currently in operation continue to emit unchecked, this doesn't have to be the case: their emissions can be captured and securely stored geologically. Hyperscalers and project developers should pursue new investments and business models for CCS to reduce existing emissions by 95% or more. For new generation projects, options like NetPower, Arbor, and CES will soon enable emissions abatement of 100%, or even more if combined with biopower to deliver carbon dioxide removal as well. Achieving this will require the development of carbon dioxide pipelines, barges, and storage facilities, which face their own challenges, such as permitting and community approval, that must be addressed directly.
6. Add More Zero-Carbon Power to the Grid
Roughly 8,200 solar, wind, and battery projects in the U.S. are seeking grid interconnection. By the end of 2025, the interconnection queue held roughly 2,060 GW of proposed generation and storage across thousands of projects, and its composition shifted meaningfully. Solar, wind, and storage volumes in the queue all declined year over year (although remained at high absolute levels) while natural gas capacity in the queue grew by 86%. Our blog post, The $5.5 Billion-Dollar Case for Enabling Data Center Load Flexibility, covers one way hyperscalers are working around the wait rather than simply enduring it. These delays need to be addressed, and permitting reform remains an unresolved, live debate. The Manchin-Barrasso bill, which once looked likely to pass, was tabled in December 2024 and never became law. As of 2026, no comprehensive federal permitting law has replaced it. One potential innovation is to use AI to accelerate the development of power flow models and streamline the paperwork required to complete the regulatory process.
7. Invest in Low-Carbon Building Materials
While wood is a promising low-carbon building material, we'll also need glass, concrete, steel, aluminum, and computer chips with minimal embodied carbon emissions. Hyperscalers currently face significant challenges accessing low-carbon versions of these materials, which will eventually be produced using low-carbon hydrogen, carbon capture and storage, and low-carbon electricity. However, these systems require significant investment, workforce development, and permitting to be built. Without these advancements, the embodied emissions from data centers will increase rapidly and significantly in the US, Europe, and globally.
8. Increase Carbon Dioxide Removals
It's already clear that AI applications at data centers will generate emissions from electricity use and embodied carbon that cannot be avoided in the near term. Estimates of current greenhouse gas emissions exceed 300 million tons per year and are likely to grow this decade. These emissions should be measured using full life-cycle analysis and then offset through high-quality carbon removal projects, preferably those with high durability.
To effectively reduce the environmental impact of AI, all eight strategies discussed must prioritize the communities most affected: frontline communities near new infrastructure, consumers facing price increases, and tribal authorities with limited legal protections. Our own research on community opposition to AI data centers found that transparency, not cost or environmental impact alone, is the dominant driver of pushback across 46 stalled or blocked projects. We explore this concern further in our blog, Who Pays for the AI? The Hidden Costs of Rising Data Center Demand, including how ratepayers, not just data center operators, often absorb the cost of new grid infrastructure. Planning should begin by understanding the needs of these communities, ensuring that efforts focus on minimizing harm while maximizing benefits. Equity and justice must be embedded in every stage of planning, production, and permitting across all strategies.
AI's Power Demand Is Indicative of Broader Electricity Demand
AI is just one part of a broader trend of rapidly growing electricity demands, including from electric vehicles, heat pumps, industrial electrification, green hydrogen, and various e-fuels. The challenges AI presents to hyperscalers, communities, regulators, and investors serve as a preview of the complex, far-reaching impacts emerging in other sectors. The same questions keep recurring. Who secures reliable, affordable power fast enough? Who ends up carrying the cost and emissions burden of getting there the wrong way?
Managing AI's power demand will require building the technology architecture, clean firm power supply, and materials strategy to meet that demand deliberately, rather than reactively. AI's carbon footprint underscores the critical need for expertise in clean electricity, grid management, decarbonization, and carbon removal—expertise that will become increasingly vital as more companies realize the complexity and cost of the journey ahead.
Fortunately, AI itself can be part of the solution. With applications in grid management, material science, and advanced manufacturing, AI has the potential to play a powerful role in the climate response.
Read the full 2025 report: ICEF Sustainable Data Centers.
Frequently Asked Questions
How much electricity do AI data centers actually use?
AI-specific computation likely accounts for around 0.04% of global electricity use today, but data centers overall (most of it non-AI computation) used about 1.5% of global electricity in 2024. In the US, which hosts roughly half the world's data centers, Lawrence Berkeley National Laboratory puts current usage at 4% of US electricity, projected to reach 9.5-15.3% by 2030 as AI-specific demand grows.
Will more efficient AI models like DeepSeek reduce data center energy demand?
Not necessarily. DeepSeek's 2025 debut showed that competitive models can be trained with less powerful chips and fewer computing hours, but whether that translates into lower total energy demand is contested. Historically, efficiency gains in computing have tended to get absorbed by increased usage rather than reducing total consumption, so the honest answer is that it depends on whether demand growth outpaces the efficiency gained.
What is being done about the embodied emissions from building AI data centers?
Embodied emissions, from concrete, steel, and IT hardware, can account for one-third to two-thirds of a data center's lifetime emissions. Strategies include using lower-carbon materials like wood where feasible, developing low-carbon concrete, steel, and chips, and standardizing emissions disclosures for building materials so operators can compare and choose lower-footprint options.
Scope 2 Emissions Explained: Tracking, Reporting, and Reducing Impact
Key Takeaways
- Scope 2 emissions (indirect emissions from energy use) are increasingly critical to address. With surging electricity demand, especially from data centers, scope 2 is a growing share of corporate emissions and a priority for decarbonization.
- Approaches to scope 2 accounting are evolving—and formal changes are now on the table. Both location-based and market-based methods remain accepted under the Greenhouse Gas Protocol. Still, the Protocol's recently closed public consultation proposes more granular approaches, including 24/7 power and carbon matching, that would better reflect the realities of modern power markets.
- Proven decarbonization levers, such as reducing energy use, entering power purchase agreements, procuring green tariffs, and buying high-quality renewable energy certificates, are already available and impactful. Decarbonization, not just measurement, must be the goal. Companies don’t need to wait to decarbonize.
Accounting for Indirect Emissions From Energy Use
As businesses and organizations strive to reduce their environmental impact, carbon accounting has become an essential tool for tracking and managing greenhouse gas (GHG) emissions. Carbon accounting helps organizations measure, report, and mitigate their emissions across various activities. A key framework for categorizing these emissions is the Greenhouse Gas Protocol (GHG Protocol), which classifies emissions into three scopes:
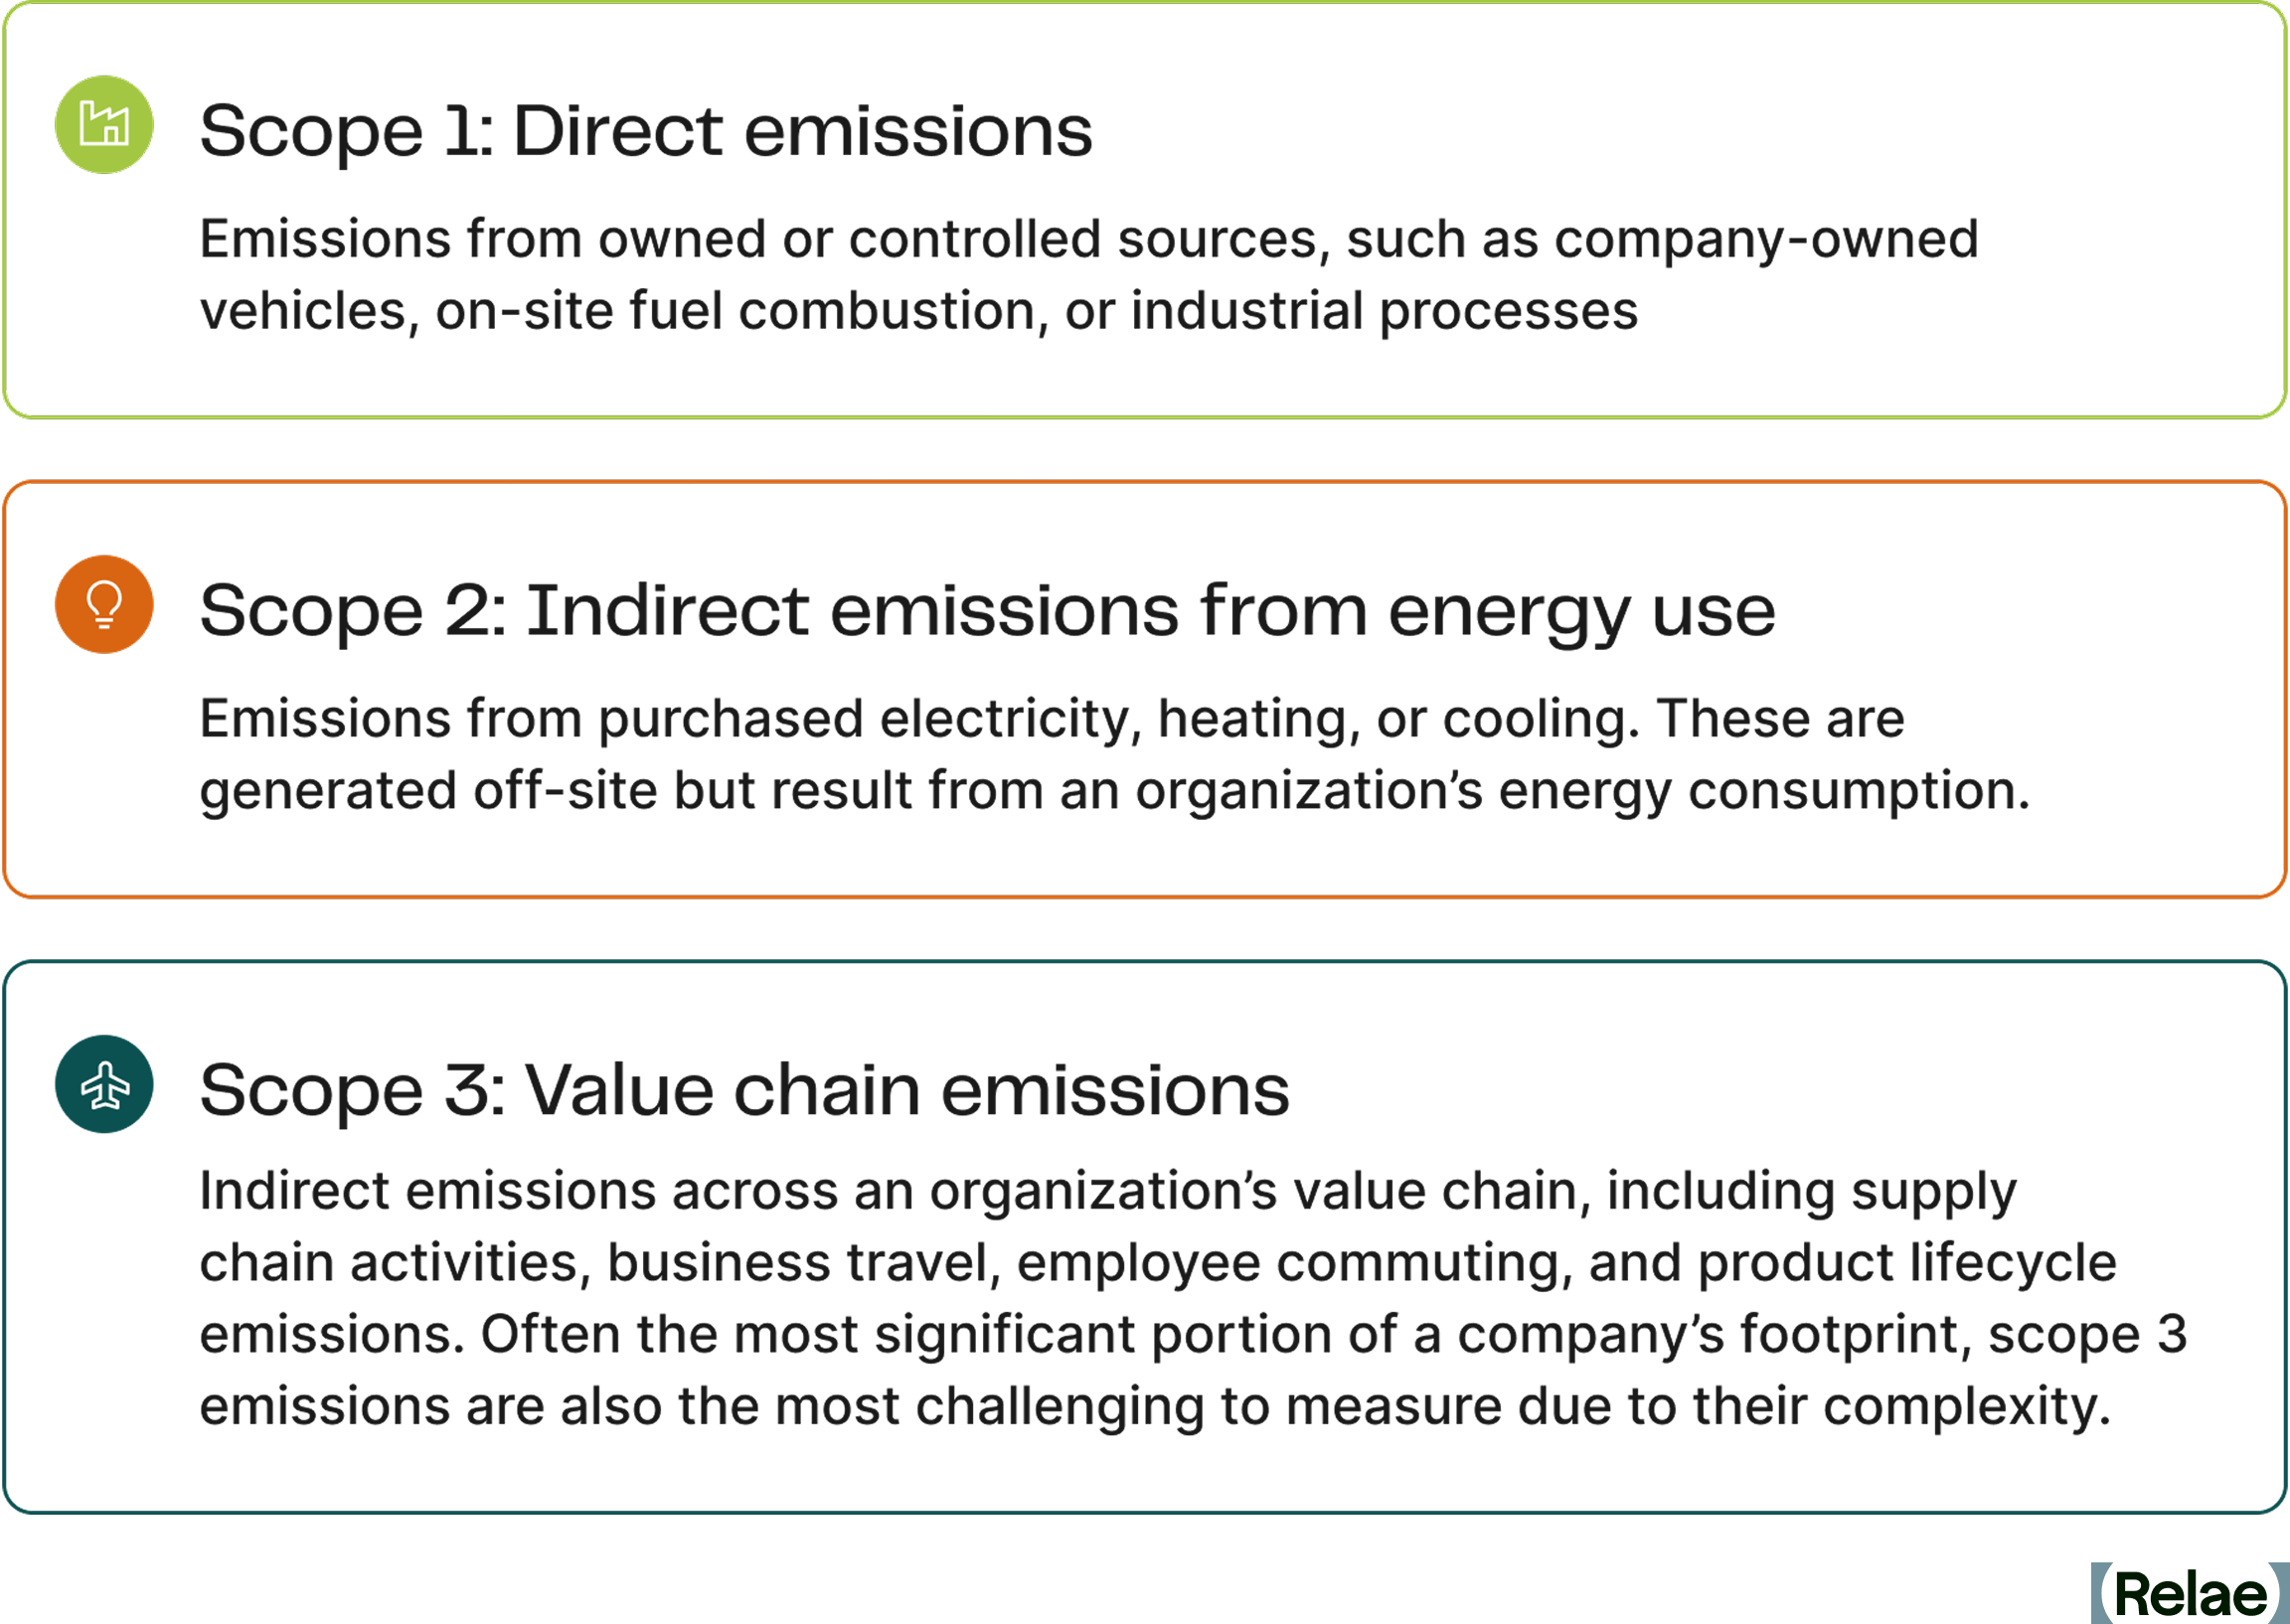
Each scope presents unique challenges and opportunities for reduction. Among them, scope 2 emissions are particularly significant because they stem from purchased energy, which is often generated using fossil fuels. However, numerous reduction mechanisms exist today to help organizations eliminate these emissions, such as improving energy efficiency in order to use less energy, and transitioning to renewable energy sources through market-based mechanisms. Understanding scope 2 emissions is crucial for businesses looking to contribute meaningfully to the global energy transition and achieve sustainability goals.
What Are Scope 2 Emissions?
Scope 2 emissions refer to indirect GHG emissions associated with the consumption of purchased energy. Unlike scope 1 emissions, which result from direct fuel combustion, scope 2 emissions arise from the generation of electricity, steam, heat, or cooling that a company procures from external sources.
The primary sources of scope 2 emissions include:
Purchased electricity: When businesses buy electricity from a utility provider, the emissions from power plants that generate this electricity are classified under scope 2.
Purchased heat, steam, and cooling: Some companies purchase heat, steam, or cooling services instead of generating them on-site. These services often come from centralized facilities that may rely on fossil fuels, thereby contributing to scope 2 emissions.
What sets scope 2 emissions apart from other scopes is the presence of market-based mechanisms that offer multiple pathways for organizations to reduce their carbon footprint. Unlike scope 1, where emissions reductions often require technological shifts or operational changes, scope 2 reductions can be achieved through strategic procurement decisions. The transition to renewable energy sources is an essential component of sustainability strategies, setting the stage for a broader energy transition across industries and economies.
How Are Scope 2 Emissions Measured Today?
The GHG Protocol currently outlines two primary approaches for calculating scope 2 emissions: the location-based method and the market-based method.
Location-Based Method
The location-based method calculates emissions for electricity consumption based on the average emissions intensity of the grid where the energy consumption occurs. This approach is mandatory under various reporting frameworks and does not take into account a company’s procurement choices.
- Relies on grid averages: Emissions are calculated based on regional grid emissions factors rather than specific energy purchases.
- Time-delayed data: Since grid emissions factors are typically updated annually, this method may not reflect real-time energy sourcing changes.
- Limited control: Companies using this method have less direct influence over their reported emissions, as they depend on the overall energy mix of their region.
Market-Based Method
The market-based method, on the other hand, reflects an organization’s actual procurement decisions and energy-sourcing strategies. It accounts for specific contracts, such as power purchase agreements (PPAs), renewable energy credits (RECs), and green tariffs, which allow businesses to claim lower emissions from their purchased electricity.
- Reflects company choices: Emissions calculations take into account contractual agreements for renewable energy purchases.
- Mechanism for electricity transition: Encourages organizations to invest in low-carbon electricity options and actively support the transition to renewables.
- Multiple reduction options: Companies can reduce their scope 2 emissions through a portfolio of mechanisms like PPAs, RECs, and green tariffs, making this method a flexible and strategic tool for decarbonization.
While market-based mechanisms provide flexibility in reducing scope 2 emissions, they also highlight the need for more precise and updated carbon accounting methodologies. For example, some decarbonization strategies, such as time-shifting energy consumption to better match renewable generation, are not accounted for under these methods. This and other limitations mean that the traditional methods outlined in the GHG Protocol are increasingly seen as outdated in an era of rapid changes in energy generation and grid dynamics. As a result, the market is shifting toward more advanced power emission accounting methodologies that provide a more accurate reflection of emissions associated with electricity use.
Proposed Changes to the GHG Protocol Scope 2 Guidance
The current GHG Protocol Scope 2 Guidance provides a market-based instrument methodology, originally designed in the early 2000s, that allows US-based companies to procure renewable energy at any point within a year from anywhere in North America and apply it to any of its annual electricity consumption within that same year. This methodology, as written, allows for a potentially significant mismatch of “emissions caused” (by consuming electricity) versus “emissions avoided” (by generating renewable electricity) in that it does not account for any of the realities of electric grids and generators, which vary significantly over different regions, seasons, and time of day.
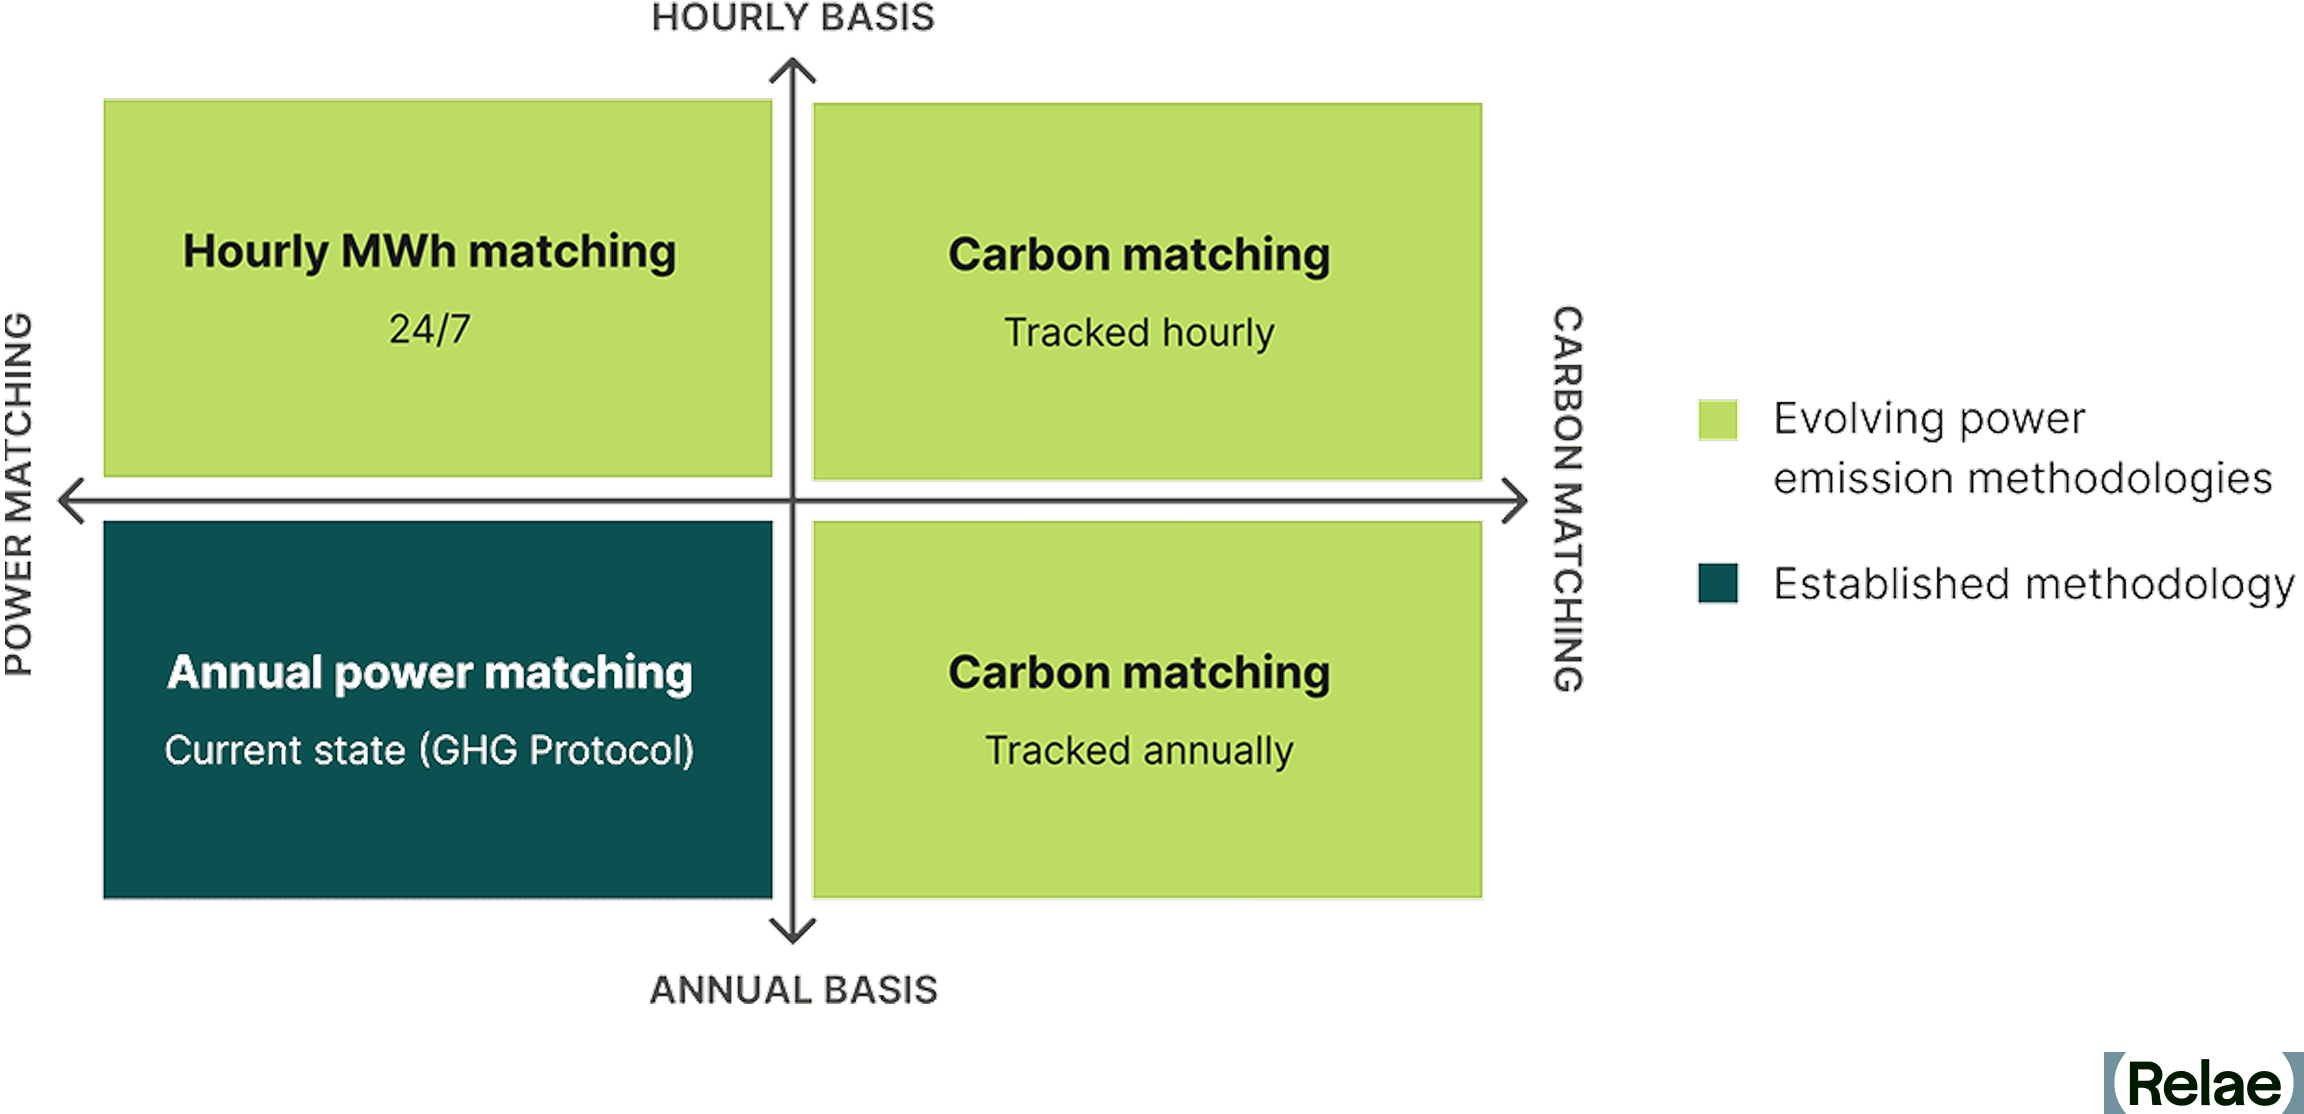
In response to this, the GHG Protocol Scope 2 Guidance is currently undergoing a revision process, which will include how emissions associated with electricity consumption are calculated. A focus of the revision process is on how to better account for the real emissions associated with a corporate’s electricity consumption, and more impactful ways of mitigating them through market-based instruments and other approaches. Advanced power emission accounting methodologies, such as 24/7 power matching and carbon matching, are being explored as ways to better represent the GHG emissions associated with electricity consumption.
- 24/7 power matching emphasizes matching electricity consumption with an equivalent amount of renewable energy production on an hourly basis.
- Carbon matching emphasizes measuring the emissions impact of incremental electricity consumption or production at a specific time.
These emerging methodologies propose a shift toward more granular temporal and region-specific matching, which could require companies to rethink their emissions reporting approach and explore more advanced tracking tools. They may also introduce new strategies beyond market-based instruments for reducing scope 2 emissions, such as time-shifting energy consumption.
As power grids continue to decarbonize and new digital tools emerge, businesses will need to adapt to these evolving methodologies to remain compliant, enhance sustainability strategies, and achieve meaningful reductions in emissions. Companies that proactively integrate advanced power emission tracking into their carbon accounting strategies will be better positioned to lead in the transition to a low-carbon economy.
How to Reduce Scope 2 Emissions
The GHG Protocol provides multiple mechanisms for reducing scope 2 emissions, allowing organizations to shift their energy consumption toward lower-carbon alternatives. These include:
- Reducing energy consumption: Improving energy efficiency in operations can significantly lower electricity use. In some cases, this involves capital investments in more energy-efficient equipment, but in other cases, it can be based on operational changes such as reducing unnecessary lighting, HVAC, and other services during non-working hours. (Electrification efforts, such as shifting from fossil fuel-powered systems to electric alternatives, may actually increase scope 2 emissions, but this can ultimately reduce overall emissions by correspondingly decreasing scope 1 emissions and allowing for renewable energy procurement.)
- RECs: Companies can purchase unbundled RECs (emissions “attributes” separated from the actual electricity product) to offset emissions associated with purchased electricity. While there has been criticism of RECs due to their significant range in quality, high-quality RECs are available, which may include ensuring regional matching, financial additionality, on-line date additionality, or tighter temporal generation to consumption matching. The use of high-quality unbundled RECs is the most accessible and realistic option for most smaller-scale companies to address scope 2 emissions.
- On-site generation and co-location: Installing on-site renewable energy generation, such as solar panels, allows companies to directly offset their electricity consumption from the grid. In some commercial settings, such as companies using leased real estate or co-located data centers, partnering with facilities that prioritize renewable energy procurement can help reduce scope 2 emissions for the facility owner while the facility occupant reduces scope 3 emissions.
- PPAs: Entering into long-term contracts with renewable energy providers ensures companies receive electricity from clean energy sources while supporting the expansion of renewable generation capacity. PPAs are available with standardized contract terms, and some service providers will aggregate demand from multiple smaller companies to reach the minimum required amount for typical PPA contracts. Hedging products are also available to reduce market risks.
- Green tariffs: Many utilities offer green tariffs that enable businesses to purchase renewable energy directly through their electricity provider, often at a premium but with lower emissions impact. For many smaller companies, this is a more viable approach than a PPA with a single renewable generator.
By adopting a combination of these strategies, businesses can significantly lower their scope 2 emissions while aligning with broader sustainability goals and regulatory requirements. The path to decarbonization requires proactive investment in cleaner energy sources, efficient consumption practices, and leveraging market-based instruments to drive the transition toward a low-carbon future.
Why Does Reducing Scope 2 Emissions Matter?
Reducing scope 2 emissions is the underpinning of decarbonizing the power sector and enabling the global energy transition. In 2025, S&P reported that corporate buyers added 15.2 GW of renewable capacity in the US, up from 9.1 GW in 2024, illustrating the growing impact of the corporate sector on the electricity grid. Cleaner grids translate to lower emissions for all energy users. Organizations that actively reduce their scope 2 emissions can contribute to decreasing demand for fossil fuel-based electricity and accelerate the deployment of renewable energy infrastructure.
For companies that own and operate data centers, this transition is especially important. AI data centers consume large amounts of electricity, and their reliance on purchased power makes them a significant source of scope 2 emissions. Since many businesses rely on third-party data center services, reducing emissions from these facilities also helps lower scope 3 emissions across industries. Corporates can influence data centers by requiring that they have a clear and explicit low-emission power strategy in place before procurement.
Beyond direct corporate benefits, reducing scope 2 emissions has a tangible long-term impact on power grids. Increased investment in renewable energy procurement sends a strong market signal, encouraging utilities and developers to expand clean energy projects. As more companies commit to sourcing renewable energy, the overall mix of grid power shifts, making low-carbon electricity more accessible and reducing reliance on fossil fuel-based generation. Ultimately, widespread corporate action in scope 2 emissions reduction supports the broader decarbonization of power markets and strengthens global climate commitments.
Frequently Asked Questions
Will RECs (renewable energy certificates) still count toward scope 2 reductions under the GHG Protocol's proposed changes?
Under the current Scope 2 Guidance, yes—RECs remain a valid market-based instrument. The proposals from the GHG Protocol's recent consultation range from retaining market-based accounting with stricter quality criteria to restructuring how instrument-based claims are reported altogether, and nothing is final until the revised standard is published. What's clear is that scrutiny is rising, particularly for unbundled RECs with weak temporal or geographic connection to a company's actual consumption, so prioritizing high-quality RECs now is the best way to future-proof a procurement strategy.
How would the proposed hourly and regional matching requirements affect companies that rely on unbundled RECs today?
Hourly (24/7) and regional matching would require renewable generation claims to line up much more closely with when and where a company actually consumes electricity. Companies relying on annually matched, unbundled RECs sourced from distant grids would likely see their reported market-based emissions rise under such requirements. The practical preparation is to start collecting more granular (ideally hourly) consumption data and shift toward RECs and contracts with tighter regional and temporal matching.
What's the practical difference between location-based and market-based scope 2 accounting, and will that distinction survive the GHG Protocol's revision?
The location-based method calculates emissions using the average emissions intensity of the local grid, regardless of procurement choices, while the market-based method reflects a company's actual contracts, such as PPAs, RECs, and green tariffs. The consultation explored options from strengthening the criteria for market-based claims to reporting emissions and market instruments in separate, complementary statements. Both concepts will exist in some form, but companies should expect the requirements behind market-based claims to tighten.
When is the new Scope 2 Guidance expected to take effect, and what should companies do now to prepare?
Per the GHG Protocol's July 2026 development plan, a draft of the revised consolidated Corporate Standard is expected for public consultation in 2027, with a final published standard currently estimated for late 2028, and adoption timelines will follow publication. Companies should take action now. Energy efficiency, PPAs, green tariffs, and high-quality RECs reduce real emissions under any accounting regime. Building hourly consumption tracking and auditing the quality of existing REC portfolios now will make any future transition smoother.