GHG Protocol Releases New Land Sector and Removals Standard
Key Takeaways
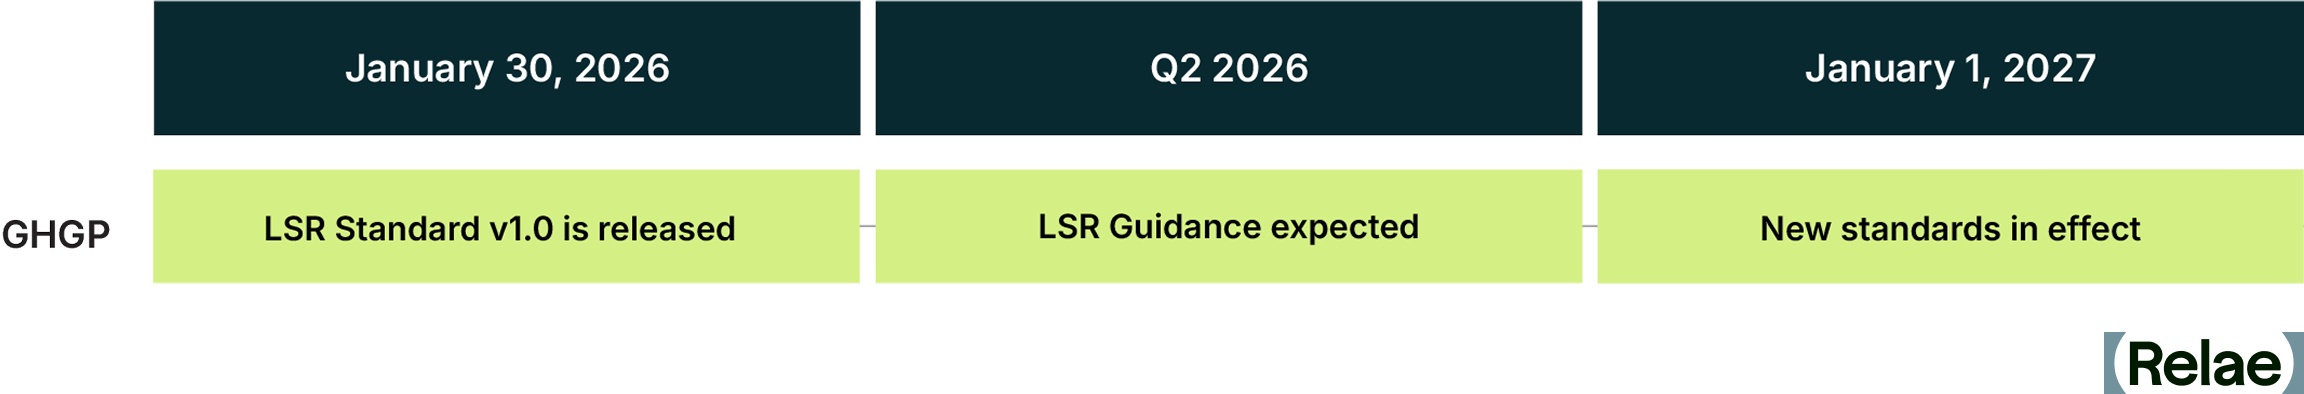
- On January 30, 2026, the Greenhouse Gas Protocol (GHG Protocol) released its long-awaited Land Sector and Removals (LSR) Standard v1.0 following a 5-year consultation process. The LSR Standard is set to take effect on January 1, 2027.
- The release of the LSR Standard represents a notable development for companies in the food and agriculture sector looking to report on land-based GHG emissions in their annual GHG inventory, as well as companies that plan to report on carbon dioxide removals (both land-based and technological).
- The accompanying Land Sector and Removals Guidance, which will provide further direction on operationalizing and implementing the LSR Standard, is expected in Q2 of 2026. However, companies with significant land-based activities may want to begin assessing the impacts of the LSR Standard on their emissions accounting procedures and decarbonization strategies today.
Why the Land Sector and Removals Standard Matters Now
Emissions from agriculture and land use change account for roughly a quarter of global emissions. Yet, for years, food, fiber, and fuel companies have lacked a clear framework for accounting and reporting on GHG emissions and carbon dioxide removals from land use. This has significantly limited their ability to demonstrate progress toward climate targets within their operations and value chain. The GHG Protocol’s Land Sector and Removals (LSR) Standard, which was released on January 30, 2026, changes that, and in doing so raises a new set of questions.
The LSR Standard provides greater clarity on what is required of companies to transparently track and report against their emissions reduction and removal targets, and opens new pathways to report on supply chain decarbonization interventions. It also represents an important advancement for companies seeking to report on carbon dioxide removals within their emissions inventory, including both land management removals and technological removals with geologic storage.
While the LSR Standard contains notable new requirements compared to the draft released in 2022, companies still face a number of open questions related to implementation and the implications for their decarbonization strategies.
The GHG Protocol’s accompanying Land Sector and Removals Guidance, scheduled for Q2 2026, is expected to offer more practical direction for implementing the LSR Standard. However, companies with significant land-based activities that require sufficient lead time to prepare should consider assessing the impacts today.
Below, we provide an overview of the LSR Standard, key changes from the 2022 draft, and actionable next steps for food, fiber, and fuel companies considering the impacts on their target-setting and emissions reporting.
What Is the Land Sector and Removals Standard?
The LSR Standard, taking effect on January 1, 2027, sets requirements and recommendations for corporate GHG accounting that cover emissions and carbon removals from agricultural and land use activities. It builds on existing GHG Protocol standards for corporate carbon accounting. Notably, the LSR Standard does not cover the forestry sector, a key break from the 2022 draft. Forest carbon accounting guidance remains under development and will be the subject of a stakeholder consultation/request for information process expected later in 2026.
Land Sector and Removals Standard vs Land Sector and Removals Guidance
The LSR Standard establishes the core requirements companies must follow, while the accompanying Land Sector and Removals Guidance, expected in Q2 of 2026, will provide more detailed implementation support. In short, the LSR Standard sets the "what" while the Land Sector and Removals Guidance will explain the "how," helping companies put those requirements into practice.
Who Should Be Using the Land Sector and Removals Standard?
The LSR Standard applies to two groups of companies:
- Any company with significant1 land-sector activities within its own operations or value chain (most notably the food, feed, fiber, biofuel, and advanced biomaterials sector).
- Any company looking to report on carbon dioxide removals within their scope 1 and scope 3 inventories (including both land management removals or technological removals).
Land management carbon dioxide removals include those from carbon sequestration through farming practices, agroforestry, or silvopastural systems on productive agricultural land. Technological carbon dioxide removals, by contrast, refer to more engineered approaches such as direct air carbon capture and storage (DACCS) or bioenergy carbon capture and storage (BECCS).
What Changed From the 2022 Draft?
Among other provisions, the LSR Standard contains notable breaks from the 2022 draft, including specific changes related to traceability, carbon dioxide removals, leakage, and land use change.
Traceability: A New Approach
Under the LSR Standard, companies that account for scope 3 emissions, removals, and other metrics must apply a spatial boundary. This boundary is determined by the level of traceability they can establish to known lands or regions (from least to most granular): global, jurisdictional (e.g., country), sourcing region (e.g., supply shed), land management unit (LMU) (e.g., farm), or harvested area. For more granular spatial boundaries, such as sourcing region and LMU, companies are required to establish physical traceability, which can be demonstrated through various chain of custody models.
The LSR Standard defines sourcing regions as predefined, spatially-explicit land areas that supply a raw material to its first point of aggregation or first processing facility in the value chain. The GHG Protocol allows some flexibility in how these boundaries are drawn. They can be defined at a tier of the value chain that includes multiple first points of aggregation or first processing facilities whose supply areas overlap.
Alongside higher integrity chain of custody models such as identity preserved, segregated, and controlled blending, the LSR Standard opens to mass balance as a chain of custody model that can be used to demonstrate physical traceability at the sourcing region-level with appropriate safeguards.
This is notable because mass balance is the most common chain of custody model for large volume agricultural commodities, and physical traceability is required to report removals according to the LSR standard. While challenges for reporting removals at sourcing region spatial boundaries still exist, this change unlocks new opportunities to decarbonize commodities and report removals within non-segregated supply chains through insetting programs.
Carbon Dioxide Removals: Clarity on Spatial Boundaries
The draft LSR Standard introduces key principles for companies choosing to report land management carbon dioxide removals, including traceability, data quality, and permanence. Translating those principles into practice remains challenging given the dynamic nature of agricultural supply chains and limited farm-level traceability.
Among other requirements, the LSR Standard maintains that companies electing to report on removals must do so as a separate accounting category from emissions. They must also identify the specific lands where carbon is stored, and conduct ongoing storage monitoring to detect and report on reversals if and when they occur.
The LSR Standard does, however, resolve one of the more consequential open questions left by the 2022 draft: where companies are to draw the spatial boundary for reporting land management carbon dioxide removals. By formalizing and permitting traceability at the sourcing-region level (with appropriate safeguards), it offers a workable middle ground between farm-level precision and the broader supply chain realities that most food and agricultural companies face.
The LSR Standard also opens to using alternative approaches to traceability, such as impact traceability, which allows companies to trace removals back to the LMU through a pathway that is separate from the physical GHG inventory. This is notable as it provides companies with optionality for recognition of farm-level supply chain investments even when physical traceability cannot be established, and inventory recognition is therefore not feasible.
Land Use and Leakage: Stronger Requirements
Finally, the LSR Standard significantly strengthens land use and economic leakage requirements compared to the 2022 draft. While the draft gave companies flexibility to choose among land-tracking metrics, the LSR Standard mandates that all companies report land occupation for both scope 1 and scope 3 in hectares and quantify land carbon leakage whenever “high leakage risk activities”2 displace food or feed production. This includes companies developing crop-based biofuels and bio-based feedstocks.
Leakage must be quantified using the Carbon Opportunity Cost, a calculation aimed at capturing how much carbon could have been stored in the absence of land management activities.
What Should Companies Do Now?
For entities reporting in accordance with the GHG Protocol’s Corporate Standard and Scope 3 Standard, the new LSR Standard goes into effect on January 1, 2027. However, the GHG Protocol’s Land Sector and Removal Guidance is not set for publication until Q2 2026, leaving many open questions related to implementation amid a short data collection and reporting cycle
In the interim, companies may consider a continuous improvement approach, evolving and improving their internal measurement and reporting mechanisms to enable more granular accounting over time. Companies may also consider running analyses to assess the impact of new requirements on the design and cost of decarbonization strategies, with a specific focus on data collection and monitoring approaches.
Ultimately, while implementation of the LSR Standard may evolve over time, it need not delay action on value chain intervention. Companies that continue investing in supply chain decarbonization are building the data infrastructure, supplier relationships, and operational resilience that yield greater visibility into supply chain risk and drive long-term value, independent of reporting standards.
As the LSR Standard's requirements develop, companies that have already begun assessing their emissions footprint and strengthening supply chain traceability and data quality are likely to be better positioned to align their reporting procedures accordingly.
Natural Capital
Relae helps investors, asset managers, and companies with land and agricultural exposure manage risk related to natural capital, meet evolving disclosure requirements, and evaluate land-based assets and supply chains with greater confidence. We combine ecological, carbon, policy, community impact, and market expertise to translate nature dependencies into financially material decisions.
Ready to Navigate What Comes Next?


Andrea Cecchin, PhD
Andrea Cecchin, PhD
,

Andrea has been a consultant and advisor for national and local governments, industry, research institutions, and NGOs on sustainable production and consumption, environmental policy, and circular economy.
Trained as an interdisciplinary and critical thinker, he has developed a transdisciplinary approach to sustainability through designing and coordinating multi-stakeholder and cross-cutting projects in Europe, South America, and North America.
Andrea has extensive academic experience in circular economy policy and business models, industrial ecology, and life cycle assessment of regenerative agriculture practices. Andrea has been an adjunct faculty member at University of North Dakota, North Dakota State University, and Minnesota State University Moorhead, where he taught introductory courses on sustainability assessment and advanced classes on environmental policy and science. He also co-led the working group “Circular Economy, Zero Waste and Innovation” within the International Sustainable Development Research Society.
Most recently, Andrea led the design and research of metrics for sustainability assessment of supply chains at HowGood, a sustainability intelligence platform for food companies, where he also served as subject matter expert on product carbon accounting, water footprinting, and impact assessment of agricultural practices.
Prometeo Project Scholarship, National Secretary of Higher Education, Science, Technology and Innovation of Ecuador
European Social Fund Scholarship, European Union
Mila Stieglitz-Courtney
Mila Stieglitz-Courtney
,
Mila has professional and academic experience spanning carbon markets, climate-smart agriculture, and net-zero strategy. Prior to joining Relae, Mila worked at Climate Impact Partners, where she conducted strategic research on corporate sustainability and the voluntary carbon market. There she developed a deep understanding of the role of nature-based carbon removal in credible private sector climate strategies. Her work spanned the impacts of regulatory and market initiatives on carbon credit demand and corporate claims, such as Article 6 of the Paris Agreement, the Voluntary Carbon Markets Integrity Initiative (VCMI), and the Science-Based Targets Initiative (SBTi). Before Climate Impact Partners, she worked as a Summer Analyst at Bloomberg New Energy Finance (BNEF), where she conducted client-facing research on the economics and carbon storage potential of regenerative agriculture in the United States. Mila holds an MS in Energy Systems and Data Analytics from University College London and a BA in Economics and Geography from Trinity College Dublin. In her postgraduate degree, her work focused on using machine learning models to forecast global crop yields under different climate scenarios.
Foundation Scholar, Trinity College Dublin
- The Standard does not define “significant.” However, the GHG Protocol notes that “some GHG programs do specify numerical significance exclusion thresholds (e.g., SBTi requires companies to set a Forest, Land, and Agriculture [FLAG] target if their FLAG-related emissions are 20 percent or more of overall emissions across scope 1, 2, and 3)."
- These include the use of food or other agricultural products for non-food, non-feed use (including crop-based biofuels or bio-based feedstocks); changes to land management or use linked to removals that result in a significant reduction in food production; or changes to cropland management practices that result in a significant reduction in crop yields per hectare.
What to Read Next
Carbon Removal, Reduction, and Avoidance Credits Explained
Key Takeaways
- Trust in carbon credits remains low. In part, this is because many mistakenly treat every credit type as interchangeable.
- Reduction, removal, and avoidance credits are verified against fundamentally different baselines, so credit quality must be judged based on type and project specifics, never with one blanket standard.
- The Integrity Council for the Voluntary Carbon Market's Core Carbon Principles now give buyers an independent bar to check against, including 44 methodologies approved across 13 eligible crediting programs, as of August 2026.
- Removal credits still make up only 5–6% of the market, even as compliance-driven demand accelerates, per our 2026 State of the Voluntary Carbon Market report.
Three Types of Carbon Credits: Reduction, Removal, and Avoidance
A carbon credit is a mechanism that allows one party to compensate another for their carbon mitigation activities. Based on their net emissions impact, there are three types of carbon credits: reduction, removal, and avoidance.
- Reduction credits reflect activities that decrease greenhouse gas emissions, compared to prior practices.
- Removal credits reflect activities that remove carbon dioxide already present in the atmosphere and oceans and lock it away for decades, centuries, or millennia.
- Avoidance credits reflect activities that prevent greenhouse gases from being emitted in the first place. For all three types, credits are assessed and issued by measuring or estimating how much carbon is reduced, removed, or avoided as a result of a credit purchase and its associated activities.
While credits are assessed in different ways depending on the type, one of the most important indicators of quality is a project's baseline - the emissions that would be present in a business-as-usual scenario, without action being taken to reduce, remove, or avoid them. Project developers use baselines as a means of comparison to assess the net emissions impact of a project.
- Baselines must be accurately set and data-driven.
- Emissions impacts of a project must be correctly calculated against its baseline.
Reduction, removal, and avoidance projects involve very different activities and, for some types of projects, it may be more challenging to establish an accurate baseline. However, without accurate baselines, climate impacts cannot be reliably determined.
Across the voluntary carbon market, Reduction credits represent roughly 20% of the purchases. Removal credits represent roughly 5% of the purchases. The remainder, roughly 75%, are avoidance credits.
Carbon Reduction Credits
Carbon reduction must drive the majority of our push to net zero, but translating carbon reduction activities into carbon credits that can be purchased is challenging. Examples of activities represented by carbon reduction credits include reducing fossil fuel use by improving fuel efficiency, or programs that reduce the methane that is generated from farms or municipal waste processing.
Reduction credits are measured and quantified against the baseline emissions of an existing technology or process. Some reduction credits are easy to track and measure, such as efficiency investments or destruction of fugitive methane. Other projects are more complex. For example, low-emission cookstove projects in developing regions rely on tracking patterns of cookstove use and quantifying emission factors for various fuel and stove combinations, both of which are hard to do. The result, as studies have shown, sometimes leads to overcrediting in reduction projects.
Superpollutant Credits
One class of reduction credit, superpollutant credits, has garnered recent attention. These credits involve the reduction of non-CO2 greenhouse gases with very strong radiative forcing, such as methane, nitrous oxides, or fluorinated gases like chlorofluorocarbons. These are not a substitute for CO2 removal, but can provide rapid and profound reductions at modest cost. Many different kinds of superpollutants exist in today’s market, worth roughly $60M today. Recent purchases by tech companies and others have highlighted the potential of these reduction credits.
Another class of reduction credit, transition credits, involves the deliberate early closure of emitting assets like coal-fired power plants or heavy manufacturing facilities. Early efforts by governments, banks, and companies around the world under the Just Energy Transition Partnership agreement jump-started transition credits as a concept at COP26. The Kinetic Coalition, in partnership with many groups including Relae, has launched work to bring transition credits to market with several pilot efforts, including closing a coal plant in the Philippines 10 years early.
Carbon Removal Credits
Projects that remove carbon come from a diverse set of solutions, from nature-based solutions like reforestation, to hybrid solutions like biochar, to engineered solutions such as direct air capture and storage. Roughly 5–6% of credits on the voluntary carbon market today are classified as removals, up from roughly 3% a few years ago.
Carbon removal baselines are determined differently depending on whether a project uses an engineered, hybrid, or nature-based solution. For engineered removals, the baseline is zero, because no carbon removal was occurring in the absence of the project. The credited removal will be the difference between the quantity of carbon removed and any emissions that occur to facilitate the removal (determined through a carbon credit life cycle assessment). Baselines for hybrid and nature-based removals can be more challenging. In natural systems, changes in carbon stocks created by removals must be measured and approximated over time, and creditable removals represent the additional carbon removed by the intervention relative to the baseline (e.g., fallow land versus a reforestation project).
Another important consideration for carbon removal credits is project durability, a measure of the likely duration of carbon storage. Stored carbon can re-enter the atmosphere either through deliberate actions (e.g., deforestation) or accidental ones (e.g., wildfires). Nature-based removals are especially vulnerable to being re-released and are usually considered less durable (i.e., stored for less than 50 years). In contrast, engineered solutions offer high durability (i.e., stored for hundreds to thousands of years), and hybrid removals also offer durability periods that are typically longer than those of nature-based removals.
While less durable, nature-based solutions are effective, cost-effective, and widely available today. They made up over 95% of all carbon removal credits issued in 2025. Engineered and hybrid solutions are more expensive and scarce but offer longer durability. Prices of engineered carbon removal are likely to fall with innovation and increased market participation, but are currently much higher than most nature-based credits. With SBTi's finalized Corporate Net-Zero Standard V2.0, this balance is likely to shift. Large companies must now purchase removal credits covering 1–100% of scope 1, scope 2, and scope 3 emissions between 2035 and their net-zero year, with an explicit focus on more durable CO2 removal credits.
Carbon Avoidance Credits
Examples of carbon avoidance include avoiding deforestation that would result in the release of carbon dioxide into the atmosphere or clean energy projects that avoid the release of emissions from burning fossil fuels in possible facilities. This can be confusing, since many avoided credits are called reduction credits, as is the case with projects under the Reducing Emissions from Deforestation and Forest Degradation (REDD+) framework. Avoidance credits make up roughly 75% of certified credits on the voluntary carbon market today - an overwhelming majority - in part due to high availability and low price.
Avoiding emissions is an important goal with numerous environmental, climate, community, and other benefits. Relae works with clients and customers across industries on developing and implementing strategies to avoid emissions within their value chain. However, there are significant challenges with the way that many carbon avoidance credits are created.
- Carbon avoidance credits are based on an estimate of the emissions that might have existed had a project not been funded. Because it is impossible to observe what might have happened in the absence of a project, carbon avoidance estimates are determined by considering historic data and contextual information. Statistical models can be used to create a presumed baseline that represents what would have happened in the absence of the project.
- Because the baseline is not observed in an avoided emissions project, there is uncertainty in calculating the number of carbon credits it produces. If the baseline is not set accurately, a project can overcredit. While the lack of a directly observed and measured baseline means avoidance credits will always have some degree of uncertainty, high-quality avoidance projects present compelling evidence to support their baselines, greatly reducing uncertainty.
New datasets, statistical techniques, and methodologies are providing opportunities for developing avoidance credits with more certainty. Three REDD+ methodologies have now cleared the Integrity Council for the Voluntary Carbon Market (ICVCM) assessment for its Core Carbon Principles (CCPs), a concrete sign that credit quality standards for avoidance projects are maturing.
Defining and Standardizing Quality in the Voluntary Carbon Market
Carbon credits are intended to reduce, remove, or avoid emissions. They pay for an environmental service that must be delivered. Companies working to generate climate benefits through credit purchases must grapple with the differences and uncertainties of credit quality to ensure that the intended benefits are realized.
While high-quality credits exist for all types of projects, a rich understanding of the differences in methodologies, geographies, physics, and ecology is required to identify high-quality projects and understand varied certainty, durability, and risk terms. Identifying high-quality carbon projects demands extensive and project-specific diligence beyond carbon market certification.
Our own diligence work reveals that high-quality projects can be hard to find. Fewer than 10% of the carbon removal projects we assessed for our 2026 State of the Voluntary Carbon Market report met our quality criteria. This diligence work now has an additional, independent backstop. As of August 2026, the ICVCM has approved 44 methodologies across 13 programs, as eligible for its CCP label, including ACR, Gold Standard, and VCS. For buyers, considering projects that are CCP-eligible should be used as a first filter—not a substitute for project-level diligence, but representing a legitimate floor.
While realized emissions impacts may be difficult to prove in some cases, it is important to remember that some projects provide additional co-benefits. REDD+ projects, for example, may have a positive impact on conservation and biodiversity, and cookstove projects may offer clear human health and social welfare benefits. However, these benefits should be assessed separately from carbon reduction, removal, or avoidance benefits.
Frequently Asked Questions
What's the difference between a carbon credit and a carbon offset?
A carbon credit represents one verified tonne of emissions reduced, removed, or avoided. A carbon offset describes how a buyer uses that credit, typically to counterbalance emissions it has not yet accounted for. The credit itself does not change type based on how it's claimed.
Which type of carbon credit—reduction, removal, or avoidance—is highest quality?
No single type is inherently highest quality. Each project, regardless of type, is verified against a defined baseline. Quality depends on how rigorously that specific baseline was set and how well the project meets other quality criteria. Removal credits from engineered sources have the most straightforward baseline (zero), and avoidance credits carry the most baseline uncertainty by design, but these are only one determinant of credit quality.
Do carbon removal credits automatically meet the ICVCM’s Core Carbon Principles?
No. The ICVCM assesses methodologies and programs, not individual projects. If a project uses a methodology that is eligible for the CCP label, this can be a useful floor but is not a guarantee of high quality.
How does SBTi's near-term removal mandate change which credits I should buy now?
SBTi's finalized Corporate Net-Zero Standard V2.0 doesn't require removal purchases until 2035, but it sets the ramp now (i.e., 1% of scope 1, scope 2, and scope 3 emissions in 2035, scaling to 100% by the net-zero year). This means the highest-durability removal supply that is scarcest and most in demand today is the same supply that many companies will need later. The SBTi guidelines are still changing, so buyers and project developers must track them closely.
SBTi Emphasizes Near-Term Carbon Removal in Revised Corporate Standard Draft
Key Takeaways
- Near-term role for carbon removals: The revised Science-Based Targets Initiative (SBTi) Corporate Net Zero Standard (CNZS) v2.0 proposes requiring or recognizing interim carbon dioxide removal (CDR) targets before companies reach net zero. This shift aims to scale up the CDR industry in line with climate science and ensure companies address residual emissions earlier rather than deferring action until their net-zero target year.
- Revised target frameworks and increased accountability: The draft standard introduces key changes, including separate targets for scope 1 and 2 emissions, enhanced scope 3 target-setting guidelines, and the recognition of market-based mechanisms for indirect mitigation of scope 3 emissions. It also requires companies to publicly disclose transition plans and assess implementation progress against targets.
- Potential for stronger action on removals: While the proposed updates are a step forward, the final standard should make near-term CDR targets mandatory rather than optional and should expand to include those for projected scope 3 residual emissions, not just scope 1. Without these stronger mandates, demand for early-stage CDR investments may remain limited, potentially slowing progress toward net-zero goals.
- Companies should prepare now: Businesses should start integrating CDR into their climate strategies now so they are equipped to navigate procurement of high-quality removal credits in the voluntary carbon market. Preparing ahead of the final CNZS v2.0 release will help companies align with science-based decarbonization pathways and demonstrate climate leadership.
What the Latest SBTi Update Means for Corporate Climate Action
On 18 March, 2025, the Science Based Targets Initiative (SBTi) released its draft Corporate Net Zero Standard (CNZS) v2.0, significantly updating its framework for corporate net-zero target setting for the first time since 2021. The draft proposes new approaches for companies to support carbon dioxide removal (CDR) in the transition to net-zero emissions, a move that could help scale the nascent CDR industry.
This release is part of a broader revision, with key proposed updates including:
- Requiring public disclosure of transition plans after companies set targets.
- Separating targets for scope 1 and 2 emissions.
- Enhancing the scope 3 target-setting framework using an impact-based prioritization process.
- Recognizing indirect mitigation (e.g., book-and-claim commodity certificates) for hard-to-trace scope 3 emissions.
- Defining a role for emissions removals in the transition to net zero.
- Providing options to recognize company leadership in beyond value chain mitigation (BVCM).
- Assessing corporate progress against targets to bolster accountability.
While formal recognition of removals in the transition to net zero is a positive step, stronger incentives will be needed in the final CNZS to ensure companies take meaningful early action on CDR. The draft standard is open for the first of two public consultations until 1 June, 2025, with a finalized version expected to launch in 2026.
What Remains the Same From the Current Standard?
SBTi’s framework remains focused on three core requirements for companies:
- Reducing emissions year-on-year to reach an approved science-based target (SBT) by 2050 or earlier.
- Investing in beyond value chain mitigation (BVCM) in the transition to net zero to support near-term global decarbonization efforts.
- Neutralizing remaining emissions from the net-zero year (achieved after at least 90% emissions reductions) and onwards with high-quality, permanent carbon removal.
Carbon credits representing emissions reductions and removals remain ineligible for meeting reduction targets within a company’s value chain (SBTs).
What’s New in CNZS v2.0 for Carbon Removals?
Until now, the SBTi encouraged companies to invest in CDR through mechanisms such as BVCM, but has not proposed requiring removal before their target net-zero year. As a result, organizations had little clarity or incentive to invest in CDR ahead of their net-zero target date, dampening near-term demand for carbon removal and delaying the industry's growth.
The new draft changes this by proposing three options for the V2.0 Standard that address the impact of residual emissions during the transition to net zero:
- Option 1 (requirement): Companies are required to set near- and long-term removal targets, including interim CDR milestones,¹ to address projected residual emissions.
- Option 2 (optional with recognition): Companies can set and receive recognition for removal targets to address projected residual emissions.
- Option 3 (flexibility of mechanism): Companies have the flexibility to address expected residual emissions either entirely through additional emissions reductions within their value chain, entirely through removals, or via a combination of both.
Notably, all three approaches apply only to residual scope 1 emissions.
On top of these approaches, SBTi has suggested two options for the minimum durability threshold of CDR purchases in their draft standard. Removals will either need to follow a ‘like for like’ approach,² where CDR storage must match the atmospheric lifetime of residual emissions, or a gradual transition approach, where carbon storage durability increases over time.
Why Mandating CDR Matters
Mandating near-term CDR reinforces the need for immediate climate action, ensuring that carbon removals complement emissions reductions rather than being deferred until the net-zero target year. The urgency of early CDR investment is clear:
- Limiting global warming to well below 2°C above pre-industrial levels requires removing billions of tonnes (gigatonnes) of carbon dioxide annually by mid-century.
- The CDR industry is in its early stages and requires sustained investment today to scale in time.
- If companies wait until their net-zero year to purchase CDR, the supply of high-quality removal credits is unlikely to be sufficient.
As part of the proposed removal targets in Option 1 (above), the CNZS v2.0 would require companies to gradually increase CDR purchases over time, ramping up to 100% of a company’s projected residual scope 1 emissions in the net-zero target year (<10% of baseline year emissions).³
What More Can Be Done?
The potential introduction of required removal targets would be a significant and welcomed step, reinforcing the importance of near-term CDR investment to support industry maturation and climate goals. However, mandatory near-term CDR targets represent only one of three potential pathways for the V2.0 standard. Moreover, neutralization of residual emissions on the path to net zero is only proposed for scope 1 emissions. While the SBTi provides clear rationale for this,⁴ SBTi should not let the complexity of projecting scope 3 emissions be a barrier to climate change mitigation. Scope 3 emissions represent the majority of emissions from SBTi-aligned companies. Furthermore, companies with high scope 3 emissions typically have a higher ability to pay compared to their industrial counterparts with high scope 1 emissions.
If interim removal targets are made optional, and scope 3 emissions remain excluded, the demand signal for near-term CDR will be limited. The public consultation (and advice of Expert Working Groups that SBTi is convening) will be essential in determining which proposed guidance matures into the final standard; consultation feedback can be provided here prior to June 1, 2025.
How Businesses Can Prepare for CNZS v2.0
Companies aligning with SBTi’s evolving guidance should begin to integrate CDR into their climate strategy now. This means:
- Understanding their residual emissions forecast and planning early investments.
- Developing a company-specific climate strategy to incorporate CDR into their sustainability roadmaps in tandem with plans to reduce value-chain emissions.
- Engaging early in the voluntary carbon market to implement these strategies and develop procurement processes to support high-quality removal projects.
- Ensuring credibility by selecting removal projects aligned with scientific best practices.
Conclusion: A Step in the Right Direction, But More Certainty Is Needed
The CNZS v2.0 draft represents a critical turning point for corporate climate action with options to formalize the role of early CDR investment through interim removal targets for signatories. However, SBTi must take a stronger stance in the final version of the revised standard by choosing to adopt requirements for near-term neutralization (rather than leaving this optional), including projected residual scope 3 emissions in near-term CDR targets, aligning durability requirements with climate science, and defining removal quality standards to ensure these efforts drive meaningful climate impact. Organizations seeking to align with this guidance should prepare by developing a comprehensive climate strategy that accounts for science-based decarbonization pathways and recognizes the role of early-stage investment in CDR solutions.
Independent Project Assurance Is Likely Your Best-Returning Spend
Key Takeaways
- The decision to fund a project is determined by a holistic review of project development maturity. This applies across capital-intensive projects, including low-carbon power generation, carbon capture and storage (CCS) solutions, sustainable aviation fuel (SAF), and broader transition infrastructure build-out. Both technical and commercial workstreams must be developed in parallel to avoid project failure.
- Early scope decisions, such as site selection, core technology selection, and nameplate capacity, are cheap to make but become exponentially disruptive and costly to reverse.
- Independent challenge and verification is tangible evidence of a disciplined, well-managed capital development process.
Bridging the Gap from Announcement to Delivery
Among project developers, a perception often persists: seeking external review signals a project in distress. In capital budgeting discussions, subjecting engineering scope and commercial assumptions to third-party interrogation can be misconstrued as a vote of no confidence in the primary delivery team.
In reality, the reverse is true. Across complex infrastructure, independent challenge is the disciplined stage-gate practice that protects capital by reconciling technical reality with commercial terms before designs are locked.
Independent Challenge Is a Sign of Strength, Not Doubt
Across capital projects, and in particular within emerging low-carbon industrial infrastructure, the gap between announced projects and delivered assets remains stark. Data from the Mission Possible Partnership’s Global Project Tracker reveals that fewer than 17% of announced commercial-scale clean industrial facilities worldwide have reached Final Investment Decision (FID) or commercial operations, leaving more than 800 major decarbonization projects stalled in front-end development.
The causes of developmental paralysis are multifaceted. While macroeconomic interest rate shifts and global supply chain disruptions sit largely outside a developer's control, project definition and developmental discipline remain entirely manageable. Even amid external volatility, a project designed with resilience will have a far greater likelihood of success.
Independent review and assurance directly strengthen a project’s chance of success and overall value. Large global project delivery organizations have applied this discipline for decades by deploying independent teams to evaluate project readiness at every stage gate. For teams lacking a dedicated internal oversight organization, or those deploying first-of-a-kind facilities, third-party independent review provides the necessary rigor to facilitate project success.
Relae’s (formerly Carbon Direct) work with Stockholm Exergi is a clear example: independent assurance helped build funder and regulator confidence in a first-of-a-kind carbon removal facility with no direct precedent to benchmark against.
Why Projects Stall Between Announcement and FID
Low-carbon infrastructure and net-zero industrial projects carry unique risks compared to the repeat delivery of established designs. Exciting new developments run a higher risk of falling victim to optimism bias or compressing development timelines to meet public announcement milestones.
It is a natural human tendency for project champions to focus on the upside during early development. However, early momentum must be balanced with processes that reintroduce industrial lessons, supply-chain realities, and operational resilience.
Front-End Loading (FEL) is a well-evidenced approach for improving capital project outcomes. Decades of benchmarking by Independent Project Analysis (IPA) show that approximately two-thirds of industrial megaprojects suffer capital cost overruns or schedule slippage of 25% or more, or encounter severe operational problems lasting more than two years post-startup. This pattern is repeating in low-carbon infrastructure: IPA’s analysis of 12 completed low-carbon projects found average cost escalation of 31% and schedule slip of almost 50%. Rigorous front-end definition remains the single strongest predictor of whether a project will achieve its cost and schedule targets.
As highlighted in the CDR 2.0: Five Pillars of Successful Project Deployment and Delivery report published by Relae, projects falter when developers push ahead without stress-testing the full delivery framework. Stage gate reviews are the mechanisms that evaluate the total project concept and underlying business case. They are most effective when executed as independent cold-eye evaluations prior to each funding gate, identifying and mitigating vulnerabilities long before final investment decisions are reached.
What Funders Need to See at Each Gate
Different stages of project development rely on distinct capital sources, each requiring specific proof points before deploying funds.
Before FEED Funding: Justifying the Engineering Spend
Front-End Engineering Design (FEED) is a major financial commitment, typically costing between 2% and 4% of total project capital cost. The funders backing this stage are usually the developer’s own balance sheet equity, strategic partners, or public grant programs. Before allocating millions of dollars to detailed engineering, these funders need confidence on the fundamentals:
- A technically sound process concept, confirmed utility balances, and an energy integration scheme that fits the site.
- Secured site control, clear zoning pathways, and no environmental fatal flaws that could derail permitting.
- Documented availability of required feedstocks, water and power, paired with demonstrable interest from target off-takers.
Before FID: Proving Bankability and Commercial Closure
As a project approaches FID, the funding audience shifts to conservative commercial lenders, infrastructure funds, and binding offtake counterparties. These capital providers are not underwriting strategic vision; they are underwriting long-term operational cash flows and debt service. Depending on the project and financing structure, capital providers may require:
- A high-confidence capital cost estimate (AACE Class 2 or Class 3) backed by frozen Piping and Instrumentation Diagrams (P&IDs), firm equipment quotes, and a realistic execution schedule with clear critical paths.
- Bankable engineering, procurement, and construction (EPC) structures that clearly allocate risk, include performance guarantees and enforceable liquidated damages.
- Fully executed, binding offtake and feedstock agreements, along with non-appealable permits and completed utility interconnection agreements, with remaining conditions clearly understood.
- An objective, third-party challenge review that assesses operational viability and distinguishes an executable engineering plan from an aspirational concept.
Commercial and Technical Co-Development: The Stage-Gate Method in Practice
A project rarely fails because of an isolated mechanical issue or a purely commercial misstep; failure happens when technical decisions and commercial terms are negotiated in silos and decisions are made without understanding of the wider implications.
We see this disconnect play out in several ways, including:
- Sizing capacity before testing market demand: An engineering team may size a facility to maximize thermodynamic efficiency and economies of scale, only for the commercial team to discover buyers will only commit to half that volume. The developer is left with an oversized, unbankable design requiring fundamental rework.
- Setting product specifications before negotiating offtake: Process engineers frequently design systems around standard vendor packages. However, when downstream transport, processing, or storage networks enforce strict purity standards, the facility faces costly equipment redesigns. This issue has materialized directly within European CCS networks. Open-access offshore storage operators, such as Norway's Northern Lights project, established strict cross-border CO2 specifications requiring tighter moisture and impurity thresholds than originally designed for.
- Locking Electrical Loads Prior to Interconnection Verification: As detailed in Relae’s analysis of physical infrastructure bottlenecks, scale is rarely constrained by capital availability; it is dictated by electrical transmission queues, substation headroom, and 24/7 firm power availability. Freezing electrical demand before verifying utility interconnection timelines risks stranding engineering work on an asset that cannot connect to the grid.
How Relae Stress Tests Projects at Each Gate
Independent reviews at each stage-gate improve success rates by stress-testing assumptions before presenting to lenders, infrastructure investors, or corporate buyers. Relae reviews projects across five categories using the TECOP framework:
- Technical: Verifying technology readiness levels (TRL), mass and energy balances, plot plan constructability, and operational availability under real-world conditions.
- Economic: Capex benchmarking, operating contingency adequacy, utility tariff sensitivities, and financial model cash-flow resilience.
- Commercial: Offtake agreement structures, feedstock contracts, contracting boundaries, EPC contract structures, and counterparty creditworthiness.
- Organizational: Owner's team capabilities, internal stage-gate governance, contractor oversight mechanisms, and execution capabilities.
- Political: Statutory permitting status, regulatory durability, carbon market policy exposure, and local community social license.
The TECOP framework is relevant for evaluating delivery risk across all project types, see more in Relae’s Criteria for High-Quality Carbon Dioxide Removal, Delivery Risk Appendix.
What makes this approach effective is sitting on both sides of the table. Having completed over 250 deep-dive technology reviews, 900+ project evaluations, and advised on more than $6 billion in industrial project finance, Relae has extensive experience evaluating the considerations important to institutional funders and buyers.
The Value of Early Independent Project AssuranceIncorporating independent review should be standard practice for modern infrastructure delivery. Because funders will perform their own rigorous diligence regardless, conducting an independent evaluation early enables developers to address vulnerabilities proactively and present a more resilient business case.
Commissioning an independent team for a cold-eye review during early project formation can be a cost-effective way to identify potential risks before they become expensive to address. Catching an unworkable process assumption, an oversized capacity plan, or a misaligned commercial interface during pre-FEED costs a tiny fraction of what it takes to fix those issues during construction
Ultimately, independent challenge is not an admission of doubt, but the disciplined stage-gate practice that protects capital by reconciling technical reality with commercial terms before designs are locked, signaling to partners, and your future funders that your project is built to deliver.
To dive deeper into the frameworks that support successful projects, read Relae's white paper: CDR 2.0: Five Pillars of Successful Project Deployment and Delivery and take a look at project assurance in action through our Stockholm Exergi Case Study.
Frequently Asked Questions
What is independent project assurance?
Independent project assurance is a structured review of a capital project by a team that sits outside the project’s delivery organization. Reviewers test the engineering scope, cost estimate, schedule, commercial agreements and permitting position against what funders will require at the next stage gate. The developer receives a clear list of gaps, risks and proposed mitigations prior to presenting the project to lenders, investors or buyers.
When should a developer commission an independent project review?
Periodically throughout the project development process - at a minimum before each major funding gate, but smaller reviews are also beneficial at earlier stages when key concept and technology decisions are being made. A review before Front-End Engineering Design (FEED) tests whether the process concept, site and supply of feedstock, water and power justify the engineering spend. A review before Final Investment Decision (FID) tests whether the cost estimate, EPC structure and binding agreements will satisfy lenders. Site, technology and capacity decisions are cheap to change in pre-FEED and expensive to reverse once detailed engineering starts.
What does an independent project review assess?
Relae structures its reviews around the TECOP framework, which covers five risk areas: technical (technology readiness, mass and energy balances, constructability), economic (capex benchmarking, contingency, financial model resilience), commercial (offtake, feedstock and EPC contracts), organizational (owner’s team capability and stage-gate governance) and political (permitting, regulatory durability and social license). Reviewers also check that technical and commercial decisions are aligned, because projects often fail where the two are developed in silos.
How does an independent project review differ from lender due diligence?
An independent project review applies a holistic approach identifying not only gaps, but also opportunities to add value and strengthen the business case. Lender and investor due diligence is often purely looking at risks and gaps, prior to committing capital. Lender diligence protects the funder and reports its findings at a point when changes are costly and can delay financial close. A developer-commissioned review takes place earlier, so the project team can fix weaknesses in scope, cost or contracts before funders see them.
GHG Protocol Releases New Land Sector and Removals Standard
Key Takeaways
- On January 30, 2026, the Greenhouse Gas Protocol (GHG Protocol) released its long-awaited Land Sector and Removals (LSR) Standard v1.0 following a 5-year consultation process. The LSR Standard is set to take effect on January 1, 2027.
- The release of the LSR Standard represents a notable development for companies in the food and agriculture sector looking to report on land-based GHG emissions in their annual GHG inventory, as well as companies that plan to report on carbon dioxide removals (both land-based and technological).
- The accompanying Land Sector and Removals Guidance, which will provide further direction on operationalizing and implementing the LSR Standard, is expected in Q2 of 2026. However, companies with significant land-based activities may want to begin assessing the impacts of the LSR Standard on their emissions accounting procedures and decarbonization strategies today.
Why the Land Sector and Removals Standard Matters Now
Emissions from agriculture and land use change account for roughly a quarter of global emissions. Yet, for years, food, fiber, and fuel companies have lacked a clear framework for accounting and reporting on GHG emissions and carbon dioxide removals from land use. This has significantly limited their ability to demonstrate progress toward climate targets within their operations and value chain. The GHG Protocol’s Land Sector and Removals (LSR) Standard, which was released on January 30, 2026, changes that, and in doing so raises a new set of questions.
The LSR Standard provides greater clarity on what is required of companies to transparently track and report against their emissions reduction and removal targets, and opens new pathways to report on supply chain decarbonization interventions. It also represents an important advancement for companies seeking to report on carbon dioxide removals within their emissions inventory, including both land management removals and technological removals with geologic storage.
While the LSR Standard contains notable new requirements compared to the draft released in 2022, companies still face a number of open questions related to implementation and the implications for their decarbonization strategies.
The GHG Protocol’s accompanying Land Sector and Removals Guidance, scheduled for Q2 2026, is expected to offer more practical direction for implementing the LSR Standard. However, companies with significant land-based activities that require sufficient lead time to prepare should consider assessing the impacts today.
Below, we provide an overview of the LSR Standard, key changes from the 2022 draft, and actionable next steps for food, fiber, and fuel companies considering the impacts on their target-setting and emissions reporting.
What Is the Land Sector and Removals Standard?
The LSR Standard, taking effect on January 1, 2027, sets requirements and recommendations for corporate GHG accounting that cover emissions and carbon removals from agricultural and land use activities. It builds on existing GHG Protocol standards for corporate carbon accounting. Notably, the LSR Standard does not cover the forestry sector, a key break from the 2022 draft. Forest carbon accounting guidance remains under development and will be the subject of a stakeholder consultation/request for information process expected later in 2026.
Land Sector and Removals Standard vs Land Sector and Removals Guidance
The LSR Standard establishes the core requirements companies must follow, while the accompanying Land Sector and Removals Guidance, expected in Q2 of 2026, will provide more detailed implementation support. In short, the LSR Standard sets the "what" while the Land Sector and Removals Guidance will explain the "how," helping companies put those requirements into practice.
Who Should Be Using the Land Sector and Removals Standard?
The LSR Standard applies to two groups of companies:
- Any company with significant1 land-sector activities within its own operations or value chain (most notably the food, feed, fiber, biofuel, and advanced biomaterials sector).
- Any company looking to report on carbon dioxide removals within their scope 1 and scope 3 inventories (including both land management removals or technological removals).
Land management carbon dioxide removals include those from carbon sequestration through farming practices, agroforestry, or silvopastural systems on productive agricultural land. Technological carbon dioxide removals, by contrast, refer to more engineered approaches such as direct air carbon capture and storage (DACCS) or bioenergy carbon capture and storage (BECCS).
What Changed From the 2022 Draft?
Among other provisions, the LSR Standard contains notable breaks from the 2022 draft, including specific changes related to traceability, carbon dioxide removals, leakage, and land use change.
Traceability: A New Approach
Under the LSR Standard, companies that account for scope 3 emissions, removals, and other metrics must apply a spatial boundary. This boundary is determined by the level of traceability they can establish to known lands or regions (from least to most granular): global, jurisdictional (e.g., country), sourcing region (e.g., supply shed), land management unit (LMU) (e.g., farm), or harvested area. For more granular spatial boundaries, such as sourcing region and LMU, companies are required to establish physical traceability, which can be demonstrated through various chain of custody models.
The LSR Standard defines sourcing regions as predefined, spatially-explicit land areas that supply a raw material to its first point of aggregation or first processing facility in the value chain. The GHG Protocol allows some flexibility in how these boundaries are drawn. They can be defined at a tier of the value chain that includes multiple first points of aggregation or first processing facilities whose supply areas overlap.
Alongside higher integrity chain of custody models such as identity preserved, segregated, and controlled blending, the LSR Standard opens to mass balance as a chain of custody model that can be used to demonstrate physical traceability at the sourcing region-level with appropriate safeguards.
This is notable because mass balance is the most common chain of custody model for large volume agricultural commodities, and physical traceability is required to report removals according to the LSR standard. While challenges for reporting removals at sourcing region spatial boundaries still exist, this change unlocks new opportunities to decarbonize commodities and report removals within non-segregated supply chains through insetting programs.
Carbon Dioxide Removals: Clarity on Spatial Boundaries
The draft LSR Standard introduces key principles for companies choosing to report land management carbon dioxide removals, including traceability, data quality, and permanence. Translating those principles into practice remains challenging given the dynamic nature of agricultural supply chains and limited farm-level traceability.
Among other requirements, the LSR Standard maintains that companies electing to report on removals must do so as a separate accounting category from emissions. They must also identify the specific lands where carbon is stored, and conduct ongoing storage monitoring to detect and report on reversals if and when they occur.
The LSR Standard does, however, resolve one of the more consequential open questions left by the 2022 draft: where companies are to draw the spatial boundary for reporting land management carbon dioxide removals. By formalizing and permitting traceability at the sourcing-region level (with appropriate safeguards), it offers a workable middle ground between farm-level precision and the broader supply chain realities that most food and agricultural companies face.
The LSR Standard also opens to using alternative approaches to traceability, such as impact traceability, which allows companies to trace removals back to the LMU through a pathway that is separate from the physical GHG inventory. This is notable as it provides companies with optionality for recognition of farm-level supply chain investments even when physical traceability cannot be established, and inventory recognition is therefore not feasible.
Land Use and Leakage: Stronger Requirements
Finally, the LSR Standard significantly strengthens land use and economic leakage requirements compared to the 2022 draft. While the draft gave companies flexibility to choose among land-tracking metrics, the LSR Standard mandates that all companies report land occupation for both scope 1 and scope 3 in hectares and quantify land carbon leakage whenever “high leakage risk activities”2 displace food or feed production. This includes companies developing crop-based biofuels and bio-based feedstocks.
Leakage must be quantified using the Carbon Opportunity Cost, a calculation aimed at capturing how much carbon could have been stored in the absence of land management activities.
What Should Companies Do Now?
For entities reporting in accordance with the GHG Protocol’s Corporate Standard and Scope 3 Standard, the new LSR Standard goes into effect on January 1, 2027. However, the GHG Protocol’s Land Sector and Removal Guidance is not set for publication until Q2 2026, leaving many open questions related to implementation amid a short data collection and reporting cycle
In the interim, companies may consider a continuous improvement approach, evolving and improving their internal measurement and reporting mechanisms to enable more granular accounting over time. Companies may also consider running analyses to assess the impact of new requirements on the design and cost of decarbonization strategies, with a specific focus on data collection and monitoring approaches.
Ultimately, while implementation of the LSR Standard may evolve over time, it need not delay action on value chain intervention. Companies that continue investing in supply chain decarbonization are building the data infrastructure, supplier relationships, and operational resilience that yield greater visibility into supply chain risk and drive long-term value, independent of reporting standards.
As the LSR Standard's requirements develop, companies that have already begun assessing their emissions footprint and strengthening supply chain traceability and data quality are likely to be better positioned to align their reporting procedures accordingly.
The Role of Improved Forest Management for Carbon Dioxide Removal
Key Takeaways
- Improved forest management (IFM) increases measurable long-term carbon storage in living trees and durable wood products.
- At the same time, it can provide strong social and ecological co-benefits.
- IFM projects like the ones developed by Weyerhaeuser and the Indigenous community of Petcacab in collaboration with Relae (formerly Carbon Direct) show how IFM practices can align climate goals with social and environmental benefits.
Forests Are Climate Solutions If We Manage Them Wisely
Forests remove carbon dioxide from the atmosphere, but they need to be thoughtfully managed to keep doing so. As buyers look to scale carbon removal, improved forest management (IFM) is gaining traction in the voluntary carbon market (VCM).
IFM focuses on enhancing how existing forests are managed to increase carbon storage over time. It’s a nature-based solution that supports climate outcomes, community livelihoods, and environmental benefits when done well.
This piece explains how IFM works, what makes a project high-quality, and how real-world IFM projects like those developed by Weyerhaeuser and Petcacab in collaboration with Relae (formerly Carbon Direct) are delivering credible results for buyers and local communities alike.
What Is Improved Forest Management?
Improved forest management is a catch-all phrase that describes management techniques that decrease emissions from forests or increase carbon removal and storage. Some management techniques, like transitioning a working forest to a conserved status, decrease emissions from forest harvest and primarily create credits for avoided emissions. Other management techniques, like harvesting forests less frequently, can lead to greater carbon removal and storage over time and create credits for additional carbon removal.
Examples of IFM Practices Include:
- Extending harvest rotations to allow more carbon accumulation
- Reducing the impact of logging on soil and surrounding trees
- Managing fire and pest risks to enhance forest health
- Transitioning some of a forest to conservation status
These strategies help forest carbon stocks grow beyond business-as-usual baselines. In carbon markets, IFM can generate carbon removal or avoided emissions credits, depending on the project's design and carbon accounting methodology.
What Makes a High-Quality IFM Carbon Removal Credit?
Buyers today face increased scrutiny around carbon credit quality. In this context, IFM projects must go beyond basic registry standards to demonstrate climate integrity and social and environmental benefits.
Relae developed the Criteria for High-Quality Carbon Dioxide Removal, an annual report published in collaboration with Microsoft to establish science-backed quality standards. This includes six core principles that define high-quality carbon removal, all of which apply to IFM projects:
- Social harms, benefits, and environmental justice - The extent to which the project prevents new social harms to people and communities, reduces existing harms, and provides meaningful benefits distribution. Since IFM projects take place in communities around the world, benefits will naturally vary from project to project.
- Environmental harms and benefits - The extent to which the project minimizes and mitigates environmental harms, as well as provides environmental benefits. Because IFM projects enhance management practices, environmental co-benefits of high-quality IFM projects are usually substantial.
- Additionality and baselines – Evidence that the project’s carbon removal would not have occurred without carbon finance. Many IFM projects fail to present compelling additionality data and narratives. High-quality projects will be able to identify the actions the project took to increase carbon storage that would not have happened without carbon finance.
- Measurement, monitoring, reporting, and verification (MMRV) – The ability to accurately quantify carbon removal in a repeatable and verifiable way, and to develop a plan for long-term monitoring of the project. IFM projects must have robust forest inventory, growth modeling, and occasional remeasurement to verify the additional carbon storage.
- Durability – The likelihood that removed carbon remains stored over time, with mechanisms in place to mitigate reversal risk. Enhanced management of fire, pests, and disease in IFM projects can enhance forest carbon durability.
- Leakage – Evaluation of whether project activities cause increased emissions elsewhere. If an IFM project substantially reduces timber supply, market demand can drive increased harvesting in other forests, undermining some of the project’s climate benefits. High-quality IFM projects minimize this risk by limiting harvest reductions, and account for any remaining leakage by issuing fewer credits.
Relae uses these criteria as part of our diligence framework when advising buyers evaluating projects and co-developing our own projects.
IFM Projects Delivering Real Impact
Weyerhaeuser: Applying Science at Scale
Weyerhaeuser, one of the largest forest owners in North America, is applying improved forest management practices across over 200,000 acres of working forests.
The IFM projects led by Weyerhaeuser are located in rural areas in the US, with low wildfire risk. These IFM projects sequester carbon by extending harvest rotations and forgoing harvest in established streamside management zones.
Relae supported Weyerhaeuser with hands-on scientific collaboration to confirm that every IFM project met the Criteria for High-Quality Carbon Dioxide Removal.
Why it matters to buyers:
- High-quality climate impact at large scale
- Transition of working forests from traditional management techniques to maximize climate impact
- Responsible forestry practices aligned with SFI® standards
- Rigorous carbon accounting and high-quality project baseline established using historical harvest records
The IFM projects led by Weyerhaeuser are some of the largest in the US today and a model for scaling science-backed forest carbon solutions.
Petcacab: Indigenous-Led Conservation in the Yucatán Peninsula
Located in the communal lands of Petcacab, Mexico, this IFM project is led by Indigenous Mayan ejidatarios—community members who have legal rights to manage the land.
Historically, forests in the ejido have been degraded through unsustainable harvesting and extensive damage from hurricanes. Through carbon finance, they are developing new forest management plans and sustainable forestry models, with revenue reinvested in health, education, and job creation.
“The rainforest for me represents my home, my work, my present, my future. We have a very daring challenge: to transform how we manage our forest, shifting from harvesting and selling timber to conserving it through the sale of carbon credits that support the development of our community.”
— Celso Chan Rivas, Carbon Project General Manager
What makes Petcacab stand out:
- Equitable benefit-sharing and strong Indigenous governance
- Critical habitat protection for endangered species
- Increased additional carbon storage through forest management and reduced land use conversion
- Transparent reporting and verified outcomes
Petcacab is recognized by Relae as a high-quality community IFM project in Mexico, with clear social, environmental, and climate outcomes.
Investing in Forests That Deliver More Than Carbon
Improved forest management is more than a carbon strategy, it’s an investment in ecosystems, communities, and long-term impact. For buyers seeking high-integrity carbon removal with social and environmental co-benefits, IFM projects offer a compelling opportunity.
IFM projects like the ones developed by Weyerhaeuser and Petcacab in collaboration with Relae show what’s possible when forests are managed with science and care. They also reflect what the voluntary carbon market needs more of: quality, transparency, and impact beyond the metric ton.
Key Trends in the 2026 Voluntary Carbon Market
Key Takeaways
- What's happening: The voluntary carbon market (VCM) stalled in 2025, with carbon credit retirements falling 7% despite a 227% surge in corporate climate commitments.
- Why it matters: Over 80% of high-durability carbon removal capacity is at risk of not being realized without additional offtake.
- The implication: For corporate buyers with 2030 climate targets, early movers will define market standards and secure the supply they need, while those who wait risk volatility and constrained access to high-quality credits.
Why the Voluntary Carbon Market Needs Action Now
The voluntary carbon market stands at a crossroads. Credit retirements in 2025 fell far below the billion-tonne-scale projections from earlier in the decade. There is a widening gulf between climate ambition and market action.
The VCM transacts credits that avoid, reduce, or remove emissions. Carbon dioxide removal (CDR), the process of removing and durably storing atmospheric CO₂, remains a small but critical segment, accounting for 5% of credits retired. Limiting overshoot of 1.5°C requires a rapid scale-up of CDR.
However, most organizations with 2030 climate goals have yet to engage in CDR procurement. Without clear market signals today, CDR supply will falter. What's missing isn't capability or knowledge, but the commitment to act. Early movers will define the market in its early stages, while latecomers may face volatility and uncertain supply.
Our latest analysis reveals both troubling trends and clear pathways forward for CDR buyers ready to move from commitment to execution.
[cta]
Five Years of Stagnation: The VCM Falls Short of Projections
For five consecutive years, muted growth and persistent oversupply of poor-quality credits have defined the market. In 2025, credit retirements—a proxy for spot-market demand—reached 157 million metric tonnes (Mt), down 7% from 2024.
This incremental growth is far below what market analysts anticipated earlier in the decade, when several projections expected demand to exceed 1 billion tonnes by 2030.
VCM Credit Trends: Concentrated in Avoidance and Reduction
The VCM has historically been concentrated in avoidance and reduction carbon projects, largely dominated by REDD+, renewable energy, and cookstove credits. 2025 marks the first year a new credit type has dominated, though: projects that reduce emissions of superpollutants now make up roughly 20% of all credits issued in the VCM. Superpollutant issuances increased by about 180% between 2020 and 2025, while retirements grew by roughly 150%.
CDR Remains a Small but Critical VCM Segment
In 2025, CDR credits accounted for only 5% of 2025 retirements, but have a more active forward offtake market—where buyers commit today to purchase credits that will be delivered in the future, providing crucial early-stage financing for projects.
Within the CDR category, high-quality credits are still hard to find. Applying our Criteria for High-Quality Carbon Dioxide Removal, we find that less than 10% of the CDR projects we review meet our high-quality threshold with minimal reservations.
Nature-Based CDR Dominates the Spot Market
Of the all CDR credits issued in the VCM in 2025, 95% originated from nature-based CDR pathways, while 5% represented high-durability CDR pathways such as biochar or bioenergy with carbon capture and storage (BECCS). This distribution reflects the mature role that nature-based CDR projects continue to play in the market, alongside the early stage of durable CDR deployment.
Within nature-based credits, supply and demand dynamics differed significantly between afforestation, reforestation, and revegetation (ARR) and improved forest management (IFM).
- For ARR credits, issuances and retirements have tracked closely at a roughly 1:1 ratio, with issuances remaining flat at around 7–8 Mt annually over the past four years, leaving little inventory available for spot purchasing.
- IFM credits, by contrast, have grown 2.5-fold since 2023, making them one of the largest sources of growth within nature-based credits, though high-quality CDR credits from IFM are in much lower supply.
For buyers, this means ARR credits are increasingly difficult to source on the spot market, while IFM credits are more readily available—though careful diligence is needed to identify high-quality projects.
Nature-based offtakes and commitments have expanded in recent years, with more than 90 Mt of future delivery now contracted or committed. The vast majority of these commitments are concentrated in ARR projects, highlighting both the supply constraints facing ARR today and buyers' foresight in securing the supply they will need in the near future.
High-Durability CDR Is Almost Entirely Forward-Looking
The spot market for high-durability CDR credits represents only 0.3% of activity in the VCM, but important dynamics are beginning to emerge as more high-durability CDR technologies reach the market.
From 2021 to 2025, roughly 80% of high-durability issuances and retirements came from biochar and geologic storage. However, the emergence of large-scale geologic CDR projects is beginning to shift the balance, with individual projects capable of delivering hundreds of thousands of tonnes annually. Early-stage methodologies such as enhanced rock weathering (ERW) and ocean alkalinity enhancement (OAE) issued their first credits in 2025, totaling roughly 12,000 tonnes.
While the spot market for high-durability CDR is growing and diversifying, forward offtake agreements continue to define the landscape. The ratio of high-durability spot retirements to volumes committed through forward offtake is 1:70—meaning for every tonne retired today, 70 tonnes have been committed for future delivery.
Forward Offtake Commitments Are Rising Across CDR Pathways
To date, forward offtake agreements, advanced market commitments (AMC), and large contracted deals with intermediaries cover more than 40 Mt of high-durability CDR, in addition to over 90 Mt of nature-based CDR. These cumulative volumes highlight the increasingly central role of forward purchasing in shaping future supply, particularly for capital-intensive, high-durability pathways.
However, the success of forward offtake strategies depends critically on careful due diligence. Without a rigorous assessment of technological readiness, project viability, and delivery risks, forward commitments risk financing projects that fail to deliver, undermining both individual investments and broader market confidence.
Market Concentration of Forward Offtake Remains High
A small group of companies continues to drive the majority of forward offtake activity. In 2025, Microsoft remained the clear market leader, accounting for roughly 60% of contracted nature-based CDR offtakes and more than 80% of high-durability offtakes with a named buyer announced to date. Other active buyers—including Google, JPMorgan Chase, Equinor, and Amazon—have expanded their commitments, but overall market concentration remains high.
This concentration reveals both opportunity and risk: while anchor buyers are proving the market model works, broader participation is needed to unlock the full scale of CDR deployment required.
Growing Gap Between Climate Ambition and Market Action
Corporate climate targets anchor most current VCM activity: All of the top-10 buyers in the market today participate based on either self-declared commitments or net-zero commitments aligned with the Science Based Targets initiative (SBTi).
Demand forecasts based on these future commitments project that total CDR demand could reach 46-110 Mt by 2030, a ~6-14x growth from today. Yet, how companies decide to implement their targets will ultimately affect the composition of CDR demand within the VCM.
Rather than relying solely on public commitments, we analyzed the behavior of companies that are actively purchasing CDR today. Should today's top buyers follow through on their stated CDR commitments, CDR demand could reach a minimum of 28 Mt by 2030, with 6.5 Mt of demand for high-durability CDR.
However, the discrepancy between observed demand and target-led scenarios shows a persistent gap between what companies say and what they do. SBTi reported a 227% surge in companies setting both near-term and net-zero targets in the 18 months leading up to mid-2025, while carbon credit retirements in the VCM fell 7% in 2025.
Shifting from intention to execution will ultimately determine whether the VCM evolves into a durable, functioning marketplace or stalls short of the scale required for credible, net-zero pathways.
Rising Trends of Greenhushing and Anonymity Obscure CDR Demand
In the broader VCM, 55% of tonnes retired on the spot market over the past three years have been anonymous, and that fraction has been increasing. A similar trend is true of high-durability CDR: nearly 40% of all offtake transactions made in 2025 did not disclose the participating buyer. This buyer behaviour could reflect the often-discussed greenhushing phenomenon.
When anonymous actors dominate, it becomes harder to track demand signals, verify corporate progress, and establish clear integrity benchmarks. This opacity creates systemic risk for the entire market.
Market Growth Tipping Points on the Horizon
Several pivotal events on the horizon could mitigate risk and unlock project development, tipping buyers into action after half a decade of limited market growth:
- Voluntary demand: SBTi's Corporate Net Zero Standard V2.0, published in June 2026, confirms credits still can’t count toward scope 1-3 targets, but introduces a voluntary recognition program starting in 2027 and mandatory removal purchasing for large companies from 2035, starting at 1% of footprint.
- Compliance demand: The UK's Emissions Trading Scheme (ETS) Authority has already committed to integrating carbon removals into the UK ETS by 2028 via an auction model. This is the first confirmed large-scale compliance pathway for CDR credits, though credit-type eligibility is still being worked out.
- Regulatory support: Publication of Article 6.4 methodologies under the Paris Agreement and loosening of CORSIA credit supply bottlenecks could expand eligible supply and boost buyer confidence.
These tipping points in policies, standards, and market structures are advancing with clear timelines, creating conditions to move CDR procurement from hesitation to activation.
CDR Supply Faces Critical Challenges
While buyer inaction poses one threat to market growth, the supply side faces its own critical challenges.
30%–220% More Investment Is Needed in Nature-Based CDR Supply
Nature-based CDR would require a 30%–220% increase in finance to support current corporate targets. Relae (formerly Carbon Direct) has identified US$18 billion in publicly committed funds for nature-based CDR announced from 2018 to 2025. If deployed immediately to generate high-quality CDR, this level of funding could translate into up to 32 Mt per year by 2030 and 290 Mt cumulatively through 2040.
This is sufficient to meet the conservative 28 Mt demand floor from today's active buyers—but falls well short of what would be needed if even a fraction of companies with 2030 targets begin executing on their stated commitments.
80% of High-Durability CDR Projects Are at Risk
The situation is more acute for high-durability CDR. We estimate that over 80% of the total 2030 credit supply pipeline is at risk, due to insufficient project offtake and financing agreements.
Without increased offtake and financing support, we expect that the landscape for capital-intensive, high-durability CDR may consolidate
CDR Buyers Will Determine Which Projects Get Built
The supply-side ecosystem features a sufficient number of high-quality CDR suppliers with the potential to scale. These suppliers face purchasing behavior insufficient to meet buyers' own stated climate goals. In this environment, every CDR procurement decision matters. Companies that delay procurement risk missing their own climate targets while also ceding competitive advantage to early movers who secure the limited supply of high-quality credits.
Five Actions to Strengthen the CDR Market
Buyers and investors can play a critical role in reducing project risk and strengthening the CDR market. Our full report details five essential actions:
- Use purchasing power wisely
- Prioritize project diligence
- Construct bankable contracts
- Support market data transparency and CDR goals
- Undertake project assurance
Each action addresses specific market failures and, when implemented strategically, can significantly improve the likelihood that high-quality CDR projects reach operation and deliver credits as contracted.
With 2030 only four years away, the window for action is rapidly closing. Early movers will secure supply and define market standards, while those who wait risk entering a crowded market with limited access to high-quality credits and escalating prices.
[cta]
Frequently Asked Questions
Why did the voluntary carbon market stall in 2025 despite rising corporate climate commitments?
Retirements fell 7% even as SBTi reported a 227% surge in companies setting near-term and net-zero targets. The gap reflects that most companies with 2030 goals haven't yet moved from setting targets to actually procuring credits.
Is carbon dioxide removal a proven market today, or still emerging?
CDR remains a small segment—about 5% of 2025 retirements—but it has an unusually active forward market, with buyers committing today to volumes delivered years from now. High-durability pathways like biochar and geologic storage are still early-stage relative to nature-based credits.
How does the new SBTi Net-Zero Standard affect corporate carbon credit strategy?
Under the new SBTi Net-Zero Standard, credits still can't be counted toward scope 1, 2, or 3 targets. But it introduces a voluntary recognition program starting in 2027, and requires large companies to begin purchasing carbon removals from 2035, starting at 1% of their footprint.
What should CDR buyers prioritize given current market conditions?
Given how concentrated forward offtake activity is today, buyers should prioritize rigorous project diligence and bankable contract structures over simply committing volume—the 2026 State of the Voluntary Carbon Market report details five recommended actions in more depth.