SBTi Emphasizes Near-Term Carbon Removal in Revised Corporate Standard Draft
The finalized Corporate Net-Zero Standard (CNZS) v2.0, released in 2026, kept early CDR voluntary through a new tiered recognition program, but added a mandatory removal requirement starting in 2035 that ramps up to cover 100% of residual scope 1, 2, and 3 emissions (extending beyond the draft’s scope 1-only focus) by a company’s net-zero year, no later than 2050.
Key Takeaways
- Near-term role for carbon removals: The revised Science-Based Targets Initiative (SBTi) Corporate Net Zero Standard (CNZS) v2.0 proposes requiring or recognizing interim carbon dioxide removal (CDR) targets before companies reach net zero. This shift aims to scale up the CDR industry in line with climate science and ensure companies address residual emissions earlier rather than deferring action until their net-zero target year.
- Revised target frameworks and increased accountability: The draft standard introduces key changes, including separate targets for scope 1 and 2 emissions, enhanced scope 3 target-setting guidelines, and the recognition of market-based mechanisms for indirect mitigation of scope 3 emissions. It also requires companies to publicly disclose transition plans and assess implementation progress against targets.
- Potential for stronger action on removals: While the proposed updates are a step forward, the final standard should make near-term CDR targets mandatory rather than optional and should expand to include those for projected scope 3 residual emissions, not just scope 1. Without these stronger mandates, demand for early-stage CDR investments may remain limited, potentially slowing progress toward net-zero goals.
- Companies should prepare now: Businesses should start integrating CDR into their climate strategies now so they are equipped to navigate procurement of high-quality removal credits in the voluntary carbon market. Preparing ahead of the final CNZS v2.0 release will help companies align with science-based decarbonization pathways and demonstrate climate leadership.
What the Latest SBTi Update Means for Corporate Climate Action
On 18 March, 2025, the Science Based Targets Initiative (SBTi) released its draft Corporate Net Zero Standard (CNZS) v2.0, significantly updating its framework for corporate net-zero target setting for the first time since 2021. The draft proposes new approaches for companies to support carbon dioxide removal (CDR) in the transition to net-zero emissions, a move that could help scale the nascent CDR industry.
This release is part of a broader revision, with key proposed updates including:
- Requiring public disclosure of transition plans after companies set targets.
- Separating targets for scope 1 and 2 emissions.
- Enhancing the scope 3 target-setting framework using an impact-based prioritization process.
- Recognizing indirect mitigation (e.g., book-and-claim commodity certificates) for hard-to-trace scope 3 emissions.
- Defining a role for emissions removals in the transition to net zero.
- Providing options to recognize company leadership in beyond value chain mitigation (BVCM).
- Assessing corporate progress against targets to bolster accountability.
While formal recognition of removals in the transition to net zero is a positive step, stronger incentives will be needed in the final CNZS to ensure companies take meaningful early action on CDR. The draft standard is open for the first of two public consultations until 1 June, 2025, with a finalized version expected to launch in 2026.
What Remains the Same From the Current Standard?
SBTi’s framework remains focused on three core requirements for companies:
- Reducing emissions year-on-year to reach an approved science-based target (SBT) by 2050 or earlier.
- Investing in beyond value chain mitigation (BVCM) in the transition to net zero to support near-term global decarbonization efforts.
- Neutralizing remaining emissions from the net-zero year (achieved after at least 90% emissions reductions) and onwards with high-quality, permanent carbon removal.
Carbon credits representing emissions reductions and removals remain ineligible for meeting reduction targets within a company’s value chain (SBTs).
What’s New in CNZS v2.0 for Carbon Removals?
Until now, the SBTi encouraged companies to invest in CDR through mechanisms such as BVCM, but has not proposed requiring removal before their target net-zero year. As a result, organizations had little clarity or incentive to invest in CDR ahead of their net-zero target date, dampening near-term demand for carbon removal and delaying the industry's growth.
The new draft changes this by proposing three options for the V2.0 Standard that address the impact of residual emissions during the transition to net zero:
- Option 1 (requirement): Companies are required to set near- and long-term removal targets, including interim CDR milestones,¹ to address projected residual emissions.
- Option 2 (optional with recognition): Companies can set and receive recognition for removal targets to address projected residual emissions.
- Option 3 (flexibility of mechanism): Companies have the flexibility to address expected residual emissions either entirely through additional emissions reductions within their value chain, entirely through removals, or via a combination of both.
Notably, all three approaches apply only to residual scope 1 emissions.
On top of these approaches, SBTi has suggested two options for the minimum durability threshold of CDR purchases in their draft standard. Removals will either need to follow a ‘like for like’ approach,² where CDR storage must match the atmospheric lifetime of residual emissions, or a gradual transition approach, where carbon storage durability increases over time.
Why Mandating CDR Matters
Mandating near-term CDR reinforces the need for immediate climate action, ensuring that carbon removals complement emissions reductions rather than being deferred until the net-zero target year. The urgency of early CDR investment is clear:
- Limiting global warming to well below 2°C above pre-industrial levels requires removing billions of tonnes (gigatonnes) of carbon dioxide annually by mid-century.
- The CDR industry is in its early stages and requires sustained investment today to scale in time.
- If companies wait until their net-zero year to purchase CDR, the supply of high-quality removal credits is unlikely to be sufficient.
As part of the proposed removal targets in Option 1 (above), the CNZS v2.0 would require companies to gradually increase CDR purchases over time, ramping up to 100% of a company’s projected residual scope 1 emissions in the net-zero target year (<10% of baseline year emissions).³
What More Can Be Done?
The potential introduction of required removal targets would be a significant and welcomed step, reinforcing the importance of near-term CDR investment to support industry maturation and climate goals. However, mandatory near-term CDR targets represent only one of three potential pathways for the V2.0 standard. Moreover, neutralization of residual emissions on the path to net zero is only proposed for scope 1 emissions. While the SBTi provides clear rationale for this,⁴ SBTi should not let the complexity of projecting scope 3 emissions be a barrier to climate change mitigation. Scope 3 emissions represent the majority of emissions from SBTi-aligned companies. Furthermore, companies with high scope 3 emissions typically have a higher ability to pay compared to their industrial counterparts with high scope 1 emissions.
If interim removal targets are made optional, and scope 3 emissions remain excluded, the demand signal for near-term CDR will be limited. The public consultation (and advice of Expert Working Groups that SBTi is convening) will be essential in determining which proposed guidance matures into the final standard; consultation feedback can be provided here prior to June 1, 2025.
How Businesses Can Prepare for CNZS v2.0
Companies aligning with SBTi’s evolving guidance should begin to integrate CDR into their climate strategy now. This means:
- Understanding their residual emissions forecast and planning early investments.
- Developing a company-specific climate strategy to incorporate CDR into their sustainability roadmaps in tandem with plans to reduce value-chain emissions.
- Engaging early in the voluntary carbon market to implement these strategies and develop procurement processes to support high-quality removal projects.
- Ensuring credibility by selecting removal projects aligned with scientific best practices.
Conclusion: A Step in the Right Direction, But More Certainty Is Needed
The CNZS v2.0 draft represents a critical turning point for corporate climate action with options to formalize the role of early CDR investment through interim removal targets for signatories. However, SBTi must take a stronger stance in the final version of the revised standard by choosing to adopt requirements for near-term neutralization (rather than leaving this optional), including projected residual scope 3 emissions in near-term CDR targets, aligning durability requirements with climate science, and defining removal quality standards to ensure these efforts drive meaningful climate impact. Organizations seeking to align with this guidance should prepare by developing a comprehensive climate strategy that accounts for science-based decarbonization pathways and recognizes the role of early-stage investment in CDR solutions.
Carbon Removal
Relae helps carbon removal buyers, investors, suppliers, and project developers navigate a complex market shaped by evolving science, quality standards, delivery risk, and claims expectations. We combine carbon removal strategy, project-level diligence, and market intelligence informed by work with leading buyers and project developers to help you assess quality, build diversified portfolios, and scale high-integrity carbon removal.
Ready to Navigate What Comes Next?


Meera Atreya, PhD
Meera Atreya, PhD
,

Dr. Atreya has worked in climate technology research and strategic advisory since 2009. She was the lead author of Bioresources within a Net-Zero Emissions Economy, a report by the Energy Transitions Commission evaluating the role of sustainable bioresources in climate change mitigation. While at SYSTEMIQ, a sustainability-focused systems change company, Meera provided strategic advice to a major climate-focused philanthropic foundation and co-authored a report on alleviating the plastic waste crisis; the United Nations Environment Programme is currently using this analysis as the basis for a global plastics treaty. Prior to SYSTEMIQ, Meera was a management consultant at McKinsey & Company, where she was designated as an Affiliate Expert in Renewable Energy & Cleantech and was a key member of the team that steered McKinsey to address its own global carbon emissions.
Meera is based in London and is an advisor to Carbon Gap and former Technical Advisory Group Member of the Science Based Targets Initiative (SBTi). She holds a PhD in Chemistry (Chemical Biology) from UC Berkeley and an A.B. cum laude from Harvard. Dr. Atreya was awarded a US National Science Foundation Graduate Research Fellowship for her doctoral research on engineering enzymes to improve the efficiency, and lower the cost, of converting cellulosic biomass to 2nd-generation biofuels.
Advisor, Science Based Targets Initiative (SBTi) Technical Advisory Group
Science Based Targets Initiative (SBTi) Expert Advisory Group on Beyond Value Chain Mitigation (BVCM)
Carbon Gap Advisory Board
Marble Climate Tech Venture Studio Mentor Programme
Designated Affiliate Expert in Renewable Energy & Cleantech, McKinsey & Company
Social Responsibility Fellow, McKinsey & Company
Graduate Research Fellow, US National Science Foundation (NSF)
Hoopes Thesis Prize Winner, Harvard University
Mila Stieglitz-Courtney
Mila Stieglitz-Courtney
,
Mila has professional and academic experience spanning carbon markets, climate-smart agriculture, and net-zero strategy. Prior to joining Relae, Mila worked at Climate Impact Partners, where she conducted strategic research on corporate sustainability and the voluntary carbon market. There she developed a deep understanding of the role of nature-based carbon removal in credible private sector climate strategies. Her work spanned the impacts of regulatory and market initiatives on carbon credit demand and corporate claims, such as Article 6 of the Paris Agreement, the Voluntary Carbon Markets Integrity Initiative (VCMI), and the Science-Based Targets Initiative (SBTi). Before Climate Impact Partners, she worked as a Summer Analyst at Bloomberg New Energy Finance (BNEF), where she conducted client-facing research on the economics and carbon storage potential of regenerative agriculture in the United States. Mila holds an MS in Energy Systems and Data Analytics from University College London and a BA in Economics and Geography from Trinity College Dublin. In her postgraduate degree, her work focused on using machine learning models to forecast global crop yields under different climate scenarios.
Foundation Scholar, Trinity College Dublin
1. Interim removal targets would be set by companies on a five-year time horizon or based on milestone years.
2. The like-for-like principle is ‘when a source of emissions and an emissions sink correspond in terms of their warming impact, and in terms of the timescale and durability of carbon storage’, as defined by the UNFCCC. Thus residual emissions from burning fossil fuels would need to be addressed through engineered removals with permanent CO2 storage.
3. By the net-zero target year, residual emissions should be <10% of baseline year emissions.
4. By the net-zero year, scope 2 emissions from energy generation should be zero. Scope 3 residual emissions from supply chains are challenging to estimate.
Dr. Meera Atreya is a member of the SBTi Technical Advisory Group and has been engaging with the organization in an external advisory capacity for the past two years.
What to Read Next
EU Emissions Trading System Reform: What It Means for CDR and International Credits
Key Takeaways
- The European Commission’s proposal to reform the EU Emissions Trading System (EU ETS) would fund 250 million tonnes of biogenic emissions capture with carbon storage (BioCCS) and direct air capture with carbon storage (DACCS), from 2031-2040.
- Our modeling suggests that the Commission’s anticipated prices are unrealistically low, meaning revenue from auctioned ETS allowances may be insufficient to fund an equivalent volume of DACCS and BioCCS.
- The proposal would also fund the procurement of up to 260 million tonnes of high-quality international carbon credits from 2036-2040. This would turn the EU into a major buyer of credits under Article 6 of the Paris Agreement, and set eligibility standards that will shape demand beyond Europe.
- Negotiations are expected to conclude in early 2027 and will determine the procurement volumes, scope of eligible projects, design of funding mechanisms, and associated timelines.
- Developers who design projects to meet demand and eligibility standards in both voluntary and compliance markets will be best placed to capture this value.
Voluntary and Compliance Markets Are Converging
Carbon project developers are already commercializing across voluntary and compliance markets. Eligible nature-based projects can sell credits to voluntary buyers or to CORSIA-obligated airlines. Similarly, ethanol plants paired with carbon capture and storage (CCS) can generate durable carbon dioxide removal (CDR) credits or monetize their low-carbon ethanol through California’s Low Carbon Fuel Standard. Corporate buyers are also guided by the Science Based Targets initiative’s (SBTi) Corporate Net Zero Standard, which introduces mandatory CDR from 2035. Increasingly, suppliers will need to consider both voluntary demand and compliance opportunities in order to maximize their economic benefits and climate impact.
The European Commission’s proposal to integrate carbon credits into the EU Emissions Trading System (ETS) creates another significant opportunity. The proposal reshapes the ETS on several fronts. It expands airline obligations, extends incentives for sustainable aviation fuel (SAF), reforms price control levers, and attaches conditions to the distribution of free allowances. All of these reforms are under negotiation with the European Parliament and the Council of the EU, with a final agreement expected in the first quarter of 2027. This blog focuses on the two elements most relevant to carbon project developers: the integration of CDR, and the procurement of international credits.
What Is the EU Emissions Trading System?
The EU ETS is Europe’s flagship emissions trading scheme: a cap-and-trade carbon market covering power, industry, aviation, and maritime shipping. The EU ETS sets an overall cap on the emissions allowed from regulated sectors. Companies must hold one allowance for every tonne of CO2 equivalent (tCO2e) they emit, or face penalties. Most allowances are sold at auctions, and those funds are recycled back into climate and energy projects in Europe. The number of allowances issued decreases annually, which tightens supply, increases prices, and sharpens the incentive to decarbonize. However, driving those final emissions to zero can become prohibitively expensive. Integrating CDR into the ETS would allow entities to compensate for the residual emissions from the hardest-to-abate sectors with an equivalent volume of CDR.
The European Climate Law and the 2040 Target
The European Climate Law sets a binding target to cut net emissions 90% below 1990 levels by 2040. The law lets international carbon credits cover “up to 5% of 1990 net Union emissions.” The baseline emissions were around 4,609 million tCO2e, meaning 5% is roughly 230 million tCO2e per year. The Commission’s proposal would replace a small share of mandated ETS emissions reductions with international credits, easing pressure on regulated entities while keeping the bulk of the effort (at least 85% reduction) at home.
The proposal now sits with the European Parliament and the Council of the EU, with members of each body working to reach consensus. Once each body has adopted a unified negotiating position, they will enter into ‘Trilogue’ negotiations alongside the Commission to agree on a final text. On current timelines, those talks will begin in early 2027.
Integration of CDR into the EU ETS
What Did the Commission Propose?
Scope: The proposal brings only biogenic emissions capture with carbon storage (BioCCS) and direct air capture with carbon storage (DACCS) credits into the ETS. As long expected, the proposal requires these units to be generated in the EU and certified under the Carbon Removal and Carbon Farming (CRCF) Regulation. The Commission chose to exclude all other project types, at least initially. The proposal does not indicate the relative procurement quantities of BioCCS and DACCS, but the Commission will pursue a portfolio approach that considers cost-effectiveness.
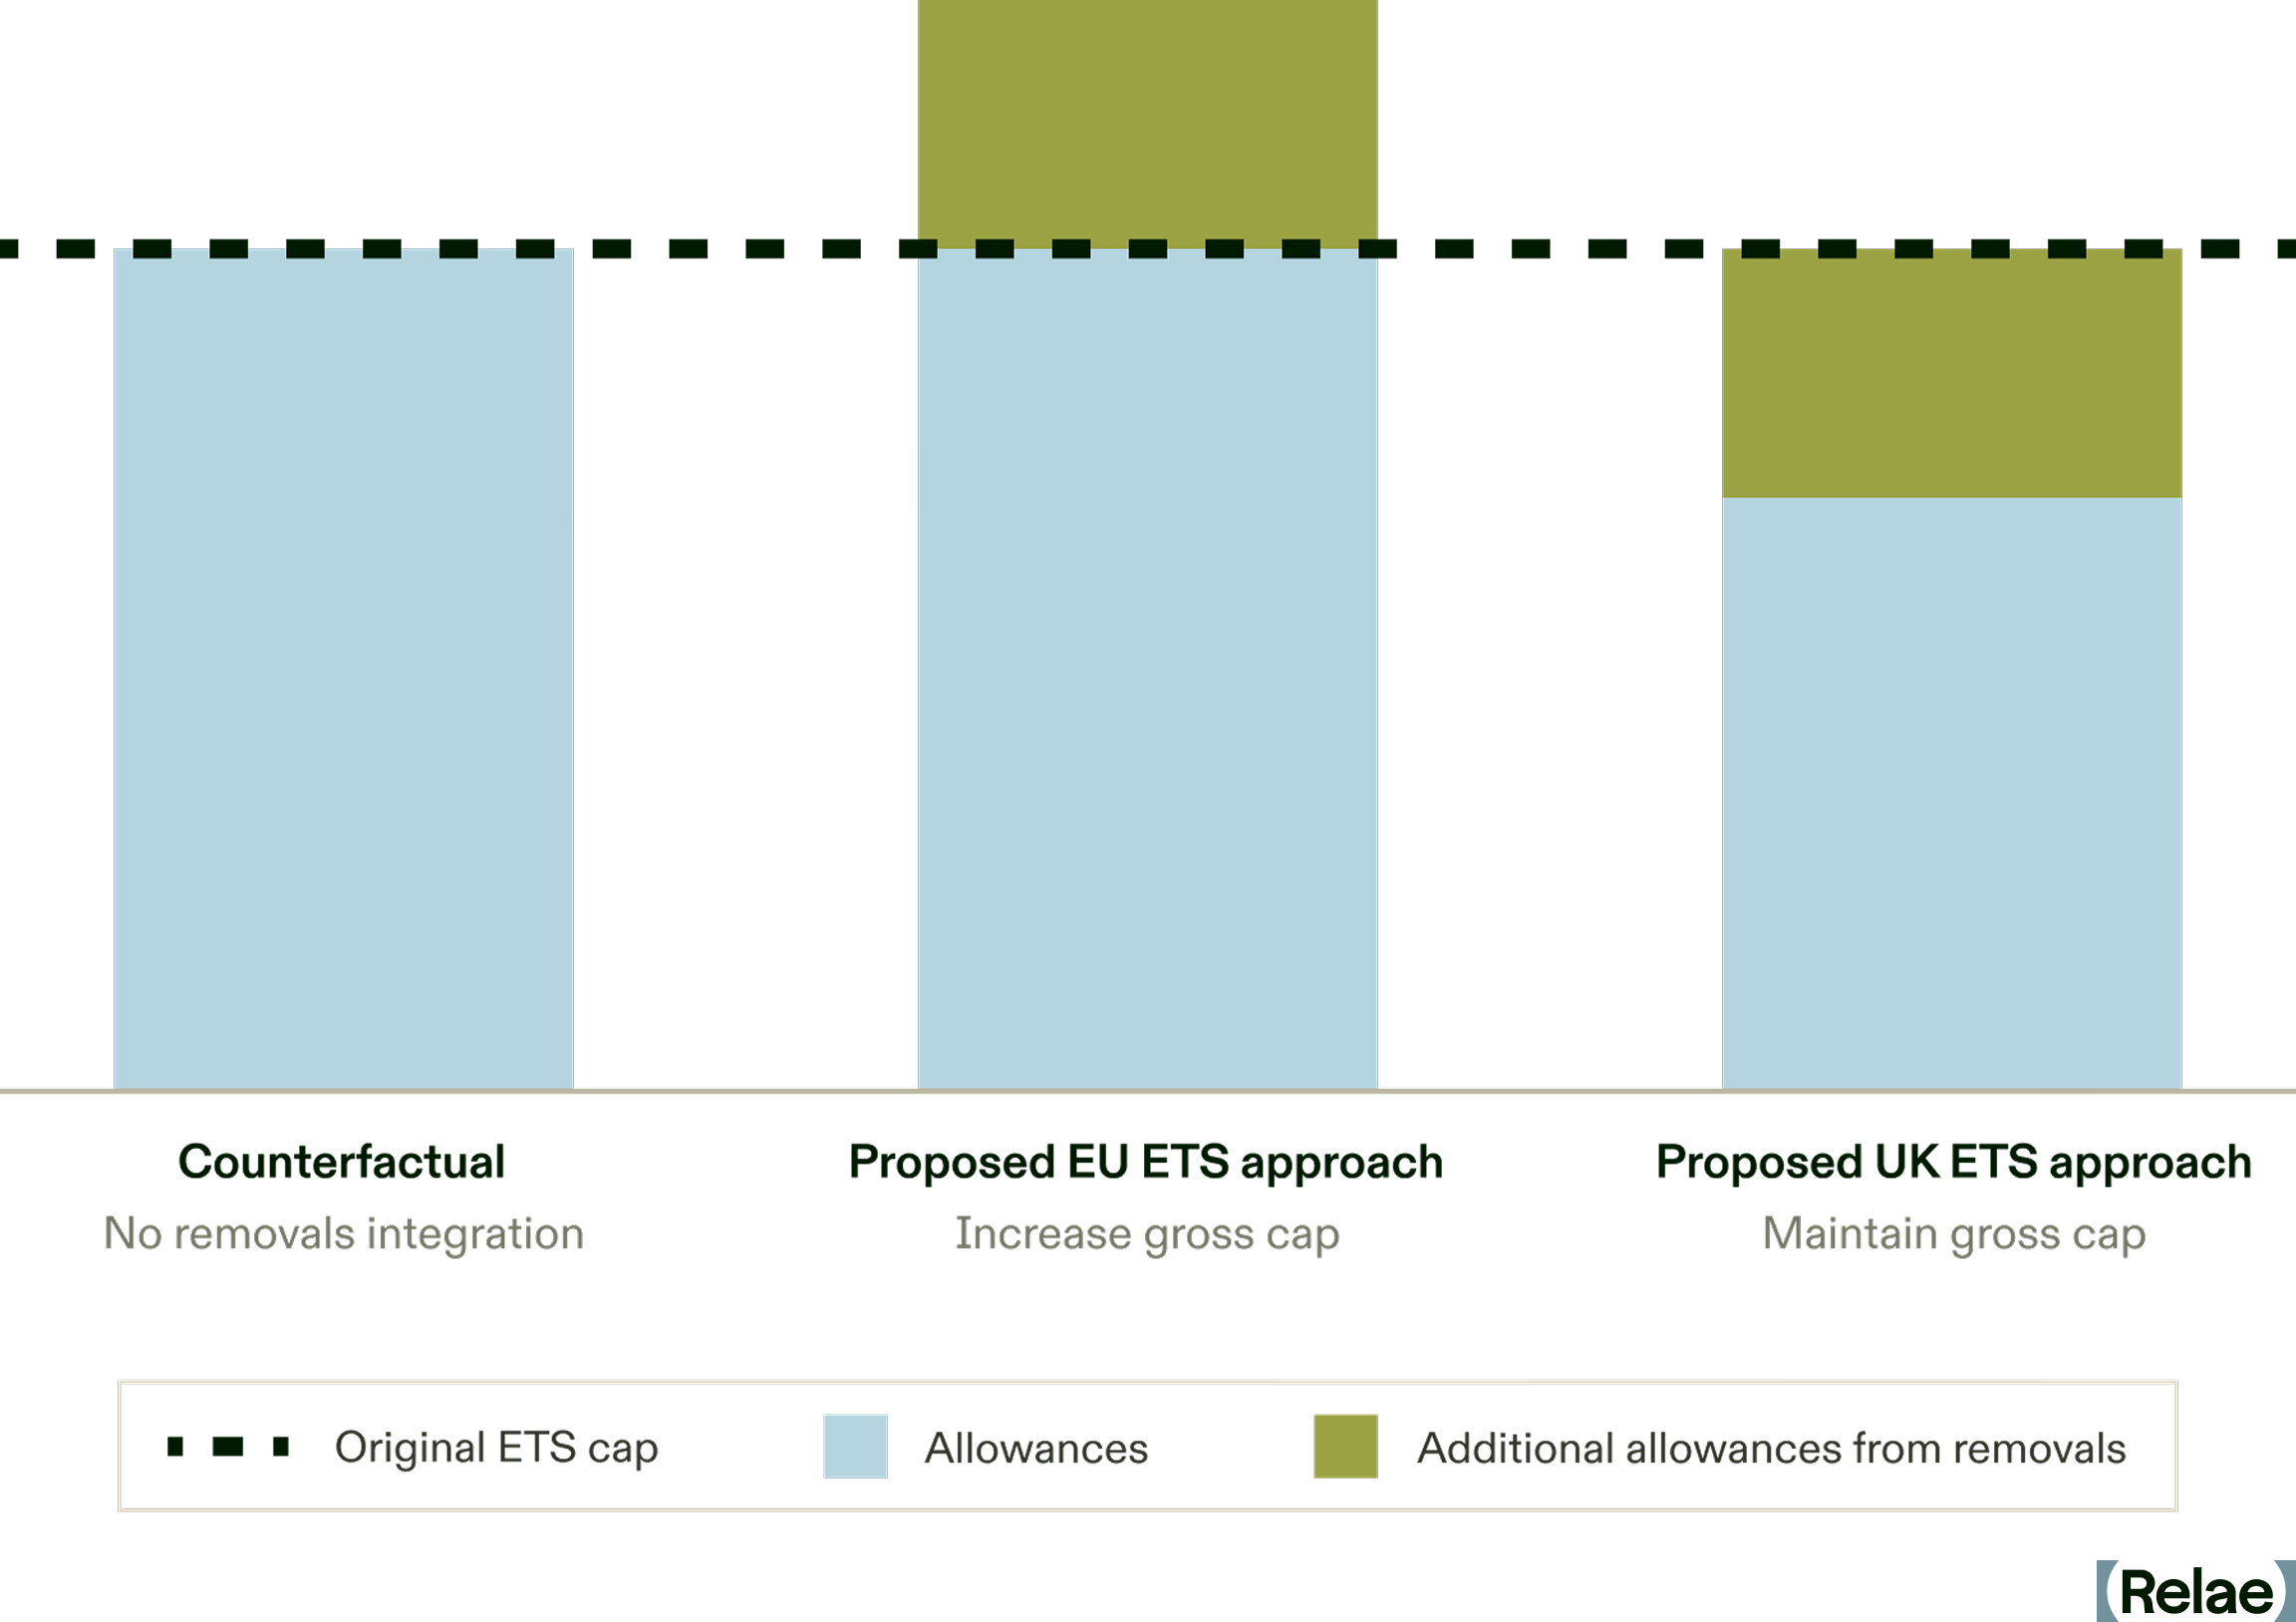
Volume: The Commission would increase the ETS cap by a total of 250 million allowances, and use the additional auction revenue to fund the purchase of 250 million tCO2e of CDR. If the initial funds are insufficient, revenue from an additional 10 million allowances would be set aside to fund these purchases.
Mechanism: BioCCS facilities regulated under the ETS that generate their own CRCF-certified CDR can use the credits to reduce their ETS obligations. Otherwise, all procurement and use of units would be managed by a central procurement facility, not by regulated entities. This design differs from the approach promoted by the UK ETS Authority in 2025 (see Figure 1). This could be relevant in discussions about relinking the systems, as fungibility of CDR generated in the respective markets will be critical to developer planning.
Timeline: The Commission can start buying eligible CDR in 2031. The volume of allowances auctioned to fund this procurement will start in 2031 and increase each year, up to 48 million allowances in 2040. The level of procurement in earlier years was not included in the proposal. An important review clause is built in: in 2034, the Commission will assess whether evidence supports the integration of more project types, and also whether regulated entities can start buying CDR directly.
What’s Under Negotiation?
Scope: Of all excluded project types, the Commission's accompanying Impact Assessment discussed biochar most favorably. Peter Liese, the European Parliament’s lead negotiator on ETS reform, initially proposed to include biochar, but capped at 20%, possibly to assuage concerns that biochar would crowd out DACCS and BioCCS due to its lower cost. Even if non-CCS CDR remains excluded for now, the final text could require new legislation to set criteria on how those projects can achieve integration in future.
Volume: Negotiators’ perspectives vary widely on the optimal volume of CDR to include in the ETS. The parliamentary Greens, more skeptical of increasing the ETS allowance cap to accommodate CDR, have proposed that the 250 million figure should be as low as 75 million. Conversely, Renew, a centrist party more supportive of CDR integration, wants to increase the figure to 300 million. In any case, specific procurement targets for all years, not only 2040, would improve market certainty and enhance project bankability.
Mechanism: Revenue from auctioned ETS allowances may be insufficient to fund an equivalent volume of CDR. Our proprietary modeling, which draws on anonymized real-world price points by suppliers, suggests the Commission’s anticipated CDR prices are unrealistically low. Separately, Council representatives have proposed to set aside 50 million allowances in case the initial funding falls short, up from the Commission’s proposed 10 million. Other ETS aspects also play a role. For example, extended provision of free allowances would reduce auction demand and depress prices. Developers will want confirmation of how much CDR the Commission will buy, regardless of the ETS allowance price.
Timeline: Negotiators and industry advocates have called for the Commission to start procuring CDR well before 2031. The review considering inclusion of non-CCS project types could also be brought forward from 2034. Both of these aspects would enhance certainty for developers, and enable projects to reach Final Investment Decision (FID).
EU Procurement of International Carbon Credits
What Did the Commission Propose?
Volume: The European Climate Law allows the use of around 230 million tCO2e of international credits per year. The European Commission proposed that the ETS use some of these credits–up to 260 million tCO2e in total across 2036-2040. In total, this demand for Paris Agreement-aligned internationally transferred mitigation outcomes (ITMOs) would be greater than the 170-215 million tCO2e projected for CORSIA Phase 1. Importantly, the ETS only represents a portion of the full amount of international credits available for EU entities to use. Rules governing how EU member states can use ITMOs to meet their climate targets are pending, and the allocation and use of those credits across EU climate policy instruments remain subject to further legislation.
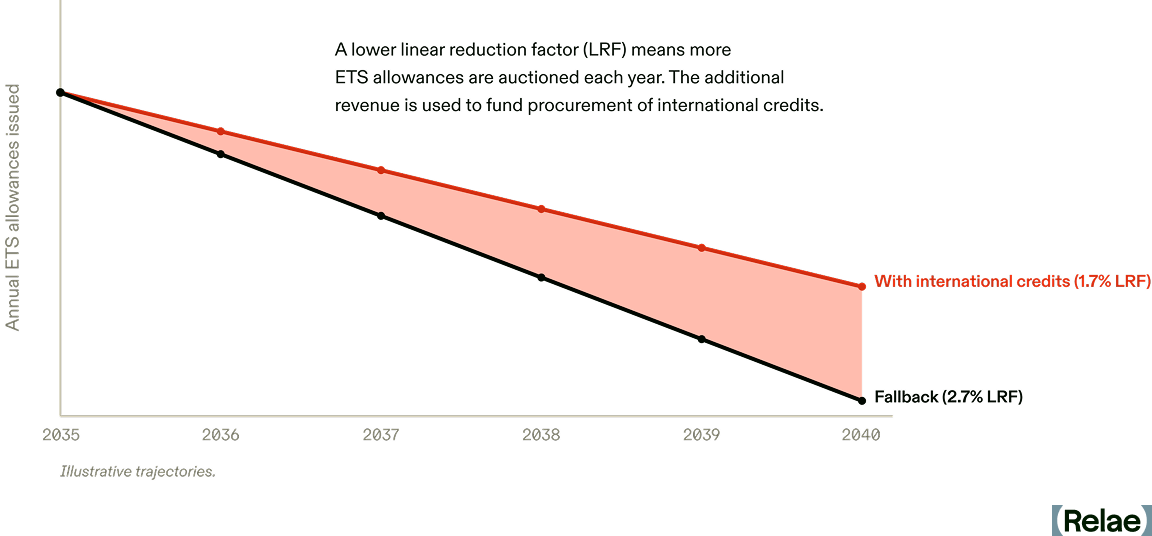
Mechanism: The linear reduction factor (LRF), which sets the rate at which the issuance of new ETS allowances declines annually, would fall from 3.7% over 2031-2035 to 1.7% from 2036-2040, rather than the 2.7% that would otherwise apply. That one-point slowdown leaves more allowances in the system. Auction revenue from up to 260 million extra allowances would fund the purchase of an equivalent volume of high-quality international credits. Again, procurement would run through a Commission facility; regulated entities cannot buy credits directly.
Scope: Credits would need to meet criteria established under the Climate Law. A proposal is expected in late 2026, expected to make reference to standards under Article 6.4 of the Paris Agreement and impose additional requirements on the quality of the host country’s climate reporting.
Timeline: Revenue from auctioned ETS allowances will be set aside for international credits from 2036 onwards. However, the European Climate Law provides for a pilot phase from 2031-2035, which could enable earlier activity from the Commission. A review in 2033 will determine if sufficient high-quality credits are available on the market—if there aren’t, the LRF will rise to 2.7%, closing the headroom opened for international credits.
What’s Under Negotiation?
Volume: The most important question is whether international credits survive the negotiations at all, with some influential parties concerned about replacing domestic emissions reductions driven by the ETS with projects outside of EU control. Parliamentary groups, members of the Council of the EU, and the European Economic and Social Committee, an EU advisory body, have all proposed that international credits be entirely excluded from the text.
Mechanism: Should international credits remain in scope, the Commission will be pushed to elaborate on expectations for the pilot period. Peter Liese’s proposal also suggested that international projects developed by EU-linked companies could be given priority. This could lead third-country governments to seek more European involvement in the development of carbon projects. Additionally, reporting on closed-door negotiations suggests that some parties want to connect international credits to the market stability reserve (MSR), which adjusts allowance supply in response to surplus in the market, and leave the LRF untouched.
Scope: The quality criteria for international credits will be laid out in separate legislation, and similar criteria may be applied to EU airlines meeting their CORSIA obligations. The Commission’s Climate Change Expert Group has already discussed meaningful restrictions, such as on projects related to avoided deforestation or based in countries with faulty reports under Article 6 of the Paris Agreement. These rules will be critical for stakeholders, as mere compliance with the rules of certification registries may not be enough to qualify a project for procurement eligibility.
Timeline: The review of the international credit market in 2033 leaves project developers little time to secure capital before procurement begins in 2036. The start date is fixed in the Climate Law, so it is not up for negotiation. However, the inflexible design of the fallback could change. As drafted, the LRF rises to the full 2.7% in 2036 if there are not enough available high-quality credits, meaning none can be used at all. Negotiators could instead use the volumes the market delivers, and scale the LRF to the remaining gap, rather than raising it in full.
Proposed EU ETS Timeline: Key Dates for CDR and International Credits
- Early 2027: Trilogue negotiations expected to begin, with a final agreement targeted for the first quarter.
- 2031: The Commission can begin buying CDR, and the pilot phase for international credits may be considered for 2031-2035.
- 2033: Review of whether enough high-quality international credits are available. If not, the LRF rises to 2.7% (in 2036-2040).
- 2034: Review of whether to admit more CDR project types and let regulated entities buy CDR directly.
- 2036: International credit procurement begins, and the LRF would fall to 1.7%.
- 2040: Allowances auctioned to fund CDR reach up to 48 million, and the 90% net emissions reduction target applies.
Positioning for What Comes Next
However the final text lands, the EU is becoming a major player in the market for CDR and internationally transferred mitigation credits. Compliance demand will become increasingly important, and if you’re raising capital for a project, you should no longer plan around voluntary buyers alone. You need a clear view of the regulatory factors that decide project viability, including committed volumes, legislative timelines, eligibility rules, and allowance price controls. We help developers formulate cohesive strategies across voluntary and compliance markets, while building quality projects that deliver the committed tonnes and impact.
Frequently Asked Questions
Can companies use carbon dioxide removal or international credits for EU ETS compliance?
Under the European Commission proposal, the Commission buys both centrally, so regulated operators cannot surrender CDR units or international credits to meet their obligations. There is one exception: a regulated entity that generates its own biogenic emissions capture with carbon storage (BioCCS) credits certified under the Carbon Removal and Carbon Farming (CRCF) Regulation can use those to reduce its ETS obligations.
Which carbon dioxide removal pathway would be eligible under the EU ETS?
Only biogenic emissions capture with carbon storage (BioCCS) and direct air carbon capture and storage (DACCS). Both must be EU-based and certified under the Carbon Removal and Carbon Farming (CRCF) Regulation. Other CDR methods are excluded for now.
When would the EU start buying carbon dioxide removal and international credits?
The two run on different timelines. The European Commission could begin purchasing CDR from 2031, with volumes ramping up to 48 million tonnes of CO2 equivalent (tCO2e) in 2040. Actual procurement volumes may depend on auction proceeds, removal costs, and the final mechanism design. International credit procurement would start in 2036.
Marine Carbon Dioxide Removal: What It Is and How It Works
Key Takeaways
- Marine carbon dioxide removal (mCDR) uses ocean-based processes—primarily ocean alkalinity enhancement (OAE) and direct ocean removal (DOR)—to capture and durably store atmospheric carbon dioxide (CO₂), without the land and freshwater constraints of terrestrial methods.
- The ocean already absorbs roughly 29% of human-caused CO₂ emissions each year, according to the 2025 Global Carbon Budget, and mCDR technologies aim to safely enhance that natural uptake without worsening ocean acidification.
- For corporate carbon buyers and project developers evaluating mCDR, the Criteria for High-Quality Marine Carbon Dioxide Removal, developed by Microsoft and Relae, outlines standards to guide responsible mCDR deployment at scale.
Reducing carbon dioxide (CO₂) emissions alone is no longer sufficient to limit global warming to 1.5°C. To effectively address climate change, scientific consensus highlights the need to remove carbon dioxide already present in the atmosphere. Marine carbon dioxide removal (mCDR), a form of ocean-based carbon removal, offers a scalable solution by leveraging the ocean’s natural ability to absorb and store carbon, without the land and resource limitations associated with terrestrial carbon removal methods.
This guide explores the fundamentals of marine carbon dioxide removal, including how it works, the technologies involved, and its role in global decarbonization.
What Is Marine Carbon Dioxide Removal?
Marine carbon dioxide removal uses ocean-based processes to capture and store carbon dioxide from the atmosphere. mCDR techniques fall into two primary categories:
- Biotic CDR, which includes using photosynthetic fixation, microalgae cultivation, and terrestrial biomass sinking, to capture and store carbon.
- Abiotic CDR, which influences CO₂ concentrations and carbonate chemistry in the seawater to absorb atmospheric CO₂ without increasing acidity. There are two main abiotic mCDR pathways: ocean alkalinity enhancement (OAE) and direct ocean removal (DOR).
How Does Marine Carbon Dioxide Removal Work?
Marine carbon dioxide removal functions via the air-sea gas exchange—a process by which the atmosphere and surface seawater maintain equal CO₂ concentrations—meaning a shift in one leads to a corresponding change in the other. This exchange allows the ocean to absorb or release CO₂ back into the atmosphere depending on concentration levels and factors like pH.
Once absorbed by the ocean, CO₂ exists in several forms, including dissolved CO₂, carbonates, and bicarbonates, influencing the ocean's pH levels. As atmospheric CO₂ levels rise, the oceans absorb roughly 12 GtCO2 annually, approximately 29% of anthropogenic CO2 emissions. This increase is disrupting the natural CO₂ balance and contributing to ocean acidification.
mCDR methods like ocean alkalinity enhancement and direct ocean removal use safe and controlled processes to increase the amount of CO2 absorbed from the atmosphere while mitigating acidification.
Understanding Ocean Alkalinity Enhancement (OAE)
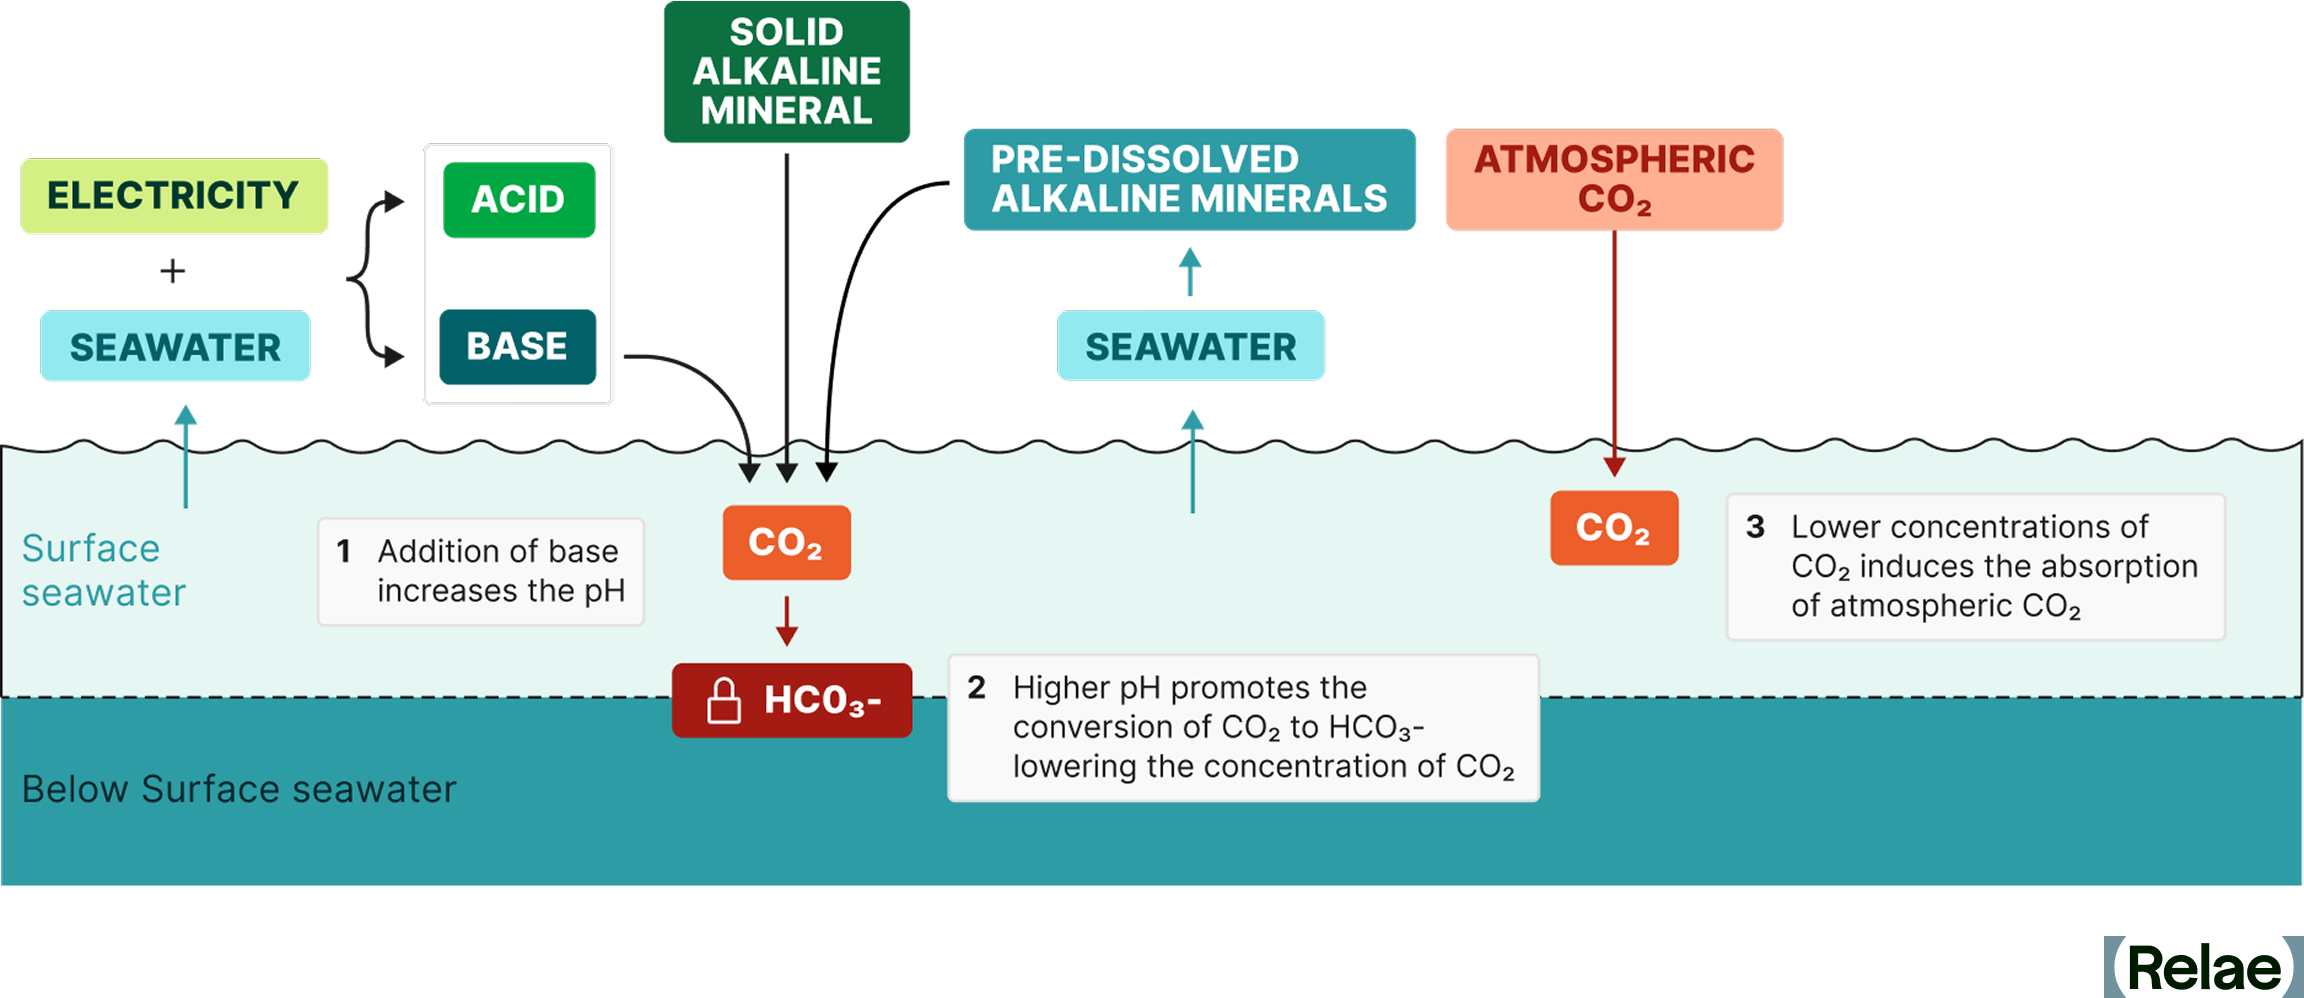
Ocean alkalinity enhancement (OAE) captures and stores atmospheric CO₂ as dissolved carbonates in the ocean by increasing the alkalinity of seawater using one of two primary methods:
- Adding alkaline minerals such as olivine or basalt to seawater.
- Using electrochemical methods to add alkaline compounds to seawater.
Both of these methods increase the alkalinity of seawater and, thereby, its capacity to absorb atmospheric CO₂ without acidification.
OAE methods can also differ by location and the manner in which seawater interacts with alkaline substances and atmospheric CO₂. This interaction may occur in the open ocean or within a controlled mCDR project facility. Each approach involves trade-offs: open ocean methods tend to be less energy-intensive but present greater uncertainties and challenges in measurement, reporting, and verification (MRV).
Understanding Direct Ocean Removal (DOR)
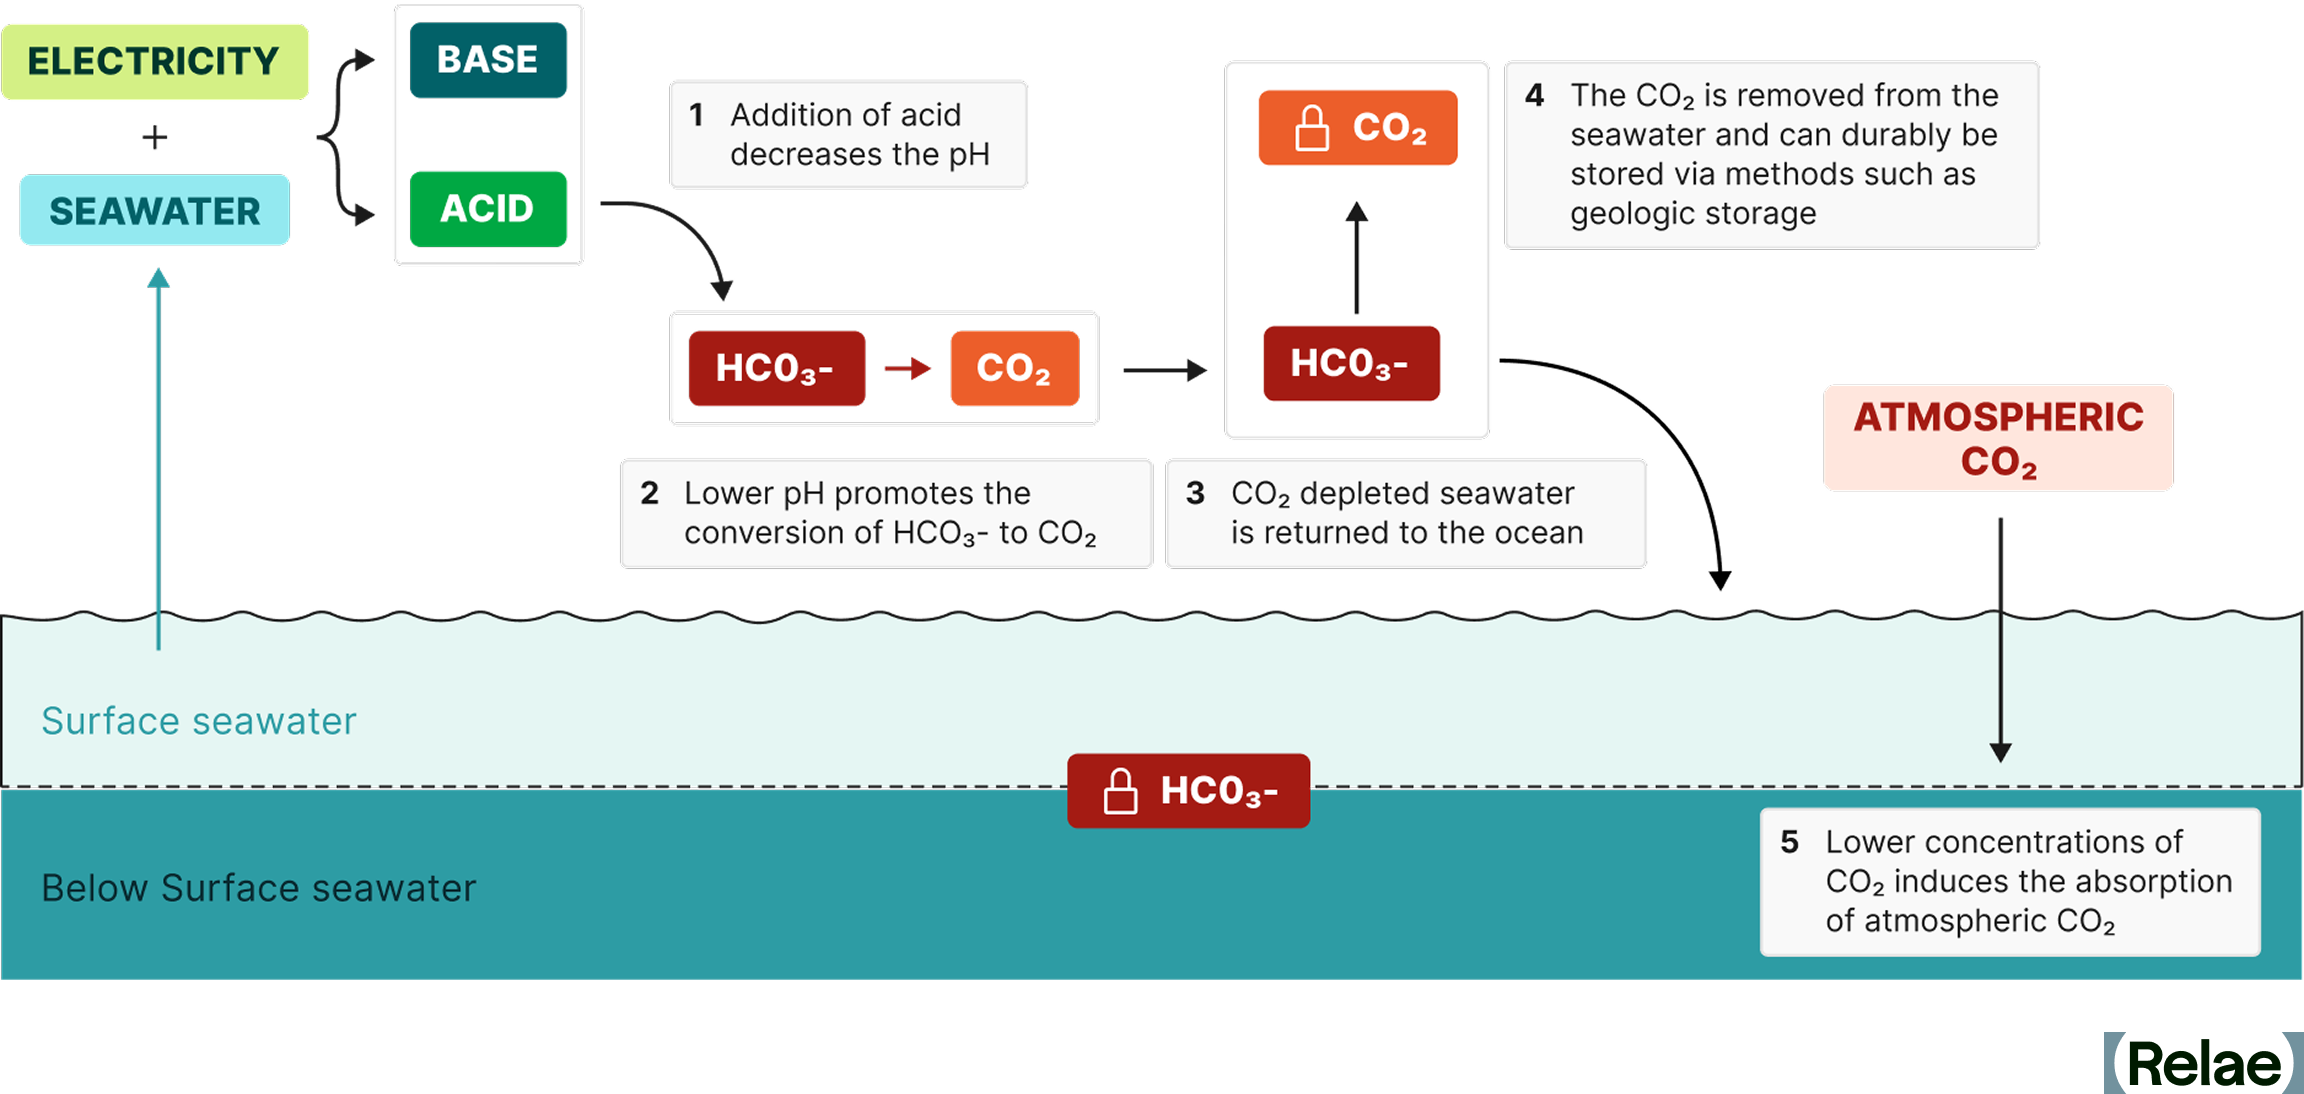
Direct ocean removal (DOR), also called direct ocean capture (DOC), removes CO₂ dissolved in seawater using the controlled acidification of seawater in a closed system using one of two primary methods:
- Electrochemical methods such as electrolysis of seawater or electrodialysis
- The addition of minerals like olivine and basalt.
The acidified and CO₂ depleted seawater is neutralized to native pH and allowed to equalize with and remove atmospheric CO₂. Once removed, CO₂ can be safely stored using geologic storage with a durability of >1,000 years.
Nomenclature for Direct Ocean Removal
Direct ocean removal is more commonly referred to as direct ocean capture. Relae believes the term direct ocean removal (DOR) is more accurate for two reasons:
- We think it is scientifically more accurate as both OAE and DOR remove CO₂ from the atmosphere but DOR directly removes CO₂ from the oceans, where in OAE, CO₂ is captured as bicarbonates in the ocean.
- DOC is a term for dissolved organic carbon, which is frequently used in mCDR project documents, reports, and the scientific literature.
Key Benefits of Marine Carbon Dioxide Removal
Understanding how mCDR works highlights its potential to address climate challenges. Here are the key benefits that make it a critical tool in global decarbonization strategies.
- Scalable carbon removal without land constraints: Marine carbon dioxide removal does not require large land areas or significant freshwater resources, making it highly scalable.
- Harnessing the ocean’s natural carbon sink: The ocean absorbs about 25% of human-generated CO₂ annually. mCDR enhances this natural process, increasing carbon storage without accelerating ocean acidification.
- Diverse technological pathways for flexibility: Technologies like ocean alkalinity enhancement and direct ocean removal offer flexible solutions tailored to different environments and project needs.
- Global reach with a large surface area: Covering over two-thirds of the Earth’s surface, the ocean provides an expansive platform for mCDR technologies globally.
- Potential to mitigate ocean acidification: Some mCDR methods, such as ocean alkalinity enhancement, not only remove CO₂ but also help restore ocean pH levels, supporting marine ecosystem health.
Challenges of Marine Carbon Dioxide Removal
While mCDR holds significant promise, it also presents challenges that must be addressed for responsible deployment.
- Technical scalability and efficiency: Scaling mCDR technologies to achieve meaningful carbon removal while maintaining energy efficiency remains a significant hurdle.
- Potential environmental impacts: Altering ocean chemistry may pose risks to marine ecosystems, with long-term effects still not fully understood.
- Measurement, reporting, and verification (MRV) complexity: Accurately measuring CO₂ removal and ensuring its durability requires advanced monitoring systems, which are still evolving.
- Regulatory and governance gaps: Clear global policies are needed to oversee mCDR deployment, manage environmental risks, and ensure accountability.
- Public perception and ethical considerations: Concerns around geoengineering and potential unintended consequences may impact public acceptance and policy support.
Deploying Marine Carbon Dioxide Removal
As mCDR technologies evolve, effective deployment will rely on adaptive management practices to address technical, environmental, and regulatory challenges. This includes robust MRV systems for accurate CO₂ removal tracking and continuous ecosystem monitoring to mitigate potential risks to marine life.
Collaborative efforts between scientists, policymakers, and project developers are key to establishing clear regulatory frameworks, optimizing technologies for efficiency and scalability, and building public trust. These practices ensure mCDR can be scaled responsibly while safeguarding ocean health.
The Future of Marine Carbon Dioxide Removal
As technologies like ocean alkalinity enhancement and direct ocean removal advance, their potential to deliver large-scale, durable carbon removal is becoming increasingly evident. Realizing this potential requires more than technological innovation—it depends on rigorous environmental monitoring, transparent reporting, and strong collaboration among project developers, carbon buyers, and policymakers.
Establishing clear, consistent standards for high-quality mCDR is essential to ensure both climate effectiveness and environmental safety. To support this, Microsoft and Relae have partnered to develop the Criteria for High-Quality Carbon Dioxide Removal.
Frequently Asked Questions
What is marine carbon dioxide removal (mCDR)?
mCDR uses ocean-based processes, primarily ocean alkalinity enhancement and direct ocean removal, to capture and durably store atmospheric CO₂. It works by increasing the ocean's natural capacity to absorb CO₂ without increasing acidification.
How does marine carbon dioxide removal compare to land-based methods like direct air capture or reforestation?
Unlike land-based approaches, mCDR doesn't require large land areas or freshwater, and the ocean's size gives it significant scaling potential. It's earlier-stage than more established pathways, though, with measurement and environmental monitoring standards still maturing.
Is marine carbon dioxide removal proven and scalable today, or still emerging?
mCDR technologies have shown promising results in lab testing and early deployments, but confirming safety and effectiveness at a large real-world scale requires more monitoring data. It's best described as an emerging pathway with strong near-term momentum, not yet a mature, at-scale solution.
What should a company look for when evaluating a marine carbon dioxide removal project or credits?
Buyers should look for rigorous carbon MRV paired with equally rigorous monitoring of ocean ecosystem health (eMRV), transparent reporting, and adherence to established frameworks like the Criteria for High-Quality Carbon Dioxide Removal.
SBTi Emphasizes Near-Term Carbon Removal in Revised Corporate Standard Draft
Key Takeaways
- Near-term role for carbon removals: The revised Science-Based Targets Initiative (SBTi) Corporate Net Zero Standard (CNZS) v2.0 proposes requiring or recognizing interim carbon dioxide removal (CDR) targets before companies reach net zero. This shift aims to scale up the CDR industry in line with climate science and ensure companies address residual emissions earlier rather than deferring action until their net-zero target year.
- Revised target frameworks and increased accountability: The draft standard introduces key changes, including separate targets for scope 1 and 2 emissions, enhanced scope 3 target-setting guidelines, and the recognition of market-based mechanisms for indirect mitigation of scope 3 emissions. It also requires companies to publicly disclose transition plans and assess implementation progress against targets.
- Potential for stronger action on removals: While the proposed updates are a step forward, the final standard should make near-term CDR targets mandatory rather than optional and should expand to include those for projected scope 3 residual emissions, not just scope 1. Without these stronger mandates, demand for early-stage CDR investments may remain limited, potentially slowing progress toward net-zero goals.
- Companies should prepare now: Businesses should start integrating CDR into their climate strategies now so they are equipped to navigate procurement of high-quality removal credits in the voluntary carbon market. Preparing ahead of the final CNZS v2.0 release will help companies align with science-based decarbonization pathways and demonstrate climate leadership.
What the Latest SBTi Update Means for Corporate Climate Action
On 18 March, 2025, the Science Based Targets Initiative (SBTi) released its draft Corporate Net Zero Standard (CNZS) v2.0, significantly updating its framework for corporate net-zero target setting for the first time since 2021. The draft proposes new approaches for companies to support carbon dioxide removal (CDR) in the transition to net-zero emissions, a move that could help scale the nascent CDR industry.
This release is part of a broader revision, with key proposed updates including:
- Requiring public disclosure of transition plans after companies set targets.
- Separating targets for scope 1 and 2 emissions.
- Enhancing the scope 3 target-setting framework using an impact-based prioritization process.
- Recognizing indirect mitigation (e.g., book-and-claim commodity certificates) for hard-to-trace scope 3 emissions.
- Defining a role for emissions removals in the transition to net zero.
- Providing options to recognize company leadership in beyond value chain mitigation (BVCM).
- Assessing corporate progress against targets to bolster accountability.
While formal recognition of removals in the transition to net zero is a positive step, stronger incentives will be needed in the final CNZS to ensure companies take meaningful early action on CDR. The draft standard is open for the first of two public consultations until 1 June, 2025, with a finalized version expected to launch in 2026.
What Remains the Same From the Current Standard?
SBTi’s framework remains focused on three core requirements for companies:
- Reducing emissions year-on-year to reach an approved science-based target (SBT) by 2050 or earlier.
- Investing in beyond value chain mitigation (BVCM) in the transition to net zero to support near-term global decarbonization efforts.
- Neutralizing remaining emissions from the net-zero year (achieved after at least 90% emissions reductions) and onwards with high-quality, permanent carbon removal.
Carbon credits representing emissions reductions and removals remain ineligible for meeting reduction targets within a company’s value chain (SBTs).
What’s New in CNZS v2.0 for Carbon Removals?
Until now, the SBTi encouraged companies to invest in CDR through mechanisms such as BVCM, but has not proposed requiring removal before their target net-zero year. As a result, organizations had little clarity or incentive to invest in CDR ahead of their net-zero target date, dampening near-term demand for carbon removal and delaying the industry's growth.
The new draft changes this by proposing three options for the V2.0 Standard that address the impact of residual emissions during the transition to net zero:
- Option 1 (requirement): Companies are required to set near- and long-term removal targets, including interim CDR milestones,¹ to address projected residual emissions.
- Option 2 (optional with recognition): Companies can set and receive recognition for removal targets to address projected residual emissions.
- Option 3 (flexibility of mechanism): Companies have the flexibility to address expected residual emissions either entirely through additional emissions reductions within their value chain, entirely through removals, or via a combination of both.
Notably, all three approaches apply only to residual scope 1 emissions.
On top of these approaches, SBTi has suggested two options for the minimum durability threshold of CDR purchases in their draft standard. Removals will either need to follow a ‘like for like’ approach,² where CDR storage must match the atmospheric lifetime of residual emissions, or a gradual transition approach, where carbon storage durability increases over time.
Why Mandating CDR Matters
Mandating near-term CDR reinforces the need for immediate climate action, ensuring that carbon removals complement emissions reductions rather than being deferred until the net-zero target year. The urgency of early CDR investment is clear:
- Limiting global warming to well below 2°C above pre-industrial levels requires removing billions of tonnes (gigatonnes) of carbon dioxide annually by mid-century.
- The CDR industry is in its early stages and requires sustained investment today to scale in time.
- If companies wait until their net-zero year to purchase CDR, the supply of high-quality removal credits is unlikely to be sufficient.
As part of the proposed removal targets in Option 1 (above), the CNZS v2.0 would require companies to gradually increase CDR purchases over time, ramping up to 100% of a company’s projected residual scope 1 emissions in the net-zero target year (<10% of baseline year emissions).³
What More Can Be Done?
The potential introduction of required removal targets would be a significant and welcomed step, reinforcing the importance of near-term CDR investment to support industry maturation and climate goals. However, mandatory near-term CDR targets represent only one of three potential pathways for the V2.0 standard. Moreover, neutralization of residual emissions on the path to net zero is only proposed for scope 1 emissions. While the SBTi provides clear rationale for this,⁴ SBTi should not let the complexity of projecting scope 3 emissions be a barrier to climate change mitigation. Scope 3 emissions represent the majority of emissions from SBTi-aligned companies. Furthermore, companies with high scope 3 emissions typically have a higher ability to pay compared to their industrial counterparts with high scope 1 emissions.
If interim removal targets are made optional, and scope 3 emissions remain excluded, the demand signal for near-term CDR will be limited. The public consultation (and advice of Expert Working Groups that SBTi is convening) will be essential in determining which proposed guidance matures into the final standard; consultation feedback can be provided here prior to June 1, 2025.
How Businesses Can Prepare for CNZS v2.0
Companies aligning with SBTi’s evolving guidance should begin to integrate CDR into their climate strategy now. This means:
- Understanding their residual emissions forecast and planning early investments.
- Developing a company-specific climate strategy to incorporate CDR into their sustainability roadmaps in tandem with plans to reduce value-chain emissions.
- Engaging early in the voluntary carbon market to implement these strategies and develop procurement processes to support high-quality removal projects.
- Ensuring credibility by selecting removal projects aligned with scientific best practices.
Conclusion: A Step in the Right Direction, But More Certainty Is Needed
The CNZS v2.0 draft represents a critical turning point for corporate climate action with options to formalize the role of early CDR investment through interim removal targets for signatories. However, SBTi must take a stronger stance in the final version of the revised standard by choosing to adopt requirements for near-term neutralization (rather than leaving this optional), including projected residual scope 3 emissions in near-term CDR targets, aligning durability requirements with climate science, and defining removal quality standards to ensure these efforts drive meaningful climate impact. Organizations seeking to align with this guidance should prepare by developing a comprehensive climate strategy that accounts for science-based decarbonization pathways and recognizes the role of early-stage investment in CDR solutions.
The Role of Improved Forest Management for Carbon Dioxide Removal
Key Takeaways
- Improved forest management (IFM) increases measurable long-term carbon storage in living trees and durable wood products.
- At the same time, it can provide strong social and ecological co-benefits.
- IFM projects like the ones developed by Weyerhaeuser and the Indigenous community of Petcacab in collaboration with Relae (formerly Carbon Direct) show how IFM practices can align climate goals with social and environmental benefits.
Forests Are Climate Solutions If We Manage Them Wisely
Forests remove carbon dioxide from the atmosphere, but they need to be thoughtfully managed to keep doing so. As buyers look to scale carbon removal, improved forest management (IFM) is gaining traction in the voluntary carbon market (VCM).
IFM focuses on enhancing how existing forests are managed to increase carbon storage over time. It’s a nature-based solution that supports climate outcomes, community livelihoods, and environmental benefits when done well.
This piece explains how IFM works, what makes a project high-quality, and how real-world IFM projects like those developed by Weyerhaeuser and Petcacab in collaboration with Relae (formerly Carbon Direct) are delivering credible results for buyers and local communities alike.
What Is Improved Forest Management?
Improved forest management is a catch-all phrase that describes management techniques that decrease emissions from forests or increase carbon removal and storage. Some management techniques, like transitioning a working forest to a conserved status, decrease emissions from forest harvest and primarily create credits for avoided emissions. Other management techniques, like harvesting forests less frequently, can lead to greater carbon removal and storage over time and create credits for additional carbon removal.
Examples of IFM Practices Include:
- Extending harvest rotations to allow more carbon accumulation
- Reducing the impact of logging on soil and surrounding trees
- Managing fire and pest risks to enhance forest health
- Transitioning some of a forest to conservation status
These strategies help forest carbon stocks grow beyond business-as-usual baselines. In carbon markets, IFM can generate carbon removal or avoided emissions credits, depending on the project's design and carbon accounting methodology.
What Makes a High-Quality IFM Carbon Removal Credit?
Buyers today face increased scrutiny around carbon credit quality. In this context, IFM projects must go beyond basic registry standards to demonstrate climate integrity and social and environmental benefits.
Relae developed the Criteria for High-Quality Carbon Dioxide Removal, an annual report published in collaboration with Microsoft to establish science-backed quality standards. This includes six core principles that define high-quality carbon removal, all of which apply to IFM projects:
- Social harms, benefits, and environmental justice - The extent to which the project prevents new social harms to people and communities, reduces existing harms, and provides meaningful benefits distribution. Since IFM projects take place in communities around the world, benefits will naturally vary from project to project.
- Environmental harms and benefits - The extent to which the project minimizes and mitigates environmental harms, as well as provides environmental benefits. Because IFM projects enhance management practices, environmental co-benefits of high-quality IFM projects are usually substantial.
- Additionality and baselines – Evidence that the project’s carbon removal would not have occurred without carbon finance. Many IFM projects fail to present compelling additionality data and narratives. High-quality projects will be able to identify the actions the project took to increase carbon storage that would not have happened without carbon finance.
- Measurement, monitoring, reporting, and verification (MMRV) – The ability to accurately quantify carbon removal in a repeatable and verifiable way, and to develop a plan for long-term monitoring of the project. IFM projects must have robust forest inventory, growth modeling, and occasional remeasurement to verify the additional carbon storage.
- Durability – The likelihood that removed carbon remains stored over time, with mechanisms in place to mitigate reversal risk. Enhanced management of fire, pests, and disease in IFM projects can enhance forest carbon durability.
- Leakage – Evaluation of whether project activities cause increased emissions elsewhere. If an IFM project substantially reduces timber supply, market demand can drive increased harvesting in other forests, undermining some of the project’s climate benefits. High-quality IFM projects minimize this risk by limiting harvest reductions, and account for any remaining leakage by issuing fewer credits.
Relae uses these criteria as part of our diligence framework when advising buyers evaluating projects and co-developing our own projects.
IFM Projects Delivering Real Impact
Weyerhaeuser: Applying Science at Scale
Weyerhaeuser, one of the largest forest owners in North America, is applying improved forest management practices across over 200,000 acres of working forests.
The IFM projects led by Weyerhaeuser are located in rural areas in the US, with low wildfire risk. These IFM projects sequester carbon by extending harvest rotations and forgoing harvest in established streamside management zones.
Relae supported Weyerhaeuser with hands-on scientific collaboration to confirm that every IFM project met the Criteria for High-Quality Carbon Dioxide Removal.
Why it matters to buyers:
- High-quality climate impact at large scale
- Transition of working forests from traditional management techniques to maximize climate impact
- Responsible forestry practices aligned with SFI® standards
- Rigorous carbon accounting and high-quality project baseline established using historical harvest records
The IFM projects led by Weyerhaeuser are some of the largest in the US today and a model for scaling science-backed forest carbon solutions.
Petcacab: Indigenous-Led Conservation in the Yucatán Peninsula
Located in the communal lands of Petcacab, Mexico, this IFM project is led by Indigenous Mayan ejidatarios—community members who have legal rights to manage the land.
Historically, forests in the ejido have been degraded through unsustainable harvesting and extensive damage from hurricanes. Through carbon finance, they are developing new forest management plans and sustainable forestry models, with revenue reinvested in health, education, and job creation.
“The rainforest for me represents my home, my work, my present, my future. We have a very daring challenge: to transform how we manage our forest, shifting from harvesting and selling timber to conserving it through the sale of carbon credits that support the development of our community.”
— Celso Chan Rivas, Carbon Project General Manager
What makes Petcacab stand out:
- Equitable benefit-sharing and strong Indigenous governance
- Critical habitat protection for endangered species
- Increased additional carbon storage through forest management and reduced land use conversion
- Transparent reporting and verified outcomes
Petcacab is recognized by Relae as a high-quality community IFM project in Mexico, with clear social, environmental, and climate outcomes.
Investing in Forests That Deliver More Than Carbon
Improved forest management is more than a carbon strategy, it’s an investment in ecosystems, communities, and long-term impact. For buyers seeking high-integrity carbon removal with social and environmental co-benefits, IFM projects offer a compelling opportunity.
IFM projects like the ones developed by Weyerhaeuser and Petcacab in collaboration with Relae show what’s possible when forests are managed with science and care. They also reflect what the voluntary carbon market needs more of: quality, transparency, and impact beyond the metric ton.
US Wood Pellet Producers: The UK Market Is Contracting. Four Markets Are Beginning.
Key Takeaways
- The UK's new biomass Contracts for Difference framework will cut industrial wood pellet imports by slightly more than half starting in April 2027. As a result, US producers will be left competing for only 1.6 million GST, an 80% reduction in US-addressable volume, with no successor market locked in.
- US wood pellet producers who move now to upgrade sustainability credentials and build relationships in emerging markets will be best positioned to capture the next generation of demand; those who wait may find the most attractive offtake opportunities already structured around someone else's supply.
- Four domestic markets now present producers with new demand opportunities: cofiring, sustainable aviation fuel (SAF), low-carbon steel, and bioenergy with carbon capture and storage (BECCS). Of these, BECCS for data centers is the strongest structural fit: hyperscalers need clean firm power, pellet mills need offtakers, and the feedstock infrastructure is already in place.
The Demand Cliff Is Real, and the Timeline Is Short
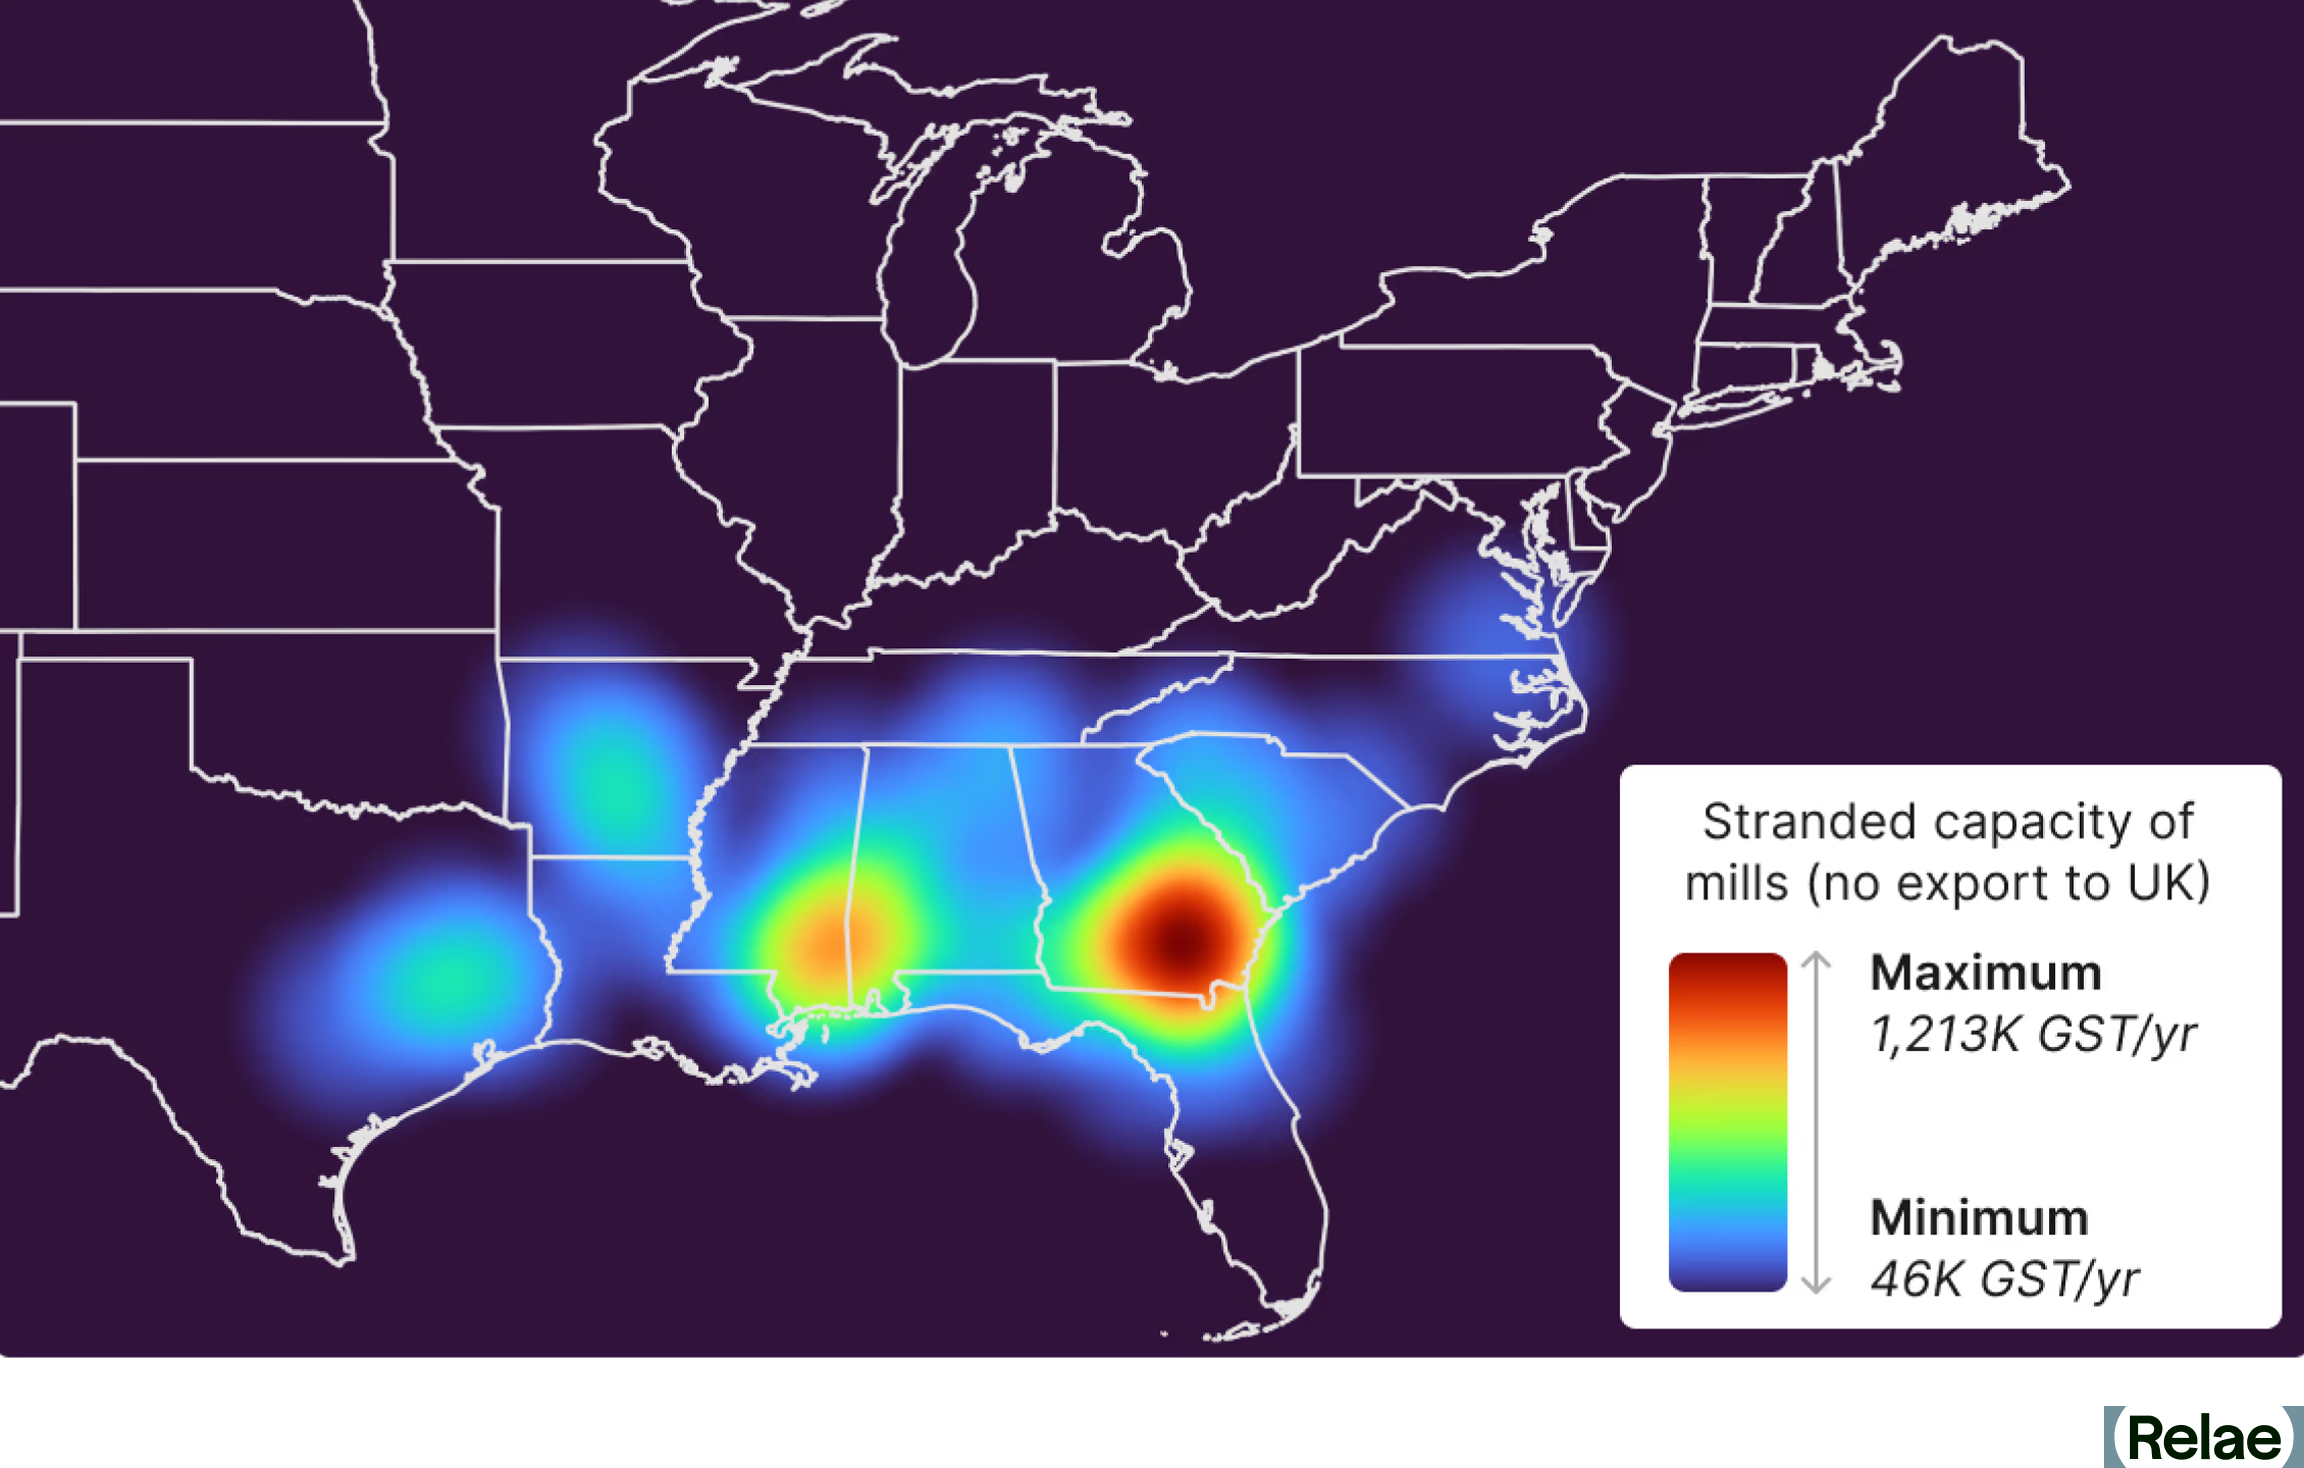
A pellet made in southern Mississippi this morning will be burned in a UK boiler about four weeks later. North America is on pace to ship more than 9 million green short tons (GST) of pellets to the UK each year—making the UK the world's largest consumer of wood pellets since 2018. The US Southeast is at the center of that supply chain: 28 large mills, 13.5 million GST of production capacity, rail spurs, export terminals, and bulk carriers, built almost entirely around UK demand.
However, the UK's new low-carbon Contracts for Difference (CfD) framework caps biomass power generators at a 27% annual capacity factor starting April 2027, down from roughly 64% today. When run hours fall by half, pellet demand follows. Existing subsidies expire in the first quarter of 2027, and the new CfD runs only to March 2031 with no commitment beyond that. Plant closures in Arkansas and Washington state, along with reduced output in Canada, are already early signals of supply chain contraction.
The Math of Who Gets Squeezed
The math is stark. By the second quarter of 2027, total annual UK pellet demand drops to 4.9 million GST. Of that:
- Approximately 2.3 million GST goes to captive, integrated UK supply chains.
- Approximately 1.0 million GST goes to Baltic suppliers, whose shipping times of one week or less become a decisive advantage as UK plants shift from baseload to dispatchable operation.
That leaves US producers competing for only 1.6 million GST. If Baltic suppliers capture more, US wood pellet exports to the UK could be effectively eliminated by 2031.
Sustainability qualification is also tightening. The new CfD cuts the supply-chain emissions ceiling from 55.6 grams of carbon dioxide equivalent per megajoule (gCO₂e/MJ) to 36.6 gCO₂e/MJ. The framework assesses compliance mill by mill, not on a portfolio average. A cleaner mill cannot carry a dirtier sibling through the door.
The producers who understand this math now have roughly 18 months to position themselves for what comes next.
From Stranded Supply to New Markets
The US Southeast's wood basket is robust: abundant inventory, strong growth-to-removal ratios, and more available residues than ever. The infrastructure is in place. The question is whether the next generation of markets can be developed quickly enough to redeploy this supply before the infrastructure sits idle.
Four pathways stand out as the strongest options for redeploying US pellet supply: BECCS for data centers, low-carbon steel, SAF, and domestic cofiring. We have rigorously assessed the logistics economics, sustainability cases, and project development for each.
BECCS for Data Centers: The Strongest Structural Fit
BECCS as a power source for data centers is the most compelling match for the situation pellet producers now face. The timing, feedstock requirements, and buyer characteristics align closely in a way that few other emerging markets can match.
Hyperscalers, the large data center operators driving an unprecedented surge in electricity demand, are signing deals for nuclear, geothermal, and small modular reactors alongside natural gas and renewables. They are doing this because annual Renewable Energy Certificates (RECs) are no longer sufficient to compensate for their scope 2 emissions, and they need clean, firm generation that can be matched to load on an hourly basis.
BECCS delivers exactly that. The Louisiana Green Fuels project—advanced by Strategic Biofuels and Relae (formerly Carbon Direct)—illustrates the model: regionally sourced forestry residues and sawmill waste generate 75 megawatts (MW) of firm electricity while sequestering over one million tonnes of CO₂ annually in deep saline formations. An ample supply of wood pellets creates a strategic opportunity for similar projects to move forward with certainty around feedstock processing, logistics, and costs.
The remaining commercial barrier is deal structure, not technology. No data center operator has yet signed an agreement to purchase both the electricity and carbon removal credits from a single BECCS plant. As scope 2 accounting tightens and domestic pellet supply becomes more readily available post-2027, the conditions for structuring the first such deal are improving fast.
"Pellet mills and data center developers have complementary problems: mills need offtakers, and data centers need local, dispatchable, clean power they can match to load on an hour-by-hour basis. BECCS is one of the few technologies that could solve both at once, and hyperscalers have shown they are willing to back early-stage clean firm power when the asset makes sense."
—Douglas Bryan, Senior Power and Energy Systems Modeler
Low-Carbon Steel: Certification Frameworks Are Arriving
Wood-derived biocarbon has a long-established niche in steelmaking. Brazil produces roughly 10% of its steel and 30% of its pig iron using charcoal from managed eucalyptus plantations—a proof of concept for biomass as a metallurgical input, if not a direct template for US producers. The plantations measurably lowered groundwater in producer regions of Minas Gerais, and charcoal's mechanical weakness relative to fossil coke has limited the model's reach beyond Brazil.
Current pilot projects use biomass in two roles. As a fuel, industrial trials have demonstrated 10% bio-coal co-injection without operational disruption, with reviews estimating that full replacement could cut blast-furnace CO₂ by around 27% per tonne of hot metal. As a reductant, biocoke is already being demonstrated at Outokumpu's pelletizing plant in Tornio, Finland. ArcelorMittal in Belgium and Tata Steel in India are running biomass pilots at tens of thousands of tonnes per year.
What makes this market worth serious attention now is the certification landscape. The Low Emission Steel Standard issued its first certifications in September 2025. The Global Steel Climate Council's Steel Climate Standard is under stakeholder review. In May 2025, Relae and Microsoft published Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors. These frameworks allow producers to internalize carbon price and environmental attribute certificate (EAC) values, closing the cost gap against fossil coke that has historically constrained biocarbon demand.
Relae worked with Eramet, a global metals company pursuing biogenic materials as a substitute for fossil coke at its Norwegian smelters, to assess high-quality carbon dioxide removal methodologies and chart a path to generating and selling carbon credits from their decarbonization projects. Producers who align their sustainability credentials to these emerging standards now will be better positioned for offtake as commercial-scale demand grows.
"Steelmaker pilots and the first low-carbon steel certifications are opening green-steel offtake to wood pellets, though commercial-scale demand remains limited. The producers that thrive in this market will be those that reliably deliver pellets aligned with high-quality sustainability standards."
—Louisa Brotherson, Hybrid Decarbonization Scientist
Sustainable Aviation Fuel: Mandates Create a Durable Demand Signal
Wood-based SAF is technically feasible via gasification to syngas, followed by Fischer-Tropsch upgrading, a proven chemistry for converting syngas to liquid hydrocarbons. Yet, the commercial challenges are substantial: the International Civil Aviation Organization estimates capital costs exceeding US$1 billion for large facilities, and production costs of US$11–48 per gallon to distillate.
The cautionary case is Fulcrum Bioenergy near Reno, Nevada, which attempted a Fischer-Tropsch process using municipal solid waste and appears to have failed due to a lack of rigorous pre-implementation testing and unrealistic timelines, a reminder that feedstock homogeneity matters enormously, and one area where pellets have a relative advantage.
Two structural dynamics make SAF worth serious attention despite those barriers. First, the European Union's (EU) SAF mandate, starting at 2% of jet fuel supply and ramping to 70% by 2050, carves out cellulosic biomass as the only qualifying feedstock once cooking oil supply is exhausted. The penalty structure in both the EU and UK creates strong demand regardless of SAF price: EU non-compliance penalties run roughly three times the price of SAF, and UK penalties can reach 13 times the cost of the fuel itself. Second, the alcohol-to-jet pathway offers a lower-capital entry point than Fischer-Tropsch, as demonstrated by Project Speedbird, a British Airways and LanzaJet collaboration targeting UK woody residues.
The near-term question is which routes have bankable offtake. Very few do yet, but the mandate structure suggests that window will shift rapidly.
"So far, facilities haven't scaled to the levels required to meet timeline demand. But the EU and UK mandate structures mean buyers are greatly incentivized to purchase SAF even at high prices, rather than pay non-compliance penalties."
—John Dees, Director, Fuels and Industrial Commodities
Domestic Cofiring: Achievable, but Not a Long-Term Anchor
Cofiring biomass with coal to produce electricity or heat is the most immediately achievable option. Most US coal-fired power plants could displace up to 10% of their input energy with raw or torrefied pellets, though plants would likely need fuel handling upgrades. Some state policies, such as Pennsylvania's Alternative Energy Portfolio Standards Act of 2004, support cofiring to meet renewable energy goals. However, there are no federal policies in the US that incentivize cofiring.
The case for cofiring as a long-term market is weak. The US coal fleet has contracted steadily for economic reasons—over 100 gigawatts (GW) of coal-fired capacity retired between 2015 and 2025—and biomass cofiring is unlikely to make a coal plant more cost-competitive. The Greenhouse Gas Protocol's scope 2 guidance does not permit buyers to procure a "strip" of electricity representing the biomass-fired fraction of output from a cofired plant; instead, buyers must accept the average total emissions from the plant in their scope 2 inventory, which limits the value proposition for corporate buyers seeking to demonstrate clean energy procurement.
The more interesting version of this pathway combines cofiring with carbon capture and storage (CCS), a combination that creates a deeper-abatement value proposition and the kind of firm, dispatchable power that corporate buyers increasingly need.
"Cofiring is a proven step toward modest emissions reductions from coal-fired electricity, but it's hard to make the economic case for it when compared to applications that command price premiums for deeper climate abatement."
—A.J. Simon, Director of Industrial Decarbonization
Sustainability Is Now the Qualification Gate
Each of these markets is more discerning about sustainable biomass sourcing than the UK power sector was a decade ago. That shift will not reverse.
US Southeast wood has real potential for high-integrity sustainability credentials, particularly in softwood residues. But it also carries downside risks when sourcing from natural stands. Through work with producers, buyers, and project developers across these markets, we have found that four questions now drive every serious procurement conversation:
- Does the supply chain have verifiable governance and chain-of-custody transparency?
- Does sourcing respect the rights of Indigenous Peoples and local communities?
- Is the wood coming from regions where forest carbon stocks are stable or growing, and not from protected areas or primary forest?
- Is sourced biomass a by-product of non-energy uses, and not the primary silviculture driver?
Producers who can answer yes to all four, and support those answers with data, are more likely to access these emerging markets. Those who cannot will find it harder to compete for offtake.
For a detailed framework on how these principles translate into contract language and certification requirements, see the 2025 Sustainable Forest Biomass Sourcing for CDR: A Buyer's Guide.
The Window Is Open, but Not Indefinitely
The US Southeast wood basket is well-positioned for the markets described here. The infrastructure is in place. What producers still need to build is the market positioning, sustainability documentation, and offtake relationships to go with it.
The producers who move now will have a meaningful head start. Those who wait for certainty may find that the most attractive offtake opportunities have already been structured around someone else's supply.
Learn more about Relae's work on SAF mandates, steel decarbonization, and sustainable biomass sourcing.
Frequently Asked Questions
What happens to US wood pellet exports when the UK's new biomass rules take effect?
Starting April 2027, the UK's signed Contracts for Difference agreement caps subsidized biomass generation at a 27% capacity factor, roughly half of today's levels. That's expected to cut total UK pellet demand to about 4.9 million GST a year, leaving only around 1.6 million GST available to US exporters.
Is BECCS for data centers a proven market, or still emerging?
The underlying technology is credible, and the Louisiana Green Fuels project already demonstrates it at commercial scale. However, the deal structure isn't yet proven. No hyperscaler has signed a single contract for both electricity and carbon removal credits from one BECCS plant, so this market is emerging rather than established.
How does low-carbon steel demand compare to sustainable aviation fuel as a market for pellet producers?
Steel offers nearer-term certification frameworks (the Low Emission Steel Standard began issuing certifications in 2025) but limited commercial-scale volume so far. SAF has a stronger long-run demand signal thanks to EU and UK blending mandates and steep non-compliance penalties, but requires far higher capital investment to enter.
What should a wood pellet producer look for when evaluating a new market?
The four sourcing questions that now gate access across all these markets are: verifiable chain-of-custody, respect for Indigenous and local community rights, sourcing from stable or growing forest carbon stocks (not primary forest), and biomass that's a by-product of non-energy uses rather than the primary driver of harvest.
The New Nasdaq Issuance Calendar Advances Transparency in the Carbon Removal Market
Key Takeaways
- The Nasdaq Carbon Issuance Calendar, a new data platform, provides carbon removal buyers and suppliers with standardized information on future offtake availability, indicative pricing, and project maturity. The platform was developed in collaboration with Relae, formerly Carbon Direct.
- The Carbon Issuance Calendar addresses the fragmentation and transparency problems of the voluntary carbon market by centralizing standardized project data and embedding our scientific diligence framework, built over 900 project reviews, giving buyers delivery-risk insight that no registry or marketplace offers today.
- The Carbon Issuance Calendar is an important early step, not the whole journey: it shows buyers what durable tonnes exist and allows them to compare projects with apples-to-apples data.
- Buyers can move from the Carbon Issuance Calendar into technical diligence, contracting, and project assurance with Relae’s advisory team. Suppliers can register to connect with buyers who are ready to engage.
Carbon Removal Project Data Has a Visibility Problem
If you're sourcing durable carbon removal credits, you may run into a familiar wall: project data scattered across dozens of developer websites, presented in inconsistent formats, with no easy way to compare one project against another. If you're a project developer, you face the mirror image of that problem: fielding individual requests for proposals, with no central place to showcase your available tonnes.
Get this wrong, and buyers may end up counting on carbon removal that never shows up - the delivery risk bugbear.
Between 2022 and 2024, high-durability engineered carbon removal made up just 2 percent of all carbon credit issuances. They remain in short supply, particularly the high-quality supply corporate buyers need. The gap is set to widen: our 2026 State of the Voluntary Carbon Market report found that more than 80% of the 2030 high-durability carbon removal projects are at risk of stalling and failing without additional offtake and financing commitments.
The Nasdaq Carbon Issuance Calendar, developed by Nasdaq in collaboration with Relae, offers an important first step toward addressing this information gap.
What Is the Nasdaq Carbon Issuance Calendar?
The Carbon Issuance Calendar is a centralized, accessible dashboard where carbon removal buyers and suppliers view standardized project data: future credit availability, indicative pricing, and project delivery status, all in one place.
The Nasdaq Carbon Issuance Calendar combines structured, developer-provided project data with project maturity assessment informed by Relae’s assessment framework and technical diligence. This helps users understand future CDR availability, indicative pricing, and potential project delivery risk through a single platform.
This expertise didn't appear overnight. It comes from sitting across the table with developers, stress-testing their science, mapping their delivery timelines against reality, and helping them show up to buyers as credible partners. The result is a track record that gives the framework embedded in the Carbon Issuance Calendar its depth. It's a starting point, built for buyers and suppliers to find each other on the basis of consistent, comparable information, using international class financial and information infrastructure.
How Buyers Should Use the Nasdaq Carbon Issuance Calendar
Today, if you're trying to procure durable carbon removal credits, you have no single place to start. You have to visit individual developer sites, request information through scattered channels, and compare projects that present data in entirely different formats before diligence has even begun. In many cases, you are comparing apples to oranges - different kinds of CDR projects with different durabilities, risks, and overall quality.
The Carbon Issuance Calendar provides a central starting point. You can view future credit availability, compare indicative pricing across projects, and begin assessing options without contacting each supplier one by one.
More importantly, the Carbon Issuance Calendar frames the data. Our scientists developed a delivery-oriented lens, built from reviewing over 900 carbon removal projects, drawing on the same rigor behind our Criteria for High-Quality Carbon Dioxide Removal, which we develop annually with Microsoft.
How Suppliers Reach Buyers Through the Carbon Issuance Calendar
If you're a project developer, the Nasdaq Carbon Issuance Calendar tackles visibility, one of the most persistent barriers to market access. You can list available tonnes, display indicative pricing, and reach a global audience of corporate and financial buyers at no cost.
The timing matters. Many first-of-a-kind engineered carbon removal projects are preparing to break ground and need bankable offtake agreements to secure financing before they can do so (a key aspect of CDR 2.0). Our analysis of approximately 140 high-durability carbon removal project developers found scale-up plans for 30 million tonnes of supply per year. Reaching that potential will take real demand: committed forward offtake, increased project equity investment, and access to lending.
Register now: you'll be positioned to connect to buyers actively looking to engage.
How Does the Carbon Issuance Calendar Differ From a Carbon Credit Registry or Carbon Removal Marketplace?
The Carbon Issuance Calendar solves a distinct, early-stage problem. It gives buyers and suppliers a centralized place to find each other and compare options against standardized information, something neither a registry nor a marketplace is built to do.
For a closer look at how registries differ and what you should weigh when navigating them, read our Navigating Carbon Credit Registries report.
Scientific Diligence Turns Visibility Into Confidence
Standardized data tells you what exists. Scientific diligence tells you what's worth pursuing.
Relae’s scientists do that work every day. Our experts apply rigorous pathway-specific criteria to live projects, evaluating delivery risk and status, and identifying where questions remain is the core of what we bring to the carbon removal market.
The Carbon Issuance Calendar puts an accessible version of that expertise at the top of the procurement funnel. It’s for everyone in the market - you don't need to be a carbon removal scientist to use it. This snapshot allows you to compare projects against each other, giving you a meaningful starting point before deeper diligence begins.
Want to go deeper on a specific project? Relae’s technical diligence team picks up right where the Carbon Issuance Calendar leaves off.
What Carbon Removal Projects Are on the Carbon Issuance Calendar Today?
The Carbon Issuance Calendar currently features engineered and hybrid carbon removal projects: direct air capture, biochar, enhanced rock weathering, and bioenergy with carbon capture and storage. These high-durability pathways offer permanence on the order of hundreds to thousands of years.
Many of these projects are at an inflection point: they’re ready to scale but dependent on committed offtake to unlock financing. The Calendar serves their needs, and the buyer’s needs, together.
Nature-based carbon removals have their own criteria and market dynamics. They may appear in a separate segment of the Carbon Issuance Calendar down the line.
From the Carbon Issuance Calendar to Completed Carbon Removal Procurement
If you're building or refining a carbon removal procurement strategy, the Carbon Issuance Calendar is the right place to start.
From there, you can choose to work with the Relae advisory team to support every later stage: technical diligence on specific projects, contracting and negotiation support, ongoing project assurance, and access to curated carbon credit sourcing. The Carbon Issuance Calendar surfaces the market; we help you navigate it, connecting you with the right developers, on the right terms, with the scientific confidence to move forward.
Moving from commitment to delivery takes structural change across the market, too—our CDR 2.0 white paper lays out the five pillars we see as essential to getting engineered and hybrid carbon removal projects built and delivering.