
Research, Analysis, & Point of View
Original insights from the Relae team on the forces reshaping power systems, GHG emissions, environmental markets, nature, and the capital and policies behind them.
In-Depth Research
Criteria for High-Quality Low Carbon Fuels 2026
Community Opposition to AI Data Centers: Lessons Learned
Carbon Capture for Gas-Fired Power Generation
Blogs
Navigating Scope 2 Accounting Changes
Key Takeaways
- Voice your opinion: The Greenhouse Gas (GHG) Protocol is updating its scope 2 guidance with final standards expected in 2027, which may require hourly and regional matching of renewable energy certificates (RECs), potentially changing how companies claim their electricity-related emission reductions.
- Act now to secure renewable energy contracts: Companies should move forward with their scope 2 climate commitments today. The GHG Protocol is expected to grandfather in contracts entered into under existing rules.
- Beyond the megawatt hour (MWh): High-impact forward REC contracts measure impact beyond the current annual MWh match requirement, maximizing near-term carbon abatement and social impact for every dollar invested.
Why 2027 Rule Changes Matter for 2030 Targets
Companies racing to meet 2030 climate targets face converging pressures: surging electricity demand, constrained renewable energy supply, and scope 2 accounting rules that could undergo significant changes by 2027.
In a recent webinar, power market experts from Relae (formerly Carbon Direct) and Ever.green explored these changes. Patti Smith, former Electricity Decarbonization Lead at Relae; Julia Millot, Senior Power Decarbonization Manager at Relae; and Liz Pearce, Chief Revenue Officer at Ever.green, unpacked what's changing and how companies can respond.
The stakes are high. Based on GHG Protocol Scope 2 Public Consultation materials, companies may need to match RECs to electricity consumption on an hourly and locational basis as early as 2028. However, we expect the GHG Protocol to grandfather forward REC contracts signed before new rules take effect, enabling companies to continue advancing toward 2030 targets amid rule uncertainty.
Big Changes to the Power Grid
The US power grid is entering sustained demand growth for the first time in decades. "Over the next five years, data centers alone are going to put [the equivalent] of four New York Cities onto the grid," Smith explains, citing forecasts that project around 200 terawatt hours of new data center load through 2030 (i.e. cumulative energy consumption). That demand growth also shows up in near-term grid planning. NERC's January 2026 Long-Term Reliability Assessment forecasts North American summer peak demand rising by 224 gigawatts—a 24% increase—over the next decade, with new data centers cited as the primary driver. These figures highlight that peak capacity and total energy consumption are directly impacted by the data center boom.
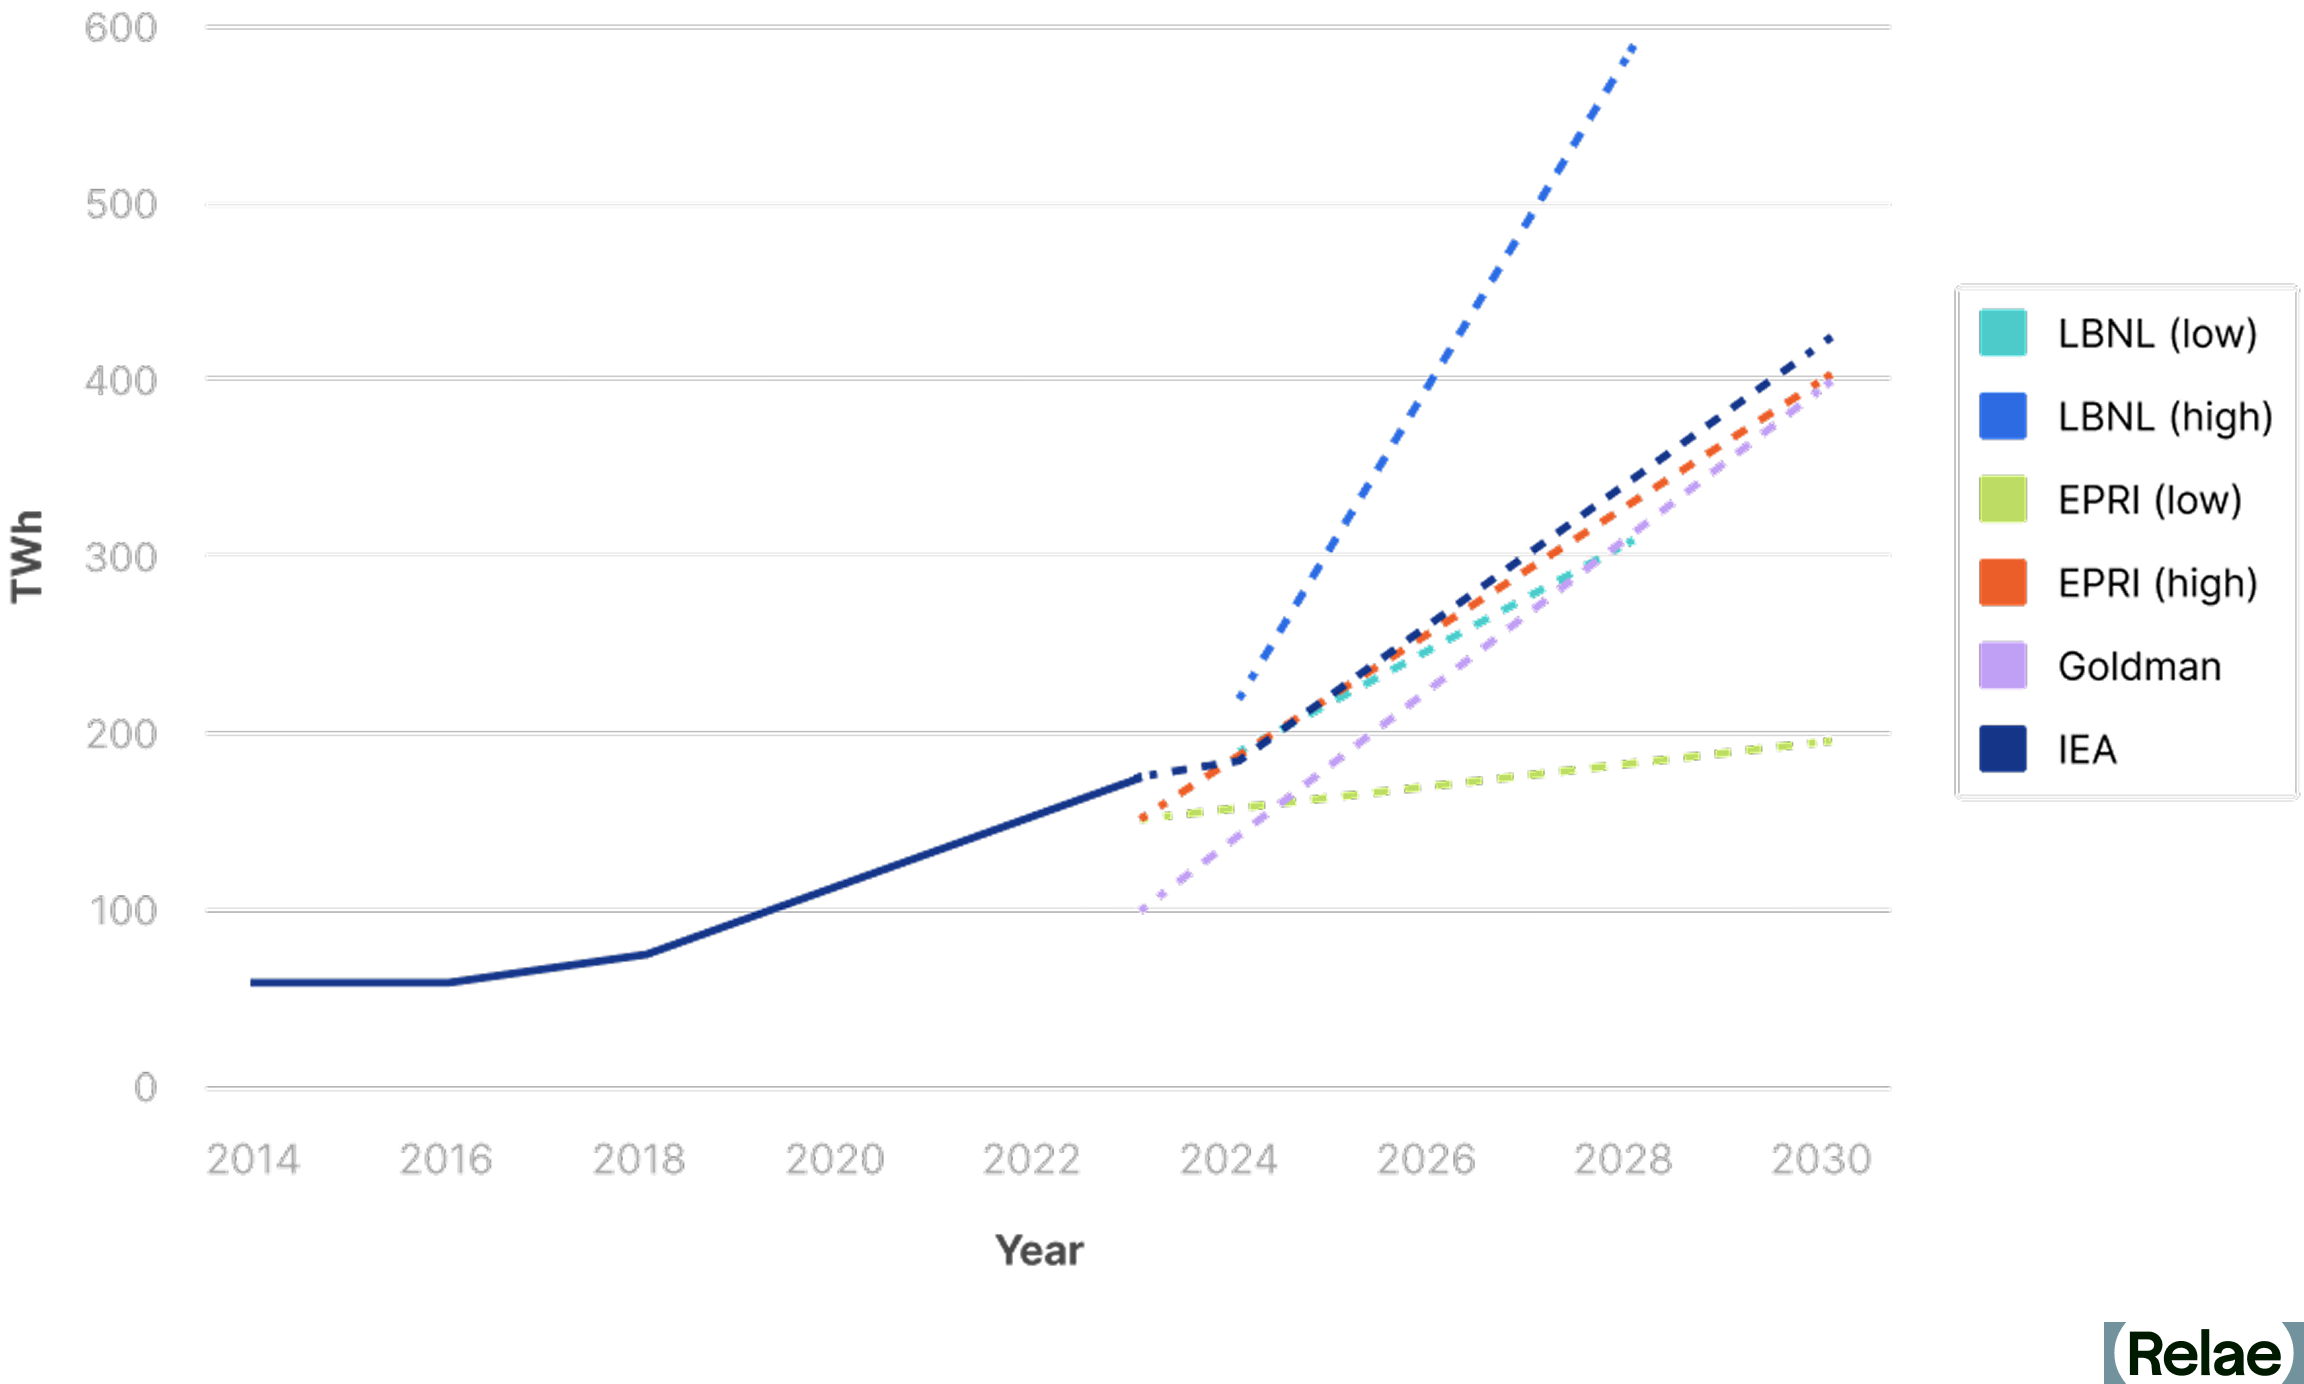
Meanwhile, new renewable projects face headwinds. Smith points to interconnection queue delays: "Solar and battery projects are taking three to five years from initial request to operation." At the same time, clean energy tax credits, which were driving wind and solar expansion, have been curtailed. New restrictions on foreign supply chain materials, which are critical to renewable project development, are further hampering the development of new clean electricity projects.
The result: Power demand is rising while new renewable electricity supply is getting throttled.
The Messy Reality of Electricity Emissions Accounting
Quantifying the emissions from an individual power plant is straightforward. Allocating those emissions to the companies that consume power is far more complicated.
Grid-supplied electricity comes from many generators that shift constantly, sometimes even second to second. Companies can’t directly measure emissions from a grid-connected load because the generators serving it continuously change.
Without direct measurement, companies need rules to estimate the emissions they are responsible for. The GHG Protocol’s Scope 2 Guidance provides that framework, establishing how companies estimate electricity-related emissions and how to reduce them through renewable energy purchases.
How Companies Currently Claim Renewable Energy
For the past decade, companies have used renewable energy purchases to achieve their scope 2 emission reduction goals. The most widely used mechanism is the REC, each representing clean energy attributes for one MWh of renewable electricity generated and added to the grid. Currently, when a company buys RECs equal to its annual electricity consumption, it can claim 100% renewable electricity. Under current rules, companies can use purchased renewable energy from anywhere in North America and apply it to any load in North America at any time during the year.
Importantly, emissions from different power grids vary widely across North America depending on time of day, time of year, and the power grid makeup.
This flexibility allows companies to match a REC from a clean grid against electricity consumption from a dirtier one, creating a potential mismatch between emissions claimed and actual emissions avoided. This gap has drawn scrutiny, contributing to the motivations for the scope 2 rules rewrite.
What's Changing in GHG Protocol Scope 2 Accounting?
On October 19, 2025, after years of consultation, the GHG Protocol released two separate proposals for public consultation:
1. Scope 2 changes: Moving away from annual REC matching to an ‘hourly and regional’ REC matching requirement.
2. New consequential methodology: A new approach to estimating emissions caused by a company’s consumption and avoided by its renewable energy contracts.
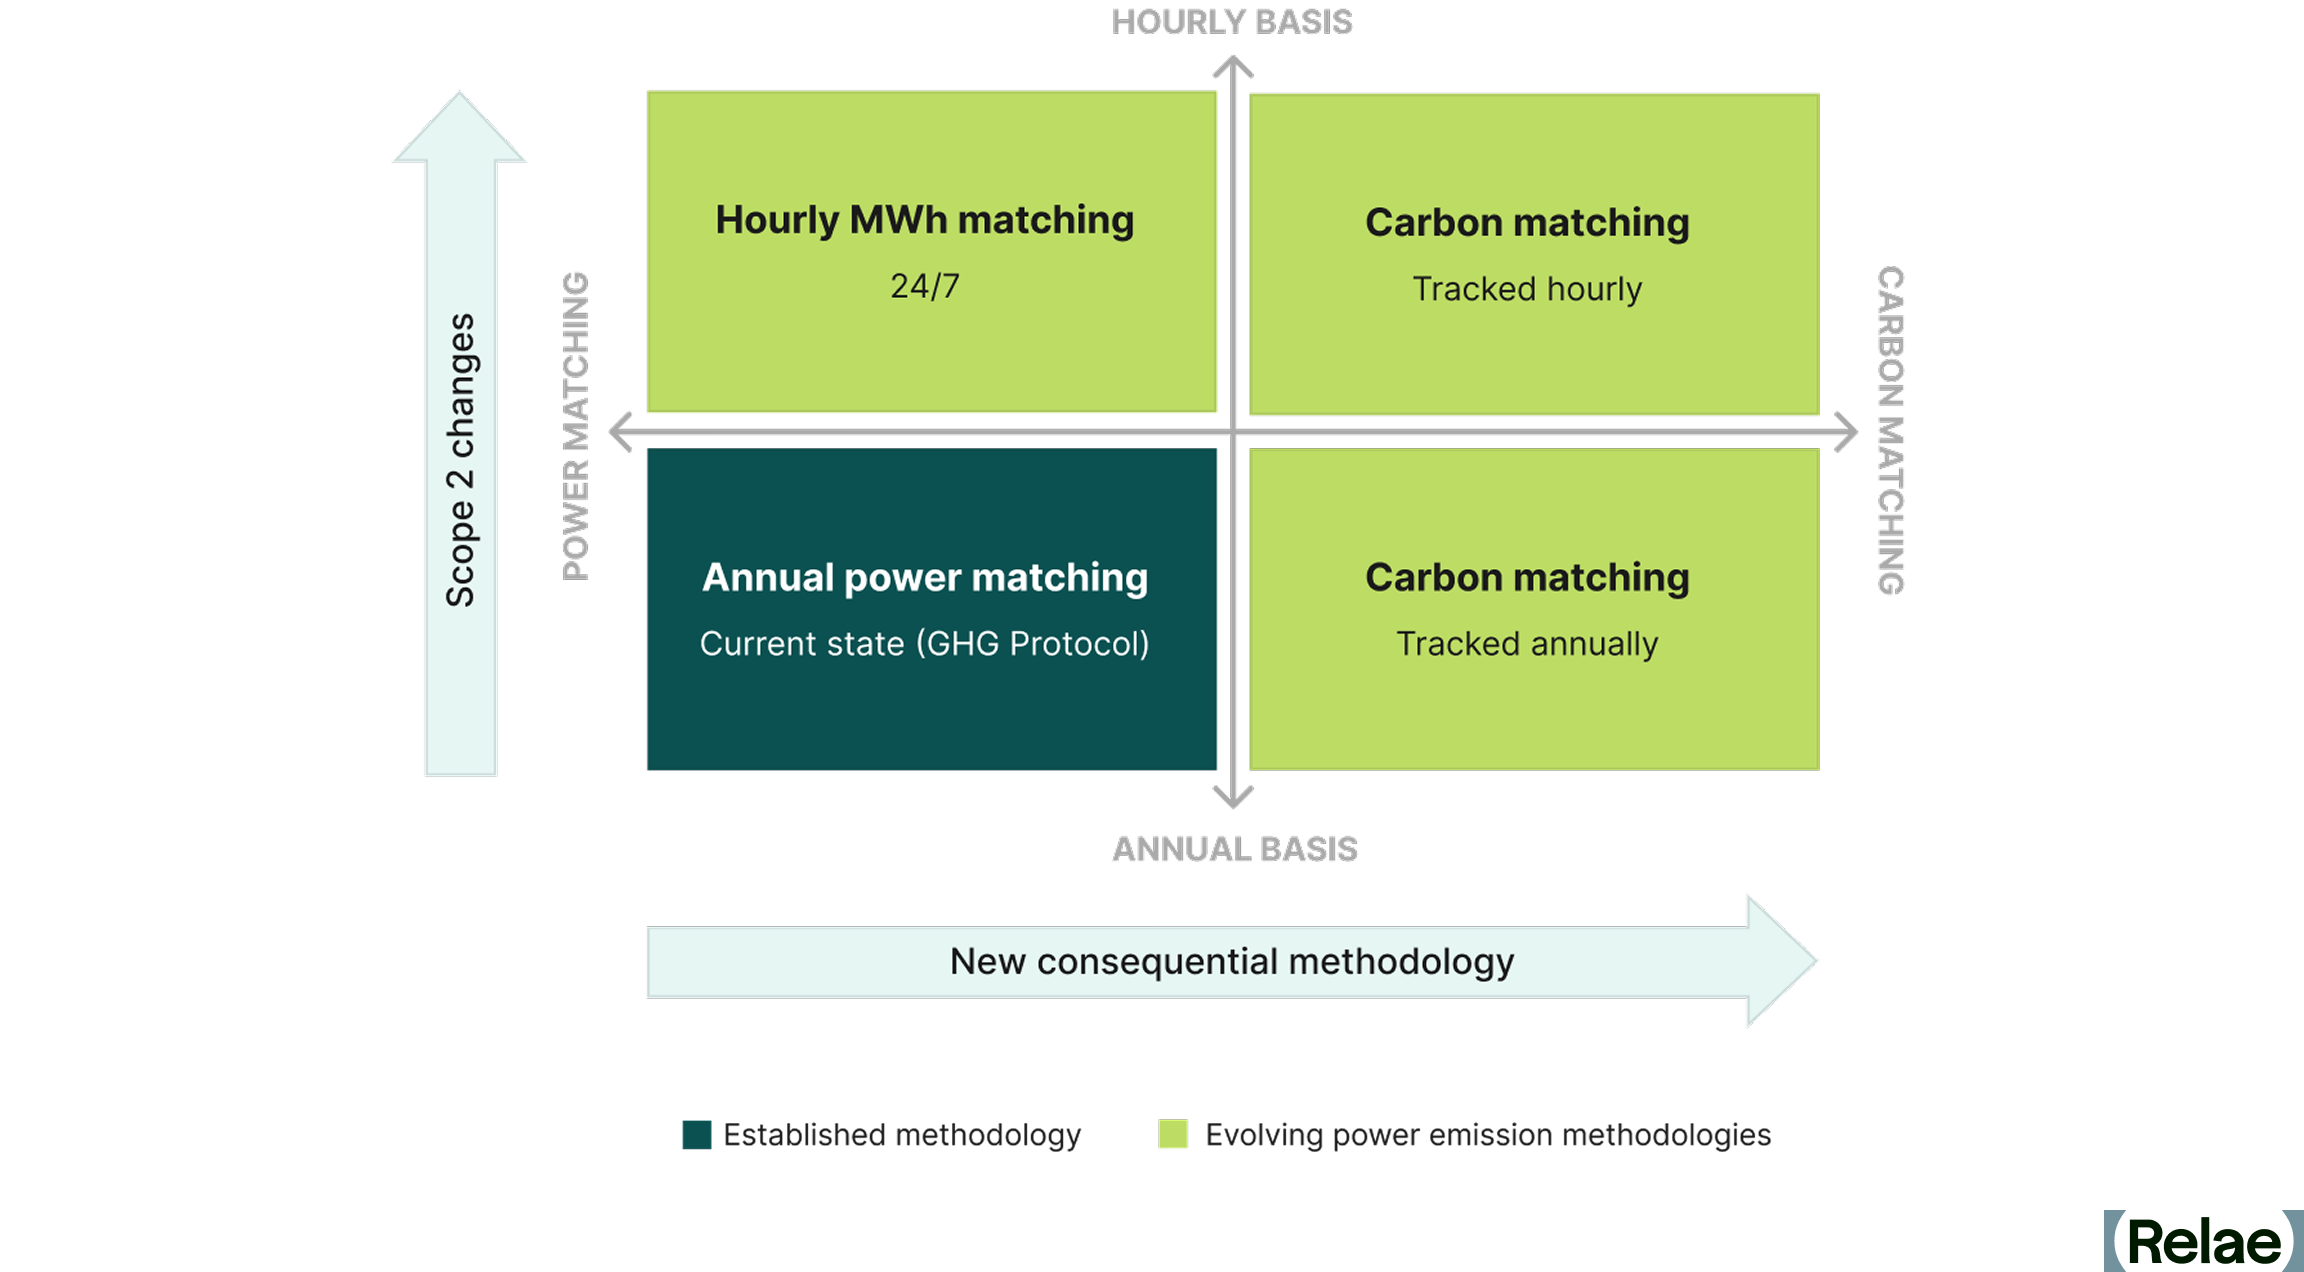
The hourly matching proposal (24/7): Companies would match RECs to consumption hour by hour within the same grid region, rather than annually across any North American grid.
"A REC generated on a Texas wind farm would not be able to be used for electricity consumed in New York," Millot explains.
The consequential approach: This proposes a carbon matching methodology, which estimates emissions caused by a load and estimates the emissions a renewable project displaces.
"Projects in the Carolinas are avoiding 0.6 or 0.7 tons of CO2 per megawatt hour, whereas a California project is probably closer to 0.2 or 0.3," Smith explains.
Projects in the Carolinas deliver more than double the climate impact per REC under the consequential rules. In this methodology, the load and generator do not need to be located in the same region.
While the proposed rules and new methodologies work through the public consultation process, it will be important for companies to start to anticipate the potential impacts on their climate goals and strategies.
Timeline for Scope 2 Accounting Changes
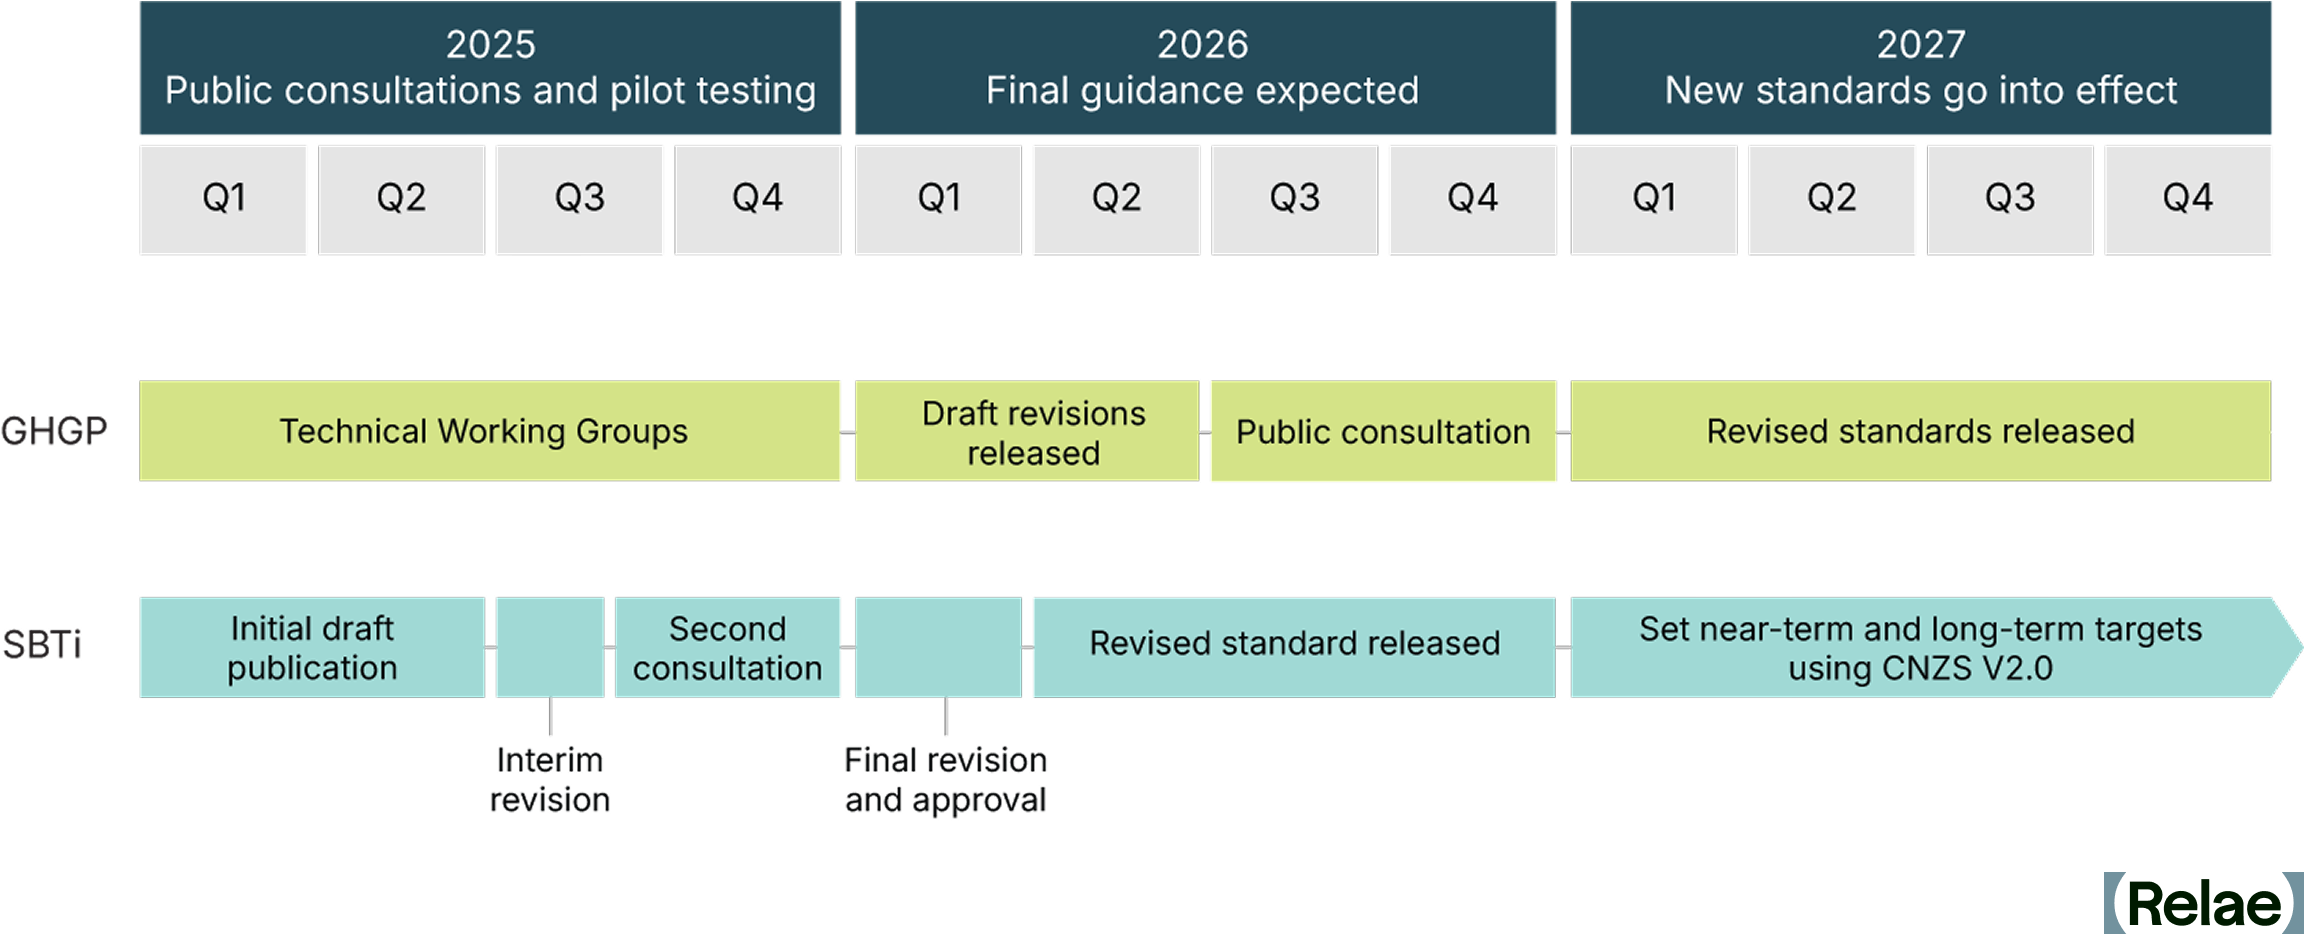
Both the Scope 2 and Consequential Electricity-Sector Emissions consultations closed January 31, 2026, after GHG Protocol extended the original deadline. The GHG Protocol is analyzing feedback with a second consultation and final standards expected by 2027, though the exact timeline is still being finalized.
Companies are encouraged to participate in the public consultation. The GHG Protocol is asking for comments on critical questions, such as:
- Should proposed rules apply to energy consumers of all sizes?
- Which geographical boundaries should be used for locational matching?
- Should existing contracts be grandfathered in?
The public consultation period is an opportunity to shape the standards that will govern electricity-related emission accounting for years to come.
Why Act Now Instead of Waiting
With final rules still in development, companies with scope 2 emission reduction goals or science-based targets face a decision: Wait for clarity or act now.
Several factors favor early action:
- Inclusion of legacy contracts. "There are a lot of indications from the committees that existing long-term contracts will be grandfathered in," Pearce notes. The draft considers a legacy clause that would allow organizations to apply pre-existing contractual agreements, even if they don’t comply with new rules.
- Throttled renewable project development. Interconnection delays for new renewable energy projects, elimination of clean energy tax credits by 2028, and limitations on foreign materials needed to develop renewable energy project components mean that new REC supply may be harder to access in future years.
- Renewable project development timelines. "There's generally a lag, sometimes six to 18 months" between contract signing and project operation, Pearce explains. That means even if you sign today, the RECs won’t be generated for up to 18 months from the signing date.
- High-impact opportunity. Through careful project selection, renewable energy investment can go beyond the annual energy match requirement and incorporate additional impactful metrics, such as higher avoided emissions and positive social impacts.
Renewable Energy Buying Options for Companies
Previously, companies have been able to buy renewable energy through the following three paths; however, they all come with their own tradeoffs.
Traditional REC Buying Options
- REC spot markets make up most corporate renewable procurement. However, they mainly come from existing projects rather than financing new development, which is critical to expanding renewable energy supply to meet rising decarbonization needs.
- Virtual power purchase agreements (VPPAs) are highly impactful but require large power loads and the ability to manage long-term financial risks. Unavailable to most companies.
- Utility green tariffs have limited availability throughout the US (depending on the utility(s) that serve your load) and vary in quality.
Alternative REC Procurement Approach
For companies that want to go beyond the REC spot market and are not large enough to pursue a VPPA, there’s an alternative procurement option available: a high-impact forward REC contract. These multi-year contracts commit to purchasing RECs from specific new projects before they're built, providing the upfront revenue certainty developers need to secure financing at a fraction of the scale and complexity of a VPPA.
Comparing Renewable Energy Procurement Options
The Path Forward
Despite rapidly increasing grid demand, renewable project headwinds, and changing accounting rules, companies can still meet 2030 scope 2 goals.
What companies should do now:
- Watch for the next round of GHG Protocol consultation on Scope 2 revisions
- Evaluate forward REC contracts to lock in terms before rule changes
- Prioritize high-impact RECs that deliver measurable climate and social benefits
Carbon Direct (Now Relae) Acquires Pachama November 2025
Carbon Direct acquires Pachama
We founded Carbon Direct in 2020 with a clear mission: to drive climate impact through science-based carbon management. Today, we are pleased to announce exciting progress in that mission. Carbon Direct is acquiring Pachama, the leading provider of digital tools to ensure integrity in the voluntary carbon market (VCM). Pachama’s digital platform for forest carbon project monitoring, reporting, and verification (MRV) will become part of Carbon Direct, advancing our science-based mission.
I have known Diego Saez Gil, Pachama's co-founder and CEO, since Carbon Direct's founding. Like Carbon Direct, Pachama is fundamentally an evidence-driven organization, translating the latest science into actionable insights for clients. Over the last few years, Pachama has developed an advanced technology platform and ecosystem to catalyze a new generation of nature-based carbon projects and push the carbon markets to evolve.
Pachama’s tools address a critical need in climate action. Its digital MRV capabilities bring unprecedented transparency and rigor to forest carbon projects at a time when the market urgently needs both. Our shared emphasis on technical excellence, collaboration, and scale makes this acquisition a natural fit - for our companies and for the broader carbon market.
Carbon Direct will now deliver an even more comprehensive solution for high-quality carbon credit development, assessment, and management grounded in science, enhanced by technology, and designed for transparency and trust. This acquisition positions Carbon Direct to:
- Advance quality and integrity across the VCM through continuous, data-driven project evaluation.
- Enhance transparency for buyers and project developers through integrated digital MRV tools and sophisticated advisory insights.
- Expand access and scale of nature-based carbon solutions to meet growing corporate and regulatory demand for verifiable climate impact.
- Accelerate innovation at the intersection of science, technology, and nature, supporting the transition to a net-zero economy.
For our clients, this means more sophisticated digital experiences, faster project evaluations, and deeper insights into carbon credit integrity. Project developers will benefit from streamlined monitoring and verification that helps quality projects scale more efficiently.
The talented team at Pachama has built exceptional tools, and I'm thrilled that many of their team members will be joining us. The mutual respect is strong, based on a shared passion for climate science and delivering high-impact work to clients.
As Diego said, "We're incredibly proud of what the team at Pachama has built. Our technology brings transparency and integrity to forest carbon projects at scale. As we explored options for our next chapter, Carbon Direct stood out for its unwavering commitment to scientific rigor, its reputation as the most trusted voice in carbon management, and its rapid growth. This is the coming together of two mission-driven teams that can accelerate impact far beyond what either could achieve alone. I'm excited to see the technology of Pachama reach new markets as part of a company that shares our dedication to quality and our vision for scaling equitable climate solutions."
I am excited to welcome Diego and the Pachama platform to Carbon Direct.
Jon Goldberg, Founder & CEO, Carbon Direct (now Relae)
Reconciliation Bill Dramatically Shifts the Clean Energy Landscape
Key Takeaways
- Accelerated phase-out schedules for key clean energy and decarbonization tax credits will shorten the runway for project development, which could stall or cancel projects.
- Urgency is paramount, and qualified projects should expedite construction and operational timelines to secure eligibility for existing credits.
- A more complicated policy landscape requires concerted effort to navigate, including with the support of policy professionals.
Reconciliation Rolls Back Much of the IRA
On Friday, July 4, 2025, the President signed a sweeping reconciliation bill, H.R. 1, that will add at least $3.3 trillion to the national debt and marks a pivotal, contentious moment for US clean energy policy. The law was enacted through the complex legislative process known as budget reconciliation, requiring only a simple majority of votes in the House and Senate. The new law substantially modifies or terminates many of the Inflation Reduction Act of 2022 (IRA)'s clean energy incentives and has extensive implications for the economic viability of American energy and manufacturing projects.
In the Senate, three Republicans crossed party lines to vote against the bill, requiring Vice President JD Vance to break the tie. In the House, only two Republicans broke ranks to vote against final passage. While some of the more complex provisions of the bill, such as new foreign entity of concern (FEOC) restrictions, will require more time to fully assess, we've prepared a rapid run-down of key alterations to IRA incentives for carbon management, hydrogen, and clean fuel technologies.
What Is the 2025 Reconciliation Bill?
While the 2025 reconciliation bill is staggering in length, scope, and severity, containing provisions to cut Medicaid, reduce nutrition assistance, raise the debt limit, and cut taxes primarily for the wealthy, some of the most drastic sections of the bill modify tax incentives and other public funding for clean energy and emissions reductions.
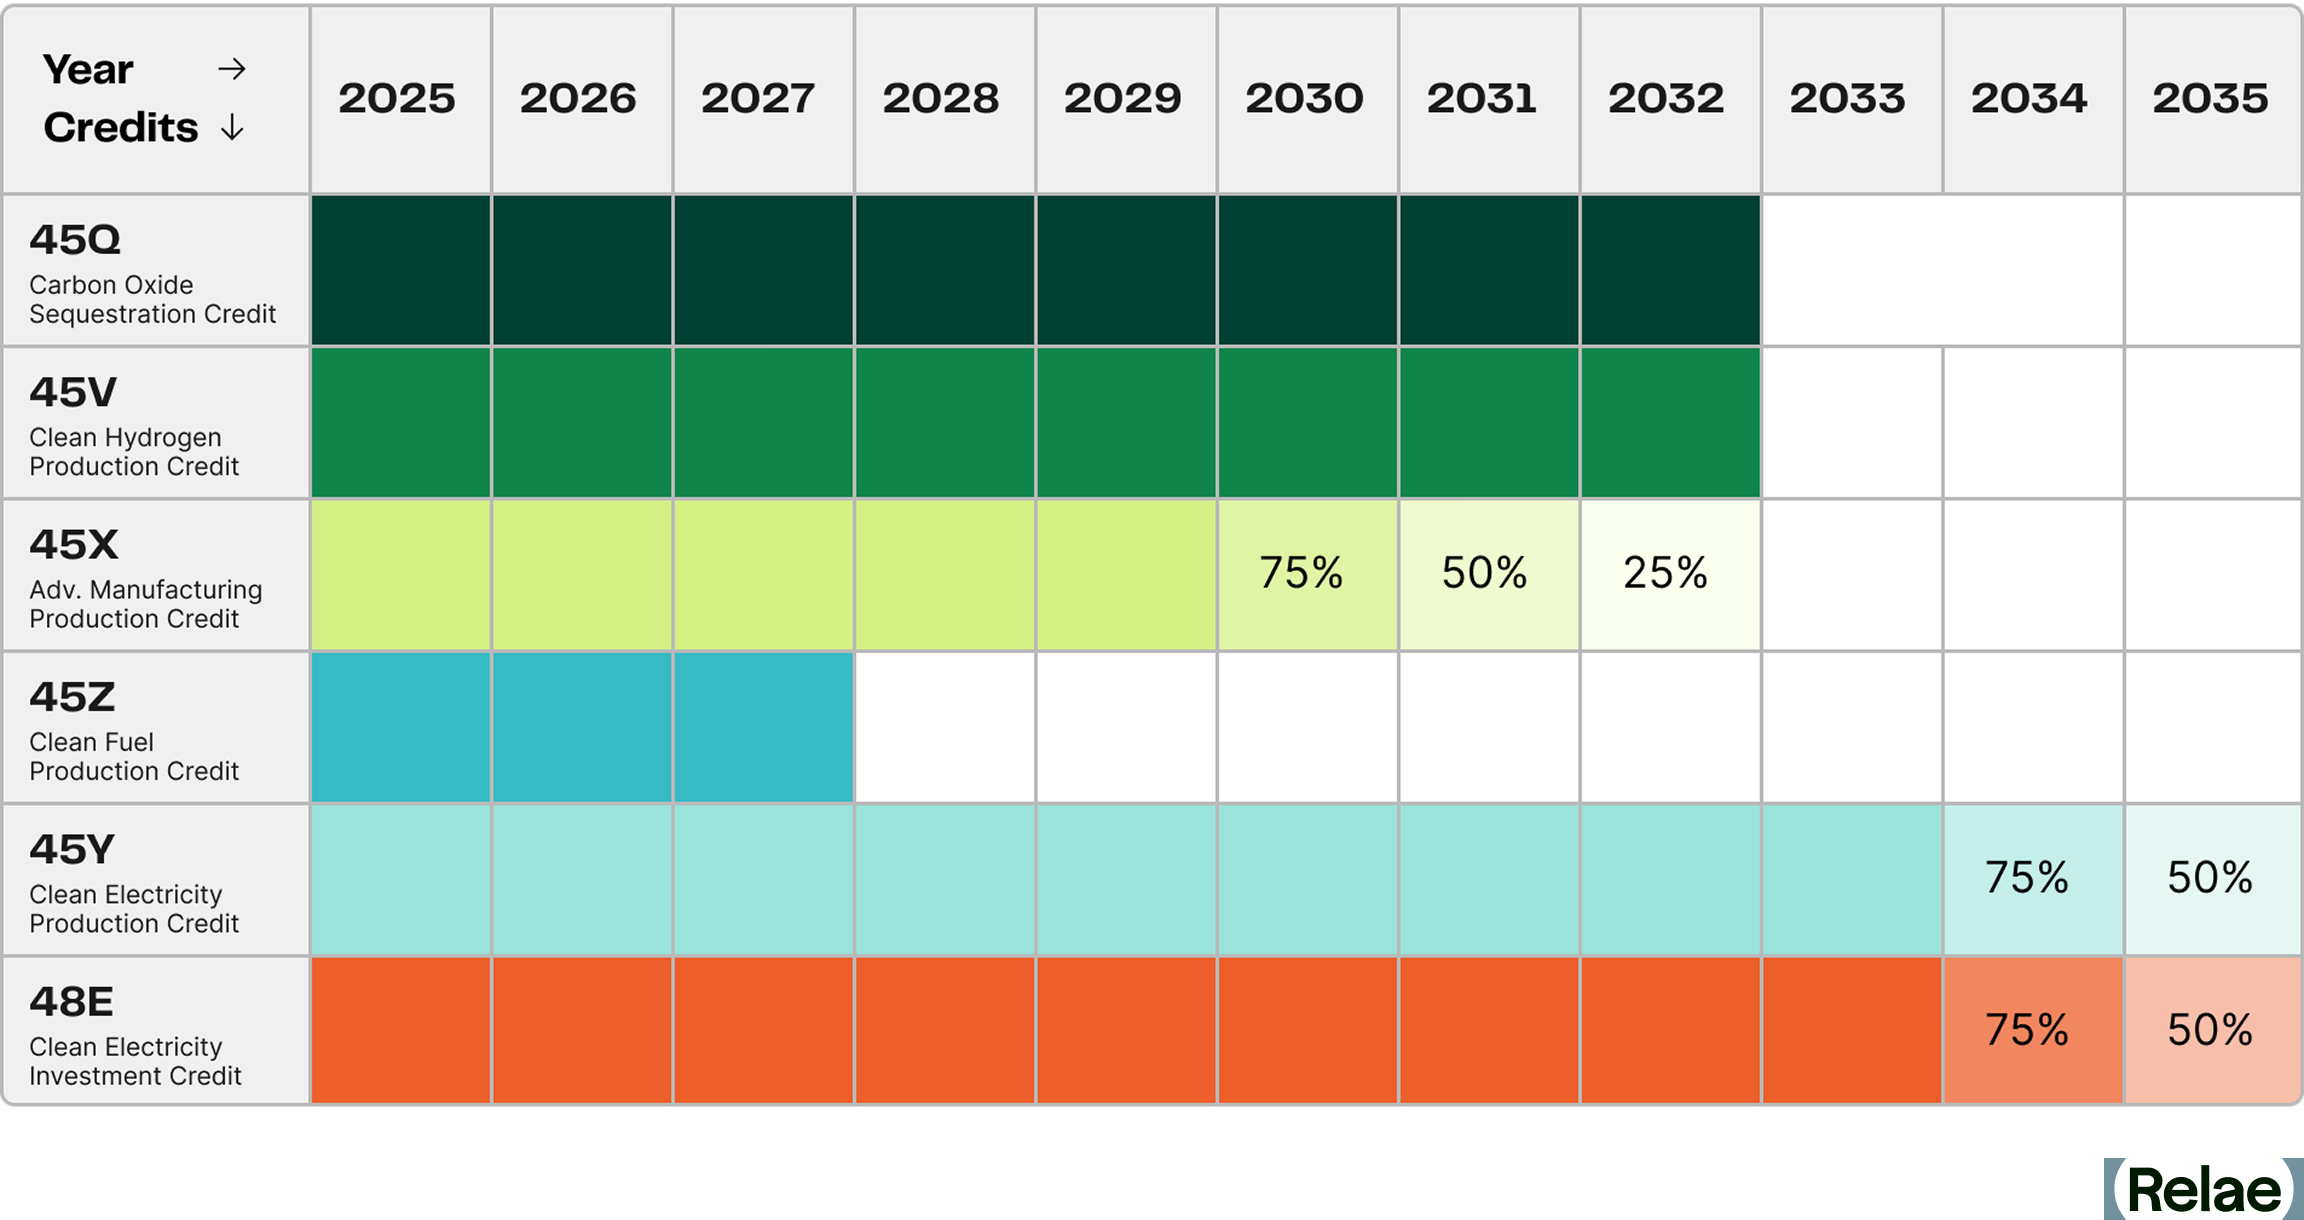
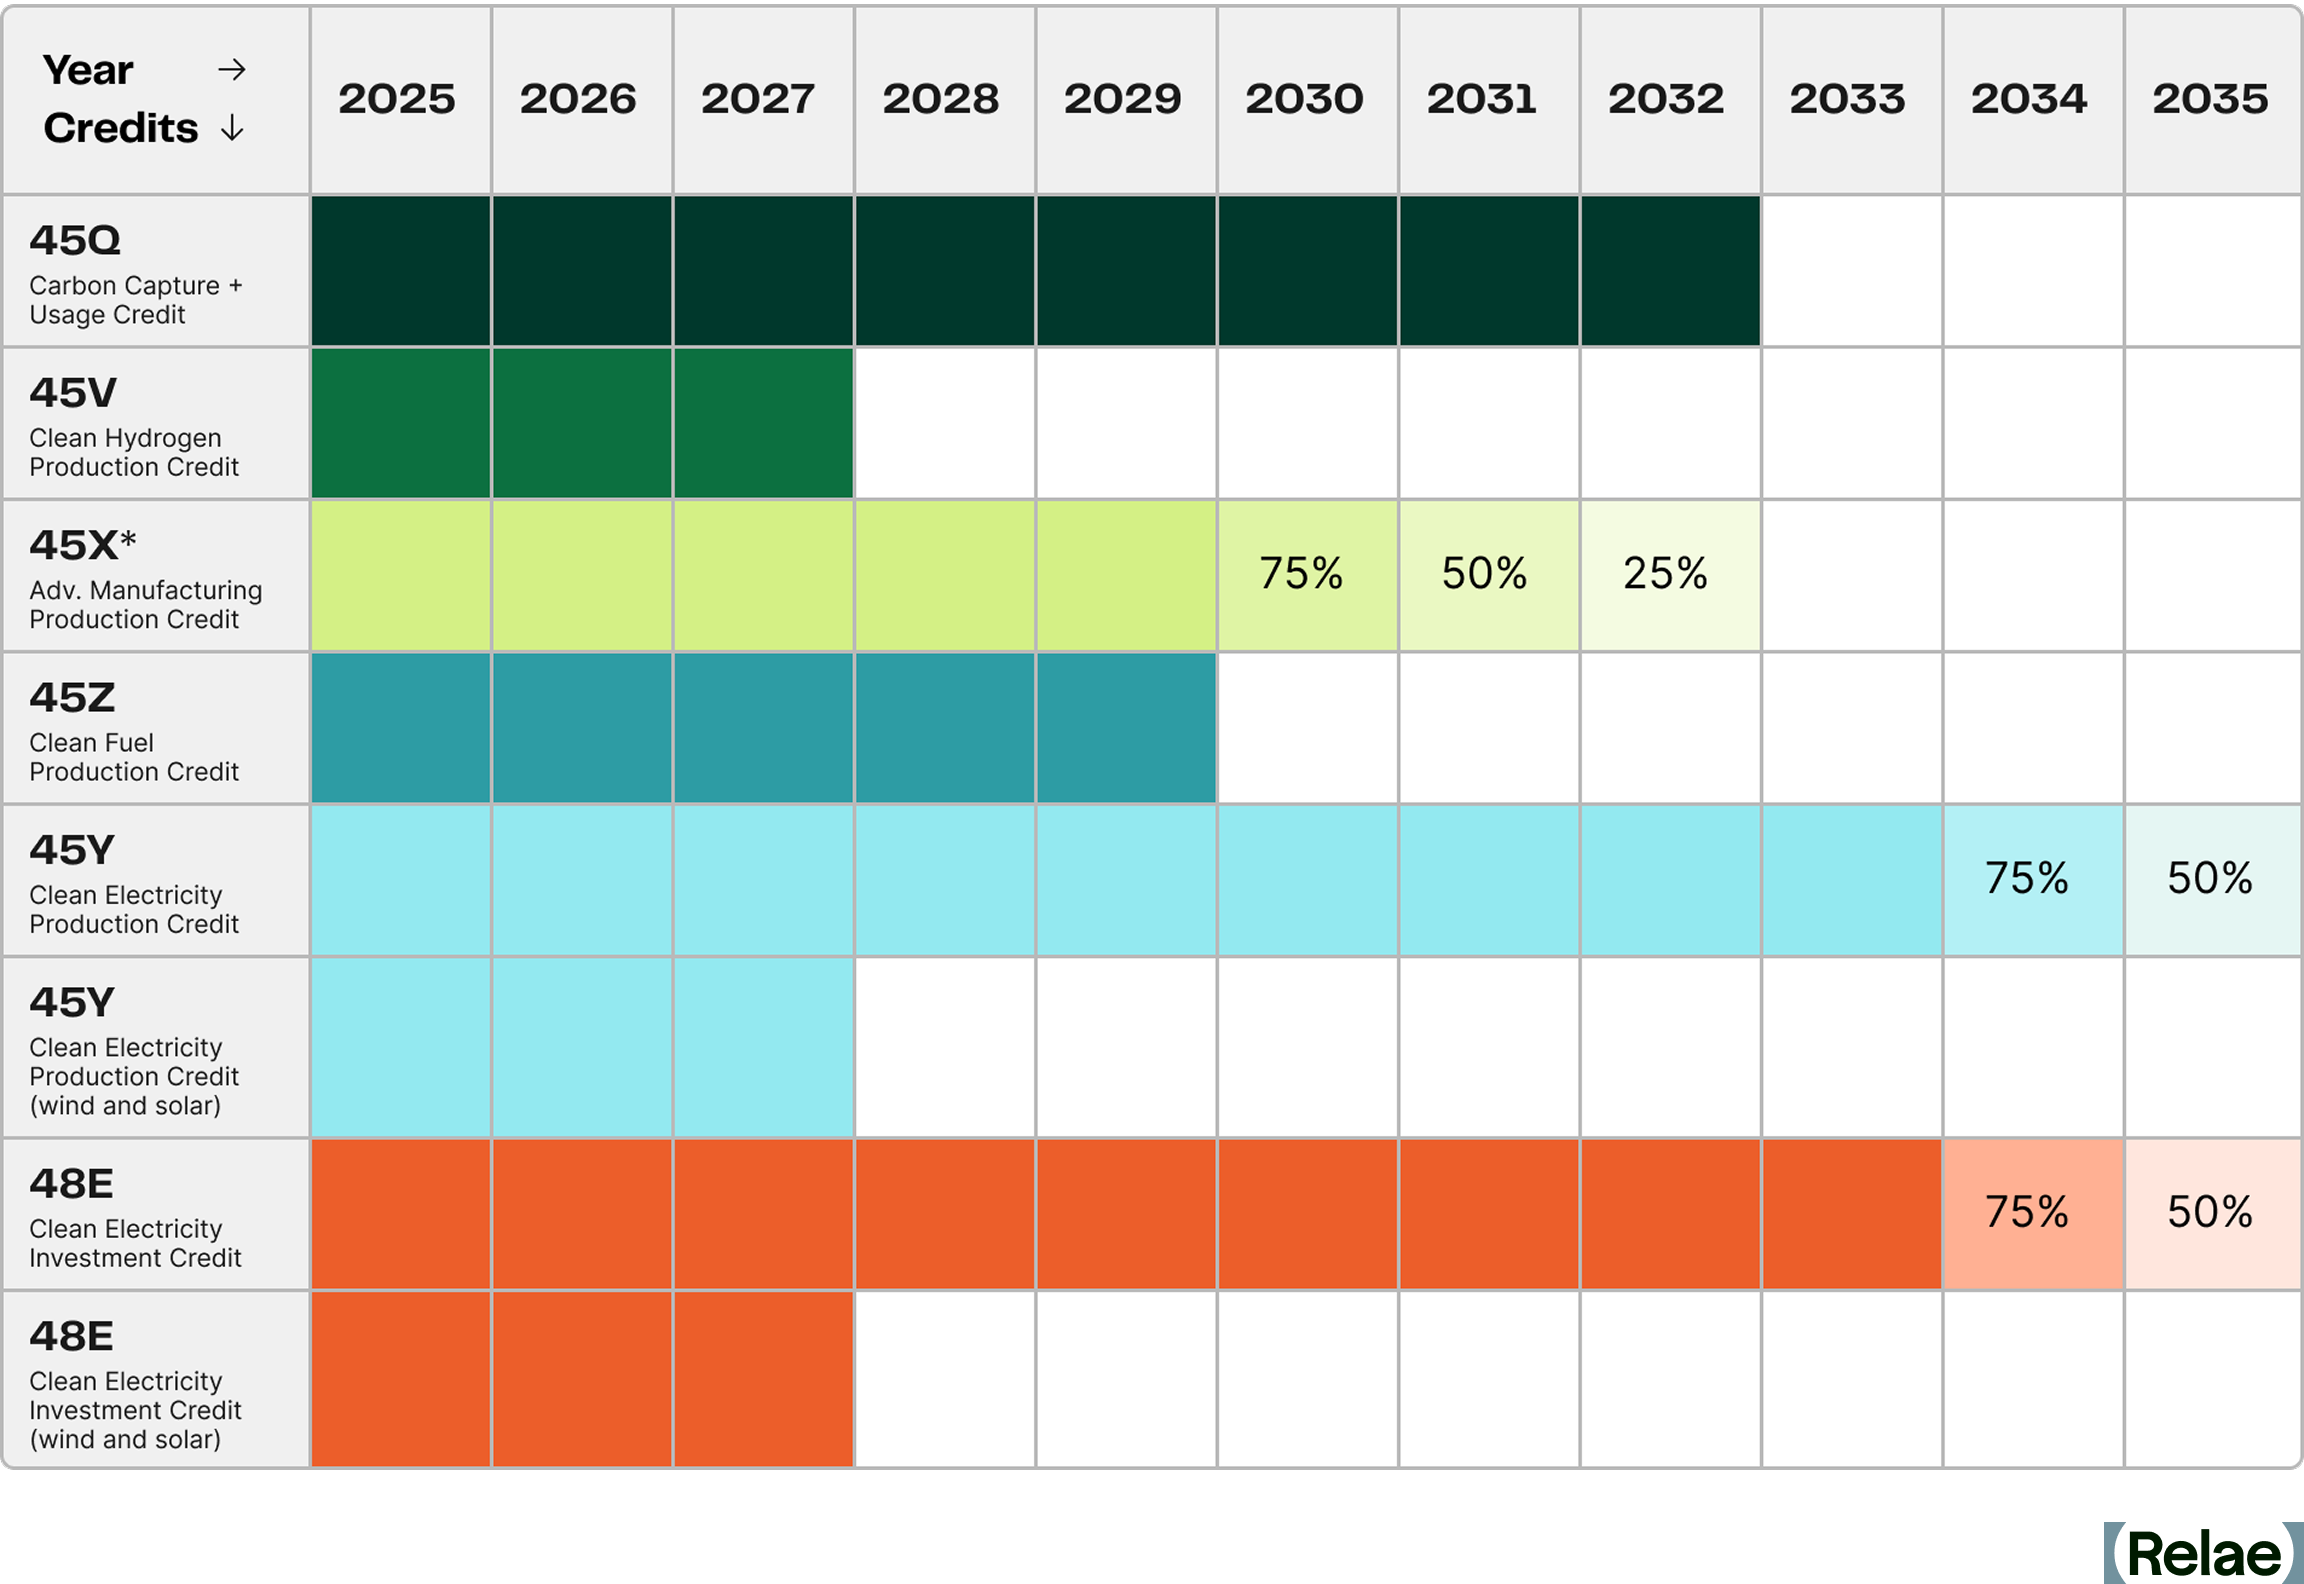
Many of the incentives to deploy clean energy that were created or enhanced under the IRA will be phased out early or repealed altogether. Credits with accelerated phase-out schedules include the newly created 45Y clean electricity production tax credit, which will no longer support wind or solar projects after 2027, and the 45V credit for clean hydrogen production for which projects must now commence construction before Jan 1, 2028 (moved up from Jan 1, 2033).
Since the passage of the reconciliation package, there has been active litigation on several provisions, including an order from a federal district court to vacate IRS guidance that would have prohibited certain wind and solar projects from securing safe harbor. The table below provides a detailed breakdown of key changes to major tax credits between the original IRA, the draft that moved through Committees in the House, and the final text that was passed by the Senate and signed into law.
Major Tax Credit Changes in the Reconciliation Law
How FEOC Restrictions Threaten Clean Energy Supply Chains
Many clean energy tax credits include ambiguous language restricting projects connected to FEOC, complicating supply chains and creating new problems for developers of clean energy projects. The law also introduces a complex matrix of new definitions, such as "Prohibited Foreign Entities," which includes both "Specified Foreign Entities" and "Foreign-Influenced Entities."
The FEOC restrictions embedded in the reconciliation bill represent a seismic shift for clean energy developers. These new rules, designed to limit the influence of Covered Nations (China, Russia, North Korea, and Iran), will disqualify projects from receiving tax credits if they source components, minerals, or intellectual property from entities tied to these nations. In other instances, the partial ownership or investment of an entity with financial ties to a Prohibited Foreign Entity may also disqualify a project from qualifying for tax credits.
This FEOC language matters for developers and investors because of the resulting global supply chain disruptions, investment uncertainty, and compliance burdens. The clean energy sector is deeply reliant on global supply chains, especially for solar panels, batteries, and wind components, industries where China currently dominates. The IRA intended to counter this by moving the manufacturing and production of these supply chains to the US. Project developers must now thoroughly review their supply chains and capital providers, and may need to quickly pivot to compliant resources.
In February 2026, the IRS released interim guidance on the FEOC provisions to provide safe harbor guidance for clean energy manufacturing, investment, and production credits to help taxpayers gauge whether material assistance was provided by a prohibited foreign entity.
Other Major Rollbacks to the IRA
Beyond clean energy tax credits, the reconciliation package also repeals and rescinds many other IRA provisions. This includes a full rescission of all unobligated IRA appropriated balances at the Department of Energy's Loan Programs Office, and several other programs, including:
- The Tribal Energy Loan Guarantee Program
- Greenhouse Gas Reduction Fund
- Transmission Facility Financing
A complete list of rescissions of energy-related funding is outlined in Sections 60001-60024 and 50402 of the law. These rescissions represent tens of billions of dollars in lost climate investments made under the IRA, which would have provided funds to state, local, and Tribal governments, federal agencies, non-profits, and commercial project developers to reduce emissions and update critical infrastructure.
What Can Project Developers and Other Companies Do?
Developers will need to act quickly to meet updated commence construction and place into service requirements, though circumstances are technology specific (e.g., safe harbor updates to 48E and 45Y). Tax credits generally have advanced commence construction and operational deadlines, resulting in a strong first-movers advantage. Companies should also review their supply chains and revise equipment and material procurement sourcing plans as necessary to address restrictions presented in the reconciliation bill.
An executive order from President Donald Trump issued on July 7 will further complicate how companies proceed. In the EO, the President directs his administration to "strictly enforce the termination of […] 45Y and 48E […] for wind and solar facilities." The Administration will likely issue extremely strict interpretations of "commence construction" clauses and FEOC requirements in forthcoming tax credit guidance issued by the Treasury Department, though these moves are quite likely to face litigation.
The new restrictions being proposed by the Administration, including specific details on FEOC, qualified equipment, commence construction, and other reporting requirements, will require additional guidance from the IRS and provide an opportunity for engagement through public comment. It is important that impacted companies weigh in during these public comment periods, not only to help inform and influence the final rules issued by the Administration, but also to build an administrative record that could support litigation efforts to strike down the final rules.
Staying Ahead of Policy Changes
Given the rapidly shifting landscape of energy policy, it's paramount that companies stay abreast of the latest changes and dedicate resources to understanding how they may be affected. Policy professionals, including the experts at Relae (formerly Carbon Direct), can support organizations as they engage in the regulatory process, anticipate and prepare for new legislation, and navigate the requirements to access essential tax credits and incentives. Even under new constraints, expert guidance can help maximize impact and minimize disruption.
Frequently Asked Questions
How does the reconciliation bill change the timelines for major clean energy tax credits?
Most clean energy tax credits saw their windows shortened relative to the original IRA:
- The 45Y and 48E credits now terminate entirely for wind and solar facilities placed in service after December 31, 2027, with a separate phase-down (75% in 2034, 50% in 2035, 0% after) for other technologies.
- The 45V clean hydrogen credit's "commence construction" deadline moved from December 31, 2032 to December 31, 2027.
- The 45Z clean fuel credit now ends on December 31, 2029 (versus 2027 in the original IRA, but bonuses for SAF have been removed and new emissions-calculation methods favor corn ethanol).
- Notably, the 45Q carbon capture credit saw little change and retained transferability, with credit values for enhanced oil recovery and utilization raised to match secure geological storage.
What are the FEOC restrictions, and why do they matter so much for developers?
FEOC ("Foreign Entity of Concern") restrictions disqualify projects from tax credits if they source components, minerals, or intellectual property from entities tied to China, Russia, North Korea, or Iran. Even partial ownership or investment ties to a "Prohibited Foreign Entity" can trigger disqualification. The definitions are complex and still being clarified through IRS guidance, meaning developers need to review supply chains and capital providers carefully and may need to pivot to compliant sourcing.
What should project developers do now in response to these changes?
Developers should move quickly to meet the earlier "commence construction" and "placed in service" deadlines, since credits now benefit early actors. This includes reviewing and potentially restructuring supply chains and procurement plans to address FEOC restrictions, and closely monitoring forthcoming IRS/Treasury guidance.
What Is Biochar? A Carbon Removal Solution Gaining Ground
Key Takeaways
- Concrete and steel contribute 13% of global CO2 emissions. These materials represent substantial scope 3 emissions for companies that are building new infrastructure, including data centers.
- Low-emission alternatives and production technologies are nascent and not yet widely deployed.
- Environmental attribute certificates (EACs) are an innovative solution that can stimulate manufacturing of sustainable commodity materials and overcome market barriers to direct physical procurement.
- Relae (formerly Carbon Direct) and Microsoft developed criteria to guide Microsoft’s high-quality EAC procurement, accelerate decarbonization, and catalyze market expansion for decarbonized materials across supply chains.
- These criteria cover seven key areas: qualifying conditions, social harms and benefits, environmental harms and benefits, additionality and baselines, catalytic impact, verifiability, and leakage.
A Vision for Low-Carbon Concrete and Steel
Concrete and steel are essential for modern construction, but are carbon-intensive. Combined, they account for approximately 13% of global carbon dioxide (CO2) emissions. As the demand for data centers and infrastructure development continues to grow, so do the embodied emissions from concrete and steel. There is an urgent need to decarbonize these sectors so that construction of new facilities remains consistent with climate commitments.
However, the markets for low-carbon concrete and steel are still in their infancy. Market barriers such as low production volumes, contracting complexity, geographic concentration of supplies, and long-distance transportation limit buyers’ ability to directly procure low-carbon building materials. As buyers and sellers overcome these barriers, the market for low-carbon building materials will mature, giving producers the confidence to invest in new manufacturing facilities and giving buyers access to decarbonized materials directly in their supply chain.
Environmental attribute certificates (EACs) represent the sustainability attributes of a material commodity, unbundled and transacted separately from the physical commodity. EACs are transacted at a price that reflects the additional cost of sustainably producing the material. While barriers to direct procurement of low-carbon materials persist, EACs can serve as a powerful tool to signal demand for low-carbon concrete and steel, catalyze market expansion, and accelerate decarbonization.
[cta]
Microsoft’s Approach to Emissions from Building Materials
To address embodied emissions and help achieve its ambitious 2030 carbon-negative goal, Microsoft aims to deeply reduce its scope 3 emissions, including from building materials, by more than half compared to a 2020 baseline. In 2023, scope 3 emissions made up over 96% of Microsoft’s total greenhouse gas footprint. To meet its 2030 target, Microsoft is focusing on addressing supply-chain emissions related to data center construction and the embodied carbon of the commodity materials used to build them. Microsoft is already working to decarbonize its building material supply chain using the following three tactics:
- Reduce the need for concrete and steel through innovative building design or the use of lower-carbon alternatives, such as sustainably sourced mass timber.
- Directly engage with suppliers to procure low-carbon alternatives to conventional concrete and steel.
- Invest in and help pilot new low-carbon production pathways.
EACs represent a fourth approach to decarbonization that can both reduce emissions and catalyze industry growth. Taken together with Microsoft’s design, procurement, and investment tactics, these actions underpin a comprehensive strategy for long-term decarbonization of the built environment.
High-Quality EACs Support Decarbonization
EACs offer a virtual, market-driven solution to decarbonize the built environment by allowing companies to support low-carbon material production when physical supply chain barriers impede direct procurement. EACs for concrete and steel function similarly to other market-based decarbonization mechanisms such as sustainable aviation fuel (SAF) certificates in the aviation sector and renewable energy certificates (RECs) in the energy sector.
These mechanisms work by decoupling the environmental benefits of low-carbon production from the physical materials themselves. EACs allow companies to claim the environmental benefits of physical low-carbon concrete or steel production, even if they do not directly or physically source those materials. EACs provide a verified claim that a purchaser has procured a product with lower emissions, enabling companies to meet climate targets and demonstrate their commitment to sustainability.
Due to their virtual nature, which limits physical oversight of the supply chain, EACs also exacerbate risks such as double counting, greenwashing, fraud, social harms, and environmental harms. Therefore, adhering to transparent, rigorous criteria is foundational to mitigating these risks.
New Criteria to Guide Procurement of High-Quality EACs
To support the integrity and effectiveness of EACs in these sectors, Relae and Microsoft have co-developed Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors. These robust criteria serve as a public resource for companies seeking credible and impactful EAC procurement pathways for low-carbon concrete and steel.
The criteria address seven key areas:
- Qualifying conditions: EACs must complement, not displace, direct procurement and represent significant emissions reductions.
- Social harms and benefits: EACs must not further social harms and should promote community engagement and social benefits such as meaningful workforce development opportunities and community climate resilience.
- Environmental harms and benefits: EACs must not perpetuate environmental harm, but instead should mitigate risks and, ideally, provide additional environmental benefits.
- Additionality and baselines: Projects funded by EACs must drive real, meaningful emissions reductions in terms of financial, regulatory, and common practice additionality.
- Catalytic impact: Prioritize transformative technologies with sector-wide decarbonization potential.
- Verifiability: Set a high bar for documentation, transparency, and independent auditing.
- Leakage: Address risks of emissions displacement to support net-positive outcomes.
These criteria provide a robust framework for companies and stakeholders to evaluate and implement commodity EACs effectively, supporting impactful change. They balance rigor with flexibility and acknowledge the nascent state of the markets for low-carbon concrete and steel. Sectoral decarbonization will advance over time, shifting the thresholds for what is considered significant, additional, and catalytic in EAC transactions. This science-driven framework can adapt to advancements in policy, industry practices, and technological readiness, ensuring EACs remain a relevant and impactful tool for years to come.
Sector-Specific Insights
In addition to providing overarching criteria and guidance on procuring EACs for the built environment, Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors also provides insights into the unique challenges and opportunities of decarbonizing concrete and steel.
Decarbonizing Concrete
EACs can support innovative decarbonization strategies for concrete, such as producing alternatives to clinker and cement, adopting supplementary cementitious materials (SCMs), and reducing emissions from cement kilns through electrification or integrating carbon capture and storage (CCS). Performance-based standards and evolving building codes may also unlock new opportunities for low-carbon concrete.
The Global Cement and Concrete Association (GCCA) publishes a rating system, Low Carbon Concrete (or Cement) Ratings, which defines eight separate low-carbon grades (AA through G). These grades correspond to the depth of decarbonization and are based on a sliding scale related to the material’s compressive strength. When developing these criteria, Microsoft considered grades AA through D to be eligible for consideration in its EAC procurements.
Decarbonizing Steel
EACs can support transformative technologies for decarbonizing steel, like direct reduced iron (DRI) with electric arc furnaces (EAF) powered by green or blue hydrogen. This support can enable the steel sector to move beyond incremental improvements and focus on capital-intensive solutions that have the potential to reshape the industry.
ResponsibleSteel, an independent standards and certification organization with membership that is broadly representative of the steel industry, publishes decarbonization progress levels, with four separate grades (PL1–PL4). These grades correspond to the depth of decarbonization and are based on a sliding scale related to the fraction of recycled scrap use in the steel manufacturing process. When developing these criteria, Microsoft included levels PL2 through PL4 for consideration in its EAC procurements.
A Blueprint for EAC Market Development
Relae and Microsoft crafted Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors as a public resource that can help shape the future of the commodity EAC market.
These criteria are designed to:
- Communicate intent: Communicate Microsoft's intent to support the decarbonization and scaling of physical commodity supply chains where they have been previously limited.
- Guide decision-making: Serve as a public guide for Microsoft's decision-making process, explaining the rationale behind pursuing or declining specific EAC pathways.
- Set high-integrity standards: Maintain high integrity for EACs at an early stage, ensuring they are used to enable future physical procurement by supporting market development.
- Stimulate partnership opportunities: Encourage potential partnerships and purchasing pipelines by clearly describing criteria for high-quality EACs.
- Publicly share detailed thinking: Build on previous work and publicly share detailed thinking, aiming to stimulate market development and guide procurement decisions.
Practical Recommendations for Implementing EACs
Whether you are a supplier, buyer, policymaker, or sustainability advocate, these new criteria offer actionable insights to help you navigate the complexities of EACs in the built environment. From setting significance thresholds to ensuring verifiability to avoiding double counting, the criteria provide clear guidance to maximize the impact of EAC-supported projects.
Beyond the technical aspects of EACs, these criteria aim to address their broader social and environmental implications. The criteria focus on the importance of community engagement, transparency, and equitable distribution of benefits in EAC project planning, ensuring that decarbonization efforts contribute to a more sustainable and just economy. The criteria are backed by extensive research, stakeholder consultations, and industry expertise.
[cta]
Meera Atreya, John Dees, David Madrid Garcia, Katherine Gomes, Grant Gutierrez, and A.J. Simon authored the Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors. We appreciate Julio Friedmann and Colin McCormick for their valuable technical insights. Adrianna Sutton, Molly Tucker, and Britt Warthen provided essential editorial and production support.
We are especially grateful to Julia Fidler and Brian Sifton, previously at Microsoft, for commissioning this report, providing detailed input, and engaging deeply with the Relae Science Team every step along the way. Special thanks to Katie Ross at Microsoft, whose leadership and coordination made the report possible.
We also extend our appreciation to the teams at RMI and Environmental Resources Management for their time, thoughtful feedback, and prior publications, which helped inform and complement this work.
Frequently Asked Questions
What is an environmental attribute certificate (EAC), and how does it differ from buying low-carbon concrete or steel directly?
An environmental attribute certificate represents the sustainability attributes of a commodity material such as concrete or steel, unbundled from the physical material and transacted separately from it. Direct procurement means a buyer purchases low-carbon concrete or steel and takes physical delivery of it for a specific project. An EAC purchase instead allows a buyer to fund and claim the environmental benefit of sustainably produced materials that are sold as typical commodities, and apply that benefit against conventional commodities in their own supply chain. EACs are priced to reflect the additional cost of producing the material sustainably, which sends a demand signal to producers. This makes EACs useful where market barriers—limited production volumes, geographic concentration of supply, or long-distance transportation—prevent buyers from sourcing low-carbon materials directly.
How do EACs for concrete and steel compare to renewable energy certificates (RECs) or sustainable aviation fuel (SAF) certificates?
Environmental attribute certificates for concrete and steel share a structure with renewable energy certificates and sustainable aviation fuel certificates: each decouples the environmental benefit of low-carbon production from the physical product, letting a buyer fund and claim that benefit without taking physical delivery. There are two key differences. First, conventional RECs represent electricity with a zero-emissions footprint, while every tonne of concrete or steel behind an EAC still carries embodied emissions — the certificate demonstrates reduction against a baseline, not a zero-emission product. Second, REC and SAF markets are established, while EACs for concrete and steel are nascent. Both differences are why rigorous criteria matter: quantifying the reduction credibly is harder, and the virtual structure carries risks of double counting, greenwashing, and fraud.
Will EACs let companies claim emissions reductions without actually reducing their built environment climate footprint?
An EAC purchase does not change the materials in a buyer's own buildings; it funds lower-emission production elsewhere in the market. Credible EAC frameworks therefore require that certificates complement rather than displace direct procurement, that they represent significant reductions against a defensible baseline, and that the funded project would not have proceeded without EAC revenue. The criteria published by Relae and Microsoft enable buyers to address these requirements directly in their procurement processes - addressing the climate and reputational risks of low-quality certificates. Used this way, EACs become an additional tool to address emissions from the built environment, supplementing design changes, direct procurement, and investment in new production pathways.
Who should use these criteria?
Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors, co-developed by Relae and Microsoft, is a public resource intended for four audiences. Buyers pursuing scope 3 reductions can use it to evaluate whether a given certificate represents a credible, additional emissions reduction. Suppliers and project developers can use it to understand what purchasers of high-quality certificates look for before bringing a project to market. Policymakers and standards bodies can draw on it while shaping rules for an emerging market. Sustainability practitioners and advocates can use it as a reference point for assessing claims made about low-carbon concrete and steel. The criteria are designed to evolve as these sectors decarbonize, and users may adapt them to meet their own levels of capability and ambition.
The Role of Improved Forest Management for Carbon Dioxide Removal
Key Takeaways
- Improved forest management (IFM) increases measurable long-term carbon storage in living trees and durable wood products.
- At the same time, it can provide strong social and ecological co-benefits.
- IFM projects like the ones developed by Weyerhaeuser and the Indigenous community of Petcacab in collaboration with Relae (formerly Carbon Direct) show how IFM practices can align climate goals with social and environmental benefits.
Forests Are Climate Solutions If We Manage Them Wisely
Forests remove carbon dioxide from the atmosphere, but they need to be thoughtfully managed to keep doing so. As buyers look to scale carbon removal, improved forest management (IFM) is gaining traction in the voluntary carbon market (VCM).
IFM focuses on enhancing how existing forests are managed to increase carbon storage over time. It’s a nature-based solution that supports climate outcomes, community livelihoods, and environmental benefits when done well.
This piece explains how IFM works, what makes a project high-quality, and how real-world IFM projects like those developed by Weyerhaeuser and Petcacab in collaboration with Relae (formerly Carbon Direct) are delivering credible results for buyers and local communities alike.
What Is Improved Forest Management?
Improved forest management is a catch-all phrase that describes management techniques that decrease emissions from forests or increase carbon removal and storage. Some management techniques, like transitioning a working forest to a conserved status, decrease emissions from forest harvest and primarily create credits for avoided emissions. Other management techniques, like harvesting forests less frequently, can lead to greater carbon removal and storage over time and create credits for additional carbon removal.
Examples of IFM Practices Include:
- Extending harvest rotations to allow more carbon accumulation
- Reducing the impact of logging on soil and surrounding trees
- Managing fire and pest risks to enhance forest health
- Transitioning some of a forest to conservation status
These strategies help forest carbon stocks grow beyond business-as-usual baselines. In carbon markets, IFM can generate carbon removal or avoided emissions credits, depending on the project's design and carbon accounting methodology.
What Makes a High-Quality IFM Carbon Removal Credit?
Buyers today face increased scrutiny around carbon credit quality. In this context, IFM projects must go beyond basic registry standards to demonstrate climate integrity and social and environmental benefits.
Relae developed the Criteria for High-Quality Carbon Dioxide Removal, an annual report published in collaboration with Microsoft to establish science-backed quality standards. This includes six core principles that define high-quality carbon removal, all of which apply to IFM projects:
- Social harms, benefits, and environmental justice - The extent to which the project prevents new social harms to people and communities, reduces existing harms, and provides meaningful benefits distribution. Since IFM projects take place in communities around the world, benefits will naturally vary from project to project.
- Environmental harms and benefits - The extent to which the project minimizes and mitigates environmental harms, as well as provides environmental benefits. Because IFM projects enhance management practices, environmental co-benefits of high-quality IFM projects are usually substantial.
- Additionality and baselines – Evidence that the project’s carbon removal would not have occurred without carbon finance. Many IFM projects fail to present compelling additionality data and narratives. High-quality projects will be able to identify the actions the project took to increase carbon storage that would not have happened without carbon finance.
- Measurement, monitoring, reporting, and verification (MMRV) – The ability to accurately quantify carbon removal in a repeatable and verifiable way, and to develop a plan for long-term monitoring of the project. IFM projects must have robust forest inventory, growth modeling, and occasional remeasurement to verify the additional carbon storage.
- Durability – The likelihood that removed carbon remains stored over time, with mechanisms in place to mitigate reversal risk. Enhanced management of fire, pests, and disease in IFM projects can enhance forest carbon durability.
- Leakage – Evaluation of whether project activities cause increased emissions elsewhere. If an IFM project substantially reduces timber supply, market demand can drive increased harvesting in other forests, undermining some of the project’s climate benefits. High-quality IFM projects minimize this risk by limiting harvest reductions, and account for any remaining leakage by issuing fewer credits.
Relae uses these criteria as part of our diligence framework when advising buyers evaluating projects and co-developing our own projects.
IFM Projects Delivering Real Impact
Weyerhaeuser: Applying Science at Scale
Weyerhaeuser, one of the largest forest owners in North America, is applying improved forest management practices across over 200,000 acres of working forests.
The IFM projects led by Weyerhaeuser are located in rural areas in the US, with low wildfire risk. These IFM projects sequester carbon by extending harvest rotations and forgoing harvest in established streamside management zones.
Relae supported Weyerhaeuser with hands-on scientific collaboration to confirm that every IFM project met the Criteria for High-Quality Carbon Dioxide Removal.
Why it matters to buyers:
- High-quality climate impact at large scale
- Transition of working forests from traditional management techniques to maximize climate impact
- Responsible forestry practices aligned with SFI® standards
- Rigorous carbon accounting and high-quality project baseline established using historical harvest records
The IFM projects led by Weyerhaeuser are some of the largest in the US today and a model for scaling science-backed forest carbon solutions.
Petcacab: Indigenous-Led Conservation in the Yucatán Peninsula
Located in the communal lands of Petcacab, Mexico, this IFM project is led by Indigenous Mayan ejidatarios—community members who have legal rights to manage the land.
Historically, forests in the ejido have been degraded through unsustainable harvesting and extensive damage from hurricanes. Through carbon finance, they are developing new forest management plans and sustainable forestry models, with revenue reinvested in health, education, and job creation.
“The rainforest for me represents my home, my work, my present, my future. We have a very daring challenge: to transform how we manage our forest, shifting from harvesting and selling timber to conserving it through the sale of carbon credits that support the development of our community.”
— Celso Chan Rivas, Carbon Project General Manager
What makes Petcacab stand out:
- Equitable benefit-sharing and strong Indigenous governance
- Critical habitat protection for endangered species
- Increased additional carbon storage through forest management and reduced land use conversion
- Transparent reporting and verified outcomes
Petcacab is recognized by Relae as a high-quality community IFM project in Mexico, with clear social, environmental, and climate outcomes.
Investing in Forests That Deliver More Than Carbon
Improved forest management is more than a carbon strategy, it’s an investment in ecosystems, communities, and long-term impact. For buyers seeking high-integrity carbon removal with social and environmental co-benefits, IFM projects offer a compelling opportunity.
IFM projects like the ones developed by Weyerhaeuser and Petcacab in collaboration with Relae show what’s possible when forests are managed with science and care. They also reflect what the voluntary carbon market needs more of: quality, transparency, and impact beyond the metric ton.
Electricity Emissions Accounting: GHG Protocol and LCA Explained
Key Takeaways
- The GHG Protocol Corporate Standard and life cycle assessment (LCA) offer distinct frameworks for measuring electricity-related emissions, one for annual corporate reporting and one for detailed cradle-to-grave analysis, leading to different emissions results.
- Renewable energy certificates (RECs) are accepted under the GHG Protocol's market-based approach to reduce reported scope 2 and scope 3: category 3 emissions, but are not explicitly addressed in ISO LCA standards, where transparent disclosure is essential.
- Using both the GHG Protocol and LCA together, while recognizing their different scopes, boundaries, and purposes, can give organizations a more complete and strategic view of electricity-related emissions and decarbonization opportunities.
Electricity-Related Emissions: Why Measurement Methods Matter
In the era of AI-driven power demand, scrutiny over electricity-related emissions is intensifying. With this increased attention comes growing confusion around how to measure and report these emissions. The GHG Protocol Corporate Standard and life cycle assessment (LCA) are two widely used methods for measuring and reporting electricity-related emissions, but each follows its own complex and often incompatible, set of rules.
This piece will examine the differences between these approaches and answer common questions such as:
- What are the differences between the GHG Protocol Corporate Standard and LCA?
- Why do they result in different emissions for the same type and amount of electricity?
- Can renewable energy contracts reduce electricity-related emissions under both methods?
- When should you use each approach?
Both the GHG Protocol Corporate Standard and LCA are powerful tools that, if used in complementary ways, can help organizations identify emissions hotspots and develop more effective pathways for decarbonization.
What Is the GHG Protocol Corporate Standard?
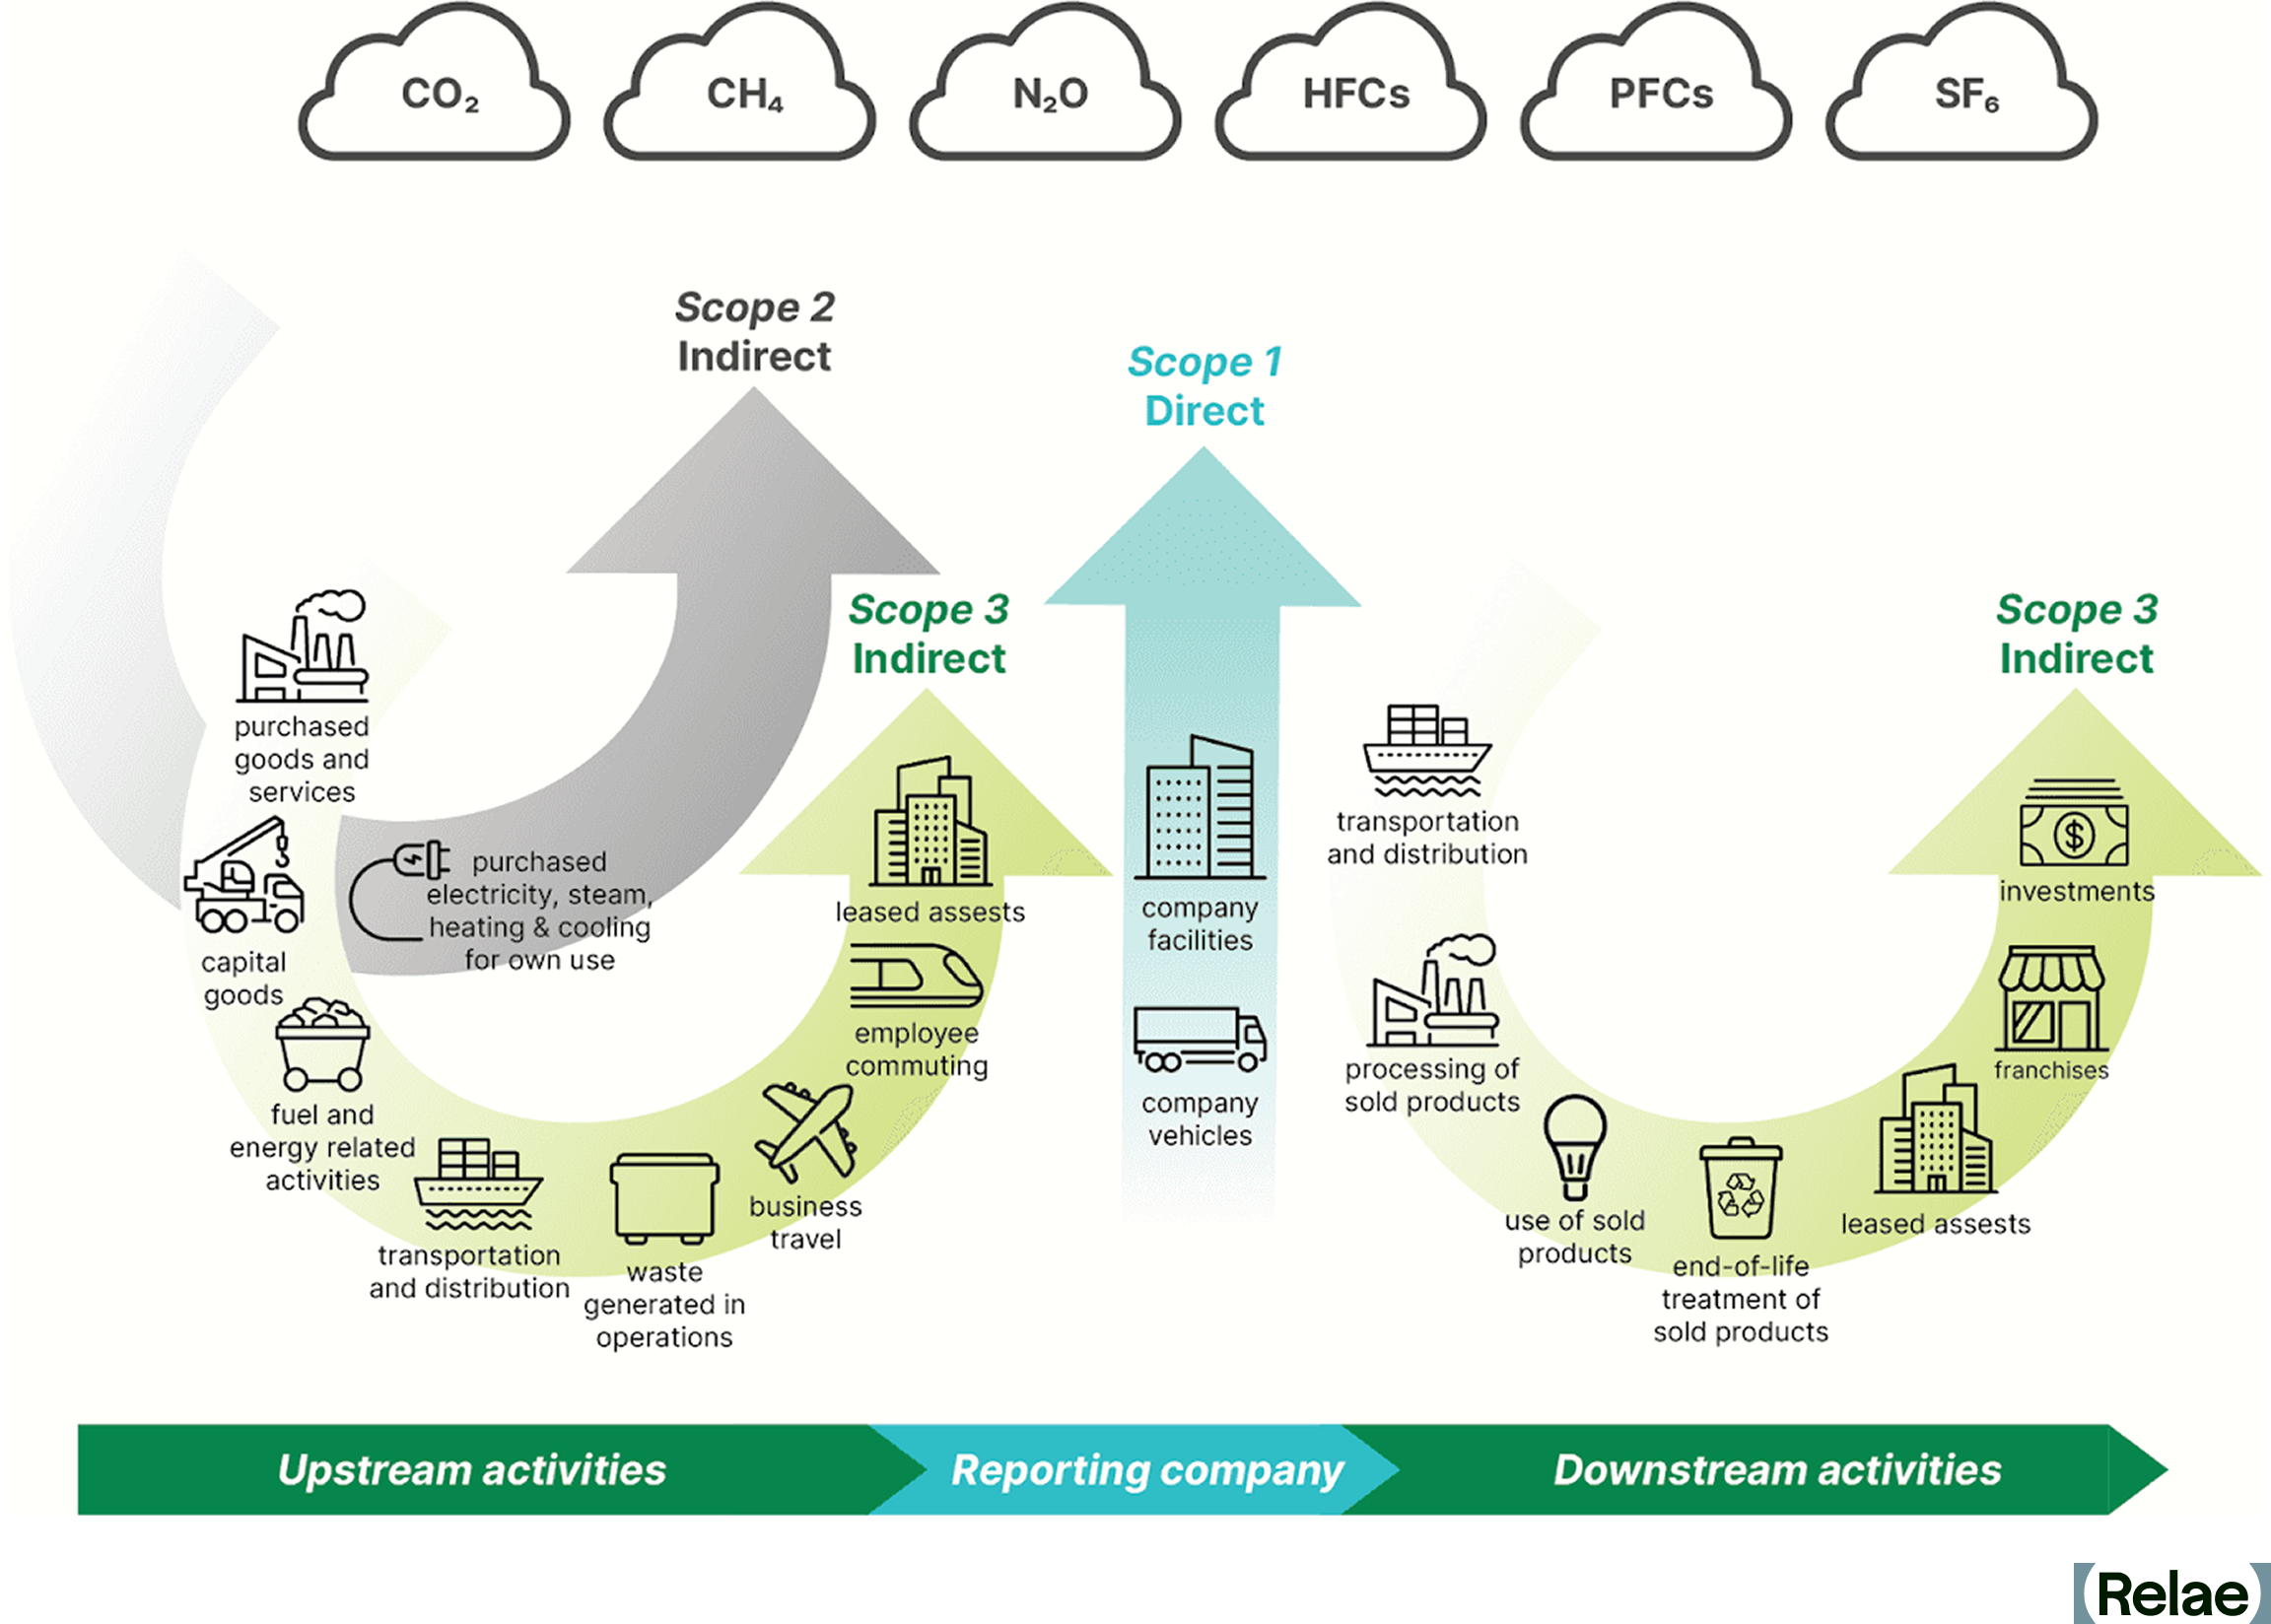
The GHG Protocol Corporate Standard is a globally recognized framework for corporate entities to publicly report GHG emissions throughout their value chain. It divides emissions into three scopes:
- Scope 1: Direct emissions from owned or controlled sources, such as company-owned vehicles, on-site fuel consumption, or industrial processes.,
- Scope 2: Indirect emissions from the generation of purchased electricity, heat, steam, or cooling. These emissions are generated off-site, but result from an organization's energy consumption.
- Scope 3: Indirect emissions across an organization's value chain. Scope 3 is divided into 15 categories, including a company's supply chain activities, business travel, employee commuting, investments, and product life cycle emissions.
This piece focuses on emissions associated with electricity consumed by a reporting entity. These electricity-related emissions primarily fall under scope 2 and scope 3: category 3 (fuel- and energy-related activities, or FERA).
Scope 2: Electricity Generation Emissions
Scope 2 emissions account for the generation of electricity a company purchases or uses. Hypothetically, if a company were powered by a single solar project, it would report zero scope 2 emissions. In reality, a company is powered by a combination of power generation assets and must report them under scope 2 emissions. These emissions can be reported using two methods:
- Location-based method: Reflects the average emissions intensity of the local electricity grid where the consumption occurs. This approach is mandatory under various reporting frameworks and does not take into account a company's procurement choices.
- Market-based method: Reflects an organization's actual procurement decisions and energy-sourcing strategies. It accounts for specific contracts, such as power purchase agreements (PPAs), renewable energy certificates (RECs), and green tariffs, which allow businesses to claim lower emissions from their purchased electricity.
Scope 3: Category 3 FERA
Scope 3: category 3 FERA reports on non-generation electricity emissions associated with:
- Upstream emissions: Emissions associated with the production and transportation of fuels needed for electricity generation
- Transmission and distribution losses: Emissions associated with the loss of electricity while delivering it from the generator to the consumer.
The GHG Protocol Corporate Standard does not include emissions associated with the manufacturing, construction, and end-of-life phases of electricity generation equipment; however, some datasets used for reporting may include manufacturing emissions. While scope 3: category 3 guidance may not require these emissions to be included, if possible, companies reporting on their electricity-related emissions should include these additional sources of emissions in order to more completely represent their total emissions impact. The GHG Protocol Scope 2 Guidance allows for the reduction of some of the reported scope 3 FERA emissions by contracting renewable energy (see Appendix B).
What is an LCA?
An LCA is a systematic method used to quantify the environmental impacts of a process, product, or project throughout its full life cycle. A life cycle includes everything from raw material extraction ("cradle") to manufacturing/production ("gate") through disposal ("grave").
LCAs primarily follow a standard published by the ISO organization (ISO 14040/14044). The ISO standards establish industry-wide rules for which processes are included and how to assign environmental burdens to products.
An LCA can be used for any product, process, or project, and can estimate multiple different environmental impacts (i.e., climate change, human health, ecotoxicity, eutrophication, ozone depletion).
Electricity-Related Emissions Can Be Different Using the GHG Protocol and an LCA
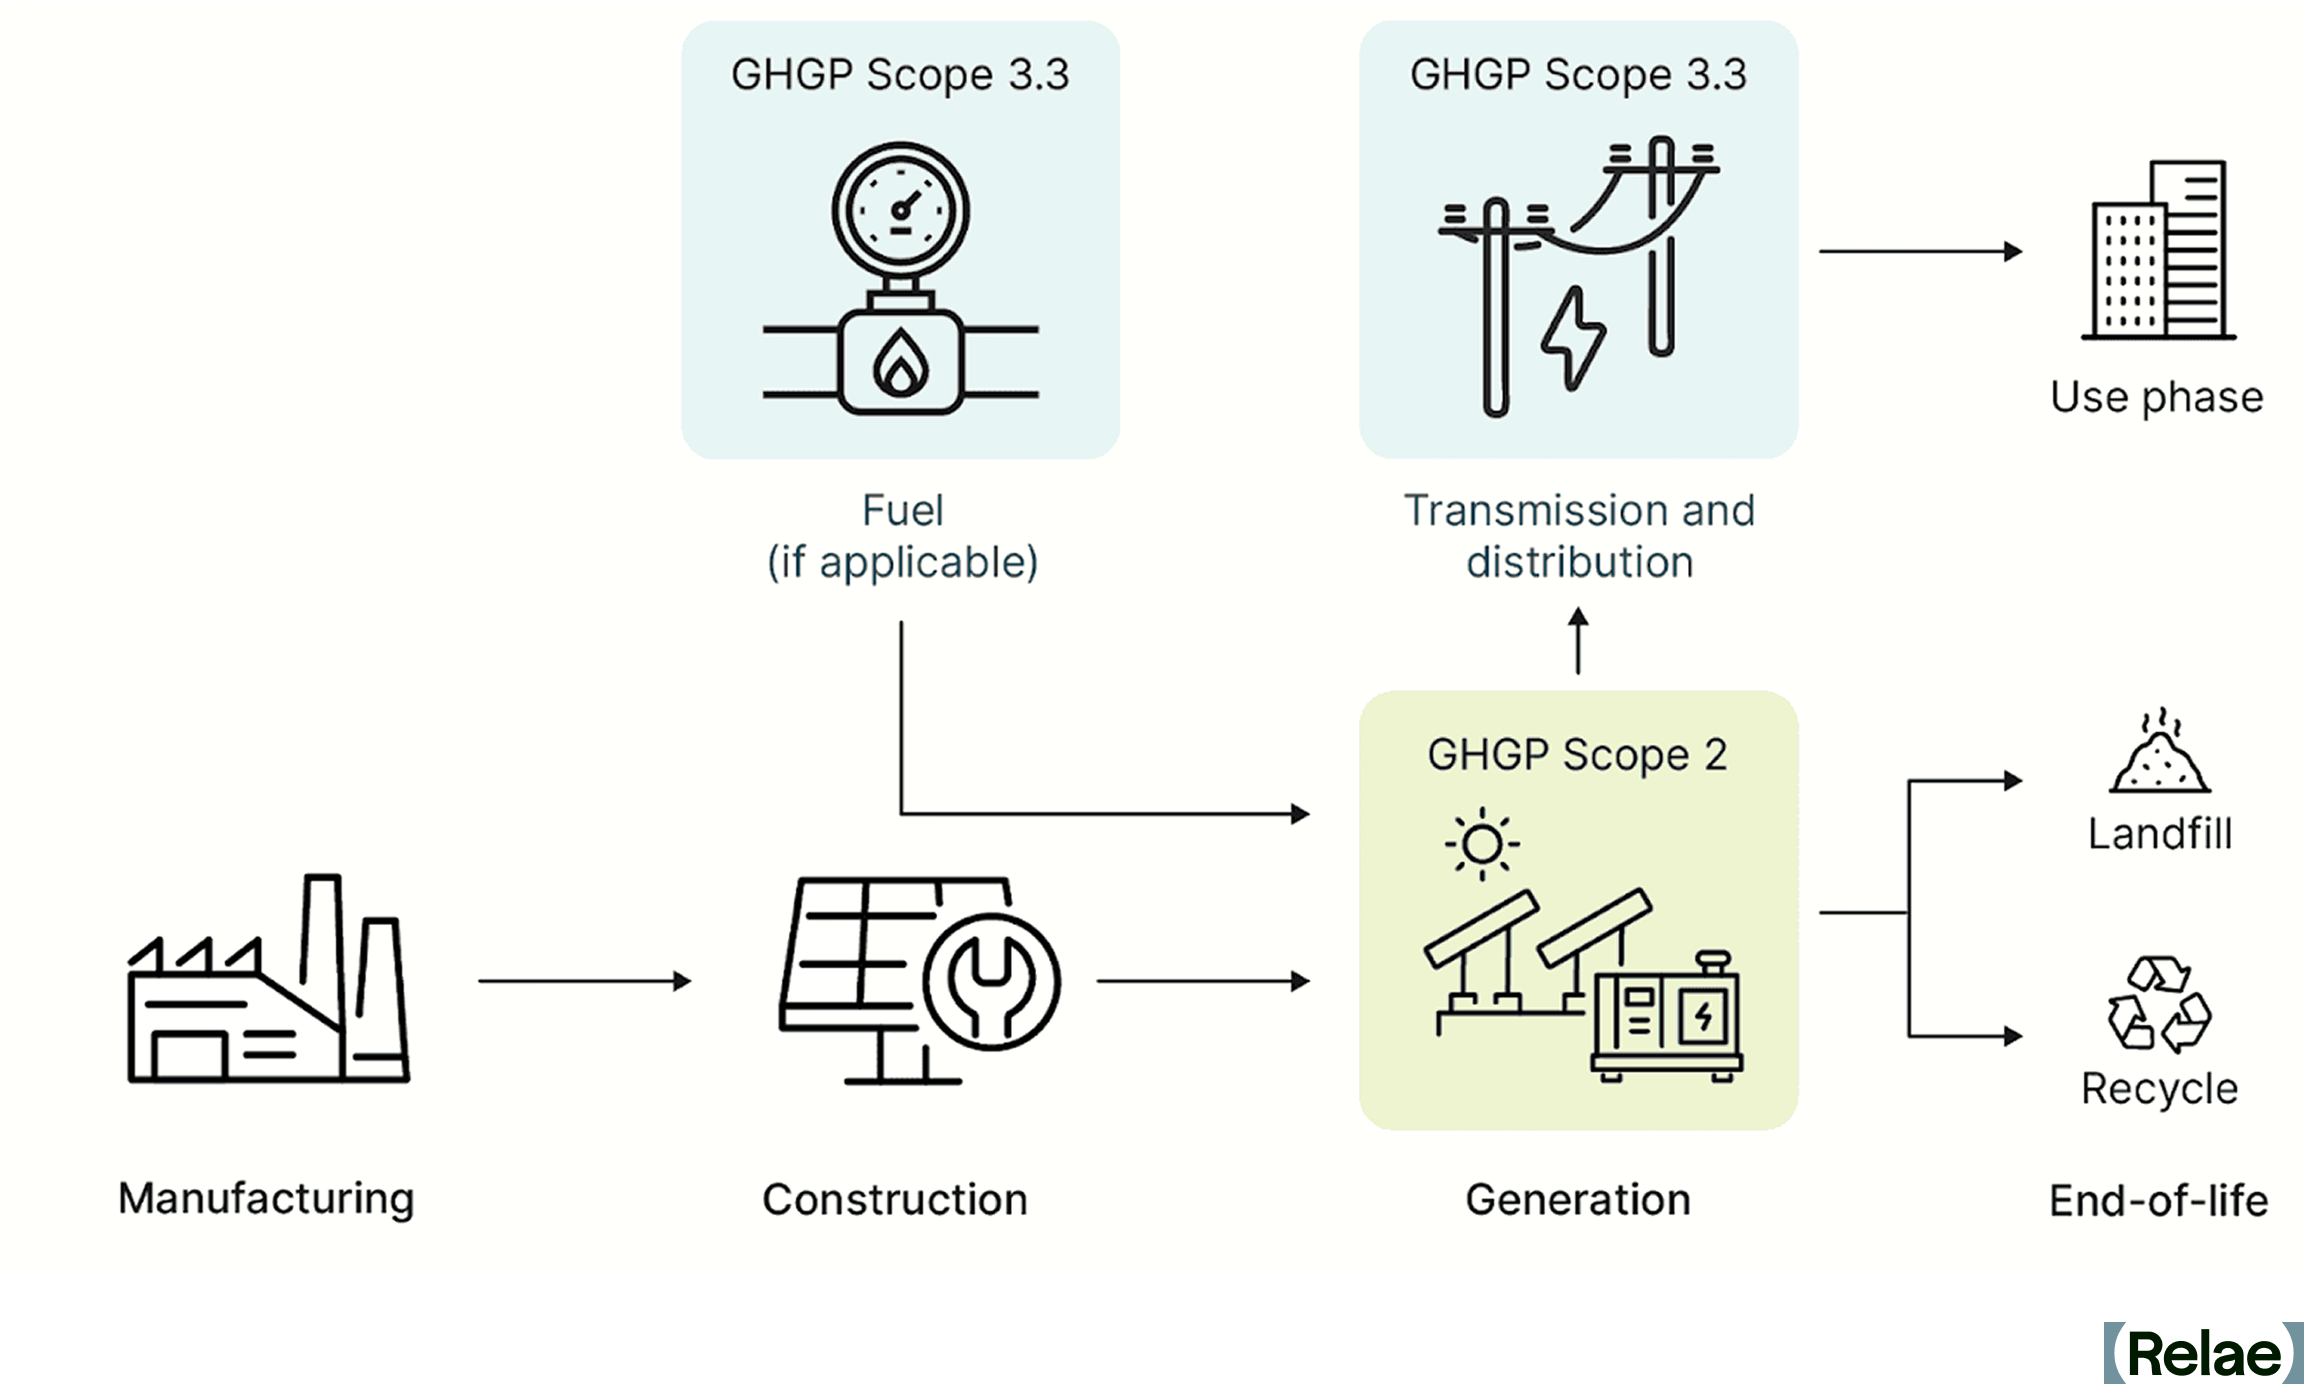
The GHG Protocol Corporate Standard and an LCA (as per ISO standards) generally include different life cycle stages of electricity use when estimating GHG emissions. Therefore, the approaches can result in different reported emissions.
Key Differences in Reporting Electricity-Related Emissions
The GHG Protocol Corporate Standard includes emissions in the following phases:
- Generation (scope 2)
- Transmission and distribution losses (scope 3: category 3)
- Fuel, if applicable (scope 3: category 3)
A “cradle-to-grave” LCA considers emissions from all activities associated with power generation, including:
- Manufacturing
- Construction
- Generation
- Fuel, if applicable
- Use-phase, if applicable
- End-of-life
Use-phase electricity-related emissions are emissions generated by electricity-consuming equipment used or sold by the reporting company (representing additional scope 1 or scope 3 emissions, respectively). Examples include sulfur hexafluoride (SF6) emissions from electrical transformers or refrigerant leakage from air conditioners with high global warming potential. Please note that both the ISO and GHG Protocol Corporate Standard provide guidelines for reporting these emissions. However, due to the equipment-specific nature of these emissions, they are excluded from the following table. The table compares electricity-related emissions associated with different electricity sources using the GHG Protocol Corporate Standard approach and the LCA approach.
Reporting Electricity-Related Emissions
* US average transportation and distribution loss rate (4.2%) times US average grid carbon intensity (410 gCO2e/kWh). Note: gCO2e/kWh = grams of carbon dioxide equivalent per kilowatt-hour. Source: GREET 2024 (US grid average. 10% fuel- and energy-related activities; 1% construction, facilities, maintenance, and end-of-life; 89% fuel combustion).
Reducing Electricity Emissions with Renewable Energy
Renewable Energy Mechanisms Under the GHG Protocol
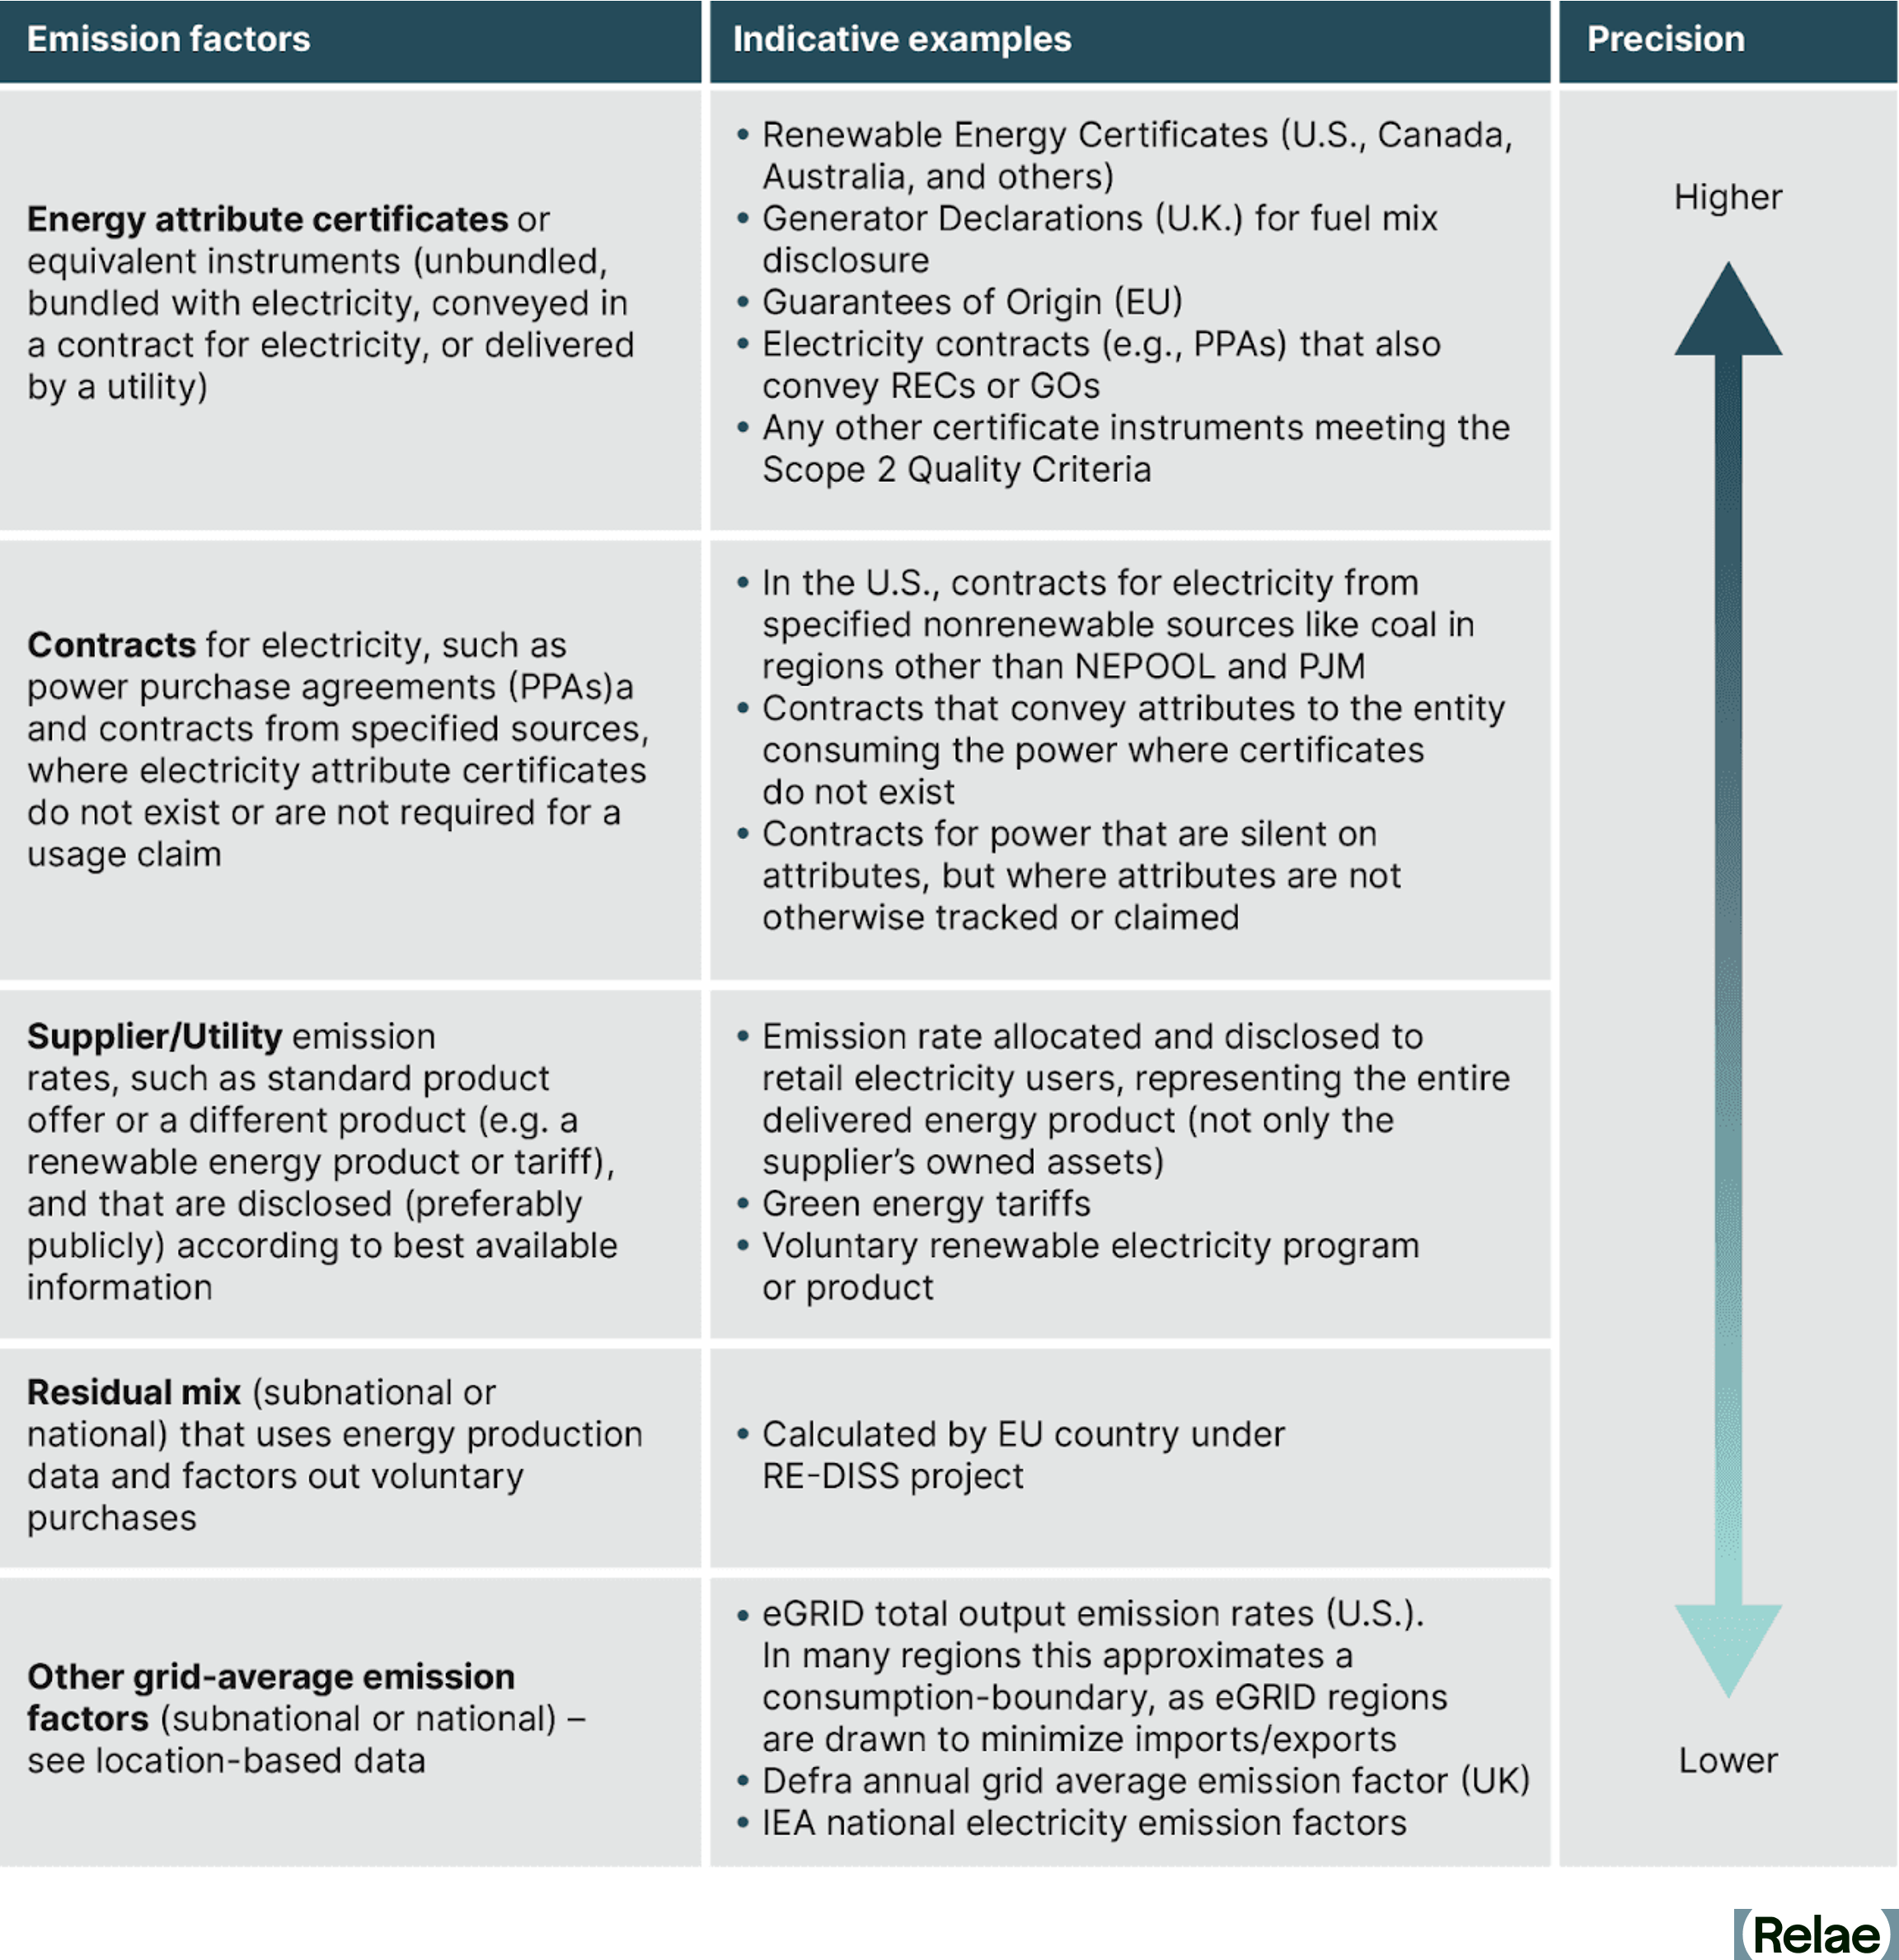
The GHG Protocol Corporate Standard allows companies to contract for renewable electricity as a mechanism to reduce reported emissions. The GHG Protocol Corporate Standard defines allowable energy contracts that can be used to reduce emissions associated with electricity consumption (market-based reporting).
In North America, one of these allowable contracts is RECs, each of which represent one megawatt-hour of renewable generation. Analogous instruments used in other locations, such as Guarantees of Origin in Europe and green electricity certificates in China, are also permissible under the GHG Protocol Corporate Standard.
RECs were developed as a contractual mechanism for renewable electricity in response to the fundamental structure of "a power grid." In a power grid, it is impossible to link a single generator to a single load. Power is injected at a point in the grid and withdrawn at a different point in the grid; there is no traceable pathway.
RECs were created to track the attributes of electricity generation entering into a power grid for the entity that consumes the power at a different point. The GHG Protocol Corporate Standard allows buyers to claim exclusive use of renewable electricity with RECs even if they are actually consuming a mixture of electricity from the grid.
Renewable Energy Mechanisms Under the LCA ISO Standard
The ISO 14040 standard does not address the use of renewable electricity contracts. However, the ISO 14044 standard provides the following guidance:
"When determining the elementary flows associated with production, the actual production mix should be used whenever possible, in order to reflect the various types of resources that are consumed. As an example, for the production and delivery of electricity, account shall be taken of the electricity mix, the efficiencies of fuel combustion, conversion, transmission and distribution losses."
It does not explicitly define whether RECs can or cannot be used in the determination of the "actual production mix." In the event an organization does procure a renewable energy contract to reduce the emissions reported within the LCA, it should disclose that clearly in order to communicate the impact of the contract on the carbon intensity of the LCA with and without the use of RECs.
Powerful Tools for Different Use Cases
The GHG Protocol Corporate Standard and LCAs following the ISO Standard are both powerful tools that can provide insight into emissions associated with electricity use. The GHG Protocol Corporate Standard allows companies to use a standardized framework to report emissions associated with electricity use and interventions on an annual basis. The LCA ISO standard is a detail-driven analysis that allows a deep dive into specific processes, projects, or products. This detailed analysis allows for deeper insights into areas where a company may have more ability to address specific interventions for emission hot spots. Using these tools together, while understanding the boundaries of each, can provide companies with a more effective and impactful approach to decarbonization.
Frequently Asked Questions
What are the differences between the GHG Protocol Corporate Standard and LCA?
The GHG Protocol is an annual corporate reporting framework covering scope 2 (generation) and scope 3: category 3 (transmission and distribution losses, fuel), while a cradle-to-grave LCA is a detailed analysis governed by ISO 14040/14044 standards that also includes manufacturing, construction, use-phase, and end-of-life emissions. LCA can also be applied to any product or process and multiple environmental impacts, not just greenhouse gas emissions.
Why do they result in different emissions for the same type and amount of electricity?
They include different life cycle stages. The GHG Protocol excludes manufacturing, construction, and end-of-life emissions of generation equipment, while an LCA includes them.
Can renewable energy contracts reduce reported electricity-related emissions under both methods?
Under the GHG Protocol, renewable energy contracts (e.g., RECs, PPAs) are explicitly allowed to report zero market-based scope 2 emissions, though scope 3 FERA emissions remain. Under ISO LCA standards, these contracts aren't explicitly addressed. Organizations may choose to apply them, but should transparently disclose LCA results both with and without the contract's impact.
When should you use the GHG Protocol vs an LCA?
Use the GHG Protocol for standardized, annual corporate-wide emissions reporting and tracking procurement interventions; use an LCA for a detailed, process- or product-specific deep dive to identify specific emissions hotspots. Relae recommends using both together for a more complete, strategic view of electricity-related emissions.
Scope 3.1 Emissions: How to Measure and Reduce Value Chain Impact
Key Takeaways
- Scope 3.1 emissions, purchased goods and services, can account for up to 67% of a company’s total carbon footprint, making them a critical category for measurement and action.
- Companies can reduce risk, meet stakeholder demands, and strengthen supply chain resilience by proactively managing scope 3.1 emissions.
- Relae empowers organizations to take meaningful action on scope 3.1 through science-based measurement, practical emissions management strategies, and deep supplier engagement.
What Are Scope 3 Emissions and Why Do They Matter?
Scope 3 emissions include all indirect greenhouse gas (GHG) emissions that occur across a company’s value chain. While scope 1 emissions are from directly owned or controlled activities, and scope 2 are indirect emissions from the generation of purchased electricity, heat, or steam, scope 3 emissions encompass upstream and downstream activities throughout the value chain.
Within scope 3, there are 15 categories, including activities such as raw material extraction, purchased services, shipping, business travel, product use, and end-of-life treatment. Critically, scope 3 emissions usually make up the majority of a company's total carbon footprint. Across sectors, CDP finds supply chain emissions average 26 times a company's operational emissions, and in supply-chain-heavy sectors like apparel, the share exceeds 95%.
Category 3.1 (purchased goods and services) is often the largest contributor. For many organizations, it can be as much as 67% of their total corporate footprint. Despite being outside a company’s direct operational control, scope 3 emissions are increasingly scrutinized by regulators, investors, and customers alike, making them essential to measure, manage, and reduce.
What Is Included in Scope 3.1 Emissions?
Scope 3.1 emissions capture all cradle-to-gate emissions associated with products and services procured by an organization. These include emissions from the extraction of raw materials, energy usage, manufacturing processes, waste, and transport and travel up to the point of delivery to the reporting company. As such, the types of activities within this category are quite extensive and disparate.
Examples of scope 3.1 items include:
- Raw materials (e.g., limestone, copper ore, lumber)
- Intermediate products (e.g., steel, electronic components, platform chemicals)
- Packaging materials
- Office supplies and equipment
- Professional services
- Cloud computing and software services
The size of scope 3.1 emissions varies widely by industry. For example, a consumer goods manufacturer sourcing large volumes of physical products may see a larger share of emissions in this category than the supplier providing the raw materials. For data centers that run on very low-carbon electricity, equipment and construction can account for 40% of lifetime emissions. For many organizations that are service-based or contract out manufacturing, scope 3.1 can be the most significant emissions category.
What Is the Strategic Value of Scope 3.1?
While scope 3.1 emissions fall outside a company’s direct operational control, they are not beyond its influence. Addressing emissions from purchased goods and services may open up a range of strategic benefits:
- Innovation opportunities through lower-carbon materials and production processes.
- Enhanced supplier relationships and engagement on shared sustainability goals.
- Improved resilience and risk mitigation across supply chains.
By assessing and acting on scope 3.1 emissions, companies can drive meaningful reductions and catalyze change throughout the entire supply chain.
What Are the Methods for Calculating Scope 3.1 Emissions?
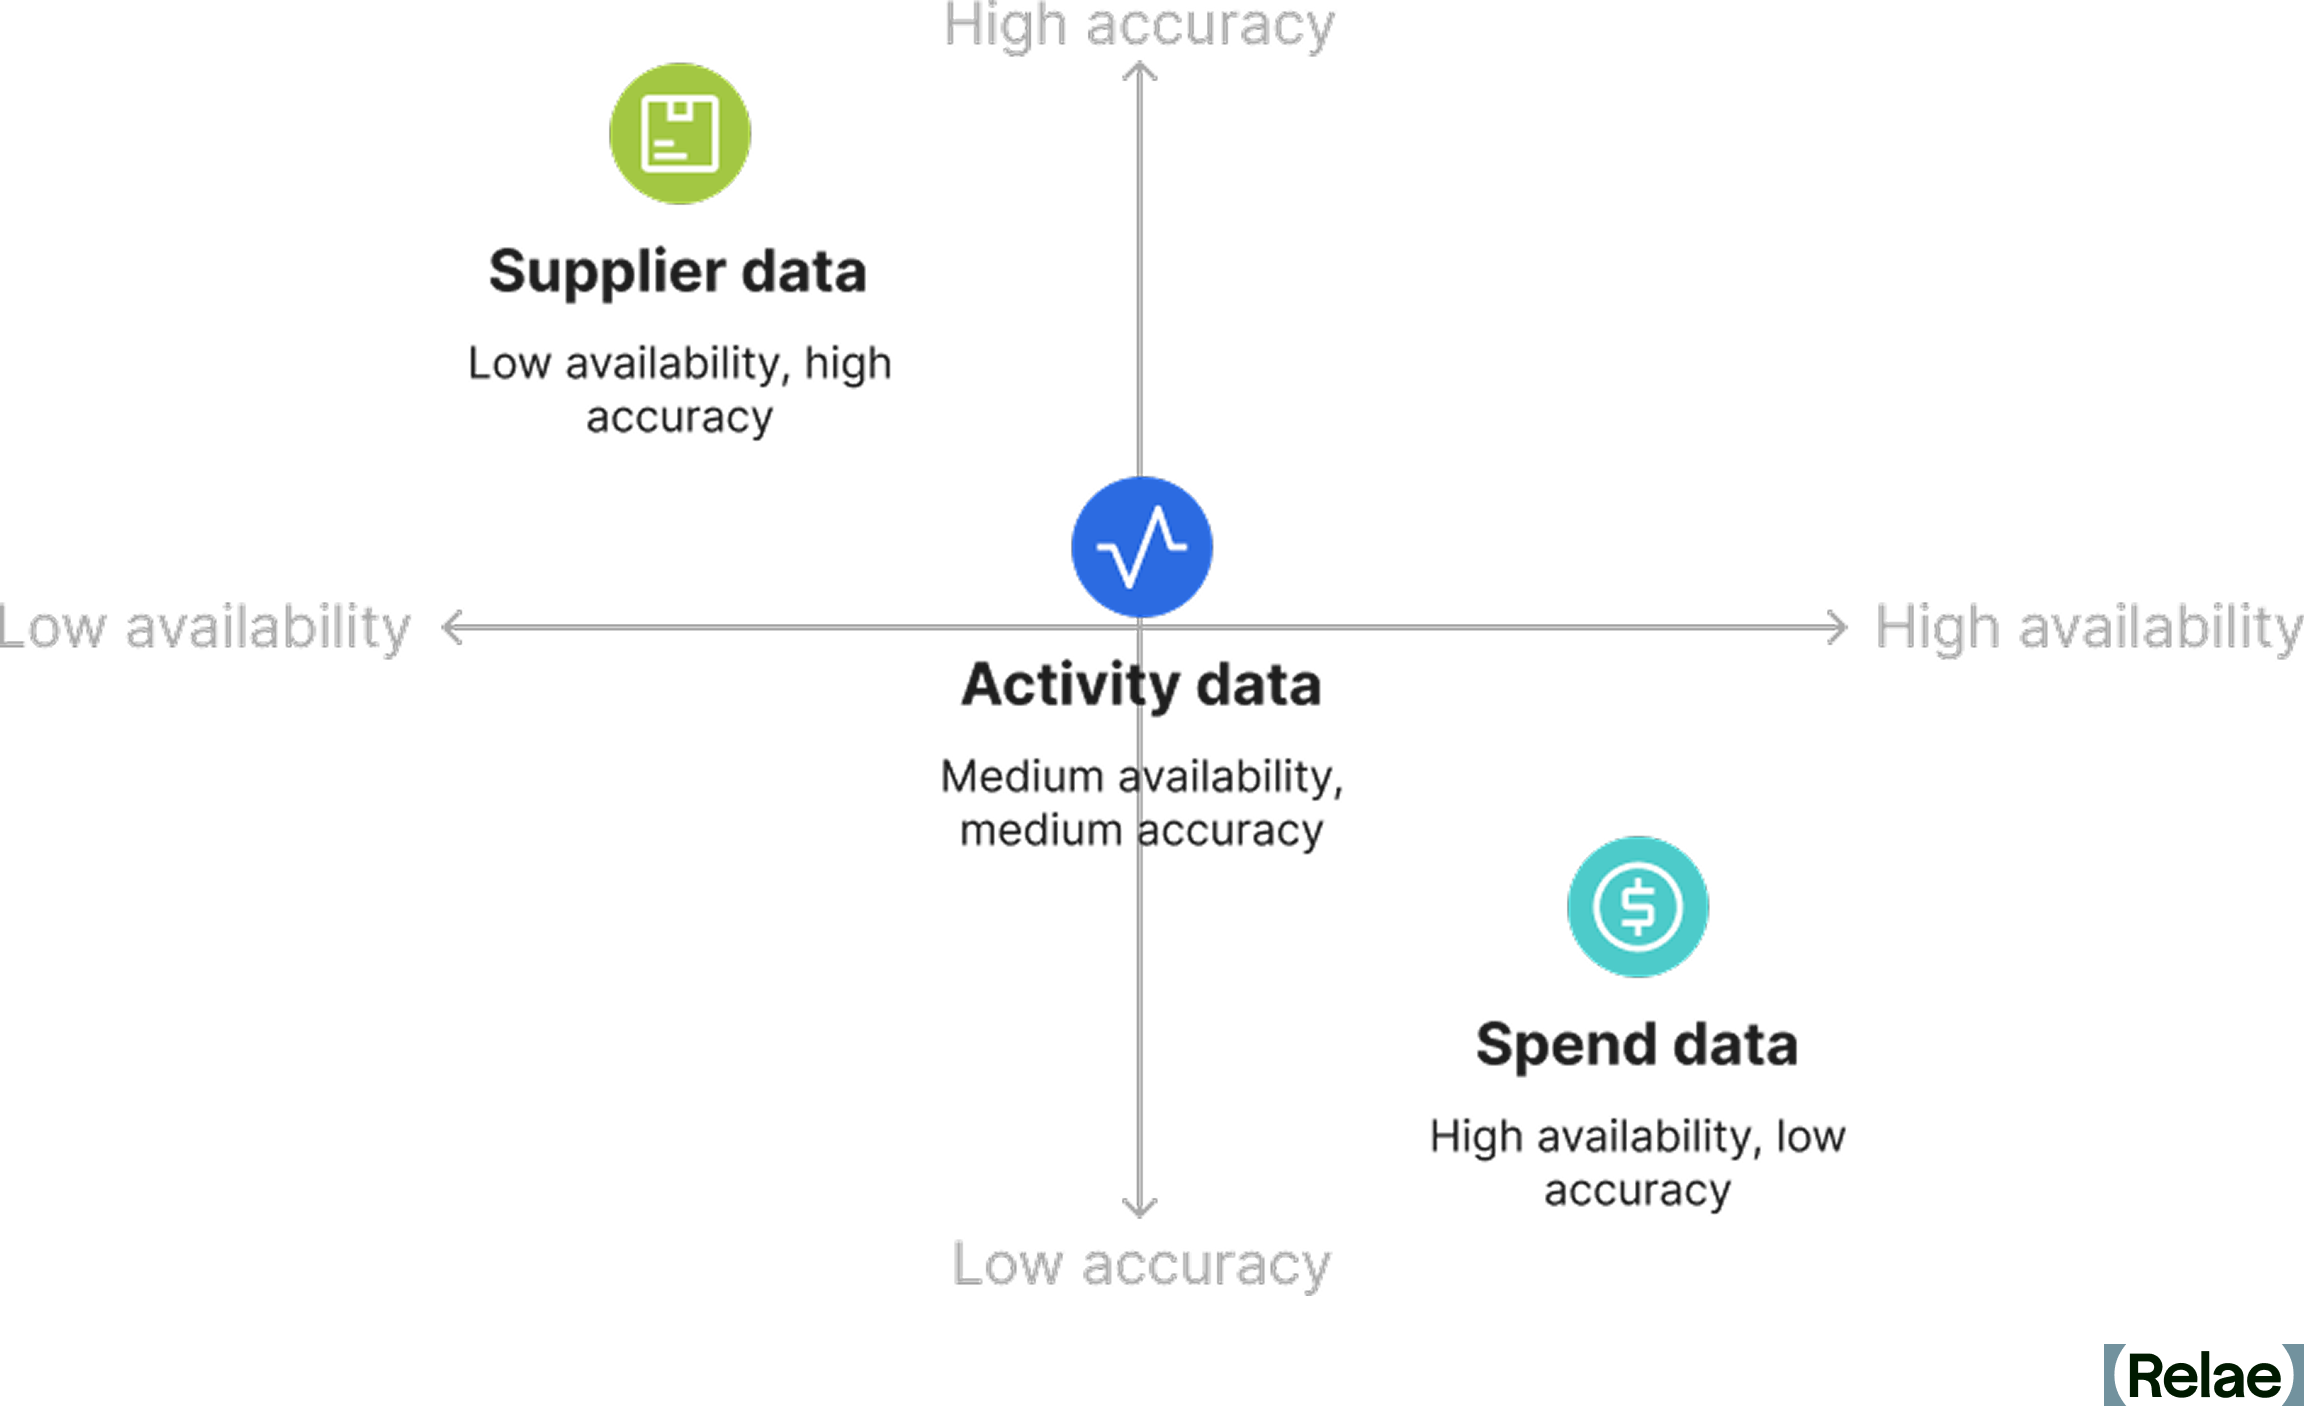
There are four methods to calculate scope 3.1 emissions based on the data collected. Each offers a different balance of speed, accuracy, and scalability.
1. The Spend-Based Method
This approach multiplies the amount of money spent on a good or service by an economic emissions factor (e.g., kg CO₂e per dollar spent). Most companies use this approach as a starting point but transition to more accurate methods as they advance in their sustainability journey.
Advantages
- Fast and scalable across categories
- Useful for initial hotspot identification
- Helps fill data gaps when activity data is unavailable
Limitations
- Lower accuracy, especially during periods of inflation or economic volatility
- Cannot reflect actual emissions reductions by suppliers
- Misalignment between price and emissions (e.g., high-cost items may not be high-emission)
2. The Average Data Method
This method uses average emissions factors for goods or services, based on industry datasets. For instance, industry life cycle assessments (LCAs) might be used to estimate the emissions associated with a kilogram of steel purchased.
Advantages
- More accurate than spend-based
- Suitable for companies refining emissions data to enable targeted reductions
Limitations
- Lack of raw data granularity
- Geographic variation limited
3. The Supplier-Specific Method
The supplier-specific method is the most accurate approach and involves collecting actual emissions data directly from suppliers. This includes LCAs, environmental product disclosures (EPDs), product carbon footprints (PCFs), supplier emissions reports, or Environmental, Social, and Governance (ESG) reports.
Advantages
- High accuracy and granularity
- Builds engagement with suppliers
- Enables tracking of supplier improvements over time
Limitations
- Challenging to scale across many suppliers
- Data may be confidential, inconsistent, or incomplete
- Requires continuous updating of supplier information
4. The Hybrid Approach
Adopting a hybrid approach allows many companies to maximize their data collection efforts by applying the supplier-specific method for high-impact purchases and using average or spend-based methods elsewhere. This tiered approach enables efficient use of resources while maintaining data quality for critical emission sources.
Where Can You Find Scope 3.1 Data?
Data for scope 3.1 emissions typically resides in procurement and finance functions. Purchase orders, invoices, and supplier contracts often contain critical information such as volume, product category, and spend. However, collecting, organizing, and analyzing this data can be resource-intensive, especially for companies with complex and global supply chains. Data type and availability play a key role in determining the method used for calculating emissions, impacting the accuracy and ability to reduce emissions.
What Are the Challenges in Measuring Scope 3.1 Emissions?
As most organizations will attest, measuring scope 3.1 has many challenges, from resource constraints to data availability. As organizations intensify their climate commitments, they are increasingly confronted with a range of technical, logistical, and strategic barriers that make accurate measurement and consistent reporting difficult. Understanding these roadblocks is critical to developing more resilient and impactful scope 3.1 measurement practices.
- Data availability and quality: Collecting high-quality data is often a bottleneck, with many organizations lacking the systems to track product-level or supplier-specific emissions. Without the proper tracking in place, emissions calculations rely on less accurate methods, making it difficult to reflect or meet reduction efforts.
- Supplier inconsistencies and allocation complexities: Even when suppliers share emissions data, the methodologies, boundaries, and underlying assumptions across them will vary widely. This adds an extra layer of difficulty to data aggregation. Additionally, the allocation of supplier emissions may vary based on the supplier’s chosen method, such as economic (based on spend and supplier revenue/emissions) or service-level (based on units purchased and supplier output/emissions). These inconsistencies can significantly affect reported totals, making it challenging to compare suppliers.
- Complex, multi-tiered supply chains: Upstream emissions can span multiple suppliers across different geographies and industries. Visibility often becomes cloudier beyond Tier 1 suppliers, making it difficult to account for emissions generated deeper in the value chain.
- Timing and synchronization: Aligning procurement, emissions calculation, and reporting cycles can be challenging. Delays in supplier disclosures or emissions factor updates can create reporting lags and misalignment.
Top Five Strategies to Reduce Scope 3.1 Emissions
Reducing scope 3.1 emissions requires balancing precise measurement with targeted action. This means identifying high-impact categories, collaborating with key suppliers, and harnessing available emissions data to improve accuracy and accountability. Here are five strategies organizations can use to start driving impact:
- Prioritize key categories and suppliers: Not all purchases contribute equally to emissions. Conduct a hotspot analysis to identify the highest-emitting goods or services and prioritize the top suppliers for engagement. Consider prioritizing the share of emissions, the share of procurement spend, and the current methodology type.
- Engage suppliers and set expectations: Encourage suppliers to measure and disclose their emissions, invest in LCAs or PCFs, and set their own science-based targets. Collaborative initiatives, such as supplier engagement programs, can support progress.
- Leverage readily available supplier reports: Many electronic companies, cloud providers, and industrial products provide detailed emissions data through EPDs, LCAs, and specific service emissions reports. For example, AWS and Google offer detailed emissions reports for data hosting and services. Leveraging these can help reduce uncertainty and improve accounting accuracy in software-heavy organizations. However, they should be utilized with caution, as some providers have faced scrutiny in 2026 for reporting efficiency gains without disclosing cloud-specific energy use or the growth in embodied hardware emissions behind it.
- Identify opportunities for low-carbon inputs: The same reports that help improve reporting accuracy can also provide more detail on the material inputs of purchased goods. This level of information can enable organizations to pursue opportunities for lower-carbon inputs to reduce emissions.
- Invest in centralized data systems: A centralized platform for carbon accounting data management can streamline emissions tracking, improve visibility, and enable scenario modeling. Several of the other strategies cannot be as effective without the right tools in place to manage this key information.
Turning Complexity Into Opportunity
Tackling scope 3.1 emissions may feel daunting, but it’s also where some of the biggest climate opportunities lie. By investing in better data, fostering supplier collaboration, and integrating sustainability into procurement practices, companies can unlock innovation, resilience, and long-term value. Organizations that lead on scope 3.1 will not only meet emerging disclosure standards but will shape the low-carbon supply chains of the future.
Frequently Asked Questions
What are scope 3 emissions, and why do they matter?
Scope 3 emissions are all the indirect greenhouse gas emissions in a company's value chain, everything from raw material extraction and purchased services to product use and disposal. They matter because they're usually the majority of a company's footprint. They also fall outside a company’s direct control, which makes them the hardest to measure and the most scrutinized by regulators and investors.
What is included in scope 3.1 emissions?
Scope 3.1 covers the cradle-to-gate emissions of everything a company buys, i.e. all emissions generated up to the point of delivery. That includes raw materials, intermediate goods like steel and electronic components, packaging, office equipment, professional services, and cloud computing. It captures the supplier's extraction, energy use, manufacturing, waste, and transport. It does not include emissions from using or disposing of your own products, which sit in other scope 3 categories.
What are the methods for calculating scope 3.1 emissions?
There are four. The spend-based method multiplies spend by an emissions factor per dollar, which is fast, scalable, and the usual starting point. The average-data method applies industry emissions factors to physical quantities, like kilograms of steel. The supplier-specific method uses actual supplier data such as LCAs, EPDs, or product carbon footprints, and is the most accurate. Most companies land on a hybrid, the final method, which takes supplier-specific data for high-impact purchases and uses estimates elsewhere.
How can companies reduce scope 3.1 emissions?
Start with a hotspot analysis to identify where emissions are coming from. This will usually show that a small share of suppliers and categories drives most of the footprint. From there, engage those suppliers on measurement and targets, use supplier reports and EPDs to replace estimates with real data, and use that detail to identify lower-carbon inputs. Centralized carbon accounting data makes each of these repeatable rather than a one-off exercise.
Do AI data centers' hardware purchases count as scope 3.1 emissions?
Yes, for a data center operator, servers and chips are purchased goods, and therefore count in scope 3.1.
Decarbonizing Concrete and Steel with Environmental Attribute Certificates
Key Takeaways
- Concrete and steel contribute 13% of global CO2 emissions. These materials represent substantial scope 3 emissions for companies that are building new infrastructure, including data centers.
- Low-emission alternatives and production technologies are nascent and not yet widely deployed.
- Environmental attribute certificates (EACs) are an innovative solution that can stimulate manufacturing of sustainable commodity materials and overcome market barriers to direct physical procurement.
- Relae (formerly Carbon Direct) and Microsoft developed criteria to guide Microsoft’s high-quality EAC procurement, accelerate decarbonization, and catalyze market expansion for decarbonized materials across supply chains.
- These criteria cover seven key areas: qualifying conditions, social harms and benefits, environmental harms and benefits, additionality and baselines, catalytic impact, verifiability, and leakage.
A Vision for Low-Carbon Concrete and Steel
Concrete and steel are essential for modern construction, but are carbon-intensive. Combined, they account for approximately 13% of global carbon dioxide (CO2) emissions. As the demand for data centers and infrastructure development continues to grow, so do the embodied emissions from concrete and steel. There is an urgent need to decarbonize these sectors so that construction of new facilities remains consistent with climate commitments.
However, the markets for low-carbon concrete and steel are still in their infancy. Market barriers such as low production volumes, contracting complexity, geographic concentration of supplies, and long-distance transportation limit buyers’ ability to directly procure low-carbon building materials. As buyers and sellers overcome these barriers, the market for low-carbon building materials will mature, giving producers the confidence to invest in new manufacturing facilities and giving buyers access to decarbonized materials directly in their supply chain.
Environmental attribute certificates (EACs) represent the sustainability attributes of a material commodity, unbundled and transacted separately from the physical commodity. EACs are transacted at a price that reflects the additional cost of sustainably producing the material. While barriers to direct procurement of low-carbon materials persist, EACs can serve as a powerful tool to signal demand for low-carbon concrete and steel, catalyze market expansion, and accelerate decarbonization.
[cta]
Microsoft’s Approach to Emissions from Building Materials
To address embodied emissions and help achieve its ambitious 2030 carbon-negative goal, Microsoft aims to deeply reduce its scope 3 emissions, including from building materials, by more than half compared to a 2020 baseline. In 2023, scope 3 emissions made up over 96% of Microsoft’s total greenhouse gas footprint. To meet its 2030 target, Microsoft is focusing on addressing supply-chain emissions related to data center construction and the embodied carbon of the commodity materials used to build them. Microsoft is already working to decarbonize its building material supply chain using the following three tactics:
- Reduce the need for concrete and steel through innovative building design or the use of lower-carbon alternatives, such as sustainably sourced mass timber.
- Directly engage with suppliers to procure low-carbon alternatives to conventional concrete and steel.
- Invest in and help pilot new low-carbon production pathways.
EACs represent a fourth approach to decarbonization that can both reduce emissions and catalyze industry growth. Taken together with Microsoft’s design, procurement, and investment tactics, these actions underpin a comprehensive strategy for long-term decarbonization of the built environment.
High-Quality EACs Support Decarbonization
EACs offer a virtual, market-driven solution to decarbonize the built environment by allowing companies to support low-carbon material production when physical supply chain barriers impede direct procurement. EACs for concrete and steel function similarly to other market-based decarbonization mechanisms such as sustainable aviation fuel (SAF) certificates in the aviation sector and renewable energy certificates (RECs) in the energy sector.
These mechanisms work by decoupling the environmental benefits of low-carbon production from the physical materials themselves. EACs allow companies to claim the environmental benefits of physical low-carbon concrete or steel production, even if they do not directly or physically source those materials. EACs provide a verified claim that a purchaser has procured a product with lower emissions, enabling companies to meet climate targets and demonstrate their commitment to sustainability.
Due to their virtual nature, which limits physical oversight of the supply chain, EACs also exacerbate risks such as double counting, greenwashing, fraud, social harms, and environmental harms. Therefore, adhering to transparent, rigorous criteria is foundational to mitigating these risks.
New Criteria to Guide Procurement of High-Quality EACs
To support the integrity and effectiveness of EACs in these sectors, Relae and Microsoft have co-developed Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors. These robust criteria serve as a public resource for companies seeking credible and impactful EAC procurement pathways for low-carbon concrete and steel.
The criteria address seven key areas:
- Qualifying conditions: EACs must complement, not displace, direct procurement and represent significant emissions reductions.
- Social harms and benefits: EACs must not further social harms and should promote community engagement and social benefits such as meaningful workforce development opportunities and community climate resilience.
- Environmental harms and benefits: EACs must not perpetuate environmental harm, but instead should mitigate risks and, ideally, provide additional environmental benefits.
- Additionality and baselines: Projects funded by EACs must drive real, meaningful emissions reductions in terms of financial, regulatory, and common practice additionality.
- Catalytic impact: Prioritize transformative technologies with sector-wide decarbonization potential.
- Verifiability: Set a high bar for documentation, transparency, and independent auditing.
- Leakage: Address risks of emissions displacement to support net-positive outcomes.
These criteria provide a robust framework for companies and stakeholders to evaluate and implement commodity EACs effectively, supporting impactful change. They balance rigor with flexibility and acknowledge the nascent state of the markets for low-carbon concrete and steel. Sectoral decarbonization will advance over time, shifting the thresholds for what is considered significant, additional, and catalytic in EAC transactions. This science-driven framework can adapt to advancements in policy, industry practices, and technological readiness, ensuring EACs remain a relevant and impactful tool for years to come.
Sector-Specific Insights
In addition to providing overarching criteria and guidance on procuring EACs for the built environment, Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors also provides insights into the unique challenges and opportunities of decarbonizing concrete and steel.
Decarbonizing Concrete
EACs can support innovative decarbonization strategies for concrete, such as producing alternatives to clinker and cement, adopting supplementary cementitious materials (SCMs), and reducing emissions from cement kilns through electrification or integrating carbon capture and storage (CCS). Performance-based standards and evolving building codes may also unlock new opportunities for low-carbon concrete.
The Global Cement and Concrete Association (GCCA) publishes a rating system, Low Carbon Concrete (or Cement) Ratings, which defines eight separate low-carbon grades (AA through G). These grades correspond to the depth of decarbonization and are based on a sliding scale related to the material’s compressive strength. When developing these criteria, Microsoft considered grades AA through D to be eligible for consideration in its EAC procurements.
Decarbonizing Steel
EACs can support transformative technologies for decarbonizing steel, like direct reduced iron (DRI) with electric arc furnaces (EAF) powered by green or blue hydrogen. This support can enable the steel sector to move beyond incremental improvements and focus on capital-intensive solutions that have the potential to reshape the industry.
ResponsibleSteel, an independent standards and certification organization with membership that is broadly representative of the steel industry, publishes decarbonization progress levels, with four separate grades (PL1–PL4). These grades correspond to the depth of decarbonization and are based on a sliding scale related to the fraction of recycled scrap use in the steel manufacturing process. When developing these criteria, Microsoft included levels PL2 through PL4 for consideration in its EAC procurements.
A Blueprint for EAC Market Development
Relae and Microsoft crafted Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors as a public resource that can help shape the future of the commodity EAC market.
These criteria are designed to:
- Communicate intent: Communicate Microsoft's intent to support the decarbonization and scaling of physical commodity supply chains where they have been previously limited.
- Guide decision-making: Serve as a public guide for Microsoft's decision-making process, explaining the rationale behind pursuing or declining specific EAC pathways.
- Set high-integrity standards: Maintain high integrity for EACs at an early stage, ensuring they are used to enable future physical procurement by supporting market development.
- Stimulate partnership opportunities: Encourage potential partnerships and purchasing pipelines by clearly describing criteria for high-quality EACs.
- Publicly share detailed thinking: Build on previous work and publicly share detailed thinking, aiming to stimulate market development and guide procurement decisions.
Practical Recommendations for Implementing EACs
Whether you are a supplier, buyer, policymaker, or sustainability advocate, these new criteria offer actionable insights to help you navigate the complexities of EACs in the built environment. From setting significance thresholds to ensuring verifiability to avoiding double counting, the criteria provide clear guidance to maximize the impact of EAC-supported projects.
Beyond the technical aspects of EACs, these criteria aim to address their broader social and environmental implications. The criteria focus on the importance of community engagement, transparency, and equitable distribution of benefits in EAC project planning, ensuring that decarbonization efforts contribute to a more sustainable and just economy. The criteria are backed by extensive research, stakeholder consultations, and industry expertise.
[cta]
Frequently Asked Questions
What is an environmental attribute certificate (EAC), and how does it differ from buying low-carbon concrete or steel directly?
An environmental attribute certificate represents the sustainability attributes of a commodity material such as concrete or steel, unbundled from the physical material and transacted separately from it. Direct procurement means a buyer purchases low-carbon concrete or steel and takes physical delivery of it for a specific project. An EAC purchase instead allows a buyer to fund and claim the environmental benefit of sustainably produced materials that are sold as typical commodities, and apply that benefit against conventional commodities in their own supply chain. EACs are priced to reflect the additional cost of producing the material sustainably, which sends a demand signal to producers. This makes EACs useful where market barriers—limited production volumes, geographic concentration of supply, or long-distance transportation—prevent buyers from sourcing low-carbon materials directly.
How do EACs for concrete and steel compare to renewable energy certificates (RECs) or sustainable aviation fuel (SAF) certificates?
Environmental attribute certificates for concrete and steel share a structure with renewable energy certificates and sustainable aviation fuel certificates: each decouples the environmental benefit of low-carbon production from the physical product, letting a buyer fund and claim that benefit without taking physical delivery. There are two key differences. First, conventional RECs represent electricity with a zero-emissions footprint, while every tonne of concrete or steel behind an EAC still carries embodied emissions — the certificate demonstrates reduction against a baseline, not a zero-emission product. Second, REC and SAF markets are established, while EACs for concrete and steel are nascent. Both differences are why rigorous criteria matter: quantifying the reduction credibly is harder, and the virtual structure carries risks of double counting, greenwashing, and fraud.
Will EACs let companies claim emissions reductions without actually reducing their built environment climate footprint?
An EAC purchase does not change the materials in a buyer's own buildings; it funds lower-emission production elsewhere in the market. Credible EAC frameworks therefore require that certificates complement rather than displace direct procurement, that they represent significant reductions against a defensible baseline, and that the funded project would not have proceeded without EAC revenue. The criteria published by Relae and Microsoft enable buyers to address these requirements directly in their procurement processes - addressing the climate and reputational risks of low-quality certificates. Used this way, EACs become an additional tool to address emissions from the built environment, supplementing design changes, direct procurement, and investment in new production pathways.
Who should use these criteria?
Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors, co-developed by Relae and Microsoft, is a public resource intended for four audiences. Buyers pursuing scope 3 reductions can use it to evaluate whether a given certificate represents a credible, additional emissions reduction. Suppliers and project developers can use it to understand what purchasers of high-quality certificates look for before bringing a project to market. Policymakers and standards bodies can draw on it while shaping rules for an emerging market. Sustainability practitioners and advocates can use it as a reference point for assessing claims made about low-carbon concrete and steel. The criteria are designed to evolve as these sectors decarbonize, and users may adapt them to meet their own levels of capability and ambition.