
Research, Analysis, & Point of View
Original insights from the Relae team on the forces reshaping power systems, GHG emissions, environmental markets, nature, and the capital and policies behind them.
In-Depth Research
Criteria for High-Quality Carbon Dioxide Removal
Criteria for High-Quality Low Carbon Fuels
Carbon Capture for Gas-Fired Power Generation
Blogs
How Does Geothermal Compare to Other Clean Firm Power Options?
Key Takeaways
- Geothermal shares the clean firm category with only three other technologies: nuclear, natural gas with carbon capture and storage (CCS), and solar or wind paired with long-duration energy storage (LDES).
- Buyers comparing geothermal to solar or unabated natural gas power contracts are comparing different products: one isn’t firm, the other isn’t clean, and both remain cheaper options because they satisfy less of what buyers currently need.
- Geothermal’s cost premium is real, but so is the value it delivers. Geothermal can reach 90%+ capacity factor, delivering dispatchable clean power around the clock, and it sidesteps the gas turbine manufacturing backlogs and pipeline infrastructure delays slowing other firm power technologies.
- Geothermal is closer to commercial readiness than most buyers realize. As demand for firm, low-carbon power intensifies, geothermal warrants a serious look alongside nuclear and gas with CCS.
Geothermal is Gaining Traction Despite Its Cost Premium
Hyperscalers, corporate energy buyers, and data center developers face unprecedented pressure to procure clean power. Wind and solar have played a major role in meeting this need, but they are intermittent, and load growth is accelerating and changing. This market pressure is creating bottlenecks that cannot be solved without new grid infrastructure and/or substantial additions of energy storage. Geothermal, which does not suffer from intermittency, has gained tremendous momentum as a challenger to wind and solar, yet it carries one seemingly glaring disadvantage: its cost.
Yet, major utilities and hyperscalers alike are lining up for geothermal offtake anyway: Southern California Edison and Google have signed separate contracts with Fervo, and Meta has two 150 MW agreements in place with Sage and XGS. These contracts are signaling a growing shift in power markets: not all megawatt-hours are created equal, and the cheapest contracts may no longer contain what buyers truly need.
Fast, Clean Firm Power: What Buyers Need Today
In the clean firm power evolution, clean came first. Buyers signed solar and wind power purchase agreements (PPAs) and matched their annual consumption with renewable energy contracts, or offset them with renewable energy certificates (RECs). With lax carbon accounting, solar and wind remain unbeatable on price. But annual emissions tallies conceal something important—a buyer can procure as much renewable electricity as it consumes over a year while still depending on the rest of the grid during the hours when those resources are unavailable. To close that gap, buyers need a source that delivers clean power around the clock, firmly in every hour, on demand.
Two unforgiving demands have followed since: speed and location. With today’s rapid buildout of new load, a power source needs to come online in time to deliver power when the customer needs it. It is also important to connect near a customer’s location because existing transmission assets are often fully subscribed. Failure on either axis can disqualify a project. However, a contract that can meet all attributes: clean in every hour, firm on demand, quick to deliver, and able to reach the load, might be the best (or only) option available. It is also likely to be considerably more expensive than those annual solar benchmarks that only met the clean condition.
Four Technologies Make the Clean Firm Power Shortlist
Given this strict set of constraints, what power options should buyers consider? The right set of technologies should aim to solve as many of the aforementioned conditions as possible, and that leaves a fairly tight shortlist:
- Solar or Wind paired with Long-Duration Energy Storage (LDES): To achieve the level of reliability that many buyers, including data centers, require, solar or wind would have to be paired with LDES, beyond 4–8 hours, to be able to cover evening hours and remain online during increasingly common extreme weather events. While there are promising LDES technologies on the horizon, most remain expensive and not yet widely commercial. Costs rise significantly compared to a standard solar or wind PPA, and viability varies by location. This will be increasingly competitive as storage costs fall, but not yet a mature firm-power solution at scale.
- Natural Gas with CCS: With large amounts of unabated natural gas generation coming online, CCS is an attractive option to mitigate a large portion of these emissions while retaining time to power (by building gas first and adding CCS later) and the dispatchability of gas-fired power. On the flip side, CCS is operationally complex, geographically restricted, and - unlike other options here - failure at any point in the CCS chain directly impacts the carbon intensity of power delivered. Gas-fired generation is also reliant on the gas delivery pipeline infrastructure, which may face capacity constraints. Finally, natural gas with CCS is 50% more costly per MWh than unabated firm gas.
- Nuclear: Nuclear is seeing renewed interest from a wide range of corporate buyers and investors. Conventional nuclear and small modular reactors (SMRs) are attracting funding and offtake deals. While nuclear power holds high potential, long development timelines, high capital costs, and technology risk remain barriers to commercializing the next wave of nuclear technologies.
- Geothermal: Geothermal can provide firm, dispatchable, and low-carbon power with capacity factors typically above 90%. Development timelines can be faster than nuclear in regions where resources are already proven, with some projects approaching commercial readiness now. Geothermal technology is still geographically constrained, but enhanced geothermal systems (EGS) are poised to expand their geographical flexibility by reducing the number of siting variables.
How to Evaluate the Right Clean Firm Power Technology for Your Project
How do these various options stack up? We compared them across six dimensions:
- Firmness: how reliably a resource can deliver power on the hour, on demand
- Carbon: the lifecycle emissions intensity when considering the operational emissions of the generating facility and the broader system carbon impacts required to meet any reliability gaps
- Time to power: a measure of how long it takes to get from “we need power” to delivery, including interconnection and schedule risk
- Cost (current): the likely cost of a PPA if signed today
- Execution risk: a measure of how likely a project’s claims regarding price, timing, and performance will hold
- Siting flexibility: a measure of how constrained a resource is to a specific geography
This frame is ultimately something the buyer should score themselves; below you will find our current read. Red (unfavorable) represents a weakness that can end an evaluation on its own, green (favorable) means the dimension won’t constrain the decision, and yellow (moderate) sits somewhere in between.
Comparing the clean firm power options is, perhaps ironically, challenging along the “clean” and “firm” lines. Every serious contender delivers low-carbon power around the clock, because that is the price of admission. Not one technology earns an unfavorable rating in those categories. And that is the catch: every weakness in the comparison table sits somewhere else. The dimensions that ultimately win (or end) these contracts may be the ones that the “clean firm” label can obscure or oversimplify.
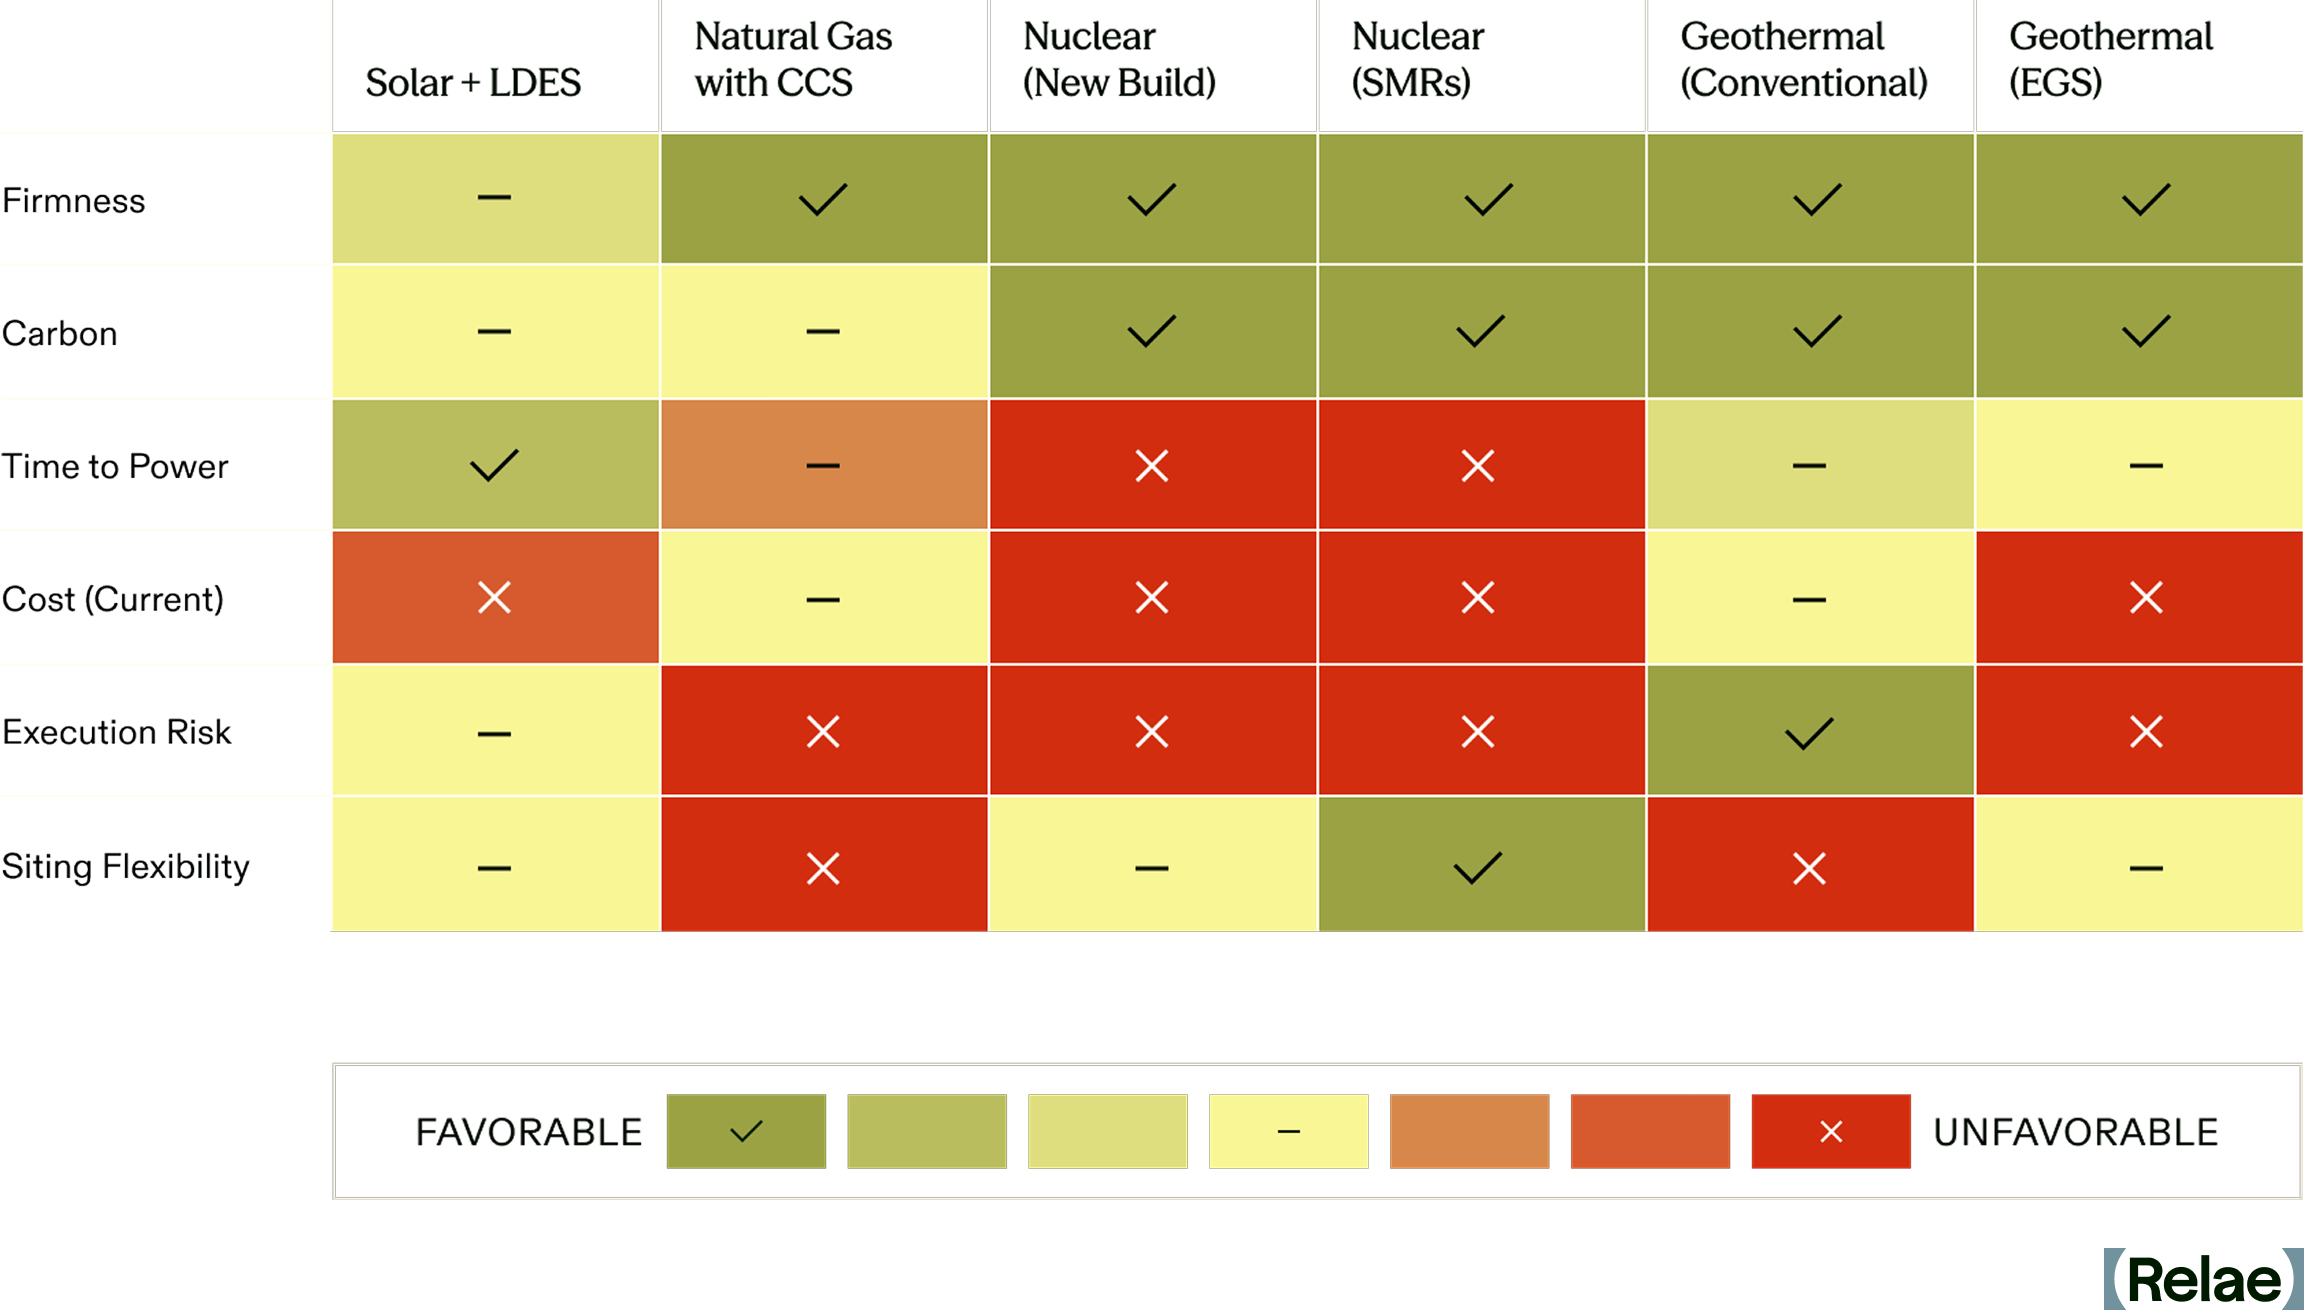
A resource that cannot be energized for a decade, or sited near load, or delivered at a price a buyer cannot defend internally, may be infeasible regardless of what else it offers. None of the four clean firm generation technology groupings clear every hurdle today, but they can satisfy different buyer priorities.
Solar or wind with LDES offers more buyer flexibility, at a price. Enough generation, storage, and other firming can deliver the reliability required, and the buyer sets that target. But the increments get expensive quickly, especially when reliability gaps remain long or unpredictable. Covering more hours means more storage and more generation to fill it, so each step toward firmness parity costs more than the one before it. Firming shortfalls also carry carbon consequences, depending on what gets called to compensate. Those emissions may be absent from GHG accounting ledgers, but that doesn’t stop them from hitting the atmosphere.
Gas with CCS is challenged by execution and siting because the product depends on a chain: gas generation, capture, transport, and a permitted storage site capable of permanent CO2 disposal at scale. Each piece can be developed and tested, but low-carbon electricity requires all of them to work together, which can only be demonstrated once all are built. A buyer cannot substitute a link, and cannot observe the whole chain before committing. Clean, in this sense, is conditional, and the delivered power could end up being far more carbon-intensive than advertised.
Nuclear ranks poorly on time, cost, and execution, but full-scale reactors and small modular reactors carry those weaknesses differently. A large reactor arrives in one piece, and its schedule and final cost come into focus as construction advances. By then, years and billions are committed; a buyer cannot learn from a fraction of a reactor before deciding whether to finish it. Small modular reactors are designed to break that capacity into increments a buyer could add as demand grows, which would ease the one-piece problem. But none are operating commercially in the US yet, and the signed deals target first power in the 2030s, so the modular promise is still years out.
Geothermal’s weaknesses work somewhat differently. Conventional hydrothermal is tightly constrained by location, which buyers can screen before choosing where to procure, or co-locate where possible. Next-generation geothermal, including EGS, could widen that geography considerably.
For EGS, the largest remaining uncertainty is execution: whether the developers can replicate successful drilling and reservoir performance at commercial scale. Part of that risk belongs to the rock, and no contract can make a reservoir perform. But drilling also produces information before the entire project has been built, and geothermal capacity can often be developed incrementally as needed. A buyer can require resource evidence before committing, tie later commitments to demonstrated performance, or spread procurement across projects rather than depend on a single field.
Geothermal’s flexibility has limits. A buyer who needs full capacity by a fixed date may have little room to wait for wells to perform before committing to the next phase. And successful wells do not eliminate risk in project expansion or guarantee performance in other locations. Execution risk stays with the resource. What geothermal offers is more opportunity to learn about that risk while a buyer can still do something about it.
Revisiting the Geothermal Premium
Geothermal contracts, especially EGS, remain expensive. But that premium looks different on this side of the comparison. Clean has a cost, but so does firmness, speed, reach, and execution. Every clean firm option pays for those attributes somewhere. Solar and wind contracts will remain cheap by comparison, but it’s the wrong comparison: the market signing geothermal contracts is pricing a much larger product.
That still leaves a hard decision. Geothermal and gas with CCS carry execution risk and siting constraints. Nuclear asks more of the buyer on cost and time. Firmed solar asks more as reliability requirements rise. The best option will change with each buyer, location, and project. Geothermal’s place in that choice is changing quickly. EGS is expanding where projects can be developed, drilling costs are falling, and commercial experience is growing. Those advances are bringing geothermal into consideration for buyers who previously had little reason to look its way.
And that may be the more revealing aspect of the geothermal market today: buyers are signing those contracts with the alternatives in full view. Their decisions offer an early indication of what clean firm power delivered in the right place and at the right time is worth, and which risks buyers are willing to carry to get it.
Frequently Asked Questions
Is Geothermal Cheaper Than a Solar PPA?
No, a geothermal power contract can be significantly more expensive than a solar PPA. But they're not the same product: solar meets annual clean-energy targets, while geothermal delivers firm, dispatchable power around the clock, which is why buyers are increasingly comparing it to nuclear and gas with CCS instead.
Is Geothermal Cheaper Than Solar with LDES?
Not necessarily on a per-contract basis, but the cost structures behave differently. Solar with LDES gets more expensive with every additional hour of reliability a buyer needs, since covering more hours means adding both more storage and more generation to fill it. Geothermal's premium, by contrast, is priced into the contract upfront as a firm, dispatchable product from day one.
How Does Geothermal's Risk Compare to Gas with CCS?
Differently, in a way that matters to buyers. Gas with CCS depends on a chain (generation, capture, transport, and storage) that can only be verified once the whole system is built, so a buyer can't test it piece by piece. Geothermal generates performance data incrementally through drilling, letting buyers require resource evidence or tie commitments to demonstrated results before committing further, though this data does not come free.
Which Deploys Faster, Geothermal or Nuclear?
Geothermal, in regions with already-proven resources. Fervo's Cape Station, for example, broke ground in 2023 and is on track for first power in late 2026 and 500 MW by 2028: a fraction of a typical new-nuclear large reactor timeline.
The 2026 Criteria: Designing and Delivering High-Quality Carbon Removal
Key Takeaways
- High-quality carbon dioxide removal (CDR) projects require robust project management and oversight to deliver credits on time and at the promised volume; delivery risk is a distinct concern that quality standards alone don't catch.
- The sixth edition of the Criteria for High-Quality Carbon Dioxide Removal is the first to provide an approach to evaluating both credit quality and delivery risk, adding a new delivery risk appendix built around the TECOP framework: technical, economic, commercial, organizational, and political risk.
- The 2026 Criteria provides a framework for developers, investors, and buyers to evaluate both project quality and delivery risk.
- This year's update draws on 170 new diligence reports from 2025 and the input of more than 60 subject matter experts, building on a foundation of six years of lessons from professional diligence across hundreds of real-world CDR projects.
The Criteria Create a Shared Standard for Credit Quality
Relae (formerly Carbon Direct) first launched the Criteria for High-Quality Carbon Dioxide Removal (the Criteria) in collaboration with Microsoft in 2021 to help rapidly and justly scale the development of high-quality carbon dioxide removal (CDR) credits. The market didn't yet have a shared definition of what "high-quality" meant, so we laid out transparent, science-based benchmarks that gave developers, investors, and buyers a common foundation to work from. Every year since, we have gone back and sharpened those benchmarks so that they keep pace with the quickly evolving industry.
But a shared definition of quality doesn't guarantee the delivery of credits as planned. The 2026 edition is the first to tackle that gap directly, pairing the Criteria's quality benchmarks with a new framework for evaluating delivery risk.
The Six Principles of High-Quality Carbon Removal
The Criteria defines six science-based principles that apply across engineered, hybrid, and nature-based CDR approaches:
- Social harms, benefits, and environmental justice: The extent to which the project prevents new social harms to people and communities, reduces existing harms, and provides meaningful benefits distribution.
- Environmental harms and benefits: The extent to which the project minimizes and mitigates environmental harms, as well as provides environmental benefits.
- Additionality and baselines: The evidence that the project’s carbon removal would not have occurred without carbon finance.
- Measurement, monitoring, reporting, and verification (MMRV): The ability to accurately quantify carbon removal in a repeatable and verifiable way, and to develop a plan for long-term monitoring of the project.
- Durability: The likelihood that removed carbon remains stored over time, with mechanisms in place to mitigate reversal risk.
- Leakage: The extent to which project activities cause increased emissions elsewhere.
These principles provide a consistent foundation for carbon removal procurement, evaluation, and project benchmarking.
[cta]
Supporting the Delivery of High-Quality CDR Credits
"Projects must work better operationally and be more commercial. Quality and delivery risk shape a project's risk profile at every point in its life, and this edition of the Criteria is the first to give buyers a way to judge both at once." Dr. Julio Friedmann, Chief Scientist, Relae
Designing projects to meet high-quality CDR criteria is only part of the challenge. Effective project planning, management, and execution are also essential to ensure that high-quality CDR tonnes successfully reach the market as planned. As discussed in CDR 2.0: Five Pillars of Successful Project Deployment and Delivery, managing delivery risk requires developers, investors, and buyers to understand the risks that can affect project success and align on how these risks are assessed and mitigated.
To support this alignment, the 2026 Criteria introduced a new Delivery Risk Appendix, which establishes a common framework and language for identifying and evaluating key delivery risks for the first time. Drawing on our broader observations of the carbon removal market and established approaches to project risk management, the appendix highlights common delivery risks across two broad CDR project types: open systems and closed systems. It organizes these risks into five categories: technical, economic, commercial, organizational, and political factors, also known as the TECOP framework.
The TECOP Framework for CDR Delivery Risk
- Technical delivery risks are associated with the technical feasibility of the project design, implementation, and long-term operation of the project
- Economic delivery risks are associated with the project’s financing structure, financial modeling assumptions, and expenditure profile
- Commercial delivery risk reflects the extent to which a project's purchase agreements, supply arrangements, and key contractual relationships are secured or well-advanced.
- Organizational delivery risks center on the project developer's capacity and capability to successfully plan, execute, and manage a project of the appropriate size and complexity.
- Political delivery risks are associated with governance, policies, and potential changes in regulatory environments, as well as the local communities’ perception of and willingness to participate in projects.
New Additions to the 2026 Criteria
Since publishing the 2025 Criteria, Relae has conducted an additional 170 diligence reports across established and emerging CDR pathways, ranging from reforestation and enhanced rock weathering (ERW) to direct air capture (DAC). To date, less than 10% of all 900+ projects the team has reviewed have met the bar for high-quality. These diligence efforts, together with insights from market analysis and ongoing synthesis of the latest scientific and technical literature, have deepened our understanding of how CDR project quality has evolved over the past year.
The 2026 Criteria leverage these insights and the expertise of more than 60 subject matter experts to reflect advances across the CDR industry and address key weaknesses that remain in the market across all pathways.
A few of the most significant updates to the Criteria include:
Addition of Direct Counterparty Considerations: Direct counterparties are the organizations that developers partner with, and are structurally dependent on, to generate credits. This can include:
- Primary feedstock providers (e.g., mines, biomass providers, tree nurseries)
- Major implementing partners (e.g., local implementation partners, base facilities, transportation and storage providers, major product offtakers)
- Land owners that make up a significant proportion of project land
To reflect the key role that direct counterparties play in high-quality credit generation, developers must conduct diligence and disclose on their direct counterparties to demonstrate that they are not causing social or environmental harm.
Increased Rigor for Enhanced Rock Weathering Projects: Over the past year, ERW’s presence in the CDR market has grown substantially, and so too has the market’s understanding of the corresponding scientific and technical rigor required to deliver high-quality tonnes. The 2026 Criteria raised the bar for how ERW projects:
- Measure and prove their carbon removal claims
- Mitigate risks related to potentially toxic elements (PTEs)
- Incorporate more sophisticated farmer protections and benefits
Projects now have to back up their numbers with multiple physical field measurements, not just computer models; and they must now track and account for every significant loss pathway, from plants taking up minerals to carbon escaping from rivers and oceans.
Use of Dynamic Baselines for ARR Projects: ARR projects are increasingly using dynamic baselines to provide a more accurate reflection of the counterfactual scenario (e.g., what would have happened in the absence of the project). This is reflected in the 2026 Criteria with a requirement that ARR projects, with the exception of agroforestry projects, use dynamic baselines with statistically matched controls.
What’s Next?
The 2026 Criteria create a clear, science-driven framework for both designing and delivering measurable, just, and durable carbon removal. However, the Criteria cannot ensure high-quality tonnes reach the market on its own; good criteria do not replace robust diligence. To put these criteria into practice, we encourage developers, standard-setting bodies, buyers, investors, and policymakers to consider how the Criteria can be used to inform their role in enabling the carbon market to deliver high-quality tonnes and to engage in deep diligence and ongoing monitoring over the life of a project.
This edition of the Criteria reflects what we have learned over the past year, but our work is not done. We will continue to update it so that it remains a living document that evolves with the science and the market. To do so effectively, it must be a collaborative effort; we welcome input from carbon market actors, academia, and communities.
Frequently Asked Questions
Who publishes the Criteria for High-Quality Carbon Dioxide Removal, and how often is it updated?
Relae (formerly Carbon Direct) first published the Criteria for High-Quality Carbon Dioxide Removal with Microsoft in 2021 and have updated it every year since. The 2026 edition reflects six years of lessons from real-world project diligence and advances in climate science.
What are the six principles of the Criteria for High-Quality Carbon Dioxide Removal?
The Criteria define six science-based principles that apply across all CDR pathways: social harms, benefits, and environmental justice; environmental harms and benefits; additionality and baselines; measurement, monitoring, reporting, and verification (MMRV); durability; and leakage.
What CDR pathways does the Criteria cover?
The Criteria include pathway-specific criteria across nine CDR pathways: afforestation, reforestation, and revegetation (ARR); mangrove forestation; improved forest management (IFM); soil carbon; enhanced rock weathering (ERW) in croplands; biomass carbon removal and storage (BiCRS); abiotic marine CDR; carbon mineralization; and direct air capture (DAC).
What is delivery risk in carbon removal?
Delivery risk is the likelihood that a project generates credits on the timeline and at the quantity committed to buyers. It's a distinct concern from credit quality: even a high-quality project can fail to deliver as planned because of technical, economic, commercial, organizational, or political risk, the five categories the Criteria's TECOP framework evaluates. The 2026 Criteria's new Delivery Risk Appendix gives developers, investors, and buyers a shared benchmark for identifying and managing these risks before they derail a project.
What's the relationship between carbon removal credit quality and delivery risk?
Credit quality and delivery risk are distinct but interrelated. A project that fails to deliver credits as planned reduces the availability of high-quality CDR tonnes in the market, and weaknesses in credit quality can themselves increase delivery risk by creating buyer uncertainty or limiting access to project financing. The 2026 Criteria provides a framework for evaluating both quality and delivery risk.
Carbon Direct Is Now Relae
Why I Started Carbon Direct
I have spent most of my career in energy and commodity markets. In these roles, I found that the most consequential opportunities come from recognizing structural change: when emerging market growth fundamentally alters commodity demand, when shale technology fundamentally reshapes the outlook for energy supply, or when physical infrastructure can no longer keep pace with economic change.
Those are the same types of questions that led me to start Carbon Direct in 2020.
Companies and governments were starting to consider climate decision-making in their most important planning. Enormous commitments were being made around carbon removal, low-carbon fuels, clean power, and industrial decarbonization. But many of those decisions were being made without independent scientific and technical expertise. I believed there was a need for a company that could bring serious scientific judgment into these consequential climate and commercial decisions.
So we built one.
Carbon Direct assembled a world-class team of scientists, engineers, market analysts, and policy experts who could evaluate our clients’ most difficult climate questions. Since 2020, more than 150 companies across six continents have relied on us to help with some of their hardest energy and climate decisions. We have completed more than 900 project diligences and have reviewed more than half of all tonnes contracted through announced carbon removal offtake agreements worldwide. Together with Microsoft, we established and annually updated the Criteria for High-Quality Carbon Dioxide Removal. In 2025, we acquired Pachama, bringing advanced digital monitoring, reporting, and verification technology into how we evaluate the integrity of forest carbon projects.
The Climate and Energy Moment We Met
Over the past few years, we saw developments on the horizon reshaping the climate and energy space. The digital economy became an energy and infrastructure economy, and our clients increasingly leaned on us to help make the decisions shaping this transition. We realized that companies cannot make credible climate commitments without understanding how electricity demand, grid constraints, and fuel choices are changing.
Carbon Direct increasingly worked at the center of a new set of critical decisions, and we spent the last year strategically reorganizing our team, our focus, and our capabilities around that shift to better meet this moment. But we were still operating under a company name that described only one important part of what we do.
I am enormously proud of what we built as Carbon Direct.
But the work we do has outgrown our name.
Today, Carbon Direct Becomes Relae
Relae - “ree-lay” - draws on the idea of a relay. In an electric system, a relay opens or closes a circuit in response to a signal. In a relay race, progress depends on a team carrying the work forward without losing momentum. The new name broadens and defines our scope. It does not change the climate mission with which we began.
Carbon removal remains central to our work and to our clients’ plans. Any credible pathway for addressing climate change requires large-scale carbon removal and the ability to deliver those removals with integrity. As Relae, our mission remains the same: to help organizations turn commercial and climate goals into credible, science-backed action. Our growing work in power and energy builds on that foundation. Relae's position at the intersection of climate and energy allows us to embed climate considerations into energy and power decisions from the start.
Where We Go From Here
Relae is structured around four areas of expertise: Power & Energy, Environmental Markets, Natural Capital, and Strategy & Analytics. Relae is one team that can move across the full spectrum of challenges and opportunities facing decision-makers today and in the years to come.
I believe consequential decisions deserve integrated intelligence, scientific rigor, and independent judgement. This is what Relae is built to do: bring climate into the decisions shaping the next generation of energy and infrastructure and help clients act on what is scientifically credible. Relae gives us a name that reflects the breadth and importance of this opportunity. I’m excited for this new chapter and how Relae meets the work ahead.
Why AI Data Centers Are Being Blocked: A Project-Level Examination
Key Takeaways
- Community opposition has blocked, withdrawn, or stalled more than $170 billion in announced AI data center investment across 20 US states since January 2024. The pace is accelerating: 6 cancellations in 2024, 25 in 2025, and more than 20 additional cancellations by May 15, 2026.
- Data center opposition is bipartisan. It spans red and blue counties, every region, and multiple grid operators, with nearly two-thirds of the blocked investment sitting in counties that voted for Donald Trump in 2024.
- Process and transparency, more than resource concerns alone, drive the fastest and most durable opposition. How a developer runs the engagement process shapes both community sentiment and the project’s ultimate success.
How Many AI Data Center Projects Have Been Cancelled?
Between January 1, 2024, and May 15, 2026, community opposition blocked, withdrew, or stalled 46 announced AI data center projects across 20 US states, representing more than $170 billion in announced investment. These values are disclosed or derived for 35 of the 46 projects; the remaining 11 carry no public figure.
[stat]
The pace of successful opposition has accelerated sharply. Cancellations rose from 6 in 2024 to 25 in 2025. The first five months of 2026 added more than 20 additional cancellations, the fastest stretch on record.
Virginia leads the state count with 11 blocked projects, followed by Indiana with 7 and Texas with 5. Together, those three states account for roughly half of all cancellations in the dataset. The PJM grid region carries the largest single share of blocked investment at $70 billion across 13 projects, followed by MISO at $37 billion.
Is Opposition to Data Centers Bipartisan?
Yes. The opposition wave crosses party lines on every measure we examined. Republican-leaning counties hosted 28 of the 46 host counties (61%), Democratic-leaning counties hosted 16 (35%), and 2 fell within five points.
Weighted by announced investment, about two-thirds of blocked dollars sat in Republican-voting counties. Strong Republican counties (those Trump won by more than 15 points) account for $99 billion across 23 projects. Strong Democratic counties account for $29 billion across 9 projects. The remaining $44 billion spans Lean Republican, Tossup, and Lean Democratic counties.
Why Are Communities Opposing Data Centers?
Communities raise a consistent set of concerns across the country: water demand, electricity rates, air quality where developers propose gas co-generation, rural character, and a lack of transparency in the development process.
Across the seven cases that we studied in depth, process, and transparency concerns were the most consistently cited factors associated with opposition. Non-disclosure agreements between developers and local officials, ownership structures in which the ultimate end-user was not publicly identified, and closed-door pre-application negotiations produce opposition faster and more durably than any other concern.
The pattern holds across very different communities: a diffuse civic mobilization in rural Georgia, an NGO water coalition in a Texas college town, a conservation coalition anchored by the Southern Environmental Law Center in Southside, Virginia, and an institutional civic organization with legal-expert and celebrity support in northern Virginia. Each produced the same outcome, and each flagged process and transparency as a dominant or top-three concern in the public record.
By the time a project reaches its first public hearing against organized community opposition, the political path of the project is largely set. Late-stage benefits packages consistently fail to reverse that trajectory. Communities read them as concessions, not commitments.
Assess Community Opposition Risk Before You Site
Community opposition is now a structural feature of the AI data center siting environment. The patterns are clear enough to act on now. Relae's Community Impacts team helps developers and capital partners implement responsible development standards through pre-siting community intelligence, calibration of benefits design to specific community contexts, and building the verification scaffolding that turns commitments into outcomes.
[cta]
Frequently Asked Questions
Which states are banning data centers in the US?
The first statewide moratoriums on data centers have arrived. In July 2026, Governor Hochul signed the country's first statewide moratorium, an executive order pausing state environmental permits for up to one year for new data centers of 50 MW or more. Texas followed weeks later, halting approvals of new data center grid connections until state regulators audit their power, water, tax, and ownership details. This is a snapshot from August 2026, and we will likely see additional changes in the months ahead.
The local picture is more developed. Individual municipalities and counties have adopted moratoria and zoning ordinance amendments that block or restrict data centers within their jurisdictions. The City of Peculiar, Missouri, removed data centers from its light-industrial zoning entirely. Monroe County, Georgia, and Jones County, Georgia, both adopted moratoria after project denials in 2025. Cassville Township, Wisconsin, and San Marcos, Texas adopted zoning and code amendments in 2026. State legislatures in Virginia, Indiana, Texas, and Missouri have taken up data center siting, ratepayer, and permitting legislation, though most bills remain in progress rather than enacted.
How much data center investment has been blocked in the US?
More than $170 billion in announced AI data center investment has been blocked, withdrawn, or stalled by community opposition across 46 projects and 20 US states between January 1, 2024 and May 15, 2026.
Relae arrived at this figure from data on 35 of the 46 projects; 11 have no publicly disclosed investment value. The pace has accelerated sharply: 6 cancellations in 2024, 25 in 2025, and more than 20 additional cancellations in the first five months of 2026 alone. Virginia leads the state count with 11 projects. The PJM grid region carries the largest single share of blocked capacity at $70 billion across 13 projects.
What causes a data center project to be cancelled by community opposition?
As of August 2026, communities cite a consistent set of concerns across cancelled projects: water demand, grid strain and residential rate impacts, air quality where developers propose gas-fired co-generation, rural character and farmland conversion, and lack of transparency in the development process.
In the seven cases we studied in depth, process and transparency were together the most consistent driver of opposition. Non-disclosure agreements between developers and local officials, shell LLC ownership structures that conceal the end-user, and closed-door pre-application negotiations produce faster and more durable opposition than any single resource concern. Late-stage benefits packages consistently fail once that transparency-driven frame has formed.
Dynamic Line Rating: The Fastest Gigawatt Is the One You Already Have
Key Takeaways
- Power demand is outrunning buildout. Meeting large load growth requires more than new generation; it requires faster interconnection and congestion relief on existing transmission lines.
- Dynamic line rating (DLR) is available today, deploys in months, and enables faster speed-to-power. On the right thermally congested lines, DLR can unlock more capacity at a fraction of new infrastructure cost. In one utility demonstration, 5% to 10% of additional capacity was enough to clear most of the congestion on the lines studied.
- DLR has been held back by weak incentives, but that is changing. Utilities earn a regulated return on capital they invest in new assets, which favors building new infrastructure over lower-cost solutions like DLR. Load growth and new Federal Energy Regulatory Commission (FERC) mandates are starting to shift the calculus.
The Grid Cannot Expand Fast Enough for AI Demand, But It Can Carry More
Power demand is booming as data centers scale across the US grid, and current grid infrastructure cannot supply it. This constraint is physical, not financial. Meeting this demand requires a significant amount of power generation and infrastructure upgrades. More than 2 terawatts of generation and storage sit in interconnection queues, roughly 1.5x the total installed generation capacity in the US.
Regional markets are working to accelerate generation buildouts, but connecting that generation to the transmission network remains expensive and slow to match speed-to-power needs. New high-voltage lines take years to permit, cost between $2 million and $6 million per mile to build, and major projects routinely take five to ten years from identification to energization. For example, PJM Interconnection LLC (PJM) identified the Doubs–Goose Creek 500 kilovolt (kV) corridor as a bottleneck feeding Data Center Alley in 2023 and set June 2027 as the date a fix was needed. Dominion Energy's published schedule for its portion of that rebuild anticipates a completion date of 2031.
A number of studies1,2 show there is headroom in the bulk transmission system. Grid-enhancing technologies, such as dynamic line rating (DLR), can convert part of that headroom into capacity today while new generation and transmission are being built. DLR lets suitable transmission lines increase their carrying capacity in real time, unlocking that headroom at a fraction of the cost of a buildout. Realizing that value is a targeting exercise with a key question: On which thermally limited lines can DLR actually relieve congestion?
What Is Dynamic Line Rating?
Dynamic line rating is a method for calculating a transmission line's real-time carrying capacity using live weather and conductor-temperature data. It lets grid operators safely carry more power whenever weather conditions allow.
Most transmission lines operate under a static rating: a fixed, conservative limit on current, set for worst-case weather and held all year. The limit is based on temperature, because pushing too much current can overheat the conductor wire. Metal conductors expand as they heat, which can make them sag and touch trees or other obstacles, causing short circuits or fires. Real conditions almost always cool a conductor better than the worst-case assumption a static rating is built on. That means the line can carry more current while staying at the same maximum conductor temperature, and therefore within the same sag and clearance envelope. That headroom is exactly what DLR captures: instead of leaving it on the table, DLR recalculates the line's rating in real time so operators can use the extra capacity safely.
Beyond a static rating is the ambient-adjusted rating (AAR), which many utilities have begun adopting. An AAR recalculates the rating from forecast ambient air temperature, typically hourly and out to several days. DLR goes further, adding wind speed and direction, solar heating, and in some deployments the conductor's measured temperature.
DLR technologies rest on a heat-balance algorithm: how fast a line heats up (from electric current and sunshine) versus how fast it cools off (from wind and cold air). The calculations are standardized in IEEE 738 in North America and CIGRE 601 internationally. The data feeding those calculations can come from line-mounted sensors, weather models, or both, depending on a tradeoff between per-span accuracy and the cost of installing sensors along every span.
Even so, DLR remains limited in the US, and AAR has been slow to arrive. FERC's Order 881 required the transmission providers it regulates to adopt AAR by July 2025, but FERC has granted numerous extensions. PJM became the first to fully implement AAR in March 2026, while Midcontinent Independent System Operator (MISO) and New York Independent System Operator (NYISO) are not expected until 2028.
The Near-Term Value of DLR: Reducing Grid Congestion
DLR's value is immediate. It can be installed in months, not years, so a currently congested line can start carrying more power the moment conditions allow, reducing congestion right away. When cheaper generation is available upstream of that line, DLR cuts costs directly, because grid operators no longer need to dispatch pricier generation downstream of the congestion to supply load. That means DLR can reduce congestion costs in the current delivery year, compared to a transmission line rebuild that sits in a decade-long queue.
Over a longer horizon, utility planners can build that headroom into long-term capacity models. This is important, because current capacity-expansion and integrated resource plan (IRP) models still run on static or seasonal ratings, and typically leave out the potential gains from grid-enhancing technologies like DLR.
NERC's large loads white paper and FERC's RM26-4 rulemaking both raise the issue of how utilities can absorb multi-hundred-megawatt data center requests without a decade-long transmission build. Solutions like DLR are one of the few tools that can compress that timeline.
The hardware itself is cheap: sensors and data management cost a small fraction of any physical upgrade. That means the economics comes down to identifying the lines that benefit most from DLR. This is particularly important because on most US grids, congestion concentrates on a small number of lines that repeatedly reach their limits. On those lines, DLR can cut congestion costs directly and defer costlier upgrades, while its potential on other lines may be far lower. As a result, identifying those high-potential, thermally congested lines is essential.
Proven DLR Examples in the Industry
Real deployments show DLR can reduce a meaningful share of transmission congestion costs, with extra carrying capacity above the static rating running roughly 5% to 30%, depending on how often that capacity is available. In Oncor's ERCOT demonstration, 5% of additional capacity would have relieved up to 60% of congestion on the target lines, and 10% would have practically eliminated it. PPL Electric in Pennsylvania/PJM reports annual customer savings of $23 million after deploying DLR across its initial three lines. The DLR installation cost about $250,000, against a rebuild alternative that would have cost about $50 million and taken far longer.
The contrast abroad is instructive. Austria's grid operator, APG, recorded about $13 million a year in congestion savings across roughly 15% of its network. While these savings are real, it's important to recognize that these results come from single, well-chosen, badly congested lines.
The UK's National Grid began with a two-year DLR trial on a single 275 kV circuit in 2022, expanded to more than 275 kilometers of its network by 2025, with estimated consumer savings of about $26 million a year. In April 2026, National Grid signed a five-year contract covering 585 kilometers more, with most installations due by 2028 and potential savings of up to $66 million. Each expansion followed measured results from the stage before it.
Where the Headroom Is: Screening PJM's Data Center Alley
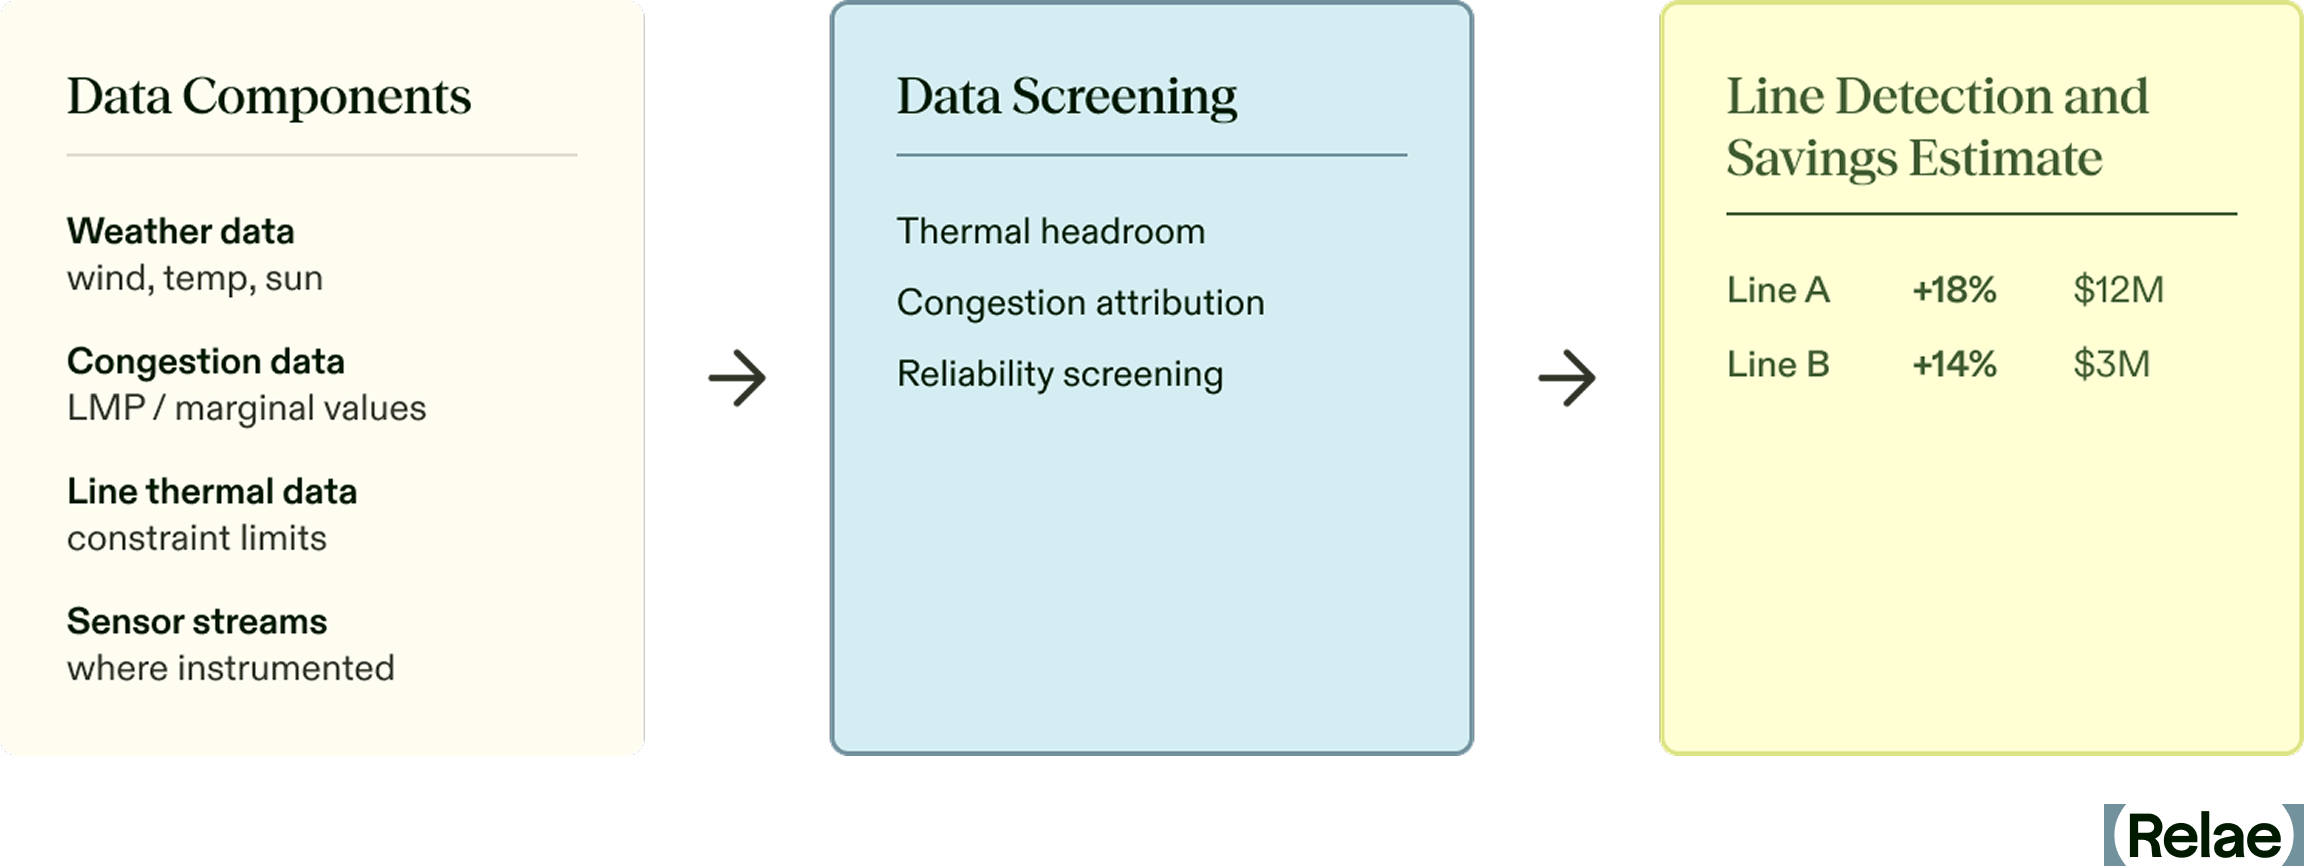
To illustrate the congestion savings from DLR, Relae screened PJM's five-minute real-time market record for every binding transmission constraint in 2025. For each one, we captured the shadow price, the marginal value of relaxing that constraint.3
Our analysis focused on thermal constraints, and then identified lines that bind frequently, in conditions milder than the worst case their static rating was set for, which is when a conductor's true rating sits above its static assumption. For the lines that we identified, congestion costs were added over the binding hours to set a bound on the savings that could result from DLR. That full amount would not necessarily be realized in practice, because the shadow price values only the next megawatt freed, and relieving one line can shift the constraint to the next. However, it serves as a useful estimate for the scale of savings that could be achieved.
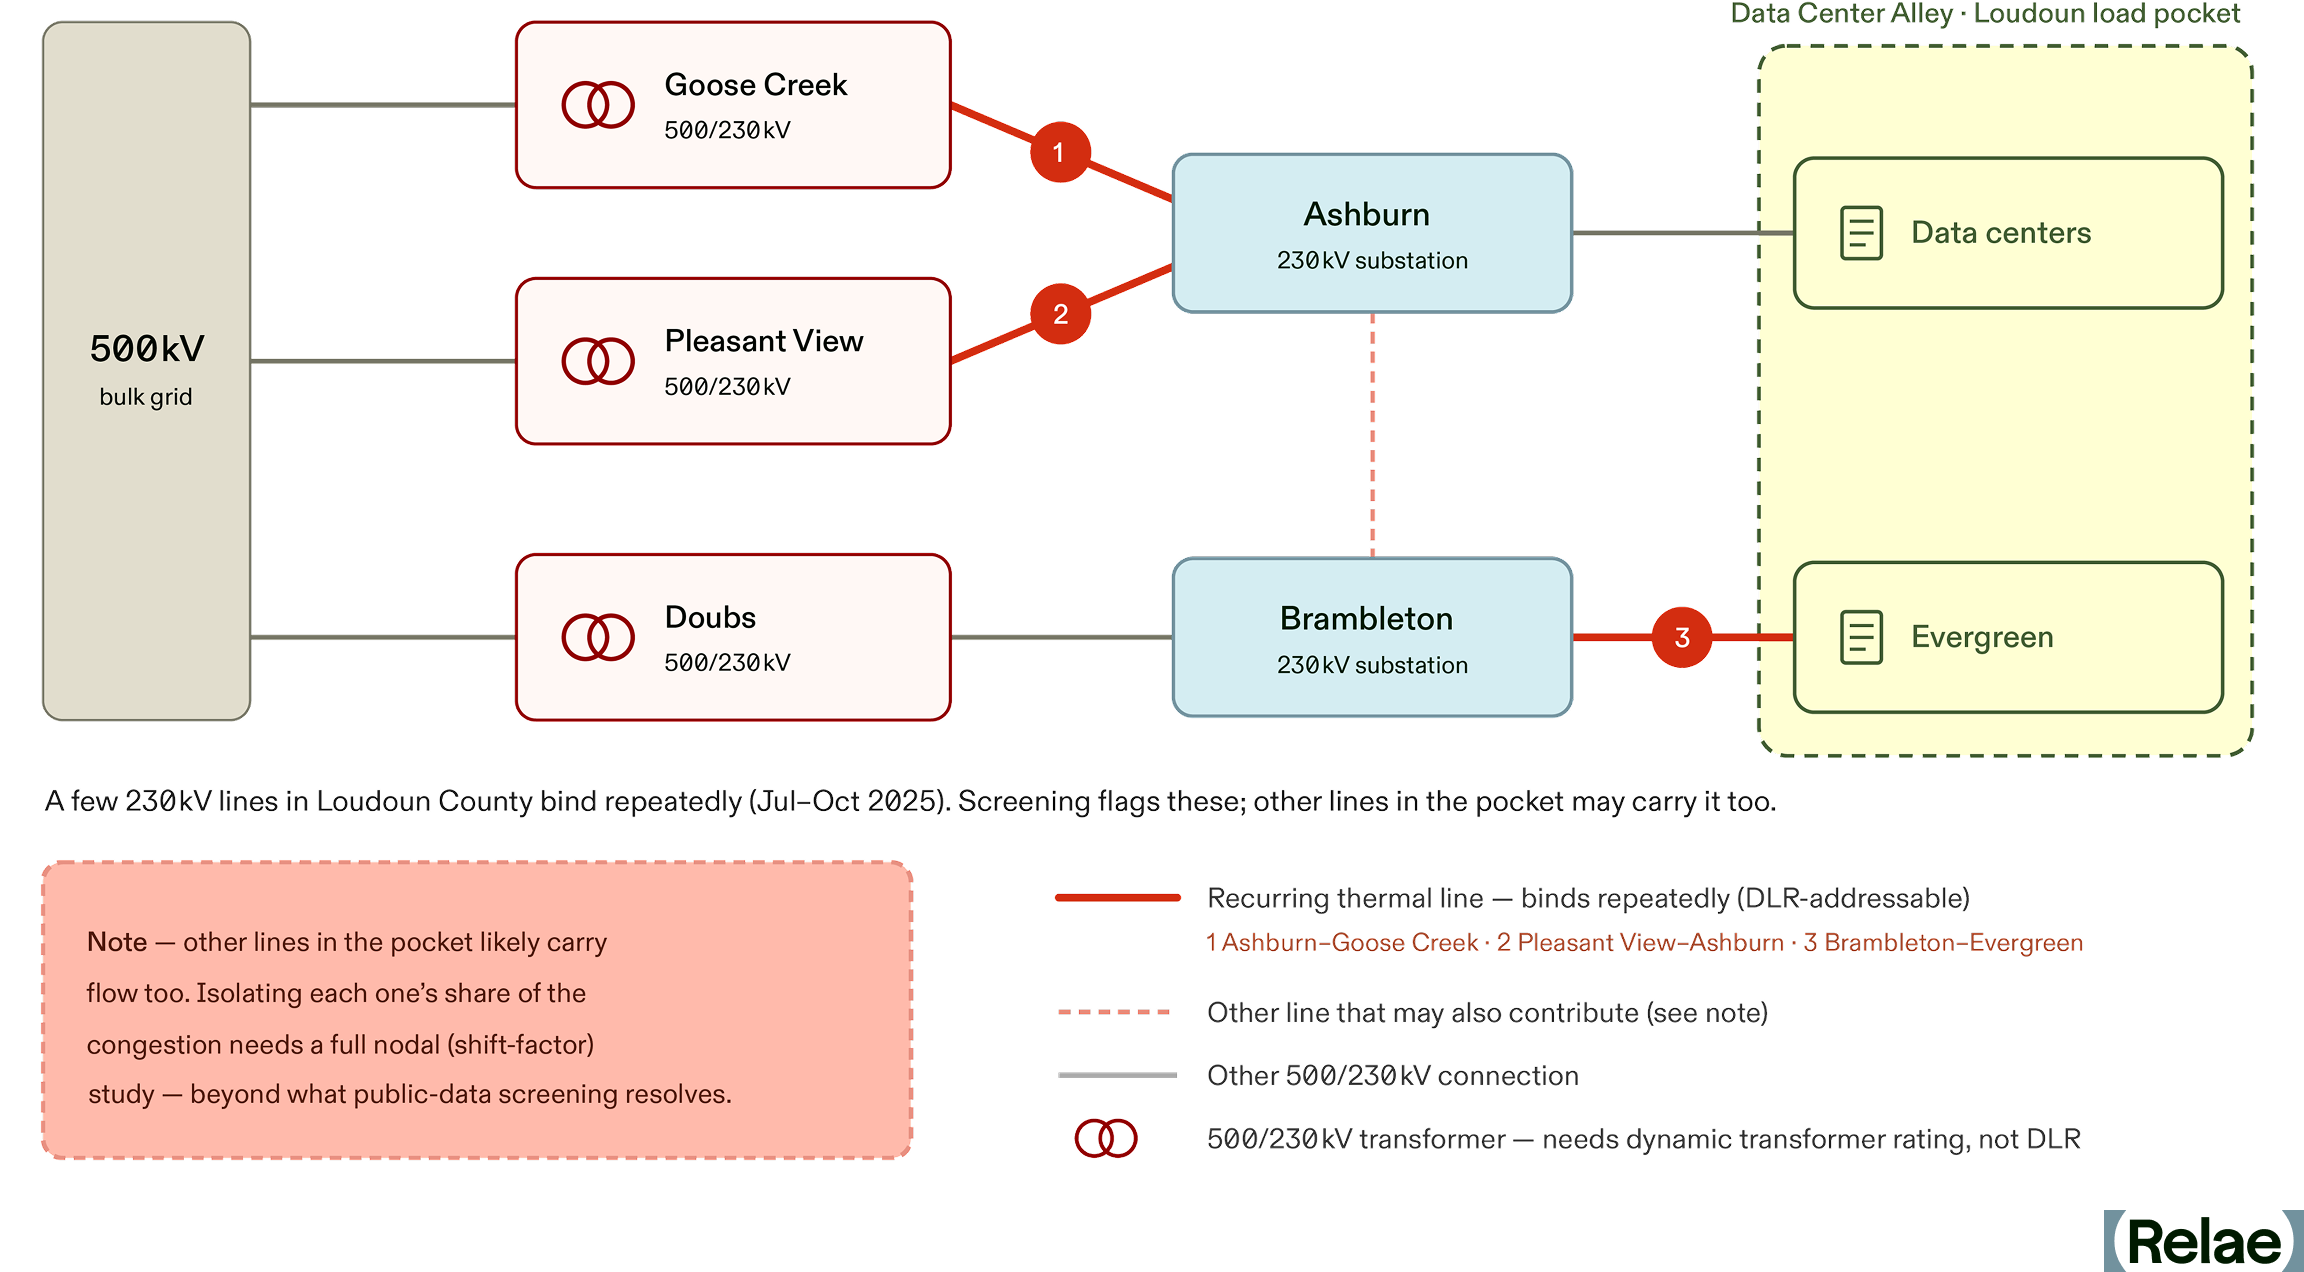
We ran the analysis on the Dominion (DOM) zone in PJM, home to Data Center Alley in Loudoun County, Virginia. Figure 2 shows a high-level section of the grid. The 500 kV bulk grid steps down through transformers to the 230 kV substations feeding the data centers, with the lines that experience recurring congestion highlighted. A handful of those 230 kV lines showed up as binding thermal constraints again and again.
The congestion in DOM isn't constant, and it concentrates in particular months and within the day in particular hours. Figure 3 shows three transmission lines within the DOM zone and the number of hours each was thermally congested in each hour-of-day slot over 2025. Binding concentrates in the warm months and, within the day, from late morning through early evening.
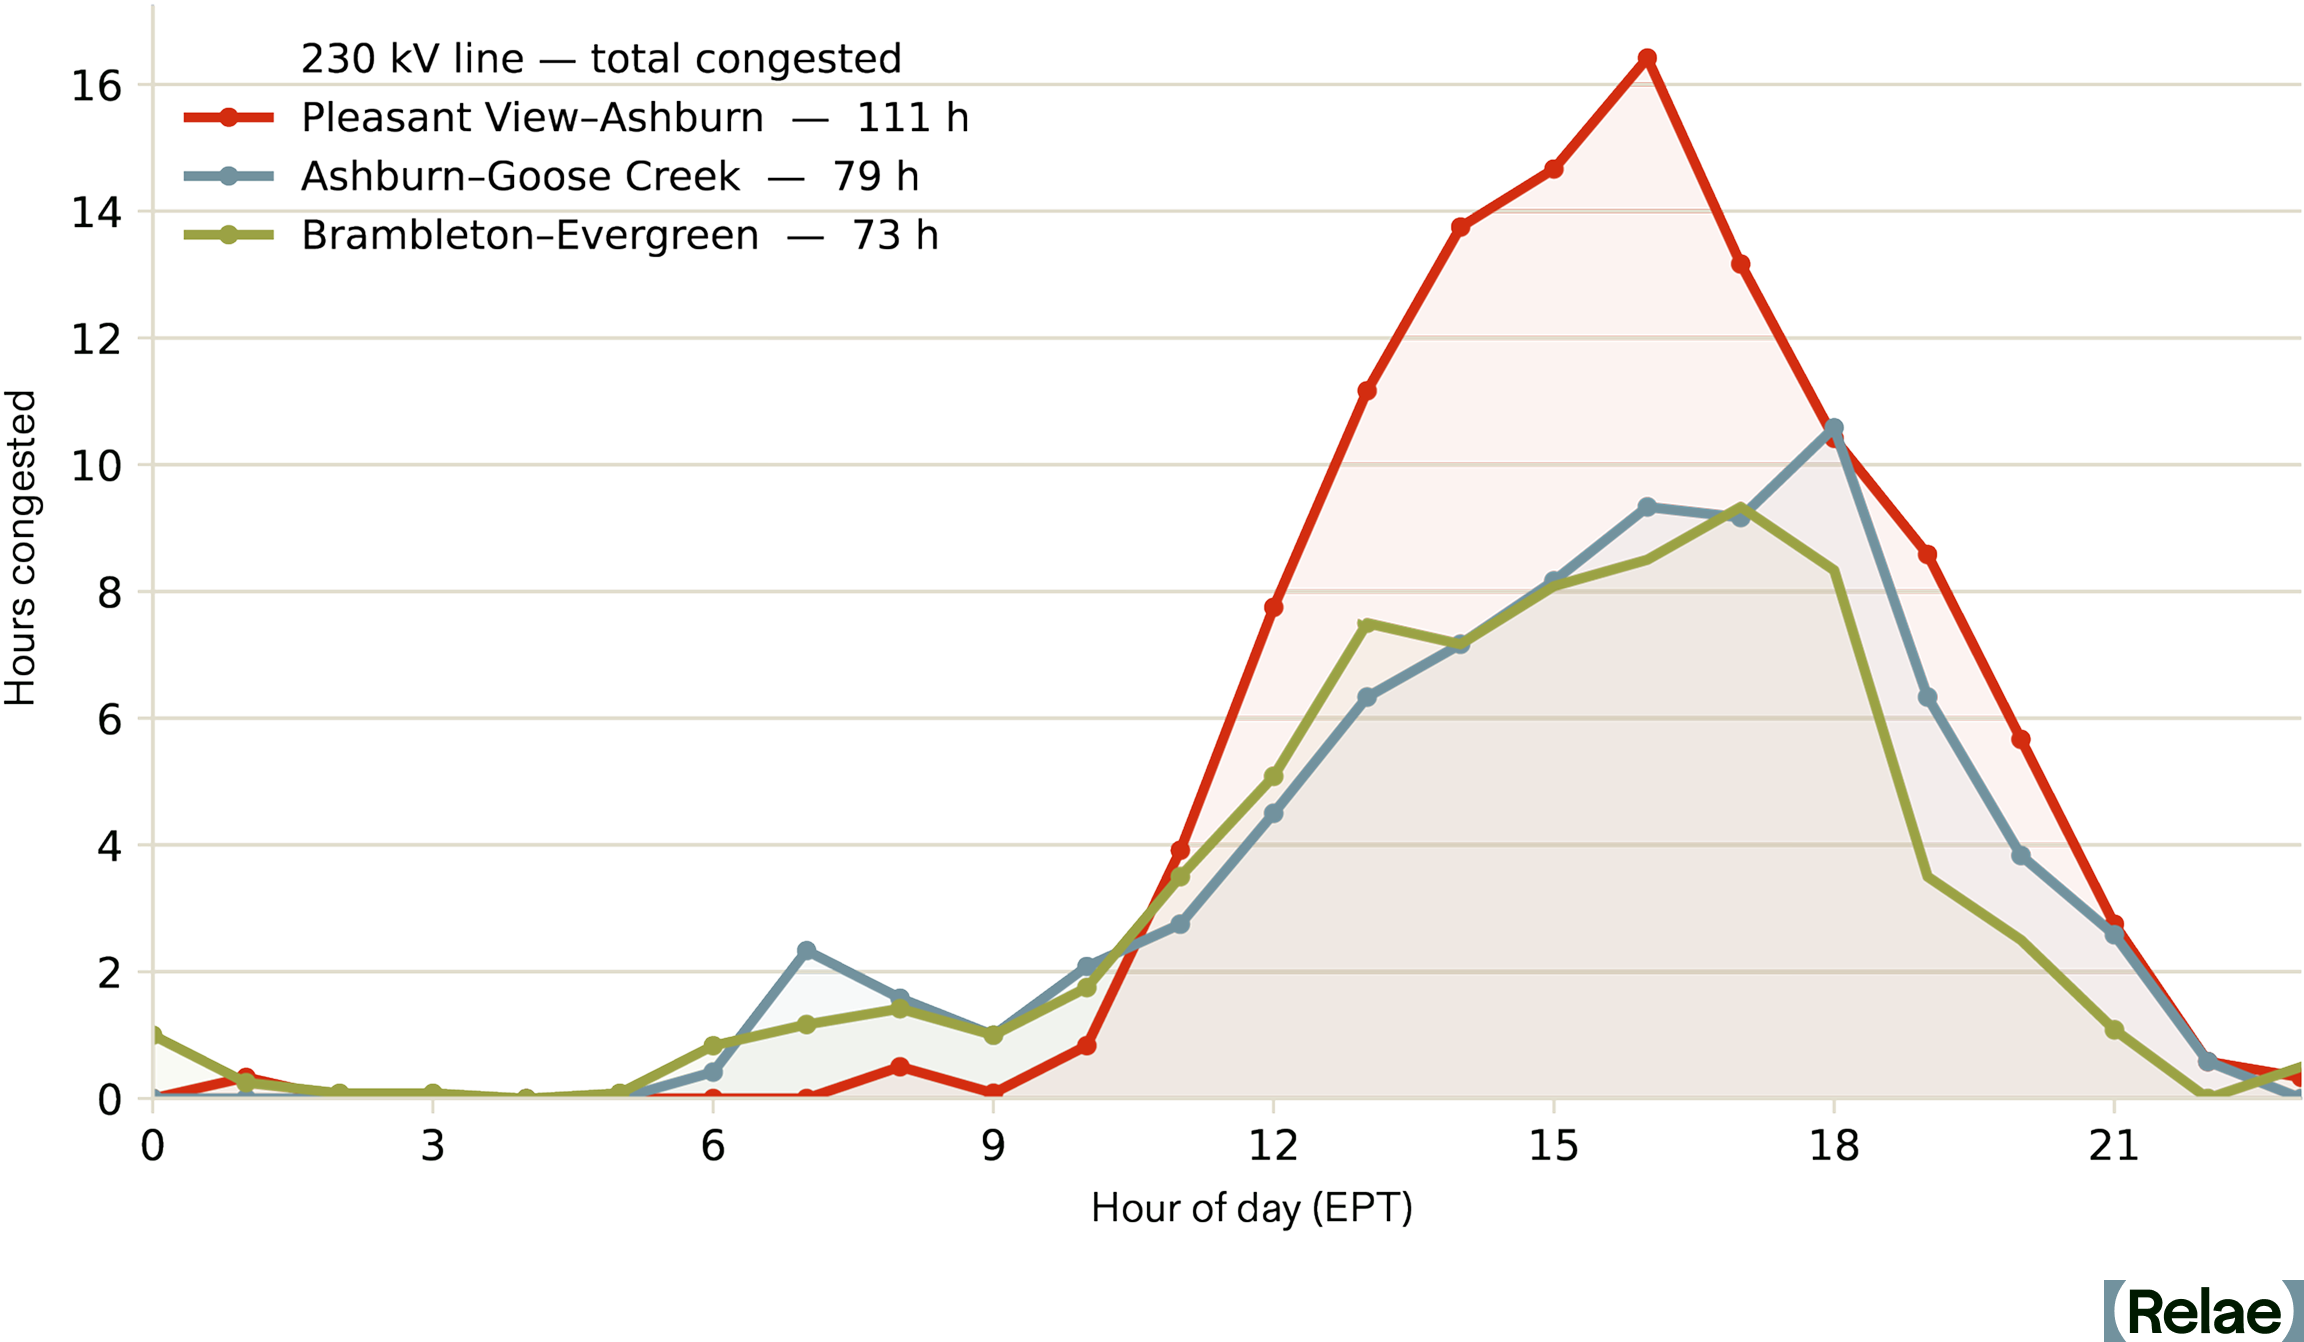
At first glance, this period looks like the wrong window for DLR. The local weather record says otherwise. These periods turn out to be some of the windiest hours of the day, not the stillest. Median wind speed at Dulles ran about 3.5 m/s, above the 0.6 m/s crossflow a static rating conventionally assumes, with fewer than 5% of observations falling below that threshold. Median ambient temperature in those hours was about 26°C, against the 35–40°C a static summer rating is typically built for. Across all three lines, the large majority of congested hours coincided with weather that would have supported a materially higher rating.
Valuing just one megawatt of DLR relief at each five-minute shadow price, the estimated savings are worth roughly $300,000 in this three-line example across about 263 line-hours.4
Because the value concentrates on a handful of thermally limited, heavily congested lines, and because the operational case has to be made line by line, capturing the opportunity is fundamentally an analytics problem: find the right lines, and prove the savings.

What Does It Take to Scale DLR?
DLR is cheap and effective, but two things stand between it and broader adoption: incentives and advanced grid analytics.
The utility cost-of-service model recovers investment in generation and transmission assets and earns its profit as a regulated return on the capital deployed. Because rates recover capital rather than power delivered, utilities have a stronger incentive to build or upgrade lines than to move more power across the ones they already own. That bias toward capital investment over optimization is why a mature technology has stayed niche in the US for years. Regulators have started to look more closely at this, but the main federal rule still mandates the milder AAR, not DLR, and leaves the return model untouched.
Contingency analysis compounds the problem. Current models are built around fixed line limits. A rating that changes hour to hour adds real modeling work, and more importantly, the system still has to hold under worst-case contingencies. So while operators already forecast weather daily for wind and solar, the harder step is trusting a forecast enough to commit a transmission limit against it. That takes significant predictive analytics built into system planning, not bolted on after.5
How Policy Is Starting to Shift the Calculus
Policy is starting to move the incentive problem. FERC's Order 881 made AAR the minimum for the transmission providers it regulates (effective July 2025, with several operators on extended timelines) and required markets to be capable of accepting dynamic ratings. PJM has started to implement this: PPL Electric has run sensor-based DLR on nine congested lines since 2022, feeding PJM's day-ahead markets.
Order 1920, FERC's first long-term transmission-planning overhaul in more than a decade, now requires planners to formally evaluate grid-enhancing technologies like DLR against conventional builds. It stops short of mandating deployment, but it forces a comparison utilities used to skip. That comparison is now written into filed tariff processes (PJM filed its plan in December 2025). Those first cycles only began in 2026, and the order allows up to three years to reach a selection, so the results are still pending.
A shared-savings incentive, letting a utility keep a slice of the congestion savings it creates, has been proposed to FERC and championed in the Advancing GETs Act, but it isn't yet a rule, so the core misalignment stands. DOE's GRIP program has funded grid-enhancing deployments, and by early 2026, 16 states had some form of advanced transmission technology requirement, with Colorado adding its Grid Optimization Act in April 2026.
The newest pressure is coming from the demand side. Through 2025–26, FERC began overhauling how large loads connect to the grid, and while none of it touches the utility's return on capital, it changes who sees the costs. FERC issued show-cause orders directing all six grid operators to justify or reform their large-load rules. This tees up consideration of alternative transmission technologies in study processes and greater transparency into costs.
And the rules are moving toward making the large load pay for the upgrades its connection requires. Pennsylvania's model large-load tariff, for example, recommends utilities charge data centers for the upgrades their interconnection makes necessary. It also instructs utilities to let those customers self-construct certain upgrades, including some affecting the wider grid. That combination is what matters. The party paying the bill now has a reason to ask whether a cheaper fix exists and, in at least one state, a route to build it. We have not yet seen a DLR deployment selected this way, because these frameworks are only months old, but the cost gap between a DLR fix and a rebuild is becoming visible to the party who pays the difference.
How Relae Helps Find the Value of DLR
Through our Power, Data, and Innovation practice, Relae combines transmission congestion data, line-level thermal constraints, and short-term weather forecasts into a single view of where dynamic ratings would actually pay. The output is a short list of candidate lines, each with a modeled capacity uplift and an estimated dollar value, turning a vague “DLR is promising” into a priced, line-by-line decision. It is the transmission-side complement to our work on the interconnection queue and demand-side flexibility. All three are ways of closing the gap between demand and delivered capacity faster than new construction allows.
For Low-Carbon Fuels, Sustainability Is the Product—and Quality Is the Value
Key Takeaways
- Buyers have been navigating the low-carbon fuels (LCF) market without a map. The LCF market is expanding rapidly, but standards, definitions, and quality claims vary widely across regions, certification schemes, and regulatory systems, leaving voluntary buyers without a holistic framework for evaluating what they procure.
- Certifications cover some of the picture, not all of it. Existing certification schemes provide valuable assurance but vary in scope and rigor, and few, if any, were designed specifically with voluntary market buyers in mind.
- The 2026 criteria give buyers a legible quality framework. The 2026 Criteria for High-Quality Low Carbon Fuels bring together key sustainability considerations across six principles, including social and environmental integrity, carbon accounting, additionality, feedstock sourcing, and leakage, giving buyers and producers a legible, living framework to navigate procurement decisions with confidence.
Verifying Quality Is Challenging in the Current Low-Carbon Fuels Market
For airlines, logistics companies, and large corporations with hard-to-abate transportation emissions, low-carbon fuels (LCFs) have become an important part of the decarbonization toolkit. Yet it remains difficult for procurement teams to answer a fundamental question: what does high-quality procurement actually look like?
Standards, definitions, and sustainability claims vary widely across regions, certification bodies, and regulatory programs. The result is a market where quality is difficult to verify, certifications are difficult to compare, and the gap between a fuel's claims and its actual sustainability profile can be hard to close. Sustainable production will be especially critical as the market scales, because low-carbon fuel systems are deeply embedded in land, agriculture, forestry, and communities.
The 2026 Criteria for High-Quality Low Carbon Fuels are designed to close this gap, giving voluntary buyers a consistent framework to evaluate the quality of what they procure and identify where additional diligence is still needed.
What Is a Low-Carbon Fuel?
For the purposes of the criteria, a low-carbon fuel, or LCF, is defined as a fuel or energy source whose lifecycle greenhouse gas (GHG) emissions are lower than those of a relevant, use-case-specific fossil fuel alternative. In this case, we are referring to the physical biofuel and its associated environmental attributes.
While LCFs may be produced through biological, synthetic, or other non-fossil pathways, the 2026 edition focuses on biofuels for transportation, which currently represent the majority of LCF production and use.
Understanding the Complex LCF Regulatory and Certification Landscape
The LCF market sits at the intersection of multiple regulatory and voluntary markets. In the US, this includes compliance programs such as the Renewable Fuel Standard (RFS) and state-level Low Carbon Fuel Standards (LCFS). Europe, the United Kingdom, Canada, and many other nations host comparable programs, often with specialized regulatory regimes for various transport sectors, e.g., aviation or maritime.
These regulatory markets coincide with and often intersect voluntary markets, which contain a multitude of standards and certifications. For producers, this creates a complex landscape of market options. For buyers, it creates a signal problem: a fuel may carry one or more certifications, comply with one or more regulatory programs, and still leave meaningful sustainability questions unaddressed.
Several organizations, including the Roundtable on Sustainable Biomaterials (RSB) and the International Sustainability and Carbon Certification (ISCC), have developed widely used standards for LCFs. These certifications assess supply chains from feedstock to end use and provide important baseline assurance.
However, they were developed with different primary audiences in mind and can vary in scope and rigor. Few existing schemes were designed to serve as a comprehensive sustainability reference for voluntary market buyers evaluating what a given fuel's certification covers and where gaps may still exist.
Simplifying High-Quality Procurement for Voluntary Buyers
The 2026 Criteria for High-Quality Low Carbon Fuels are not designed to replace or compete with existing certification schemes. Rather, they consolidate key sustainability considerations from across the landscape of existing frameworks into a single, legible reference built specifically for voluntary market decision-makers.
The criteria apply across the full LCF supply chain, covering not only fuel producers but also fuel blenders, aggregators, and certificate traders. This LCF systems view encompasses the full set of production, certification, and procurement arrangements through which LCFs are generated and claimed. This reflects the reality that sustainability outcomes in this market are shaped by many actors, not just at the point of production.
The criteria distinguish between requirements that must be met (minimum thresholds for quality and integrity) and considerations that should be addressed, reflecting best practices and aspirational standards. This distinction is intentional: the criteria set a floor while leaving room for market participants to demonstrate quality in ways appropriate to their specific context.
The criteria are organized around six core principles that together define what high-quality LCF production and procurement looks like.
Six Principles for Procuring High-Quality Low-Carbon Fuels
- Social harms, benefits, and environmental justice: preventing new harms to communities, reducing existing ones, and ensuring equitable distribution of benefits
- Environmental harms and benefits: minimizing impacts on air, soil, water, and biodiversity
- Carbon accounting: accurately quantifying lifecycle GHG emissions using credible methodologies and tracking environmental attributes to prevent double-counting
- Additionality: demonstrating that voluntary market support enables outcomes that would not otherwise occur
- Feedstock sourcing: ensuring responsible and equitable sourcing practices and requiring end-to-end chain-of-custody documentation traceable to the point of generation
- Leakage: assessing and mitigating activity-shifting and market leakage associated with the LCF system
Where a fuel's existing certification or regulatory program adherence already addresses one or more of these core principles, that coverage should be disclosed to the buyer by the producer. Buyers can then use the criteria to identify where certification coverage aligns with quality expectations, and where supplemental diligence is needed.
A Living Framework for a Market in Motion
The LCF market will continue to evolve as policy frameworks are shifting, certification systems are maturing, and new production pathways are emerging. The 2026 edition reflects the current state of the LCF market and is intended as a living resource, with future updates possible as the market develops and new science emerges. Future editions may expand to cover synthetic LCF pathways, renewable natural gas, and sector-specific considerations such as maritime fuels.
For buyers navigating voluntary LCF procurement, the criteria offer a practical starting point: a framework to evaluate what existing certifications cover, identify where additional diligence is needed, and build procurement decisions on a consistent quality foundation. For producers, they provide clear guidance on what a sustainability demonstration looks like for voluntary market buyers.
Frequently Asked Questions
What is a low-carbon fuel?
A low-carbon fuel is a fuel whose lifecycle greenhouse gas emissions are lower than a comparable fossil fuel alternative for the same use case. The 2026 LCF Criteria focus specifically on biofuels for transportation, which currently make up most LCF production and use.
What do the 2026 Criteria for High-Quality Low Carbon Fuels cover?
The criteria are organized around six principles: social harms, benefits, and environmental justice; environmental harms and benefits; carbon accounting; additionality; feedstock sourcing; and leakage. Together they give buyers and producers a consistent way to evaluate what high-quality LCF production and procurement looks like.
Do the LCF criteria replace existing certifications like RSB or ISCC?
No. The criteria aren't designed to replace or compete with existing certification schemes such as the Roundtable on Sustainable Biomaterials (RSB) or the International Sustainability and Carbon Certification (ISCC). Instead, they consolidate key sustainability considerations from across those frameworks into a single reference so buyers can see what their certification already covers and where supplemental diligence may be needed.
Who do the LCF criteria apply to across the supply chain?
The criteria apply across the full LCF supply chain, not just producers, but also feedstock suppliers, fuel blenders, aggregators, and certificate traders, reflecting that sustainability outcomes are shaped by many actors, not only the producer.
What's the difference between the "must" and "should" requirements in the LCF criteria?
"Must" requirements set minimum thresholds for quality and integrity that need to be met, while "should" considerations reflect best practices and aspirational standards market participants can work toward. This sets a floor while leaving room for participants to demonstrate quality in ways suited to their specific context.
US Wood Pellet Producers: The UK Market Is Contracting. Four Markets Are Beginning.
Key Takeaways
- The UK's new biomass Contracts for Difference framework will cut industrial wood pellet imports by slightly more than half starting in April 2027. As a result, US producers will be left competing for only 1.6 million GST, an 80% reduction in US-addressable volume, with no successor market locked in.
- US wood pellet producers who move now to upgrade sustainability credentials and build relationships in emerging markets will be best positioned to capture the next generation of demand; those who wait may find the most attractive offtake opportunities already structured around someone else's supply.
- Four domestic markets now present producers with new demand opportunities: cofiring, sustainable aviation fuel (SAF), low-carbon steel, and bioenergy with carbon capture and storage (BECCS). Of these, BECCS for data centers is the strongest structural fit: hyperscalers need clean firm power, pellet mills need offtakers, and the feedstock infrastructure is already in place.
The Demand Cliff Is Real, and the Timeline Is Short
A pellet made in southern Mississippi this morning will be burned in a UK boiler about four weeks later. North America is on pace to ship more than 9 million green short tons (GST) of pellets to the UK each year—making the UK the world's largest consumer of wood pellets since 2018. The US Southeast is at the center of that supply chain: 28 large mills, 13.5 million GST of production capacity, rail spurs, export terminals, and bulk carriers, built almost entirely around UK demand.
However, the UK's new low-carbon Contracts for Difference (CfD) framework caps biomass power generators at a 27% annual capacity factor starting April 2027, down from roughly 64% today. When run hours fall by half, pellet demand follows. Existing subsidies expire in the first quarter of 2027, and the new CfD runs only to March 2031 with no commitment beyond that. Plant closures in Arkansas and Washington state, along with reduced output in Canada, are already early signals of supply chain contraction.
The Math of Who Gets Squeezed
The math is stark. By the second quarter of 2027, total annual UK pellet demand drops to 4.9 million GST. Of that:
- Approximately 2.3 million GST goes to captive, integrated UK supply chains.
- Approximately 1.0 million GST goes to Baltic suppliers, whose shipping times of one week or less become a decisive advantage as UK plants shift from baseload to dispatchable operation.
That leaves US producers competing for only 1.6 million GST. If Baltic suppliers capture more, US wood pellet exports to the UK could be effectively eliminated by 2031.
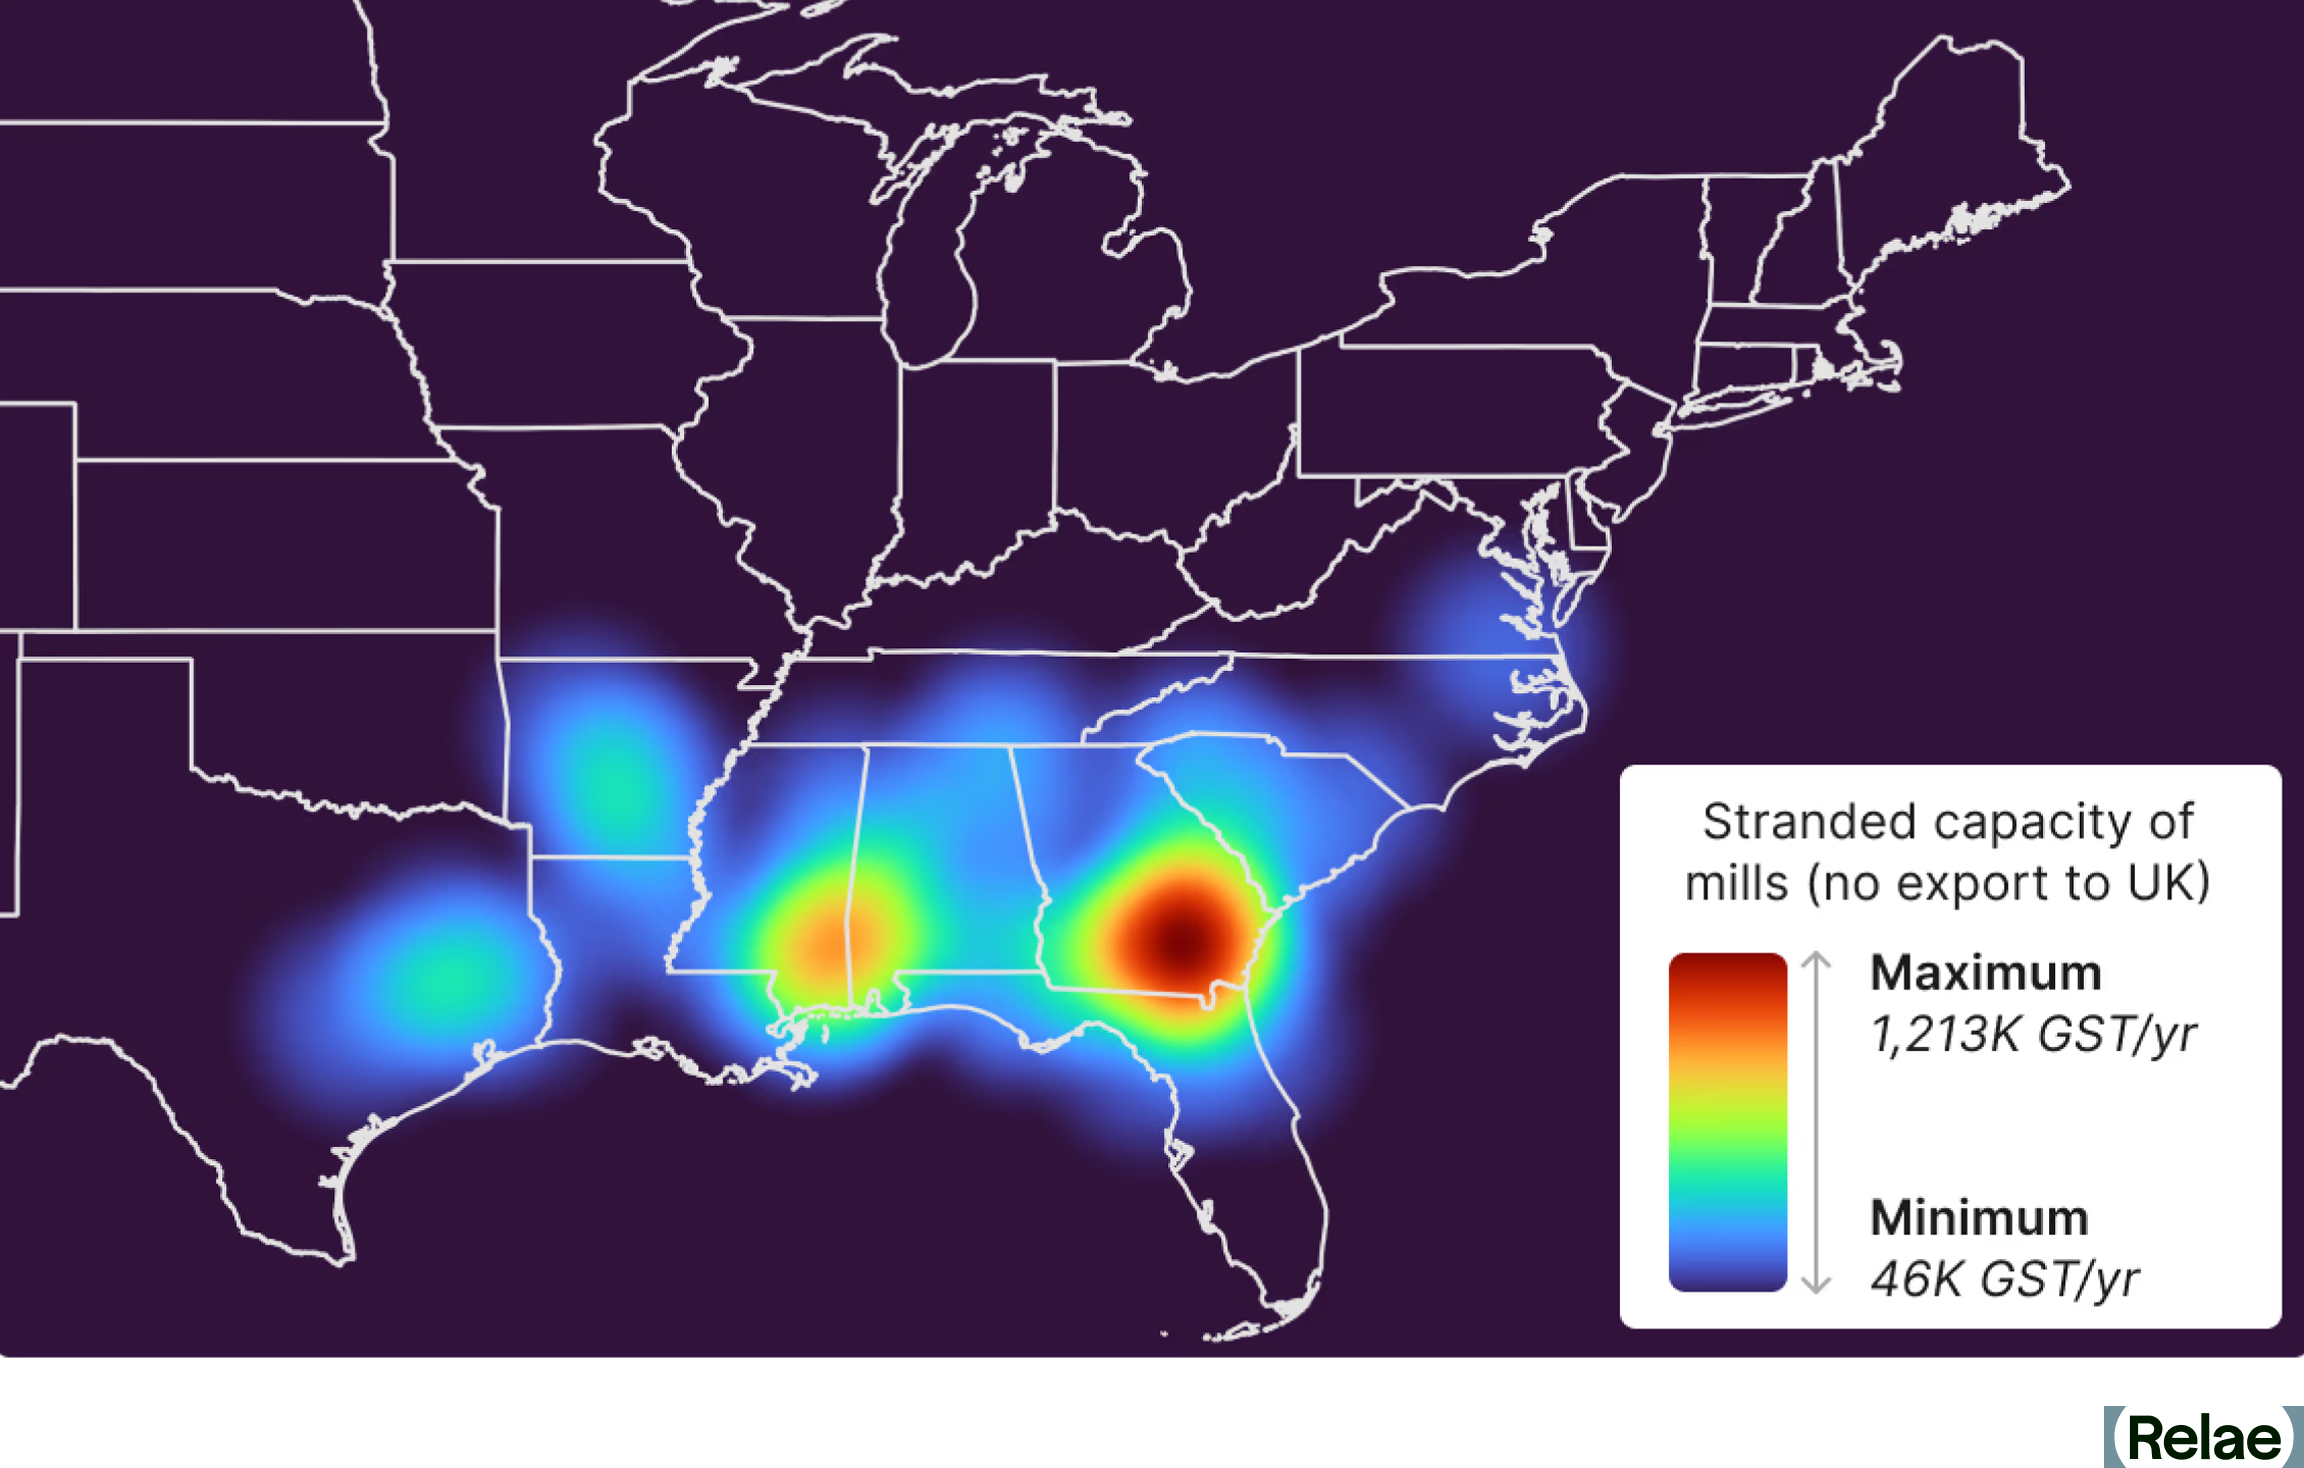
Sustainability qualification is also tightening. The new CfD cuts the supply-chain emissions ceiling from 55.6 grams of carbon dioxide equivalent per megajoule (gCO₂e/MJ) to 36.6 gCO₂e/MJ. The framework assesses compliance mill by mill, not on a portfolio average. A cleaner mill cannot carry a dirtier sibling through the door.
The producers who understand this math now have roughly 18 months to position themselves for what comes next.
From Stranded Supply to New Markets
The US Southeast's wood basket is robust: abundant inventory, strong growth-to-removal ratios, and more available residues than ever. The infrastructure is in place. The question is whether the next generation of markets can be developed quickly enough to redeploy this supply before the infrastructure sits idle.
Four pathways stand out as the strongest options for redeploying US pellet supply: BECCS for data centers, low-carbon steel, SAF, and domestic cofiring. We have rigorously assessed the logistics economics, sustainability cases, and project development for each.
BECCS for Data Centers: The Strongest Structural Fit
BECCS as a power source for data centers is the most compelling match for the situation pellet producers now face. The timing, feedstock requirements, and buyer characteristics align closely in a way that few other emerging markets can match.
Hyperscalers, the large data center operators driving an unprecedented surge in electricity demand, are signing deals for nuclear, geothermal, and small modular reactors alongside natural gas and renewables. They are doing this because annual Renewable Energy Certificates (RECs) are no longer sufficient to compensate for their scope 2 emissions, and they need clean, firm generation that can be matched to load on an hourly basis.
BECCS delivers exactly that. The Louisiana Green Fuels project—advanced by Strategic Biofuels and Relae (formerly Carbon Direct)—illustrates the model: regionally sourced forestry residues and sawmill waste generate 75 megawatts (MW) of firm electricity while sequestering over one million tonnes of CO₂ annually in deep saline formations. An ample supply of wood pellets creates a strategic opportunity for similar projects to move forward with certainty around feedstock processing, logistics, and costs.
The remaining commercial barrier is deal structure, not technology. No data center operator has yet signed an agreement to purchase both the electricity and carbon removal credits from a single BECCS plant. As scope 2 accounting tightens and domestic pellet supply becomes more readily available post-2027, the conditions for structuring the first such deal are improving fast.
"Pellet mills and data center developers have complementary problems: mills need offtakers, and data centers need local, dispatchable, clean power they can match to load on an hour-by-hour basis. BECCS is one of the few technologies that could solve both at once, and hyperscalers have shown they are willing to back early-stage clean firm power when the asset makes sense."
—Douglas Bryan, Senior Power and Energy Systems Modeler
Low-Carbon Steel: Certification Frameworks Are Arriving
Wood-derived biocarbon has a long-established niche in steelmaking. Brazil produces roughly 10% of its steel and 30% of its pig iron using charcoal from managed eucalyptus plantations—a proof of concept for biomass as a metallurgical input, if not a direct template for US producers. The plantations measurably lowered groundwater in producer regions of Minas Gerais, and charcoal's mechanical weakness relative to fossil coke has limited the model's reach beyond Brazil.
Current pilot projects use biomass in two roles. As a fuel, industrial trials have demonstrated 10% bio-coal co-injection without operational disruption, with reviews estimating that full replacement could cut blast-furnace CO₂ by around 27% per tonne of hot metal. As a reductant, biocoke is already being demonstrated at Outokumpu's pelletizing plant in Tornio, Finland. ArcelorMittal in Belgium and Tata Steel in India are running biomass pilots at tens of thousands of tonnes per year.
What makes this market worth serious attention now is the certification landscape. The Low Emission Steel Standard issued its first certifications in September 2025. The Global Steel Climate Council's Steel Climate Standard is under stakeholder review. In May 2025, Relae and Microsoft published Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors. These frameworks allow producers to internalize carbon price and environmental attribute certificate (EAC) values, closing the cost gap against fossil coke that has historically constrained biocarbon demand.
Relae worked with Eramet, a global metals company pursuing biogenic materials as a substitute for fossil coke at its Norwegian smelters, to assess high-quality carbon dioxide removal methodologies and chart a path to generating and selling carbon credits from their decarbonization projects. Producers who align their sustainability credentials to these emerging standards now will be better positioned for offtake as commercial-scale demand grows.
"Steelmaker pilots and the first low-carbon steel certifications are opening green-steel offtake to wood pellets, though commercial-scale demand remains limited. The producers that thrive in this market will be those that reliably deliver pellets aligned with high-quality sustainability standards."
—Louisa Brotherson, Hybrid Decarbonization Scientist
Sustainable Aviation Fuel: Mandates Create a Durable Demand Signal
Wood-based SAF is technically feasible via gasification to syngas, followed by Fischer-Tropsch upgrading, a proven chemistry for converting syngas to liquid hydrocarbons. Yet, the commercial challenges are substantial: the International Civil Aviation Organization estimates capital costs exceeding US$1 billion for large facilities, and production costs of US$11–48 per gallon to distillate.
The cautionary case is Fulcrum Bioenergy near Reno, Nevada, which attempted a Fischer-Tropsch process using municipal solid waste and appears to have failed due to a lack of rigorous pre-implementation testing and unrealistic timelines, a reminder that feedstock homogeneity matters enormously, and one area where pellets have a relative advantage.
Two structural dynamics make SAF worth serious attention despite those barriers. First, the European Union's (EU) SAF mandate, starting at 2% of jet fuel supply and ramping to 70% by 2050, carves out cellulosic biomass as the only qualifying feedstock once cooking oil supply is exhausted. The penalty structure in both the EU and UK creates strong demand regardless of SAF price: EU non-compliance penalties run roughly three times the price of SAF, and UK penalties can reach 13 times the cost of the fuel itself. Second, the alcohol-to-jet pathway offers a lower-capital entry point than Fischer-Tropsch, as demonstrated by Project Speedbird, a British Airways and LanzaJet collaboration targeting UK woody residues.
The near-term question is which routes have bankable offtake. Very few do yet, but the mandate structure suggests that window will shift rapidly.
"So far, facilities haven't scaled to the levels required to meet timeline demand. But the EU and UK mandate structures mean buyers are greatly incentivized to purchase SAF even at high prices, rather than pay non-compliance penalties."
—John Dees, Director, Fuels and Industrial Commodities
Domestic Cofiring: Achievable, but Not a Long-Term Anchor
Cofiring biomass with coal to produce electricity or heat is the most immediately achievable option. Most US coal-fired power plants could displace up to 10% of their input energy with raw or torrefied pellets, though plants would likely need fuel handling upgrades. Some state policies, such as Pennsylvania's Alternative Energy Portfolio Standards Act of 2004, support cofiring to meet renewable energy goals. However, there are no federal policies in the US that incentivize cofiring.
The case for cofiring as a long-term market is weak. The US coal fleet has contracted steadily for economic reasons—over 100 gigawatts (GW) of coal-fired capacity retired between 2015 and 2025—and biomass cofiring is unlikely to make a coal plant more cost-competitive. The Greenhouse Gas Protocol's scope 2 guidance does not permit buyers to procure a "strip" of electricity representing the biomass-fired fraction of output from a cofired plant; instead, buyers must accept the average total emissions from the plant in their scope 2 inventory, which limits the value proposition for corporate buyers seeking to demonstrate clean energy procurement.
The more interesting version of this pathway combines cofiring with carbon capture and storage (CCS), a combination that creates a deeper-abatement value proposition and the kind of firm, dispatchable power that corporate buyers increasingly need.
"Cofiring is a proven step toward modest emissions reductions from coal-fired electricity, but it's hard to make the economic case for it when compared to applications that command price premiums for deeper climate abatement."
—A.J. Simon, Director of Industrial Decarbonization
Sustainability Is Now the Qualification Gate
Each of these markets is more discerning about sustainable biomass sourcing than the UK power sector was a decade ago. That shift will not reverse.
US Southeast wood has real potential for high-integrity sustainability credentials, particularly in softwood residues. But it also carries downside risks when sourcing from natural stands. Through work with producers, buyers, and project developers across these markets, we have found that four questions now drive every serious procurement conversation:
- Does the supply chain have verifiable governance and chain-of-custody transparency?
- Does sourcing respect the rights of Indigenous Peoples and local communities?
- Is the wood coming from regions where forest carbon stocks are stable or growing, and not from protected areas or primary forest?
- Is sourced biomass a by-product of non-energy uses, and not the primary silviculture driver?
Producers who can answer yes to all four, and support those answers with data, are more likely to access these emerging markets. Those who cannot will find it harder to compete for offtake.
For a detailed framework on how these principles translate into contract language and certification requirements, see the 2025 Sustainable Forest Biomass Sourcing for CDR: A Buyer's Guide.
The Window Is Open, but Not Indefinitely
The US Southeast wood basket is well-positioned for the markets described here. The infrastructure is in place. What producers still need to build is the market positioning, sustainability documentation, and offtake relationships to go with it.
The producers who move now will have a meaningful head start. Those who wait for certainty may find that the most attractive offtake opportunities have already been structured around someone else's supply.
Learn more about Relae's work on SAF mandates, steel decarbonization, and sustainable biomass sourcing.
Frequently Asked Questions
What happens to US wood pellet exports when the UK's new biomass rules take effect?
Starting April 2027, the UK's signed Contracts for Difference agreement caps subsidized biomass generation at a 27% capacity factor, roughly half of today's levels. That's expected to cut total UK pellet demand to about 4.9 million GST a year, leaving only around 1.6 million GST available to US exporters.
Is BECCS for data centers a proven market, or still emerging?
The underlying technology is credible, and the Louisiana Green Fuels project already demonstrates it at commercial scale. However, the deal structure isn't yet proven. No hyperscaler has signed a single contract for both electricity and carbon removal credits from one BECCS plant, so this market is emerging rather than established.
How does low-carbon steel demand compare to sustainable aviation fuel as a market for pellet producers?
Steel offers nearer-term certification frameworks (the Low Emission Steel Standard began issuing certifications in 2025) but limited commercial-scale volume so far. SAF has a stronger long-run demand signal thanks to EU and UK blending mandates and steep non-compliance penalties, but requires far higher capital investment to enter.
What should a wood pellet producer look for when evaluating a new market?
The four sourcing questions that now gate access across all these markets are: verifiable chain-of-custody, respect for Indigenous and local community rights, sourcing from stable or growing forest carbon stocks (not primary forest), and biomass that's a by-product of non-energy uses rather than the primary driver of harvest.
The Sustainable Aviation Fuel Cost Premium Is Permanent
Key Takeaways
- Sustainable aviation fuel (SAF) will not reach price parity with fossil jet fuel under any realistic near-term scenario. The cost premium is structural—rooted in the chemistry of feedstocks—not a temporary artifact of early-stage markets.
- Neither airlines nor corporate buyers are purchasing SAF for its energy content. Both are buying sustainability claims: airlines for regulatory compliance and scope 1 credentials, corporates for scope 3 emissions reporting and social license to operate. The fuel is incidental to both transactions.
- Corporate offtakes can play a genuine role in building the SAF industry, but only if they create capacity that would not otherwise exist. Additionality is not a technicality; it is the entire value proposition.
- High-integrity SAF procurement requires evaluating not just carbon reduction, but feedstock sourcing, leakage, and social and environmental harms. The newly released Criteria for High-Quality Low Carbon Fuels from Relae (formerly Carbon Direct) provides a framework for doing this rigorously.
A Major Deal Illustrates How the SAF Market Really Works
On June 5, 2026, Google and American Airlines announced a three-year agreement under which Google will purchase sustainable aviation fuel (SAF) certificates (SAFc) associated with 35 million gallons of SAF. American will take physical delivery of the fuel at Chicago O'Hare. Google receives the emissions attributes. The arrangement relies on book-and-claim accounting, in which the physical fuel and the environmental attribute are legally separated and transferred to different parties.
The deal is a window into how the SAF market works, and what every company in the value chain needs to understand before entering it.
The SAF Cost Premium Is Structural, Not a Market Inefficiency
There is a persistent hope in the aviation industry that SAF will eventually reach price parity with fossil jet fuel. This will not happen, at least not through any mechanism that currently exists or is credibly in development.
The economics are the product of thermodynamics. Petroleum is pre-deoxygenated; over millions of years, heat and pressure stripped oxygen from biological material, concentrating energy into the hydrocarbons we pump out of the ground today. Bio-based SAF feedstocks, e.g., vegetable oils, agricultural residues, and other biomass, are oxygen-rich (carbohydrates, not hydrocarbons). Power-to-liquid e-fuels start from captured CO₂, which is fully oxidized.
Either way, every SAF production pathway must pay an energy debt to remove or chemically reduce that oxygen, in the form of hydrogen deoxygenation, energy inputs, and processing costs. This is not a manufacturing inefficiency that scale will solve. It is a constraint baked into the feedstocks themselves.
The numbers reflect this. According to the European Union Aviation Safety Agency (EASA), the average market price of SAF in 2025 was approximately €1,925 per tonne, roughly three times the €640 per tonne average for conventional jet fuel.
The cheapest pathway, hydroprocessed esters and fatty acids (HEFA), produced from waste oils like used cooking oil or tallow, represents almost all current SAF supply and sits at the lower end of the SAF cost range. Costlier cellulosic and e-fuel pathways push it higher. EASA estimates 2025 production costs for power-to-liquid e-fuels at €7,520 per tonne, more than ten times the cost of conventional kerosene. While these costs can and will come down, none are expected to approach price parity.
The feedstock ceiling compounds this. HEFA from waste oils is the cheapest SAF pathway, but waste oil supply is finite and competes with renewable diesel, which typically offers better margins for producers. As mandates push SAF volumes beyond what HEFA can supply, the industry must move to cellulosic biomass or power-to-liquid pathways, at progressively higher cost. Scaling the SAF industry does not automatically bring prices down. In the near term, it pushes them up.
Policy Determines Who Absorbs the Cost
If price parity is not coming, the cost premium lands somewhere. Two policy philosophies have emerged to answer that question.
Europe has largely adopted the polluter-pays principle: SAF mandates place the cost burden on fuel suppliers and, by extension, on airlines and their passengers. The EU's ReFuelEU Aviation regulation and the UK's SAF mandate both carry steep penalties for non-compliance. As Relae has documented, in the UK, those penalties range from three to 13 times the cost of compliance, depending on the obligation type and year, signaling that regulators are serious about pushing aviation toward sustainable fuels.
The United States approached the problem differently, leaning on taxpayer subsidies.The Inflation Reduction Act (IRA) 45Z Clean Fuel Production Credit and its predecessor, the 40B Sustainable Aviation Fuel Credit sought to socialize much of the cost premium. The appeal of this approach was that it made SAF economics viable without raising ticket prices. Its vulnerability was political: when the IRA's incentive landscape was revised, the project pipelines that had formed around those credits evaporated quickly. US taxpayer-funded support proved politically less durable than the UK and EU’s mandated compliance obligations.
Neither model works in isolation. Mandates without bankable project finance generate demand signals but no new supply. Incentives without policy durability attract project interest but cannot get facilities to final investment decisions. The deals that have actually moved capital combine a stable policy floor, whether mandate or incentive, with long-term private commitments that provide the revenue certainty project finance requires.
The Google-American Airlines deal illustrates the incentives-plus-private-commitment structure. The deal explicitly credits the Illinois SAF tax credit as the enabling policy lever. HEFA SAF of this type is eligible to generate Renewable Fuel Standard credits (RINs), and fuel produced from 2025 onward qualifies for the IRA's 45Z Clean Fuel Production Credit. This stack provides additional floor economics. The corporate offtake completes the structure by delivering the revenue certainty that volatile policy credits alone cannot. Remove any one of those elements and the deal's economics likely do not hold.
Nobody in this Market Is Buying SAF for its Energy Content
This is the key to understanding how the SAF market works. Neither airlines nor corporate buyers purchase SAF for its energy content. Airports have kerosene. Airlines do not need SAF to keep planes in the air. Corporate buyers, like Google, have minimal operational use for aviation fuel at all. While recent global disruptions in crude oil supply have highlighted SAF in the context of energy security, the industry as it exists today does not represent a realistic hedge against conventional fuel volatility.
What all parties are buying is the sustainability attribute attached to the fuel. For airlines, the relevant claim is a scope 1 emissions reduction: the right to report lower lifecycle carbon intensity for their flight operations. For corporate buyers, the relevant claim is a scope 3 reduction, a documented abatement of the emissions associated with their employees' business travel. Book-and-claim accounting makes this architecture explicit: it legally severs the physical fuel from the environmental attribute, allowing each to be transferred to the party that values it. The fuel is the delivery mechanism for the claim.
This distinction matters for assessing the market. Airlines operate on among the lowest margins of any major industry. They cannot absorb the cost premium voluntarily without fundamentally compromising their finances. They participate in SAF markets when required to by mandate, or when a corporate partner subsidizes the premium by purchasing certificates downstream. The cost premium does not disappear; it shifts. Understanding where it lands is the starting point for any serious procurement decision.
Corporate climate programs have finite budgets. SAF competes with renewable electricity procurement, fleet electrification, CO2 removal, and supply chain decarbonization for the same dollars. Buyers who want their sustainability claims to match the actual sources of their emissions (rather than offsetting aviation with unrelated activities elsewhere) have a genuine reason to prefer SAF.
A SAF Claim Is Only as Strong as the Quality Behind it
SAF buyers and sellers trade sustainability claims. The quality of those claims is the entire value proposition, and the reputational liability travels with them. The companies with the greatest willingness to pay for SAF certificates tend to be those with the most brand exposure: high-profile technology companies, professional services firms, and financial institutions. These are also the companies most likely to face scrutiny from regulators, NGOs, and investors if a claim does not hold up. Buying a certificate does not protect a company from that scrutiny. It transfers the liability along with the attribute.
That means a rigorous buyer needs to answer at least three distinct questions before relying on a SAF claim.
- Does this fuel actually reduce lifecycle emissions?
SAF's climate case rests on a carbon cycle argument: the feedstock absorbs CO₂ from the atmosphere as it grows, so when that carbon is released during combustion, the net addition to the atmosphere is theoretically near zero. But that logic holds only if upstream production is clean, and it often is not.
Indirect land use change (when demand for a feedstock crop displaces food agriculture elsewhere, triggering clearing of forests or grasslands) can generate substantial emissions elsewhere in the global land and food system, eroding or eliminating the lifecycle benefit. Even waste-based feedstocks are not automatically clean: used cooking oil and tallow have existing market uses, and diverting them without careful accounting can displace those uses, alter commodity markets, and create emissions leakage elsewhere.
- Is the purchase additional?
Additionality asks whether the procurement caused SAF to exist that otherwise would not have. This is a harder question than it appears, especially in markets where multiple policy support mechanisms are already active. For the Google-American Airlines deal, one critical variable for financial additionality—the SAFc price—has not been disclosed. If Illinois credits and federal RINs already cover most of the HEFA cost premium, then the question of what Google's purchase actually caused to happen is genuinely open. However, American Airlines has stated publicly that the long-term nature of the agreement enabled them to secure a new SAF offtake with Valero Marketing and Supply Company. The supply arrangement that may not have been bankable on the basis of volatile RIN markets and changeable policy alone. That is a real additionality argument. But it requires transparency to evaluate. The undisclosed SAF credit price is a current market liability, not just in this deal, but across the voluntary SAF market broadly.
Long-term offtakes do something that policy credits cannot: they provide stable, bankable revenue certainty. RIN prices fluctuate. Tax credits change with administrations. Neither can reliably anchor a final investment decision at the project level. A multi-year, creditworthy offtake agreement can. This is the distinctive and genuinely valuable role that corporate buyers play in this market: not paying the cost premium per gallon, but reducing the financial risk premium that keeps capital on the sidelines.
- Is the full supply chain sound?
Carbon claims are not the only dimension of sustainability that matters to a buyer's reputation. Companies making claims about their SAF procurement are implicitly making claims about their supply chains. That means labor practices, community impacts, Indigenous rights, feedstock sourcing integrity, and market leakage from displaced uses all fall within the scope of what a rigorous buyer should evaluate. A SAF supply chain that displaces food crops, harms a proximate community, or causes deforestation through indirect land use change creates a reputational problem that no certificate can fix.
What High-Integrity SAF Procurement Looks Like
The voluntary SAF market is still early, and the transparency it requires does not yet exist consistently. Relae recently released the Criteria for High-Quality Low Carbon Fuels, a comprehensive, publicly available framework designed to help close that gap.
The criteria address six principles across the full supply chain: carbon accounting, additionality, feedstock sourcing, leakage, environmental harms, and social harms and environmental justice. They are designed as a practical reference for what a credible SAF claim requires, and where existing certifications may leave gaps that require additional diligence.
At the transaction level, five questions should have clear answers before any buyer signs an offtake:
- Is the certificate linked to a specific project or supply agreement?
- Is that project financially dependent on the offtake, after accounting for all policy support already in the stack?
- Is the lifecycle emissions profile documented across the full well-to-wheel boundary, including indirect effects?
- Are the feedstock sourcing and supply chain risks assessed and disclosed?
- Has the producer evaluated leakage and community impacts?
The Google-American Airlines deal demonstrates what serious voluntary SAF procurement can look like. The Criteria for High-Quality Low Carbon Fuels provides the framework buyers need to evaluate deals like this one rigorously.