US Wood Pellet Producers: The UK Market Is Contracting. Four Markets Are Beginning.
Key Takeaways
- The UK's new biomass Contracts for Difference framework will cut industrial wood pellet imports by slightly more than half starting in April 2027. As a result, US producers will be left competing for only 1.6 million GST, an 80% reduction in US-addressable volume, with no successor market locked in.
- US wood pellet producers who move now to upgrade sustainability credentials and build relationships in emerging markets will be best positioned to capture the next generation of demand; those who wait may find the most attractive offtake opportunities already structured around someone else's supply.
- Four domestic markets now present producers with new demand opportunities: cofiring, sustainable aviation fuel (SAF), low-carbon steel, and bioenergy with carbon capture and storage (BECCS). Of these, BECCS for data centers is the strongest structural fit: hyperscalers need clean firm power, pellet mills need offtakers, and the feedstock infrastructure is already in place.
The Demand Cliff Is Real, and the Timeline Is Short
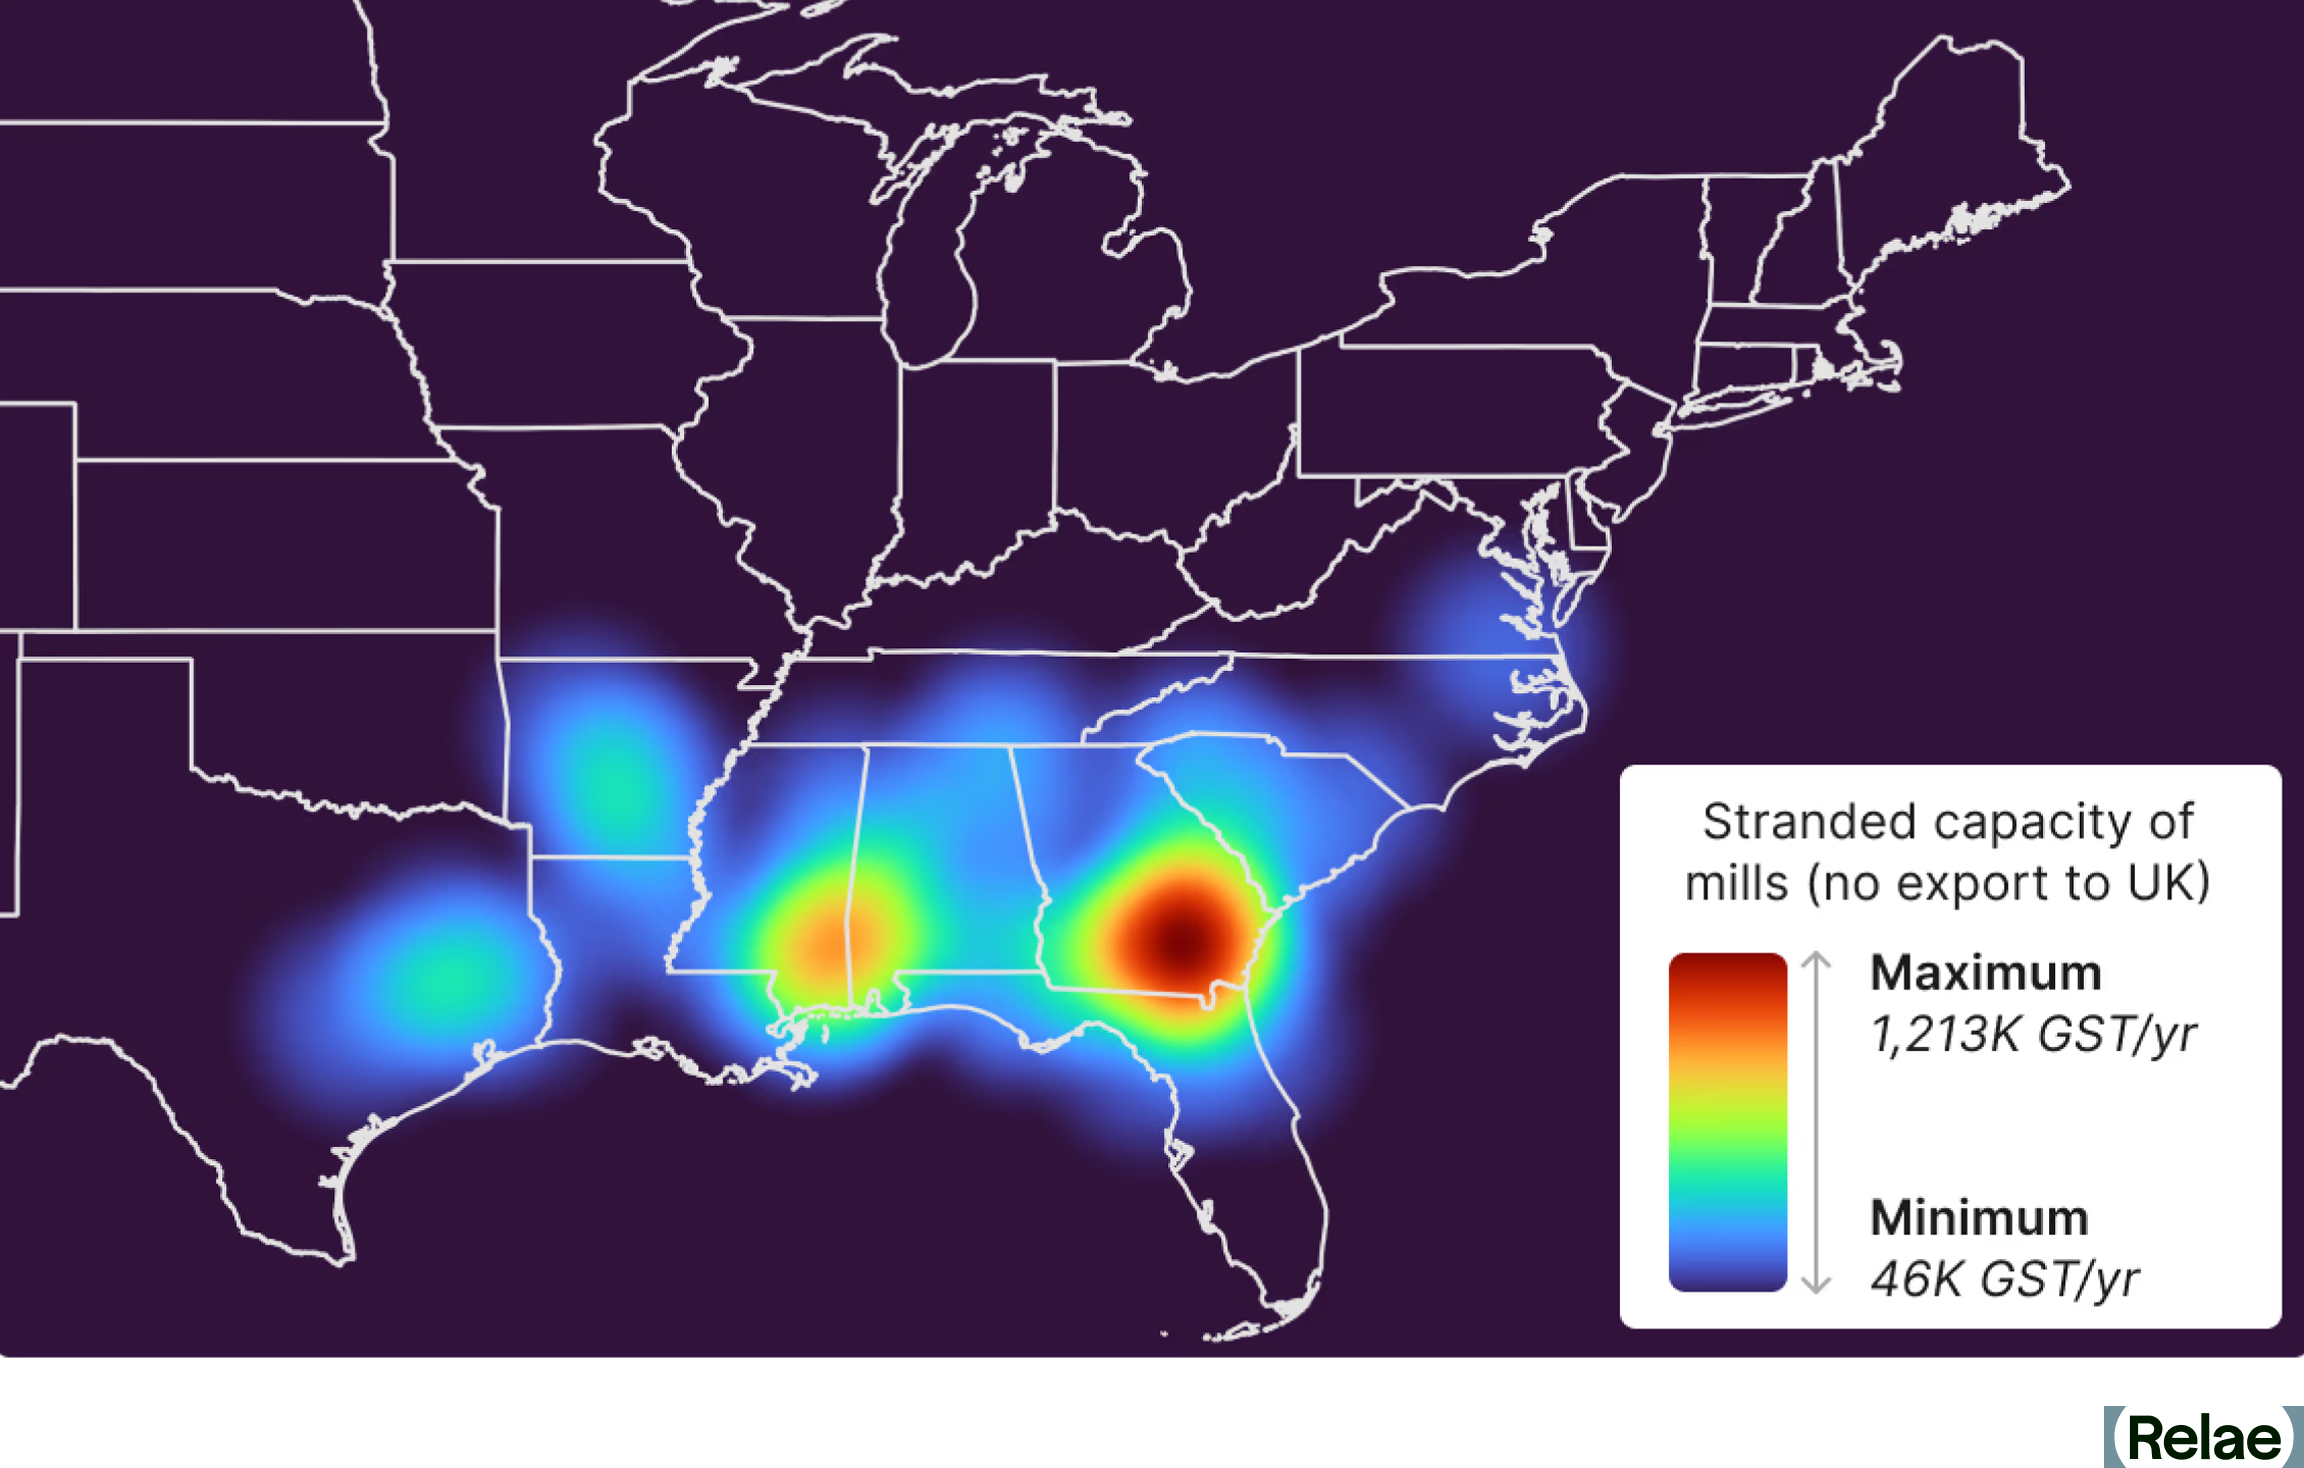
A pellet made in southern Mississippi this morning will be burned in a UK boiler about four weeks later. North America is on pace to ship more than 9 million green short tons (GST) of pellets to the UK each year—making the UK the world's largest consumer of wood pellets since 2018. The US Southeast is at the center of that supply chain: 28 large mills, 13.5 million GST of production capacity, rail spurs, export terminals, and bulk carriers, built almost entirely around UK demand.
However, the UK's new low-carbon Contracts for Difference (CfD) framework caps biomass power generators at a 27% annual capacity factor starting April 2027, down from roughly 64% today. When run hours fall by half, pellet demand follows. Existing subsidies expire in the first quarter of 2027, and the new CfD runs only to March 2031 with no commitment beyond that. Plant closures in Arkansas and Washington state, along with reduced output in Canada, are already early signals of supply chain contraction.
The Math of Who Gets Squeezed
The math is stark. By the second quarter of 2027, total annual UK pellet demand drops to 4.9 million GST. Of that:
- Approximately 2.3 million GST goes to captive, integrated UK supply chains.
- Approximately 1.0 million GST goes to Baltic suppliers, whose shipping times of one week or less become a decisive advantage as UK plants shift from baseload to dispatchable operation.
That leaves US producers competing for only 1.6 million GST. If Baltic suppliers capture more, US wood pellet exports to the UK could be effectively eliminated by 2031.
Sustainability qualification is also tightening. The new CfD cuts the supply-chain emissions ceiling from 55.6 grams of carbon dioxide equivalent per megajoule (gCO₂e/MJ) to 36.6 gCO₂e/MJ. The framework assesses compliance mill by mill, not on a portfolio average. A cleaner mill cannot carry a dirtier sibling through the door.
The producers who understand this math now have roughly 18 months to position themselves for what comes next.
From Stranded Supply to New Markets
The US Southeast's wood basket is robust: abundant inventory, strong growth-to-removal ratios, and more available residues than ever. The infrastructure is in place. The question is whether the next generation of markets can be developed quickly enough to redeploy this supply before the infrastructure sits idle.
Four pathways stand out as the strongest options for redeploying US pellet supply: BECCS for data centers, low-carbon steel, SAF, and domestic cofiring. We have rigorously assessed the logistics economics, sustainability cases, and project development for each.
BECCS for Data Centers: The Strongest Structural Fit
BECCS as a power source for data centers is the most compelling match for the situation pellet producers now face. The timing, feedstock requirements, and buyer characteristics align closely in a way that few other emerging markets can match.
Hyperscalers, the large data center operators driving an unprecedented surge in electricity demand, are signing deals for nuclear, geothermal, and small modular reactors alongside natural gas and renewables. They are doing this because annual Renewable Energy Certificates (RECs) are no longer sufficient to compensate for their scope 2 emissions, and they need clean, firm generation that can be matched to load on an hourly basis.
BECCS delivers exactly that. The Louisiana Green Fuels project—advanced by Strategic Biofuels and Relae (formerly Carbon Direct)—illustrates the model: regionally sourced forestry residues and sawmill waste generate 75 megawatts (MW) of firm electricity while sequestering over one million tonnes of CO₂ annually in deep saline formations. An ample supply of wood pellets creates a strategic opportunity for similar projects to move forward with certainty around feedstock processing, logistics, and costs.
The remaining commercial barrier is deal structure, not technology. No data center operator has yet signed an agreement to purchase both the electricity and carbon removal credits from a single BECCS plant. As scope 2 accounting tightens and domestic pellet supply becomes more readily available post-2027, the conditions for structuring the first such deal are improving fast.
"Pellet mills and data center developers have complementary problems: mills need offtakers, and data centers need local, dispatchable, clean power they can match to load on an hour-by-hour basis. BECCS is one of the few technologies that could solve both at once, and hyperscalers have shown they are willing to back early-stage clean firm power when the asset makes sense."
—Douglas Bryan, Senior Power and Energy Systems Modeler
Low-Carbon Steel: Certification Frameworks Are Arriving
Wood-derived biocarbon has a long-established niche in steelmaking. Brazil produces roughly 10% of its steel and 30% of its pig iron using charcoal from managed eucalyptus plantations—a proof of concept for biomass as a metallurgical input, if not a direct template for US producers. The plantations measurably lowered groundwater in producer regions of Minas Gerais, and charcoal's mechanical weakness relative to fossil coke has limited the model's reach beyond Brazil.
Current pilot projects use biomass in two roles. As a fuel, industrial trials have demonstrated 10% bio-coal co-injection without operational disruption, with reviews estimating that full replacement could cut blast-furnace CO₂ by around 27% per tonne of hot metal. As a reductant, biocoke is already being demonstrated at Outokumpu's pelletizing plant in Tornio, Finland. ArcelorMittal in Belgium and Tata Steel in India are running biomass pilots at tens of thousands of tonnes per year.
What makes this market worth serious attention now is the certification landscape. The Low Emission Steel Standard issued its first certifications in September 2025. The Global Steel Climate Council's Steel Climate Standard is under stakeholder review. In May 2025, Relae and Microsoft published Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors. These frameworks allow producers to internalize carbon price and environmental attribute certificate (EAC) values, closing the cost gap against fossil coke that has historically constrained biocarbon demand.
Relae worked with Eramet, a global metals company pursuing biogenic materials as a substitute for fossil coke at its Norwegian smelters, to assess high-quality carbon dioxide removal methodologies and chart a path to generating and selling carbon credits from their decarbonization projects. Producers who align their sustainability credentials to these emerging standards now will be better positioned for offtake as commercial-scale demand grows.
"Steelmaker pilots and the first low-carbon steel certifications are opening green-steel offtake to wood pellets, though commercial-scale demand remains limited. The producers that thrive in this market will be those that reliably deliver pellets aligned with high-quality sustainability standards."
—Louisa Brotherson, Hybrid Decarbonization Scientist
Sustainable Aviation Fuel: Mandates Create a Durable Demand Signal
Wood-based SAF is technically feasible via gasification to syngas, followed by Fischer-Tropsch upgrading, a proven chemistry for converting syngas to liquid hydrocarbons. Yet, the commercial challenges are substantial: the International Civil Aviation Organization estimates capital costs exceeding US$1 billion for large facilities, and production costs of US$11–48 per gallon to distillate.
The cautionary case is Fulcrum Bioenergy near Reno, Nevada, which attempted a Fischer-Tropsch process using municipal solid waste and appears to have failed due to a lack of rigorous pre-implementation testing and unrealistic timelines, a reminder that feedstock homogeneity matters enormously, and one area where pellets have a relative advantage.
Two structural dynamics make SAF worth serious attention despite those barriers. First, the European Union's (EU) SAF mandate, starting at 2% of jet fuel supply and ramping to 70% by 2050, carves out cellulosic biomass as the only qualifying feedstock once cooking oil supply is exhausted. The penalty structure in both the EU and UK creates strong demand regardless of SAF price: EU non-compliance penalties run roughly three times the price of SAF, and UK penalties can reach 13 times the cost of the fuel itself. Second, the alcohol-to-jet pathway offers a lower-capital entry point than Fischer-Tropsch, as demonstrated by Project Speedbird, a British Airways and LanzaJet collaboration targeting UK woody residues.
The near-term question is which routes have bankable offtake. Very few do yet, but the mandate structure suggests that window will shift rapidly.
"So far, facilities haven't scaled to the levels required to meet timeline demand. But the EU and UK mandate structures mean buyers are greatly incentivized to purchase SAF even at high prices, rather than pay non-compliance penalties."
—John Dees, Director, Fuels and Industrial Commodities
Domestic Cofiring: Achievable, but Not a Long-Term Anchor
Cofiring biomass with coal to produce electricity or heat is the most immediately achievable option. Most US coal-fired power plants could displace up to 10% of their input energy with raw or torrefied pellets, though plants would likely need fuel handling upgrades. Some state policies, such as Pennsylvania's Alternative Energy Portfolio Standards Act of 2004, support cofiring to meet renewable energy goals. However, there are no federal policies in the US that incentivize cofiring.
The case for cofiring as a long-term market is weak. The US coal fleet has contracted steadily for economic reasons—over 100 gigawatts (GW) of coal-fired capacity retired between 2015 and 2025—and biomass cofiring is unlikely to make a coal plant more cost-competitive. The Greenhouse Gas Protocol's scope 2 guidance does not permit buyers to procure a "strip" of electricity representing the biomass-fired fraction of output from a cofired plant; instead, buyers must accept the average total emissions from the plant in their scope 2 inventory, which limits the value proposition for corporate buyers seeking to demonstrate clean energy procurement.
The more interesting version of this pathway combines cofiring with carbon capture and storage (CCS), a combination that creates a deeper-abatement value proposition and the kind of firm, dispatchable power that corporate buyers increasingly need.
"Cofiring is a proven step toward modest emissions reductions from coal-fired electricity, but it's hard to make the economic case for it when compared to applications that command price premiums for deeper climate abatement."
—A.J. Simon, Director of Industrial Decarbonization
Sustainability Is Now the Qualification Gate
Each of these markets is more discerning about sustainable biomass sourcing than the UK power sector was a decade ago. That shift will not reverse.
US Southeast wood has real potential for high-integrity sustainability credentials, particularly in softwood residues. But it also carries downside risks when sourcing from natural stands. Through work with producers, buyers, and project developers across these markets, we have found that four questions now drive every serious procurement conversation:
- Does the supply chain have verifiable governance and chain-of-custody transparency?
- Does sourcing respect the rights of Indigenous Peoples and local communities?
- Is the wood coming from regions where forest carbon stocks are stable or growing, and not from protected areas or primary forest?
- Is sourced biomass a by-product of non-energy uses, and not the primary silviculture driver?
Producers who can answer yes to all four, and support those answers with data, are more likely to access these emerging markets. Those who cannot will find it harder to compete for offtake.
For a detailed framework on how these principles translate into contract language and certification requirements, see the 2025 Sustainable Forest Biomass Sourcing for CDR: A Buyer's Guide.
The Window Is Open, but Not Indefinitely
The US Southeast wood basket is well-positioned for the markets described here. The infrastructure is in place. What producers still need to build is the market positioning, sustainability documentation, and offtake relationships to go with it.
The producers who move now will have a meaningful head start. Those who wait for certainty may find that the most attractive offtake opportunities have already been structured around someone else's supply.
Learn more about Relae's work on SAF mandates, steel decarbonization, and sustainable biomass sourcing.
Frequently Asked Questions
What happens to US wood pellet exports when the UK's new biomass rules take effect?
Starting April 2027, the UK's signed Contracts for Difference agreement caps subsidized biomass generation at a 27% capacity factor, roughly half of today's levels. That's expected to cut total UK pellet demand to about 4.9 million GST a year, leaving only around 1.6 million GST available to US exporters.
Is BECCS for data centers a proven market, or still emerging?
The underlying technology is credible, and the Louisiana Green Fuels project already demonstrates it at commercial scale. However, the deal structure isn't yet proven. No hyperscaler has signed a single contract for both electricity and carbon removal credits from one BECCS plant, so this market is emerging rather than established.
How does low-carbon steel demand compare to sustainable aviation fuel as a market for pellet producers?
Steel offers nearer-term certification frameworks (the Low Emission Steel Standard began issuing certifications in 2025) but limited commercial-scale volume so far. SAF has a stronger long-run demand signal thanks to EU and UK blending mandates and steep non-compliance penalties, but requires far higher capital investment to enter.
What should a wood pellet producer look for when evaluating a new market?
The four sourcing questions that now gate access across all these markets are: verifiable chain-of-custody, respect for Indigenous and local community rights, sourcing from stable or growing forest carbon stocks (not primary forest), and biomass that's a by-product of non-energy uses rather than the primary driver of harvest.
Natural Capital
Relae helps investors, asset managers, and companies with land and agricultural exposure manage risk related to natural capital, meet evolving disclosure requirements, and evaluate land-based assets and supply chains with greater confidence. We combine ecological, carbon, policy, community impact, and market expertise to translate nature dependencies into financially material decisions.
Ready to Navigate What Comes Next?


Shirin Mavandad
Shirin Mavandad

Shirin has a diverse professional background spanning nature based solutions, energy policy, and data analysis. Before joining Relae, she worked as a Research Associate for CLASP where she conducted policyresearch on the efficiency and accessibility of household appliances across an international landscape. Prior to CLASP, she also worked at Indufor North America where she supported client-based consulting work relating to landscape conservation and forestry. During her time in undergrad, Shirin also worked in the UC Davis SCOW lab where she facilitated research on enhancing the carbon sequestration properties of agricultural soils.
What to Read Next
The Role of Improved Forest Management for Carbon Dioxide Removal
Key Takeaways
- Improved forest management (IFM) increases measurable long-term carbon storage in living trees and durable wood products.
- At the same time, it can provide strong social and ecological co-benefits.
- IFM projects like the ones developed by Weyerhaeuser and the Indigenous community of Petcacab in collaboration with Relae (formerly Carbon Direct) show how IFM practices can align climate goals with social and environmental benefits.
Forests Are Climate Solutions If We Manage Them Wisely
Forests remove carbon dioxide from the atmosphere, but they need to be thoughtfully managed to keep doing so. As buyers look to scale carbon removal, improved forest management (IFM) is gaining traction in the voluntary carbon market (VCM).
IFM focuses on enhancing how existing forests are managed to increase carbon storage over time. It’s a nature-based solution that supports climate outcomes, community livelihoods, and environmental benefits when done well.
This piece explains how IFM works, what makes a project high-quality, and how real-world IFM projects like those developed by Weyerhaeuser and Petcacab in collaboration with Relae (formerly Carbon Direct) are delivering credible results for buyers and local communities alike.
What Is Improved Forest Management?
Improved forest management is a catch-all phrase that describes management techniques that decrease emissions from forests or increase carbon removal and storage. Some management techniques, like transitioning a working forest to a conserved status, decrease emissions from forest harvest and primarily create credits for avoided emissions. Other management techniques, like harvesting forests less frequently, can lead to greater carbon removal and storage over time and create credits for additional carbon removal.
Examples of IFM Practices Include:
- Extending harvest rotations to allow more carbon accumulation
- Reducing the impact of logging on soil and surrounding trees
- Managing fire and pest risks to enhance forest health
- Transitioning some of a forest to conservation status
These strategies help forest carbon stocks grow beyond business-as-usual baselines. In carbon markets, IFM can generate carbon removal or avoided emissions credits, depending on the project's design and carbon accounting methodology.
What Makes a High-Quality IFM Carbon Removal Credit?
Buyers today face increased scrutiny around carbon credit quality. In this context, IFM projects must go beyond basic registry standards to demonstrate climate integrity and social and environmental benefits.
Relae developed the Criteria for High-Quality Carbon Dioxide Removal, an annual report published in collaboration with Microsoft to establish science-backed quality standards. This includes six core principles that define high-quality carbon removal, all of which apply to IFM projects:
- Social harms, benefits, and environmental justice - The extent to which the project prevents new social harms to people and communities, reduces existing harms, and provides meaningful benefits distribution. Since IFM projects take place in communities around the world, benefits will naturally vary from project to project.
- Environmental harms and benefits - The extent to which the project minimizes and mitigates environmental harms, as well as provides environmental benefits. Because IFM projects enhance management practices, environmental co-benefits of high-quality IFM projects are usually substantial.
- Additionality and baselines – Evidence that the project’s carbon removal would not have occurred without carbon finance. Many IFM projects fail to present compelling additionality data and narratives. High-quality projects will be able to identify the actions the project took to increase carbon storage that would not have happened without carbon finance.
- Measurement, monitoring, reporting, and verification (MMRV) – The ability to accurately quantify carbon removal in a repeatable and verifiable way, and to develop a plan for long-term monitoring of the project. IFM projects must have robust forest inventory, growth modeling, and occasional remeasurement to verify the additional carbon storage.
- Durability – The likelihood that removed carbon remains stored over time, with mechanisms in place to mitigate reversal risk. Enhanced management of fire, pests, and disease in IFM projects can enhance forest carbon durability.
- Leakage – Evaluation of whether project activities cause increased emissions elsewhere. If an IFM project substantially reduces timber supply, market demand can drive increased harvesting in other forests, undermining some of the project’s climate benefits. High-quality IFM projects minimize this risk by limiting harvest reductions, and account for any remaining leakage by issuing fewer credits.
Relae uses these criteria as part of our diligence framework when advising buyers evaluating projects and co-developing our own projects.
IFM Projects Delivering Real Impact
Weyerhaeuser: Applying Science at Scale
Weyerhaeuser, one of the largest forest owners in North America, is applying improved forest management practices across over 200,000 acres of working forests.
The IFM projects led by Weyerhaeuser are located in rural areas in the US, with low wildfire risk. These IFM projects sequester carbon by extending harvest rotations and forgoing harvest in established streamside management zones.
Relae supported Weyerhaeuser with hands-on scientific collaboration to confirm that every IFM project met the Criteria for High-Quality Carbon Dioxide Removal.
Why it matters to buyers:
- High-quality climate impact at large scale
- Transition of working forests from traditional management techniques to maximize climate impact
- Responsible forestry practices aligned with SFI® standards
- Rigorous carbon accounting and high-quality project baseline established using historical harvest records
The IFM projects led by Weyerhaeuser are some of the largest in the US today and a model for scaling science-backed forest carbon solutions.
Petcacab: Indigenous-Led Conservation in the Yucatán Peninsula
Located in the communal lands of Petcacab, Mexico, this IFM project is led by Indigenous Mayan ejidatarios—community members who have legal rights to manage the land.
Historically, forests in the ejido have been degraded through unsustainable harvesting and extensive damage from hurricanes. Through carbon finance, they are developing new forest management plans and sustainable forestry models, with revenue reinvested in health, education, and job creation.
“The rainforest for me represents my home, my work, my present, my future. We have a very daring challenge: to transform how we manage our forest, shifting from harvesting and selling timber to conserving it through the sale of carbon credits that support the development of our community.”
— Celso Chan Rivas, Carbon Project General Manager
What makes Petcacab stand out:
- Equitable benefit-sharing and strong Indigenous governance
- Critical habitat protection for endangered species
- Increased additional carbon storage through forest management and reduced land use conversion
- Transparent reporting and verified outcomes
Petcacab is recognized by Relae as a high-quality community IFM project in Mexico, with clear social, environmental, and climate outcomes.
Investing in Forests That Deliver More Than Carbon
Improved forest management is more than a carbon strategy, it’s an investment in ecosystems, communities, and long-term impact. For buyers seeking high-integrity carbon removal with social and environmental co-benefits, IFM projects offer a compelling opportunity.
IFM projects like the ones developed by Weyerhaeuser and Petcacab in collaboration with Relae show what’s possible when forests are managed with science and care. They also reflect what the voluntary carbon market needs more of: quality, transparency, and impact beyond the metric ton.
What Is Biochar? A Carbon Removal Solution Gaining Ground
Key Takeaways
- Biochar is the fastest-growing durable carbon removal method in the voluntary carbon market, accounting for 93% of all durable removal volumes contracted in the first quarter of 2026 alone.
- Scientists still have an incomplete understanding of biochar durability in soils, and there is some uncertainty regarding biochar's ultimate climate impact.
- Biochar carbon removal crediting must reflect conservative, science-based estimates of durability to safeguard against overcrediting.
- Relae’s (formerly Carbon Direct) detailed analysis highlights the key scientific issues affecting biochar soil durability to better inform credible carbon removal.
Biochar Is Gaining Momentum in Carbon Removal
Biochar has entered the spotlight as a scalable climate solution. It is being adopted for its carbon storage potential and agricultural co-benefits. Commercial uptake of biochar has expanded dramatically since 2019 and continues to accelerate, due to the voluntary carbon market. In the first quarter of 2026 alone, 2.3 million tonnes of total durable carbon dioxide removal (CDR) have been contracted, with biochar accounting for 93% of that volume, driven substantially by a single Microsoft-Liferaft deal for one million tonnes. Established and emerging CDR registries have developed biochar protocols and are certifying biochar carbon credits.
In addition to CDR, biochar can bring numerous co-benefits when it is applied to soil. These benefits include improved water and nutrient retention, pH adjustment, and pollution remediation. In agricultural and forage systems, improvements in soil quality following biochar application can lead to enhanced plant growth. Biochar also promotes rural economic development and can be a part of a circular economy that stewards its resources judiciously.
As purchases of biochar credits grow, a central question has not yet been fully answered: How durable is biochar carbon storage, and what are the best methods to assess this? This blog explores the science of biochar durability, also known as permanence, and how credible science can inform the carbon removal market.
What Is Biochar and How Is It Made?
Biomass heated in an oxygen-deficient environment produces biochar, a solid, carbon-rich material. In the near or full absence of oxygen, that process is called pyrolysis. Biochar can be produced from various kinds of biomass, including agricultural or forest residues, construction debris, organic waste, seaweed, and more. Biochar is also gaining attention for its potential as an ingredient within engineered materials, such as cement.
Biochar achieves CDR by durably storing carbon dioxide (CO₂) that was removed from the atmosphere via photosynthesis and plant growth. Carbon stored in living plants will stay stored during the plant’s lifespan. Once it dies, a plant’s biomass decomposes, cycling most of the stored carbon back into the atmosphere. By introducing technological interventions into this carbon cycle, such as using pyrolysis to produce biochar, the carbon that nature captured via photosynthesis can be stored longer than it would have been otherwise. Pyrolysis converts some of the carbon from biomass into chemical compounds with a higher resistance to environmental degradation. How much carbon converts to these more recalcitrant forms depends on the type of biomass used and the heating conditions, including temperature and time. After biochar is produced, the highly recalcitrant fraction of carbon can be stored for long periods of time, as long as the biochar does not combust.
Common methods of biochar production include:
- Industrial pyrolysis systems: Modern pyrolysis systems heat biomass in a low or no-oxygen environment, creating biochar and gaseous compounds known as synthesis gas. Synthesis gas is typically combusted in a controlled system to provide heat for the system. Low air emissions can be achieved for these systems, which is important to maximizing the environmental benefits of biochar production.
- Modular pyrolysis systems: Smaller, transportable pyrolysis units serve farm-scale or decentralized production. Unlike open kilns, these systems retain temperature control and sensor-based monitoring similar to industrial pyrolysis, and some use autothermal designs that recycle non-condensable gases for heat rather than relying on an external energy source. This makes them a middle option for smaller producers seeking more process control and emissions oversight than open-kiln methods allow, without the capital cost of a large, fixed industrial plant.
- Kon-Tiki kilns: This is a less complex and, therefore, more widely deployable method of biochar production. However, air pollution from this method is likely to be higher than from industrial pyrolysis and can be significant enough to undermine the carbon benefits of biochar production. In Kon-Tiki kilns, biomass is burned in an open-top, conical kiln. Biomass is continually added to the process and finally quenched with water.
- Trench mounds: Trench production is one of the simplest forms of biochar production and is used often by smallholder farmers. Biomass is buried in a trench, covered, and combusted to produce biochar. Air pollution from tench mound production is likely to be significant and even higher than from Kon-Tiki kilns.
How Biochar Durability Is Quantified
Durability, or permanence, is a key metric used to quantify carbon removal from biochar; it describes the amount of carbon that remains stored in biochar for 100 years or more after it is applied to soil.
Quantifying durability relies on experiments and models to project permanence. There are a number of established and emerging approaches to evaluating biochar recalcitrance to chemical decomposition and storage permanence. Most of these are based on short-term incubation experiments in laboratories, where scientists seal biochar in a container with other organic matter and measure carbon changes over a period of weeks to months. These approaches typically treat biochar as having multiple pools of carbon that differ in their ability to resist decomposition.
While these experiments offer insights into decomposition dynamics, they have two significant limitations. First, these approaches do not measure biochar decomposition and durability in the real world (e.g., after biochar is applied to agricultural soils), meaning they do not capture the effects of actual soil and other environmental factors. Research has shown that different soils can strongly influence decomposition rates. Second, the short duration of these experiments means there is significant potential for error in extrapolating the results to time periods of centuries and beyond.
Why Quantifying Durability Accurately Is Critical
Biochar CDR certification methodologies use a range of approaches to quantify permanence. Most commonly these are based on biochar’s chemical composition, namely the hydrogen-to-organic-carbon ratio (H/Corg). Models that correlate H/Corg with projected permanence, from decay models applied to biochar decomposition experiments, are used to calculate a permanence factor. Other quantification methods include measuring the random reflectance of biochar to estimate the amount of highly recalcitrant carbon in biochar.
The risks of inaccurate durability estimates for carbon removal buyers are significant. Overestimating durability can lead to ineffective CDR spending, reputational risk from overstated climate impact, and delayed progress on net-zero and compliance goals. Buyers need to understand and engage with durability estimation methods to ensure they are procuring high-quality biochar credits.
Why Underground Coal Isn't a Valid Durability Comparison
Recent research proposes a new approach to quantifying biochar durability. The authors assert that random reflectance—a parameter developed in the field of organic petrology (the study of organic matter in rocks)—can be used to characterize durability. Using a component of coal (known as "inertinite") as an analogue for biochar, they propose a benchmark random reflectance of 2% as an "inertinite benchmark" for biochar. They argue that the entire fraction of biochar that meets that benchmark will degrade over approximately 100 million years. This is a large departure from other estimates of biochar durability, and we believe this to be at odds with more conservative models.
There are several reasons to doubt this method. The coal-biochar analogy is inadequate because coal buried underground is not exposed to the same degradation conditions as biochar in soil. Underground coal has lower exposure to oxygen, water, and ultraviolet light, all of which are plentiful in surface soils. Each of these is associated with well-understood decay mechanisms. Furthermore, the process of geologic burial dramatically changes the physical structure of organic matter. Additionally, the permanence factor that the reflectance method allows (i.e., up to 100% carbon retention over extremely long time scales) contradicts experimental evidence that some carbon loss will occur over years or decades.
Subsequent research from the same authors has since recommended pairing random reflectance analysis with H/Corg rather than relying on either alone. This is a refinement of the original approach meant to support more reliable quantification of biochar durability and avoid overcrediting CDR from biochar.
Where Biochar Science Is Headed Next
Biochar stability science will keep advancing. Research into biochar degradation pathways in soil will continue to refine permanence models and inform the relevance of coal analogues. Long-term field measurement studies, with a high density of in-soil sampling to quantify persistence over time, should be a near-term priority that biochar CDR projects can contribute to. Additional studies should investigate pathways to increase durability and rigorously develop modern isotopic, spectroscopic, and chemical techniques for enabling robust assessments of biochar durability.
Crediting Biochar Means Getting Durability Right
Biochar is a promising solution for both soil health and climate impact. Nevertheless, carbon removal certification protocols will need updating as the science of biochar durability evolves. Relae cautions against excessively generous claims of biochar CDR durability, in both permanence factor and timeframe, given the important uncertainties outlined above.
Protocols should not outpace science in terms of permanence assessment, and crediting should stay rooted in an understanding of what drives biochar permanence that is backed by science, including production conditions (e.g., high temperatures) and biochar composition (i.e., low H/Corg). At a time when investment in biochar is booming and the science of biochar is evolving, the voluntary carbon market must keep pace.
Frequently Asked Questions
Is biochar carbon negative?
Biochar can provide net carbon dioxide removal when the amount of carbon durably stored exceeds the emissions associated with producing, transporting, and using the biochar. Plants capture CO2 from the atmosphere through photosynthesis and store that carbon in biomass. Left alone, most of that carbon returns to the atmosphere within years to decades as the biomass decomposes or burns. Converting biomass to biochar stabilizes a portion of that carbon into forms that can stay stored for centuries or longer, delivering a net removal once those production emissions are accounted for..
Is biochar considered an engineered, hybrid, or nature-based carbon removal solution? Biochar is considered a hybrid carbon removal solution because it combines natural carbon uptake through photosynthesis with a technological intervention. Biomass first removes and stores atmospheric carbon as it grows, and pyrolysis then converts a portion of that biomass carbon into more stable forms that keep carbon from returning to the atmosphere for longer periods.
How do carbon removal registries currently estimate biochar's durability? Registries use decay models based on biochar's ratio of hydrogen to organic carbon (H/Corg ratio), which correlates with how resistant the biochar is to microbial breakdown, combined with environmental factors where biochar is applied, like soil temperature, moisture, and application context, to estimate what fraction of the carbon remains stable (i.e., not converted back to CO2) over a defined timeframe. Methodologies typically also require third-party lab testing of feedstock and pyrolysis conditions to substantiate durability claims. Some registries and methodologies also incorporate random reflectance as part of durability quantification, although the scientific basis for using reflectance to estimate long-term biochar durability remains under debate.
How long does biochar actually store carbon?
Biochar does not have a single storage lifetime. Some of its carbon decomposes relatively quickly, while more stable fractions can remain stored for centuries or longer, depending on the biochar’s properties and the conditions where it is stored. Because these estimates rely on models rather than direct observation, carbon crediting has to balance two risks: crediting more durability than actually exists, and being so conservative it undercredits real removals and threatens project viability.
Marine Carbon Dioxide Removal: What It Is and How It Works
Key Takeaways
- Marine carbon dioxide removal (mCDR) uses ocean-based processes—primarily ocean alkalinity enhancement (OAE) and direct ocean removal (DOR)—to capture and durably store atmospheric carbon dioxide (CO₂), without the land and freshwater constraints of terrestrial methods.
- The ocean already absorbs roughly 29% of human-caused CO₂ emissions each year, according to the 2025 Global Carbon Budget, and mCDR technologies aim to safely enhance that natural uptake without worsening ocean acidification.
- For corporate carbon buyers and project developers evaluating mCDR, the Criteria for High-Quality Marine Carbon Dioxide Removal, developed by Microsoft and Relae, outlines standards to guide responsible mCDR deployment at scale.
Reducing carbon dioxide (CO₂) emissions alone is no longer sufficient to limit global warming to 1.5°C. To effectively address climate change, scientific consensus highlights the need to remove carbon dioxide already present in the atmosphere. Marine carbon dioxide removal (mCDR), a form of ocean-based carbon removal, offers a scalable solution by leveraging the ocean’s natural ability to absorb and store carbon, without the land and resource limitations associated with terrestrial carbon removal methods.
This guide explores the fundamentals of marine carbon dioxide removal, including how it works, the technologies involved, and its role in global decarbonization.
What Is Marine Carbon Dioxide Removal?
Marine carbon dioxide removal uses ocean-based processes to capture and store carbon dioxide from the atmosphere. mCDR techniques fall into two primary categories:
- Biotic CDR, which includes using photosynthetic fixation, microalgae cultivation, and terrestrial biomass sinking, to capture and store carbon.
- Abiotic CDR, which influences CO₂ concentrations and carbonate chemistry in the seawater to absorb atmospheric CO₂ without increasing acidity. There are two main abiotic mCDR pathways: ocean alkalinity enhancement (OAE) and direct ocean removal (DOR).
How Does Marine Carbon Dioxide Removal Work?
Marine carbon dioxide removal functions via the air-sea gas exchange—a process by which the atmosphere and surface seawater maintain equal CO₂ concentrations—meaning a shift in one leads to a corresponding change in the other. This exchange allows the ocean to absorb or release CO₂ back into the atmosphere depending on concentration levels and factors like pH.
Once absorbed by the ocean, CO₂ exists in several forms, including dissolved CO₂, carbonates, and bicarbonates, influencing the ocean's pH levels. As atmospheric CO₂ levels rise, the oceans absorb roughly 12 GtCO2 annually, approximately 29% of anthropogenic CO2 emissions. This increase is disrupting the natural CO₂ balance and contributing to ocean acidification.
mCDR methods like ocean alkalinity enhancement and direct ocean removal use safe and controlled processes to increase the amount of CO2 absorbed from the atmosphere while mitigating acidification.
Understanding Ocean Alkalinity Enhancement (OAE)
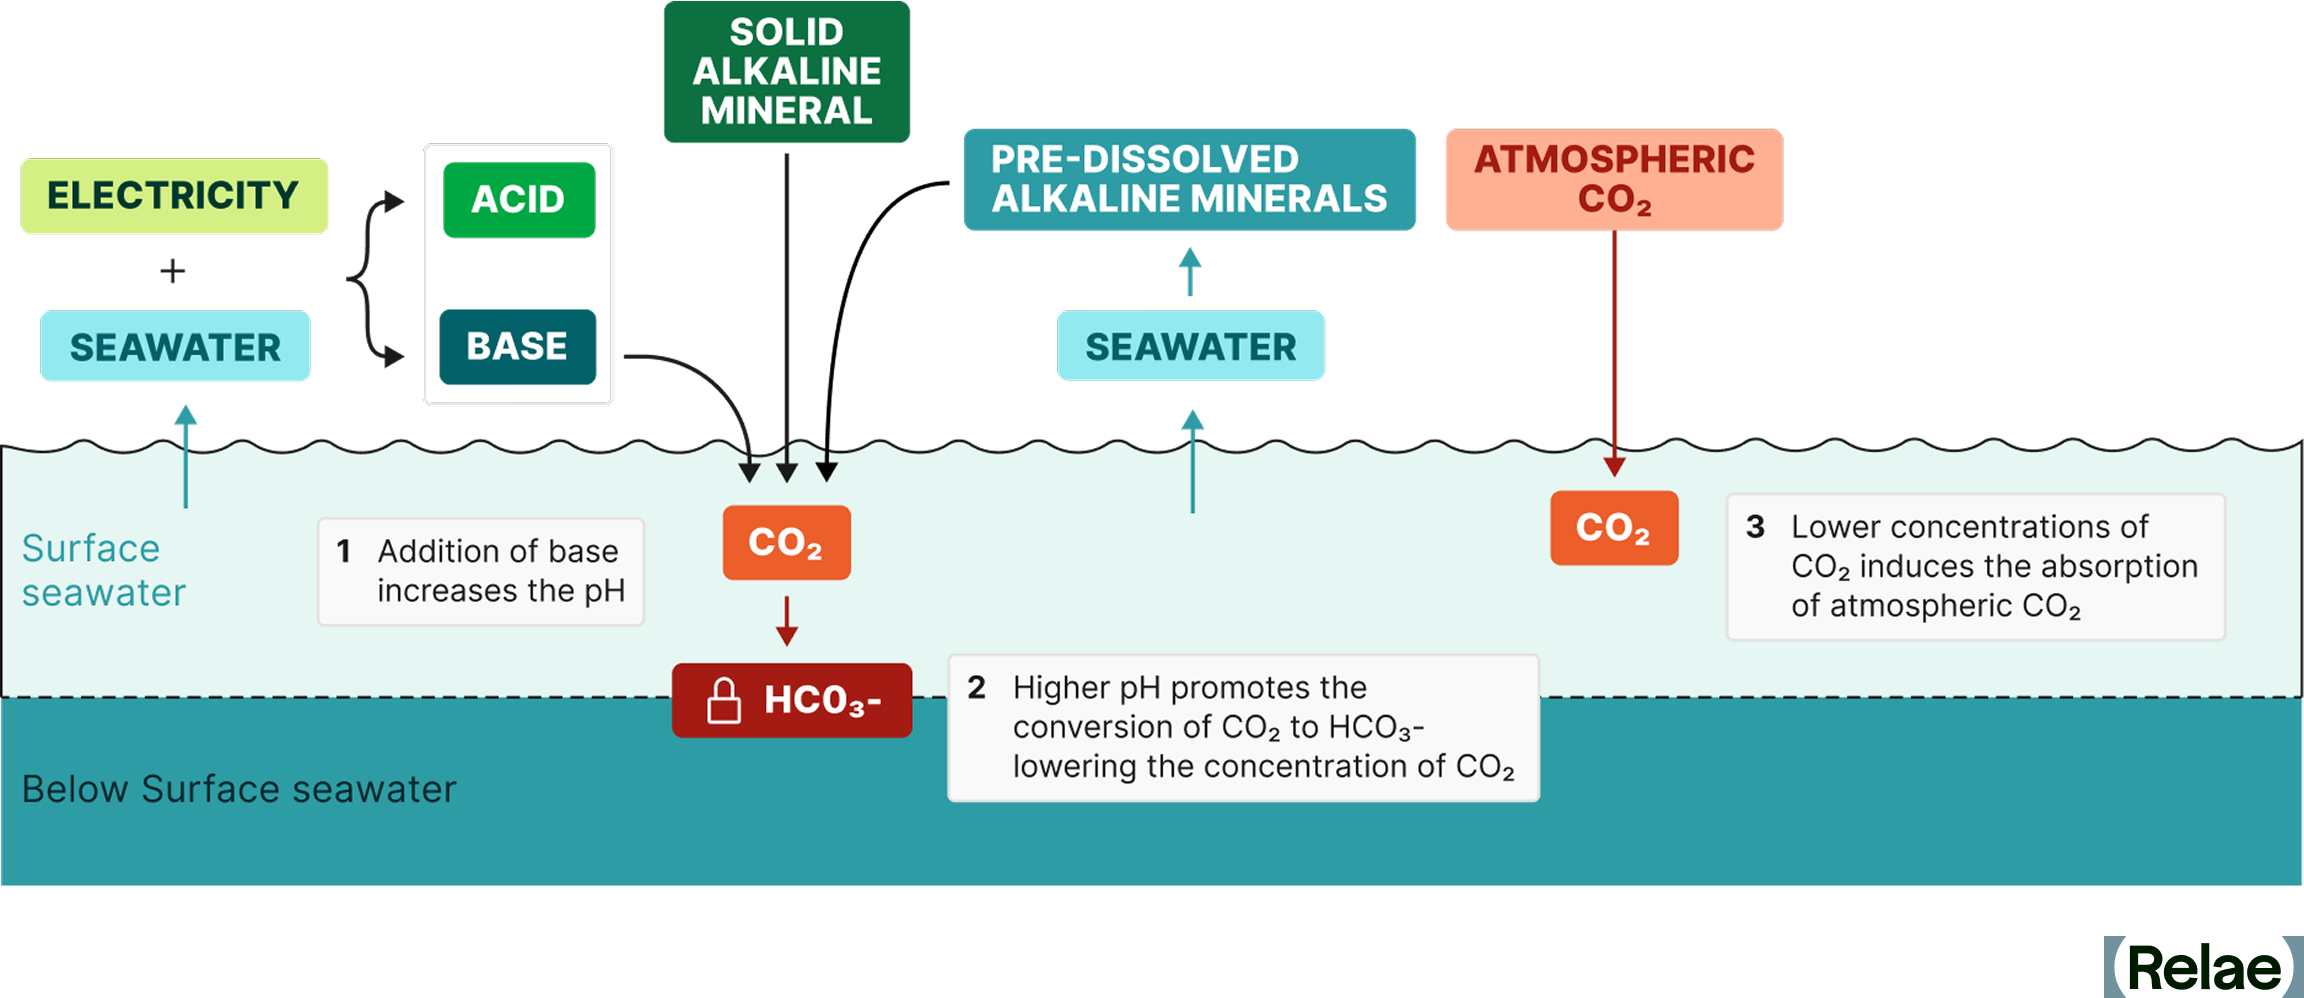
Ocean alkalinity enhancement (OAE) captures and stores atmospheric CO₂ as dissolved carbonates in the ocean by increasing the alkalinity of seawater using one of two primary methods:
- Adding alkaline minerals such as olivine or basalt to seawater.
- Using electrochemical methods to add alkaline compounds to seawater.
Both of these methods increase the alkalinity of seawater and, thereby, its capacity to absorb atmospheric CO₂ without acidification.
OAE methods can also differ by location and the manner in which seawater interacts with alkaline substances and atmospheric CO₂. This interaction may occur in the open ocean or within a controlled mCDR project facility. Each approach involves trade-offs: open ocean methods tend to be less energy-intensive but present greater uncertainties and challenges in measurement, reporting, and verification (MRV).
Understanding Direct Ocean Removal (DOR)
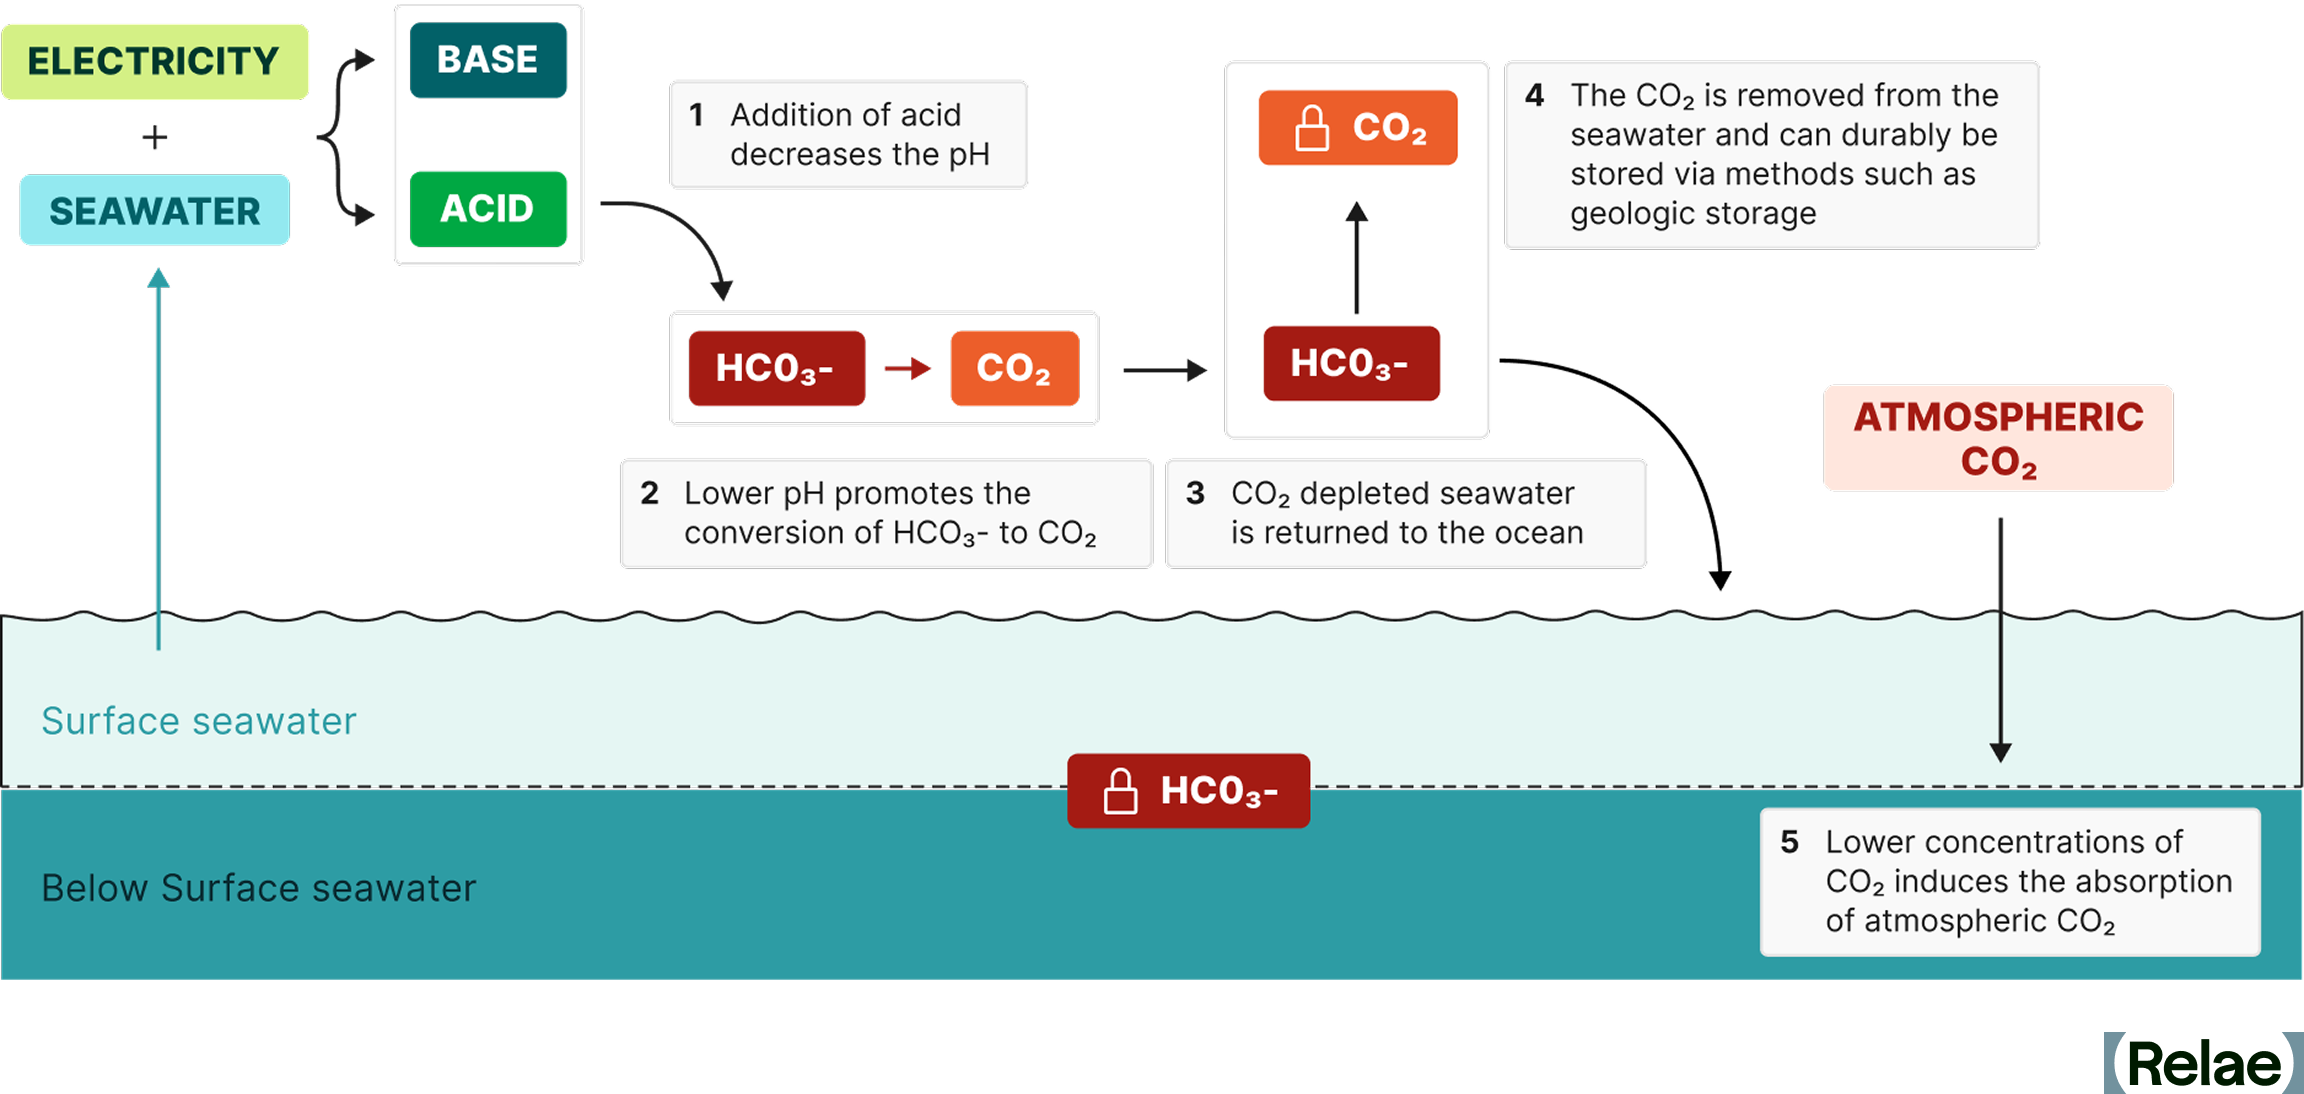
Direct ocean removal (DOR), also called direct ocean capture (DOC), removes CO₂ dissolved in seawater using the controlled acidification of seawater in a closed system using one of two primary methods:
- Electrochemical methods such as electrolysis of seawater or electrodialysis
- The addition of minerals like olivine and basalt.
The acidified and CO₂ depleted seawater is neutralized to native pH and allowed to equalize with and remove atmospheric CO₂. Once removed, CO₂ can be safely stored using geologic storage with a durability of >1,000 years.
Nomenclature for Direct Ocean Removal
Direct ocean removal is more commonly referred to as direct ocean capture. Relae believes the term direct ocean removal (DOR) is more accurate for two reasons:
- We think it is scientifically more accurate as both OAE and DOR remove CO₂ from the atmosphere but DOR directly removes CO₂ from the oceans, where in OAE, CO₂ is captured as bicarbonates in the ocean.
- DOC is a term for dissolved organic carbon, which is frequently used in mCDR project documents, reports, and the scientific literature.
Key Benefits of Marine Carbon Dioxide Removal
Understanding how mCDR works highlights its potential to address climate challenges. Here are the key benefits that make it a critical tool in global decarbonization strategies.
- Scalable carbon removal without land constraints: Marine carbon dioxide removal does not require large land areas or significant freshwater resources, making it highly scalable.
- Harnessing the ocean’s natural carbon sink: The ocean absorbs about 25% of human-generated CO₂ annually. mCDR enhances this natural process, increasing carbon storage without accelerating ocean acidification.
- Diverse technological pathways for flexibility: Technologies like ocean alkalinity enhancement and direct ocean removal offer flexible solutions tailored to different environments and project needs.
- Global reach with a large surface area: Covering over two-thirds of the Earth’s surface, the ocean provides an expansive platform for mCDR technologies globally.
- Potential to mitigate ocean acidification: Some mCDR methods, such as ocean alkalinity enhancement, not only remove CO₂ but also help restore ocean pH levels, supporting marine ecosystem health.
Challenges of Marine Carbon Dioxide Removal
While mCDR holds significant promise, it also presents challenges that must be addressed for responsible deployment.
- Technical scalability and efficiency: Scaling mCDR technologies to achieve meaningful carbon removal while maintaining energy efficiency remains a significant hurdle.
- Potential environmental impacts: Altering ocean chemistry may pose risks to marine ecosystems, with long-term effects still not fully understood.
- Measurement, reporting, and verification (MRV) complexity: Accurately measuring CO₂ removal and ensuring its durability requires advanced monitoring systems, which are still evolving.
- Regulatory and governance gaps: Clear global policies are needed to oversee mCDR deployment, manage environmental risks, and ensure accountability.
- Public perception and ethical considerations: Concerns around geoengineering and potential unintended consequences may impact public acceptance and policy support.
Deploying Marine Carbon Dioxide Removal
As mCDR technologies evolve, effective deployment will rely on adaptive management practices to address technical, environmental, and regulatory challenges. This includes robust MRV systems for accurate CO₂ removal tracking and continuous ecosystem monitoring to mitigate potential risks to marine life.
Collaborative efforts between scientists, policymakers, and project developers are key to establishing clear regulatory frameworks, optimizing technologies for efficiency and scalability, and building public trust. These practices ensure mCDR can be scaled responsibly while safeguarding ocean health.
The Future of Marine Carbon Dioxide Removal
As technologies like ocean alkalinity enhancement and direct ocean removal advance, their potential to deliver large-scale, durable carbon removal is becoming increasingly evident. Realizing this potential requires more than technological innovation—it depends on rigorous environmental monitoring, transparent reporting, and strong collaboration among project developers, carbon buyers, and policymakers.
Establishing clear, consistent standards for high-quality mCDR is essential to ensure both climate effectiveness and environmental safety. To support this, Microsoft and Relae have partnered to develop the Criteria for High-Quality Carbon Dioxide Removal.
Frequently Asked Questions
What is marine carbon dioxide removal (mCDR)?
mCDR uses ocean-based processes, primarily ocean alkalinity enhancement and direct ocean removal, to capture and durably store atmospheric CO₂. It works by increasing the ocean's natural capacity to absorb CO₂ without increasing acidification.
How does marine carbon dioxide removal compare to land-based methods like direct air capture or reforestation?
Unlike land-based approaches, mCDR doesn't require large land areas or freshwater, and the ocean's size gives it significant scaling potential. It's earlier-stage than more established pathways, though, with measurement and environmental monitoring standards still maturing.
Is marine carbon dioxide removal proven and scalable today, or still emerging?
mCDR technologies have shown promising results in lab testing and early deployments, but confirming safety and effectiveness at a large real-world scale requires more monitoring data. It's best described as an emerging pathway with strong near-term momentum, not yet a mature, at-scale solution.
What should a company look for when evaluating a marine carbon dioxide removal project or credits?
Buyers should look for rigorous carbon MRV paired with equally rigorous monitoring of ocean ecosystem health (eMRV), transparent reporting, and adherence to established frameworks like the Criteria for High-Quality Carbon Dioxide Removal.
US Wood Pellet Producers: The UK Market Is Contracting. Four Markets Are Beginning.
Key Takeaways
- The UK's new biomass Contracts for Difference framework will cut industrial wood pellet imports by slightly more than half starting in April 2027. As a result, US producers will be left competing for only 1.6 million GST, an 80% reduction in US-addressable volume, with no successor market locked in.
- US wood pellet producers who move now to upgrade sustainability credentials and build relationships in emerging markets will be best positioned to capture the next generation of demand; those who wait may find the most attractive offtake opportunities already structured around someone else's supply.
- Four domestic markets now present producers with new demand opportunities: cofiring, sustainable aviation fuel (SAF), low-carbon steel, and bioenergy with carbon capture and storage (BECCS). Of these, BECCS for data centers is the strongest structural fit: hyperscalers need clean firm power, pellet mills need offtakers, and the feedstock infrastructure is already in place.
The Demand Cliff Is Real, and the Timeline Is Short
A pellet made in southern Mississippi this morning will be burned in a UK boiler about four weeks later. North America is on pace to ship more than 9 million green short tons (GST) of pellets to the UK each year—making the UK the world's largest consumer of wood pellets since 2018. The US Southeast is at the center of that supply chain: 28 large mills, 13.5 million GST of production capacity, rail spurs, export terminals, and bulk carriers, built almost entirely around UK demand.
However, the UK's new low-carbon Contracts for Difference (CfD) framework caps biomass power generators at a 27% annual capacity factor starting April 2027, down from roughly 64% today. When run hours fall by half, pellet demand follows. Existing subsidies expire in the first quarter of 2027, and the new CfD runs only to March 2031 with no commitment beyond that. Plant closures in Arkansas and Washington state, along with reduced output in Canada, are already early signals of supply chain contraction.
The Math of Who Gets Squeezed
The math is stark. By the second quarter of 2027, total annual UK pellet demand drops to 4.9 million GST. Of that:
- Approximately 2.3 million GST goes to captive, integrated UK supply chains.
- Approximately 1.0 million GST goes to Baltic suppliers, whose shipping times of one week or less become a decisive advantage as UK plants shift from baseload to dispatchable operation.
That leaves US producers competing for only 1.6 million GST. If Baltic suppliers capture more, US wood pellet exports to the UK could be effectively eliminated by 2031.
Sustainability qualification is also tightening. The new CfD cuts the supply-chain emissions ceiling from 55.6 grams of carbon dioxide equivalent per megajoule (gCO₂e/MJ) to 36.6 gCO₂e/MJ. The framework assesses compliance mill by mill, not on a portfolio average. A cleaner mill cannot carry a dirtier sibling through the door.
The producers who understand this math now have roughly 18 months to position themselves for what comes next.
From Stranded Supply to New Markets
The US Southeast's wood basket is robust: abundant inventory, strong growth-to-removal ratios, and more available residues than ever. The infrastructure is in place. The question is whether the next generation of markets can be developed quickly enough to redeploy this supply before the infrastructure sits idle.
Four pathways stand out as the strongest options for redeploying US pellet supply: BECCS for data centers, low-carbon steel, SAF, and domestic cofiring. We have rigorously assessed the logistics economics, sustainability cases, and project development for each.
BECCS for Data Centers: The Strongest Structural Fit
BECCS as a power source for data centers is the most compelling match for the situation pellet producers now face. The timing, feedstock requirements, and buyer characteristics align closely in a way that few other emerging markets can match.
Hyperscalers, the large data center operators driving an unprecedented surge in electricity demand, are signing deals for nuclear, geothermal, and small modular reactors alongside natural gas and renewables. They are doing this because annual Renewable Energy Certificates (RECs) are no longer sufficient to compensate for their scope 2 emissions, and they need clean, firm generation that can be matched to load on an hourly basis.
BECCS delivers exactly that. The Louisiana Green Fuels project—advanced by Strategic Biofuels and Relae (formerly Carbon Direct)—illustrates the model: regionally sourced forestry residues and sawmill waste generate 75 megawatts (MW) of firm electricity while sequestering over one million tonnes of CO₂ annually in deep saline formations. An ample supply of wood pellets creates a strategic opportunity for similar projects to move forward with certainty around feedstock processing, logistics, and costs.
The remaining commercial barrier is deal structure, not technology. No data center operator has yet signed an agreement to purchase both the electricity and carbon removal credits from a single BECCS plant. As scope 2 accounting tightens and domestic pellet supply becomes more readily available post-2027, the conditions for structuring the first such deal are improving fast.
"Pellet mills and data center developers have complementary problems: mills need offtakers, and data centers need local, dispatchable, clean power they can match to load on an hour-by-hour basis. BECCS is one of the few technologies that could solve both at once, and hyperscalers have shown they are willing to back early-stage clean firm power when the asset makes sense."
—Douglas Bryan, Senior Power and Energy Systems Modeler
Low-Carbon Steel: Certification Frameworks Are Arriving
Wood-derived biocarbon has a long-established niche in steelmaking. Brazil produces roughly 10% of its steel and 30% of its pig iron using charcoal from managed eucalyptus plantations—a proof of concept for biomass as a metallurgical input, if not a direct template for US producers. The plantations measurably lowered groundwater in producer regions of Minas Gerais, and charcoal's mechanical weakness relative to fossil coke has limited the model's reach beyond Brazil.
Current pilot projects use biomass in two roles. As a fuel, industrial trials have demonstrated 10% bio-coal co-injection without operational disruption, with reviews estimating that full replacement could cut blast-furnace CO₂ by around 27% per tonne of hot metal. As a reductant, biocoke is already being demonstrated at Outokumpu's pelletizing plant in Tornio, Finland. ArcelorMittal in Belgium and Tata Steel in India are running biomass pilots at tens of thousands of tonnes per year.
What makes this market worth serious attention now is the certification landscape. The Low Emission Steel Standard issued its first certifications in September 2025. The Global Steel Climate Council's Steel Climate Standard is under stakeholder review. In May 2025, Relae and Microsoft published Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors. These frameworks allow producers to internalize carbon price and environmental attribute certificate (EAC) values, closing the cost gap against fossil coke that has historically constrained biocarbon demand.
Relae worked with Eramet, a global metals company pursuing biogenic materials as a substitute for fossil coke at its Norwegian smelters, to assess high-quality carbon dioxide removal methodologies and chart a path to generating and selling carbon credits from their decarbonization projects. Producers who align their sustainability credentials to these emerging standards now will be better positioned for offtake as commercial-scale demand grows.
"Steelmaker pilots and the first low-carbon steel certifications are opening green-steel offtake to wood pellets, though commercial-scale demand remains limited. The producers that thrive in this market will be those that reliably deliver pellets aligned with high-quality sustainability standards."
—Louisa Brotherson, Hybrid Decarbonization Scientist
Sustainable Aviation Fuel: Mandates Create a Durable Demand Signal
Wood-based SAF is technically feasible via gasification to syngas, followed by Fischer-Tropsch upgrading, a proven chemistry for converting syngas to liquid hydrocarbons. Yet, the commercial challenges are substantial: the International Civil Aviation Organization estimates capital costs exceeding US$1 billion for large facilities, and production costs of US$11–48 per gallon to distillate.
The cautionary case is Fulcrum Bioenergy near Reno, Nevada, which attempted a Fischer-Tropsch process using municipal solid waste and appears to have failed due to a lack of rigorous pre-implementation testing and unrealistic timelines, a reminder that feedstock homogeneity matters enormously, and one area where pellets have a relative advantage.
Two structural dynamics make SAF worth serious attention despite those barriers. First, the European Union's (EU) SAF mandate, starting at 2% of jet fuel supply and ramping to 70% by 2050, carves out cellulosic biomass as the only qualifying feedstock once cooking oil supply is exhausted. The penalty structure in both the EU and UK creates strong demand regardless of SAF price: EU non-compliance penalties run roughly three times the price of SAF, and UK penalties can reach 13 times the cost of the fuel itself. Second, the alcohol-to-jet pathway offers a lower-capital entry point than Fischer-Tropsch, as demonstrated by Project Speedbird, a British Airways and LanzaJet collaboration targeting UK woody residues.
The near-term question is which routes have bankable offtake. Very few do yet, but the mandate structure suggests that window will shift rapidly.
"So far, facilities haven't scaled to the levels required to meet timeline demand. But the EU and UK mandate structures mean buyers are greatly incentivized to purchase SAF even at high prices, rather than pay non-compliance penalties."
—John Dees, Director, Fuels and Industrial Commodities
Domestic Cofiring: Achievable, but Not a Long-Term Anchor
Cofiring biomass with coal to produce electricity or heat is the most immediately achievable option. Most US coal-fired power plants could displace up to 10% of their input energy with raw or torrefied pellets, though plants would likely need fuel handling upgrades. Some state policies, such as Pennsylvania's Alternative Energy Portfolio Standards Act of 2004, support cofiring to meet renewable energy goals. However, there are no federal policies in the US that incentivize cofiring.
The case for cofiring as a long-term market is weak. The US coal fleet has contracted steadily for economic reasons—over 100 gigawatts (GW) of coal-fired capacity retired between 2015 and 2025—and biomass cofiring is unlikely to make a coal plant more cost-competitive. The Greenhouse Gas Protocol's scope 2 guidance does not permit buyers to procure a "strip" of electricity representing the biomass-fired fraction of output from a cofired plant; instead, buyers must accept the average total emissions from the plant in their scope 2 inventory, which limits the value proposition for corporate buyers seeking to demonstrate clean energy procurement.
The more interesting version of this pathway combines cofiring with carbon capture and storage (CCS), a combination that creates a deeper-abatement value proposition and the kind of firm, dispatchable power that corporate buyers increasingly need.
"Cofiring is a proven step toward modest emissions reductions from coal-fired electricity, but it's hard to make the economic case for it when compared to applications that command price premiums for deeper climate abatement."
—A.J. Simon, Director of Industrial Decarbonization
Sustainability Is Now the Qualification Gate
Each of these markets is more discerning about sustainable biomass sourcing than the UK power sector was a decade ago. That shift will not reverse.
US Southeast wood has real potential for high-integrity sustainability credentials, particularly in softwood residues. But it also carries downside risks when sourcing from natural stands. Through work with producers, buyers, and project developers across these markets, we have found that four questions now drive every serious procurement conversation:
- Does the supply chain have verifiable governance and chain-of-custody transparency?
- Does sourcing respect the rights of Indigenous Peoples and local communities?
- Is the wood coming from regions where forest carbon stocks are stable or growing, and not from protected areas or primary forest?
- Is sourced biomass a by-product of non-energy uses, and not the primary silviculture driver?
Producers who can answer yes to all four, and support those answers with data, are more likely to access these emerging markets. Those who cannot will find it harder to compete for offtake.
For a detailed framework on how these principles translate into contract language and certification requirements, see the 2025 Sustainable Forest Biomass Sourcing for CDR: A Buyer's Guide.
The Window Is Open, but Not Indefinitely
The US Southeast wood basket is well-positioned for the markets described here. The infrastructure is in place. What producers still need to build is the market positioning, sustainability documentation, and offtake relationships to go with it.
The producers who move now will have a meaningful head start. Those who wait for certainty may find that the most attractive offtake opportunities have already been structured around someone else's supply.
Learn more about Relae's work on SAF mandates, steel decarbonization, and sustainable biomass sourcing.
Frequently Asked Questions
What happens to US wood pellet exports when the UK's new biomass rules take effect?
Starting April 2027, the UK's signed Contracts for Difference agreement caps subsidized biomass generation at a 27% capacity factor, roughly half of today's levels. That's expected to cut total UK pellet demand to about 4.9 million GST a year, leaving only around 1.6 million GST available to US exporters.
Is BECCS for data centers a proven market, or still emerging?
The underlying technology is credible, and the Louisiana Green Fuels project already demonstrates it at commercial scale. However, the deal structure isn't yet proven. No hyperscaler has signed a single contract for both electricity and carbon removal credits from one BECCS plant, so this market is emerging rather than established.
How does low-carbon steel demand compare to sustainable aviation fuel as a market for pellet producers?
Steel offers nearer-term certification frameworks (the Low Emission Steel Standard began issuing certifications in 2025) but limited commercial-scale volume so far. SAF has a stronger long-run demand signal thanks to EU and UK blending mandates and steep non-compliance penalties, but requires far higher capital investment to enter.
What should a wood pellet producer look for when evaluating a new market?
The four sourcing questions that now gate access across all these markets are: verifiable chain-of-custody, respect for Indigenous and local community rights, sourcing from stable or growing forest carbon stocks (not primary forest), and biomass that's a by-product of non-energy uses rather than the primary driver of harvest.
SBTi Emphasizes Near-Term Carbon Removal in Revised Corporate Standard Draft
Key Takeaways
- Near-term role for carbon removals: The revised Science-Based Targets Initiative (SBTi) Corporate Net Zero Standard (CNZS) v2.0 proposes requiring or recognizing interim carbon dioxide removal (CDR) targets before companies reach net zero. This shift aims to scale up the CDR industry in line with climate science and ensure companies address residual emissions earlier rather than deferring action until their net-zero target year.
- Revised target frameworks and increased accountability: The draft standard introduces key changes, including separate targets for scope 1 and 2 emissions, enhanced scope 3 target-setting guidelines, and the recognition of market-based mechanisms for indirect mitigation of scope 3 emissions. It also requires companies to publicly disclose transition plans and assess implementation progress against targets.
- Potential for stronger action on removals: While the proposed updates are a step forward, the final standard should make near-term CDR targets mandatory rather than optional and should expand to include those for projected scope 3 residual emissions, not just scope 1. Without these stronger mandates, demand for early-stage CDR investments may remain limited, potentially slowing progress toward net-zero goals.
- Companies should prepare now: Businesses should start integrating CDR into their climate strategies now so they are equipped to navigate procurement of high-quality removal credits in the voluntary carbon market. Preparing ahead of the final CNZS v2.0 release will help companies align with science-based decarbonization pathways and demonstrate climate leadership.
What the Latest SBTi Update Means for Corporate Climate Action
On 18 March, 2025, the Science Based Targets Initiative (SBTi) released its draft Corporate Net Zero Standard (CNZS) v2.0, significantly updating its framework for corporate net-zero target setting for the first time since 2021. The draft proposes new approaches for companies to support carbon dioxide removal (CDR) in the transition to net-zero emissions, a move that could help scale the nascent CDR industry.
This release is part of a broader revision, with key proposed updates including:
- Requiring public disclosure of transition plans after companies set targets.
- Separating targets for scope 1 and 2 emissions.
- Enhancing the scope 3 target-setting framework using an impact-based prioritization process.
- Recognizing indirect mitigation (e.g., book-and-claim commodity certificates) for hard-to-trace scope 3 emissions.
- Defining a role for emissions removals in the transition to net zero.
- Providing options to recognize company leadership in beyond value chain mitigation (BVCM).
- Assessing corporate progress against targets to bolster accountability.
While formal recognition of removals in the transition to net zero is a positive step, stronger incentives will be needed in the final CNZS to ensure companies take meaningful early action on CDR. The draft standard is open for the first of two public consultations until 1 June, 2025, with a finalized version expected to launch in 2026.
What Remains the Same From the Current Standard?
SBTi’s framework remains focused on three core requirements for companies:
- Reducing emissions year-on-year to reach an approved science-based target (SBT) by 2050 or earlier.
- Investing in beyond value chain mitigation (BVCM) in the transition to net zero to support near-term global decarbonization efforts.
- Neutralizing remaining emissions from the net-zero year (achieved after at least 90% emissions reductions) and onwards with high-quality, permanent carbon removal.
Carbon credits representing emissions reductions and removals remain ineligible for meeting reduction targets within a company’s value chain (SBTs).
What’s New in CNZS v2.0 for Carbon Removals?
Until now, the SBTi encouraged companies to invest in CDR through mechanisms such as BVCM, but has not proposed requiring removal before their target net-zero year. As a result, organizations had little clarity or incentive to invest in CDR ahead of their net-zero target date, dampening near-term demand for carbon removal and delaying the industry's growth.
The new draft changes this by proposing three options for the V2.0 Standard that address the impact of residual emissions during the transition to net zero:
- Option 1 (requirement): Companies are required to set near- and long-term removal targets, including interim CDR milestones,¹ to address projected residual emissions.
- Option 2 (optional with recognition): Companies can set and receive recognition for removal targets to address projected residual emissions.
- Option 3 (flexibility of mechanism): Companies have the flexibility to address expected residual emissions either entirely through additional emissions reductions within their value chain, entirely through removals, or via a combination of both.
Notably, all three approaches apply only to residual scope 1 emissions.
On top of these approaches, SBTi has suggested two options for the minimum durability threshold of CDR purchases in their draft standard. Removals will either need to follow a ‘like for like’ approach,² where CDR storage must match the atmospheric lifetime of residual emissions, or a gradual transition approach, where carbon storage durability increases over time.
Why Mandating CDR Matters
Mandating near-term CDR reinforces the need for immediate climate action, ensuring that carbon removals complement emissions reductions rather than being deferred until the net-zero target year. The urgency of early CDR investment is clear:
- Limiting global warming to well below 2°C above pre-industrial levels requires removing billions of tonnes (gigatonnes) of carbon dioxide annually by mid-century.
- The CDR industry is in its early stages and requires sustained investment today to scale in time.
- If companies wait until their net-zero year to purchase CDR, the supply of high-quality removal credits is unlikely to be sufficient.
As part of the proposed removal targets in Option 1 (above), the CNZS v2.0 would require companies to gradually increase CDR purchases over time, ramping up to 100% of a company’s projected residual scope 1 emissions in the net-zero target year (<10% of baseline year emissions).³
What More Can Be Done?
The potential introduction of required removal targets would be a significant and welcomed step, reinforcing the importance of near-term CDR investment to support industry maturation and climate goals. However, mandatory near-term CDR targets represent only one of three potential pathways for the V2.0 standard. Moreover, neutralization of residual emissions on the path to net zero is only proposed for scope 1 emissions. While the SBTi provides clear rationale for this,⁴ SBTi should not let the complexity of projecting scope 3 emissions be a barrier to climate change mitigation. Scope 3 emissions represent the majority of emissions from SBTi-aligned companies. Furthermore, companies with high scope 3 emissions typically have a higher ability to pay compared to their industrial counterparts with high scope 1 emissions.
If interim removal targets are made optional, and scope 3 emissions remain excluded, the demand signal for near-term CDR will be limited. The public consultation (and advice of Expert Working Groups that SBTi is convening) will be essential in determining which proposed guidance matures into the final standard; consultation feedback can be provided here prior to June 1, 2025.
How Businesses Can Prepare for CNZS v2.0
Companies aligning with SBTi’s evolving guidance should begin to integrate CDR into their climate strategy now. This means:
- Understanding their residual emissions forecast and planning early investments.
- Developing a company-specific climate strategy to incorporate CDR into their sustainability roadmaps in tandem with plans to reduce value-chain emissions.
- Engaging early in the voluntary carbon market to implement these strategies and develop procurement processes to support high-quality removal projects.
- Ensuring credibility by selecting removal projects aligned with scientific best practices.
Conclusion: A Step in the Right Direction, But More Certainty Is Needed
The CNZS v2.0 draft represents a critical turning point for corporate climate action with options to formalize the role of early CDR investment through interim removal targets for signatories. However, SBTi must take a stronger stance in the final version of the revised standard by choosing to adopt requirements for near-term neutralization (rather than leaving this optional), including projected residual scope 3 emissions in near-term CDR targets, aligning durability requirements with climate science, and defining removal quality standards to ensure these efforts drive meaningful climate impact. Organizations seeking to align with this guidance should prepare by developing a comprehensive climate strategy that accounts for science-based decarbonization pathways and recognizes the role of early-stage investment in CDR solutions.
GHG Protocol Releases New Land Sector and Removals Standard
Key Takeaways
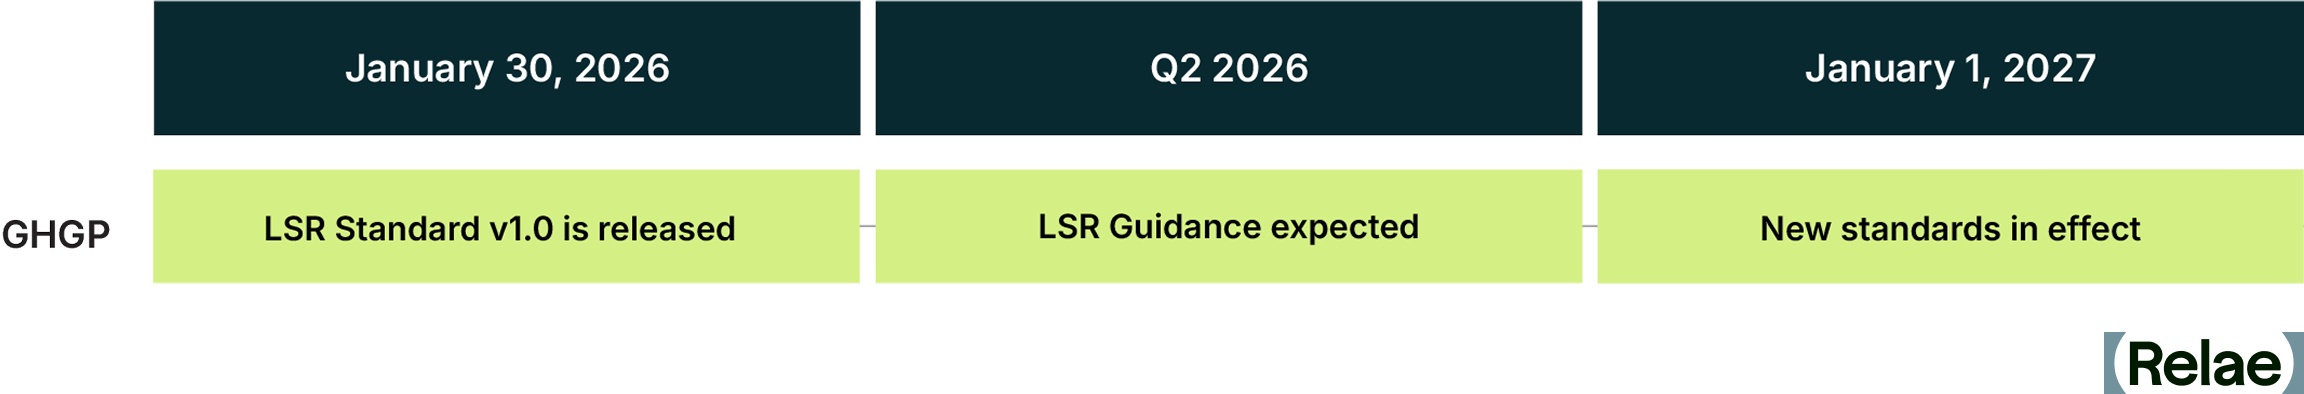
- On January 30, 2026, the Greenhouse Gas Protocol (GHG Protocol) released its long-awaited Land Sector and Removals (LSR) Standard v1.0 following a 5-year consultation process. The LSR Standard is set to take effect on January 1, 2027.
- The release of the LSR Standard represents a notable development for companies in the food and agriculture sector looking to report on land-based GHG emissions in their annual GHG inventory, as well as companies that plan to report on carbon dioxide removals (both land-based and technological).
- The accompanying Land Sector and Removals Guidance, which will provide further direction on operationalizing and implementing the LSR Standard, is expected in Q2 of 2026. However, companies with significant land-based activities may want to begin assessing the impacts of the LSR Standard on their emissions accounting procedures and decarbonization strategies today.
Why the Land Sector and Removals Standard Matters Now
Emissions from agriculture and land use change account for roughly a quarter of global emissions. Yet, for years, food, fiber, and fuel companies have lacked a clear framework for accounting and reporting on GHG emissions and carbon dioxide removals from land use. This has significantly limited their ability to demonstrate progress toward climate targets within their operations and value chain. The GHG Protocol’s Land Sector and Removals (LSR) Standard, which was released on January 30, 2026, changes that, and in doing so raises a new set of questions.
The LSR Standard provides greater clarity on what is required of companies to transparently track and report against their emissions reduction and removal targets, and opens new pathways to report on supply chain decarbonization interventions. It also represents an important advancement for companies seeking to report on carbon dioxide removals within their emissions inventory, including both land management removals and technological removals with geologic storage.
While the LSR Standard contains notable new requirements compared to the draft released in 2022, companies still face a number of open questions related to implementation and the implications for their decarbonization strategies.
The GHG Protocol’s accompanying Land Sector and Removals Guidance, scheduled for Q2 2026, is expected to offer more practical direction for implementing the LSR Standard. However, companies with significant land-based activities that require sufficient lead time to prepare should consider assessing the impacts today.
Below, we provide an overview of the LSR Standard, key changes from the 2022 draft, and actionable next steps for food, fiber, and fuel companies considering the impacts on their target-setting and emissions reporting.
What Is the Land Sector and Removals Standard?
The LSR Standard, taking effect on January 1, 2027, sets requirements and recommendations for corporate GHG accounting that cover emissions and carbon removals from agricultural and land use activities. It builds on existing GHG Protocol standards for corporate carbon accounting. Notably, the LSR Standard does not cover the forestry sector, a key break from the 2022 draft. Forest carbon accounting guidance remains under development and will be the subject of a stakeholder consultation/request for information process expected later in 2026.
Land Sector and Removals Standard vs Land Sector and Removals Guidance
The LSR Standard establishes the core requirements companies must follow, while the accompanying Land Sector and Removals Guidance, expected in Q2 of 2026, will provide more detailed implementation support. In short, the LSR Standard sets the "what" while the Land Sector and Removals Guidance will explain the "how," helping companies put those requirements into practice.
Who Should Be Using the Land Sector and Removals Standard?
The LSR Standard applies to two groups of companies:
- Any company with significant1 land-sector activities within its own operations or value chain (most notably the food, feed, fiber, biofuel, and advanced biomaterials sector).
- Any company looking to report on carbon dioxide removals within their scope 1 and scope 3 inventories (including both land management removals or technological removals).
Land management carbon dioxide removals include those from carbon sequestration through farming practices, agroforestry, or silvopastural systems on productive agricultural land. Technological carbon dioxide removals, by contrast, refer to more engineered approaches such as direct air carbon capture and storage (DACCS) or bioenergy carbon capture and storage (BECCS).
What Changed From the 2022 Draft?
Among other provisions, the LSR Standard contains notable breaks from the 2022 draft, including specific changes related to traceability, carbon dioxide removals, leakage, and land use change.
Traceability: A New Approach
Under the LSR Standard, companies that account for scope 3 emissions, removals, and other metrics must apply a spatial boundary. This boundary is determined by the level of traceability they can establish to known lands or regions (from least to most granular): global, jurisdictional (e.g., country), sourcing region (e.g., supply shed), land management unit (LMU) (e.g., farm), or harvested area. For more granular spatial boundaries, such as sourcing region and LMU, companies are required to establish physical traceability, which can be demonstrated through various chain of custody models.
The LSR Standard defines sourcing regions as predefined, spatially-explicit land areas that supply a raw material to its first point of aggregation or first processing facility in the value chain. The GHG Protocol allows some flexibility in how these boundaries are drawn. They can be defined at a tier of the value chain that includes multiple first points of aggregation or first processing facilities whose supply areas overlap.
Alongside higher integrity chain of custody models such as identity preserved, segregated, and controlled blending, the LSR Standard opens to mass balance as a chain of custody model that can be used to demonstrate physical traceability at the sourcing region-level with appropriate safeguards.
This is notable because mass balance is the most common chain of custody model for large volume agricultural commodities, and physical traceability is required to report removals according to the LSR standard. While challenges for reporting removals at sourcing region spatial boundaries still exist, this change unlocks new opportunities to decarbonize commodities and report removals within non-segregated supply chains through insetting programs.
Carbon Dioxide Removals: Clarity on Spatial Boundaries
The draft LSR Standard introduces key principles for companies choosing to report land management carbon dioxide removals, including traceability, data quality, and permanence. Translating those principles into practice remains challenging given the dynamic nature of agricultural supply chains and limited farm-level traceability.
Among other requirements, the LSR Standard maintains that companies electing to report on removals must do so as a separate accounting category from emissions. They must also identify the specific lands where carbon is stored, and conduct ongoing storage monitoring to detect and report on reversals if and when they occur.
The LSR Standard does, however, resolve one of the more consequential open questions left by the 2022 draft: where companies are to draw the spatial boundary for reporting land management carbon dioxide removals. By formalizing and permitting traceability at the sourcing-region level (with appropriate safeguards), it offers a workable middle ground between farm-level precision and the broader supply chain realities that most food and agricultural companies face.
The LSR Standard also opens to using alternative approaches to traceability, such as impact traceability, which allows companies to trace removals back to the LMU through a pathway that is separate from the physical GHG inventory. This is notable as it provides companies with optionality for recognition of farm-level supply chain investments even when physical traceability cannot be established, and inventory recognition is therefore not feasible.
Land Use and Leakage: Stronger Requirements
Finally, the LSR Standard significantly strengthens land use and economic leakage requirements compared to the 2022 draft. While the draft gave companies flexibility to choose among land-tracking metrics, the LSR Standard mandates that all companies report land occupation for both scope 1 and scope 3 in hectares and quantify land carbon leakage whenever “high leakage risk activities”2 displace food or feed production. This includes companies developing crop-based biofuels and bio-based feedstocks.
Leakage must be quantified using the Carbon Opportunity Cost, a calculation aimed at capturing how much carbon could have been stored in the absence of land management activities.
What Should Companies Do Now?
For entities reporting in accordance with the GHG Protocol’s Corporate Standard and Scope 3 Standard, the new LSR Standard goes into effect on January 1, 2027. However, the GHG Protocol’s Land Sector and Removal Guidance is not set for publication until Q2 2026, leaving many open questions related to implementation amid a short data collection and reporting cycle
In the interim, companies may consider a continuous improvement approach, evolving and improving their internal measurement and reporting mechanisms to enable more granular accounting over time. Companies may also consider running analyses to assess the impact of new requirements on the design and cost of decarbonization strategies, with a specific focus on data collection and monitoring approaches.
Ultimately, while implementation of the LSR Standard may evolve over time, it need not delay action on value chain intervention. Companies that continue investing in supply chain decarbonization are building the data infrastructure, supplier relationships, and operational resilience that yield greater visibility into supply chain risk and drive long-term value, independent of reporting standards.
As the LSR Standard's requirements develop, companies that have already begun assessing their emissions footprint and strengthening supply chain traceability and data quality are likely to be better positioned to align their reporting procedures accordingly.