The 2026 Criteria: Designing and Delivering High-Quality Carbon Removal
Key Takeaways
- High-quality carbon dioxide removal (CDR) projects require robust project management and oversight to deliver credits on time and at the promised volume; delivery risk is a distinct concern that quality standards alone don't catch.
- The sixth edition of the Criteria for High-Quality Carbon Dioxide Removal is the first to provide an approach to evaluating both credit quality and delivery risk, adding a new delivery risk appendix built around the TECOP framework: technical, economic, commercial, organizational, and political risk.
- The 2026 Criteria provides a framework for developers, investors, and buyers to evaluate both project quality and delivery risk.
- This year's update draws on 170 new diligence reports from 2025 and the input of more than 60 subject matter experts, building on a foundation of six years of lessons from professional diligence across hundreds of real-world CDR projects.
The Criteria Create a Shared Standard for Credit Quality
Relae (formerly Carbon Direct) first launched the Criteria for High-Quality Carbon Dioxide Removal (the Criteria) in collaboration with Microsoft in 2021 to help rapidly and justly scale the development of high-quality carbon dioxide removal (CDR) credits. The market didn't yet have a shared definition of what "high-quality" meant, so we laid out transparent, science-based benchmarks that gave developers, investors, and buyers a common foundation to work from. Every year since, we have gone back and sharpened those benchmarks so that they keep pace with the quickly evolving industry.
But a shared definition of quality doesn't guarantee the delivery of credits as planned. The 2026 edition is the first to tackle that gap directly, pairing the Criteria's quality benchmarks with a new framework for evaluating delivery risk.
The Six Principles of High-Quality Carbon Removal
The Criteria defines six science-based principles that apply across engineered, hybrid, and nature-based CDR approaches:
- Social harms, benefits, and environmental justice: The extent to which the project prevents new social harms to people and communities, reduces existing harms, and provides meaningful benefits distribution.
- Environmental harms and benefits: The extent to which the project minimizes and mitigates environmental harms, as well as provides environmental benefits.
- Additionality and baselines: The evidence that the project’s carbon removal would not have occurred without carbon finance.
- Measurement, monitoring, reporting, and verification (MMRV): The ability to accurately quantify carbon removal in a repeatable and verifiable way, and to develop a plan for long-term monitoring of the project.
- Durability: The likelihood that removed carbon remains stored over time, with mechanisms in place to mitigate reversal risk.
- Leakage: The extent to which project activities cause increased emissions elsewhere.
These principles provide a consistent foundation for carbon removal procurement, evaluation, and project benchmarking.
[cta]
Supporting the Delivery of High-Quality CDR Credits
"Projects must work better operationally and be more commercial. Quality and delivery risk shape a project's risk profile at every point in its life, and this edition of the Criteria is the first to give buyers a way to judge both at once." Dr. Julio Friedmann, Chief Scientist, Relae
Designing projects to meet high-quality CDR criteria is only part of the challenge. Effective project planning, management, and execution are also essential to ensure that high-quality CDR tonnes successfully reach the market as planned. As discussed in CDR 2.0: Five Pillars of Successful Project Deployment and Delivery, managing delivery risk requires developers, investors, and buyers to understand the risks that can affect project success and align on how these risks are assessed and mitigated.
To support this alignment, the 2026 Criteria introduced a new Delivery Risk Appendix, which establishes a common framework and language for identifying and evaluating key delivery risks for the first time. Drawing on our broader observations of the carbon removal market and established approaches to project risk management, the appendix highlights common delivery risks across two broad CDR project types: open systems and closed systems. It organizes these risks into five categories: technical, economic, commercial, organizational, and political factors, also known as the TECOP framework.
The TECOP Framework for CDR Delivery Risk
- Technical delivery risks are associated with the technical feasibility of the project design, implementation, and long-term operation of the project
- Economic delivery risks are associated with the project’s financing structure, financial modeling assumptions, and expenditure profile
- Commercial delivery risk reflects the extent to which a project's purchase agreements, supply arrangements, and key contractual relationships are secured or well-advanced.
- Organizational delivery risks center on the project developer's capacity and capability to successfully plan, execute, and manage a project of the appropriate size and complexity.
- Political delivery risks are associated with governance, policies, and potential changes in regulatory environments, as well as the local communities’ perception of and willingness to participate in projects.
New Additions to the 2026 Criteria
Since publishing the 2025 Criteria, Relae has conducted an additional 170 diligence reports across established and emerging CDR pathways, ranging from reforestation and enhanced rock weathering (ERW) to direct air capture (DAC). To date, less than 10% of all 900+ projects the team has reviewed have met the bar for high-quality. These diligence efforts, together with insights from market analysis and ongoing synthesis of the latest scientific and technical literature, have deepened our understanding of how CDR project quality has evolved over the past year.
The 2026 Criteria leverage these insights and the expertise of more than 60 subject matter experts to reflect advances across the CDR industry and address key weaknesses that remain in the market across all pathways.
A few of the most significant updates to the Criteria include:
Addition of Direct Counterparty Considerations: Direct counterparties are the organizations that developers partner with, and are structurally dependent on, to generate credits. This can include:
- Primary feedstock providers (e.g., mines, biomass providers, tree nurseries)
- Major implementing partners (e.g., local implementation partners, base facilities, transportation and storage providers, major product offtakers)
- Land owners that make up a significant proportion of project land
To reflect the key role that direct counterparties play in high-quality credit generation, developers must conduct diligence and disclose on their direct counterparties to demonstrate that they are not causing social or environmental harm.
Increased Rigor for Enhanced Rock Weathering Projects: Over the past year, ERW’s presence in the CDR market has grown substantially, and so too has the market’s understanding of the corresponding scientific and technical rigor required to deliver high-quality tonnes. The 2026 Criteria raised the bar for how ERW projects:
- Measure and prove their carbon removal claims
- Mitigate risks related to potentially toxic elements (PTEs)
- Incorporate more sophisticated farmer protections and benefits
Projects now have to back up their numbers with multiple physical field measurements, not just computer models; and they must now track and account for every significant loss pathway, from plants taking up minerals to carbon escaping from rivers and oceans.
Use of Dynamic Baselines for ARR Projects: ARR projects are increasingly using dynamic baselines to provide a more accurate reflection of the counterfactual scenario (e.g., what would have happened in the absence of the project). This is reflected in the 2026 Criteria with a requirement that ARR projects, with the exception of agroforestry projects, use dynamic baselines with statistically matched controls.
What’s Next?
The 2026 Criteria create a clear, science-driven framework for both designing and delivering measurable, just, and durable carbon removal. However, the Criteria cannot ensure high-quality tonnes reach the market on its own; good criteria do not replace robust diligence. To put these criteria into practice, we encourage developers, standard-setting bodies, buyers, investors, and policymakers to consider how the Criteria can be used to inform their role in enabling the carbon market to deliver high-quality tonnes and to engage in deep diligence and ongoing monitoring over the life of a project.
This edition of the Criteria reflects what we have learned over the past year, but our work is not done. We will continue to update it so that it remains a living document that evolves with the science and the market. To do so effectively, it must be a collaborative effort; we welcome input from carbon market actors, academia, and communities.
Frequently Asked Questions
Who publishes the Criteria for High-Quality Carbon Dioxide Removal, and how often is it updated?
Relae (formerly Carbon Direct) first published the Criteria for High-Quality Carbon Dioxide Removal with Microsoft in 2021 and have updated it every year since. The 2026 edition reflects six years of lessons from real-world project diligence and advances in climate science.
What are the six principles of the Criteria for High-Quality Carbon Dioxide Removal?
The Criteria define six science-based principles that apply across all CDR pathways: social harms, benefits, and environmental justice; environmental harms and benefits; additionality and baselines; measurement, monitoring, reporting, and verification (MMRV); durability; and leakage.
What CDR pathways does the Criteria cover?
The Criteria include pathway-specific criteria across nine CDR pathways: afforestation, reforestation, and revegetation (ARR); mangrove forestation; improved forest management (IFM); soil carbon; enhanced rock weathering (ERW) in croplands; biomass carbon removal and storage (BiCRS); abiotic marine CDR; carbon mineralization; and direct air capture (DAC).
What is delivery risk in carbon removal?
Delivery risk is the likelihood that a project generates credits on the timeline and at the quantity committed to buyers. It's a distinct concern from credit quality: even a high-quality project can fail to deliver as planned because of technical, economic, commercial, organizational, or political risk, the five categories the Criteria's TECOP framework evaluates. The 2026 Criteria's new Delivery Risk Appendix gives developers, investors, and buyers a shared benchmark for identifying and managing these risks before they derail a project.
What's the relationship between carbon removal credit quality and delivery risk?
Credit quality and delivery risk are distinct but interrelated. A project that fails to deliver credits as planned reduces the availability of high-quality CDR tonnes in the market, and weaknesses in credit quality can themselves increase delivery risk by creating buyer uncertainty or limiting access to project financing. The 2026 Criteria provides a framework for evaluating both quality and delivery risk.
Carbon Removal
Relae helps carbon removal buyers, investors, suppliers, and project developers navigate a complex market shaped by evolving science, quality standards, delivery risk, and claims expectations. We combine carbon removal strategy, project-level diligence, and market intelligence informed by work with leading buyers and project developers to help you assess quality, build diversified portfolios, and scale high-integrity carbon removal.
Download the Criteria


Hannah Brigham
Hannah Brigham

Hannah has professional and academic experience doing work related to carbon accounting, climate-smart agriculture, and project management. At Relae, Hannah works across the Science Team to both manage reviews of CDR projects and develop tools and processes to further improve Relae’s assessment of high quality CDR.
Prior to joining Relae, Hannah worked as a sustainability consultant at ClimatePartner. There she supported clients from a range of sectors in calculating corporate and product carbon footprints with a focus on companies in the agriculture sector. Hannah also served as a Peace Corps Volunteer in Madagascar, working alongside local community members to implement regenerative agriculture and gardening practices.
What to Read Next
Direct Air Capture, Simply Explained
Key Takeaways
- Emissions cuts alone are not happening fast enough to meet global climate goals. Direct air capture (DAC) removes carbon dioxide (CO2) that is already in the atmosphere. It has become one of the fastest-growing carbon removal approaches even as it stays capital-intensive.
- DAC's core advantage is flexibility. Because the atmosphere fully mixes within about two weeks, a DAC facility can be sited almost anywhere with clean power and CO2 storage and still deliver the same climate benefit.
- DAC investment has grown to roughly US$2.2 billion across 37 specialized companies since 2021. Per-tonne costs (currently US$500–1,000 or more) remain the technology's central barrier to scale.
- US federal support for DAC is still unsettled. The US Department of Energy cut its regional DAC hub program from a planned US$3.5 billion to roughly US$1.2 billion between October 2025 and April 2026. This is a signal that deployment funding, not the underlying science, is DAC's biggest near-term risk.
What Is Direct Air Capture?
Direct air capture (DAC) works by sucking in air, filtering it to remove CO2 that has built up over time and still sits in the atmosphere. To be effective, DAC must draw a lot of air into separating equipment like filter banks or cooling towers. This is similar to the small-scale systems that have scrubbed CO2 from air in spacecraft and submarines for decades. From there, CO2 filtering typically involves a chemical process that binds the CO2 for release later. While the most commonly used chemical compounds in this process are liquid solvents or solid sorbents, other chemical, electrical, and physical processes could also work.
After the filtering process, the captured CO2 is usually stored in one of two ways. The most important is geological storage, which keeps CO2 out of the air and oceans indefinitely in deep geological formations (typically a mile down or more) and offers the clearest climate benefits. The second is storing the CO2 in products like concrete, which offers clearer commercial benefits. A new generation of mineralization projects is expanding this second pathway, turning captured CO2 into building materials rather than only storing it underground. In addition, CO2 can be recycled into fuels and chemicals, which prevents net-new CO2 from being released but does not count as a carbon removal solution since these materials are eventually used, releasing the captured CO2 back to the atmosphere.
The Advantages of Direct Air Capture
DAC has many advantages as a CO2 removal approach. First and foremost, it's scalable. In effect, there are no practical limits to our ability to scrub CO2 from the sky or store it in deep geological formations around the world. This means scaling can be fast and removals profound.
It's straightforward. The devices remove CO2 from the air, a meter measures it, and operators store and monitor that CO2. It's clearly additional (meaning it only happens with financial and human intervention), easily verified, and durable (stored for many hundreds of years or more), meeting the bar set by our own Criteria for High-Quality Carbon Dioxide Removal.
It has a small physical footprint. Typical DACe systems do the carbon removal work of trees with 1,000–2,000 times less space. This leaves more room for conservation, agriculture, rewilding, and other important work.
It can be done anywhere with low-carbon energy and CO2 storage options. Globally, our atmosphere mixes fully every two weeks, meaning that CO2 released in China or Australia arrives over the US (and vice versa) in this amount of time. Because of this, DAC facilities can be sited anywhere and still have a climate benefit—as long as there is sufficient clean energy available and options for CO2 storage or use are nearby. This reduces competition for land and provides opportunities for economic development in regions with the right resources.
Finally, and most critically, DAC is a backstop technology. While reducing emissions remains the top priority, there are certain types of emissions that are either very hard or very expensive to abate. The last fraction of hard-to-abate emissions can be managed through DAC, effectively capping global costs to reach net-zero emissions. In fact, the more rapidly DAC scales and deploys, the less total energy and cost are needed to achieve key climate goals.
Challenges and Concerns of Direct Air Capture
Like all climate mitigation approaches, DAC has challenges. The primary challenge today is cost. Today's large-scale systems cost roughly US$500–1,000 or more per tonne of CO2 removed, depending on the technology and site, though several developers are targeting US$100–150 per tonne over the next 10 years. Although the costs will come down over time through deployment and wider adoption, today's high costs are a barrier to investment and deployment.
Another challenge is around the energy requirements associated with DAC. Pulling one million tonnes per year of CO2 out of the air requires roughly 200–300 megawatts of zero-carbon energy (a combination of heat and electricity). Given the limited supply of zero-carbon energy available today, there is a valid question about whether this is the best use of that resource today.
Finally, there is the question of environmental risks and community burdens of DAC. Experience to date suggests that the total environmental burdens and consequences of this pathway are among the lowest of any clean energy and climate technology. But since DAC systems involve heavy equipment and chemicals, questions about the full environmental risks and burdens to communities remain, especially given its limited commercial deployment. Although most DAC systems will be sited in remote locations, not near communities, and pose no serious environmental risks, reasonable concerns must be addressed before permitting and building future DAC projects.
Why the Excitement Now?
Although current climate science and added urgency from organizations like the Intergovernmental Panel on Climate Change (IPCC) have driven interest in DAC, other important advances have fed broad interest and excitement about its potential. Since 2017, DAC technology has matured greatly, including the deployment and operation of many projects around the world. Costs have dropped, new pathways have opened, and private investment in DAC-specific companies has reached roughly US$2.2 billion across 37 companies since 2021.
Two large facilities illustrate where deployment stands today. Climeworks' Mammoth plant in Iceland has been operating since May 2024, although not at full capacity. Occidental's Stratos plant in Texas remains delayed past its most recent 2026 second quarter target due to a component issue, with no confirmed new startup date as of this writing. Both facilities carry substantial commercial offtake agreements from aviation, energy, insurance, and tech companies, agreements that continue to hold even as construction timelines have slipped.
In part, interest results from new policy advancements. In the US, the Inflation Reduction Act's 45Q tax credit, maintained under the 2025 One Big Beautiful Bill Act, currently provides US$180 per tonne for DAC paired with dedicated geologic storage, with added parity for utilized CO2. The Department of Energy's Regional Direct Air Capture Hubs program, originally planned at US$3.5 billion, was cut back sharply in an October 2025 review. It was then partially restored in April 2026 when the Department of Energy confirmed its two flagship projects, Project Cypress in Louisiana and the South Texas DAC Hub, would proceed. The program's total is now expected to be near US$1.2 billion. In addition, California has amended its Low-Carbon Fuel Standard to allow DAC as a compliance mechanism, and the US Department of Energy has explored a pilot program to purchase valid, durable carbon dioxide removal, including DAC. Recently, the Carbon Dioxide Removal Leadership Act was introduced to Congress, which would require the Secretary of Energy to remove CO2 directly from ambient air or seawater.
Other programs around the world reflect this growing interest. In the UK and EU, governments have promised CO2 removal purchases this decade, which will likely include DAC. Research programs have begun in Canada, the UK, Germany, Japan, and China. Developing nations increasingly see DAC as a potential new industry and hope to take advantage of their natural resources to expand energy access while being paid to remove CO2 from the air and oceans.
The Future of Direct Air Capture
I'm pleased to have played a small role in DAC's new prominence. I've had the good fortune of being at DAC project groundbreakings and ribbon cuttings, led the first-ever government grants program for DAC, worked with scientists to develop new DAC technologies, published analysis over a decade ago on the need for DAC, and testified before the US Congress on the benefits and needs of DAC on three separate occasions. Based on my experience in DAC over the last 16 years, I believe that smart investment, policy, deployment, and community engagement will convert the promise of DAC into thousands of projects. These projects will help avoid the worst outcomes of climate change and restore some natural balance to the world. With federal support now concentrated on fewer, better-resourced flagship projects, rather than spread across two dozen early-stage hubs, the DAC field is being pushed toward fewer high-profile delays and more repeatable, bankable deployments.
Frequently Asked Questions
How does direct air capture differ from capturing carbon at an industrial site?
Industrial, or point-source, capture removes CO2 at a smokestack, where concentrations are high. Direct air capture removes CO2 that is already spread throughout the open atmosphere. DAC facilities can operate almost anywhere with available clean power and storage, not only next to a specific emitter.
Is direct air capture actually operating today, or is it still experimental?
Direct air capture is operating today; it is not just experimental. Climeworks' Mammoth plant in Iceland has been running since May 2024, and dozens of smaller facilities are active worldwide. However, the largest US projects, including Occidental's Stratos plant in Texas, are still working through startup delays. Once it begins operating, DAC will be fully commercial, although limited in deployment.
How much does it cost to remove one tonne of CO2 with direct air capture?
Current large-scale direct air capture systems cost roughly US$500–1,000 or more per tonne of CO2 removed, depending on the technology and facility site. Several developers are targeting costs of US$100–150 per tonne later this decade, though that has not yet been demonstrated at commercial scale and is likely to take 10 years or more to achieve
Does using direct air capture reduce the need to cut emissions?
No. Direct air capture is a backstop for emissions that are difficult or costly to eliminate outright, not a substitute for cutting emissions in the first place. Reducing emissions remains a priority; DAC addresses both what is left over (residual emissions) and what’s already in the air and oceans.
Low-Carbon Fuels Under RED: Why Quality Can Differ and How Buyers Can Look Beyond the Certificate
Key Takeaways
- The EU Renewable Energy Directive (RED III) sets the sustainability rules behind clean fuel markets in Europe, and frameworks in the UK and US draw on it. Producers typically show compliance through certification schemes recognized by the European Commission, such as ISCC and RSB.
- Certification provides evidence that a fuel meets the regulatory minimum, but schemes apply RED differently, particularly on topics like social outcomes and leakage. As a result, two compliant fuels can differ in quality.
- Relae’s Criteria for High-Quality Low Carbon Fuels give buyers a single benchmark for assessing quality beyond compliance. By comparing a producer’s certificate against the criteria, buyers can identify gaps and develop contract provisions on quality areas the certificate does not cover, tailored to their own priorities. This can help buyers identify and manage quality risk and stay ahead of tighter regulations likely to come under RED IV.
RED Sets the Bar for Clean Fuels in Europe and Beyond
RED III is a key regulatory framework governing sustainability requirements for clean fuels. Its sustainability criteria underpin Europe’s clean fuels markets, including sustainable aviation fuel (SAF) under ReFuelEU Aviation, marine biofuels under FuelEU Maritime, and biomethane injected into Europe’s gas grid. Its reach extends beyond the EU, too. The UK Renewable Transport Fuel Obligation and SAF Mandate apply sustainability criteria modeled on RED, and the certification schemes built around RED will play a role in California’s new feedstock sustainability requirements under its Low Carbon Fuel Standard.
A Certificate Confirms Compliance, Not Quality
Low-carbon fuel producers typically demonstrate compliance with RED through voluntary certification schemes recognized by the European Commission, such as the International Sustainability & Carbon Certification (ISCC) and the Roundtable on Sustainable Biomaterials (RSB). A certificate provides evidence that a fuel clears the regulatory bar. Every recognized certification scheme covers RED’s core requirements, but each applies them differently, and some go further than others.
How Certification Schemes Can Differ
Certification schemes tend to differ most on questions RED only partly addresses. Social outcomes are one example. RED largely requires certified producers to comply with the laws of the country where the feedstock is grown or the fuel is produced. Following local law, however, is not the same as paying living wages, respecting land rights, or delivering benefits to nearby communities, especially where local protections are weaker than the EU’s. Some schemes fill that gap with their own social requirements; and others do less.
Leakage is another example. It refers to emissions a fuel causes outside its own supply chain, which its carbon intensity does not reflect. One common form is indirect land-use change (ILUC). When cropland or feedstock is redirected to fuel production, the food, feed, or other uses it previously supplied still need to be met elsewhere. That can push cropland expansion into forests or grasslands, releasing the carbon they store. RED manages this risk by limiting the use of feedstocks most associated with expansion into high-carbon-stock land. However, RED acknowledges that ILUC is not limited to these high-risk feedstocks, and diverting waste feedstocks from existing uses can have similar knock-on effects. Without asking specific questions about a given producer’s supply chain, buyers may have limited visibility into the leakage risk behind the fuel they buy.
These examples show that, on paper, two RED-compliant fuels can look the same while differing significantly in overall quality. One reason is that they can be certified under schemes with different requirements on issues such as social outcomes. Another is that RED is built to work at scale, applying a consistent set of rules across the whole market. That consistency is a strength, but it means that some issues, such as leakage, are addressed at the system level rather than for each individual fuel. For buyers, the certificate is a useful starting point for offtake conversations, but may not be enough on its own to judge the quality of what they are buying.
Assessing Quality Beyond Compliance
So how can a buyer tell whether one certified fuel is higher quality than another? Today, doing so means comparing certification schemes rule-by-rule, which is cumbersome. Relae’s Criteria for High-Quality Low Carbon Fuels provides a shared definition for what “better than compliant” means. It brings together requirements from RED, CORSIA, ISCC, RSB, national SAF mandates, and other frameworks into a single benchmark, and adds criteria on social outcomes, additionality, and leakage. We built the criteria for voluntary buyers, but they are just as useful for regulated companies that want to go beyond meeting their mandates and show how well they do it.
How Buyers Can Apply the Criteria, and How Relae Can Help
In practice, buyers can use Relae’s criteria in four steps. Each one calls for technical judgment on scheme rules, supply chains, and contract terms. Relae’s fuels team works alongside buyers at every stage, from the first certificate review to the final offtake terms.
- Start with the certificate. Confirm which scheme the fuel is certified under, what the certificate covers, and whether the producer holds any optional add-ons, such as a low ILUC risk certification. Our team reviews certificates and the scheme rules behind them to confirm what is and is not covered.
- Map the certificate against Relae’s quality criteria. Sort each criterion into what the certificate already covers, what it partly covers, and what it does not address. Our experts carry out this mapping for a specific fuel and pathway and highlight the gaps that matter most.
- Ask the producer to fill the gaps. Turn each gap into a direct question, for example, how the producer verifies wages and land rights in its supply chain, or how it manages ILUC risk. The answers help buyers see where quality risks may lie that compliance alone does not cover. We help prepare these questions and assess the producer’s responses and evidence.
- Build the answers into an offtake agreement. Use the answers to develop contract provisions on quality that the certification does not cover, such as additional verification, disclosure, or feedstock-sourcing requirements. These provisions help buyers manage quality risks over the life of the deal, whether it’s a SAF offtake agreement or another fuel supply contract, and support the sustainability claims they make about the fuel. Our fuels experts work with buyers and their counsel to shape these provisions.
Procuring for Where Standards Are Heading
The criteria are also a guide to what may come next. The European Commission is preparing its post-2030 renewable energy framework (RED IV). The Commission held a public consultation from March to June 2026, and plans to propose legislation by the end of the year. The final scope is not yet known, but industry submissions point to areas where bioenergy rules could tighten, such as stricter traceability and on-site audits for imported waste feedstocks. Buyers who procure against where standards are heading, not just today’s minimum, will be less exposed when the rules change and better able to back up the sustainability claims they make about their fuel.
[cta]
Frequently Asked Questions
What is RED III?
RED III is the current version of the EU Renewable Energy Directive. It sets renewable energy targets and the sustainability criteria that biofuels, biogas, and other renewable fuels must meet to count under EU regulations. Those criteria apply across Europe’s clean fuel markets, including SAF under ReFuelEU Aviation and marine fuels under FuelEU Maritime.
How do producers show their fuel complies with RED?
Most producers use a voluntary certification scheme recognized by the European Commission, such as ISCC or RSB. The scheme audits the producer and its supply chain against RED’s requirements and issues a certificate if they are met.
Are all RED-recognized certification schemes the same?
No. Every recognized scheme covers RED’s core requirements, but each applies them differently, and some add requirements or optional add-ons of their own. Certification schemes differ the most on issues RED only partly addresses, such as social outcomes and leakage. As a result, two RED-compliant fuels can differ in overall quality.
Who should use the Relae Criteria for High-Quality Low Carbon Fuels?
We designed the Criteria for High-Quality Low Carbon Fuels for voluntary buyers, but they are equally useful for regulated companies. Buyers can compare a producer’s certificate against the criteria to find gaps, raise those gaps in offtake discussions, and address them through contract provisions. Relae works with both voluntary and compliance buyers to apply the criteria to specific fuels and deals, from assessing producers to shaping offtake terms.
What is RED IV, and why does it matter for buyers today?
RED IV is the post-2030 renewable energy framework the European Commission is preparing. The Commission consulted on it from March to June 2026, and plans to propose legislation by the end of 2026. Sustainability rules for bioenergy could tighten. Buyers who procure against where standards are heading, rather than today’s minimum, will be less exposed when the rules change.
The Role of Improved Forest Management for Carbon Dioxide Removal
Key Takeaways
- Improved forest management (IFM) increases measurable long-term carbon storage in living trees and durable wood products.
- At the same time, it can provide strong social and ecological co-benefits.
- IFM projects like the ones developed by Weyerhaeuser and the Indigenous community of Petcacab in collaboration with Relae (formerly Carbon Direct) show how IFM practices can align climate goals with social and environmental benefits.
Forests Are Climate Solutions If We Manage Them Wisely
Forests remove carbon dioxide from the atmosphere, but they need to be thoughtfully managed to keep doing so. As buyers look to scale carbon removal, improved forest management (IFM) is gaining traction in the voluntary carbon market (VCM).
IFM focuses on enhancing how existing forests are managed to increase carbon storage over time. It’s a nature-based solution that supports climate outcomes, community livelihoods, and environmental benefits when done well.
This piece explains how IFM works, what makes a project high-quality, and how real-world IFM projects like those developed by Weyerhaeuser and Petcacab in collaboration with Relae (formerly Carbon Direct) are delivering credible results for buyers and local communities alike.
What Is Improved Forest Management?
Improved forest management is a catch-all phrase that describes management techniques that decrease emissions from forests or increase carbon removal and storage. Some management techniques, like transitioning a working forest to a conserved status, decrease emissions from forest harvest and primarily create credits for avoided emissions. Other management techniques, like harvesting forests less frequently, can lead to greater carbon removal and storage over time and create credits for additional carbon removal.
Examples of IFM Practices Include:
- Extending harvest rotations to allow more carbon accumulation
- Reducing the impact of logging on soil and surrounding trees
- Managing fire and pest risks to enhance forest health
- Transitioning some of a forest to conservation status
These strategies help forest carbon stocks grow beyond business-as-usual baselines. In carbon markets, IFM can generate carbon removal or avoided emissions credits, depending on the project's design and carbon accounting methodology.
What Makes a High-Quality IFM Carbon Removal Credit?
Buyers today face increased scrutiny around carbon credit quality. In this context, IFM projects must go beyond basic registry standards to demonstrate climate integrity and social and environmental benefits.
Relae developed the Criteria for High-Quality Carbon Dioxide Removal, an annual report published in collaboration with Microsoft to establish science-backed quality standards. This includes six core principles that define high-quality carbon removal, all of which apply to IFM projects:
- Social harms, benefits, and environmental justice - The extent to which the project prevents new social harms to people and communities, reduces existing harms, and provides meaningful benefits distribution. Since IFM projects take place in communities around the world, benefits will naturally vary from project to project.
- Environmental harms and benefits - The extent to which the project minimizes and mitigates environmental harms, as well as provides environmental benefits. Because IFM projects enhance management practices, environmental co-benefits of high-quality IFM projects are usually substantial.
- Additionality and baselines – Evidence that the project’s carbon removal would not have occurred without carbon finance. Many IFM projects fail to present compelling additionality data and narratives. High-quality projects will be able to identify the actions the project took to increase carbon storage that would not have happened without carbon finance.
- Measurement, monitoring, reporting, and verification (MMRV) – The ability to accurately quantify carbon removal in a repeatable and verifiable way, and to develop a plan for long-term monitoring of the project. IFM projects must have robust forest inventory, growth modeling, and occasional remeasurement to verify the additional carbon storage.
- Durability – The likelihood that removed carbon remains stored over time, with mechanisms in place to mitigate reversal risk. Enhanced management of fire, pests, and disease in IFM projects can enhance forest carbon durability.
- Leakage – Evaluation of whether project activities cause increased emissions elsewhere. If an IFM project substantially reduces timber supply, market demand can drive increased harvesting in other forests, undermining some of the project’s climate benefits. High-quality IFM projects minimize this risk by limiting harvest reductions, and account for any remaining leakage by issuing fewer credits.
Relae uses these criteria as part of our diligence framework when advising buyers evaluating projects and co-developing our own projects.
IFM Projects Delivering Real Impact
Weyerhaeuser: Applying Science at Scale
Weyerhaeuser, one of the largest forest owners in North America, is applying improved forest management practices across over 200,000 acres of working forests.
The IFM projects led by Weyerhaeuser are located in rural areas in the US, with low wildfire risk. These IFM projects sequester carbon by extending harvest rotations and forgoing harvest in established streamside management zones.
Relae supported Weyerhaeuser with hands-on scientific collaboration to confirm that every IFM project met the Criteria for High-Quality Carbon Dioxide Removal.
Why it matters to buyers:
- High-quality climate impact at large scale
- Transition of working forests from traditional management techniques to maximize climate impact
- Responsible forestry practices aligned with SFI® standards
- Rigorous carbon accounting and high-quality project baseline established using historical harvest records
The IFM projects led by Weyerhaeuser are some of the largest in the US today and a model for scaling science-backed forest carbon solutions.
Petcacab: Indigenous-Led Conservation in the Yucatán Peninsula
Located in the communal lands of Petcacab, Mexico, this IFM project is led by Indigenous Mayan ejidatarios—community members who have legal rights to manage the land.
Historically, forests in the ejido have been degraded through unsustainable harvesting and extensive damage from hurricanes. Through carbon finance, they are developing new forest management plans and sustainable forestry models, with revenue reinvested in health, education, and job creation.
“The rainforest for me represents my home, my work, my present, my future. We have a very daring challenge: to transform how we manage our forest, shifting from harvesting and selling timber to conserving it through the sale of carbon credits that support the development of our community.”
— Celso Chan Rivas, Carbon Project General Manager
What makes Petcacab stand out:
- Equitable benefit-sharing and strong Indigenous governance
- Critical habitat protection for endangered species
- Increased additional carbon storage through forest management and reduced land use conversion
- Transparent reporting and verified outcomes
Petcacab is recognized by Relae as a high-quality community IFM project in Mexico, with clear social, environmental, and climate outcomes.
Investing in Forests That Deliver More Than Carbon
Improved forest management is more than a carbon strategy, it’s an investment in ecosystems, communities, and long-term impact. For buyers seeking high-integrity carbon removal with social and environmental co-benefits, IFM projects offer a compelling opportunity.
IFM projects like the ones developed by Weyerhaeuser and Petcacab in collaboration with Relae show what’s possible when forests are managed with science and care. They also reflect what the voluntary carbon market needs more of: quality, transparency, and impact beyond the metric ton.
The 2026 Criteria: Designing and Delivering High-Quality Carbon Removal
Key Takeaways
- High-quality carbon dioxide removal (CDR) projects require robust project management and oversight to deliver credits on time and at the promised volume; delivery risk is a distinct concern that quality standards alone don't catch.
- The sixth edition of the Criteria for High-Quality Carbon Dioxide Removal is the first to provide an approach to evaluating both credit quality and delivery risk, adding a new delivery risk appendix built around the TECOP framework: technical, economic, commercial, organizational, and political risk.
- The 2026 Criteria provides a framework for developers, investors, and buyers to evaluate both project quality and delivery risk.
- This year's update draws on 170 new diligence reports from 2025 and the input of more than 60 subject matter experts, building on a foundation of six years of lessons from professional diligence across hundreds of real-world CDR projects.
The Criteria Create a Shared Standard for Credit Quality
Relae (formerly Carbon Direct) first launched the Criteria for High-Quality Carbon Dioxide Removal (the Criteria) in collaboration with Microsoft in 2021 to help rapidly and justly scale the development of high-quality carbon dioxide removal (CDR) credits. The market didn't yet have a shared definition of what "high-quality" meant, so we laid out transparent, science-based benchmarks that gave developers, investors, and buyers a common foundation to work from. Every year since, we have gone back and sharpened those benchmarks so that they keep pace with the quickly evolving industry.
But a shared definition of quality doesn't guarantee the delivery of credits as planned. The 2026 edition is the first to tackle that gap directly, pairing the Criteria's quality benchmarks with a new framework for evaluating delivery risk.
The Six Principles of High-Quality Carbon Removal
The Criteria defines six science-based principles that apply across engineered, hybrid, and nature-based CDR approaches:
- Social harms, benefits, and environmental justice: The extent to which the project prevents new social harms to people and communities, reduces existing harms, and provides meaningful benefits distribution.
- Environmental harms and benefits: The extent to which the project minimizes and mitigates environmental harms, as well as provides environmental benefits.
- Additionality and baselines: The evidence that the project’s carbon removal would not have occurred without carbon finance.
- Measurement, monitoring, reporting, and verification (MMRV): The ability to accurately quantify carbon removal in a repeatable and verifiable way, and to develop a plan for long-term monitoring of the project.
- Durability: The likelihood that removed carbon remains stored over time, with mechanisms in place to mitigate reversal risk.
- Leakage: The extent to which project activities cause increased emissions elsewhere.
These principles provide a consistent foundation for carbon removal procurement, evaluation, and project benchmarking.
[cta]
Supporting the Delivery of High-Quality CDR Credits
"Projects must work better operationally and be more commercial. Quality and delivery risk shape a project's risk profile at every point in its life, and this edition of the Criteria is the first to give buyers a way to judge both at once." Dr. Julio Friedmann, Chief Scientist, Relae
Designing projects to meet high-quality CDR criteria is only part of the challenge. Effective project planning, management, and execution are also essential to ensure that high-quality CDR tonnes successfully reach the market as planned. As discussed in CDR 2.0: Five Pillars of Successful Project Deployment and Delivery, managing delivery risk requires developers, investors, and buyers to understand the risks that can affect project success and align on how these risks are assessed and mitigated.
To support this alignment, the 2026 Criteria introduced a new Delivery Risk Appendix, which establishes a common framework and language for identifying and evaluating key delivery risks for the first time. Drawing on our broader observations of the carbon removal market and established approaches to project risk management, the appendix highlights common delivery risks across two broad CDR project types: open systems and closed systems. It organizes these risks into five categories: technical, economic, commercial, organizational, and political factors, also known as the TECOP framework.
The TECOP Framework for CDR Delivery Risk
- Technical delivery risks are associated with the technical feasibility of the project design, implementation, and long-term operation of the project
- Economic delivery risks are associated with the project’s financing structure, financial modeling assumptions, and expenditure profile
- Commercial delivery risk reflects the extent to which a project's purchase agreements, supply arrangements, and key contractual relationships are secured or well-advanced.
- Organizational delivery risks center on the project developer's capacity and capability to successfully plan, execute, and manage a project of the appropriate size and complexity.
- Political delivery risks are associated with governance, policies, and potential changes in regulatory environments, as well as the local communities’ perception of and willingness to participate in projects.
New Additions to the 2026 Criteria
Since publishing the 2025 Criteria, Relae has conducted an additional 170 diligence reports across established and emerging CDR pathways, ranging from reforestation and enhanced rock weathering (ERW) to direct air capture (DAC). To date, less than 10% of all 900+ projects the team has reviewed have met the bar for high-quality. These diligence efforts, together with insights from market analysis and ongoing synthesis of the latest scientific and technical literature, have deepened our understanding of how CDR project quality has evolved over the past year.
The 2026 Criteria leverage these insights and the expertise of more than 60 subject matter experts to reflect advances across the CDR industry and address key weaknesses that remain in the market across all pathways.
A few of the most significant updates to the Criteria include:
Addition of Direct Counterparty Considerations: Direct counterparties are the organizations that developers partner with, and are structurally dependent on, to generate credits. This can include:
- Primary feedstock providers (e.g., mines, biomass providers, tree nurseries)
- Major implementing partners (e.g., local implementation partners, base facilities, transportation and storage providers, major product offtakers)
- Land owners that make up a significant proportion of project land
To reflect the key role that direct counterparties play in high-quality credit generation, developers must conduct diligence and disclose on their direct counterparties to demonstrate that they are not causing social or environmental harm.
Increased Rigor for Enhanced Rock Weathering Projects: Over the past year, ERW’s presence in the CDR market has grown substantially, and so too has the market’s understanding of the corresponding scientific and technical rigor required to deliver high-quality tonnes. The 2026 Criteria raised the bar for how ERW projects:
- Measure and prove their carbon removal claims
- Mitigate risks related to potentially toxic elements (PTEs)
- Incorporate more sophisticated farmer protections and benefits
Projects now have to back up their numbers with multiple physical field measurements, not just computer models; and they must now track and account for every significant loss pathway, from plants taking up minerals to carbon escaping from rivers and oceans.
Use of Dynamic Baselines for ARR Projects: ARR projects are increasingly using dynamic baselines to provide a more accurate reflection of the counterfactual scenario (e.g., what would have happened in the absence of the project). This is reflected in the 2026 Criteria with a requirement that ARR projects, with the exception of agroforestry projects, use dynamic baselines with statistically matched controls.
What’s Next?
The 2026 Criteria create a clear, science-driven framework for both designing and delivering measurable, just, and durable carbon removal. However, the Criteria cannot ensure high-quality tonnes reach the market on its own; good criteria do not replace robust diligence. To put these criteria into practice, we encourage developers, standard-setting bodies, buyers, investors, and policymakers to consider how the Criteria can be used to inform their role in enabling the carbon market to deliver high-quality tonnes and to engage in deep diligence and ongoing monitoring over the life of a project.
This edition of the Criteria reflects what we have learned over the past year, but our work is not done. We will continue to update it so that it remains a living document that evolves with the science and the market. To do so effectively, it must be a collaborative effort; we welcome input from carbon market actors, academia, and communities.
Frequently Asked Questions
Who publishes the Criteria for High-Quality Carbon Dioxide Removal, and how often is it updated?
Relae (formerly Carbon Direct) first published the Criteria for High-Quality Carbon Dioxide Removal with Microsoft in 2021 and have updated it every year since. The 2026 edition reflects six years of lessons from real-world project diligence and advances in climate science.
What are the six principles of the Criteria for High-Quality Carbon Dioxide Removal?
The Criteria define six science-based principles that apply across all CDR pathways: social harms, benefits, and environmental justice; environmental harms and benefits; additionality and baselines; measurement, monitoring, reporting, and verification (MMRV); durability; and leakage.
What CDR pathways does the Criteria cover?
The Criteria include pathway-specific criteria across nine CDR pathways: afforestation, reforestation, and revegetation (ARR); mangrove forestation; improved forest management (IFM); soil carbon; enhanced rock weathering (ERW) in croplands; biomass carbon removal and storage (BiCRS); abiotic marine CDR; carbon mineralization; and direct air capture (DAC).
What is delivery risk in carbon removal?
Delivery risk is the likelihood that a project generates credits on the timeline and at the quantity committed to buyers. It's a distinct concern from credit quality: even a high-quality project can fail to deliver as planned because of technical, economic, commercial, organizational, or political risk, the five categories the Criteria's TECOP framework evaluates. The 2026 Criteria's new Delivery Risk Appendix gives developers, investors, and buyers a shared benchmark for identifying and managing these risks before they derail a project.
What's the relationship between carbon removal credit quality and delivery risk?
Credit quality and delivery risk are distinct but interrelated. A project that fails to deliver credits as planned reduces the availability of high-quality CDR tonnes in the market, and weaknesses in credit quality can themselves increase delivery risk by creating buyer uncertainty or limiting access to project financing. The 2026 Criteria provides a framework for evaluating both quality and delivery risk.
GHG Protocol Releases New Land Sector and Removals Standard
Key Takeaways
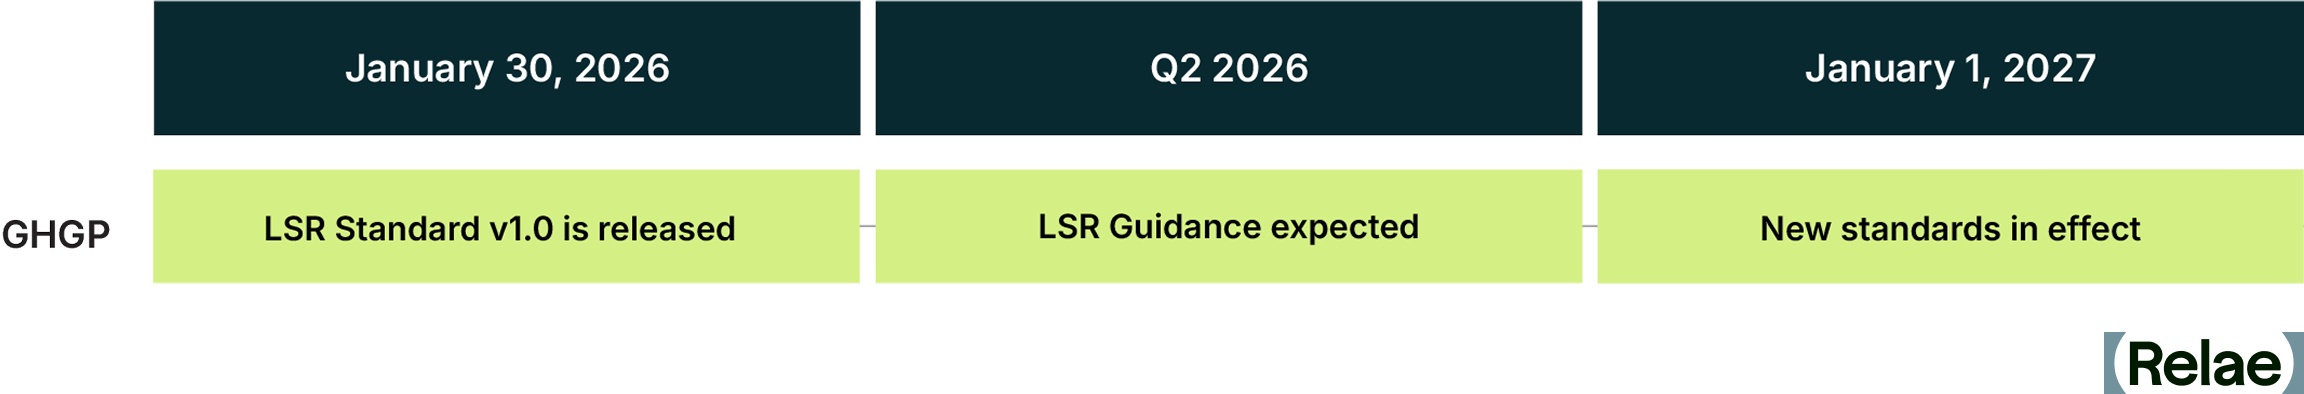
- On January 30, 2026, the Greenhouse Gas Protocol (GHG Protocol) released its long-awaited Land Sector and Removals (LSR) Standard v1.0 following a 5-year consultation process. The LSR Standard is set to take effect on January 1, 2027.
- The release of the LSR Standard represents a notable development for companies in the food and agriculture sector looking to report on land-based GHG emissions in their annual GHG inventory, as well as companies that plan to report on carbon dioxide removals (both land-based and technological).
- The accompanying Land Sector and Removals Guidance, which will provide further direction on operationalizing and implementing the LSR Standard, is expected in Q2 of 2026. However, companies with significant land-based activities may want to begin assessing the impacts of the LSR Standard on their emissions accounting procedures and decarbonization strategies today.
Why the Land Sector and Removals Standard Matters Now
Emissions from agriculture and land use change account for roughly a quarter of global emissions. Yet, for years, food, fiber, and fuel companies have lacked a clear framework for accounting and reporting on GHG emissions and carbon dioxide removals from land use. This has significantly limited their ability to demonstrate progress toward climate targets within their operations and value chain. The GHG Protocol’s Land Sector and Removals (LSR) Standard, which was released on January 30, 2026, changes that, and in doing so raises a new set of questions.
The LSR Standard provides greater clarity on what is required of companies to transparently track and report against their emissions reduction and removal targets, and opens new pathways to report on supply chain decarbonization interventions. It also represents an important advancement for companies seeking to report on carbon dioxide removals within their emissions inventory, including both land management removals and technological removals with geologic storage.
While the LSR Standard contains notable new requirements compared to the draft released in 2022, companies still face a number of open questions related to implementation and the implications for their decarbonization strategies.
The GHG Protocol’s accompanying Land Sector and Removals Guidance, scheduled for Q2 2026, is expected to offer more practical direction for implementing the LSR Standard. However, companies with significant land-based activities that require sufficient lead time to prepare should consider assessing the impacts today.
Below, we provide an overview of the LSR Standard, key changes from the 2022 draft, and actionable next steps for food, fiber, and fuel companies considering the impacts on their target-setting and emissions reporting.
What Is the Land Sector and Removals Standard?
The LSR Standard, taking effect on January 1, 2027, sets requirements and recommendations for corporate GHG accounting that cover emissions and carbon removals from agricultural and land use activities. It builds on existing GHG Protocol standards for corporate carbon accounting. Notably, the LSR Standard does not cover the forestry sector, a key break from the 2022 draft. Forest carbon accounting guidance remains under development and will be the subject of a stakeholder consultation/request for information process expected later in 2026.
Land Sector and Removals Standard vs Land Sector and Removals Guidance
The LSR Standard establishes the core requirements companies must follow, while the accompanying Land Sector and Removals Guidance, expected in Q2 of 2026, will provide more detailed implementation support. In short, the LSR Standard sets the "what" while the Land Sector and Removals Guidance will explain the "how," helping companies put those requirements into practice.
Who Should Be Using the Land Sector and Removals Standard?
The LSR Standard applies to two groups of companies:
- Any company with significant1 land-sector activities within its own operations or value chain (most notably the food, feed, fiber, biofuel, and advanced biomaterials sector).
- Any company looking to report on carbon dioxide removals within their scope 1 and scope 3 inventories (including both land management removals or technological removals).
Land management carbon dioxide removals include those from carbon sequestration through farming practices, agroforestry, or silvopastural systems on productive agricultural land. Technological carbon dioxide removals, by contrast, refer to more engineered approaches such as direct air carbon capture and storage (DACCS) or bioenergy carbon capture and storage (BECCS).
What Changed From the 2022 Draft?
Among other provisions, the LSR Standard contains notable breaks from the 2022 draft, including specific changes related to traceability, carbon dioxide removals, leakage, and land use change.
Traceability: A New Approach
Under the LSR Standard, companies that account for scope 3 emissions, removals, and other metrics must apply a spatial boundary. This boundary is determined by the level of traceability they can establish to known lands or regions (from least to most granular): global, jurisdictional (e.g., country), sourcing region (e.g., supply shed), land management unit (LMU) (e.g., farm), or harvested area. For more granular spatial boundaries, such as sourcing region and LMU, companies are required to establish physical traceability, which can be demonstrated through various chain of custody models.
The LSR Standard defines sourcing regions as predefined, spatially-explicit land areas that supply a raw material to its first point of aggregation or first processing facility in the value chain. The GHG Protocol allows some flexibility in how these boundaries are drawn. They can be defined at a tier of the value chain that includes multiple first points of aggregation or first processing facilities whose supply areas overlap.
Alongside higher integrity chain of custody models such as identity preserved, segregated, and controlled blending, the LSR Standard opens to mass balance as a chain of custody model that can be used to demonstrate physical traceability at the sourcing region-level with appropriate safeguards.
This is notable because mass balance is the most common chain of custody model for large volume agricultural commodities, and physical traceability is required to report removals according to the LSR standard. While challenges for reporting removals at sourcing region spatial boundaries still exist, this change unlocks new opportunities to decarbonize commodities and report removals within non-segregated supply chains through insetting programs.
Carbon Dioxide Removals: Clarity on Spatial Boundaries
The draft LSR Standard introduces key principles for companies choosing to report land management carbon dioxide removals, including traceability, data quality, and permanence. Translating those principles into practice remains challenging given the dynamic nature of agricultural supply chains and limited farm-level traceability.
Among other requirements, the LSR Standard maintains that companies electing to report on removals must do so as a separate accounting category from emissions. They must also identify the specific lands where carbon is stored, and conduct ongoing storage monitoring to detect and report on reversals if and when they occur.
The LSR Standard does, however, resolve one of the more consequential open questions left by the 2022 draft: where companies are to draw the spatial boundary for reporting land management carbon dioxide removals. By formalizing and permitting traceability at the sourcing-region level (with appropriate safeguards), it offers a workable middle ground between farm-level precision and the broader supply chain realities that most food and agricultural companies face.
The LSR Standard also opens to using alternative approaches to traceability, such as impact traceability, which allows companies to trace removals back to the LMU through a pathway that is separate from the physical GHG inventory. This is notable as it provides companies with optionality for recognition of farm-level supply chain investments even when physical traceability cannot be established, and inventory recognition is therefore not feasible.
Land Use and Leakage: Stronger Requirements
Finally, the LSR Standard significantly strengthens land use and economic leakage requirements compared to the 2022 draft. While the draft gave companies flexibility to choose among land-tracking metrics, the LSR Standard mandates that all companies report land occupation for both scope 1 and scope 3 in hectares and quantify land carbon leakage whenever “high leakage risk activities”2 displace food or feed production. This includes companies developing crop-based biofuels and bio-based feedstocks.
Leakage must be quantified using the Carbon Opportunity Cost, a calculation aimed at capturing how much carbon could have been stored in the absence of land management activities.
What Should Companies Do Now?
For entities reporting in accordance with the GHG Protocol’s Corporate Standard and Scope 3 Standard, the new LSR Standard goes into effect on January 1, 2027. However, the GHG Protocol’s Land Sector and Removal Guidance is not set for publication until Q2 2026, leaving many open questions related to implementation amid a short data collection and reporting cycle
In the interim, companies may consider a continuous improvement approach, evolving and improving their internal measurement and reporting mechanisms to enable more granular accounting over time. Companies may also consider running analyses to assess the impact of new requirements on the design and cost of decarbonization strategies, with a specific focus on data collection and monitoring approaches.
Ultimately, while implementation of the LSR Standard may evolve over time, it need not delay action on value chain intervention. Companies that continue investing in supply chain decarbonization are building the data infrastructure, supplier relationships, and operational resilience that yield greater visibility into supply chain risk and drive long-term value, independent of reporting standards.
As the LSR Standard's requirements develop, companies that have already begun assessing their emissions footprint and strengthening supply chain traceability and data quality are likely to be better positioned to align their reporting procedures accordingly.
Independent Project Assurance Is Likely Your Best-Returning Spend
Key Takeaways
- The decision to fund a project is determined by a holistic review of project development maturity. This applies across capital-intensive projects, including low-carbon power generation, carbon capture and storage (CCS) solutions, sustainable aviation fuel (SAF), and broader transition infrastructure build-out. Both technical and commercial workstreams must be developed in parallel to avoid project failure.
- Early scope decisions, such as site selection, core technology selection, and nameplate capacity, are cheap to make but become exponentially disruptive and costly to reverse.
- Independent challenge and verification is tangible evidence of a disciplined, well-managed capital development process.
Bridging the Gap from Announcement to Delivery
Among project developers, a perception often persists: seeking external review signals a project in distress. In capital budgeting discussions, subjecting engineering scope and commercial assumptions to third-party interrogation can be misconstrued as a vote of no confidence in the primary delivery team.
In reality, the reverse is true. Across complex infrastructure, independent challenge is the disciplined stage-gate practice that protects capital by reconciling technical reality with commercial terms before designs are locked.
Independent Challenge Is a Sign of Strength, Not Doubt
Across capital projects, and in particular within emerging low-carbon industrial infrastructure, the gap between announced projects and delivered assets remains stark. Data from the Mission Possible Partnership’s Global Project Tracker reveals that fewer than 17% of announced commercial-scale clean industrial facilities worldwide have reached Final Investment Decision (FID) or commercial operations, leaving more than 800 major decarbonization projects stalled in front-end development.
The causes of developmental paralysis are multifaceted. While macroeconomic interest rate shifts and global supply chain disruptions sit largely outside a developer's control, project definition and developmental discipline remain entirely manageable. Even amid external volatility, a project designed with resilience will have a far greater likelihood of success.
Independent review and assurance directly strengthen a project’s chance of success and overall value. Large global project delivery organizations have applied this discipline for decades by deploying independent teams to evaluate project readiness at every stage gate. For teams lacking a dedicated internal oversight organization, or those deploying first-of-a-kind facilities, third-party independent review provides the necessary rigor to facilitate project success.
Relae’s (formerly Carbon Direct) work with Stockholm Exergi is a clear example: independent assurance helped build funder and regulator confidence in a first-of-a-kind carbon removal facility with no direct precedent to benchmark against.
Why Projects Stall Between Announcement and FID
Low-carbon infrastructure and net-zero industrial projects carry unique risks compared to the repeat delivery of established designs. Exciting new developments run a higher risk of falling victim to optimism bias or compressing development timelines to meet public announcement milestones.
It is a natural human tendency for project champions to focus on the upside during early development. However, early momentum must be balanced with processes that reintroduce industrial lessons, supply-chain realities, and operational resilience.
Front-End Loading (FEL) is a well-evidenced approach for improving capital project outcomes. Decades of benchmarking by Independent Project Analysis (IPA) show that approximately two-thirds of industrial megaprojects suffer capital cost overruns or schedule slippage of 25% or more, or encounter severe operational problems lasting more than two years post-startup. This pattern is repeating in low-carbon infrastructure: IPA’s analysis of 12 completed low-carbon projects found average cost escalation of 31% and schedule slip of almost 50%. Rigorous front-end definition remains the single strongest predictor of whether a project will achieve its cost and schedule targets.
As highlighted in the CDR 2.0: Five Pillars of Successful Project Deployment and Delivery report published by Relae, projects falter when developers push ahead without stress-testing the full delivery framework. Stage gate reviews are the mechanisms that evaluate the total project concept and underlying business case. They are most effective when executed as independent cold-eye evaluations prior to each funding gate, identifying and mitigating vulnerabilities long before final investment decisions are reached.
What Funders Need to See at Each Gate
Different stages of project development rely on distinct capital sources, each requiring specific proof points before deploying funds.
Before FEED Funding: Justifying the Engineering Spend
Front-End Engineering Design (FEED) is a major financial commitment, typically costing between 2% and 4% of total project capital cost. The funders backing this stage are usually the developer’s own balance sheet equity, strategic partners, or public grant programs. Before allocating millions of dollars to detailed engineering, these funders need confidence on the fundamentals:
- A technically sound process concept, confirmed utility balances, and an energy integration scheme that fits the site.
- Secured site control, clear zoning pathways, and no environmental fatal flaws that could derail permitting.
- Documented availability of required feedstocks, water and power, paired with demonstrable interest from target off-takers.
Before FID: Proving Bankability and Commercial Closure
As a project approaches FID, the funding audience shifts to conservative commercial lenders, infrastructure funds, and binding offtake counterparties. These capital providers are not underwriting strategic vision; they are underwriting long-term operational cash flows and debt service. Depending on the project and financing structure, capital providers may require:
- A high-confidence capital cost estimate (AACE Class 2 or Class 3) backed by frozen Piping and Instrumentation Diagrams (P&IDs), firm equipment quotes, and a realistic execution schedule with clear critical paths.
- Bankable engineering, procurement, and construction (EPC) structures that clearly allocate risk, include performance guarantees and enforceable liquidated damages.
- Fully executed, binding offtake and feedstock agreements, along with non-appealable permits and completed utility interconnection agreements, with remaining conditions clearly understood.
- An objective, third-party challenge review that assesses operational viability and distinguishes an executable engineering plan from an aspirational concept.
Commercial and Technical Co-Development: The Stage-Gate Method in Practice
A project rarely fails because of an isolated mechanical issue or a purely commercial misstep; failure happens when technical decisions and commercial terms are negotiated in silos and decisions are made without understanding of the wider implications.
We see this disconnect play out in several ways, including:
- Sizing capacity before testing market demand: An engineering team may size a facility to maximize thermodynamic efficiency and economies of scale, only for the commercial team to discover buyers will only commit to half that volume. The developer is left with an oversized, unbankable design requiring fundamental rework.
- Setting product specifications before negotiating offtake: Process engineers frequently design systems around standard vendor packages. However, when downstream transport, processing, or storage networks enforce strict purity standards, the facility faces costly equipment redesigns. This issue has materialized directly within European CCS networks. Open-access offshore storage operators, such as Norway's Northern Lights project, established strict cross-border CO2 specifications requiring tighter moisture and impurity thresholds than originally designed for.
- Locking Electrical Loads Prior to Interconnection Verification: As detailed in Relae’s analysis of physical infrastructure bottlenecks, scale is rarely constrained by capital availability; it is dictated by electrical transmission queues, substation headroom, and 24/7 firm power availability. Freezing electrical demand before verifying utility interconnection timelines risks stranding engineering work on an asset that cannot connect to the grid.
How Relae Stress Tests Projects at Each Gate
Independent reviews at each stage-gate improve success rates by stress-testing assumptions before presenting to lenders, infrastructure investors, or corporate buyers. Relae reviews projects across five categories using the TECOP framework:
- Technical: Verifying technology readiness levels (TRL), mass and energy balances, plot plan constructability, and operational availability under real-world conditions.
- Economic: Capex benchmarking, operating contingency adequacy, utility tariff sensitivities, and financial model cash-flow resilience.
- Commercial: Offtake agreement structures, feedstock contracts, contracting boundaries, EPC contract structures, and counterparty creditworthiness.
- Organizational: Owner's team capabilities, internal stage-gate governance, contractor oversight mechanisms, and execution capabilities.
- Political: Statutory permitting status, regulatory durability, carbon market policy exposure, and local community social license.
The TECOP framework is relevant for evaluating delivery risk across all project types, see more in Relae’s Criteria for High-Quality Carbon Dioxide Removal, Delivery Risk Appendix.
What makes this approach effective is sitting on both sides of the table. Having completed over 250 deep-dive technology reviews, 900+ project evaluations, and advised on more than $6 billion in industrial project finance, Relae has extensive experience evaluating the considerations important to institutional funders and buyers.
The Value of Early Independent Project AssuranceIncorporating independent review should be standard practice for modern infrastructure delivery. Because funders will perform their own rigorous diligence regardless, conducting an independent evaluation early enables developers to address vulnerabilities proactively and present a more resilient business case.
Commissioning an independent team for a cold-eye review during early project formation can be a cost-effective way to identify potential risks before they become expensive to address. Catching an unworkable process assumption, an oversized capacity plan, or a misaligned commercial interface during pre-FEED costs a tiny fraction of what it takes to fix those issues during construction
Ultimately, independent challenge is not an admission of doubt, but the disciplined stage-gate practice that protects capital by reconciling technical reality with commercial terms before designs are locked, signaling to partners, and your future funders that your project is built to deliver.
To dive deeper into the frameworks that support successful projects, read Relae's white paper: CDR 2.0: Five Pillars of Successful Project Deployment and Delivery and take a look at project assurance in action through our Stockholm Exergi Case Study.
Frequently Asked Questions
What is independent project assurance?
Independent project assurance is a structured review of a capital project by a team that sits outside the project’s delivery organization. Reviewers test the engineering scope, cost estimate, schedule, commercial agreements and permitting position against what funders will require at the next stage gate. The developer receives a clear list of gaps, risks and proposed mitigations prior to presenting the project to lenders, investors or buyers.
When should a developer commission an independent project review?
Periodically throughout the project development process - at a minimum before each major funding gate, but smaller reviews are also beneficial at earlier stages when key concept and technology decisions are being made. A review before Front-End Engineering Design (FEED) tests whether the process concept, site and supply of feedstock, water and power justify the engineering spend. A review before Final Investment Decision (FID) tests whether the cost estimate, EPC structure and binding agreements will satisfy lenders. Site, technology and capacity decisions are cheap to change in pre-FEED and expensive to reverse once detailed engineering starts.
What does an independent project review assess?
Relae structures its reviews around the TECOP framework, which covers five risk areas: technical (technology readiness, mass and energy balances, constructability), economic (capex benchmarking, contingency, financial model resilience), commercial (offtake, feedstock and EPC contracts), organizational (owner’s team capability and stage-gate governance) and political (permitting, regulatory durability and social license). Reviewers also check that technical and commercial decisions are aligned, because projects often fail where the two are developed in silos.
How does an independent project review differ from lender due diligence?
An independent project review applies a holistic approach identifying not only gaps, but also opportunities to add value and strengthen the business case. Lender and investor due diligence is often purely looking at risks and gaps, prior to committing capital. Lender diligence protects the funder and reports its findings at a point when changes are costly and can delay financial close. A developer-commissioned review takes place earlier, so the project team can fix weaknesses in scope, cost or contracts before funders see them.



