Low-Carbon Fuel Certification: How Market Rules Shape the Value of a Fuel
Key Takeaways
- The revenue stack for a given fuel is set by the rules that govern the market for low-carbon fuels: regulations, certification schemes, certificate registries, and corporate accounting frameworks.
- Regulators and buyers reward characteristics beyond regulatory eligibility and carbon intensity, such as reportability, broader sustainability, and advanced technology.
- Relae helps producers with commercial strategy relating to feedstock, production pathway, and certification, which impact access to markets.
The Route to Market Is a Strategic Choice
Low-carbon fuels (LCFs), such as sustainable aviation fuel (SAF) and renewable natural gas (RNG), will cost more to make than their fossil equivalents for the foreseeable future. Projects narrow that gap through some combination of regulatory-market value, sales of environmental attribute certificates (EACs) to voluntary buyers, and financial incentives such as the 45Z Clean Fuel Production Credit.
Regulatory programs are pulling investment into new facilities and novel production routes, and voluntary reporting frameworks are moving toward allowing companies to count fuel certificates in their emissions inventories. What the revenue stack for a given fuel looks like is set by the rules that govern the market for LCFs: regulations, certification schemes, certificate registries, and corporate accounting frameworks.
In voluntary markets, the certification scheme, certificate registry, and reporting framework determine the official carbon intensity (CI) of the fuel, the number of certificates generated, and how buyers can use them to make claims.
In regulatory programs across Europe and North America, the rules determine how the fuel is classified, and whether its feedstock receives premium value, is capped, or is excluded altogether. Producers who understand how their market entry decisions impact value will be better positioned now and going forward.
What Is Carbon Intensity?
A fuel’s CI measures the life cycle greenhouse gas emissions per unit of fuel, usually expressed in grams of carbon dioxide-equivalent per megajoule (gCO2e/MJ). It covers feedstock production, conversion, transport, and use. Each program defines its own methodology for calculating it, which is why the same batch of fuel can carry a different CI depending on which program’s rules apply.
EACs Carry a Fuel’s Value to Market
An LCF EAC records characteristics of a batch of fuel separately from the fuel itself, such as whether it qualifies for a given program, the CI, or its feedstock. The certificate can travel with the fuel (bundled) or be sold on its own (unbundled):
Bundled EACs
In most regulatory markets, an obligated party purchases the fuel and its certificate together. These buyers are mainly fuel suppliers, as under the California Low Carbon Fuel Standard (LCFS), and airlines, as under the EU Emissions Trading System and the Carbon Offsetting and Reduction Scheme for International Aviation (CORSIA). They need both the physical fuel and the EAC that proves the fuel is eligible.
Unbundled EACs (Book-and-Claim)
Often in the voluntary market, the fuel is consumed wherever it can be delivered. The EAC is sold separately to whoever wants to claim its attributes, a system called book-and-claim. This matters because most companies have no control over the fuel burned in their supply chains: a company that ships freight cannot choose the fuel its carriers use, but it can buy EACs with a certified CI and claim the associated emissions reduction.
In both markets, the characteristics the EAC carries determine the regulatory and voluntary value in a fuel’s revenue stack.
Three Layers of Rules Determine the Value of an EAC
An LCF producer chooses the feedstock, production pathway, and markets to sell into. How those choices translate to the value of a fuel’s EAC is determined by three layers of rules that govern the LCF market (Table 1).
Table 1. The three layers of rules that set an LCF EAC’s value. Examples are illustrative and not exhaustive. ISCC = International Sustainability and Carbon Certification; RSB = Roundtable on Sustainable Biomaterials; SAFc = sustainable aviation fuel certificate; RED III = Renewable Energy Directive; GHG = greenhouse gas; SABA = Sustainable Aviation Buyers Alliance. Source: Relae.
Where the Rules Disagree: Three Feedstock and Pathway Examples
The result is that the same batch of fuel can carry a different CI, or a different classification, depending on which rules it is subject to. Three examples below demonstrate how production pathway decisions can impact a fuel’s value:
- Manure-based RNG ⇨ avoided emissions. The three layers treat avoided emissions differently. At the regulatory program and voluntary standard layer, ISCC PLUS follows the EU Renewable Energy Directive (RED III) in crediting methane emissions avoided through improved manure management, but CORSIA does not. At the registry and accounting layer, the Greenhouse Gas (GHG) Protocol’s draft Action and Market Instruments (AMI) Standard and the AIM Platform have proposed separating avoided emissions from a fuel’s direct life cycle emissions and reporting the two on different statements, and whether negative CI values from avoided emissions are accepted at all depends on the registry where the EACs are listed.
- Crop-based feedstocks ⇨ indirect land use change (iLUC). Regulators don’t agree on how to incorporate iLUC, either. Under the LCFS, modeled iLUC emissions for all crop-based fuels are positive. Under CORSIA, they can be positive or negative. Under RED III, iLUC is excluded from the CI, though separate rules restrict feedstocks deemed high-risk for iLUC. And because modeling and assumptions keep evolving, iLUC values are also subject to change over time.
- Synthetic fuel ⇨ e-SAF mandates. Regulatory programs also differ on what counts as a given category of fuel. ReFuelEU Aviation and the UK SAF Mandate both reserve a share of their mandates for e-SAF, but define it differently. The EU requires the fuel to qualify as a renewable fuel of non-biological origin (RFNBO). The UK sets its own power-to-liquid criteria, including which electricity sources it accepts. The same e-SAF can therefore count toward one sub-mandate and not the other.
Beyond Eligibility: EAC Characteristics the Market Rewards
In regulatory markets, an EAC’s value depends first on whether the fuel is eligible and how it is classified. In voluntary markets, value depends on the fuel’s CI and the number of certificates issued. Both regulators and voluntary buyers also reward characteristics beyond that baseline, and those characteristics can impact a fuel’s revenue stack:
- Voluntary reportability. The value of an EAC depends on how a buyer can report it, today and in the future. The GHG Protocol is still finalizing its rules for fuel certificates and what a buyer can claim. Certificates that fit cleanly within those rules may command a premium.
- Breadth of sustainability criteria. Some buyers screen EACs against criteria beyond emissions savings. The Sustainable Aviation Buyers Alliance (SABA) explicitly prefers advanced feedstocks and certification schemes with stronger social and environmental safeguards. Regulations set a minimum bar, but voluntary markets have no single standard for a high-quality EAC. The Relae Criteria for High-Quality Low Carbon Fuels consolidate these characteristics into one framework, and can show producers how their fuel and certification choices measure up against it.
- Advanced feedstocks and technologies. Fuel from novel pathways typically costs more than fuel from established ones, and some buyers are willing to pay that premium: early buyers want to support technologies that need offtake to reach commercial scale, and others want to diversify supply ahead of expected constraints on hydroprocessed esters and fatty acids (HEFA) SAF.¹ Regulators reward the same pathways directly through e-SAF sub-mandates and financial incentives, such as the UK Revenue Certainty Mechanism.
Where Should Producers Start?
How each program treats a feedstock, how each methodology calculates CI, and what each set of buyers will pay for are inputs to the feedstock, production pathway, and offtake decisions themselves. Once those decisions are made and contracts are signed, the route to market is largely fixed. Producers should weigh the routes open to them against three questions before committing:
- How will my feedstock, production pathway, and certification affect access to markets?
- How do I position my product within overlapping voluntary and regulatory markets?
- Who are my buyers and what do they require or prefer?
A sound strategy must consider the complex interactions between voluntary and regulatory markets, certification schemes and registries, and buyer preferences.
The landscape continues to evolve, with new national certification programs and regulations for LCFs emerging across the globe and accounting frameworks shifting. The policy experts, scientists, engineers, and economists at Relae help producers understand how each certification route affects the value of their fuel in the markets they want to enter, choose feedstocks and pathways with that in mind, and make sure the claims behind their EACs are high-quality and hold up to buyer and registry scrutiny as the rules evolve.
Frequently Asked Questions
What is the difference between a bundled and an unbundled EAC?
A bundled EAC is sold with the physical fuel, usually to an obligated party under a regulatory program such as the LCFS or ReFuelEU Aviation. An unbundled EAC is sold separately from the fuel through book-and-claim, so a buyer can claim its attributes without taking delivery of or consuming the fuel.
What is the difference between a regulation, a certification scheme, a registry, and a corporate accounting framework?
A regulation or voluntary standard sets the CI methodology and decides whether certain feedstocks are rewarded, capped, or excluded. A certification scheme verifies that a batch of fuel meets that methodology. A registry issues and tracks the certificates and can apply additional rules on CI, while corporate accounting frameworks determine what a voluntary buyer can claim.
Why can the same fuel have more than one carbon intensity?
Each regulatory program and voluntary standard sets its own CI methodology, and registries can add rules of their own. Manure-based RNG is one example: RED III and ISCC PLUS credit avoided methane emissions, CORSIA does not, and some registries cap CI at zero. The same batch can therefore carry different CIs depending on where it is certified and what market it is sold into.
How does carbon intensity affect LCFS credits?
Under the LCFS, the number of credits a fuel generates depends on how far its certified CI falls below the program’s fossil fuel benchmark for that year. Credit price is set by the market, so a lower CI increases the credits a producer has to sell, and the program’s rules decide the CI of the fuel.
Environmental Markets
Relae guides buyers, investors, producers, and project developers through the market instruments designed to mitigate environmental impacts. Our work combines science-based quality criteria, project-level diligence, market and policy intelligence, and commercial execution to help you make defensible decisions, capture green premiums, and finance the clean energy transition.
Criteria for High-Quality Low Carbon Fuels


Hannah Williams
Hannah Williams
,
Hannah Williams is an economist with a background in biofuels, agriculturesustainability, agriculture, and natural resource management. She has a wide range of research experience that includes utilizing algae-based fertilizers in agricultural operations, managing risk in federal subsidy programs for wastewater infrastructure, and optimizing sustainable aviation fuel supply chains.
Prior to joining Relae, Hannah was a Research Associate in the Department of Agricultural and Resource Economics at the University of Tennessee, Knoxville. In that role, she optimized sustainable aviation fuel supply chains in the Southeastern United States to estimate costs, maximize profitability, and manage risk with a stochastic mixed-integer linear programming model. She also developed spatial regression models to determine the impact of weather and soil erosion on corn and soybean yields in the United States.
Outstanding Graduate Student, University of Tennessee Department of Agricultural and Resource Economics
James Greever Agricultural Development and Enrichment Award, University of Tennessee Herbert College of Agriculture
Chimdi Obienu
Chimdi Obienu
,

Before Relae, Chimdi worked as the Carbon Markets Data and Policy Lead at EcoAct (part of Schneider Electric), where he created the knowledge management system covering frameworks such as CORSIA, Article 6 of the Paris Agreement, and the ICVCM Core Carbon Principles. As part of the Research and Innovation Team, he built scenario modeling tools to quantify the exposure to regulatory carbon pricing mechanisms, such as the EU ETS and CBAM, as well as the costs of assorted carbon offsetting approaches.
At EcoAct, Chimdi also worked as a sustainability consultant, supporting clients with GHG inventory accounting, environmental disclosures (e.g., CDP), and the development of decarbonization strategies.
Chimdi began his career in Washington DC, advising clients on policy developments and technology innovation across the energy and transportation sectors.
Best Student, University of Sussex MSc in Energy Policy
1. HEFA is the dominant commercial SAF pathway. The limited supply of fat, oil, and grease feedstocks, and regulatory caps on their use, are expected to limit its growth.
What to Read Next
Low-Carbon Fuels Under RED: Why Quality Can Differ and How Buyers Can Look Beyond the Certificate
Key Takeaways
- The EU Renewable Energy Directive (RED III) sets the sustainability rules behind clean fuel markets in Europe, and frameworks in the UK and US draw on it. Producers typically show compliance through certification schemes recognized by the European Commission, such as ISCC and RSB.
- Certification provides evidence that a fuel meets the regulatory minimum, but schemes apply RED differently, particularly on topics like social outcomes and leakage. As a result, two compliant fuels can differ in quality.
- Relae’s Criteria for High-Quality Low Carbon Fuels give buyers a single benchmark for assessing quality beyond compliance. By comparing a producer’s certificate against the criteria, buyers can identify gaps and develop contract provisions on quality areas the certificate does not cover, tailored to their own priorities. This can help buyers identify and manage quality risk and stay ahead of tighter regulations likely to come under RED IV.
RED Sets the Bar for Clean Fuels in Europe and Beyond
RED III is a key regulatory framework governing sustainability requirements for clean fuels. Its sustainability criteria underpin Europe’s clean fuels markets, including sustainable aviation fuel (SAF) under ReFuelEU Aviation, marine biofuels under FuelEU Maritime, and biomethane injected into Europe’s gas grid. Its reach extends beyond the EU, too. The UK Renewable Transport Fuel Obligation and SAF Mandate apply sustainability criteria modeled on RED, and the certification schemes built around RED will play a role in California’s new feedstock sustainability requirements under its Low Carbon Fuel Standard.
A Certificate Confirms Compliance, Not Quality
Low-carbon fuel producers typically demonstrate compliance with RED through voluntary certification schemes recognized by the European Commission, such as the International Sustainability & Carbon Certification (ISCC) and the Roundtable on Sustainable Biomaterials (RSB). A certificate provides evidence that a fuel clears the regulatory bar. Every recognized certification scheme covers RED’s core requirements, but each applies them differently, and some go further than others.
How Certification Schemes Can Differ
Certification schemes tend to differ most on questions RED only partly addresses. Social outcomes are one example. RED largely requires certified producers to comply with the laws of the country where the feedstock is grown or the fuel is produced. Following local law, however, is not the same as paying living wages, respecting land rights, or delivering benefits to nearby communities, especially where local protections are weaker than the EU’s. Some schemes fill that gap with their own social requirements; and others do less.
Leakage is another example. It refers to emissions a fuel causes outside its own supply chain, which its carbon intensity does not reflect. One common form is indirect land-use change (ILUC). When cropland or feedstock is redirected to fuel production, the food, feed, or other uses it previously supplied still need to be met elsewhere. That can push cropland expansion into forests or grasslands, releasing the carbon they store. RED manages this risk by limiting the use of feedstocks most associated with expansion into high-carbon-stock land. However, RED acknowledges that ILUC is not limited to these high-risk feedstocks, and diverting waste feedstocks from existing uses can have similar knock-on effects. Without asking specific questions about a given producer’s supply chain, buyers may have limited visibility into the leakage risk behind the fuel they buy.
These examples show that, on paper, two RED-compliant fuels can look the same while differing significantly in overall quality. One reason is that they can be certified under schemes with different requirements on issues such as social outcomes. Another is that RED is built to work at scale, applying a consistent set of rules across the whole market. That consistency is a strength, but it means that some issues, such as leakage, are addressed at the system level rather than for each individual fuel. For buyers, the certificate is a useful starting point for offtake conversations, but may not be enough on its own to judge the quality of what they are buying.
Assessing Quality Beyond Compliance
So how can a buyer tell whether one certified fuel is higher quality than another? Today, doing so means comparing certification schemes rule-by-rule, which is cumbersome. Relae’s Criteria for High-Quality Low Carbon Fuels provides a shared definition for what “better than compliant” means. It brings together requirements from RED, CORSIA, ISCC, RSB, national SAF mandates, and other frameworks into a single benchmark, and adds criteria on social outcomes, additionality, and leakage. We built the criteria for voluntary buyers, but they are just as useful for regulated companies that want to go beyond meeting their mandates and show how well they do it.
How Buyers Can Apply the Criteria, and How Relae Can Help
In practice, buyers can use Relae’s criteria in four steps. Each one calls for technical judgment on scheme rules, supply chains, and contract terms. Relae’s fuels team works alongside buyers at every stage, from the first certificate review to the final offtake terms.
- Start with the certificate. Confirm which scheme the fuel is certified under, what the certificate covers, and whether the producer holds any optional add-ons, such as a low ILUC risk certification. Our team reviews certificates and the scheme rules behind them to confirm what is and is not covered.
- Map the certificate against Relae’s quality criteria. Sort each criterion into what the certificate already covers, what it partly covers, and what it does not address. Our experts carry out this mapping for a specific fuel and pathway and highlight the gaps that matter most.
- Ask the producer to fill the gaps. Turn each gap into a direct question, for example, how the producer verifies wages and land rights in its supply chain, or how it manages ILUC risk. The answers help buyers see where quality risks may lie that compliance alone does not cover. We help prepare these questions and assess the producer’s responses and evidence.
- Build the answers into an offtake agreement. Use the answers to develop contract provisions on quality that the certification does not cover, such as additional verification, disclosure, or feedstock-sourcing requirements. These provisions help buyers manage quality risks over the life of the deal, whether it’s a SAF offtake agreement or another fuel supply contract, and support the sustainability claims they make about the fuel. Our fuels experts work with buyers and their counsel to shape these provisions.
Procuring for Where Standards Are Heading
The criteria are also a guide to what may come next. The European Commission is preparing its post-2030 renewable energy framework (RED IV). The Commission held a public consultation from March to June 2026, and plans to propose legislation by the end of the year. The final scope is not yet known, but industry submissions point to areas where bioenergy rules could tighten, such as stricter traceability and on-site audits for imported waste feedstocks. Buyers who procure against where standards are heading, not just today’s minimum, will be less exposed when the rules change and better able to back up the sustainability claims they make about their fuel.
[cta]
Frequently Asked Questions
What is RED III?
RED III is the current version of the EU Renewable Energy Directive. It sets renewable energy targets and the sustainability criteria that biofuels, biogas, and other renewable fuels must meet to count under EU regulations. Those criteria apply across Europe’s clean fuel markets, including SAF under ReFuelEU Aviation and marine fuels under FuelEU Maritime.
How do producers show their fuel complies with RED?
Most producers use a voluntary certification scheme recognized by the European Commission, such as ISCC or RSB. The scheme audits the producer and its supply chain against RED’s requirements and issues a certificate if they are met.
Are all RED-recognized certification schemes the same?
No. Every recognized scheme covers RED’s core requirements, but each applies them differently, and some add requirements or optional add-ons of their own. Certification schemes differ the most on issues RED only partly addresses, such as social outcomes and leakage. As a result, two RED-compliant fuels can differ in overall quality.
Who should use the Relae Criteria for High-Quality Low Carbon Fuels?
We designed the Criteria for High-Quality Low Carbon Fuels for voluntary buyers, but they are equally useful for regulated companies. Buyers can compare a producer’s certificate against the criteria to find gaps, raise those gaps in offtake discussions, and address them through contract provisions. Relae works with both voluntary and compliance buyers to apply the criteria to specific fuels and deals, from assessing producers to shaping offtake terms.
What is RED IV, and why does it matter for buyers today?
RED IV is the post-2030 renewable energy framework the European Commission is preparing. The Commission consulted on it from March to June 2026, and plans to propose legislation by the end of 2026. Sustainability rules for bioenergy could tighten. Buyers who procure against where standards are heading, rather than today’s minimum, will be less exposed when the rules change.
Decarbonizing Cement and Concrete: Are Their Emissions Set in Stone?
Key Takeaways
- Cement is the key ingredient in concrete and is responsible for more than 80% of concrete’s emissions. Cement’s GHG emissions are the primary technical challenge in decarbonizing an industry that accounts for over 8% of annual global greenhouse gas emissions.
- The global market for low-carbon concrete is constrained by the slow deployment of breakthrough technologies, yet demand from major buyers such as hyperscalers, developers, and infrastructure investors is accelerating. This mismatch between demand and supply is creating a new market mechanism: environmental attribute certificates (EACs) for building materials.
- EACs represent the climate benefits of low-carbon materials and can be traded separately from the physical product. These certificates, when backed by robust technical diligence, offer a near-term funding mechanism to accelerate decarbonization across the cement and concrete supply chain.
The AI Boom Meets an Industrial Reality
As the market for AI infrastructure expands, data center construction is accelerating—and with it, demand for concrete, one of the most carbon-intensive materials in the built environment. For both builders and material suppliers, the embodied carbon of cement and concrete is under a microscope due to its significant climate impact. Hyperscalers, like Microsoft and Meta, have 2030 targets that far outpace the concrete industry’s readiness to provide near-term low-emissions materials.
This piece explores why cement and concrete decarbonization is so challenging and how credible, high-quality EACs can help bridge the ambition gap.
Cement and Concrete: An Important Distinction
These two terms are often used interchangeably, but they are not the same—and the distinction matters for decarbonization strategy. Cement is the reactive ingredient in concrete, acting like an egg in a cake batter. Concrete itself is a blend of cement, aggregates (like sand and gravel), and water (the batter overall). While concrete is widely used and often seen as the emissions culprit, it is actually cement—just 15% of the mix by volume—that is responsible for more than 80% of concrete’s lifecycle carbon emissions.
Why Is Concrete so Hard to Decarbonize?
Concrete is the second most-used material on Earth after water. Despite emitting only ~0.13 kg of CO₂ per kilogram, its sheer scale gives it an outsized climate impact—contributing around 8% of global CO₂ emissions. Yet decarbonization has been slow, held back by technical, structural, and accounting challenges across a complex supply chain.
The Supply Chain Behind Concrete’s Carbon Footprint
To understand why decarbonizing concrete is so difficult, it’s essential to understand how it’s made and what drives its emissions. Three factors explain much of the difficulty:
- Cement is made in an emissions-intensive process. Cement is produced by heating limestone to extreme temperatures (~1450 °C) to create clinker, a reactive material that binds sand and aggregates into concrete. This energy and carbon-intensive process is where the majority of the emissions occur.
- Concrete is made to order. Concrete is a blend of cement, aggregate, and water. It is made to order at local batch plants and poured on-site or used in precast molds, with mix designs tailored to specific compressive strength and durability requirements.
- The supply chain is decentralized and performance-driven. Because concrete mixtures must meet application-specific performance requirements, low-carbon innovations are limited to those that do not decrease product quality and performance at any point in the value chain.
This layered supply chain, from kiln to batch plant to job site, means decarbonization strategies must be compatible with local infrastructure, material availability, and performance needs. There is no single lever to pull.
Clinker Is the Main Emissions Driver
Clinker production alone accounts for the majority of cement’s emissions, due to the chemical process (calcination) that converts limestone into lime and releases CO2. Not only does calcination directly produce CO2, but the combustion of fossil fuels used to heat the kiln adds to the emissions of the overall process.
Low-Carbon Concrete Technology: Invented, Not Yet Deployed
Six promising technologies are in development to address cement and concrete emissions, including:
- Carbon Capture and Storage (CCS): CCS can be retrofitted to capture the fuel and process emissions from clinker production, delivering nearly complete decarbonization of the cement manufacturing process. CCS can be combined with electrification or fuel switching to deliver deeper decarbonization
- Supplementary cementitous materials (SCMs): SCMs offer two key benefits: they can partially replace conventional cement in concrete mixtures, and certain SCMs react with CO₂ from industrial or atmospheric sources to enable durable carbon storage.
- Electrification: Electrifying kiln heating systems can reduce emissions from fossil fuel combustion during clinker production. When powered by low-carbon electricity, this approach lowers the carbon intensity of cement manufacturing while maintaining the high temperatures required for clinker formation.
- Fuel Switching: Natural gas, biomass, and renewable natural gas are low carbon-intensity fuels that can replace the higher-emitting coal and refuse derived fuel that usually drive the clinker production process. Unlike electrification, some alternative fuels can be used as 'drop-in' replacements in existing equipment.
- Synthetic and recycled aggregates: Alternatives to traditional gravel and crushed stone, made from waste materials or industrial byproducts, which can lower emissions and reduce resource extraction.
- CO2 curing: A process where concrete is cured with captured CO2 instead of air, helping lock carbon into the material and partially offsetting upstream process emissions.
Each solution faces deployment challenges, from raw material availability and geographic constraints to cost, performance certification, and integration with legacy infrastructure.
Few decarbonization strategies have reached industrial scale today, but these strategies are being piloted and demonstrated, and given targeted support, some have the potential to significantly decarbonize the future of the industry.
The Gap Between Targets and Real Market Capacity
Hyperscalers, utilities, real estate developers, and other large organizations with ambitious scope 3 targets are looking to significantly reduce the embodied carbon throughout their supply chain. However, the current supply of deeply decarbonized cement and concrete is insufficient to support these targets through direct procurement alone; the low-carbon material simply does not exist at the required volume or in the right geographies. In some cases, pilot plants produce too little material to meet large-scale demand, while projects capable of larger volumes may not yet be located in regions where interested buyers are concentrated.
In this context, EACs offer a flexible mechanism to fund innovation and bridge the gap. By unbundling climate attributes from physical materials, near-term obstacles, such as geographic availability, can be overcome while channeling capital toward scalable and catalytic solutions.
When backed by rigorous life cycle assessments and high-quality, transparent traceability standards, EACs can provide the financial bridge for truly innovative suppliers to invest in the capital solutions required to decarbonize cement and concrete. EACs can serve a catalytic role to support scalable strategies and help ensure that first-of-a-kind facilities are built, and direct procurement of low-carbon concrete is increasingly feasible in the years to come.
How Environmental Attribute Certificates Work in Cement and Concrete Markets
EACs translate emissions reductions from low-carbon cement and concrete production into climate attributes that can be purchased separately from the physical material. Instead of requiring buyers to procure low-carbon concrete directly from a specific supplier site, EACs allow the climate benefit associated with that production to be transacted independently through a book and claim model.
In practice, a producer implements a verified emissions reduction intervention, such as reducing clinker content through supplementary cementitious materials, installing carbon capture at a kiln, or deploying alternative cement chemistries. The resulting emissions reductions are quantified through life cycle assessment and product-level disclosures such as Environmental Product Declarations. Verified reductions can then be converted into certificates representing the climate benefit of that lower-emissions production.
Buyers can purchase these certificates to support the deployment of low-carbon cement and concrete technologies while making progress toward embodied carbon reduction targets. In this way, EACs provide an early demand signal and a revenue stream that can help producers finance capital-intensive decarbonization investments across the cement and concrete supply chain.
What This Means for Suppliers and Buyers
Whether you are procuring concrete or producing it, EACs are only one part of a broader decarbonization strategy. Navigating this space requires decisions at the intersection of technical feasibility, GHG accounting, and capital strategy. Key considerations include:
- GHG accounting and reportability: Life cycle assessments, Environmental Product Declarations, and other product-level attributes must be tracked and transacted with high integrity. Buyers should report their EAC activities responsibly, especially in the current absence of formal standards and guidance.
- Procurement alignment: EAC buyers must ensure purchased certificates reflect equivalent performance grade materials to what was directly procured for structural applications.
- Monetization pathways: Book-and-claim EAC models offer producers a way to fund capital-intensive decarbonization upgrades while giving buyers a credible way to meet interim scope 3 goals. EAC transactions can take many forms and should be designed thoughtfully to minimize risks such as double counting.
Frequently Asked Questions
What is low-carbon cement, and how does it work?
Low-carbon cement reduces emissions by replacing traditional clinker with supplementary cementitious materials (SCMs), switching to cleaner fuels, electrifying kilns, or capturing CO₂ at the point of production. Because cement is responsible for more than 80% of concrete's lifecycle emissions, interventions targeting clinker production deliver the greatest climate impact. Most approaches are technically proven at smaller scales but have not yet reached the industrial volumes needed to meet mainstream demand.
How do EACs for cement and concrete compare to direct procurement of low-carbon materials?
Direct procurement means physically buying low-carbon concrete from a supplier, which requires that product to exist at conditions that often can not be met today. EACs decouple the climate benefit from the physical material, allowing buyers to fund verified emissions reductions across the supply chain even when direct sourcing isn't feasible. Both approaches can count toward scope 3 targets, but EACs offer more flexibility in the near term while the low-carbon materials market matures.
Is low-carbon concrete proven and available at scale today?
The core technologies for decarbonizing cement and concrete are technically demonstrated, but most have not reached commercial scale. Supply is geographically concentrated and insufficient to meet the volume demands of large buyers like hyperscalers, utilities, and real estate developers. This gap between technical readiness and market availability is precisely what makes EACs a valuable bridging mechanism right now.
What should a company look for when evaluating EACs for cement and concrete?
High-quality EACs should be backed by rigorous life cycle assessments and transparent traceability standards that tie the certificate to a specific, verifiable emissions reduction intervention. Buyers should also confirm that the certificates represent materials with equivalent performance grades to what they are directly procuring for structural applications, and that accounting practices minimize risks like double counting. Working with a technically credible advisor to evaluate EAC quality is essential, since the market currently lacks formal standards and guidance.
How Relae Can Help Decarbonize Cement and Concrete
Decarbonizing cement and concrete is both a technical and a strategic challenge. Relae brings integrated expertise across geochemistry, life cycle assessment, carbon accounting, and industrial decarbonization strategy to help buyers and producers navigate the complex path to decarbonization. Relae works directly with producers developing low-carbon cement and concrete technologies and with global buyers seeking credible pathways to address embodied emissions in construction. Our team combines industrial decarbonization engineering, geochemical expertise, and carbon accounting to evaluate emerging EAC frameworks and ensure they deliver real climate impact.
- EAC advisory for buyers: Relae helps buyers procure high-quality EACs through criteria development and in-depth technical diligence of EAC offerings across a range of low-carbon commodities, supporting purchased certificates that reflect genuine, verifiable climate impact.
- EAC advisory for suppliers: Relae helps producers design high-quality EAC interventions and assess potential EAC claims throughout the supply chain, informed by technical assessment, book-and-claim systems, and market landscaping.
- For both: Relae’s levelized cost of carbon abatement tooling provides custom modeling to assess trade-offs across cement and concrete decarbonization pathways, helping ensure that every dollar of climate spend goes further.
The 2026 Criteria: Designing and Delivering High-Quality Carbon Removal
Key Takeaways
- High-quality carbon dioxide removal (CDR) projects require robust project management and oversight to deliver credits on time and at the promised volume; delivery risk is a distinct concern that quality standards alone don't catch.
- The sixth edition of the Criteria for High-Quality Carbon Dioxide Removal is the first to provide an approach to evaluating both credit quality and delivery risk, adding a new delivery risk appendix built around the TECOP framework: technical, economic, commercial, organizational, and political risk.
- The 2026 Criteria provides a framework for developers, investors, and buyers to evaluate both project quality and delivery risk.
- This year's update draws on 170 new diligence reports from 2025 and the input of more than 60 subject matter experts, building on a foundation of six years of lessons from professional diligence across hundreds of real-world CDR projects.
The Criteria Create a Shared Standard for Credit Quality
Relae (formerly Carbon Direct) first launched the Criteria for High-Quality Carbon Dioxide Removal (the Criteria) in collaboration with Microsoft in 2021 to help rapidly and justly scale the development of high-quality carbon dioxide removal (CDR) credits. The market didn't yet have a shared definition of what "high-quality" meant, so we laid out transparent, science-based benchmarks that gave developers, investors, and buyers a common foundation to work from. Every year since, we have gone back and sharpened those benchmarks so that they keep pace with the quickly evolving industry.
But a shared definition of quality doesn't guarantee the delivery of credits as planned. The 2026 edition is the first to tackle that gap directly, pairing the Criteria's quality benchmarks with a new framework for evaluating delivery risk.
The Six Principles of High-Quality Carbon Removal
The Criteria defines six science-based principles that apply across engineered, hybrid, and nature-based CDR approaches:
- Social harms, benefits, and environmental justice: The extent to which the project prevents new social harms to people and communities, reduces existing harms, and provides meaningful benefits distribution.
- Environmental harms and benefits: The extent to which the project minimizes and mitigates environmental harms, as well as provides environmental benefits.
- Additionality and baselines: The evidence that the project’s carbon removal would not have occurred without carbon finance.
- Measurement, monitoring, reporting, and verification (MMRV): The ability to accurately quantify carbon removal in a repeatable and verifiable way, and to develop a plan for long-term monitoring of the project.
- Durability: The likelihood that removed carbon remains stored over time, with mechanisms in place to mitigate reversal risk.
- Leakage: The extent to which project activities cause increased emissions elsewhere.
These principles provide a consistent foundation for carbon removal procurement, evaluation, and project benchmarking.
[cta]
Supporting the Delivery of High-Quality CDR Credits
"Projects must work better operationally and be more commercial. Quality and delivery risk shape a project's risk profile at every point in its life, and this edition of the Criteria is the first to give buyers a way to judge both at once." Dr. Julio Friedmann, Chief Scientist, Relae
Designing projects to meet high-quality CDR criteria is only part of the challenge. Effective project planning, management, and execution are also essential to ensure that high-quality CDR tonnes successfully reach the market as planned. As discussed in CDR 2.0: Five Pillars of Successful Project Deployment and Delivery, managing delivery risk requires developers, investors, and buyers to understand the risks that can affect project success and align on how these risks are assessed and mitigated.
To support this alignment, the 2026 Criteria introduced a new Delivery Risk Appendix, which establishes a common framework and language for identifying and evaluating key delivery risks for the first time. Drawing on our broader observations of the carbon removal market and established approaches to project risk management, the appendix highlights common delivery risks across two broad CDR project types: open systems and closed systems. It organizes these risks into five categories: technical, economic, commercial, organizational, and political factors, also known as the TECOP framework.
The TECOP Framework for CDR Delivery Risk
- Technical delivery risks are associated with the technical feasibility of the project design, implementation, and long-term operation of the project
- Economic delivery risks are associated with the project’s financing structure, financial modeling assumptions, and expenditure profile
- Commercial delivery risk reflects the extent to which a project's purchase agreements, supply arrangements, and key contractual relationships are secured or well-advanced.
- Organizational delivery risks center on the project developer's capacity and capability to successfully plan, execute, and manage a project of the appropriate size and complexity.
- Political delivery risks are associated with governance, policies, and potential changes in regulatory environments, as well as the local communities’ perception of and willingness to participate in projects.
New Additions to the 2026 Criteria
Since publishing the 2025 Criteria, Relae has conducted an additional 170 diligence reports across established and emerging CDR pathways, ranging from reforestation and enhanced rock weathering (ERW) to direct air capture (DAC). To date, less than 10% of all 900+ projects the team has reviewed have met the bar for high-quality. These diligence efforts, together with insights from market analysis and ongoing synthesis of the latest scientific and technical literature, have deepened our understanding of how CDR project quality has evolved over the past year.
The 2026 Criteria leverage these insights and the expertise of more than 60 subject matter experts to reflect advances across the CDR industry and address key weaknesses that remain in the market across all pathways.
A few of the most significant updates to the Criteria include:
Addition of Direct Counterparty Considerations: Direct counterparties are the organizations that developers partner with, and are structurally dependent on, to generate credits. This can include:
- Primary feedstock providers (e.g., mines, biomass providers, tree nurseries)
- Major implementing partners (e.g., local implementation partners, base facilities, transportation and storage providers, major product offtakers)
- Land owners that make up a significant proportion of project land
To reflect the key role that direct counterparties play in high-quality credit generation, developers must conduct diligence and disclose on their direct counterparties to demonstrate that they are not causing social or environmental harm.
Increased Rigor for Enhanced Rock Weathering Projects: Over the past year, ERW’s presence in the CDR market has grown substantially, and so too has the market’s understanding of the corresponding scientific and technical rigor required to deliver high-quality tonnes. The 2026 Criteria raised the bar for how ERW projects:
- Measure and prove their carbon removal claims
- Mitigate risks related to potentially toxic elements (PTEs)
- Incorporate more sophisticated farmer protections and benefits
Projects now have to back up their numbers with multiple physical field measurements, not just computer models; and they must now track and account for every significant loss pathway, from plants taking up minerals to carbon escaping from rivers and oceans.
Use of Dynamic Baselines for ARR Projects: ARR projects are increasingly using dynamic baselines to provide a more accurate reflection of the counterfactual scenario (e.g., what would have happened in the absence of the project). This is reflected in the 2026 Criteria with a requirement that ARR projects, with the exception of agroforestry projects, use dynamic baselines with statistically matched controls.
What’s Next?
The 2026 Criteria create a clear, science-driven framework for both designing and delivering measurable, just, and durable carbon removal. However, the Criteria cannot ensure high-quality tonnes reach the market on its own; good criteria do not replace robust diligence. To put these criteria into practice, we encourage developers, standard-setting bodies, buyers, investors, and policymakers to consider how the Criteria can be used to inform their role in enabling the carbon market to deliver high-quality tonnes and to engage in deep diligence and ongoing monitoring over the life of a project.
This edition of the Criteria reflects what we have learned over the past year, but our work is not done. We will continue to update it so that it remains a living document that evolves with the science and the market. To do so effectively, it must be a collaborative effort; we welcome input from carbon market actors, academia, and communities.
Frequently Asked Questions
Who publishes the Criteria for High-Quality Carbon Dioxide Removal, and how often is it updated?
Relae (formerly Carbon Direct) first published the Criteria for High-Quality Carbon Dioxide Removal with Microsoft in 2021 and have updated it every year since. The 2026 edition reflects six years of lessons from real-world project diligence and advances in climate science.
What are the six principles of the Criteria for High-Quality Carbon Dioxide Removal?
The Criteria define six science-based principles that apply across all CDR pathways: social harms, benefits, and environmental justice; environmental harms and benefits; additionality and baselines; measurement, monitoring, reporting, and verification (MMRV); durability; and leakage.
What CDR pathways does the Criteria cover?
The Criteria include pathway-specific criteria across nine CDR pathways: afforestation, reforestation, and revegetation (ARR); mangrove forestation; improved forest management (IFM); soil carbon; enhanced rock weathering (ERW) in croplands; biomass carbon removal and storage (BiCRS); abiotic marine CDR; carbon mineralization; and direct air capture (DAC).
What is delivery risk in carbon removal?
Delivery risk is the likelihood that a project generates credits on the timeline and at the quantity committed to buyers. It's a distinct concern from credit quality: even a high-quality project can fail to deliver as planned because of technical, economic, commercial, organizational, or political risk, the five categories the Criteria's TECOP framework evaluates. The 2026 Criteria's new Delivery Risk Appendix gives developers, investors, and buyers a shared benchmark for identifying and managing these risks before they derail a project.
What's the relationship between carbon removal credit quality and delivery risk?
Credit quality and delivery risk are distinct but interrelated. A project that fails to deliver credits as planned reduces the availability of high-quality CDR tonnes in the market, and weaknesses in credit quality can themselves increase delivery risk by creating buyer uncertainty or limiting access to project financing. The 2026 Criteria provides a framework for evaluating both quality and delivery risk.
Steel Decarbonization: How EACs Scale Low-Carbon Production by 2030
Key Takeaways
- Decarbonizing steel is key to meeting ambitious climate targets in the face of rapidly expanding AI infrastructure as well as broader infrastructure growth.
- The gap between corporate climate ambitions and near-term commercial reality is widening. Despite strong demand signals from hyperscalers and other major buyers, leading producers have recently canceled or delayed flagship green steel projects, citing high energy costs, slow hydrogen market development, and unfavorable policy environments.
- Bridging this gap requires significant capital investment and supporting mechanisms to scale low-carbon technologies. Environmental attribute certificates offer an effective mechanism to channel capital toward transformative, low-carbon steel projects, supporting technology scale-up, as well as providing a way for buyers to meet their emissions reduction targets.
- To protect the credibility of environmental attribute certificates as a market mechanism for decarbonization, projects should seek to meet rigorous quality criteria such as additionality, verifiability, and catalytic impact.
Forging New Climate Ambitions for Steel Production
Decarbonizing steel production is essential to meet global climate targets. Steel production accounts for approximately 7–9% of global CO2 emissions. This is driven chiefly by coal-based primary steelmaking, which still accounts for the majority of global production. Globally, at least 1.8 billion tonnes of crude steel were produced in 2025 to serve a broad array of industries including real estate, infrastructure, automotive, and data center construction.
As hyperscalers race to build the infrastructure underpinning the AI revolution, steel demand for data center construction, and associated energy infrastructure, is increasing. While the relative share of data center demand for steel versus global steel demand is small, the need for approximately 20,000 tonnes of steel per data center has a material impact on hyperscaler’s public climate commitments. Microsoft, Meta, and other large technology companies have set ambitious 2030 climate targets that include their scope 3 emissions. The embodied carbon of the steel used to build their data centers sits squarely in scope 3.
Hyperscaler’s climate commitments have generated sector-specific demand for decarbonized steel, presenting an opportunity to affect steel decarbonization more broadly. Despite this demand, the supply of low-carbon steel remains limited. The industry faces significant scale-up challenges due to the diffuse nature of demand and the nascent market. Catalyzing growth in decarbonized steel production will require market innovations and new production pathways designed to overcome these challenges. Credible environmental attribute certificates can help bridge the gap between today’s market and tomorrow’s low-carbon steel sector.
What is an Environmental Attribute Certificate?
An environmental attribute certificate (EAC) represents the environmental attributes of a product that can be unbundled and transacted separately from the underlying physical commodity. The most widely used EACs today are renewable energy certificates (RECs), which track the environmental attributes of renewable electricity. The same concept can also be applied to steel and iron, as well as to materials such as cement and concrete.
In a book and claim model, a steel producer can implement a verified emissions reduction intervention, quantify the resulting lowered carbon intensity per tonne of steel produced, and convert that into tradeable certificates. Buyers can then purchase those certificates to support the deployment of low-carbon steelmaking capacity in cases where direct procurement of low-carbon steel is currently impractical due to geographic, contracting, or scheduling incompatibilities.
EACs are distinct from carbon credits. They do not represent emissions reduced or avoided relative to a counterfactual; they represent the intrinsic carbon intensity of the material produced, measured through a life cycle assessment.
Decarbonizing Steel Requires Significant Capital and Infrastructure Deployment
Steel Production Today
Steel is currently made via three main production routes. About 71% of the world’s steel is produced through the blast furnace–basic oxygen furnace (BF-BOF) route, which emits an average of 2.33 tonnes of carbon dioxide (tCO2) per tonne of crude steel. A further 24% is produced using scrap-based electric arc furnaces (EAFs), which emit 0.68 tCO2 per tonne on average—far lower, but still dependent on the carbon intensity of grid electricity. The remaining roughly 5% uses direct reduced iron combined with an EAF (DRI-EAF), typically using natural gas, emitting 1.37 tCO₂ per tonne on average.
While increasing scrap-based production is a critical decarbonization lever, scrap availability is limited. Primary steel production, which uses iron ore as the main feedstock rather than recycled scrap, will remain necessary at large volumes through 2050. This makes it essential to decarbonize ore-based pathways, especially ironmaking: the step where iron ore is reduced to iron and where most emissions occur.
Decarbonizing ore-based steel production requires one of three fundamental interventions: (1) replacing coal and natural gas with low-carbon fuels such as hydrogen or bio-coke, (2) electrifying ironmaking directly, or (3) capturing and storing the CO2 generated from fossil-fuel-based processes. All three involve significant capital expenditure and dependencies on infrastructure that is not yet in place at the necessary scale. As a result, the energy and cost challenge is substantial.
Low-Carbon Steel: Emerging Pathways
A range of transformative technological pathways are currently in development to overcome these barriers, offering the potential to deliver deep decarbonization to the steel industry exceeding 90% by 2050:
- Hydrogen-based DRI-EAF: Using green hydrogen instead of natural gas within the DRI process provides a pathway to significantly lower the carbon intensity of ironmaking. Producers such as Stegra are deploying commercial-scale facilities designed to utilize 100% green hydrogen to reduce iron ore.
- Electrifying ironmaking:
- Molten oxide electrolysis: Boston Metal is commercializing a process that uses electricity to directly convert iron ore to molten metal through electrolysis at high temperature, eliminating the need for hydrogen or carbon reductants entirely.
- Low-temperature electrowinning: Colorado-based startup Electra uses renewable electricity to extract iron from ore via an aqueous electrochemical process that operates at near-ambient temperature.
- Carbon capture and storage (CCS): For blast furnaces and DRI plants with long remaining lifetimes, retrofitting with CCS technology can significantly reduce emissions. With new high-emitting capacity still being built, and assets expected to operate for decades, integrating CCS will be essential to avoid long-term carbon lock-in and to decarbonize these facilities over time. To date, commercial-scale deployment remains limited. The Al Reyadah facility at Emirates Steel is the only project currently capturing CO2 from a DRI process at scale, though a handful of other large-scale projects have entered the development pipeline.
Progress and Setbacks: A Mixed Picture
The past year sent contradictory signals about the pace of steel decarbonization. On the demand side, technology companies with ambitious climate targets are actively signaling their intent to procure near-zero steel and support its development.
In September 2025, Microsoft and Stegra announced a landmark agreement that combines a physical supply deal for low-carbon steel with a separate EAC purchase agreement. Around the same time, Meta announced an agreement with Electra to purchase EACs tied to the startup’s clean iron production, becoming one of the first buyers to use the EAC model for an entirely novel, pre-commercial ironmaking technology. Nucor, the largest US steelmaker, also entered into a physical iron purchase agreement with Electra.
Despite these demand signals, the industry has experienced significant setbacks. A series of low-carbon steel project cancellations and delays has raised questions about the pace and viability of the steel transition, especially due to the high costs associated with green hydrogen production.
At present, the green premium for most low-carbon steel remains too high for buyers. A combination of sustained policy support, long-term demand signals from buyers willing to pay more, and scaling of supporting industries, such as green hydrogen production, is necessary for the low-carbon steel industry to be successful in the long run.
How EACs Can Bridge the Funding Gap in Steel
EACs unbundle low-carbon steel attributes from the physical material, reducing the friction between buyers who are willing to pay a green premium and geographic or logistical constraints that may inhibit physical offtake. Buyers, such as hyperscalers procuring conventional steel for data center construction in locations where low-carbon steel is not yet available, can purchase these certificates to support the development of low-carbon capacity, attribute lower-carbon production to their steel use via a market-based mechanism, and advance toward their scope 3 targets.
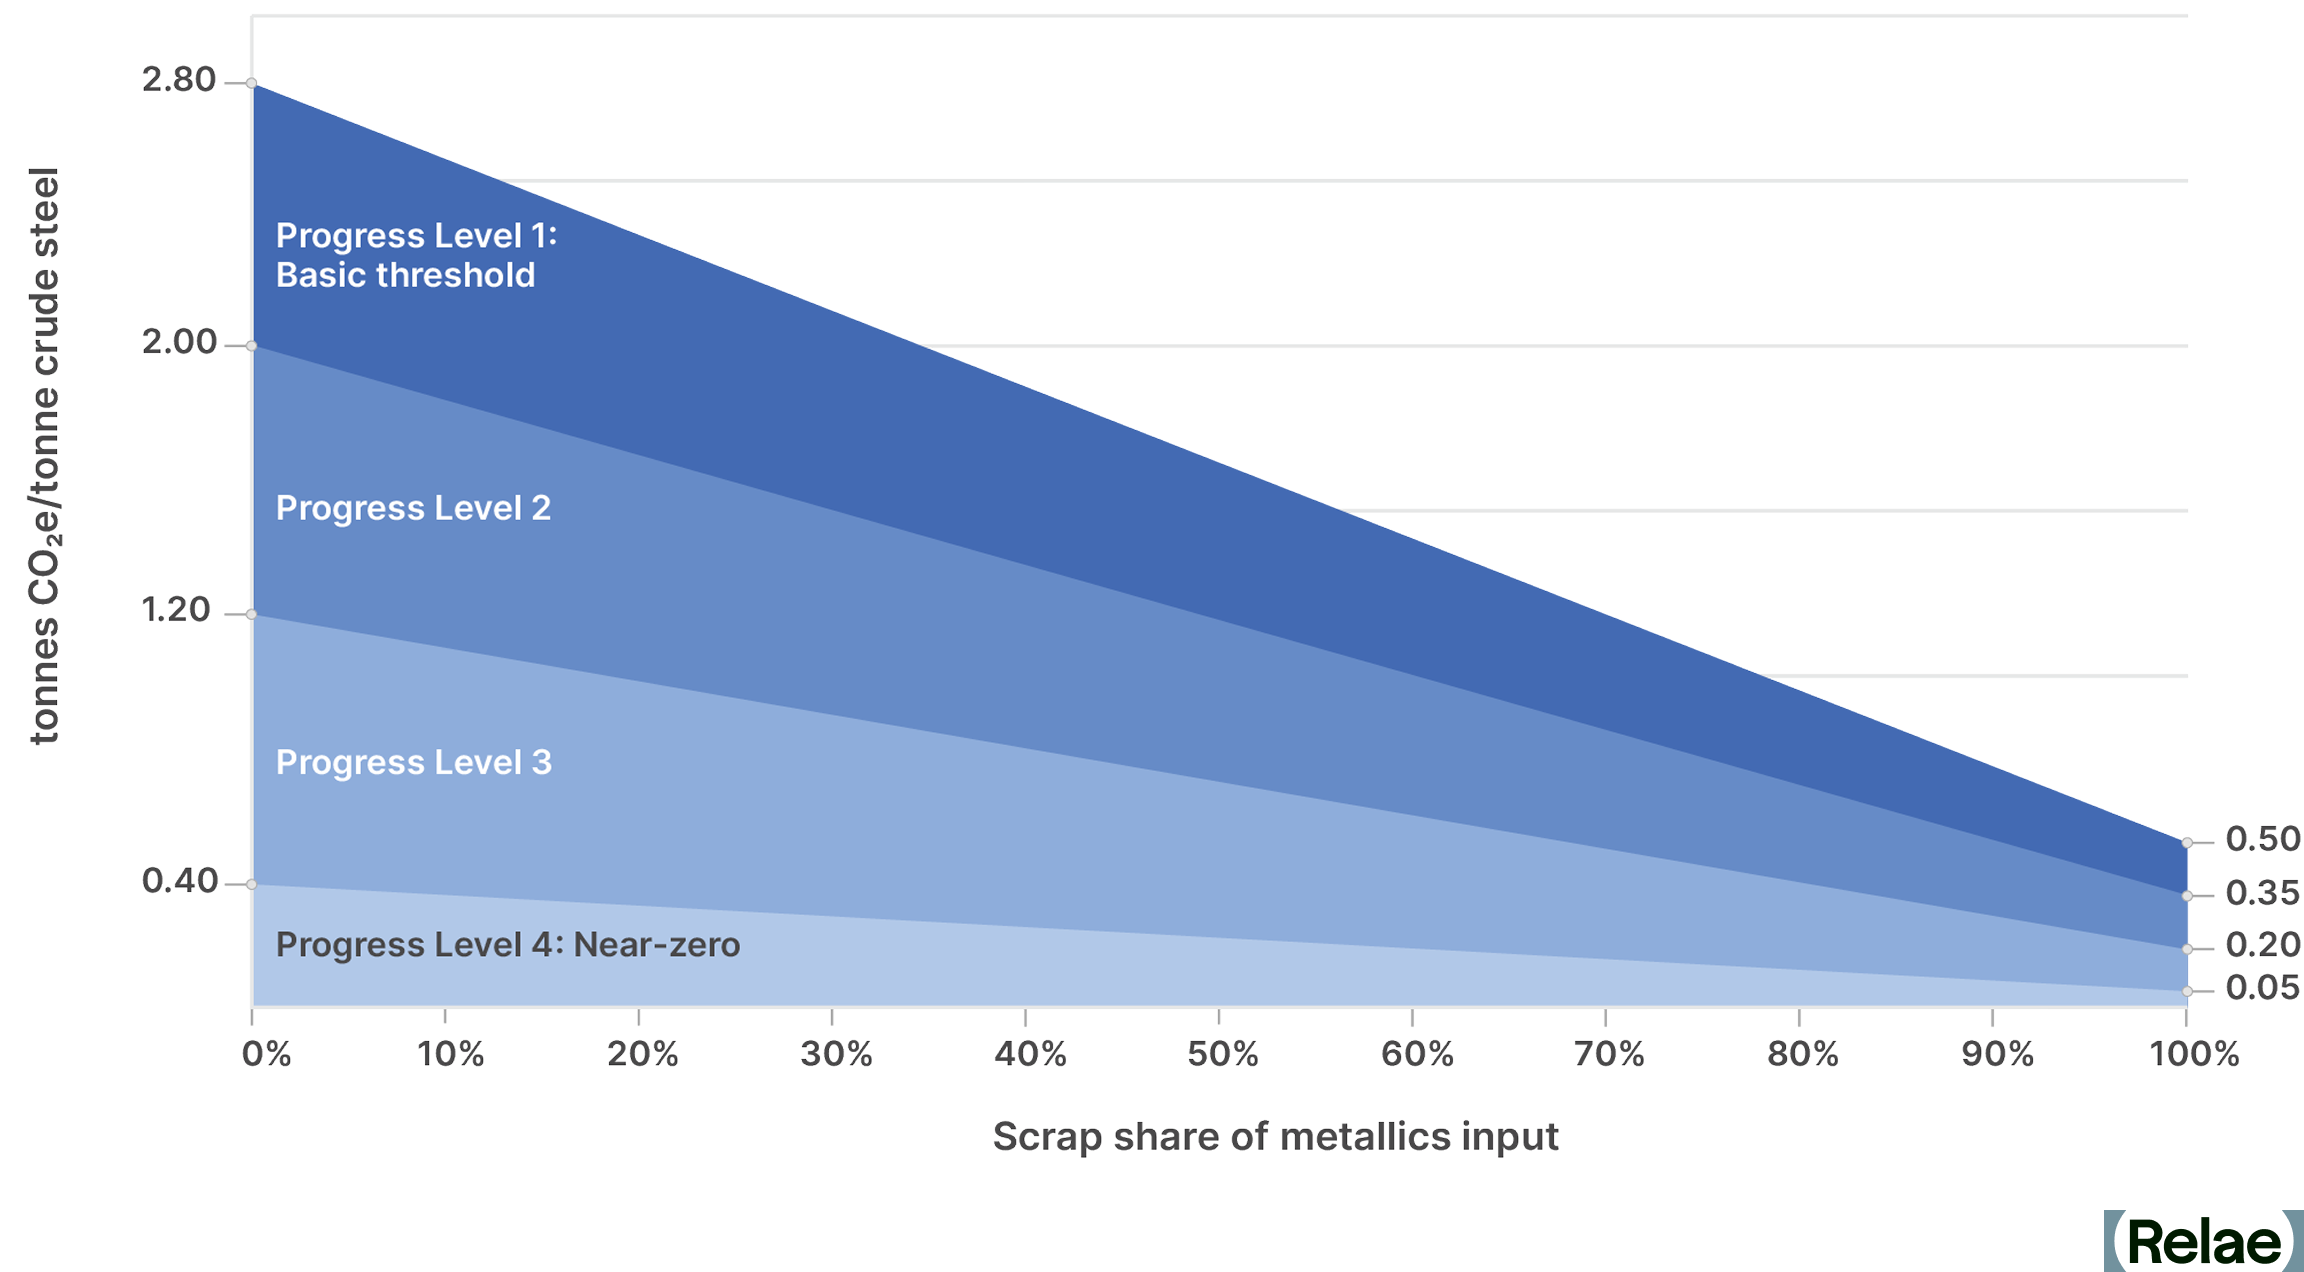
A primary objective of the Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors, jointly developed by Relae (formerly Carbon Direct) and Microsoft, is to establish high-integrity standards for the EAC market in these sectors. For steel EACs, that means demonstrating significant emissions reduction performance by reaching at least Progress Level 2 in the ResponsibleSteel Decarbonization Progress Levels framework, and aiming to achieve Progress Level 3 by 2030. ResponsibleSteel’s scrap-variable benchmark provides a technology-neutral mechanism to evaluate emissions reduction performance by accounting for the specific proportion of scrap used.
EACs for steel are designed to be catalytic. Rather than supporting incremental improvements that are already becoming cost-competitive, they should target transformative capital changes, such as replacing BF-BOF routes with DRI-EAF, adopting low-carbon hydrogen in DRI processes, or deploying novel ironmaking technologies. Multi-year purchase agreements are particularly powerful because they provide the investment certainty that first-of-a-kind projects need to access capital at a lower cost.
What this Means for Buyers and Suppliers of Low-Carbon Steel
Whether you are producing or procuring steel, EACs are only one part of a broader decarbonization strategy. For buyers with significant emissions from steel, and other building materials such as cement and concrete, EACs can be a powerful tool to help advance scope 3 reduction goals where supply for physical low-carbon materials is limited. Suppliers can complement commercialization strategies for low-carbon materials by using EACs to monetize emissions reductions, generate additional revenue to support decarbonization investments, and help scale markets for low-carbon materials. Navigating the steel market requires decisions at the intersection of technical feasibility, greenhouse gas accounting, and capital strategy. Key considerations include:
- Greenhouse gas accounting and reportability: Cradle-to-gate emissions for steel production must be tracked using life cycle assessments and should strive for interoperability with environmental product declarations (EPDs). EAC transactions must be reported transparently, especially given the absence of formal market standards at this stage.
- Additionality and catalytic impact: EAC purchases must demonstrably support projects that would not proceed without financial support from the EAC market mechanism, and projects should have a credible pathway toward the near-zero (Progress Level 4) threshold on the ResponsibleSteel framework.
- Avoiding double counting: EAC buyers must verify that the environmental attributes they purchase are not also being claimed by the physical product buyer via an EPD.
FAQs
What is an environmental attribute certificate (EAC) for steel?
An EAC represents the environmental attributes of low-carbon steel, unbundled from the physical material itself, so a producer can quantify a verified reduction in carbon intensity per tonne and sell that value as a separate, tradeable certificate. Buyers can purchase EACs to support low-carbon steel production while still working toward their own emissions targets.
How is an EAC different from a carbon credit?
An EAC reflects the intrinsic carbon intensity of the material itself, measured through a life cycle assessment. That's different from a carbon credit, which represents carbon dioxide actively avoided, reduced or removed from the atmosphere relative to a baseline.
How are AI data centers impacting the demand for low-carbon steel?
Data centers use roughly 20,000 tonnes of steel each, and as hyperscalers build out AI infrastructure, that steel use counts toward their scope 3 emissions and public climate targets. That's turned data center construction into a meaningful driver of demand for low-carbon steel, even though supply remains limited.
What makes an EAC credible enough to count toward a company's emissions goals?
A credible steel EAC needs to meet criteria like additionality (the project wouldn't happen without the EAC revenue), verifiability through life cycle assessment, and catalytic impact toward transformative technology rather than incremental gains. Relae (formerly Carbon Direct) and Microsoft jointly developed criteria for high-quality EACs in the steel and concrete sectors, which set a threshold of at least Progress Level 2 on the ResponsibleSteel Decarbonization framework today, rising to Progress Level 3 by 2030.
Can a producer sell an EAC and also get credit for the physical steel elsewhere?
No. EAC producers need to confirm the environmental attributes they're selling aren't also being claimed by whoever buys the physical steel through an environmental product declaration; otherwise the same emissions reduction gets counted twice.
The New Nasdaq Issuance Calendar Advances Transparency in the Carbon Removal Market
Key Takeaways
- The Nasdaq Carbon Issuance Calendar, a new data platform, provides carbon removal buyers and suppliers with standardized information on future offtake availability, indicative pricing, and project maturity. The platform was developed in collaboration with Relae, formerly Carbon Direct.
- The Carbon Issuance Calendar addresses the fragmentation and transparency problems of the voluntary carbon market by centralizing standardized project data and embedding our scientific diligence framework, built over 900 project reviews, giving buyers delivery-risk insight that no registry or marketplace offers today.
- The Carbon Issuance Calendar is an important early step, not the whole journey: it shows buyers what durable tonnes exist and allows them to compare projects with apples-to-apples data.
- Buyers can move from the Carbon Issuance Calendar into technical diligence, contracting, and project assurance with Relae’s advisory team. Suppliers can register to connect with buyers who are ready to engage.
Carbon Removal Project Data Has a Visibility Problem
If you're sourcing durable carbon removal credits, you may run into a familiar wall: project data scattered across dozens of developer websites, presented in inconsistent formats, with no easy way to compare one project against another. If you're a project developer, you face the mirror image of that problem: fielding individual requests for proposals, with no central place to showcase your available tonnes.
Get this wrong, and buyers may end up counting on carbon removal that never shows up - the delivery risk bugbear.
Between 2022 and 2024, high-durability engineered carbon removal made up just 2 percent of all carbon credit issuances. They remain in short supply, particularly the high-quality supply corporate buyers need. The gap is set to widen: our 2026 State of the Voluntary Carbon Market report found that more than 80% of the 2030 high-durability carbon removal projects are at risk of stalling and failing without additional offtake and financing commitments.
The Nasdaq Carbon Issuance Calendar, developed by Nasdaq in collaboration with Relae, offers an important first step toward addressing this information gap.
What Is the Nasdaq Carbon Issuance Calendar?
The Carbon Issuance Calendar is a centralized, accessible dashboard where carbon removal buyers and suppliers view standardized project data: future credit availability, indicative pricing, and project delivery status, all in one place.
The Nasdaq Carbon Issuance Calendar combines structured, developer-provided project data with project maturity assessment informed by Relae’s assessment framework and technical diligence. This helps users understand future CDR availability, indicative pricing, and potential project delivery risk through a single platform.
This expertise didn't appear overnight. It comes from sitting across the table with developers, stress-testing their science, mapping their delivery timelines against reality, and helping them show up to buyers as credible partners. The result is a track record that gives the framework embedded in the Carbon Issuance Calendar its depth. It's a starting point, built for buyers and suppliers to find each other on the basis of consistent, comparable information, using international class financial and information infrastructure.
How Buyers Should Use the Nasdaq Carbon Issuance Calendar
Today, if you're trying to procure durable carbon removal credits, you have no single place to start. You have to visit individual developer sites, request information through scattered channels, and compare projects that present data in entirely different formats before diligence has even begun. In many cases, you are comparing apples to oranges - different kinds of CDR projects with different durabilities, risks, and overall quality.
The Carbon Issuance Calendar provides a central starting point. You can view future credit availability, compare indicative pricing across projects, and begin assessing options without contacting each supplier one by one.
More importantly, the Carbon Issuance Calendar frames the data. Our scientists developed a delivery-oriented lens, built from reviewing over 900 carbon removal projects, drawing on the same rigor behind our Criteria for High-Quality Carbon Dioxide Removal, which we develop annually with Microsoft.
How Suppliers Reach Buyers Through the Carbon Issuance Calendar
If you're a project developer, the Nasdaq Carbon Issuance Calendar tackles visibility, one of the most persistent barriers to market access. You can list available tonnes, display indicative pricing, and reach a global audience of corporate and financial buyers at no cost.
The timing matters. Many first-of-a-kind engineered carbon removal projects are preparing to break ground and need bankable offtake agreements to secure financing before they can do so (a key aspect of CDR 2.0). Our analysis of approximately 140 high-durability carbon removal project developers found scale-up plans for 30 million tonnes of supply per year. Reaching that potential will take real demand: committed forward offtake, increased project equity investment, and access to lending.
Register now: you'll be positioned to connect to buyers actively looking to engage.
How Does the Carbon Issuance Calendar Differ From a Carbon Credit Registry or Carbon Removal Marketplace?
The Carbon Issuance Calendar solves a distinct, early-stage problem. It gives buyers and suppliers a centralized place to find each other and compare options against standardized information, something neither a registry nor a marketplace is built to do.
For a closer look at how registries differ and what you should weigh when navigating them, read our Navigating Carbon Credit Registries report.
Scientific Diligence Turns Visibility Into Confidence
Standardized data tells you what exists. Scientific diligence tells you what's worth pursuing.
Relae’s scientists do that work every day. Our experts apply rigorous pathway-specific criteria to live projects, evaluating delivery risk and status, and identifying where questions remain is the core of what we bring to the carbon removal market.
The Carbon Issuance Calendar puts an accessible version of that expertise at the top of the procurement funnel. It’s for everyone in the market - you don't need to be a carbon removal scientist to use it. This snapshot allows you to compare projects against each other, giving you a meaningful starting point before deeper diligence begins.
Want to go deeper on a specific project? Relae’s technical diligence team picks up right where the Carbon Issuance Calendar leaves off.
What Carbon Removal Projects Are on the Carbon Issuance Calendar Today?
The Carbon Issuance Calendar currently features engineered and hybrid carbon removal projects: direct air capture, biochar, enhanced rock weathering, and bioenergy with carbon capture and storage. These high-durability pathways offer permanence on the order of hundreds to thousands of years.
Many of these projects are at an inflection point: they’re ready to scale but dependent on committed offtake to unlock financing. The Calendar serves their needs, and the buyer’s needs, together.
Nature-based carbon removals have their own criteria and market dynamics. They may appear in a separate segment of the Carbon Issuance Calendar down the line.
From the Carbon Issuance Calendar to Completed Carbon Removal Procurement
If you're building or refining a carbon removal procurement strategy, the Carbon Issuance Calendar is the right place to start.
From there, you can choose to work with the Relae advisory team to support every later stage: technical diligence on specific projects, contracting and negotiation support, ongoing project assurance, and access to curated carbon credit sourcing. The Carbon Issuance Calendar surfaces the market; we help you navigate it, connecting you with the right developers, on the right terms, with the scientific confidence to move forward.
Moving from commitment to delivery takes structural change across the market, too—our CDR 2.0 white paper lays out the five pillars we see as essential to getting engineered and hybrid carbon removal projects built and delivering.
Independent Project Assurance Is Likely Your Best-Returning Spend
Key Takeaways
- The decision to fund a project is determined by a holistic review of project development maturity. This applies across capital-intensive projects, including low-carbon power generation, carbon capture and storage (CCS) solutions, sustainable aviation fuel (SAF), and broader transition infrastructure build-out. Both technical and commercial workstreams must be developed in parallel to avoid project failure.
- Early scope decisions, such as site selection, core technology selection, and nameplate capacity, are cheap to make but become exponentially disruptive and costly to reverse.
- Independent challenge and verification is tangible evidence of a disciplined, well-managed capital development process.
Bridging the Gap from Announcement to Delivery
Among project developers, a perception often persists: seeking external review signals a project in distress. In capital budgeting discussions, subjecting engineering scope and commercial assumptions to third-party interrogation can be misconstrued as a vote of no confidence in the primary delivery team.
In reality, the reverse is true. Across complex infrastructure, independent challenge is the disciplined stage-gate practice that protects capital by reconciling technical reality with commercial terms before designs are locked.
Independent Challenge Is a Sign of Strength, Not Doubt
Across capital projects, and in particular within emerging low-carbon industrial infrastructure, the gap between announced projects and delivered assets remains stark. Data from the Mission Possible Partnership’s Global Project Tracker reveals that fewer than 17% of announced commercial-scale clean industrial facilities worldwide have reached Final Investment Decision (FID) or commercial operations, leaving more than 800 major decarbonization projects stalled in front-end development.
The causes of developmental paralysis are multifaceted. While macroeconomic interest rate shifts and global supply chain disruptions sit largely outside a developer's control, project definition and developmental discipline remain entirely manageable. Even amid external volatility, a project designed with resilience will have a far greater likelihood of success.
Independent review and assurance directly strengthen a project’s chance of success and overall value. Large global project delivery organizations have applied this discipline for decades by deploying independent teams to evaluate project readiness at every stage gate. For teams lacking a dedicated internal oversight organization, or those deploying first-of-a-kind facilities, third-party independent review provides the necessary rigor to facilitate project success.
Relae’s (formerly Carbon Direct) work with Stockholm Exergi is a clear example: independent assurance helped build funder and regulator confidence in a first-of-a-kind carbon removal facility with no direct precedent to benchmark against.
Why Projects Stall Between Announcement and FID
Low-carbon infrastructure and net-zero industrial projects carry unique risks compared to the repeat delivery of established designs. Exciting new developments run a higher risk of falling victim to optimism bias or compressing development timelines to meet public announcement milestones.
It is a natural human tendency for project champions to focus on the upside during early development. However, early momentum must be balanced with processes that reintroduce industrial lessons, supply-chain realities, and operational resilience.
Front-End Loading (FEL) is a well-evidenced approach for improving capital project outcomes. Decades of benchmarking by Independent Project Analysis (IPA) show that approximately two-thirds of industrial megaprojects suffer capital cost overruns or schedule slippage of 25% or more, or encounter severe operational problems lasting more than two years post-startup. This pattern is repeating in low-carbon infrastructure: IPA’s analysis of 12 completed low-carbon projects found average cost escalation of 31% and schedule slip of almost 50%. Rigorous front-end definition remains the single strongest predictor of whether a project will achieve its cost and schedule targets.
As highlighted in the CDR 2.0: Five Pillars of Successful Project Deployment and Delivery report published by Relae, projects falter when developers push ahead without stress-testing the full delivery framework. Stage gate reviews are the mechanisms that evaluate the total project concept and underlying business case. They are most effective when executed as independent cold-eye evaluations prior to each funding gate, identifying and mitigating vulnerabilities long before final investment decisions are reached.
What Funders Need to See at Each Gate
Different stages of project development rely on distinct capital sources, each requiring specific proof points before deploying funds.
Before FEED Funding: Justifying the Engineering Spend
Front-End Engineering Design (FEED) is a major financial commitment, typically costing between 2% and 4% of total project capital cost. The funders backing this stage are usually the developer’s own balance sheet equity, strategic partners, or public grant programs. Before allocating millions of dollars to detailed engineering, these funders need confidence on the fundamentals:
- A technically sound process concept, confirmed utility balances, and an energy integration scheme that fits the site.
- Secured site control, clear zoning pathways, and no environmental fatal flaws that could derail permitting.
- Documented availability of required feedstocks, water and power, paired with demonstrable interest from target off-takers.
Before FID: Proving Bankability and Commercial Closure
As a project approaches FID, the funding audience shifts to conservative commercial lenders, infrastructure funds, and binding offtake counterparties. These capital providers are not underwriting strategic vision; they are underwriting long-term operational cash flows and debt service. Depending on the project and financing structure, capital providers may require:
- A high-confidence capital cost estimate (AACE Class 2 or Class 3) backed by frozen Piping and Instrumentation Diagrams (P&IDs), firm equipment quotes, and a realistic execution schedule with clear critical paths.
- Bankable engineering, procurement, and construction (EPC) structures that clearly allocate risk, include performance guarantees and enforceable liquidated damages.
- Fully executed, binding offtake and feedstock agreements, along with non-appealable permits and completed utility interconnection agreements, with remaining conditions clearly understood.
- An objective, third-party challenge review that assesses operational viability and distinguishes an executable engineering plan from an aspirational concept.
Commercial and Technical Co-Development: The Stage-Gate Method in Practice
A project rarely fails because of an isolated mechanical issue or a purely commercial misstep; failure happens when technical decisions and commercial terms are negotiated in silos and decisions are made without understanding of the wider implications.
We see this disconnect play out in several ways, including:
- Sizing capacity before testing market demand: An engineering team may size a facility to maximize thermodynamic efficiency and economies of scale, only for the commercial team to discover buyers will only commit to half that volume. The developer is left with an oversized, unbankable design requiring fundamental rework.
- Setting product specifications before negotiating offtake: Process engineers frequently design systems around standard vendor packages. However, when downstream transport, processing, or storage networks enforce strict purity standards, the facility faces costly equipment redesigns. This issue has materialized directly within European CCS networks. Open-access offshore storage operators, such as Norway's Northern Lights project, established strict cross-border CO2 specifications requiring tighter moisture and impurity thresholds than originally designed for.
- Locking Electrical Loads Prior to Interconnection Verification: As detailed in Relae’s analysis of physical infrastructure bottlenecks, scale is rarely constrained by capital availability; it is dictated by electrical transmission queues, substation headroom, and 24/7 firm power availability. Freezing electrical demand before verifying utility interconnection timelines risks stranding engineering work on an asset that cannot connect to the grid.
How Relae Stress Tests Projects at Each Gate
Independent reviews at each stage-gate improve success rates by stress-testing assumptions before presenting to lenders, infrastructure investors, or corporate buyers. Relae reviews projects across five categories using the TECOP framework:
- Technical: Verifying technology readiness levels (TRL), mass and energy balances, plot plan constructability, and operational availability under real-world conditions.
- Economic: Capex benchmarking, operating contingency adequacy, utility tariff sensitivities, and financial model cash-flow resilience.
- Commercial: Offtake agreement structures, feedstock contracts, contracting boundaries, EPC contract structures, and counterparty creditworthiness.
- Organizational: Owner's team capabilities, internal stage-gate governance, contractor oversight mechanisms, and execution capabilities.
- Political: Statutory permitting status, regulatory durability, carbon market policy exposure, and local community social license.
The TECOP framework is relevant for evaluating delivery risk across all project types, see more in Relae’s Criteria for High-Quality Carbon Dioxide Removal, Delivery Risk Appendix.
What makes this approach effective is sitting on both sides of the table. Having completed over 250 deep-dive technology reviews, 900+ project evaluations, and advised on more than $6 billion in industrial project finance, Relae has extensive experience evaluating the considerations important to institutional funders and buyers.
The Value of Early Independent Project AssuranceIncorporating independent review should be standard practice for modern infrastructure delivery. Because funders will perform their own rigorous diligence regardless, conducting an independent evaluation early enables developers to address vulnerabilities proactively and present a more resilient business case.
Commissioning an independent team for a cold-eye review during early project formation can be a cost-effective way to identify potential risks before they become expensive to address. Catching an unworkable process assumption, an oversized capacity plan, or a misaligned commercial interface during pre-FEED costs a tiny fraction of what it takes to fix those issues during construction
Ultimately, independent challenge is not an admission of doubt, but the disciplined stage-gate practice that protects capital by reconciling technical reality with commercial terms before designs are locked, signaling to partners, and your future funders that your project is built to deliver.
To dive deeper into the frameworks that support successful projects, read Relae's white paper: CDR 2.0: Five Pillars of Successful Project Deployment and Delivery and take a look at project assurance in action through our Stockholm Exergi Case Study.
Frequently Asked Questions
What is independent project assurance?
Independent project assurance is a structured review of a capital project by a team that sits outside the project’s delivery organization. Reviewers test the engineering scope, cost estimate, schedule, commercial agreements and permitting position against what funders will require at the next stage gate. The developer receives a clear list of gaps, risks and proposed mitigations prior to presenting the project to lenders, investors or buyers.
When should a developer commission an independent project review?
Periodically throughout the project development process - at a minimum before each major funding gate, but smaller reviews are also beneficial at earlier stages when key concept and technology decisions are being made. A review before Front-End Engineering Design (FEED) tests whether the process concept, site and supply of feedstock, water and power justify the engineering spend. A review before Final Investment Decision (FID) tests whether the cost estimate, EPC structure and binding agreements will satisfy lenders. Site, technology and capacity decisions are cheap to change in pre-FEED and expensive to reverse once detailed engineering starts.
What does an independent project review assess?
Relae structures its reviews around the TECOP framework, which covers five risk areas: technical (technology readiness, mass and energy balances, constructability), economic (capex benchmarking, contingency, financial model resilience), commercial (offtake, feedstock and EPC contracts), organizational (owner’s team capability and stage-gate governance) and political (permitting, regulatory durability and social license). Reviewers also check that technical and commercial decisions are aligned, because projects often fail where the two are developed in silos.
How does an independent project review differ from lender due diligence?
An independent project review applies a holistic approach identifying not only gaps, but also opportunities to add value and strengthen the business case. Lender and investor due diligence is often purely looking at risks and gaps, prior to committing capital. Lender diligence protects the funder and reports its findings at a point when changes are costly and can delay financial close. A developer-commissioned review takes place earlier, so the project team can fix weaknesses in scope, cost or contracts before funders see them.