



The Relae Blog
Original insights from the Relae team on the forces reshaping power systems, GHG emissions, environmental markets, nature, and the capital and policies behind them.
Low-Carbon Fuels Under RED: Why Quality Can Differ and How Buyers Can Look Beyond the Certificate
Key Takeaways
- The EU Renewable Energy Directive (RED III) sets the sustainability rules behind clean fuel markets in Europe, and frameworks in the UK and US draw on it. Producers typically show compliance through certification schemes recognized by the European Commission, such as ISCC and RSB.
- Certification provides evidence that a fuel meets the regulatory minimum, but schemes apply RED differently, particularly on topics like social outcomes and leakage. As a result, two compliant fuels can differ in quality.
- Relae’s Criteria for High-Quality Low Carbon Fuels give buyers a single benchmark for assessing quality beyond compliance. By comparing a producer’s certificate against the criteria, buyers can identify gaps and develop contract provisions on quality areas the certificate does not cover, tailored to their own priorities. This can help buyers identify and manage quality risk and stay ahead of tighter regulations likely to come under RED IV.
RED Sets the Bar for Clean Fuels in Europe and Beyond
RED III is a key regulatory framework governing sustainability requirements for clean fuels. Its sustainability criteria underpin Europe’s clean fuels markets, including sustainable aviation fuel (SAF) under ReFuelEU Aviation, marine biofuels under FuelEU Maritime, and biomethane injected into Europe’s gas grid. Its reach extends beyond the EU, too. The UK Renewable Transport Fuel Obligation and SAF Mandate apply sustainability criteria modeled on RED, and the certification schemes built around RED will play a role in California’s new feedstock sustainability requirements under its Low Carbon Fuel Standard.
A Certificate Confirms Compliance, Not Quality
Low-carbon fuel producers typically demonstrate compliance with RED through voluntary certification schemes recognized by the European Commission, such as the International Sustainability & Carbon Certification (ISCC) and the Roundtable on Sustainable Biomaterials (RSB). A certificate provides evidence that a fuel clears the regulatory bar. Every recognized certification scheme covers RED’s core requirements, but each applies them differently, and some go further than others.
How Certification Schemes Can Differ
Certification schemes tend to differ most on questions RED only partly addresses. Social outcomes are one example. RED largely requires certified producers to comply with the laws of the country where the feedstock is grown or the fuel is produced. Following local law, however, is not the same as paying living wages, respecting land rights, or delivering benefits to nearby communities, especially where local protections are weaker than the EU’s. Some schemes fill that gap with their own social requirements; and others do less.
Leakage is another example. It refers to emissions a fuel causes outside its own supply chain, which its carbon intensity does not reflect. One common form is indirect land-use change (ILUC). When cropland or feedstock is redirected to fuel production, the food, feed, or other uses it previously supplied still need to be met elsewhere. That can push cropland expansion into forests or grasslands, releasing the carbon they store. RED manages this risk by limiting the use of feedstocks most associated with expansion into high-carbon-stock land. However, RED acknowledges that ILUC is not limited to these high-risk feedstocks, and diverting waste feedstocks from existing uses can have similar knock-on effects. Without asking specific questions about a given producer’s supply chain, buyers may have limited visibility into the leakage risk behind the fuel they buy.
These examples show that, on paper, two RED-compliant fuels can look the same while differing significantly in overall quality. One reason is that they can be certified under schemes with different requirements on issues such as social outcomes. Another is that RED is built to work at scale, applying a consistent set of rules across the whole market. That consistency is a strength, but it means that some issues, such as leakage, are addressed at the system level rather than for each individual fuel. For buyers, the certificate is a useful starting point for offtake conversations, but may not be enough on its own to judge the quality of what they are buying.
Assessing Quality Beyond Compliance
So how can a buyer tell whether one certified fuel is higher quality than another? Today, doing so means comparing certification schemes rule-by-rule, which is cumbersome. Relae’s Criteria for High-Quality Low Carbon Fuels provides a shared definition for what “better than compliant” means. It brings together requirements from RED, CORSIA, ISCC, RSB, national SAF mandates, and other frameworks into a single benchmark, and adds criteria on social outcomes, additionality, and leakage. We built the criteria for voluntary buyers, but they are just as useful for regulated companies that want to go beyond meeting their mandates and show how well they do it.
How Buyers Can Apply the Criteria, and How Relae Can Help
In practice, buyers can use Relae’s criteria in four steps. Each one calls for technical judgment on scheme rules, supply chains, and contract terms. Relae’s fuels team works alongside buyers at every stage, from the first certificate review to the final offtake terms.
- Start with the certificate. Confirm which scheme the fuel is certified under, what the certificate covers, and whether the producer holds any optional add-ons, such as a low ILUC risk certification. Our team reviews certificates and the scheme rules behind them to confirm what is and is not covered.
- Map the certificate against Relae’s quality criteria. Sort each criterion into what the certificate already covers, what it partly covers, and what it does not address. Our experts carry out this mapping for a specific fuel and pathway and highlight the gaps that matter most.
- Ask the producer to fill the gaps. Turn each gap into a direct question, for example, how the producer verifies wages and land rights in its supply chain, or how it manages ILUC risk. The answers help buyers see where quality risks may lie that compliance alone does not cover. We help prepare these questions and assess the producer’s responses and evidence.
- Build the answers into an offtake agreement. Use the answers to develop contract provisions on quality that the certification does not cover, such as additional verification, disclosure, or feedstock-sourcing requirements. These provisions help buyers manage quality risks over the life of the deal, whether it’s a SAF offtake agreement or another fuel supply contract, and support the sustainability claims they make about the fuel. Our fuels experts work with buyers and their counsel to shape these provisions.
Procuring for Where Standards Are Heading
The criteria are also a guide to what may come next. The European Commission is preparing its post-2030 renewable energy framework (RED IV). The Commission held a public consultation from March to June 2026, and plans to propose legislation by the end of the year. The final scope is not yet known, but industry submissions point to areas where bioenergy rules could tighten, such as stricter traceability and on-site audits for imported waste feedstocks. Buyers who procure against where standards are heading, not just today’s minimum, will be less exposed when the rules change and better able to back up the sustainability claims they make about their fuel.
[cta]
Frequently Asked Questions
What is RED III?
RED III is the current version of the EU Renewable Energy Directive. It sets renewable energy targets and the sustainability criteria that biofuels, biogas, and other renewable fuels must meet to count under EU regulations. Those criteria apply across Europe’s clean fuel markets, including SAF under ReFuelEU Aviation and marine fuels under FuelEU Maritime.
How do producers show their fuel complies with RED?
Most producers use a voluntary certification scheme recognized by the European Commission, such as ISCC or RSB. The scheme audits the producer and its supply chain against RED’s requirements and issues a certificate if they are met.
Are all RED-recognized certification schemes the same?
No. Every recognized scheme covers RED’s core requirements, but each applies them differently, and some add requirements or optional add-ons of their own. Certification schemes differ the most on issues RED only partly addresses, such as social outcomes and leakage. As a result, two RED-compliant fuels can differ in overall quality.
Who should use the Relae Criteria for High-Quality Low Carbon Fuels?
We designed the Criteria for High-Quality Low Carbon Fuels for voluntary buyers, but they are equally useful for regulated companies. Buyers can compare a producer’s certificate against the criteria to find gaps, raise those gaps in offtake discussions, and address them through contract provisions. Relae works with both voluntary and compliance buyers to apply the criteria to specific fuels and deals, from assessing producers to shaping offtake terms.
What is RED IV, and why does it matter for buyers today?
RED IV is the post-2030 renewable energy framework the European Commission is preparing. The Commission consulted on it from March to June 2026, and plans to propose legislation by the end of 2026. Sustainability rules for bioenergy could tighten. Buyers who procure against where standards are heading, rather than today’s minimum, will be less exposed when the rules change.
Article 6.4: A New Opportunity for Cement Decarbonization
Key Takeaways
- Carbon credits are one of several instruments for decarbonizing cement, alongside environmental attribute certificates (EACs) and direct procurement of lower-carbon products. Each serves a different purpose, and buyers and developers should understand how they interact before engaging.
- Article 6.4 of the Paris Agreement is becoming a reference point for public and private carbon credit procurement, so the quality of its methodologies now holds significant weight.
- Proposed methodology A6.4-PMM010 - Partial substitution of fossil fuels by MSW in cement manufacture largely aligns with Relae and Microsoft’s Criteria for High-Quality EACs in the Concrete and Steel Sectors. However, Relae identified opportunities to strengthen provisions addressing interactions between carbon credits and environmental product declaration (EDP), where credited reductions are deducted from the product's EPD, with the aim of reducing the risk of the same mitigation being claimed more than once.
Article 6.4 Joins the Cement Decarbonization Toolkit
Article 6.4 of the Paris Agreement is expanding the financing options for decarbonizing cement and concrete. Environmental attribute certificates (EACs) let buyers pay for lower-carbon production without taking physical delivery of the product, while carbon credit methodologies reward manufacturers for storing captured CO2 in their products.
Relae is actively shaping this market: conducting technical diligence for buyers of cement EACs, providing project assurance and go-to-market support for industrial decarbonization projects, and leading market development through the publication of the Criteria for High-Quality EACs in the Concrete and Steel Sectors, in collaboration with Microsoft.
To build on these efforts, Relae (as Carbon Direct) recently participated in the public consultation for a proposed carbon credit methodology under the Paris Agreement Crediting Mechanism (PACM). Methodology A6.4-PMM010 would credit emissions reductions from replacing fossil fuels with municipal solid waste (MSW) in the production of cement clinker. The approach was proposed by the Inter-American Cement Federation (FICEM), which in 2026 partnered with the UN Industrial Development Organization to work to decarbonize the sector across Latin America.
The PACM, established under Article 6.4 of the Paris Agreement, could underpin national climate strategies and voluntary offsetting demand for years to come. One potential avenue of influence is the SBTi Corporate Net Zero Standard V2.0, which has introduced formal recognition of market-based instruments. As both public and private entities weigh their carbon credit procurement options, this is a critical juncture for getting the methodologies right.
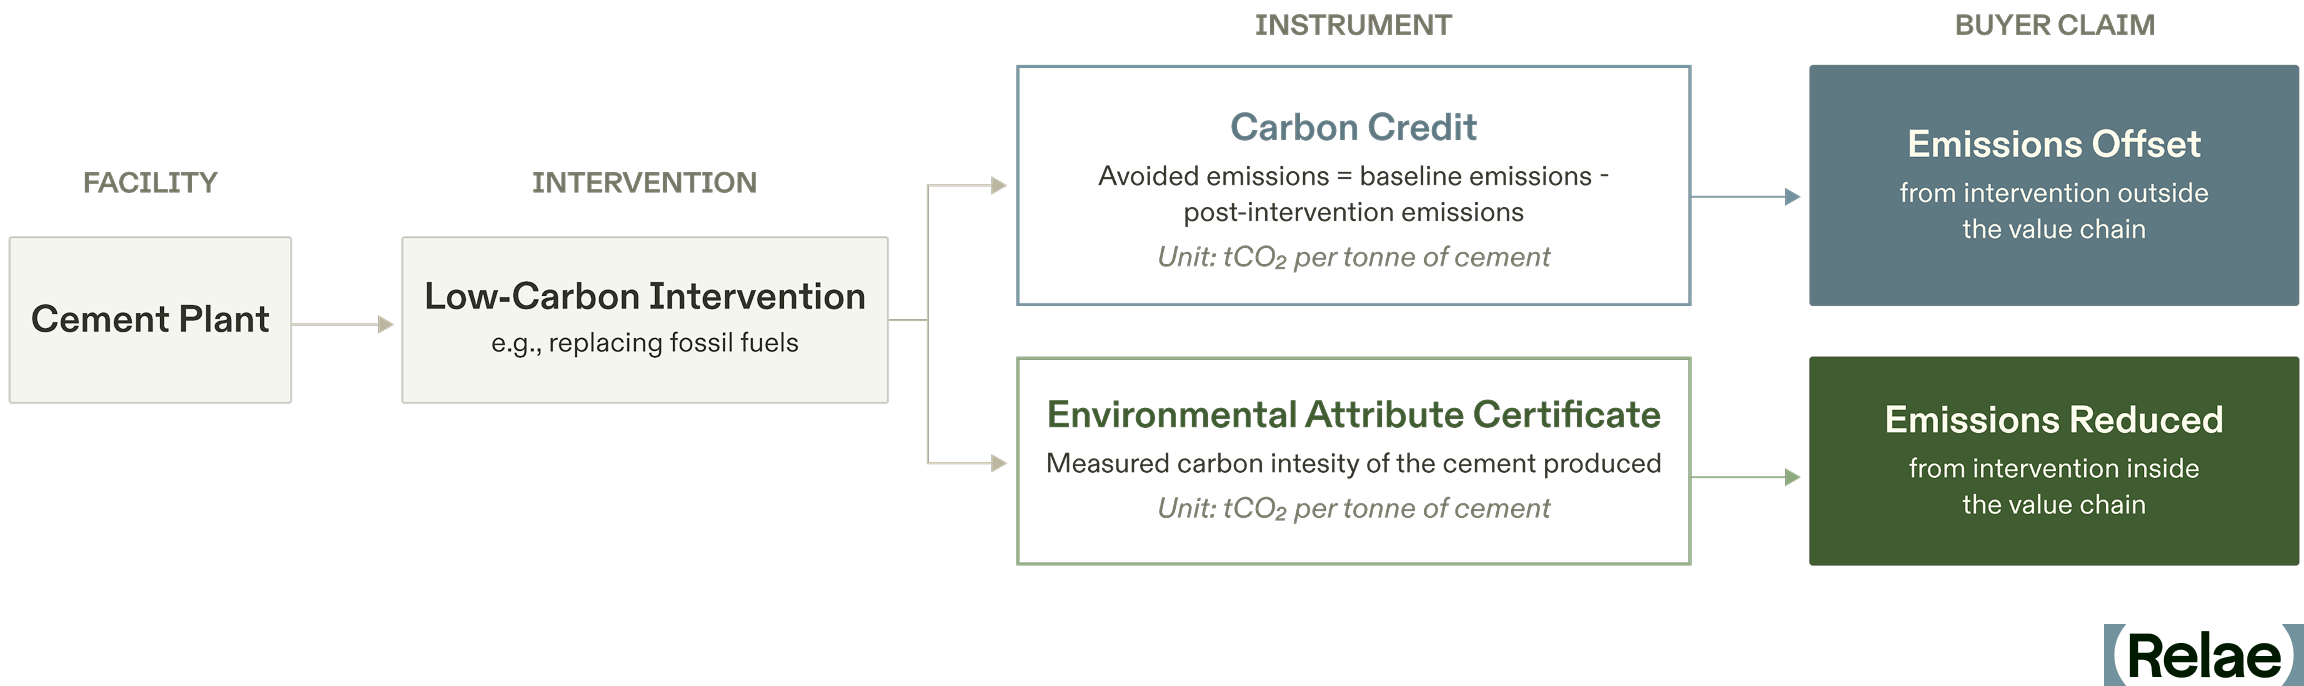
Two Key Options for Decarbonizing Cement: Carbon Credits and EACs
Concrete and steel are indispensable to modern construction and together account for approximately 13% of global CO2 emissions. With demand for infrastructure continuing to rise, including via data centers, decarbonizing these sectors is essential for new construction to remain consistent with climate commitments.
Carbon credits are one route to financing that work. A credit is issued for each tonne of emissions reduced below a baseline, meaning the emissions that would have occurred without the intervention. For a cement plant, credits might be issued for switching to low-carbon fuels or installing new equipment that reduces emissions. Companies buy credits to offset emissions outside their own value chains, and in doing so channel finance to projects that would not otherwise proceed.
EACs are a second route, and one that Relae is helping to shape. An EAC assigns a measured environmental characteristic to a unit of product (e.g., tonnes of CO2 per tonne of cement), usually established through an attributional life cycle assessment. The buyer pays for the lower-carbon attribute of a product and reports it against its own value chain emissions, which makes EACs a tool for scope 3 decarbonization rather than for offsetting.
While methodology A6.4-PMM010 is for carbon credits, we use the Relae EAC criteria as our reference point, as both instruments depend on the same foundations. An intervention must be traceable to a specific facility, the carbon impact must be quantifiable with a defensible method, and the project must be assessed for its social and environmental harms and benefits. The criteria set out in depth how Relae tests those foundations for an EAC claim, and the same tests apply with little adjustment to a crediting methodology.
Regardless of the preferred market instrument, replacing fossil fuels in cement production should be read as a partial solution. Kiln fuel combustion accounts for roughly 35% of the CO₂ emitted in clinker production, while the remaining 65% arises from process emissions inherent to calcination: when the heated limestone breaks down into lime and releases CO2 as a byproduct. As such, Relae considers this as part of a multi-step decarbonization strategy that should ultimately address calcination emissions through carbon capture, novel binders, or substitution of the clinker itself.
Why the PACM Matters for Carbon Credit Buyers
While there is a lack of supply today, PACM credits have the potential to underpin carbon credit demand. Corporate buyers looking to make recognized offsetting claims have reason to favor units issued under a government-endorsed UNFCCC mechanism. The European Climate Law references Article 6.4 quality standards, and the EU is expected to tie the eligibility of procured international credits to its methodologies. The German federal government has used UN-recognized credits to offset its business travel emissions since 2014, and UK government agencies have also sought PACM credits to fulfill their offsetting needs.
A strength of the PACM is its centralized structure. The 12-person Supervisory Body (SB) makes all final approvals, following methodology recommendations from the Methodological Expert Panel (MEP). All methodologies draw on the same Article 6.4 standards and tools. For example, A6.4-PMM010 relies heavily on the Standard on Baselines and the Tool on Emissions from Solid Waste Disposal Sites. Together, these can be used to calculate the counterfactual emissions from waste diverted from landfill, and dictate how to monitor waste conditions over the crediting period.
The potential for the PACM to scale is conditional. As the market matures, voluntary buyers can choose from a widening range of high-quality carbon credits. Moreover, the European Commission has shown, via its criticism of CORSIA, that the EU will make robust efforts to prohibit procurement from projects it considers flawed. As such, the PACM will only succeed if it provides compelling methodologies to accompany solid governance. That is the standard against which Relae reviewed the fossil fuel substitution methodology.
Relae’s Response to the Cement Methodology A6.4-PMM010
Alignment With Our High-Quality Criteria
We found methodology A6.4-PMM010 for carbon credits to largely align with our high-quality criteria. Certain gaps in the methodology are addressed by the Article 6.4 standards and tools it references, and the combination provides additional safeguards intended to support robust integrity.
In both the methodology and our criteria, additionality must be shown on regulatory, financial, and common practice grounds. Crediting is limited to the capacity installed at validation, so carbon finance improves existing production rather than funding new clinker capacity, which aligns with our catalytic impact criterion. The methodology also credits both displaced fossil fuel and avoided landfill methane, a dual benefit that strengthens the case for these projects, especially where landfill sites are poorly managed (e.g., do not flare methane).
We proposed only two major refinements: updating the landfill methane baseline at each verification, and closing the double-counting gap with environmental product declarations (EPDs).
Landfill Methane Baseline
Under Article 6.4, an independent verifier checks a project’s reported results for each monitoring period before new credits are issued. Relae proposed that the landfill methane baseline be re-established at each of these verifications: from site measurements where available, and by re-selecting the default value to match current conditions where they are not.
The baseline rests on two factors that can shift as a waste disposal site is capped, compacted, or drained: the oxidation factor (the share of methane absorbed by landfill cover before release), and the methane correction factor (how much of the waste decomposes without oxygen).
The Article 6.4 Tool on Emissions from Solid Waste Disposal Sites offers measured and default routes for setting these values, but the methodology does not specify which applies. A project developer could apply default values from the tool and leave them static for the whole crediting period. Re-selecting those values at each verification, rather than locking them in at the outset, keeps the baseline tied to how the site is actually performing throughout its crediting period.
Double-Counting Concerns
The Article 6.4 Activity Standard rightly requires that issued credits do not overlap with other emissions mitigation crediting schemes. However, the A6.4-PMM010 does not explicitly say how that applies to EPDs, which report a cement product's carbon intensity. Relae proposed closing that gap directly: the EPD should report the new, lower carbon intensity achieved after the intervention without subtracting the avoided emissions again. The methodology should also require an annual declaration confirming that the credit and the EPD aren’t claiming the same reduction twice.
An EPD reports a cement product’s carbon intensity, so a lower-carbon cement can earn value in two places at once: through the carbon credit, and through the EPD itself, which is exactly where the double-counting risk sits. EPD standards already keep the avoided emissions out of a product’s carbon intensity, reporting them separately from the product’s life-cycle stages, but A6.4-PMM010 never references that separation.
Explicitly addressing this distinction in the methodology, and pairing it with Relae’s proposed annual declaration, could strengthen transparency and reduce the risk of overlapping claims associated with the same emissions reductions, where the same emissions reduction can’t be claimed once through the credit and again through the product’s own carbon footprint.
How Relae Can Help
A6.4-PMM010 is a well-designed methodology, but market-based mechanisms for enabling cement decarbonization are evolving faster than practical guidance on how to use them credibly. Relae works with buyers and cement producers navigating this landscape. For buyers, we conduct technical due diligence, advise on procurement strategy, and guide robust claims. For producers and project developers, we assess which market-based mechanism suits a given plant and provide the analytical, market intelligence, and go-to-market support needed to monetize the chosen mechanisms credibly.
Frequently Asked Questions
What is the difference between a carbon credit and an Environmental Attribute Certificate (EAC)?
A carbon credit represents one tonne of emissions reduced below a baseline, and a buyer uses it to offset emissions outside their value chain. An EAC attaches a measured carbon attribute to a unit of product, such as cement, which the buyer reports against its own scope 3 emissions rather than for offsetting.
What is the relationship between Article 6.4 of the Paris Agreement and the Paris Agreement Crediting Mechanism (PACM)?
Article 6.4 of the Paris Agreement establishes the PACM, which refers to the registry itself along with the methodologies, standards, and tools that govern the credits listed on it. Article 6.4 is the treaty provision, and PACM is the mechanism built under it, so people often use the two terms interchangeably.
How do PACM credits differ from other credits available on the voluntary carbon market (VCM)?
PACM methodologies and standards are developed through a transparent UNFCCC process, which sets them apart from most VCM credits. This does not make PACM credits inherently higher quality, but some buyers, especially governments, prefer to tie procurement to PACM standards. Another key difference is that 7% of PACM credits are deducted at issuance–5% are transferred to the UN Adaptation Fund, and 2% are cancelled for overall mitigation.
The New Nasdaq Issuance Calendar Advances Transparency in the Carbon Removal Market
Key Takeaways
- The Nasdaq Carbon Issuance Calendar, a new data platform, provides carbon removal buyers and suppliers with standardized information on future offtake availability, indicative pricing, and project maturity. The platform was developed in collaboration with Relae, formerly Carbon Direct.
- The Carbon Issuance Calendar addresses the fragmentation and transparency problems of the voluntary carbon market by centralizing standardized project data and embedding our scientific diligence framework, built over 900 project reviews, giving buyers delivery-risk insight that no registry or marketplace offers today.
- The Carbon Issuance Calendar is an important early step, not the whole journey: it shows buyers what durable tonnes exist and allows them to compare projects with apples-to-apples data.
- Buyers can move from the Carbon Issuance Calendar into technical diligence, contracting, and project assurance with Relae’s advisory team. Suppliers can register to connect with buyers who are ready to engage.
Carbon Removal Project Data Has a Visibility Problem
If you're sourcing durable carbon removal credits, you may run into a familiar wall: project data scattered across dozens of developer websites, presented in inconsistent formats, with no easy way to compare one project against another. If you're a project developer, you face the mirror image of that problem: fielding individual requests for proposals, with no central place to showcase your available tonnes.
Get this wrong, and buyers may end up counting on carbon removal that never shows up - the delivery risk bugbear.
Between 2022 and 2024, high-durability engineered carbon removal made up just 2 percent of all carbon credit issuances. They remain in short supply, particularly the high-quality supply corporate buyers need. The gap is set to widen: our 2026 State of the Voluntary Carbon Market report found that more than 80% of the 2030 high-durability carbon removal projects are at risk of stalling and failing without additional offtake and financing commitments.
The Nasdaq Carbon Issuance Calendar, developed by Nasdaq in collaboration with Relae, offers an important first step toward addressing this information gap.
What Is the Nasdaq Carbon Issuance Calendar?
The Carbon Issuance Calendar is a centralized, accessible dashboard where carbon removal buyers and suppliers view standardized project data: future credit availability, indicative pricing, and project delivery status, all in one place.
The Nasdaq Carbon Issuance Calendar combines structured, developer-provided project data with project maturity assessment informed by Relae’s assessment framework and technical diligence. This helps users understand future CDR availability, indicative pricing, and potential project delivery risk through a single platform.
This expertise didn't appear overnight. It comes from sitting across the table with developers, stress-testing their science, mapping their delivery timelines against reality, and helping them show up to buyers as credible partners. The result is a track record that gives the framework embedded in the Carbon Issuance Calendar its depth. It's a starting point, built for buyers and suppliers to find each other on the basis of consistent, comparable information, using international class financial and information infrastructure.
How Buyers Should Use the Nasdaq Carbon Issuance Calendar
Today, if you're trying to procure durable carbon removal credits, you have no single place to start. You have to visit individual developer sites, request information through scattered channels, and compare projects that present data in entirely different formats before diligence has even begun. In many cases, you are comparing apples to oranges - different kinds of CDR projects with different durabilities, risks, and overall quality.
The Carbon Issuance Calendar provides a central starting point. You can view future credit availability, compare indicative pricing across projects, and begin assessing options without contacting each supplier one by one.
More importantly, the Carbon Issuance Calendar frames the data. Our scientists developed a delivery-oriented lens, built from reviewing over 900 carbon removal projects, drawing on the same rigor behind our Criteria for High-Quality Carbon Dioxide Removal, which we develop annually with Microsoft.
How Suppliers Reach Buyers Through the Carbon Issuance Calendar
If you're a project developer, the Nasdaq Carbon Issuance Calendar tackles visibility, one of the most persistent barriers to market access. You can list available tonnes, display indicative pricing, and reach a global audience of corporate and financial buyers at no cost.
The timing matters. Many first-of-a-kind engineered carbon removal projects are preparing to break ground and need bankable offtake agreements to secure financing before they can do so (a key aspect of CDR 2.0). Our analysis of approximately 140 high-durability carbon removal project developers found scale-up plans for 30 million tonnes of supply per year. Reaching that potential will take real demand: committed forward offtake, increased project equity investment, and access to lending.
Register now: you'll be positioned to connect to buyers actively looking to engage.
How Does the Carbon Issuance Calendar Differ From a Carbon Credit Registry or Carbon Removal Marketplace?
The Carbon Issuance Calendar solves a distinct, early-stage problem. It gives buyers and suppliers a centralized place to find each other and compare options against standardized information, something neither a registry nor a marketplace is built to do.
For a closer look at how registries differ and what you should weigh when navigating them, read our Navigating Carbon Credit Registries report.
Scientific Diligence Turns Visibility Into Confidence
Standardized data tells you what exists. Scientific diligence tells you what's worth pursuing.
Relae’s scientists do that work every day. Our experts apply rigorous pathway-specific criteria to live projects, evaluating delivery risk and status, and identifying where questions remain is the core of what we bring to the carbon removal market.
The Carbon Issuance Calendar puts an accessible version of that expertise at the top of the procurement funnel. It’s for everyone in the market - you don't need to be a carbon removal scientist to use it. This snapshot allows you to compare projects against each other, giving you a meaningful starting point before deeper diligence begins.
Want to go deeper on a specific project? Relae’s technical diligence team picks up right where the Carbon Issuance Calendar leaves off.
What Carbon Removal Projects Are on the Carbon Issuance Calendar Today?
The Carbon Issuance Calendar currently features engineered and hybrid carbon removal projects: direct air capture, biochar, enhanced rock weathering, and bioenergy with carbon capture and storage. These high-durability pathways offer permanence on the order of hundreds to thousands of years.
Many of these projects are at an inflection point: they’re ready to scale but dependent on committed offtake to unlock financing. The Calendar serves their needs, and the buyer’s needs, together.
Nature-based carbon removals have their own criteria and market dynamics. They may appear in a separate segment of the Carbon Issuance Calendar down the line.
From the Carbon Issuance Calendar to Completed Carbon Removal Procurement
If you're building or refining a carbon removal procurement strategy, the Carbon Issuance Calendar is the right place to start.
From there, you can choose to work with the Relae advisory team to support every later stage: technical diligence on specific projects, contracting and negotiation support, ongoing project assurance, and access to curated carbon credit sourcing. The Carbon Issuance Calendar surfaces the market; we help you navigate it, connecting you with the right developers, on the right terms, with the scientific confidence to move forward.
Moving from commitment to delivery takes structural change across the market, too—our CDR 2.0 white paper lays out the five pillars we see as essential to getting engineered and hybrid carbon removal projects built and delivering.
Independent Project Assurance Is Likely Your Best-Returning Spend
Key Takeaways
- The decision to fund a project is determined by a holistic review of project development maturity. This applies across capital-intensive projects, including low-carbon power generation, carbon capture and storage (CCS) solutions, sustainable aviation fuel (SAF), and broader transition infrastructure build-out. Both technical and commercial workstreams must be developed in parallel to avoid project failure.
- Early scope decisions, such as site selection, core technology selection, and nameplate capacity, are cheap to make but become exponentially disruptive and costly to reverse.
- Independent challenge and verification is tangible evidence of a disciplined, well-managed capital development process.
Bridging the Gap from Announcement to Delivery
Among project developers, a perception often persists: seeking external review signals a project in distress. In capital budgeting discussions, subjecting engineering scope and commercial assumptions to third-party interrogation can be misconstrued as a vote of no confidence in the primary delivery team.
In reality, the reverse is true. Across complex infrastructure, independent challenge is the disciplined stage-gate practice that protects capital by reconciling technical reality with commercial terms before designs are locked.
Independent Challenge Is a Sign of Strength, Not Doubt
Across capital projects, and in particular within emerging low-carbon industrial infrastructure, the gap between announced projects and delivered assets remains stark. Data from the Mission Possible Partnership’s Global Project Tracker reveals that fewer than 17% of announced commercial-scale clean industrial facilities worldwide have reached Final Investment Decision (FID) or commercial operations, leaving more than 800 major decarbonization projects stalled in front-end development.
The causes of developmental paralysis are multifaceted. While macroeconomic interest rate shifts and global supply chain disruptions sit largely outside a developer's control, project definition and developmental discipline remain entirely manageable. Even amid external volatility, a project designed with resilience will have a far greater likelihood of success.
Independent review and assurance directly strengthen a project’s chance of success and overall value. Large global project delivery organizations have applied this discipline for decades by deploying independent teams to evaluate project readiness at every stage gate. For teams lacking a dedicated internal oversight organization, or those deploying first-of-a-kind facilities, third-party independent review provides the necessary rigor to facilitate project success.
Relae’s (formerly Carbon Direct) work with Stockholm Exergi is a clear example: independent assurance helped build funder and regulator confidence in a first-of-a-kind carbon removal facility with no direct precedent to benchmark against.
Why Projects Stall Between Announcement and FID
Low-carbon infrastructure and net-zero industrial projects carry unique risks compared to the repeat delivery of established designs. Exciting new developments run a higher risk of falling victim to optimism bias or compressing development timelines to meet public announcement milestones.
It is a natural human tendency for project champions to focus on the upside during early development. However, early momentum must be balanced with processes that reintroduce industrial lessons, supply-chain realities, and operational resilience.
Front-End Loading (FEL) is a well-evidenced approach for improving capital project outcomes. Decades of benchmarking by Independent Project Analysis (IPA) show that approximately two-thirds of industrial megaprojects suffer capital cost overruns or schedule slippage of 25% or more, or encounter severe operational problems lasting more than two years post-startup. This pattern is repeating in low-carbon infrastructure: IPA’s analysis of 12 completed low-carbon projects found average cost escalation of 31% and schedule slip of almost 50%. Rigorous front-end definition remains the single strongest predictor of whether a project will achieve its cost and schedule targets.
As highlighted in the CDR 2.0: Five Pillars of Successful Project Deployment and Delivery report published by Relae, projects falter when developers push ahead without stress-testing the full delivery framework. Stage gate reviews are the mechanisms that evaluate the total project concept and underlying business case. They are most effective when executed as independent cold-eye evaluations prior to each funding gate, identifying and mitigating vulnerabilities long before final investment decisions are reached.
What Funders Need to See at Each Gate
Different stages of project development rely on distinct capital sources, each requiring specific proof points before deploying funds.
Before FEED Funding: Justifying the Engineering Spend
Front-End Engineering Design (FEED) is a major financial commitment, typically costing between 2% and 4% of total project capital cost. The funders backing this stage are usually the developer’s own balance sheet equity, strategic partners, or public grant programs. Before allocating millions of dollars to detailed engineering, these funders need confidence on the fundamentals:
- A technically sound process concept, confirmed utility balances, and an energy integration scheme that fits the site.
- Secured site control, clear zoning pathways, and no environmental fatal flaws that could derail permitting.
- Documented availability of required feedstocks, water and power, paired with demonstrable interest from target off-takers.
Before FID: Proving Bankability and Commercial Closure
As a project approaches FID, the funding audience shifts to conservative commercial lenders, infrastructure funds, and binding offtake counterparties. These capital providers are not underwriting strategic vision; they are underwriting long-term operational cash flows and debt service. Depending on the project and financing structure, capital providers may require:
- A high-confidence capital cost estimate (AACE Class 2 or Class 3) backed by frozen Piping and Instrumentation Diagrams (P&IDs), firm equipment quotes, and a realistic execution schedule with clear critical paths.
- Bankable engineering, procurement, and construction (EPC) structures that clearly allocate risk, include performance guarantees and enforceable liquidated damages.
- Fully executed, binding offtake and feedstock agreements, along with non-appealable permits and completed utility interconnection agreements, with remaining conditions clearly understood.
- An objective, third-party challenge review that assesses operational viability and distinguishes an executable engineering plan from an aspirational concept.
Commercial and Technical Co-Development: The Stage-Gate Method in Practice
A project rarely fails because of an isolated mechanical issue or a purely commercial misstep; failure happens when technical decisions and commercial terms are negotiated in silos and decisions are made without understanding of the wider implications.
We see this disconnect play out in several ways, including:
- Sizing capacity before testing market demand: An engineering team may size a facility to maximize thermodynamic efficiency and economies of scale, only for the commercial team to discover buyers will only commit to half that volume. The developer is left with an oversized, unbankable design requiring fundamental rework.
- Setting product specifications before negotiating offtake: Process engineers frequently design systems around standard vendor packages. However, when downstream transport, processing, or storage networks enforce strict purity standards, the facility faces costly equipment redesigns. This issue has materialized directly within European CCS networks. Open-access offshore storage operators, such as Norway's Northern Lights project, established strict cross-border CO2 specifications requiring tighter moisture and impurity thresholds than originally designed for.
- Locking Electrical Loads Prior to Interconnection Verification: As detailed in Relae’s analysis of physical infrastructure bottlenecks, scale is rarely constrained by capital availability; it is dictated by electrical transmission queues, substation headroom, and 24/7 firm power availability. Freezing electrical demand before verifying utility interconnection timelines risks stranding engineering work on an asset that cannot connect to the grid.
How Relae Stress Tests Projects at Each Gate
Independent reviews at each stage-gate improve success rates by stress-testing assumptions before presenting to lenders, infrastructure investors, or corporate buyers. Relae reviews projects across five categories using the TECOP framework:
- Technical: Verifying technology readiness levels (TRL), mass and energy balances, plot plan constructability, and operational availability under real-world conditions.
- Economic: Capex benchmarking, operating contingency adequacy, utility tariff sensitivities, and financial model cash-flow resilience.
- Commercial: Offtake agreement structures, feedstock contracts, contracting boundaries, EPC contract structures, and counterparty creditworthiness.
- Organizational: Owner's team capabilities, internal stage-gate governance, contractor oversight mechanisms, and execution capabilities.
- Political: Statutory permitting status, regulatory durability, carbon market policy exposure, and local community social license.
The TECOP framework is relevant for evaluating delivery risk across all project types, see more in Relae’s Criteria for High-Quality Carbon Dioxide Removal, Delivery Risk Appendix.
What makes this approach effective is sitting on both sides of the table. Having completed over 250 deep-dive technology reviews, 900+ project evaluations, and advised on more than $6 billion in industrial project finance, Relae has extensive experience evaluating the considerations important to institutional funders and buyers.
The Value of Early Independent Project AssuranceIncorporating independent review should be standard practice for modern infrastructure delivery. Because funders will perform their own rigorous diligence regardless, conducting an independent evaluation early enables developers to address vulnerabilities proactively and present a more resilient business case.
Commissioning an independent team for a cold-eye review during early project formation can be a cost-effective way to identify potential risks before they become expensive to address. Catching an unworkable process assumption, an oversized capacity plan, or a misaligned commercial interface during pre-FEED costs a tiny fraction of what it takes to fix those issues during construction
Ultimately, independent challenge is not an admission of doubt, but the disciplined stage-gate practice that protects capital by reconciling technical reality with commercial terms before designs are locked, signaling to partners, and your future funders that your project is built to deliver.
To dive deeper into the frameworks that support successful projects, read Relae's white paper: CDR 2.0: Five Pillars of Successful Project Deployment and Delivery and take a look at project assurance in action through our Stockholm Exergi Case Study.
Frequently Asked Questions
What is independent project assurance?
Independent project assurance is a structured review of a capital project by a team that sits outside the project’s delivery organization. Reviewers test the engineering scope, cost estimate, schedule, commercial agreements and permitting position against what funders will require at the next stage gate. The developer receives a clear list of gaps, risks and proposed mitigations prior to presenting the project to lenders, investors or buyers.
When should a developer commission an independent project review?
Periodically throughout the project development process - at a minimum before each major funding gate, but smaller reviews are also beneficial at earlier stages when key concept and technology decisions are being made. A review before Front-End Engineering Design (FEED) tests whether the process concept, site and supply of feedstock, water and power justify the engineering spend. A review before Final Investment Decision (FID) tests whether the cost estimate, EPC structure and binding agreements will satisfy lenders. Site, technology and capacity decisions are cheap to change in pre-FEED and expensive to reverse once detailed engineering starts.
What does an independent project review assess?
Relae structures its reviews around the TECOP framework, which covers five risk areas: technical (technology readiness, mass and energy balances, constructability), economic (capex benchmarking, contingency, financial model resilience), commercial (offtake, feedstock and EPC contracts), organizational (owner’s team capability and stage-gate governance) and political (permitting, regulatory durability and social license). Reviewers also check that technical and commercial decisions are aligned, because projects often fail where the two are developed in silos.
How does an independent project review differ from lender due diligence?
An independent project review applies a holistic approach identifying not only gaps, but also opportunities to add value and strengthen the business case. Lender and investor due diligence is often purely looking at risks and gaps, prior to committing capital. Lender diligence protects the funder and reports its findings at a point when changes are costly and can delay financial close. A developer-commissioned review takes place earlier, so the project team can fix weaknesses in scope, cost or contracts before funders see them.
Introducing the Diligence Collection: High-Quality Carbon Removal, Vetted
Key Takeaways
- Relae (formerly Carbon Direct) has conducted over 900 comprehensive, rigorous reviews of carbon removal (CDR) projects around the world. But fewer than 10% meet our standard for high-quality. In today’s market, scientifically-credible CDR supply is scarce.
- To identify high-quality projects, buyers and investors previously had to commission numerous deep diligences, which often made it a lengthy and complex process, not well-suited to most market participants.
- The Diligence Collection changes that paradigm by giving you direct access to existing comprehensive analysis on a curated set of high-quality CDR projects. The hard work of identifying high-quality projects is already done, allowing you to move faster, spend less, and procure with more confidence.
Relae Sets the Bar for High-Quality CDR
Since 2020, every year Relae has released an updated version of the Criteria for High-Quality Carbon Dioxide Removal in collaboration with Microsoft. The Criteria set the standard for scientific rigor across nine CDR pathways and across six technical dimensions. Using this standard, the Relae team has conducted diligence on over 900 CDR projects across 63 countries. Our diligence has been used for over 50% of all tonnes contracted through announced CDR offtake agreements worldwide, including diligence for the majority of tonnes from Microsoft’s announced offtakes. This gives Relae a uniquely deep understanding of the CDR market; and importantly, it has highlighted that high-quality projects in the voluntary carbon market are scarce.
Quality Is the Central Challenge in CDR Procurement
Only 10% of the projects that Relae has assessed meet our high-quality criteria. This means that without rigorous, scientific assessment, buyers and investors run real risk of exposing themselves to delivery shortfalls, financial loss, and reputational damage.
This presents a series of challenges to buyers and investors interested in procuring or investing in CDR. Conducting diligence on CDR projects is time-intensive, complex, and requires deep expertise. Building the internal capacity to rigorously evaluate a wide variety of CDR projects isn’t practical for most actors. But conducting the in-depth diligence required to procure or invest confidently requires real commitment, especially when a significant proportion of the projects diligenced may not be high-quality. Finding the needle in the CDR haystack isn’t easy.
The Case for Curated CDR
The Diligence Collection directly addresses these challenges by providing self-serve access to diligence on a curated set of high-quality CDR projects vetted by Relae. Every project has already been evaluated against the Criteria for High-Quality Carbon Dioxide Removal, the science-based benchmark jointly established by Relae in collaboration with Microsoft. The Collection includes projects reviewed on behalf of Microsoft and other major buyers, and more broadly reflects our diligence work across the market.
With the Diligence Collection, you're not starting from scratch. Instead, you're starting from a shortlist of some of the highest-quality CDR opportunities available, with robust scientific diligence to back them up. The bottleneck that's slowed procurement for so many organizations is no longer a concern.
The Collection offers two levels of diligence, matched to the level of scrutiny your commitment warrants:
- Desk review: An executive-level assessment using available project documentation, enough to make an informed shortlisting decision or purchase.
- Deep diligence: A comprehensive technical evaluation covering project design, operational risk, technology assessment, policy landscape, and community impacts, reflecting the same methodology that's informed the procurement programs of Microsoft and other major buyers.
Both tiers include the option to commission an updated evaluation as your needs evolve.
What Rigorous CDR Diligence Involves
The depth of Relae’s diligence sets the Diligence Collection apart. Our desk review process involves conducting detailed assessments to evaluate projects against 6 quality principles: social harms, benefits, and environmental justice; environmental harms and benefits; additionality and baselines; measurement, monitoring, reporting, and verification; durability; and leakage. The result is a comprehensive report that assesses projects against these criteria, highlighting the project's overall quality, strengths, and weaknesses in a clear, succinct way that supports decision-making.
Many of our reports dig even deeper. Our deep diligences assess both a project’s quality and its delivery risk. To evaluate delivery risk, we assess projects across 5 elements: technologic, economic, commercial, operational, and political. Deep diligence is conducted over 3-4 months, which includes weekly back-and-forth with the supplier and a site visit to understand all of the nuances of the project and validate developer claims on the ground. The resulting report not only documents a project's strengths and weaknesses, but also outlines risk mitigation measures and recommends improvements over time.
Broader Access, Stronger Market
Forward offtake demand in the CDR market has historically concentrated among a handful of large buyers, and as our 2026 State of the Voluntary Carbon Market report notes, diversifying that pool is essential to enabling the next generation of CDR supply. The Diligence Collection is built to support exactly that. By making the scientific rigor behind the world's largest CDR transactions available through a self-service platform, it opens credible procurement to organizations at any stage of purchasing. More buyers accessing high-quality, de-risked projects means more capital flowing to suppliers, more projects able to scale, and a more resilient market that doesn't depend on a small number of actors to function.
High-quality CDR supply is scarce, and the best projects are in high demand. The Diligence Collection gives you the foundation to act efficiently and with confidence, without starting from zero.
[cta]
Frequently Asked Questions
Who Can Access the Relae Diligence Collection?
The Diligence Collection is available to approved subscribers, including CDR buyers and investors seeking to more efficiently evaluate carbon removal projects. To preserve the independence and integrity of the Collection and protect proprietary diligence insights, access is not available to project developers or rating agencies.
How Is the Relae Diligence Collection Different From a Rating Agency or Market Intelligence Platform?
Most rating platforms optimize for quantity; we optimize for quality. Our process includes pathway-specific risk assessments and, in many cases, site visits from our in-house scientists, engineers, and technical experts—the same multidisciplinary team and judgment behind our own portfolio decisions and the procurement programs we support directly. The Collection also includes projects diligenced before they've received external ratings, giving you visibility into promising opportunities at the pre-commercialization stage.
Does Inclusion in the Relae Diligence Collection Mean Relae Endorses a Project?
Inclusion means a project was evaluated through our scientific diligence process and, at the time of review, met our Criteria for High-Quality Carbon Dioxide Removal. It reflects a positive diligence outcome based on the information available during the review and the project's stage of development at that time. As projects and market conditions evolve, we recommend considering whether updated diligence or additional evaluation is appropriate for your specific procurement or investment objectives.
Can I Request Diligence on a Project That Isn't Already in the Collection?
Yes. You can commission us to diligence a specific project based on your procurement or investment priorities. Whether it's later added to the Diligence Collection depends on a few factors beyond just meeting our quality bar, including consent from you as the commissioning buyer and approval from the project developer.
The Six Policy Responses States Used to Legislate Data Centers in 2026
Key Takeaways
- Community opposition to data center development has become a national conversation, and state legislatures are now responding with a broad spectrum of policy responses to address constituent concerns.
- Relae’s policy experts have identified six broad categories of policy responses: tax incentives, disclosure requirements, transparency rules, cost allocation, incentive clawbacks, and moratoria. In 2026, incentive bills are stalling while disclosure, cost allocation, and clawback bills are advancing.
- The shifting action of state legislatures across these categories can guide developers on the relative political openness or opposition to data center developments across the United States, and should inform site selection and investment decisions.
- Every state legislature will be back in session in 2027, including major data-center markets like North Dakota, Nevada, and Texas that sat out 2026, so this picture will keep changing.
Which States Are Getting Harder to Build In
Community concerns have translated into opposition, delaying, derailing, or altogether denying projects. Local debates over land, water, and electricity prices have moved into statehouses as a result.
If you're trying to figure out "Which states are becoming harder (or easier) to site a data center in, and why?", the state legislature is where that answer is being written. Last year, we tracked the initial wave of state bills on data centers. This year, the volume of bills has grown. The policy categories we used last year still broadly hold, but the distribution of emphasis across these categories has shifted significantly.
Relae’s policy experts reviewed the bills introduced in 2026 legislative sessions related to data centers and identified six categories of policy responses available to a state: tax incentives (“reward it”), disclosure requirements (“review it”), transparency rules (“reveal it”), cost allocation (“shape it”), incentive clawbacks (“revoke it”), and moratoria (“stop it”). These categories do contain some overlap, but together they show a range of what legislatures are trying.
Each response answers at least one of three questions local communities have been posing for over a year now: Who bears the costs of new generation, transmission, and other grid upgrades? What are constituents entitled to know about data center developments in their region? Who decides whether a project goes forward?
For each policy response, we selected at least one representative bill that is either most consequential financially or most impactful to developer timelines. Notably, states with significant data center development pressure, such as North Dakota, Nevada, and Texas, did not have regular sessions in 2026, meaning the scope of policy responses reflected here is not exhaustive.
Six State Policy Responses to Watch for Data Center Siting and Investment
Which policy response a state reaches for, and how that bill fares in the legislative process, signals how politically open or resistant it currently is to new data center development. That political landscape should directly inform data center site selection and investment decisions - and it’s changing quickly.
1. Reward It: Data Center Tax Incentives and Subsidies
These bills try to attract data centers by giving them a financial reason to locate in a state. We call this response "reward it." It typically means property tax exemptions, sales tax breaks on equipment, or reduced utility taxes, usually in exchange for a minimum investment and a job-creation commitment.
West Virginia Senate Bill 623, the “West Virginia-Powered Data Center Incentive Act,” would have exempted data center equipment from property taxes and cut business taxes for the utilities supplying power to the data center. To qualify, a data center would have needed to invest at least $50 million, create 50 jobs, and run on coal-generated electricity for at least 80% of its operational capacity. The bill died in committee without a vote, which is emblematic of how this category of bills fared in 2026.
Relative to the approximately 50 bills introduced (and 9 passed) in 2025 that provided tax incentives for data centers, this category declined significantly in the 2026 session. Part of the drop off could also be a product of the current tax laws of many states, which already include substantial tax incentives for data centers.
For developers, this is the category to watch shrink: fewer states are actively competing to hand out new incentives, so existing programs may be close to the extent of what's on offer going forward.
2. Review It: Data Center Disclosure Requirements
Under what we call the "review it" response, these bills require specific information to be shared with regulators or grid operators before or while the project is built, usually about power demand, interconnection plans, or backup generation.
Pennsylvania House Bill 1834, the “Data Center Act,” would direct the state’s Public Utility Commission (PUC) to oversee commercial data centers with a peak demand of 25 megawatts or greater. It would require disclosure of information relating to interconnection requests as well as planned backup generation. It would also fast-track interconnection for facilities that bring incremental clean firm resources. That disclosure helps grid planners in PJM spot duplicate projects in their interconnection queue, while also helping state leaders to understand if projects in the state are in jeopardy of being lured elsewhere. The House passed the bill 104-95, and is awaiting action in the Senate.
This category, which also includes bills that require disclosure of information around environmental impacts and power or water usage, has grown in 2026. Pennsylvania has been at the center of many discussions around data centers and utility affordability this year. Governor Josh Shapiro's initiative on utility affordability identifies data center load as the pressure point while a wider discussion evolves in PJM over capacity costs.
3. Reveal It: Data Center Transparency Rules and NDA Bans
This is a new category in 2026. We call it the "reveal it" response: bills that stop public officials from signing non-disclosure agreements about data center projects. The goal is to inform residents about who is behind a proposed facility and how much power it will use.
Ohio House Bill 695 would bar county commissioners, township trustees, village mayors, and council members from entering into nondisclosure agreements (NDAs) related to their official duties. It directly targets the NDAs that have kept local officials from telling residents who is behind a proposed project or how much power it would consume. The Ohio legislature is in session until December 17, and the bill is still awaiting action in committee. A similar bill in Pennsylvania, House Bill 2359, would tie NDA prohibitions to a data center sales tax exemption. That bill has passed the House and is also currently pending in the Senate. Separately, in August, Gov. Shapiro banned NDA use outright on any data center project the state oversees.
4. Shape It: Data Center Cost Allocation and Ratepayer Protection
These bills aim to allocate more of the grid infrastructure costs associated with upgrades to the data center. New power lines, substations, and other transmission costs fall on the data center, not on everyone else's electric bill, under what we call the "shape it" response.
California Senate Bill 886, the California Technology Innovation and Ratepayer Protection Act, was signed into law by Governor Gavin Newsom on September 21, 2026, as part of a seven-bill data center package. It passed the Senate 28-10 and the Assembly 49-7. It requires the California PUC to establish or update electricity tariffs by January 1, 2028, for data centers entering new transmission-level interconnection agreements on or after January 1, 2027. Under it, developers bear the cost of transmission upgrades and face a 10-year early termination fee if they back out or fail to reach capacity. This is a strong template for keeping the costs of serving large loads from impacting retail ratepayers, and similar bills should be expected in other states in 2027.
5. Revoke It: Data Center Incentive Clawbacks
These bills take back or narrow tax breaks a state already granted (the "revoke it" response), usually once lawmakers start weighing what those incentives are actually costing the state against what they bought.
Washington Senate Bill 6231, signed into law by Governor Bob Ferguson in April, will remove the sales tax exemption for replacing or refurbishing existing server equipment. The category of bills revoking previous tax incentives for data center development and operation has grown substantially as more states are starting to reconsider the large incentives they put into place at the beginning of the data center boom. Over 50 bills in more than 20 states have sought to restrict data center incentives in 2026, including New Jersey Senate Bill S4390, which was signed into law in August.
6. Stop It: Data Center Development Moratoria
These bills seek to temporarily restrict certain new data center development outright (the "stop it" response), usually for a fixed period while the state studies the impact on the grid, water use, or electricity rates.
New York Senate Bill S10642/Assembly Bill A11560, the Responsible Data Center Development Act, would impose a permit moratorium on data centers of 20 megawatts or more. It passed the legislature on June 4th and is awaiting action by Governor Kathy Hochul. If signed into law, it would be the first moratorium enacted through a legislature. Separately, Governor Hochul has issued an executive order to establish a temporary moratorium on data centers, though her order only applies to facilities of 50 megawatts or more.
This category did not exist a year ago within state legislatures, but as public concern about data centers has grown, several moratorium bills have been introduced. Maine’s LD 307 passed through the state legislature and would have done the same, but was vetoed by Governor Janet Mills in April. In Texas, Governor Greg Abbott has issued orders to state agencies to halt data center approvals in ERCOT until audits can be completed, and in September, he expanded the pause to also cover a review of environmental permits.
It is important to note that many of the moratoria put in place at the state level, whether through the legislature or via executive action, are temporary, usually one year in duration. Often, the moratoria being considered include a plan to study the impacts of data centers on communities and whether utility rates may rise.
What to Watch in 2027
The most consequential policies in 2026 didn’t come through legislatures. They came from executive action by the governors of New York and Texas, which went further than any legislature with respect to their financial and commercial impact. The outcome of the 2026 midterm elections will shape the appetite of both the legislative and executive branches for additional action. In addition, every state legislature will be in session in early 2027, including North Dakota, Nevada, and Texas, which all sat out 2026, so we expect significant policy developments to continue at the state level next year.
In legislatures, the pattern across all six policy responses points in the same direction: recent legislative activity suggests that some states are moving from attracting data center development through incentives toward imposing additional conditions, oversight requirements, or restrictions on new development. Fewer bills providing new incentives for data centers are being introduced or are stalling in legislatures, while bills on cost allocation, disclosure, incentive reduction, and permitting are advancing more successfully.
Map Your State's Regulatory Risk
Site selection and investment decisions increasingly hinge on which of these six responses a state is pulling, and how fast that can change. Talk to our Policy Advisory Team about what a state's current and pending legislation means for a specific project or portfolio.
Beyond Backup Generators: Hydrogen as Baseload Power for AI Infrastructure
Key Takeaways
- Speed to operation is the value proposition. While grid interconnection can take 3-5 years in constrained regions, hydrogen fuel cell systems can be deployed in a fraction of that time—a large advantage for operators racing to meet data center capacity demands.
- Hydrogen is moving beyond backup. Fuel cells could supply 6-15% of incremental data center power, functioning as primary or near-primary power rather than emergency standby.
- Higher fuel costs can be rational. When the alternative is a multi-year wait for grid power and the development loss that comes with it, paying a premium for hydrogen is better than falling behind.
The Grid Can’t Keep Up With Data Centers
The data center infrastructure buildout is moving at a pace the US power grid was never designed to accommodate. Cleanview tracks about 63 GW of operating US data center capacity and another 392 GW in planning, roughly six times what exists today. Developers in high-demand corridors—Northern Virginia, Central Texas, Phoenix—are finding that the grid can't deliver new capacity fast enough.
Interconnection queues now stretch 3-5 years in many regions, and that’s before accounting for permitting, transmission upgrades, and substation buildouts. For operators that need power online faster than the grid can deliver it, this timeline gap is a fundamental constraint on the business.
This mismatch between AI deployment, generator bottlenecks, and grid timelines is why hydrogen is entering the conversation as a viable power option for a growing subset of data center deployments, alongside natural gas with carbon capture, geothermal, and long-duration energy storage.
Hydrogen Fuel Cells: From Standby to Primary Power
For most of its history in data centers, hydrogen has been discussed as a cleaner replacement for diesel backup generators. That framing undersells the opportunity.
The shift happening now is more fundamental: hydrogen fuel cells are being evaluated as primary or near-primary power sources for behind-the-meter and facilities that can’t wait for grid connection. Notably, many modern fuel cell systems—including solid oxide fuel cells—can run on natural gas today and transition to hydrogen as clean supply becomes available. Bloom Energy's 2024 deal with American Electric Power to provide up to 1 GW of fuel cells for data center power illustrates this approach: the systems will initially run on natural gas, with the capability to switch to 100% hydrogen in the future.
Furthermore, fuel cell systems are modular, can be deployed incrementally as load grows, and provide continuous power output. This is a promising path, and one that will scale only as fast as the fuel cell supply chain can keep up. Unlike solar or wind, fuel cells aren’t weather-dependent. Running on hydrogen, they produce zero direct emissions at the point of use. Running on natural gas, they still emit CO2, but their higher efficiency gives them a lower carbon intensity than a comparable gas turbine.
Goldman Sachs estimates that fuel cells could supply 6-15% of incremental data center power (the estimate doesn't specify fuel mix, though most near-term deployments would run primarily on natural gas). This is a meaningful share of new capacity, driven largely by operators who face years-long waits for both grid connections and new gas turbines. Bloom Energy, whose fuel cell products serve data center applications, has been a notable outlier in an otherwise struggling hydrogen sector, with its stock rising sharply on strong revenue performance and growing investor enthusiasm around data center power demand.
Speed to power depends on the fuel. Solid oxide fuel cells run on pipeline natural gas today, so operators do not wait for a hydrogen supply chain. Bloom states it can deliver onsite power for an entire data center in as little as 90 days, with the ability to add modules as load grows under certain circumstances. In all but a few select locations, hydrogen comes later when the same systems switch fuels as clean supply scales. Projects that need hydrogen from day one face additional challenges. Limited hydrogen availability and supporting infrastructure across much of the US can undermine the potential speed advantage of hydrogen-dependent projects. Nevertheless, locations with suitable hydrogen supply and supporting infrastructure may offer viable near-term opportunities.
The Hydrogen Premium: When Paying More Makes Sense
Hydrogen-generated power is more expensive than other forms of electricity generation in most markets. The logistics penalty (including compression, transport, and storage) can push hydrogen from $4/kg at the production site to $8-16/kg delivered, making the economics look unfavorable on a simple $/MWh comparison. In practical terms, hydrogen at $4-6/kg translates to roughly $120-180/MWh on an energy-content basis (LHV). At a fuel cell electrical efficiency of around 50%—typical for solid oxide systems—the effective cost of electricity rises to approximately $240-360/MWh for co-located production, compared to $40-60/MWh for natural gas fuel cells, $51-129/MWh for gas combined cycle, and $144-276/MWh for gas peakers. Operators can improve hydrogen economics by co-locating with production, avoiding the logistics penalty that can double or quadruple delivered costs.
While expensive, this cost comparison misses the central point. The relevant question is not whether hydrogen is cheaper than grid power, but whether it is better than having no access to power at all.
For an operator with signed contracts and a 100 MW facility sitting idle during a multi-year interconnection queue, the opportunity cost is substantial. At average US wholesale colocation rates (~$196/kW/month - a record high), a facility of that size represents roughly $235 million per year in potential revenue—meaning even a single year of delay can outweigh years of hydrogen fuel premiums.
The Inflation Reduction Act’s 45V Production Tax Credit further compresses the gap, offering up to $3/kg for clean hydrogen production—but projects must begin construction by December 31, 2027, to qualify. That deadline adds urgency to what’s already a time-sensitive calculus.
Reframing the Cost Debate for Speed-to-Power
The debate about whether hydrogen is cost-competitive with grid power misses the strategic challenge facing data center operators today: the fastest path to reliable, clean power. Hydrogen can play a consequential role in that timeline in some markets.
Assessing that requires modeling the full picture: grid interconnection timelines, hydrogen supply chain costs at a specific location, the 45V credit’s impact on project economics, and how hydrogen compares to batteries and other bridging technologies for a data center’s particular load profile.
Relae’s advisory team helps data center operators and technology companies evaluate these tradeoffs with rigorous, independent analysis. If speed to operation is a factor in your energy planning, let’s talk.
Frequently Asked Questions
How much faster is hydrogen fuel cell deployment than waiting for grid interconnection?
Grid interconnection in constrained regions can take 3-5 years once permitting, transmission upgrades, and substation buildouts are factored in. Fuel cell systems, especially those that start on natural gas and then transition to hydrogen, can be deployed in a fraction of that time. They are modular and can be installed and scaled incrementally as a facility’s load grows, though the pace depends on equipment and fuel supply.
If hydrogen costs more than grid power, why would an operator choose it?
For an operator with a 100 MW facility sitting idle during a multi-year interconnection queue, the lost revenue—roughly $235 million a year at average US wholesale colocation rates—can outweigh years of hydrogen’s fuel premium. That makes the higher cost a rational tradeoff against a multi-year wait for grid power, not just an expensive alternative to it.
Do hydrogen fuel cell systems have to run on pure hydrogen from day one?
No. Many modern fuel cell systems, including solid oxide fuel cells, can run on natural gas today and transition to hydrogen as clean supply becomes available. Bloom Energy’s up to 1 GW agreement with American Electric Power follows this model: the systems start on natural gas, with the capability to switch to 100% hydrogen as the hydrogen supply chain matures.
Data Centers Need a New Approach to Community Benefits
Key Takeaways
- Community Benefits Agreements (CBAs) have existed for two decades, and the data center buildout is exposing where the legacy model breaks.
- Across 46 cancelled or stalled US data center projects that Relae analyzed, late-stage benefits packages may be insufficient to change outcomes. Process, transparency, and proof of delivery did.
- The next generation of CBAs, especially for data centers, needs to be meaningful in scope and community voice, measurable in delivery and outcomes, and durable across political and generational divides.
Communities Are Rejecting the Legacy Benefits Model
In a white paper published earlier this year, Relae documented 46 US data center projects that were cancelled, stalled, or withdrawn between January 2024 and May 2026. Together, these projects represent more than US$170 billion in announced investment associated with projects canceled, stalled, or withdrawn following community opposition. Developers led with projects that included reactive communications and limited benefits packages negotiated under the pressure of rapid development timelines and local permitting and approval processes.
[stat]
Across these cases, local communities expressed concerns ranging from environmental and natural resource concerns to electricity rate impacts, to the lack of transparency and accountable development approaches. Even more importantly, communities do not clearly see how AI-driven data center development directly benefits them and advances their priorities and local social and economic goals.
The legacy community benefits models that data center developers are deploying were designed for a different kind of project, in a different political context. The public and local communities are demanding a new model to meet the current moment.
What Is a Community Benefits Agreement? A Brief History of CBAs
Community Benefits Agreements, or CBAs, have been a feature of US infrastructure development for twenty years. The foundational practitioner manual was published by Julian Gross, Greg LeRoy, and Madeline Janis-Aparicio in 2005, and the Partnership for Working Families coalition has carried the practice forward since.
The frame has expanded. Just Transition principles from labor and climate justice coalitions, the former federal Justice40 Initiative, and contemporary CBA templates from civil rights organizations like the NAACP have pushed the field toward binding equity commitments, durable community ownership stakes, and, where Indigenous or culturally significant sites are implicated, free prior and informed consent. These frameworks moved the field forward.
Relae examined CBAs across 40 US climate and clean energy projects in our prior white paper, Codifying Community Benefits in US Climate and Clean Energy Projects. Our analysis found that developers now routinely integrate multiple benefit types, including fiscal, workforce, infrastructure, environmental, and procedural commitments. CBAs for climate and clean energy projects have evolved, and this has brought many improvements, even though imperfections remain. The absence of a shared standard for defining and monitoring those benefits can leave outcomes uneven and often inequitable across host communities. Some efforts attempted to create a unified structure. For example, the Department of Energy had a Community Benefits Plan requirement on every Bipartisan Infrastructure Law and Inflation Reduction Act application, weighted at twenty percent of technical review.
Even still, these models were subject to political whims and did not advance localized and community-driven benefits. The gap now is in the timing, verification, and enforcement layer that turns those commitments into outcomes.
Community Data Center Opposition Is Breaking the Old CBA Model
Data center capital is arriving faster than any wave of large-load infrastructure since the shale gas boom. BCG estimates hyperscalers will spend US$1.8 trillion on data center-related capex in the US between 2024 and 2030. According to Dell'Oro Group, the four largest US cloud providers (Amazon, Microsoft, Google, and Meta) spent over US$340 billion in 2025 alone, with Amazon leading at $125 billion. Communities are responding faster, too. According to both Data Center Watch and Relae's own Data Center Cancellations Tracker, the opposition wave documented is mobilizing in weeks, not months.
Data center opposition in the US is bipartisan. It spans red and blue counties, every region, and multiple grid operators, with nearly two-thirds of the blocked investment sitting in counties that voted for Donald Trump in 2024.
By the time a developer reaches a public hearing with strong local community organization, the path of the project is largely set. Late-stage benefits packages that are offered as contractual agreements to side-step community concerns are proving to be ineffective. Communities read them as concessions, not commitments. Good Jobs First has now turned that critique on the data center sector, warning that hyperscale developers risk using the CBA label to whitewash bad deals.
What Makes a Community Benefits Agreement Actually Work?
The next generation of community benefits needs to pass three tests: meaningful, measurable, and durable.
1. Meaningful. Benefits should be calibrated to the host community's burden and vulnerability profile and be developed in collaboration with local community leaders and community-based organizations. Developers should draw on best-in-class methods in environmental justice analyses to help develop strong and responsible community engagement plans to involve residents and impacted communities in data center design decisions. Communities most exposed to siting harm must be at the table on equal footing with adjacent jurisdictions.
2. Measurable. For developers to be accountable to local communities, benefits frameworks need to include metrics for tracking and verifying both investment and outcomes. SMART (specific, measurable, attainable, relevant, and time-bound) milestones, independent monitoring, and secured financial obligations should be the default, not the exception. Historically, DOE's Community Benefits Plan requirements provided an example of incorporating measurable community commitments into federal funding applications. Although these federal requirements have since been rescinded, their emphasis on specific milestones and accountability offers lessons for voluntary community benefits frameworks and have set a usable floor, with at least one specific, measurable, achievable, realistic, and time-bound milestone per budget period. RMI's analysis shows how that floor translates to project-level design. The same logic applies to data centers. If a commitment cannot be measured by the community, it is not a commitment.
3. Durable. Benefits have to survive political winds and local electoral politics. Any benefits that a developer delivers should also be intergenerational in scale, or at least be scaled to the planned lifecycle operations of the data center itself. A CBA built only on conversations negotiated in a closed room will not hold. Durable benefits are written with enforcement mechanisms, conditional triggers, and modification rights that the community can exercise. The strongest form of durability is community ownership, in the shape of revenue share, community trust structures, or potential co-ownership of infrastructure or assets like battery storage or renewable energy generation. Microsoft's Community-First AI Infrastructure framework is a useful industry signal, but voluntary frameworks do not substitute for instruments the community can enforce.
Where Developers and Capital Partners Go From Here
The cancellation surge is a structural feature of the current data center siting environment. The patterns are legible enough to act on now. Three moves matter most.
1. Engage early, and well before site selection. Genuine engagement means naming the end user on the application, opening pre-application discussions to the public, and treating disclosure as a siting strategy rather than a legal afterthought.
2. Calibrate benefits to the host community, not to a template. Pre-siting analysis of demographic, environmental, and infrastructure indicators tells a developer whether drinking-water investment, energy burden protection, noise mitigation, or air-quality remediation will land as a real benefit for that community. Likewise, community involvement and voice in benefits design are equally important to shape calibrated and meaningful benefits. The same investment delivers very different value across communities.
3. Build verification into the instrument from day one. SMART milestones, independent monitoring, secured financial obligations, and modification rights the community can exercise belong in the agreement at signing, not bolted on later. Capital partners should expect to see these structures in their own diligence. A commitment without measurement is a promise, and communities are no longer accepting promises.
The Next Generation of Community Benefits Is Being Written Now
The next generation of community benefits is being designed right now, across municipal halls, civic coalitions, capital diligence checklists, and developer playbooks. The frameworks that will work are the ones that pass three tests: meaningful in scope and community voice, measurable in delivery and outcomes, and durable across political and generational divides.
Relae's Responsible Development team works with developers, capital partners, and host communities to build these frameworks from the ground up. Pre-siting community intelligence, burden-calibrated benefits design, and the verification scaffolding that converts commitments into outcomes.
The shift from reactive to proactive community engagement puts the focus on whether developers are willing to advance the capital to develop meaningful, measurable, and durable community benefits.
[cta]
Frequently Asked Questions
Why do data centers need community benefits agreements?
Communities opposing data center projects cite concerns ranging from environmental and rate impacts to a lack of transparency, and often don’t see how the project benefits them directly. Across 46 cancelled or stalled US data center projects Relae analyzed, representing more than US$170 billion in blocked investment, late-stage benefits offered under pressure didn’t change outcomes. A community benefits agreement lets developers deliver benefits proactively and make them verifiable, rather than reactively once opposition has organized.
What’s the difference between a legacy community benefits agreement and a next-generation one?
Legacy CBAs were often negotiated with specific legal and formal entities like County Commissions or City Councils and had narrow focuses on workforce or economic development. Oftentimes, these tools were offered as concessions through negotiation, rather than commitments, which is why communities are rejecting them. A next-generation community benefits agreement is meaningful, measurable, and durable from the start, with benefits calibrated to the host community rather than bolted on later.
Who should be involved in negotiating a community benefits agreement for a data center?
Benefits should be developed with local community leaders and community-based organizations, with the most affected communities at the table on equal footing with adjacent jurisdictions. Developers, capital partners, and host communities all have a role in building the SMART milestones and independent monitoring that turn those commitments into outcomes.