



The Relae Blog
Original insights from the Relae team on the forces reshaping power systems, GHG emissions, environmental markets, nature, and the capital and policies behind them.
Electricity Emissions Accounting: GHG Protocol and LCA Explained
Key Takeaways
- The GHG Protocol Corporate Standard and life cycle assessment (LCA) offer distinct frameworks for measuring electricity-related emissions, one for annual corporate reporting and one for detailed cradle-to-grave analysis, leading to different emissions results.
- Renewable energy certificates (RECs) are accepted under the GHG Protocol's market-based approach to reduce reported scope 2 and scope 3: category 3 emissions, but are not explicitly addressed in ISO LCA standards, where transparent disclosure is essential.
- Using both the GHG Protocol and LCA together, while recognizing their different scopes, boundaries, and purposes, can give organizations a more complete and strategic view of electricity-related emissions and decarbonization opportunities.
Electricity-Related Emissions: Why Measurement Methods Matter
In the era of AI-driven power demand, scrutiny over electricity-related emissions is intensifying. With this increased attention comes growing confusion around how to measure and report these emissions. The GHG Protocol Corporate Standard and life cycle assessment (LCA) are two widely used methods for measuring and reporting electricity-related emissions, but each follows its own complex and often incompatible, set of rules.
This piece will examine the differences between these approaches and answer common questions such as:
- What are the differences between the GHG Protocol Corporate Standard and LCA?
- Why do they result in different emissions for the same type and amount of electricity?
- Can renewable energy contracts reduce electricity-related emissions under both methods?
- When should you use each approach?
Both the GHG Protocol Corporate Standard and LCA are powerful tools that, if used in complementary ways, can help organizations identify emissions hotspots and develop more effective pathways for decarbonization.
What Is the GHG Protocol Corporate Standard?
The GHG Protocol Corporate Standard is a globally recognized framework for corporate entities to publicly report GHG emissions throughout their value chain. It divides emissions into three scopes:
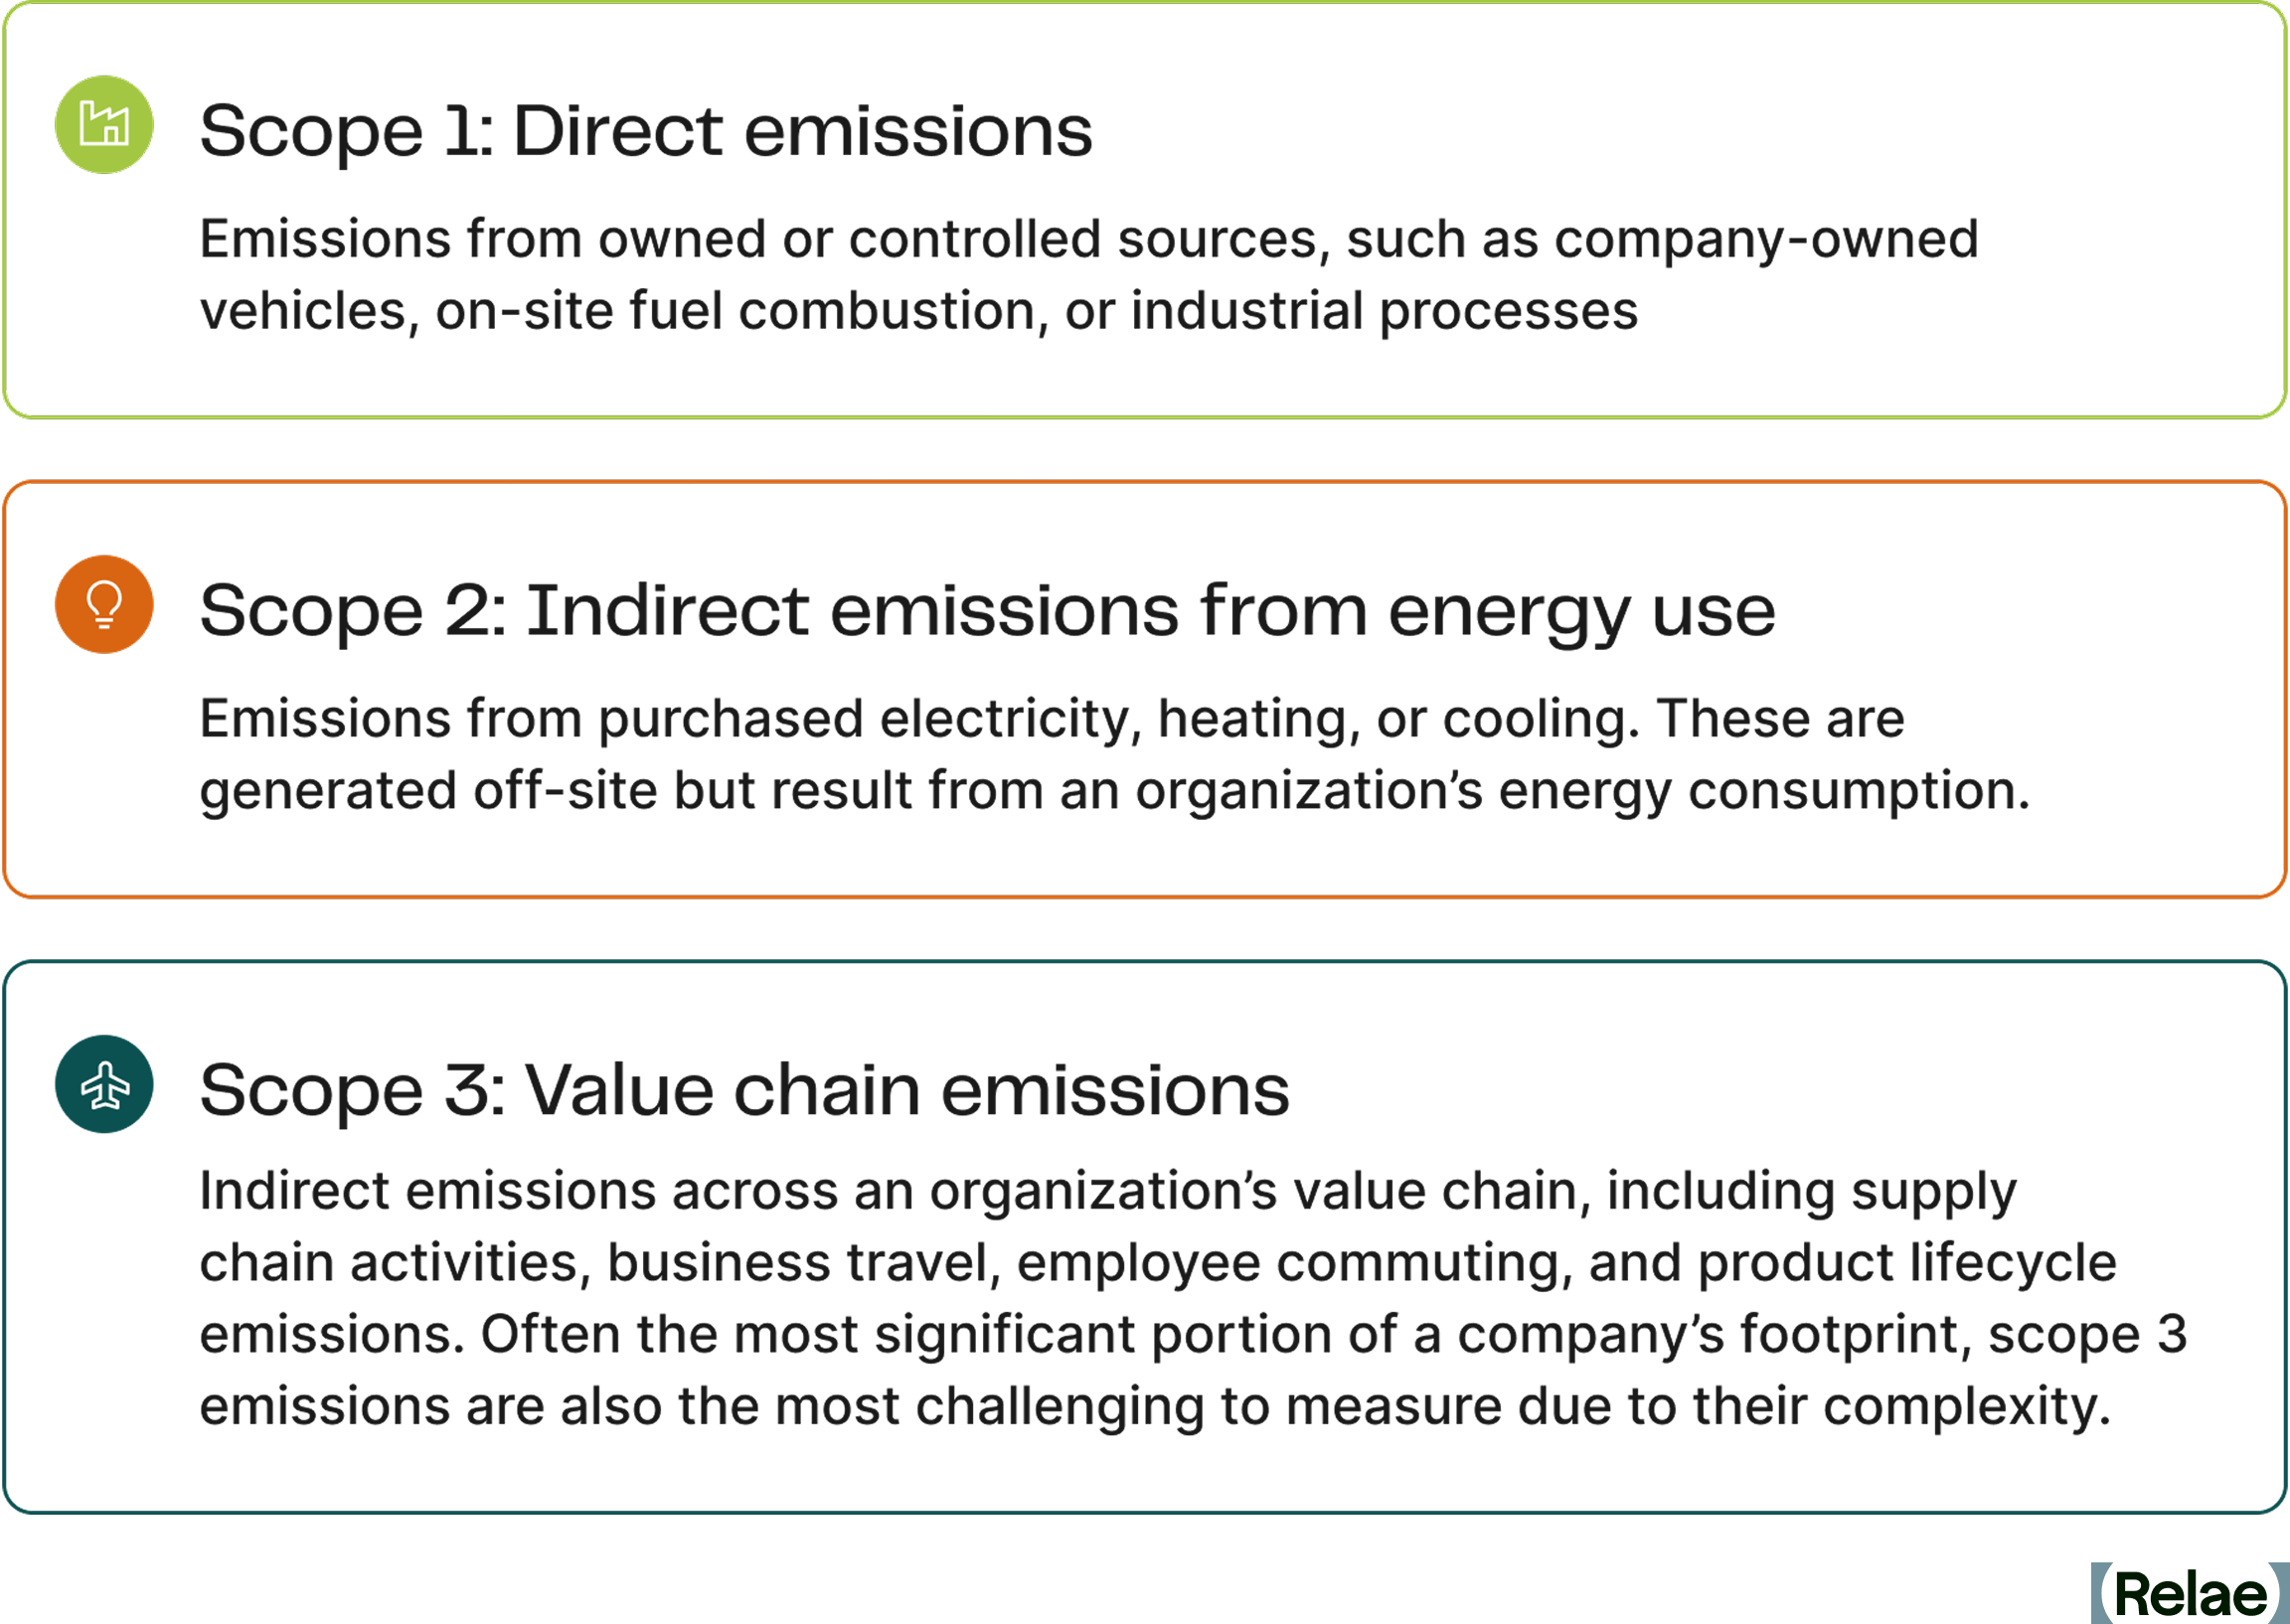
- Scope 1: Direct emissions from owned or controlled sources, such as company-owned vehicles, on-site fuel consumption, or industrial processes.,
- Scope 2: Indirect emissions from the generation of purchased electricity, heat, steam, or cooling. These emissions are generated off-site, but result from an organization's energy consumption.
- Scope 3: Indirect emissions across an organization's value chain. Scope 3 is divided into 15 categories, including a company's supply chain activities, business travel, employee commuting, investments, and product life cycle emissions.
This piece focuses on emissions associated with electricity consumed by a reporting entity. These electricity-related emissions primarily fall under scope 2 and scope 3: category 3 (fuel- and energy-related activities, or FERA).
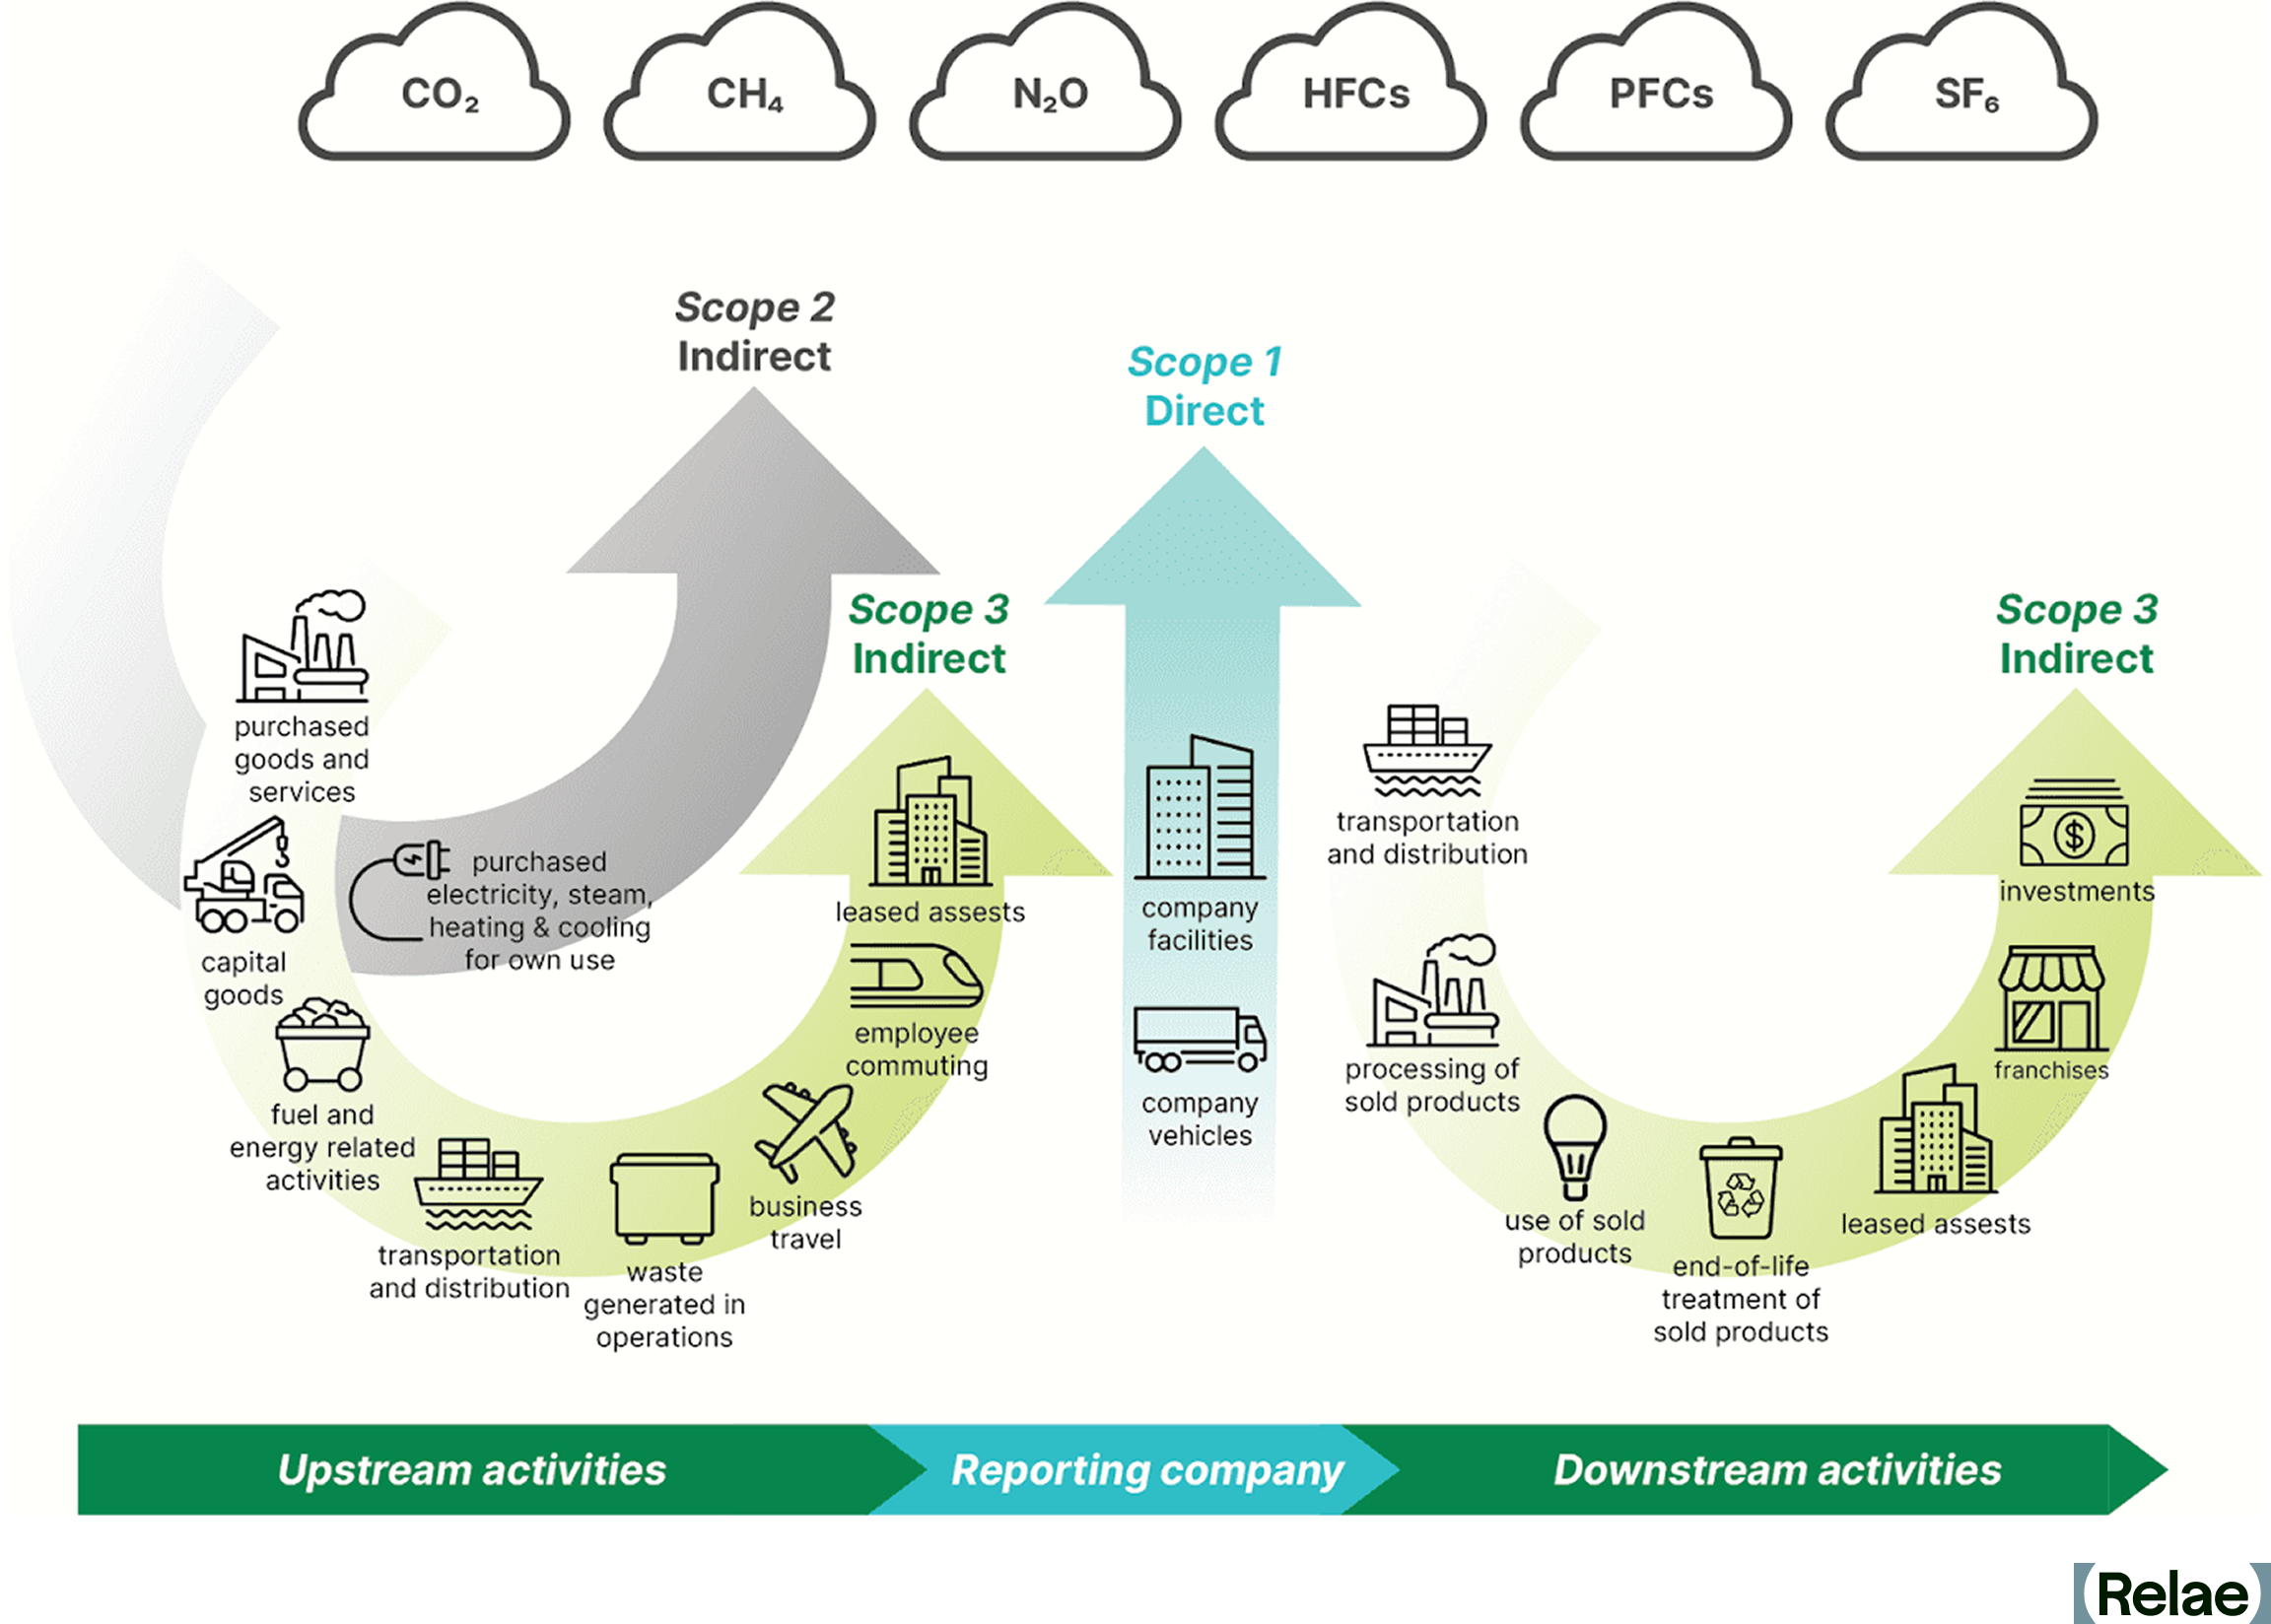
Scope 2: Electricity Generation Emissions
Scope 2 emissions account for the generation of electricity a company purchases or uses. Hypothetically, if a company were powered by a single solar project, it would report zero scope 2 emissions. In reality, a company is powered by a combination of power generation assets and must report them under scope 2 emissions. These emissions can be reported using two methods:
- Location-based method: Reflects the average emissions intensity of the local electricity grid where the consumption occurs. This approach is mandatory under various reporting frameworks and does not take into account a company's procurement choices.
- Market-based method: Reflects an organization's actual procurement decisions and energy-sourcing strategies. It accounts for specific contracts, such as power purchase agreements (PPAs), renewable energy certificates (RECs), and green tariffs, which allow businesses to claim lower emissions from their purchased electricity.
Scope 3: Category 3 FERA
Scope 3: category 3 FERA reports on non-generation electricity emissions associated with:
- Upstream emissions: Emissions associated with the production and transportation of fuels needed for electricity generation
- Transmission and distribution losses: Emissions associated with the loss of electricity while delivering it from the generator to the consumer.
The GHG Protocol Corporate Standard does not include emissions associated with the manufacturing, construction, and end-of-life phases of electricity generation equipment; however, some datasets used for reporting may include manufacturing emissions. While scope 3: category 3 guidance may not require these emissions to be included, if possible, companies reporting on their electricity-related emissions should include these additional sources of emissions in order to more completely represent their total emissions impact. The GHG Protocol Scope 2 Guidance allows for the reduction of some of the reported scope 3 FERA emissions by contracting renewable energy (see Appendix B).
What is an LCA?
An LCA is a systematic method used to quantify the environmental impacts of a process, product, or project throughout its full life cycle. A life cycle includes everything from raw material extraction ("cradle") to manufacturing/production ("gate") through disposal ("grave").
LCAs primarily follow a standard published by the ISO organization (ISO 14040/14044). The ISO standards establish industry-wide rules for which processes are included and how to assign environmental burdens to products.
An LCA can be used for any product, process, or project, and can estimate multiple different environmental impacts (i.e., climate change, human health, ecotoxicity, eutrophication, ozone depletion).
Electricity-Related Emissions Can Be Different Using the GHG Protocol and an LCA
The GHG Protocol Corporate Standard and an LCA (as per ISO standards) generally include different life cycle stages of electricity use when estimating GHG emissions. Therefore, the approaches can result in different reported emissions.
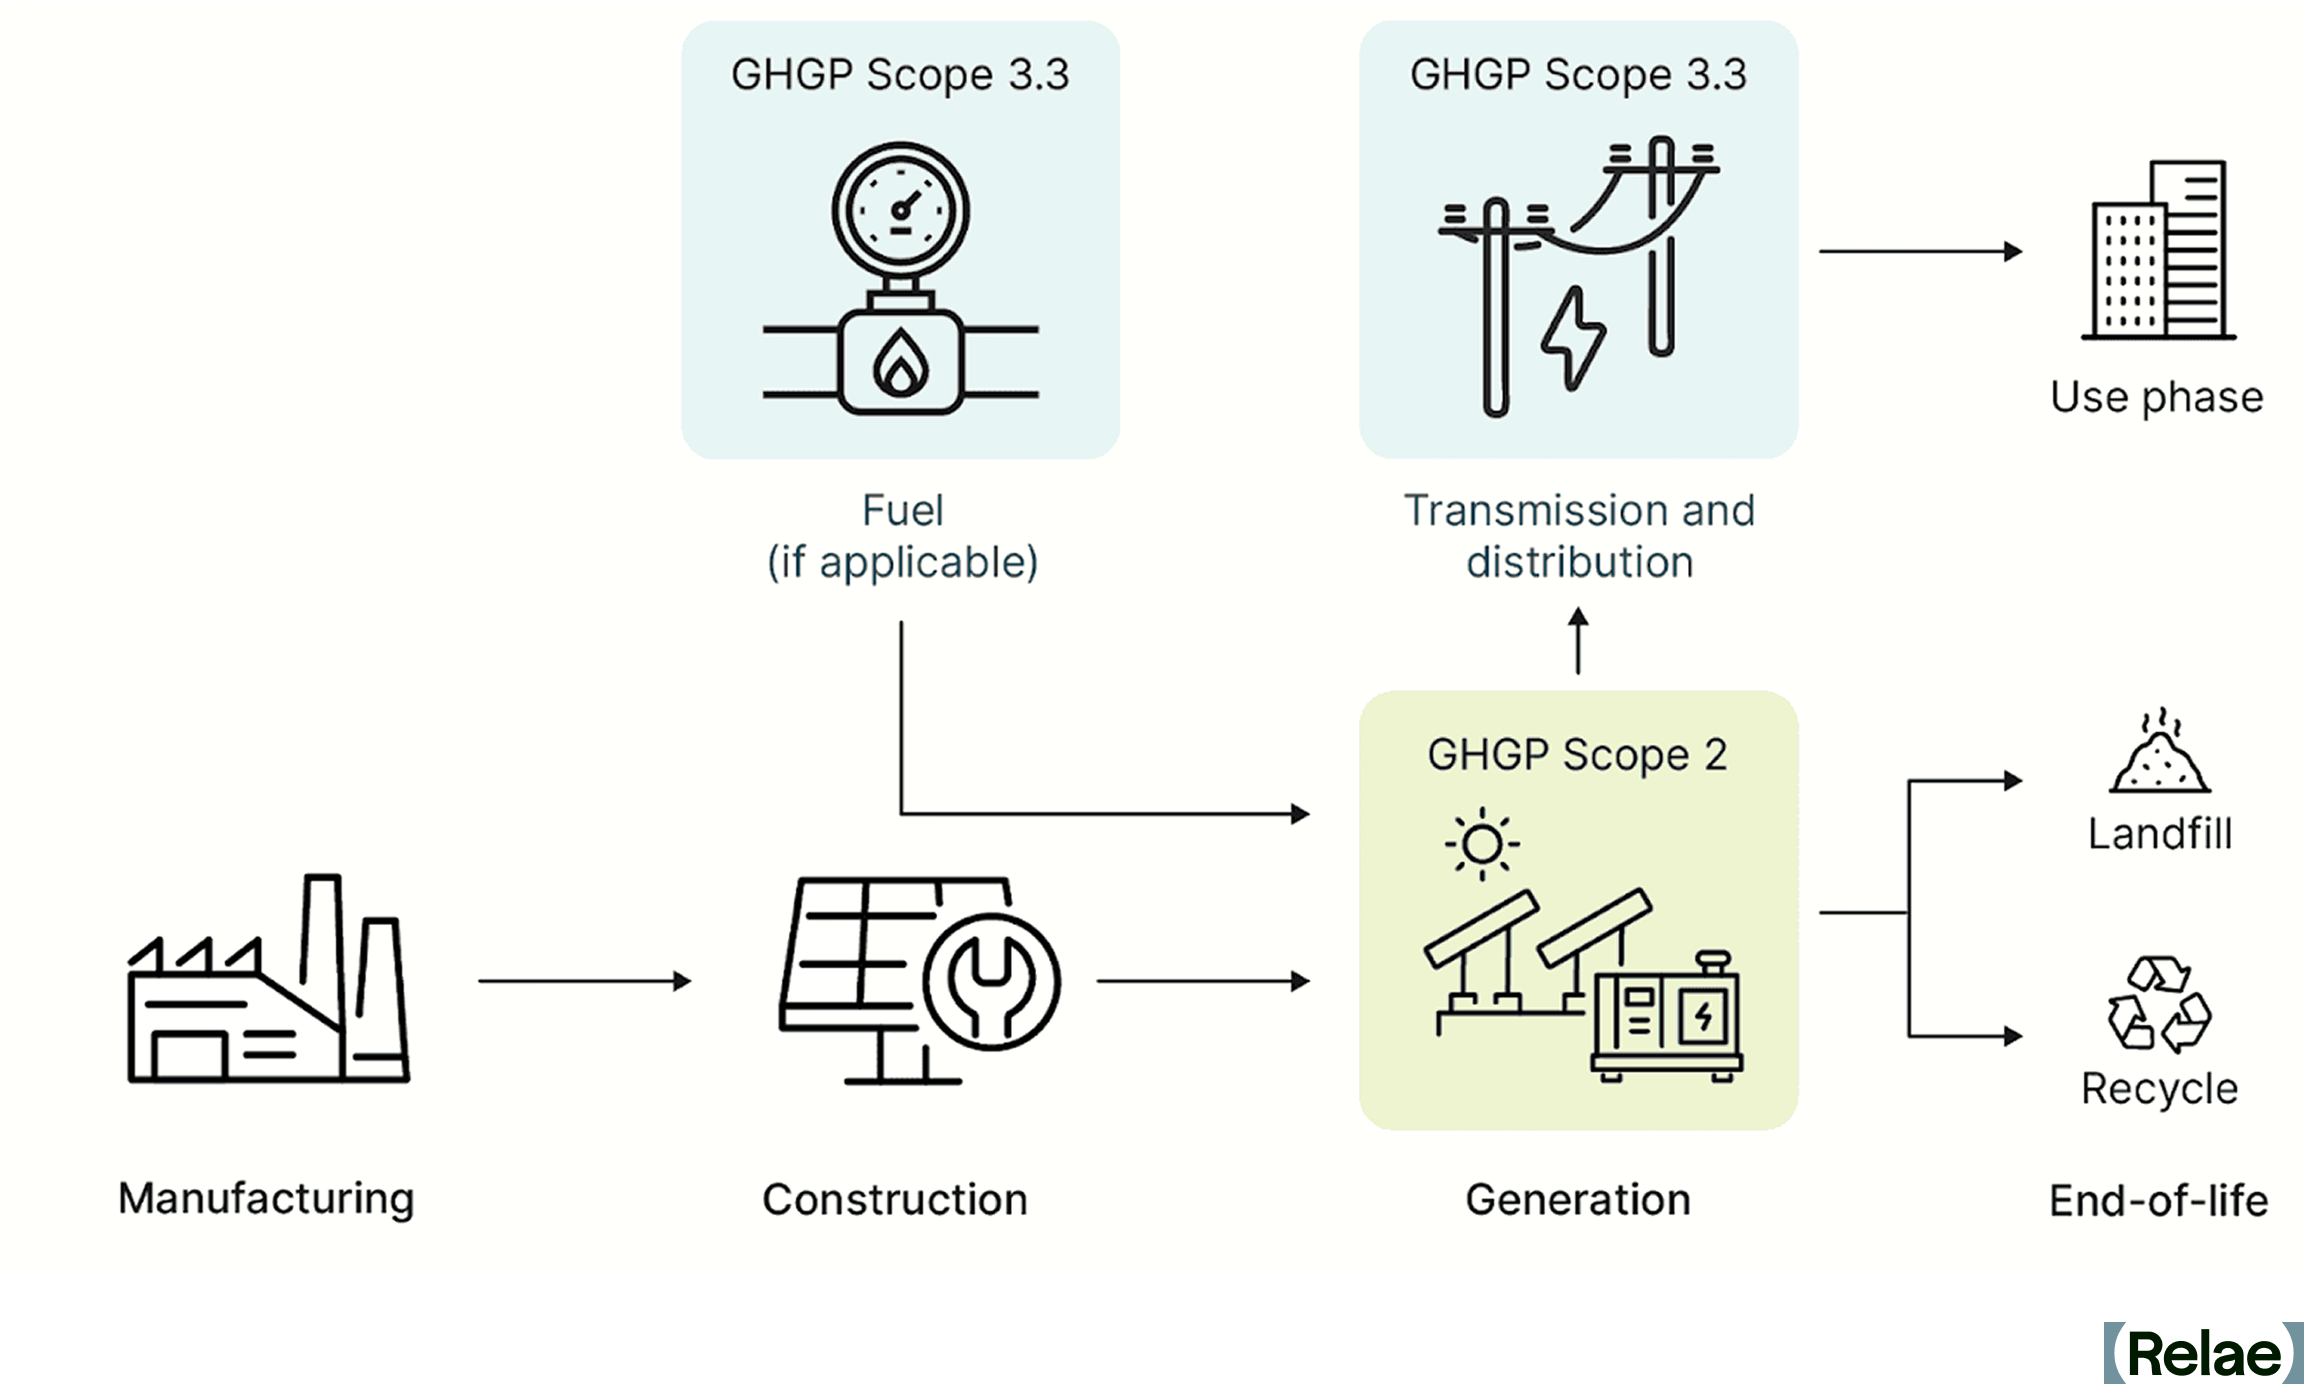
Key Differences in Reporting Electricity-Related Emissions
The GHG Protocol Corporate Standard includes emissions in the following phases:
- Generation (scope 2)
- Transmission and distribution losses (scope 3: category 3)
- Fuel, if applicable (scope 3: category 3)
A “cradle-to-grave” LCA considers emissions from all activities associated with power generation, including:
- Manufacturing
- Construction
- Generation
- Fuel, if applicable
- Use-phase, if applicable
- End-of-life
Use-phase electricity-related emissions are emissions generated by electricity-consuming equipment used or sold by the reporting company (representing additional scope 1 or scope 3 emissions, respectively). Examples include sulfur hexafluoride (SF6) emissions from electrical transformers or refrigerant leakage from air conditioners with high global warming potential. Please note that both the ISO and GHG Protocol Corporate Standard provide guidelines for reporting these emissions. However, due to the equipment-specific nature of these emissions, they are excluded from the following table. The table compares electricity-related emissions associated with different electricity sources using the GHG Protocol Corporate Standard approach and the LCA approach.
Reporting Electricity-Related Emissions
* US average transportation and distribution loss rate (4.2%) times US average grid carbon intensity (410 gCO2e/kWh). Note: gCO2e/kWh = grams of carbon dioxide equivalent per kilowatt-hour. Source: GREET 2024 (US grid average. 10% fuel- and energy-related activities; 1% construction, facilities, maintenance, and end-of-life; 89% fuel combustion).
Reducing Electricity Emissions with Renewable Energy
Renewable Energy Mechanisms Under the GHG Protocol
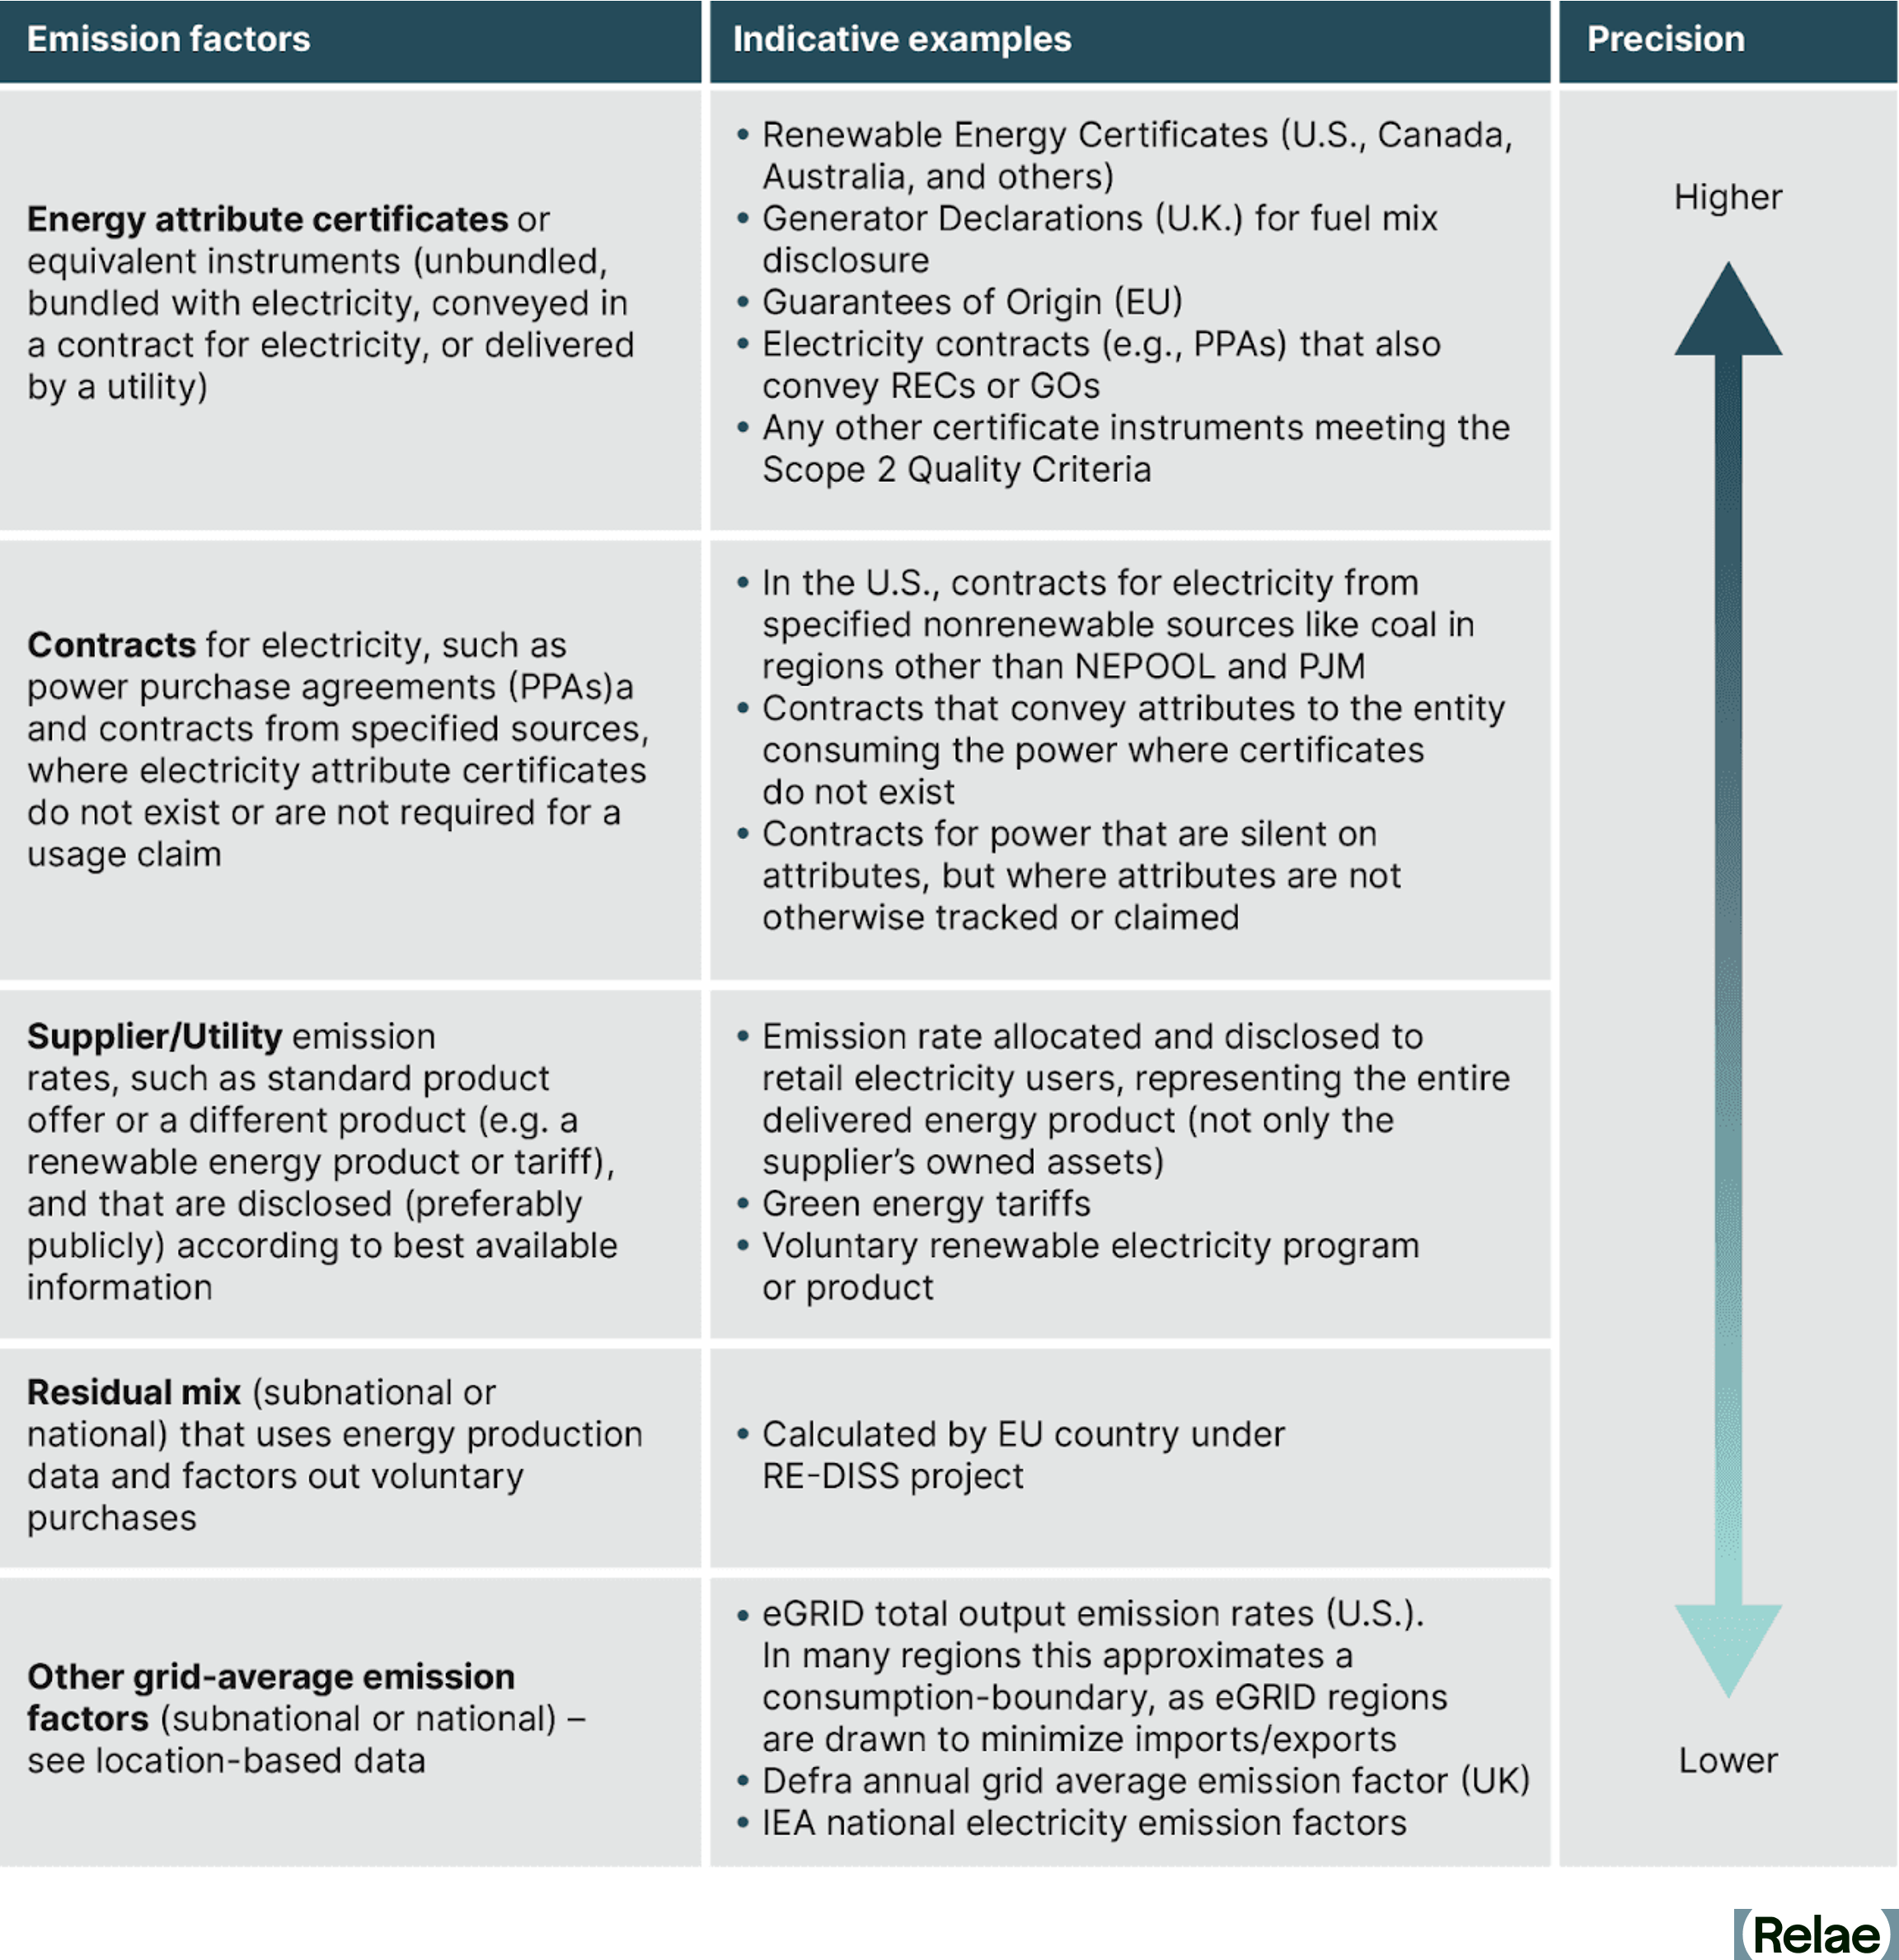
The GHG Protocol Corporate Standard allows companies to contract for renewable electricity as a mechanism to reduce reported emissions. The GHG Protocol Corporate Standard defines allowable energy contracts that can be used to reduce emissions associated with electricity consumption (market-based reporting).
In North America, one of these allowable contracts is RECs, each of which represent one megawatt-hour of renewable generation. Analogous instruments used in other locations, such as Guarantees of Origin in Europe and green electricity certificates in China, are also permissible under the GHG Protocol Corporate Standard.
RECs were developed as a contractual mechanism for renewable electricity in response to the fundamental structure of "a power grid." In a power grid, it is impossible to link a single generator to a single load. Power is injected at a point in the grid and withdrawn at a different point in the grid; there is no traceable pathway.
RECs were created to track the attributes of electricity generation entering into a power grid for the entity that consumes the power at a different point. The GHG Protocol Corporate Standard allows buyers to claim exclusive use of renewable electricity with RECs even if they are actually consuming a mixture of electricity from the grid.
Renewable Energy Mechanisms Under the LCA ISO Standard
The ISO 14040 standard does not address the use of renewable electricity contracts. However, the ISO 14044 standard provides the following guidance:
"When determining the elementary flows associated with production, the actual production mix should be used whenever possible, in order to reflect the various types of resources that are consumed. As an example, for the production and delivery of electricity, account shall be taken of the electricity mix, the efficiencies of fuel combustion, conversion, transmission and distribution losses."
It does not explicitly define whether RECs can or cannot be used in the determination of the "actual production mix." In the event an organization does procure a renewable energy contract to reduce the emissions reported within the LCA, it should disclose that clearly in order to communicate the impact of the contract on the carbon intensity of the LCA with and without the use of RECs.
Powerful Tools for Different Use Cases
The GHG Protocol Corporate Standard and LCAs following the ISO Standard are both powerful tools that can provide insight into emissions associated with electricity use. The GHG Protocol Corporate Standard allows companies to use a standardized framework to report emissions associated with electricity use and interventions on an annual basis. The LCA ISO standard is a detail-driven analysis that allows a deep dive into specific processes, projects, or products. This detailed analysis allows for deeper insights into areas where a company may have more ability to address specific interventions for emission hot spots. Using these tools together, while understanding the boundaries of each, can provide companies with a more effective and impactful approach to decarbonization.
Frequently Asked Questions
What are the differences between the GHG Protocol Corporate Standard and LCA?
The GHG Protocol is an annual corporate reporting framework covering scope 2 (generation) and scope 3: category 3 (transmission and distribution losses, fuel), while a cradle-to-grave LCA is a detailed analysis governed by ISO 14040/14044 standards that also includes manufacturing, construction, use-phase, and end-of-life emissions. LCA can also be applied to any product or process and multiple environmental impacts, not just greenhouse gas emissions.
Why do they result in different emissions for the same type and amount of electricity?
They include different life cycle stages. The GHG Protocol excludes manufacturing, construction, and end-of-life emissions of generation equipment, while an LCA includes them.
Can renewable energy contracts reduce reported electricity-related emissions under both methods?
Under the GHG Protocol, renewable energy contracts (e.g., RECs, PPAs) are explicitly allowed to report zero market-based scope 2 emissions, though scope 3 FERA emissions remain. Under ISO LCA standards, these contracts aren't explicitly addressed. Organizations may choose to apply them, but should transparently disclose LCA results both with and without the contract's impact.
When should you use the GHG Protocol vs an LCA?
Use the GHG Protocol for standardized, annual corporate-wide emissions reporting and tracking procurement interventions; use an LCA for a detailed, process- or product-specific deep dive to identify specific emissions hotspots. Relae recommends using both together for a more complete, strategic view of electricity-related emissions.
Scope 3.1 Emissions: How to Measure and Reduce Value Chain Impact
Key Takeaways
- Scope 3.1 emissions, purchased goods and services, can account for up to 67% of a company’s total carbon footprint, making them a critical category for measurement and action.
- Companies can reduce risk, meet stakeholder demands, and strengthen supply chain resilience by proactively managing scope 3.1 emissions.
- Relae empowers organizations to take meaningful action on scope 3.1 through science-based measurement, practical emissions management strategies, and deep supplier engagement.
What Are Scope 3 Emissions and Why Do They Matter?
Scope 3 emissions include all indirect greenhouse gas (GHG) emissions that occur across a company’s value chain. While scope 1 emissions are from directly owned or controlled activities, and scope 2 are indirect emissions from the generation of purchased electricity, heat, or steam, scope 3 emissions encompass upstream and downstream activities throughout the value chain.
Within scope 3, there are 15 categories, including activities such as raw material extraction, purchased services, shipping, business travel, product use, and end-of-life treatment. Critically, scope 3 emissions usually make up the majority of a company's total carbon footprint. Across sectors, CDP finds supply chain emissions average 26 times a company's operational emissions, and in supply-chain-heavy sectors like apparel, the share exceeds 95%.
Category 3.1 (purchased goods and services) is often the largest contributor. For many organizations, it can be as much as 67% of their total corporate footprint. Despite being outside a company’s direct operational control, scope 3 emissions are increasingly scrutinized by regulators, investors, and customers alike, making them essential to measure, manage, and reduce.
What Is Included in Scope 3.1 Emissions?
Scope 3.1 emissions capture all cradle-to-gate emissions associated with products and services procured by an organization. These include emissions from the extraction of raw materials, energy usage, manufacturing processes, waste, and transport and travel up to the point of delivery to the reporting company. As such, the types of activities within this category are quite extensive and disparate.
Examples of scope 3.1 items include:
- Raw materials (e.g., limestone, copper ore, lumber)
- Intermediate products (e.g., steel, electronic components, platform chemicals)
- Packaging materials
- Office supplies and equipment
- Professional services
- Cloud computing and software services
The size of scope 3.1 emissions varies widely by industry. For example, a consumer goods manufacturer sourcing large volumes of physical products may see a larger share of emissions in this category than the supplier providing the raw materials. For data centers that run on very low-carbon electricity, equipment and construction can account for 40% of lifetime emissions. For many organizations that are service-based or contract out manufacturing, scope 3.1 can be the most significant emissions category.
What Is the Strategic Value of Scope 3.1?
While scope 3.1 emissions fall outside a company’s direct operational control, they are not beyond its influence. Addressing emissions from purchased goods and services may open up a range of strategic benefits:
- Innovation opportunities through lower-carbon materials and production processes.
- Enhanced supplier relationships and engagement on shared sustainability goals.
- Improved resilience and risk mitigation across supply chains.
By assessing and acting on scope 3.1 emissions, companies can drive meaningful reductions and catalyze change throughout the entire supply chain.
What Are the Methods for Calculating Scope 3.1 Emissions?
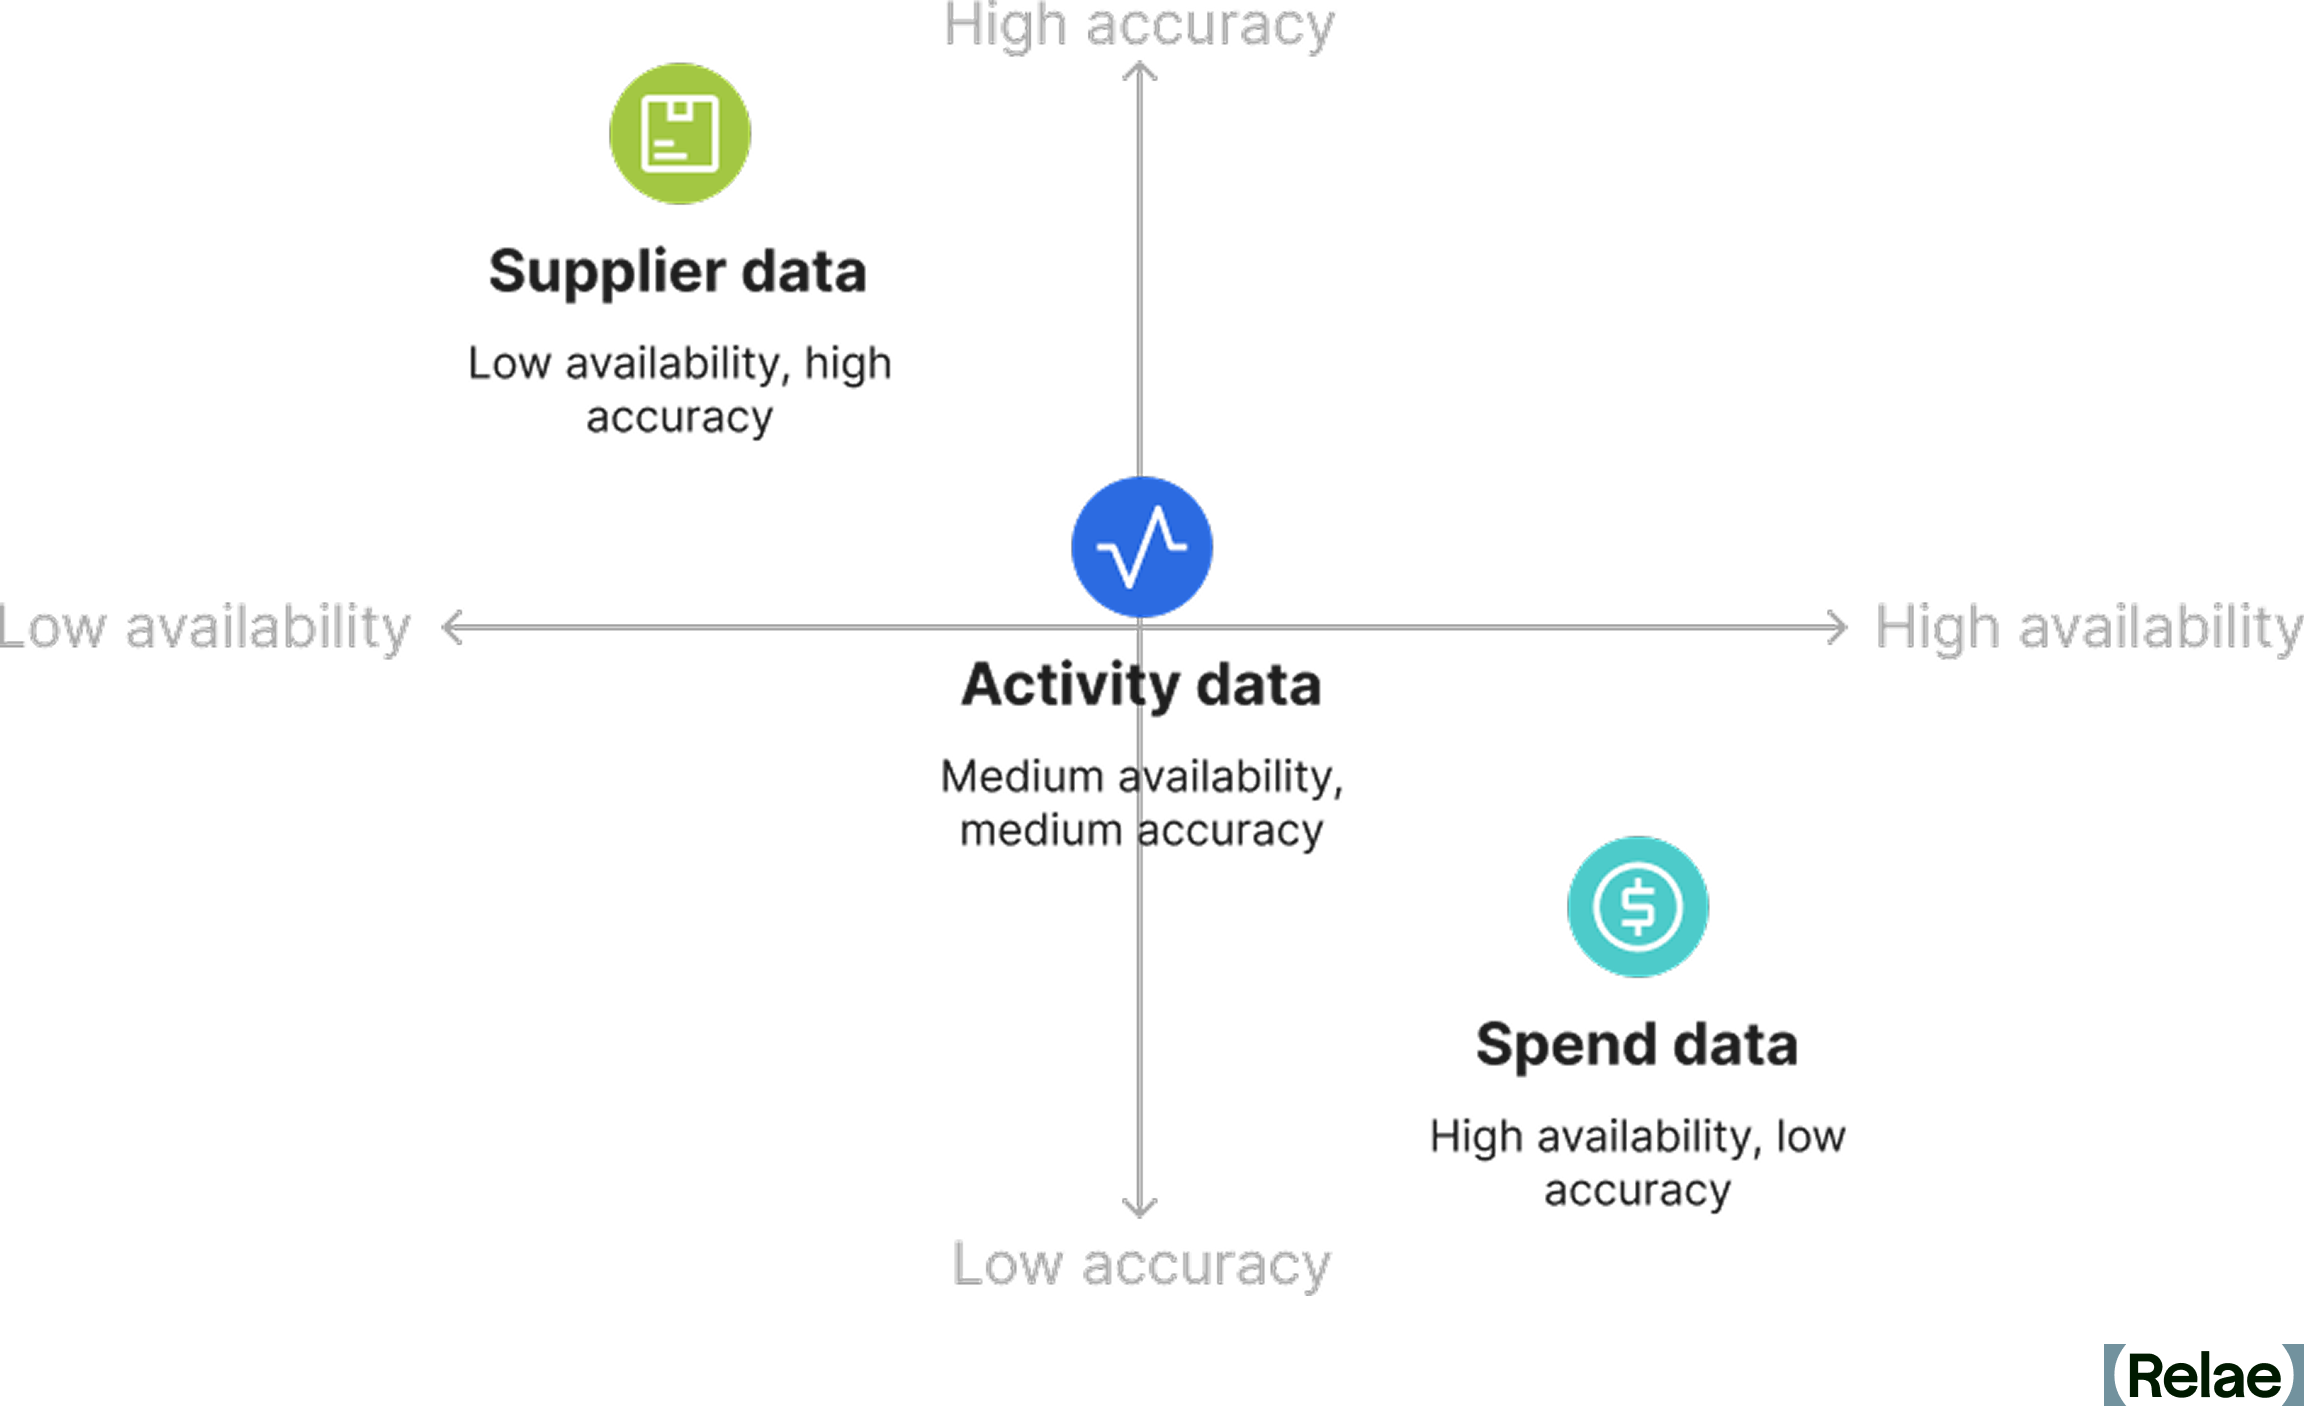
There are four methods to calculate scope 3.1 emissions based on the data collected. Each offers a different balance of speed, accuracy, and scalability.
1. The Spend-Based Method
This approach multiplies the amount of money spent on a good or service by an economic emissions factor (e.g., kg CO₂e per dollar spent). Most companies use this approach as a starting point but transition to more accurate methods as they advance in their sustainability journey.
Advantages
- Fast and scalable across categories
- Useful for initial hotspot identification
- Helps fill data gaps when activity data is unavailable
Limitations
- Lower accuracy, especially during periods of inflation or economic volatility
- Cannot reflect actual emissions reductions by suppliers
- Misalignment between price and emissions (e.g., high-cost items may not be high-emission)
2. The Average Data Method
This method uses average emissions factors for goods or services, based on industry datasets. For instance, industry life cycle assessments (LCAs) might be used to estimate the emissions associated with a kilogram of steel purchased.
Advantages
- More accurate than spend-based
- Suitable for companies refining emissions data to enable targeted reductions
Limitations
- Lack of raw data granularity
- Geographic variation limited
3. The Supplier-Specific Method
The supplier-specific method is the most accurate approach and involves collecting actual emissions data directly from suppliers. This includes LCAs, environmental product disclosures (EPDs), product carbon footprints (PCFs), supplier emissions reports, or Environmental, Social, and Governance (ESG) reports.
Advantages
- High accuracy and granularity
- Builds engagement with suppliers
- Enables tracking of supplier improvements over time
Limitations
- Challenging to scale across many suppliers
- Data may be confidential, inconsistent, or incomplete
- Requires continuous updating of supplier information
4. The Hybrid Approach
Adopting a hybrid approach allows many companies to maximize their data collection efforts by applying the supplier-specific method for high-impact purchases and using average or spend-based methods elsewhere. This tiered approach enables efficient use of resources while maintaining data quality for critical emission sources.
Where Can You Find Scope 3.1 Data?
Data for scope 3.1 emissions typically resides in procurement and finance functions. Purchase orders, invoices, and supplier contracts often contain critical information such as volume, product category, and spend. However, collecting, organizing, and analyzing this data can be resource-intensive, especially for companies with complex and global supply chains. Data type and availability play a key role in determining the method used for calculating emissions, impacting the accuracy and ability to reduce emissions.
What Are the Challenges in Measuring Scope 3.1 Emissions?
As most organizations will attest, measuring scope 3.1 has many challenges, from resource constraints to data availability. As organizations intensify their climate commitments, they are increasingly confronted with a range of technical, logistical, and strategic barriers that make accurate measurement and consistent reporting difficult. Understanding these roadblocks is critical to developing more resilient and impactful scope 3.1 measurement practices.
- Data availability and quality: Collecting high-quality data is often a bottleneck, with many organizations lacking the systems to track product-level or supplier-specific emissions. Without the proper tracking in place, emissions calculations rely on less accurate methods, making it difficult to reflect or meet reduction efforts.
- Supplier inconsistencies and allocation complexities: Even when suppliers share emissions data, the methodologies, boundaries, and underlying assumptions across them will vary widely. This adds an extra layer of difficulty to data aggregation. Additionally, the allocation of supplier emissions may vary based on the supplier’s chosen method, such as economic (based on spend and supplier revenue/emissions) or service-level (based on units purchased and supplier output/emissions). These inconsistencies can significantly affect reported totals, making it challenging to compare suppliers.
- Complex, multi-tiered supply chains: Upstream emissions can span multiple suppliers across different geographies and industries. Visibility often becomes cloudier beyond Tier 1 suppliers, making it difficult to account for emissions generated deeper in the value chain.
- Timing and synchronization: Aligning procurement, emissions calculation, and reporting cycles can be challenging. Delays in supplier disclosures or emissions factor updates can create reporting lags and misalignment.
Top Five Strategies to Reduce Scope 3.1 Emissions
Reducing scope 3.1 emissions requires balancing precise measurement with targeted action. This means identifying high-impact categories, collaborating with key suppliers, and harnessing available emissions data to improve accuracy and accountability. Here are five strategies organizations can use to start driving impact:
- Prioritize key categories and suppliers: Not all purchases contribute equally to emissions. Conduct a hotspot analysis to identify the highest-emitting goods or services and prioritize the top suppliers for engagement. Consider prioritizing the share of emissions, the share of procurement spend, and the current methodology type.
- Engage suppliers and set expectations: Encourage suppliers to measure and disclose their emissions, invest in LCAs or PCFs, and set their own science-based targets. Collaborative initiatives, such as supplier engagement programs, can support progress.
- Leverage readily available supplier reports: Many electronic companies, cloud providers, and industrial products provide detailed emissions data through EPDs, LCAs, and specific service emissions reports. For example, AWS and Google offer detailed emissions reports for data hosting and services. Leveraging these can help reduce uncertainty and improve accounting accuracy in software-heavy organizations. However, they should be utilized with caution, as some providers have faced scrutiny in 2026 for reporting efficiency gains without disclosing cloud-specific energy use or the growth in embodied hardware emissions behind it.
- Identify opportunities for low-carbon inputs: The same reports that help improve reporting accuracy can also provide more detail on the material inputs of purchased goods. This level of information can enable organizations to pursue opportunities for lower-carbon inputs to reduce emissions.
- Invest in centralized data systems: A centralized platform for carbon accounting data management can streamline emissions tracking, improve visibility, and enable scenario modeling. Several of the other strategies cannot be as effective without the right tools in place to manage this key information.
Turning Complexity Into Opportunity
Tackling scope 3.1 emissions may feel daunting, but it’s also where some of the biggest climate opportunities lie. By investing in better data, fostering supplier collaboration, and integrating sustainability into procurement practices, companies can unlock innovation, resilience, and long-term value. Organizations that lead on scope 3.1 will not only meet emerging disclosure standards but will shape the low-carbon supply chains of the future.
Frequently Asked Questions
What are scope 3 emissions, and why do they matter?
Scope 3 emissions are all the indirect greenhouse gas emissions in a company's value chain, everything from raw material extraction and purchased services to product use and disposal. They matter because they're usually the majority of a company's footprint. They also fall outside a company’s direct control, which makes them the hardest to measure and the most scrutinized by regulators and investors.
What is included in scope 3.1 emissions?
Scope 3.1 covers the cradle-to-gate emissions of everything a company buys, i.e. all emissions generated up to the point of delivery. That includes raw materials, intermediate goods like steel and electronic components, packaging, office equipment, professional services, and cloud computing. It captures the supplier's extraction, energy use, manufacturing, waste, and transport. It does not include emissions from using or disposing of your own products, which sit in other scope 3 categories.
What are the methods for calculating scope 3.1 emissions?
There are four. The spend-based method multiplies spend by an emissions factor per dollar, which is fast, scalable, and the usual starting point. The average-data method applies industry emissions factors to physical quantities, like kilograms of steel. The supplier-specific method uses actual supplier data such as LCAs, EPDs, or product carbon footprints, and is the most accurate. Most companies land on a hybrid, the final method, which takes supplier-specific data for high-impact purchases and uses estimates elsewhere.
How can companies reduce scope 3.1 emissions?
Start with a hotspot analysis to identify where emissions are coming from. This will usually show that a small share of suppliers and categories drives most of the footprint. From there, engage those suppliers on measurement and targets, use supplier reports and EPDs to replace estimates with real data, and use that detail to identify lower-carbon inputs. Centralized carbon accounting data makes each of these repeatable rather than a one-off exercise.
Do AI data centers' hardware purchases count as scope 3.1 emissions?
Yes, for a data center operator, servers and chips are purchased goods, and therefore count in scope 3.1.
Decarbonizing Concrete and Steel with Environmental Attribute Certificates
Key Takeaways
- Concrete and steel contribute 13% of global CO2 emissions. These materials represent substantial scope 3 emissions for companies that are building new infrastructure, including data centers.
- Low-emission alternatives and production technologies are nascent and not yet widely deployed.
- Environmental attribute certificates (EACs) are an innovative solution that can stimulate manufacturing of sustainable commodity materials and overcome market barriers to direct physical procurement.
- Relae (formerly Carbon Direct) and Microsoft developed criteria to guide Microsoft’s high-quality EAC procurement, accelerate decarbonization, and catalyze market expansion for decarbonized materials across supply chains.
- These criteria cover seven key areas: qualifying conditions, social harms and benefits, environmental harms and benefits, additionality and baselines, catalytic impact, verifiability, and leakage.
A Vision for Low-Carbon Concrete and Steel
Concrete and steel are essential for modern construction, but are carbon-intensive. Combined, they account for approximately 13% of global carbon dioxide (CO2) emissions. As the demand for data centers and infrastructure development continues to grow, so do the embodied emissions from concrete and steel. There is an urgent need to decarbonize these sectors so that construction of new facilities remains consistent with climate commitments.
However, the markets for low-carbon concrete and steel are still in their infancy. Market barriers such as low production volumes, contracting complexity, geographic concentration of supplies, and long-distance transportation limit buyers’ ability to directly procure low-carbon building materials. As buyers and sellers overcome these barriers, the market for low-carbon building materials will mature, giving producers the confidence to invest in new manufacturing facilities and giving buyers access to decarbonized materials directly in their supply chain.
Environmental attribute certificates (EACs) represent the sustainability attributes of a material commodity, unbundled and transacted separately from the physical commodity. EACs are transacted at a price that reflects the additional cost of sustainably producing the material. While barriers to direct procurement of low-carbon materials persist, EACs can serve as a powerful tool to signal demand for low-carbon concrete and steel, catalyze market expansion, and accelerate decarbonization.
[cta]
Microsoft’s Approach to Emissions from Building Materials
To address embodied emissions and help achieve its ambitious 2030 carbon-negative goal, Microsoft aims to deeply reduce its scope 3 emissions, including from building materials, by more than half compared to a 2020 baseline. In 2023, scope 3 emissions made up over 96% of Microsoft’s total greenhouse gas footprint. To meet its 2030 target, Microsoft is focusing on addressing supply-chain emissions related to data center construction and the embodied carbon of the commodity materials used to build them. Microsoft is already working to decarbonize its building material supply chain using the following three tactics:
- Reduce the need for concrete and steel through innovative building design or the use of lower-carbon alternatives, such as sustainably sourced mass timber.
- Directly engage with suppliers to procure low-carbon alternatives to conventional concrete and steel.
- Invest in and help pilot new low-carbon production pathways.
EACs represent a fourth approach to decarbonization that can both reduce emissions and catalyze industry growth. Taken together with Microsoft’s design, procurement, and investment tactics, these actions underpin a comprehensive strategy for long-term decarbonization of the built environment.
High-Quality EACs Support Decarbonization
EACs offer a virtual, market-driven solution to decarbonize the built environment by allowing companies to support low-carbon material production when physical supply chain barriers impede direct procurement. EACs for concrete and steel function similarly to other market-based decarbonization mechanisms such as sustainable aviation fuel (SAF) certificates in the aviation sector and renewable energy certificates (RECs) in the energy sector.
These mechanisms work by decoupling the environmental benefits of low-carbon production from the physical materials themselves. EACs allow companies to claim the environmental benefits of physical low-carbon concrete or steel production, even if they do not directly or physically source those materials. EACs provide a verified claim that a purchaser has procured a product with lower emissions, enabling companies to meet climate targets and demonstrate their commitment to sustainability.
Due to their virtual nature, which limits physical oversight of the supply chain, EACs also exacerbate risks such as double counting, greenwashing, fraud, social harms, and environmental harms. Therefore, adhering to transparent, rigorous criteria is foundational to mitigating these risks.
New Criteria to Guide Procurement of High-Quality EACs
To support the integrity and effectiveness of EACs in these sectors, Relae and Microsoft have co-developed Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors. These robust criteria serve as a public resource for companies seeking credible and impactful EAC procurement pathways for low-carbon concrete and steel.
The criteria address seven key areas:
- Qualifying conditions: EACs must complement, not displace, direct procurement and represent significant emissions reductions.
- Social harms and benefits: EACs must not further social harms and should promote community engagement and social benefits such as meaningful workforce development opportunities and community climate resilience.
- Environmental harms and benefits: EACs must not perpetuate environmental harm, but instead should mitigate risks and, ideally, provide additional environmental benefits.
- Additionality and baselines: Projects funded by EACs must drive real, meaningful emissions reductions in terms of financial, regulatory, and common practice additionality.
- Catalytic impact: Prioritize transformative technologies with sector-wide decarbonization potential.
- Verifiability: Set a high bar for documentation, transparency, and independent auditing.
- Leakage: Address risks of emissions displacement to support net-positive outcomes.
These criteria provide a robust framework for companies and stakeholders to evaluate and implement commodity EACs effectively, supporting impactful change. They balance rigor with flexibility and acknowledge the nascent state of the markets for low-carbon concrete and steel. Sectoral decarbonization will advance over time, shifting the thresholds for what is considered significant, additional, and catalytic in EAC transactions. This science-driven framework can adapt to advancements in policy, industry practices, and technological readiness, ensuring EACs remain a relevant and impactful tool for years to come.
Sector-Specific Insights
In addition to providing overarching criteria and guidance on procuring EACs for the built environment, Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors also provides insights into the unique challenges and opportunities of decarbonizing concrete and steel.
Decarbonizing Concrete
EACs can support innovative decarbonization strategies for concrete, such as producing alternatives to clinker and cement, adopting supplementary cementitious materials (SCMs), and reducing emissions from cement kilns through electrification or integrating carbon capture and storage (CCS). Performance-based standards and evolving building codes may also unlock new opportunities for low-carbon concrete.
The Global Cement and Concrete Association (GCCA) publishes a rating system, Low Carbon Concrete (or Cement) Ratings, which defines eight separate low-carbon grades (AA through G). These grades correspond to the depth of decarbonization and are based on a sliding scale related to the material’s compressive strength. When developing these criteria, Microsoft considered grades AA through D to be eligible for consideration in its EAC procurements.
Decarbonizing Steel
EACs can support transformative technologies for decarbonizing steel, like direct reduced iron (DRI) with electric arc furnaces (EAF) powered by green or blue hydrogen. This support can enable the steel sector to move beyond incremental improvements and focus on capital-intensive solutions that have the potential to reshape the industry.
ResponsibleSteel, an independent standards and certification organization with membership that is broadly representative of the steel industry, publishes decarbonization progress levels, with four separate grades (PL1–PL4). These grades correspond to the depth of decarbonization and are based on a sliding scale related to the fraction of recycled scrap use in the steel manufacturing process. When developing these criteria, Microsoft included levels PL2 through PL4 for consideration in its EAC procurements.
A Blueprint for EAC Market Development
Relae and Microsoft crafted Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors as a public resource that can help shape the future of the commodity EAC market.
These criteria are designed to:
- Communicate intent: Communicate Microsoft's intent to support the decarbonization and scaling of physical commodity supply chains where they have been previously limited.
- Guide decision-making: Serve as a public guide for Microsoft's decision-making process, explaining the rationale behind pursuing or declining specific EAC pathways.
- Set high-integrity standards: Maintain high integrity for EACs at an early stage, ensuring they are used to enable future physical procurement by supporting market development.
- Stimulate partnership opportunities: Encourage potential partnerships and purchasing pipelines by clearly describing criteria for high-quality EACs.
- Publicly share detailed thinking: Build on previous work and publicly share detailed thinking, aiming to stimulate market development and guide procurement decisions.
Practical Recommendations for Implementing EACs
Whether you are a supplier, buyer, policymaker, or sustainability advocate, these new criteria offer actionable insights to help you navigate the complexities of EACs in the built environment. From setting significance thresholds to ensuring verifiability to avoiding double counting, the criteria provide clear guidance to maximize the impact of EAC-supported projects.
Beyond the technical aspects of EACs, these criteria aim to address their broader social and environmental implications. The criteria focus on the importance of community engagement, transparency, and equitable distribution of benefits in EAC project planning, ensuring that decarbonization efforts contribute to a more sustainable and just economy. The criteria are backed by extensive research, stakeholder consultations, and industry expertise.
[cta]
Frequently Asked Questions
What is an environmental attribute certificate (EAC), and how does it differ from buying low-carbon concrete or steel directly?
An environmental attribute certificate represents the sustainability attributes of a commodity material such as concrete or steel, unbundled from the physical material and transacted separately from it. Direct procurement means a buyer purchases low-carbon concrete or steel and takes physical delivery of it for a specific project. An EAC purchase instead allows a buyer to fund and claim the environmental benefit of sustainably produced materials that are sold as typical commodities, and apply that benefit against conventional commodities in their own supply chain. EACs are priced to reflect the additional cost of producing the material sustainably, which sends a demand signal to producers. This makes EACs useful where market barriers—limited production volumes, geographic concentration of supply, or long-distance transportation—prevent buyers from sourcing low-carbon materials directly.
How do EACs for concrete and steel compare to renewable energy certificates (RECs) or sustainable aviation fuel (SAF) certificates?
Environmental attribute certificates for concrete and steel share a structure with renewable energy certificates and sustainable aviation fuel certificates: each decouples the environmental benefit of low-carbon production from the physical product, letting a buyer fund and claim that benefit without taking physical delivery. There are two key differences. First, conventional RECs represent electricity with a zero-emissions footprint, while every tonne of concrete or steel behind an EAC still carries embodied emissions — the certificate demonstrates reduction against a baseline, not a zero-emission product. Second, REC and SAF markets are established, while EACs for concrete and steel are nascent. Both differences are why rigorous criteria matter: quantifying the reduction credibly is harder, and the virtual structure carries risks of double counting, greenwashing, and fraud.
Will EACs let companies claim emissions reductions without actually reducing their built environment climate footprint?
An EAC purchase does not change the materials in a buyer's own buildings; it funds lower-emission production elsewhere in the market. Credible EAC frameworks therefore require that certificates complement rather than displace direct procurement, that they represent significant reductions against a defensible baseline, and that the funded project would not have proceeded without EAC revenue. The criteria published by Relae and Microsoft enable buyers to address these requirements directly in their procurement processes - addressing the climate and reputational risks of low-quality certificates. Used this way, EACs become an additional tool to address emissions from the built environment, supplementing design changes, direct procurement, and investment in new production pathways.
Who should use these criteria?
Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors, co-developed by Relae and Microsoft, is a public resource intended for four audiences. Buyers pursuing scope 3 reductions can use it to evaluate whether a given certificate represents a credible, additional emissions reduction. Suppliers and project developers can use it to understand what purchasers of high-quality certificates look for before bringing a project to market. Policymakers and standards bodies can draw on it while shaping rules for an emerging market. Sustainability practitioners and advocates can use it as a reference point for assessing claims made about low-carbon concrete and steel. The criteria are designed to evolve as these sectors decarbonize, and users may adapt them to meet their own levels of capability and ambition.
Who Pays for AI? The Hidden Cost of Rising Data Center Demand
Key Takeaways
- AI data centers are driving the fastest electricity demand growth in decades: US data centers consume an estimated 4 to 5% of US electricity today, projected to reach as much as 9 to 17% by 2030 (EPRI).
- Without deliberate cost allocation, residential and small-business ratepayers subsidize private AI infrastructure.
- Peer-reviewed modeling projects data center growth could raise US power costs 6 to 29% nationally by 2030, and up to 57% in the hardest-hit regions.
- Utility commissioners, state regulators, and policymakers now have working models to draw from, including large-load tariffs, dedicated rate classes, and direct assignment of transmission costs.
AI Data Center Energy Demand Is Testing the Limits of the Grid
AI is driving electricity demand at a pace the US grid has not seen in decades. US data centers already consume an estimated 4 to 5% of the nation's electricity, and EPRI projects that share could reach 9 to 17% by 2030. Behind nearly every AI model and digital product is the invisible infrastructure that powers it: data centers. These facilities are resource-intensive, requiring massive amounts of electricity to power servers, substantial water for cooling, and extensive new grid infrastructure.
In the race to decarbonize the grid, data centers are emerging as a critical pressure point. This infrastructure sits at the intersection of digital growth and climate action, forcing a difficult question: who pays to power AI?
Legacy Utility Models Weren’t Built for this Growth
Utilities must upgrade aging grid infrastructure to meet this new surge in electricity demand, while maintaining reliability. Under legacy utility frameworks, it's often ratepayers who foot the bill for those upgrades. And the costs are not distributed equitably.
Traditional utility planning assumes that increased demand justifies expanded investment in generation and transmission infrastructure. When a new type of large customer, like a tech company, moves into a utility’s service territory, utilities plan new infrastructure to meet that projected demand.
Utilities typically recover the cost of new infrastructure through a process called rate base cost recovery. This allows utilities to charge all customers in the “rate base” for the expenses incurred, including thousands of individuals, families, and small businesses, even when those costs stem from the demands of just a few large users.
This legacy model struggles to keep pace in the AI boom era, where massive new electricity demand can double within a few years, a scale of growth that used to take decades. Additionally, while data centers create short-term construction jobs, there are almost no lasting employment benefits for local communities.
It's clearly inequitable for all ratepayers to bear the costs of upgrading the grid to benefit just a small number of massive data centers. But that's not the only problem. If utilities decide to meet new power demand from large data centers with new fossil fuel generation, such as gas peaker plants, they risk creating stranded assets: infrastructure that becomes obsolete or uneconomical as climate targets, clean energy mandates, or the cost-effectiveness of renewables accelerates. Once built, ratepayers will have to continue paying for these long-lived investments for years, even if they are underutilized or retired early due to policy shifts. This risk is no longer hypothetical: to serve projected data center load, Georgia regulators approved a plan to extend the lives of two massive coal plants to as late as 2038, and Virginia regulators stripped roughly $350 million tied to speculative early-stage data center projects out of Dominion Energy's revenue forecast.
If utilities are locking in decades of new fossil fuel generation to meet short-term data center growth, ratepayers may be left holding the bag for infrastructure that contradicts their climate goals and state mandates, with little ratepayer or community input into the decision. Effectively, local communities may be subsidizing a technology that they did not directly ask for in the first place and has little to no direct community benefits. The result is a long-term misalignment between utility investment strategy and the public interest.
Ratepayers Bear the Cost of Private AI Expansion
The economic burden of data center expansion can fall disproportionately on households and small businesses. But data centers, as the largest and fastest-growing users, often negotiate bespoke contracts, subsidized rates, or fixed-price electricity agreements that shield them from long-term cost volatility.
This can result in other customers, especially residential and low-income ratepayers, bearing a disproportionate share of the infrastructure and maintenance costs. In many states, residential and low-income customers already experience energy cost burdens that exceed affordability thresholds. Adding the weight of infrastructure investments to serve energy-intensive data centers, without sharing those costs equitably, exacerbates an already regressive utility cost allocation system.
Georgia shows how these costs reach ratepayers even when regulators act. Georgia Power customers absorbed six rate increases totaling roughly $43 per month between 2023 and 2025, and while regulators approved a base-rate freeze through 2028, the freeze excluded fuel and storm costs. In 2026 fuel-cost proceedings, testimony showed that large industrial and data center customers raise other customers' monthly fuel costs by 5 to 11%, prompting the Georgia Public Service Commission to open an investigation into how fuel costs are allocated between large loads and residential customers. Ratepayers noticed: in November 2025, both Georgia PSC seats flipped in elections run explicitly on utility bills and data center cost-shifting. In Virginia, regulators approved a rate increase of roughly $16 per month for typical Dominion Energy residential customers amid surging data center demand.
These examples are not anomalies. A peer-reviewed study in Environmental Research Letters projects that data center growth could raise US power costs 6 to 29% nationally by 2030, and up to 57% in the hardest-hit regions, with Virginia among the steepest. This is a systemic shift in energy demand, one that places a growing burden on communities and lacks clear public benefits.
Environmental and Community Impacts Are Mounting
Beyond economic impacts, the geography of data center development reveals another layer of inequity: environmental justice. Data center siting often prioritizes affordable land, low resource costs (e.g., electricity, water), and climate considerations like heat variability. They also rely on proximity to pre-existing fossil fuel generation and transmission infrastructure. Research now confirms the pattern this creates: an analysis of 550 EPA-regulated data centers found that air pollution burdens near data centers rise with the share of people of color living nearby, and a 2026 Washington state study found more than half the state's data centers sit in census tracts with the highest concentrations of people of color.
These communities often absorb the negative externalities beyond their electricity bills, including increased air pollution from peaker plants and on-site diesel or gas backup generators, traffic and construction noise, water stress, and land use changes. Simultaneously, they do not receive direct net positive benefits. Frontline communities are paying attention to this trend, and opposition has become a defining force in where AI infrastructure gets built. Gallup finds 71% of Americans now oppose a data center in their own area, and Data Center Watch counted roughly $130 billion in projects blocked or delayed in the first quarter of 2026 alone. The stakes of community opposition are increasing and intensifying.
The consequences of ignoring communities are now playing out in federal court. At xAI's Colossus facility in Memphis, developers operated dozens of on-site gas turbines without air permits in a majority-Black area already burdened by industrial pollution. After the Shelby County Health Department granted permits for a subset of turbines in July 2025, the fight moved to xAI's second campus across the state line: in April 2026, the NAACP filed a Clean Air Act lawsuit over roughly 27 unpermitted gas turbines at the Colossus 2 site in Southaven, Mississippi, seeking penalties of more than $100,000 per day. On-site power can help reduce demand on the grid, which can be a benefit. But when that generation runs without permits or oversight, nearby communities bear unmeasured health and environmental impacts from hazardous emissions, and the litigation now underway shows how quickly unpermitted power becomes a legal and reputational liability.
To date, data center developers do not appear to have maximized potential community benefits or engagement. Data centers have not typically employed many local residents beyond construction phases, resulting in limited economic benefits, particularly when facility ownership is distant from the local community or has few local ties. When these same communities already experience high pollution burden or economic precarity, the cumulative impact of a new data center can deepen existing vulnerabilities.
Water use is also a mounting environmental justice concern. Many data centers rely on evaporative cooling systems that draw millions of gallons of water per day, and peer-reviewed research finds significant gaps in how the industry discloses its water footprint. In drought-prone regions, this can stress already-depleted aquifers and heighten tensions over water access.
The result is a high-stakes tradeoff between digital infrastructure and local resource resilience, one that communities should be a part of deciding.
States and Regulators Are Writing the New Rules
Virginia, the "Data Center Capital of the World," is home to 674 data centers that consume an estimated 25% of the state's electricity, a share EPRI projects could reach 39 to 57% by 2030, the highest of any state. After legislators considered but did not pass data center bills in the 2025 session, the 2026 General Assembly passed roughly 15 data center bills, including legislation, signed in May 2026, directing regulators to ensure data center costs are not subsidized by other customers, along with new requirements for site impact assessments and water-use reporting. Virginia's State Corporation Commission had already created a dedicated rate class for high energy use customers, with 14-year contract terms and minimum charges that apply whether or not the projected load materializes, and in August 2026 it went further, ordering Dominion to develop a tariff that directly assigns transmission costs to the data centers that trigger them.
Virginia is not alone. Ohio regulators approved a landmark tariff requiring large data centers to pay for 85% of the capacity they request, whether or not they use it. Oregon's POWER Act created the nation's first legislated rate class for data centers. Texas gave its grid operator authority to curtail large loads during emergencies. Minnesota, California, Alabama, Tennessee, South Dakota, Nebraska, and Florida have all enacted their own ratepayer-protection measures, and at the federal level, FERC ordered the nation's largest grid operator to write new rules for data centers that co-locate with power plants, citing the need for consumer protection and clear cost allocation. State energy officials are also proactively planning for data center expansion.
The direction is clear. The unresolved question is whether these reforms move faster than the costs already flowing to ratepayers.
What Is the Public Good of Data Centers?
AI infrastructure powers innovation, job creation, research, and the technologies we rely on every day. But it may also bring inequitable social and direct financial costs. Like highways, factories, and pipelines before them, the question remains: What is the public good of AI data centers? How should we hold data center developers accountable to the public interest, which values a clean energy future? We need clear-eyed assessments of how data centers impact energy affordability, climate progress, and environmental equity.
Yesterday's utility policy frameworks were not designed for hyperscale AI data centers. The reforms now underway are a start, but without sustained attention they may still force the public to subsidize private expansion, through economic and environmental costs, often without equitable community engagement, climate accountability, or local benefit.
AI Data Center Growth Needs Accountability, Equity, and Reform
To align data center growth with the public interest, the stakeholders involved now have proven models to build on:
- Utilities and regulators can require large customers to pay an equitable share of new infrastructure costs, as Ohio's minimum-take tariff and Virginia's dedicated rate class now do.
- Public Utility Commissions can mandate equity and community impact assessments during siting and permitting, following Virginia's new site assessment requirements.
- States can condition tax incentives and zoning approvals on local hiring, emissions reductions, and community benefits agreements.
- Data center developers can prioritize clean power and commit to transparent, equitable community engagement and benefits plans before opposition, litigation, and cancellations decide the outcome for them.
As we build the digital backbone of the next century, we must avoid repeating injustices of the past. A just energy transition requires more than megawatts: it demands equity, policy interventions, and real climate progress.
[cta]
Frequently Asked Questions
How do utilities typically recover the cost of infrastructure built to serve large data center customers, and why does this burden fall on other ratepayers?
Utilities recover infrastructure investments through rate base cost recovery: regulators approve new generation, transmission, and distribution spending, and the costs are spread across all customers in the rate base through their monthly bills. That model worked when demand growth was gradual and diffuse, but when a single data center campus drives hundreds of megawatts of new investment, standard cost allocation spreads those costs across households and small businesses unless regulators adopt a special tariff or rate class that assigns them to the customer who caused them.
What are stranded assets in the context of data center power demand, and how do they create long-term risk for utilities and ratepayers?
Stranded assets are long-lived infrastructure investments, like new gas plants built for projected data center load, that become underused or uneconomical before they are paid off, whether because demand never materializes or because policy and market shifts overtake them. Because utilities recover those costs through rates over decades, ratepayers keep paying even if the asset sits idle. The risk is acute today because data center demand forecasts are highly uncertain: Virginia regulators removed roughly $350 million tied to speculative data center projects from one utility's revenue forecast in 2025.
Why do data centers often locate in rural or low-income communities, and what are the environmental justice implications?
Data center siting favors cheap land, fast permitting, low-cost power and water, and proximity to existing generation and transmission, conditions most common in rural, low-income, and historically marginalized communities. Research confirms the consequences: analysis of 550 EPA-regulated data centers found air pollution burdens rise with the share of people of color living nearby. These communities absorb the air pollution, water stress, noise, and land use impacts while receiving few lasting jobs or direct benefits.
What regulatory or policy tools can states and Public Utility Commissions use to ensure data center growth doesn't unfairly shift costs to residential and small-business ratepayers?
The toolkit has expanded rapidly since 2025. Commissions can create dedicated large-load rate classes and tariffs with minimum take-or-pay provisions, long contract terms, collateral requirements, and exit fees, as Ohio and Virginia have done; directly assign infrastructure enhancement costs to the customers that trigger them; and require site impact assessments during permitting. Legislatures can codify ratepayer protections, require water and load-forecast transparency, and condition tax incentives on community benefits, models now in place in at least eight states.
This commentary reflects public policy analysis and opinion, not legal advice or regulatory determinations.
Scope 1 Emissions Explained: How to Track, Report, and Reduce Operational Carbon
Key Takeaways
- Scope 1 emissions are direct and controllable, making them a powerful starting point for decarbonization.
- Reducing scope 1 emissions can improve energy efficiency and lower operating costs.
- Reporting on scope 1 emissions is now required under new climate regulations, and companies that act now will gain an edge.
Why Scope 1 Emissions Matter Now
When we talk about corporate decarbonization, scope 2 and scope 3 emissions tend to take up the headlines, with a focus on renewable energy certificates (RECs) or challenges like complex supply chains. But scope 1 emissions, those produced directly from sources a company owns or controls, don’t get as much airtime. This is a missed opportunity.
As AI data center growth pushes companies towards on-site power, more organizations are confronting scope 1 boundaries for the first time. Scope 1 emissions enable companies to take immediate, tangible action to cut carbon, drive operational efficiencies, and get ahead of growing regulatory pressure.
What Are Scope 1 Emissions?
Scope 1 emissions are the direct greenhouse gas (GHG) emissions from sources that a company owns or controls. They mostly come from activities where fuels are combusted on-site within an organization’s operations. For industries that combust high amounts of fuels within their operations (e.g., oil and gas, chemicals, manufacturing), scope 1 can represent a significant share of the company’s emissions. For industries that outsource most of their production, scope 1 can be a smaller share of the overall footprint.
Scope 1 emissions typically fall into four categories:
- Stationary combustion: Emissions from burning fuels on-site for heating, manufacturing, or electricity generation. This includes boilers, furnaces, and turbines at company facilities.
- Mobile combustion: Emissions from company-owned or operated vehicles and equipment, such as cars, aircraft, delivery fleets, ships, or construction machinery.
- Fugitive emissions: Unintentional leaks or releases of gases, often from refrigeration and air conditioning systems. These can have an outsized impact because many refrigerants have global warming potentials (GWPs) hundreds or even thousands of times greater than carbon dioxide.
- Self-produced energy: Emissions from electricity, heat, or steam generated on-site, such as through natural gas-fired generators or cogeneration plants, even when the energy is used internally.
Identifying and categorizing scope 1 emissions correctly are the first steps toward uncovering potential operational improvements and carbon reduction approaches.
On-Site Power for AI Data Centers
As AI pushes data center operators toward on-site (“behind-the-meter”) power, a high-stakes accounting question follows: are those behind-the-meter emissions scope 1 or scope 2? The answer comes down to control, not location.
Under the GHG Protocol, emissions from on-site generation are scope 1 only when the reporting company owns or financially controls the generating asset (i.e., the self-produced energy category above). In most data center power deals, a third party owns and operates the generator and sells the electricity to the data center. In that structure, the company buying the power reports the emissions as scope 2, and the company generating the power reports the combustion as scope 1. Given the growth in emissions from the scale of AI infrastructure, getting the boundary right matters for corporate credibility.
Why Scope 1 Emissions Are a Strategic Priority
While scope 3 is often talked about as the largest source of emissions for corporations, that isn’t the case for all industries. For heavy sectors like oil and gas, chemicals, and manufacturing, scope 1 emissions aren't just significant - they are the bedrock of the emissions story. Other industries depend on these sectors' outputs to operate their own businesses, meaning that decarbonizing heavy industries’ scope 1 emissions can also drive reductions across other organizations’ scope 3 emissions.
Since scope 1 emissions are typically within a company’s direct operational control, they present a great starting point for decarbonization. Unlike scope 3 emissions, which require influencing suppliers, customers, or partners, companies can take immediate action on scope 1 sources. Even for industries with relatively small scope 1 footprints, reductions can often happen more quickly through internal decisions, such as equipment upgrades, process improvements, or fuel switching.
Regulatory momentum is also making scope 1 management increasingly urgent. Policies like the European Union’s Corporate Sustainability Reporting Directive (CSRD), California’s Climate Corporate Data Accountability Act (SB 253), and global ISSB-aligned frameworks are requiring companies to measure and publicly disclose their scope 1 emissions. Even within voluntary frameworks, reporting on scope 1 emissions is getting tighter. Within the Science-Based Targets Initiative (SBTi)’s new draft Net Zero Standard, scope 1 emissions must now have a separate target from scope 2 emissions, and the boundary must cover 100% of scope 1 emissions whereas previously the boundary was 95% of emissions. These market shifts highlight the importance of reducing scope 1 emissions.
Operationally, reducing scope 1 emissions offers business value. Many scope 1 reduction strategies, such as upgrading to more efficient equipment or reducing fuel waste can lower energy bills, improve asset performance, and reduce maintenance costs. For companies focused on both sustainability and profitability, targeting scope 1 emissions delivers a strong return on investment.
How to Calculate Scope 1 Emissions
To reduce scope 1 emissions, companies need to know exactly what and how much they are emitting. Calculating scope 1 emissions starts with gathering the right data at the facility level and understanding the activities that generate emissions.
What to Measure
Scope 1 emissions come from activities such as fuel combustion in boilers or vehicle fleets, refrigerant leaks from cooling systems, and on-site energy generation. Ideally, companies should collect activity data, like gallons of diesel used, cubic meters of natural gas consumed, or kilograms of refrigerant leaked and replaced. In cases where direct measurement isn’t possible, companies often rely on estimations, using financial spend data or industry intensity metrics as a proxy for fuel consumption.
Where to Find the Data
Facility-level data is the backbone of comprehensive and comparable scope 1 accounting. Much of the required data can be sourced from utility bills, fuel receipts, maintenance logs for HVAC and refrigeration systems, and reports from on-site equipment operators. Increasingly, companies are deploying sensors to capture real-time data on fuel consumption, refrigerant leaks, and on-site energy generation, improving both accuracy and responsiveness.
How to Calculate the Emissions
Emissions are calculated by applying the emissions factors (i.e., the amount of greenhouse gases emitted per the quantity of fuel or refrigerant) to the collected activity data. Many companies use carbon accounting software to automate calculations, track emissions over time, and ensure consistency with recognized standards like the GHG Protocol. Expert support is often critical, especially for sectors with complex operations. Carbon accounting experts help ensure the data is complete, auditable, and aligned with evolving regulatory requirements.
Accurate scope 1 data builds a strong foundation for compliance as well as for setting credible reduction targets and tracking long-term performance.
How to Reduce Scope 1 Emissions
With scope 1 emissions data in hand, companies can begin identifying and implementing reduction strategies. Because these emissions are within the organization’s operational control, companies often have multiple levers they can pull.
Operational Strategies
- Fuel switching: Replacing fossil fuels like natural gas or diesel with lower-carbon alternatives, like green hydrogen or renewable electricity, can significantly reduce direct emissions from stationary and mobile combustion. Depending on the switch, this could result in higher scope 2 emissions, but these can be more readily addressed through market-based instruments, thus lowering the overall footprint.
- Equipment upgrades: Modernizing boilers, generators, fleets, and other combustion-based equipment can improve energy efficiency and cut emissions. Newer technologies often perform better and emit less.
- Process innovation: In emissions-intensive industries like cement and steel production, rethinking industrial processes can yield dramatic reductions. Low-carbon production methods are increasingly becoming commercially viable.
- Leak detection and repair: Methane leaks from oil and gas operations and refrigerant leaks from cooling systems are major contributors to scope 1 emissions. Deploying monitoring technologies and maintaining rapid-response repair programs can fix leaks before they lead to large amounts of emissions.
Strategic Procurement
- Vendor selection: Companies can prioritize suppliers that offer lower-emissions alternatives for fuels, materials, and services.
- Fleet electrification: Procuring electric vehicles for delivery, service, and logistics fleets reduces both emissions and long-term fuel and maintenance costs.
- Equipment design: Working with suppliers to source modular, emissions-efficient machinery can reduce on-site fuel use and improve flexibility over time.
Driving Innovation Through R&D
- Low-carbon products: Research and development teams can design products and processes that inherently require less energy, or lower-carbon energy, to produce, lowering scope 1 emissions at the source.
- Material innovation: Developing new chemistries or alternative materials can avoid high-emission production methods, contributing to broader decarbonization goals.
- Closed-loop systems: Designing circular, waste-reducing systems can minimize both raw material use and the on-site emissions associated with production and disposal.
Reducing scope 1 emissions often requires up-front investment, whether it’s upgrading equipment, switching to alternative fuels, or embedding low-carbon principles into procurement and R&D strategies. While the initial costs can be substantial, they deliver long-term value through improved operational efficiency, reduced regulatory risk, lower energy expenses, and enhanced brand value in a marketplace that increasingly rewards climate leadership.
Frequently Asked Questions
What are the main categories of scope 1 emissions?
Scope 1 emissions fall into four categories: stationary combustion (fuels burned on-site in boilers, furnaces, or turbines), mobile combustion (company-owned or -operated vehicles and equipment), fugitive emissions (leaks of refrigerants or methane, which often carry outsized global warming potential), and self-produced energy (electricity, heat, or steam generated by equipment the company owns or controls).
Which regulations require companies to report scope 1 emissions, and when do they take effect?
The EU’s Corporate Sustainability Reporting Directive (CSRD) already requires scope 1 disclosure for companies in its first reporting waves. In the US, California’s SB 253 requires companies with over $1 billion in annual revenue doing business in California to report scope 1 and scope 2 emissions, with first reports due November 10, 2026. ISSB-aligned disclosure rules are extending similar requirements across other jurisdictions.
What’s the fastest way for a company to start reducing scope 1 emissions?
Start by measuring at the facility level, since this activity data shows where emissions concentrate. From there, the quickest wins are usually operational, such as repairing refrigerant and methane leaks, upgrading inefficient combustion equipment, and electrifying vehicle fleets, because they sit within the company’s direct control and often pay back through lower fuel and maintenance costs.
Is behind-the-meter power scope 1 or scope 2?
It depends on who controls the generating asset. If a company owns or financially controls its on-site generation, the emissions are scope 1. If a third party owns and operates the generator and sells the power- the structure behind most data center power deals- the buyer reports those emissions as scope 2 under the GHG Protocol’s Scope 2 Guidance.
How SAF Mandates in the EU and UK Are Reshaping Aviation Fuel Markets
Key Takeaways
- SAF and e-SAF mandates are reshaping the aviation fuel market. The EU and UK impose steep non-compliance penalties, turning regulatory requirements into a strategic lever for those who act early.
- Non-compliance is costly. Penalties run roughly 3 times the cost of compliance in the EU and from about 2 to 13 times in the UK, making long-term planning essential to mitigate risk.
- e-SAF producers have a unique opportunity. Mandates and penalties are shifting the economics of aviation fuel, making e-SAF more attractive despite historically high production costs.
How SAF Compliance Stacks Up
Airlines and fuel suppliers operating in Europe and the UK face growing economic uncertainty due to stringent mandates requiring the adoption of sustainable aviation fuels (SAF) with carve-outs for SAF produced from renewable hydrogen, also known as Power-to-Liquids (PtL) or e-SAF.1 These mandates, aimed at reducing aviation emissions, carry steep penalties (up to 13 times the cost of compliance) for fuel suppliers who fail to meet required quotas. While this creates cost uncertainty for airlines and passengers, it opens a strategic opportunity for e-SAF producers. These producers are challenged by high production costs relative to other SAF on the market and a limited set of buyers that can afford the premium on a voluntary basis.
This piece explores the cost implications for aviation being shaped by these EU and UK SAF mandates and outlines how airlines and suppliers can respond strategically to minimize risk and maximize opportunities. By understanding these dynamics, industry stakeholders can turn regulatory compliance into a source of competitive advantage.
Understanding SAF Mandates in the EU and UK
The EU Commission’s ReFuelEU Aviation regulation, part of the European Green Deal, sets binding targets for aviation sustainability. Beginning in 2025, ReFuelEU mandated that aviation fuel suppliers offer a minimum percentage of SAF and e-SAF at EU airports. By 2030, suppliers must blend at least 6% SAF, including 1.2% e-SAF. To discourage tankering practices (carrying excess fuel for return trips, increasing emissions), ReFuelEU Aviation requires airline operators to refuel at least 90% of their annual aviation fuel needs at a given EU airport before departure.
In parallel, the UK Department for Transport (DfT) mandates a higher SAF blend of 10% by 2030 and places greater emphasis on reducing reliance on hydrogenated esters and fatty acids (HEFA) SAF fuels, which face eventual limitations on feedstock supply. HEFA’s allowable share will decline annually from 100% in 2025 to 42% in 2040. The UK also includes a sub-mandate specifically for PtL SAF.
The Real Cost of Falling Behind on SAF Mandates
The financial impact of these mandates is significant. Each year, the European Union Aviation Safety Agency (EASA) publishes regulatory reference prices for SAF, e-SAF, and conventional jet fuel (CJF) that anchor non-compliance penalties in the EU, most recently the 2025 Aviation Fuels Reference Prices for ReFuelEU Aviation. Using these reference prices for current-year costs and projected production costs or prices for SAF, e-SAF, and CJF from 2030–2050, the following analysis compares EU and UK compliance versus non-compliance penalties, converting all figures to US$/gallon.2
The price gap between SAF and fossil jet fuels remains wide. In 2025, SAF is approximately three times the price of CJF, while e-SAF is nearly twelve times more expensive. Projections indicate this price gap narrows by 2030, but far more for SAF than for e-SAF. The projected price of SAF in 2030 is US$5.46/gallon, more than double the estimated US$2.41/gallon for CJF. The price difference is even greater for e-SAF: with no traded e-SAF market yet, projected 2030 prices span US$5.70/gallon to US$33.00/gallon, with a central estimate around US$18/gallon, or roughly seven times the price of CJF.
Estimated Jet Fuel Prices 2025-2050 (US$/Gallon)
Source: European Union Aviation Safety Agency. 2025 Aviation Fuels Reference Prices for ReFuelEU Aviation. (link); UK Department for Transport. SAF Mandate: Final-stage Cost Benefit Analysis. (link); EUROCONTROL. Aviation Outlook 2050: Main Report. (link)
The mandates carry strict penalties for non-compliance. Penalties for non-compliance in the EU are set at a minimum of two times the price difference between SAF and CJF per gallon of unmet obligation. Additionally, fuel suppliers must supply any unmet fuel obligations in subsequent reporting periods, which pushes the cost of non-compliance in the EU to three times the cost of compliance.
In the UK, penalties work differently: fuel suppliers must pay a fixed buy-out price per megajoule (MJ) of unmet obligation, which translates to US$24.64/gallon of unmet SAF obligation and US$26.08/gallon of unmet e-SAF obligation.3 Because the buy-out is fixed while compliance costs vary, UK penalties range from about 2 times the cost of compliance for e-SAF to 13 times for SAF in later years. The intent is clear: regulators are serious about pushing aviation towards sustainable fuels.
Cost-Comparison of Compliance vs Non-Compliance (US$/Gallon)
Note: The cost of compliance under both mandates is calculated as the price premium of SAF/e-SAF over CJF per ton, using region-specific SAF prices: the EU SAF price reflects HEFA-based supply (ReFuelEU imposes no HEFA cap), while the UK SAF price is a weighted average of HEFA and higher-cost advanced pathways based on the UK's declining HEFA cap. The e-SAF (PtL) price is the same in both regions.
Cost-Comparison of Complicance vs Non-Compliance (US$/Gallon)
e-SAF Has a Policy-Driven Market Opportunity
These price differentials present risk and opportunity. Airlines and fuel suppliers that fall short of compliance will face steep penalties. Those who comply strategically, can mitigate those risks and benefit from financial incentives that help offset higher fuel costs.
Incentive structures support SAF and e-SAF production. For example, the EU’s Emissions Trading System (ETS) has allocated allowances to offset SAF costs, especially for renewable fuels of non-biological origin (or e-SAF). Similarly, the UK offers tradable certificates and has now legislated a Revenue Certainty Mechanism (Sustainable Aviation Fuel Act 2026) that will guarantee SAF producers a set strike price through contracts-for-difference-style agreements, funded by a levy on fuel suppliers, with the first allocation round expected in 2027. The UK’s ETS also provides an indirect incentive as SAF use by airlines lowers compliance costs through reducing required allowances.
Strategic Recommendations for Airlines and Suppliers
To navigate this shifting landscape, airlines and fuel suppliers must think strategically about procurement and compliance, potentially including:
- Proactive procurement: Airlines and fuel suppliers should prioritize securing long-term contracts with SAF and e-SAF producers. Early engagement can help ensure access to limited supply and stable pricing.
- Leverage incentive programs: Actively participate in available incentive schemes, such as the EU ETS and UK tradable certificates, to minimize compliance costs.
- Invest in e-SAF production: Consider strategic investments or partnerships in e-SAF production to align sustainability goals with regulatory requirements and financial incentives.
- Plan for volatility: Develop robust risk mitigation plans, using flexible procurement strategies and financial instruments to buffer against supply chain disruptions and price swings.
Turning Mandates into Market Momentum
As 2030 approaches, the pressure on airlines and fuel suppliers to comply with SAF mandates will intensify. Those who proactively respond to and embrace the mandates can transform regulatory requirements into strategic opportunities. Rather than viewing mandates as burdens, forward-looking stakeholders can use them to drive sustainable innovation and long-term resilience.
The EU and UK mandates for SAF and e-SAF represent an emerging shift in aviation fuel markets. Stakeholders that act now, by engaging with incentives and investing in sustainable fuel solutions, will emerge as industry leaders. Now is the time for airlines, fuel suppliers, and e-SAF producers to act decisively, transforming regulatory compliance from a costly obligation into a clear competitive advantage.
Frequently Asked Questions
What happens if an airline or fuel supplier misses its SAF mandate quota?
Fuel suppliers—the obligated parties—pay a penalty on every unmet tonne: in the EU, twice the price gap between SAF and jet fuel, plus supplying the shortfall in a later period; in the UK, a fixed buy-out price (£0.137/MJ for SAF, £0.145/MJ for e-SAF). Combined, non-compliance runs roughly 3 times the cost of complying in the EU and from about 2 to 13 times in the UK.
What is e-SAF, and how is it different from other SAF?
e-SAF, also called Power-to-Liquid (PtL) fuel, is made from renewable or low-carbon electricity, hydrogen, and captured CO₂ rather than biomass feedstocks. It costs more to produce than conventional SAF today, but both the EU (from 2030) and UK (from 2028) mandates carve out a specific, growing sub-quota for it.
What is the UK's Revenue Certainty Mechanism?
It is a UK government scheme, modeled on the Contracts for Difference structure used in the power sector, that guarantees SAF producers a set strike price for up to 10 years, funded by a levy on aviation fuel suppliers. It became law through the Sustainable Aviation Fuel Act 2026, and the first contract allocation round is expected in 2027.
Is the EU considering changes to its SAF mandate timeline?
The EU has scheduled a formal review of ReFuelEU Aviation for 2027, following calls from airline groups to delay the 2030 e-SAF sub-target. No delay has been adopted, and the European Commission has said it remains "fully committed" to both the SAF and e-SAF mandates and that the 2027 review will evaluate the regulation rather than revise it.
Can corporate buyers still claim SAF benefits from fuel used to meet these mandates?
No, mandated volumes are claimed in the compliance market, so to avoid additionality concerns, voluntary corporate scope 3 claims (typically made through SAF certificates and book-and-claim) must come from supply beyond what the mandates require. As mandate demand grows, the pool available to voluntary buyers tightens, which is why early procurement locks in both supply and price.
From Capture-Ready to Capture-Committed: Decarbonizing Natural Gas with CCS
Key Takeaways
- Data centers are driving surging demand for new, firm electricity supply, accelerating natural gas-fired power generation.
- Carbon capture and storage (CCS) offers a practical way to balance long-term climate commitments with the need for new electricity generation in the near term.
- New natural gas-fired power plants must be capture-committed, not just capture-ready, potentially delivering power in 18 months and decarbonized power 18-24 months later.
- Capture-committed plants integrate planning and finance for the CO₂ capture, transport, and storage value chain from the start.
- Relae believes early investment in engineering, infrastructure, and community engagement is essential to meet capture commitments.
A New Era of Electricity Demand and Climate Pressure
The US and much of the developed world are experiencing profound growth in electricity demand. Two main forces are driving this trend: (1) the push to electrify existing uses, such as vehicles and heating, to improve energy security, enhance system efficiency, and reduce air pollution; and (2) the growth of energy-intensive sectors like manufacturing, telecommunications, and AI data centers.
Among these drivers, AI is creating unique demands that catalyze specific investments in electric power generation. Astonishing AI data center buildout, led by a handful of large technology firms (sometimes called “hyperscalers”) and their utility and construction partners, is accelerating energy consumption. These firms prioritize speed. When asked for their top five criteria for bringing new AI infrastructure online, one executive responded: “Speed, speed, speed, cost, and carbon emissions.”
Data centers require reliable, always-on power (referred to as “firm power”). This differs from other use cases, such as residential or commercial, which do not need the same amount of power across all hours. While hyperscalers and their partners are investing in renewables, nuclear, and geothermal energy at a remarkable pace, renewable resources alone do not yet meet the exploding demand for firm power.
Natural Gas Provides Firm Power but Drives Emissions Higher
The mismatch between data center power needs and variable renewable generation is fueling a boom in natural gas-fired power generation. The pipeline of new natural gas-fired power plants is enormous. Plants under construction in 2025 would, by themselves, add roughly 25 million tonnes of greenhouse gases each year to the air and oceans. The full suite of plants in planning is at least 10 times larger. Existing gas plants are also being used more and staying online longer.
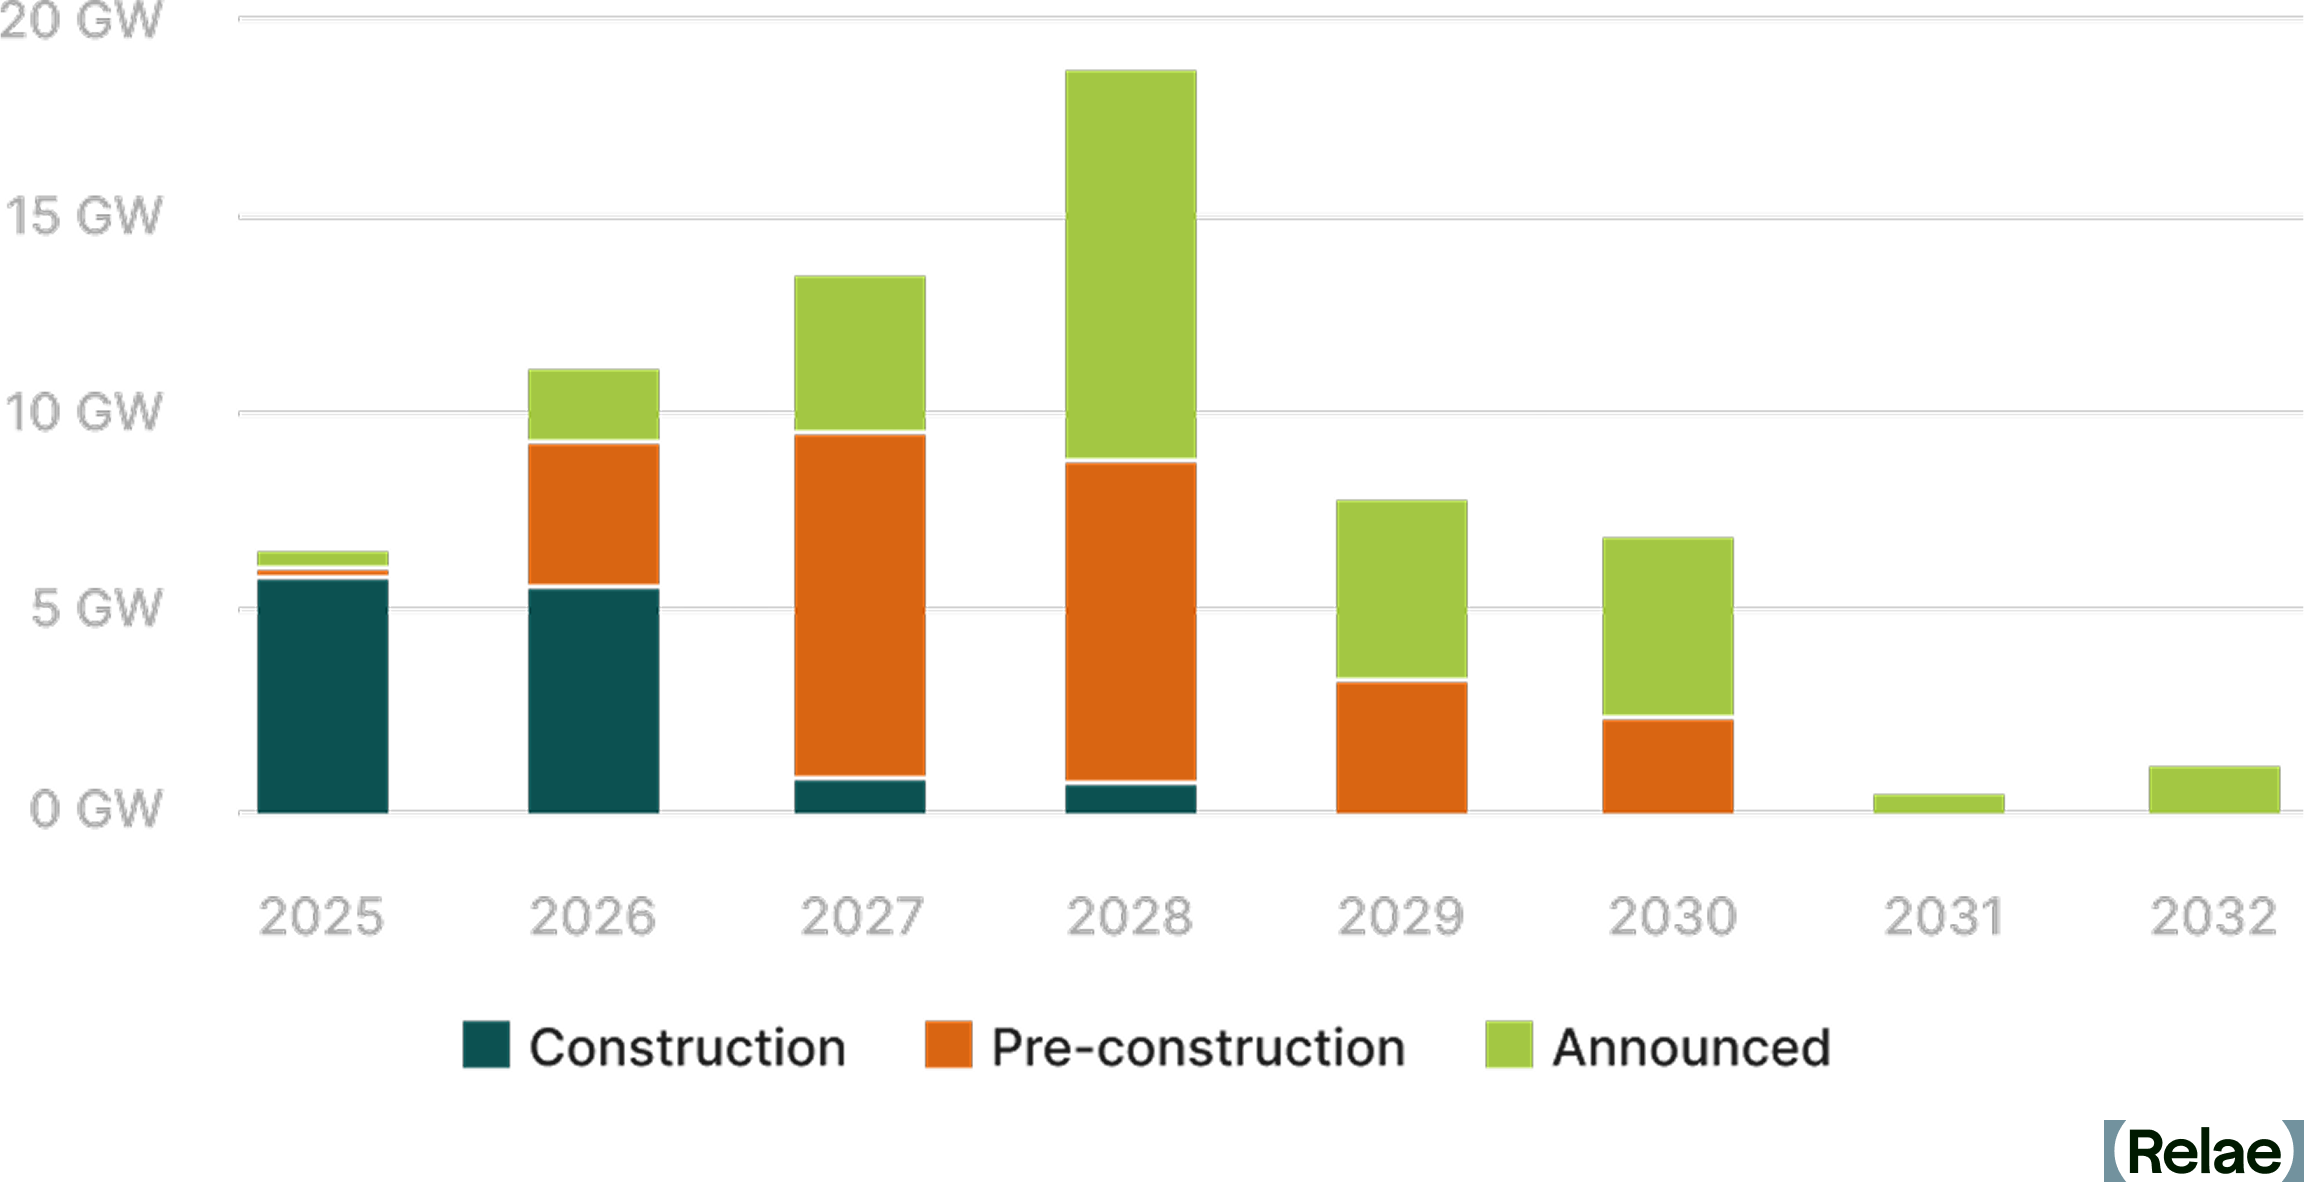
This rapid buildout is creating tension with corporate climate goals. Hyperscalers remain seriously committed to reducing emissions, but their ability to hit those targets is undermined by the need to procure new, large-scale electricity generation quickly.
Carbon Capture Aligns with Data Center Energy Demands
Carbon capture and storage is one way to bridge the gap. Data centers operate continuously and may have the ability to shift or curtail load. This demand profile suits the duty cycles of natural gas turbines and CCS facilities well. The potential to reduce direct emissions is profound: today’s CCS technology can capture 95% or more of CO₂ emissions at competitive costs in many markets.
This has led to a resurging interest in the concept of capture-ready gas power generation. New natural gas power plants can be built and brought online in 18 months. In a capture-ready plant, the developers integrate the necessary interfaces and reserve additional land, water, and energy to enable a carbon capture project to be built at a future date. In favorable locations, carbon capture can be added to a capture-ready plant in 18-24 months.
However, past experience shows that capture-ready plants rarely deliver. The ambition and commitment of the developers were contingent on policy and market signals that were either too small or never materialized. While the base plant may have made economic sense in terms of energy value for investment, it does not appear anyone was willing to pay the climate premium for CCS.
As David Hawkins of the Natural Resource Defense Council famously said, “If your plant is capture ready, my driveway is Ferrari ready.” To bring David’s humorous analogy back to the specifics here: don’t build a new driveway without at least a downpayment on the car.
How to Build Capture-Committed Power Plants for CCS
A better approach is building capture-committed plants, namely facilities that integrate CCS from the start. To be capture-committed, project developers must:
- Identify geologic storage for the many millions of metric tons of CO2 that these plants will produce each year over the next 20-30 years.
- Plan reliable CO₂ transportation from power generation to geologic storage by pipeline, rail, barge, or truck.
- Engage credible vendors of carbon capture technology that serve their needs and fit their goals.
- Fund front-end engineering design (FEED) studies.
- Arrange, or help to arrange, financing for the construction, commissioning, and operation of all necessary components in the CO₂ capture, transportation, and storage value chain.
- Ensure natural gas supply has near-zero fugitive methane emissions.
- Partner with local and frontline stakeholders to incorporate community impact into project planning, design, and financing.
Capture-committed plants send strong market signals. They help build the permitting pathways and develop the workforce, infrastructure, and community acceptance needed to avoid extra expense and delays. Done well, early commitments and investments will likely create repeatable models that reduce build times and costs.
A Path Toward Power That’s Clean Firm and Future-Ready
Eventually more carbon-free power in the form of renewables, nuclear, and geothermal energy will be deployed to serve national and international electric load growth for all types of electrification. Over time, these resources will likely displace natural gas. Until then, hundreds of millions of tons of CO₂ will be emitted each year unless commitments are made to take tangible action now.
Capture-committed natural gas-fired plants offer a pragmatic solution. With the right planning, financing, and community engagement, they can provide reliable power without locking in emissions, and they can deliver enormous benefits compared to uncontrolled operation. Federal and state governments can accelerate this transition by honoring and increasing CCS grants, supporting shared infrastructure, and streamlining permitting for CCS plants as they have for other clean energy supplies. These investments will enable the construction of cleaner, more resilient power infrastructure for the industries driving demand, from AI data centers to heavy industry.
[cta]
Frequently Asked Questions
What is the difference between a capture-ready and a capture-committed power plant?
A capture-ready plant creates an option to add carbon capture in the future, whereas a capture-committed plant treats capture as part of the project from day one. In a capture-ready plant, developers install the right interfaces and reserve extra land, water, and energy, but nothing obligates them to build the capture project, ever. A capture-committed developer secures options for CO₂ transportation and geologic storage, relationships with capture equipment vendors, funding for engineering studies, and financing across the full value chain before the base plant comes online.
Why have capture-ready plants historically failed to add carbon capture?
Nobody was willing to pay the climate premium. Capture-ready developers built plants that made economic sense on energy value alone, then waited for policy and market signals to justify carbon capture. Those signals were either too weak or never arrived, so the option went unexercised and no capture project was ever designed. The base plant runs uncontrolled for decades while the reserved land sits empty. David Hawkins of the Natural Resources Defense Council captured the problem well: "If your plant is capture ready, my driveway is Ferrari ready." Preserving an option costs very little. Exercising it costs a great deal, and capture-ready facilities rarely came with the funding to do so.
If renewables, nuclear, and geothermal will eventually displace gas, why invest in CCS for gas plants now?
Because greenhouse gas emissions happen in the meantime. Gas plants being built today will operate for 20 to 30 years, long before carbon-free resources scale enough to displace them. Left uncontrolled, they will emit hundreds of millions of tons of CO₂ over that span. Capture on those plants avoids most of it. Today's technology can capture 95% or more of CO₂ emissions at competitive costs in many markets.
What can federal and state governments do to accelerate capture-committed projects?
Three kinds of support matter most: funding, infrastructure, and permitting. Governments should honor and extend existing CCS incentives. Developers make capture commitments years before any revenue arrives, so uncertainty in government funding undermines the confidence these projects require. Governments should also support shared CO₂ transport and storage infrastructure. Common pipelines, rail terminals, and storage hubs make it easier for developers to secure physical CO2 offtake. Finally, permitting for CCS should be streamlined the way it has been for other clean energy supplies. Permitting delay is a leading cause of cost overruns, and a capture-committed plant should be able to pursue capture and storage with the same intensity and speed as electricity generation.
Marine Carbon Dioxide Removal: What It Is and How It Works
Key Takeaways
- Marine carbon dioxide removal (mCDR) uses ocean-based processes—primarily ocean alkalinity enhancement (OAE) and direct ocean removal (DOR)—to capture and durably store atmospheric carbon dioxide (CO₂), without the land and freshwater constraints of terrestrial methods.
- The ocean already absorbs roughly 29% of human-caused CO₂ emissions each year, according to the 2025 Global Carbon Budget, and mCDR technologies aim to safely enhance that natural uptake without worsening ocean acidification.
- For corporate carbon buyers and project developers evaluating mCDR, the Criteria for High-Quality Marine Carbon Dioxide Removal, developed by Microsoft and Relae, outlines standards to guide responsible mCDR deployment at scale.
Reducing carbon dioxide (CO₂) emissions alone is no longer sufficient to limit global warming to 1.5°C. To effectively address climate change, scientific consensus highlights the need to remove carbon dioxide already present in the atmosphere. Marine carbon dioxide removal (mCDR), a form of ocean-based carbon removal, offers a scalable solution by leveraging the ocean’s natural ability to absorb and store carbon, without the land and resource limitations associated with terrestrial carbon removal methods.
This guide explores the fundamentals of marine carbon dioxide removal, including how it works, the technologies involved, and its role in global decarbonization.
What Is Marine Carbon Dioxide Removal?
Marine carbon dioxide removal uses ocean-based processes to capture and store carbon dioxide from the atmosphere. mCDR techniques fall into two primary categories:
- Biotic CDR, which includes using photosynthetic fixation, microalgae cultivation, and terrestrial biomass sinking, to capture and store carbon.
- Abiotic CDR, which influences CO₂ concentrations and carbonate chemistry in the seawater to absorb atmospheric CO₂ without increasing acidity. There are two main abiotic mCDR pathways: ocean alkalinity enhancement (OAE) and direct ocean removal (DOR).
How Does Marine Carbon Dioxide Removal Work?
Marine carbon dioxide removal functions via the air-sea gas exchange—a process by which the atmosphere and surface seawater maintain equal CO₂ concentrations—meaning a shift in one leads to a corresponding change in the other. This exchange allows the ocean to absorb or release CO₂ back into the atmosphere depending on concentration levels and factors like pH.
Once absorbed by the ocean, CO₂ exists in several forms, including dissolved CO₂, carbonates, and bicarbonates, influencing the ocean's pH levels. As atmospheric CO₂ levels rise, the oceans absorb roughly 12 GtCO2 annually, approximately 29% of anthropogenic CO2 emissions. This increase is disrupting the natural CO₂ balance and contributing to ocean acidification.
mCDR methods like ocean alkalinity enhancement and direct ocean removal use safe and controlled processes to increase the amount of CO2 absorbed from the atmosphere while mitigating acidification.
Understanding Ocean Alkalinity Enhancement (OAE)
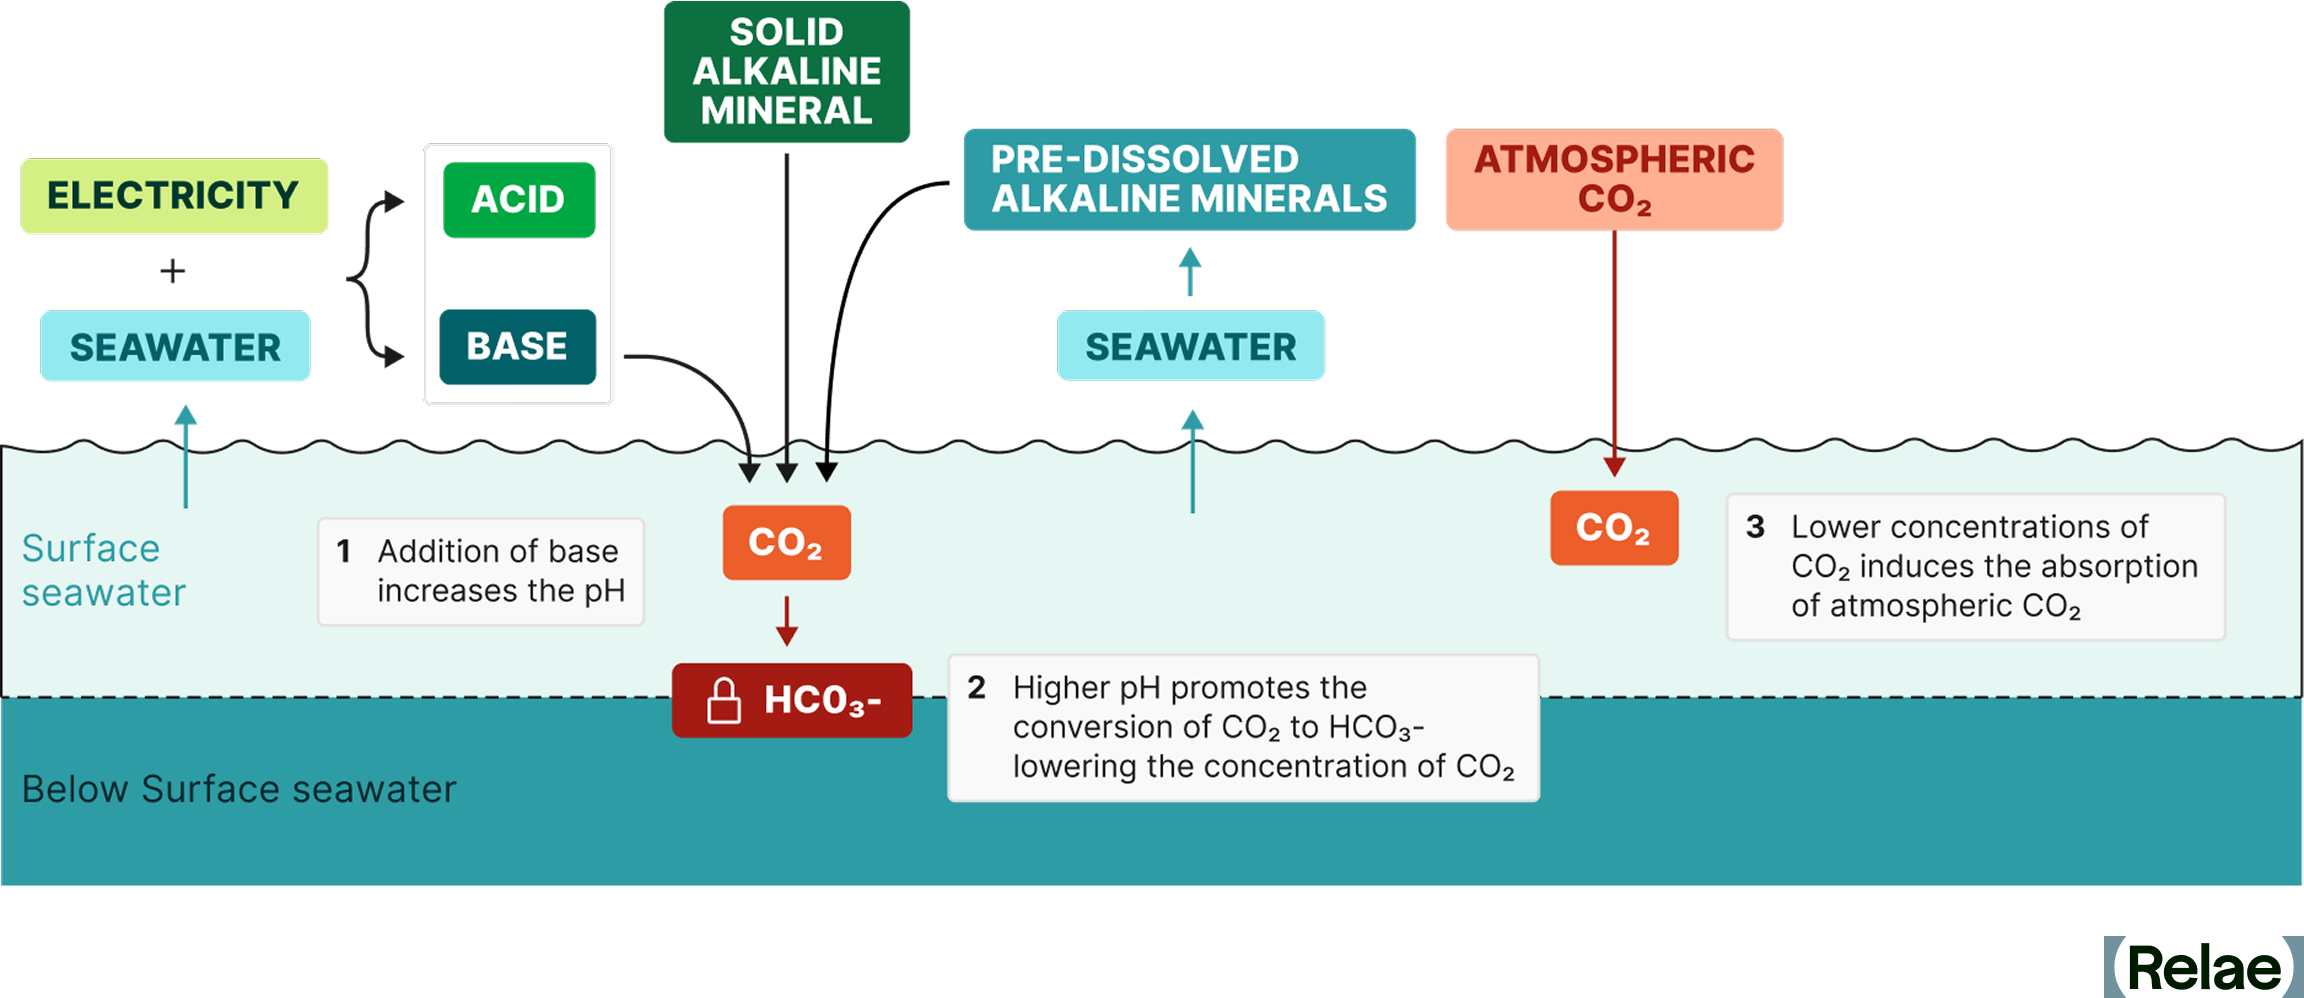
Ocean alkalinity enhancement (OAE) captures and stores atmospheric CO₂ as dissolved carbonates in the ocean by increasing the alkalinity of seawater using one of two primary methods:
- Adding alkaline minerals such as olivine or basalt to seawater.
- Using electrochemical methods to add alkaline compounds to seawater.
Both of these methods increase the alkalinity of seawater and, thereby, its capacity to absorb atmospheric CO₂ without acidification.
OAE methods can also differ by location and the manner in which seawater interacts with alkaline substances and atmospheric CO₂. This interaction may occur in the open ocean or within a controlled mCDR project facility. Each approach involves trade-offs: open ocean methods tend to be less energy-intensive but present greater uncertainties and challenges in measurement, reporting, and verification (MRV).
Understanding Direct Ocean Removal (DOR)
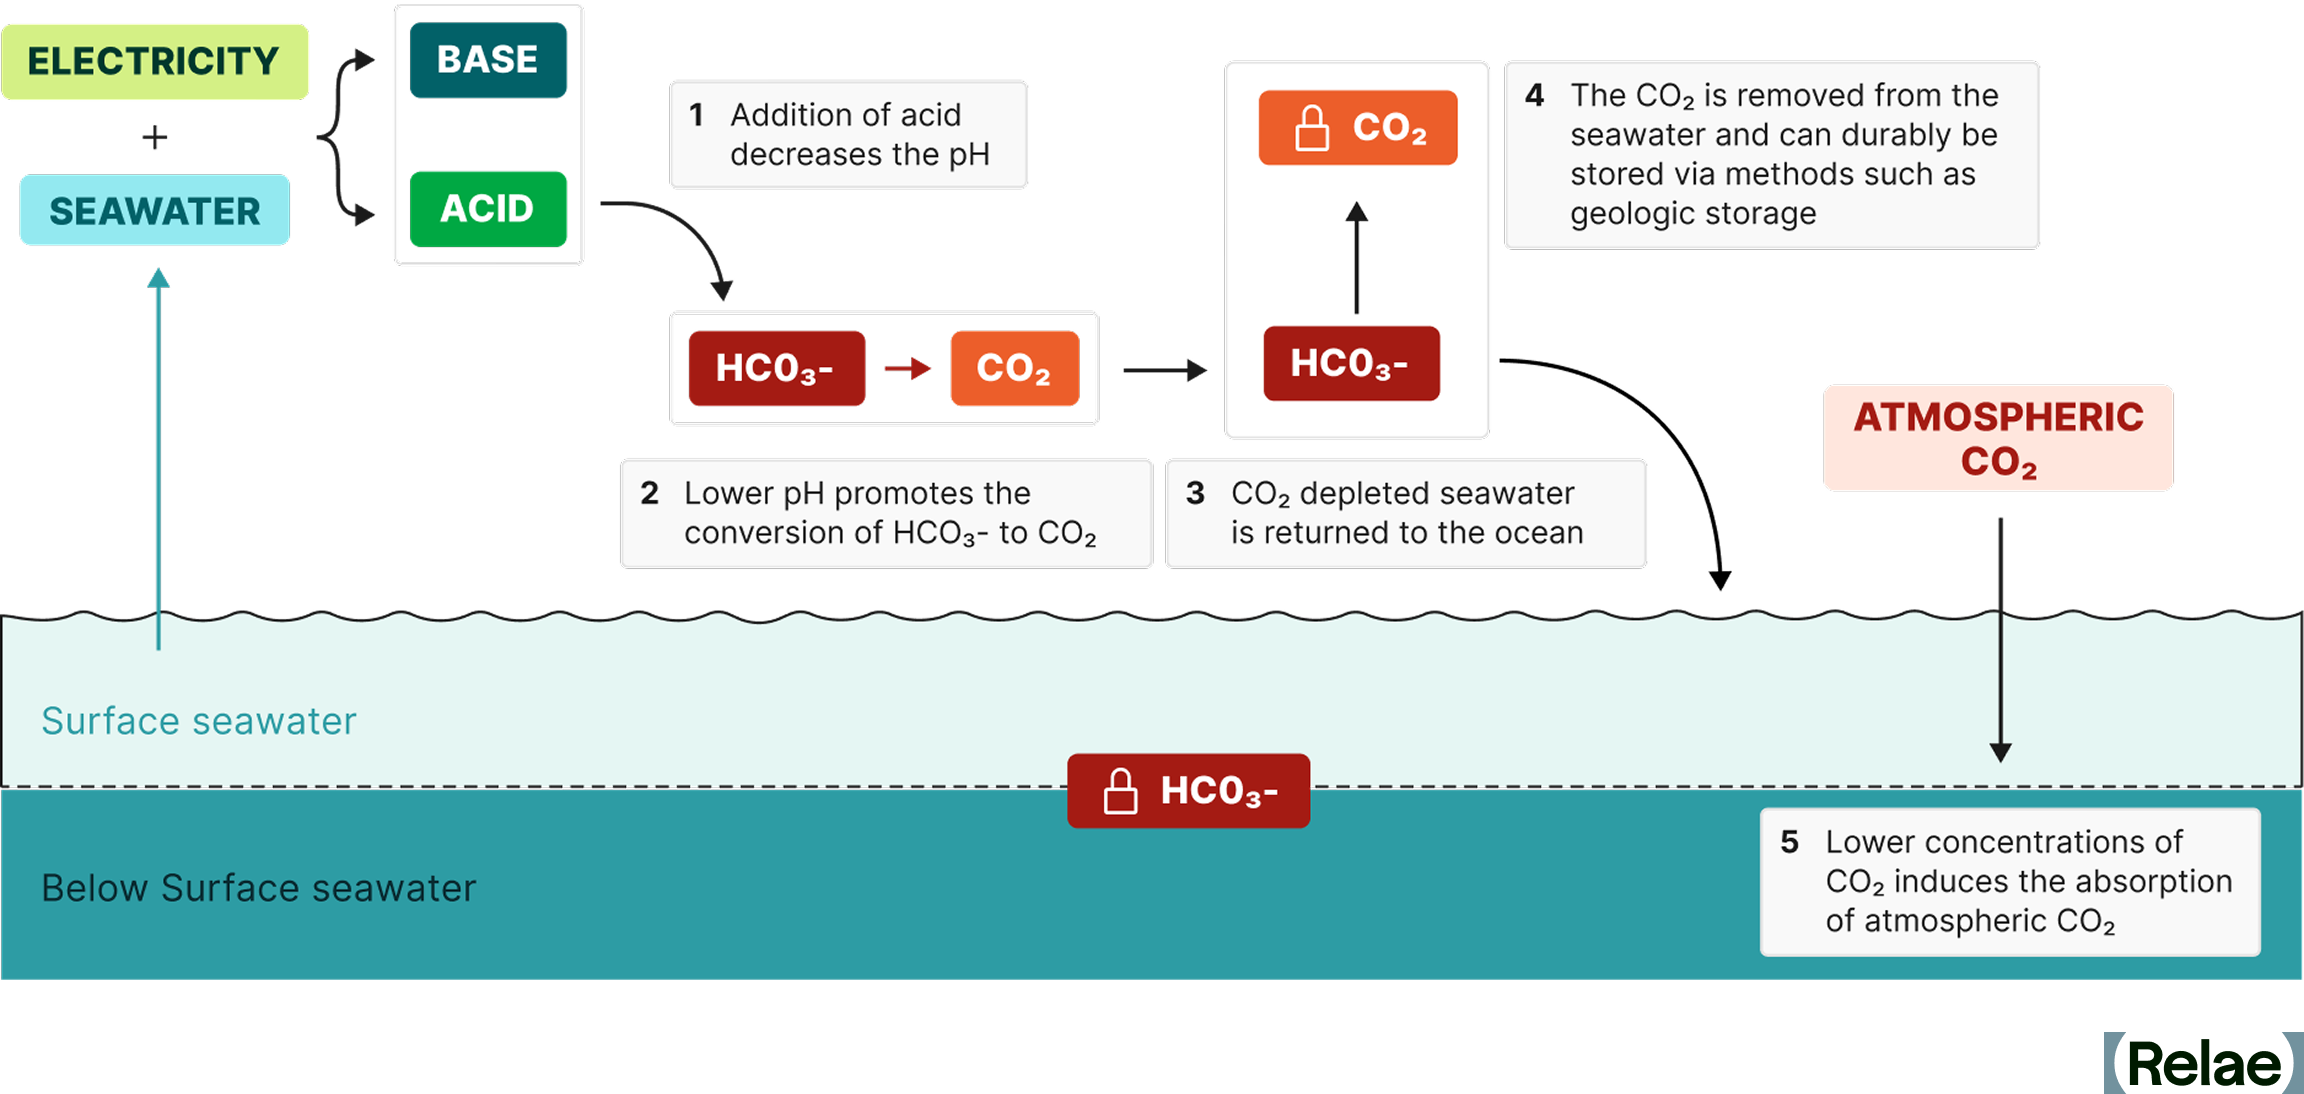
Direct ocean removal (DOR), also called direct ocean capture (DOC), removes CO₂ dissolved in seawater using the controlled acidification of seawater in a closed system using one of two primary methods:
- Electrochemical methods such as electrolysis of seawater or electrodialysis
- The addition of minerals like olivine and basalt.
The acidified and CO₂ depleted seawater is neutralized to native pH and allowed to equalize with and remove atmospheric CO₂. Once removed, CO₂ can be safely stored using geologic storage with a durability of >1,000 years.
Nomenclature for Direct Ocean Removal
Direct ocean removal is more commonly referred to as direct ocean capture. Relae believes the term direct ocean removal (DOR) is more accurate for two reasons:
- We think it is scientifically more accurate as both OAE and DOR remove CO₂ from the atmosphere but DOR directly removes CO₂ from the oceans, where in OAE, CO₂ is captured as bicarbonates in the ocean.
- DOC is a term for dissolved organic carbon, which is frequently used in mCDR project documents, reports, and the scientific literature.
Key Benefits of Marine Carbon Dioxide Removal
Understanding how mCDR works highlights its potential to address climate challenges. Here are the key benefits that make it a critical tool in global decarbonization strategies.
- Scalable carbon removal without land constraints: Marine carbon dioxide removal does not require large land areas or significant freshwater resources, making it highly scalable.
- Harnessing the ocean’s natural carbon sink: The ocean absorbs about 25% of human-generated CO₂ annually. mCDR enhances this natural process, increasing carbon storage without accelerating ocean acidification.
- Diverse technological pathways for flexibility: Technologies like ocean alkalinity enhancement and direct ocean removal offer flexible solutions tailored to different environments and project needs.
- Global reach with a large surface area: Covering over two-thirds of the Earth’s surface, the ocean provides an expansive platform for mCDR technologies globally.
- Potential to mitigate ocean acidification: Some mCDR methods, such as ocean alkalinity enhancement, not only remove CO₂ but also help restore ocean pH levels, supporting marine ecosystem health.
Challenges of Marine Carbon Dioxide Removal
While mCDR holds significant promise, it also presents challenges that must be addressed for responsible deployment.
- Technical scalability and efficiency: Scaling mCDR technologies to achieve meaningful carbon removal while maintaining energy efficiency remains a significant hurdle.
- Potential environmental impacts: Altering ocean chemistry may pose risks to marine ecosystems, with long-term effects still not fully understood.
- Measurement, reporting, and verification (MRV) complexity: Accurately measuring CO₂ removal and ensuring its durability requires advanced monitoring systems, which are still evolving.
- Regulatory and governance gaps: Clear global policies are needed to oversee mCDR deployment, manage environmental risks, and ensure accountability.
- Public perception and ethical considerations: Concerns around geoengineering and potential unintended consequences may impact public acceptance and policy support.
Deploying Marine Carbon Dioxide Removal
As mCDR technologies evolve, effective deployment will rely on adaptive management practices to address technical, environmental, and regulatory challenges. This includes robust MRV systems for accurate CO₂ removal tracking and continuous ecosystem monitoring to mitigate potential risks to marine life.
Collaborative efforts between scientists, policymakers, and project developers are key to establishing clear regulatory frameworks, optimizing technologies for efficiency and scalability, and building public trust. These practices ensure mCDR can be scaled responsibly while safeguarding ocean health.
The Future of Marine Carbon Dioxide Removal
As technologies like ocean alkalinity enhancement and direct ocean removal advance, their potential to deliver large-scale, durable carbon removal is becoming increasingly evident. Realizing this potential requires more than technological innovation—it depends on rigorous environmental monitoring, transparent reporting, and strong collaboration among project developers, carbon buyers, and policymakers.
Establishing clear, consistent standards for high-quality mCDR is essential to ensure both climate effectiveness and environmental safety. To support this, Microsoft and Relae have partnered to develop the Criteria for High-Quality Carbon Dioxide Removal.
Frequently Asked Questions
What is marine carbon dioxide removal (mCDR)?
mCDR uses ocean-based processes, primarily ocean alkalinity enhancement and direct ocean removal, to capture and durably store atmospheric CO₂. It works by increasing the ocean's natural capacity to absorb CO₂ without increasing acidification.
How does marine carbon dioxide removal compare to land-based methods like direct air capture or reforestation?
Unlike land-based approaches, mCDR doesn't require large land areas or freshwater, and the ocean's size gives it significant scaling potential. It's earlier-stage than more established pathways, though, with measurement and environmental monitoring standards still maturing.
Is marine carbon dioxide removal proven and scalable today, or still emerging?
mCDR technologies have shown promising results in lab testing and early deployments, but confirming safety and effectiveness at a large real-world scale requires more monitoring data. It's best described as an emerging pathway with strong near-term momentum, not yet a mature, at-scale solution.
What should a company look for when evaluating a marine carbon dioxide removal project or credits?
Buyers should look for rigorous carbon MRV paired with equally rigorous monitoring of ocean ecosystem health (eMRV), transparent reporting, and adherence to established frameworks like the Criteria for High-Quality Carbon Dioxide Removal.