Introducing the Diligence Collection: High-Quality Carbon Removal, Vetted
Key Takeaways
- Relae (formerly Carbon Direct) has conducted over 900 comprehensive, rigorous reviews of carbon removal (CDR) projects around the world. But fewer than 10% meet our standard for high-quality. In today’s market, scientifically-credible CDR supply is scarce.
- To identify high-quality projects, buyers and investors previously had to commission numerous deep diligences, which often made it a lengthy and complex process, not well-suited to most market participants.
- The Diligence Collection changes that paradigm by giving you direct access to existing comprehensive analysis on a curated set of high-quality CDR projects. The hard work of identifying high-quality projects is already done, allowing you to move faster, spend less, and procure with more confidence.
Relae Sets the Bar for High-Quality CDR
Since 2020, every year Relae has released an updated version of the Criteria for High-Quality Carbon Dioxide Removal in collaboration with Microsoft. The Criteria set the standard for scientific rigor across nine CDR pathways and across six technical dimensions. Using this standard, the Relae team has conducted diligence on over 900 CDR projects across 63 countries. Our diligence has been used for over 50% of all tonnes contracted through announced CDR offtake agreements worldwide, including diligence for the majority of tonnes from Microsoft’s announced offtakes. This gives Relae a uniquely deep understanding of the CDR market; and importantly, it has highlighted that high-quality projects in the voluntary carbon market are scarce.
Quality Is the Central Challenge in CDR Procurement
Only 10% of the projects that Relae has assessed meet our high-quality criteria. This means that without rigorous, scientific assessment, buyers and investors run real risk of exposing themselves to delivery shortfalls, financial loss, and reputational damage.
This presents a series of challenges to buyers and investors interested in procuring or investing in CDR. Conducting diligence on CDR projects is time-intensive, complex, and requires deep expertise. Building the internal capacity to rigorously evaluate a wide variety of CDR projects isn’t practical for most actors. But conducting the in-depth diligence required to procure or invest confidently requires real commitment, especially when a significant proportion of the projects diligenced may not be high-quality. Finding the needle in the CDR haystack isn’t easy.
The Case for Curated CDR
The Diligence Collection directly addresses these challenges by providing self-serve access to diligence on a curated set of high-quality CDR projects vetted by Relae. Every project has already been evaluated against the Criteria for High-Quality Carbon Dioxide Removal, the science-based benchmark jointly established by Relae in collaboration with Microsoft. The Collection includes projects reviewed on behalf of Microsoft and other major buyers, and more broadly reflects our diligence work across the market.
With the Diligence Collection, you're not starting from scratch. Instead, you're starting from a shortlist of some of the highest-quality CDR opportunities available, with robust scientific diligence to back them up. The bottleneck that's slowed procurement for so many organizations is no longer a concern.
The Collection offers two levels of diligence, matched to the level of scrutiny your commitment warrants:
- Desk review: An executive-level assessment using available project documentation, enough to make an informed shortlisting decision or purchase.
- Deep diligence: A comprehensive technical evaluation covering project design, operational risk, technology assessment, policy landscape, and community impacts, reflecting the same methodology that's informed the procurement programs of Microsoft and other major buyers.
Both tiers include the option to commission an updated evaluation as your needs evolve.
What Rigorous CDR Diligence Involves
The depth of Relae’s diligence sets the Diligence Collection apart. Our desk review process involves conducting detailed assessments to evaluate projects against 6 quality principles: social harms, benefits, and environmental justice; environmental harms and benefits; additionality and baselines; measurement, monitoring, reporting, and verification; durability; and leakage. The result is a comprehensive report that assesses projects against these criteria, highlighting the project's overall quality, strengths, and weaknesses in a clear, succinct way that supports decision-making.
Many of our reports dig even deeper. Our deep diligences assess both a project’s quality and its delivery risk. To evaluate delivery risk, we assess projects across 5 elements: technologic, economic, commercial, operational, and political. Deep diligence is conducted over 3-4 months, which includes weekly back-and-forth with the supplier and a site visit to understand all of the nuances of the project and validate developer claims on the ground. The resulting report not only documents a project's strengths and weaknesses, but also outlines risk mitigation measures and recommends improvements over time.
Broader Access, Stronger Market
Forward offtake demand in the CDR market has historically concentrated among a handful of large buyers, and as our 2026 State of the Voluntary Carbon Market report notes, diversifying that pool is essential to enabling the next generation of CDR supply. The Diligence Collection is built to support exactly that. By making the scientific rigor behind the world's largest CDR transactions available through a self-service platform, it opens credible procurement to organizations at any stage of purchasing. More buyers accessing high-quality, de-risked projects means more capital flowing to suppliers, more projects able to scale, and a more resilient market that doesn't depend on a small number of actors to function.
High-quality CDR supply is scarce, and the best projects are in high demand. The Diligence Collection gives you the foundation to act efficiently and with confidence, without starting from zero.
[cta]
Frequently Asked Questions
Who Can Access the Relae Diligence Collection?
The Diligence Collection is available to approved subscribers, including CDR buyers and investors seeking to more efficiently evaluate carbon removal projects. To preserve the independence and integrity of the Collection and protect proprietary diligence insights, access is not available to project developers or rating agencies.
How Is the Relae Diligence Collection Different From a Rating Agency or Market Intelligence Platform?
Most rating platforms optimize for quantity; we optimize for quality. Our process includes pathway-specific risk assessments and, in many cases, site visits from our in-house scientists, engineers, and technical experts—the same multidisciplinary team and judgment behind our own portfolio decisions and the procurement programs we support directly. The Collection also includes projects diligenced before they've received external ratings, giving you visibility into promising opportunities at the pre-commercialization stage.
Does Inclusion in the Relae Diligence Collection Mean Relae Endorses a Project?
Inclusion means a project was evaluated through our scientific diligence process and, at the time of review, met our Criteria for High-Quality Carbon Dioxide Removal. It reflects a positive diligence outcome based on the information available during the review and the project's stage of development at that time. As projects and market conditions evolve, we recommend considering whether updated diligence or additional evaluation is appropriate for your specific procurement or investment objectives.
Can I Request Diligence on a Project That Isn't Already in the Collection?
Yes. You can commission us to diligence a specific project based on your procurement or investment priorities. Whether it's later added to the Diligence Collection depends on a few factors beyond just meeting our quality bar, including consent from you as the commissioning buyer and approval from the project developer.
Carbon Removal
Relae helps carbon removal buyers, investors, suppliers, and project developers navigate a complex market shaped by evolving science, quality standards, delivery risk, and claims expectations. We combine carbon removal strategy, project-level diligence, and market intelligence informed by work with leading buyers and project developers to help you assess quality, build diversified portfolios, and scale high-integrity carbon removal.
Vetted, High-Quality Carbon Removal Projects


Hannah Brigham
Hannah Brigham

Hannah has professional and academic experience doing work related to carbon accounting, climate-smart agriculture, and project management. At Relae, Hannah works across the Science Team to both manage reviews of CDR projects and develop tools and processes to further improve Relae’s assessment of high quality CDR.
Prior to joining Relae, Hannah worked as a sustainability consultant at ClimatePartner. There she supported clients from a range of sectors in calculating corporate and product carbon footprints with a focus on companies in the agriculture sector. Hannah also served as a Peace Corps Volunteer in Madagascar, working alongside local community members to implement regenerative agriculture and gardening practices.
Zara Ahmed, DrPH
Zara Ahmed, DrPH
Prior to working at Relae, Dr. Ahmed was the Government Affairs and Policy Lead for the COVID-19 Response at the CDC. She rejoined CDC in August 2021 after two years at the Guttmacher Institute as the Associate Director for Federal Issues. Before her time at the Guttmacher Institute, Dr. Ahmed spent 10 years with the CDC, including seven years based overseas at US embassies in Rwanda, Namibia and Haiti as a senior technical advisor, and three years as the Associate Division Director for Policy and Communications in the Division of Global Health Protection at CDC headquarters in Atlanta.In addition, Dr. Ahmed has worked as a sexual health counselor at an alternative high school in Michigan and as a consultant in Bangladesh on the labor rights of migrant women. Dr. Ahmed has also conducted field research on sex worker rights in Cambodia, health financing in rural Cameroon, and donor coordination of malaria programs in Senegal. She holds a BA in political science from Brown University, MPP and MPH degrees from the University of Michigan, a MBA from the University of Oklahoma, and a DrPH from the University of North Carolina, where she is also an adjunct faculty member.
Certificate of Appreciation for Extraordinary Effort and Impact, US Embassy, Port-au-Prince (2016)
Center for Global Health Director’s Award for Partnership, CDC (2015)
Certificate of Appreciation for Exceptional Technical Support, US Embassy, Port-au-Prince (2015)
What to Read Next
The 2026 Criteria: Designing and Delivering High-Quality Carbon Removal
Key Takeaways
- High-quality carbon dioxide removal (CDR) projects require robust project management and oversight to deliver credits on time and at the promised volume; delivery risk is a distinct concern that quality standards alone don't catch.
- The sixth edition of the Criteria for High-Quality Carbon Dioxide Removal is the first to provide an approach to evaluating both credit quality and delivery risk, adding a new delivery risk appendix built around the TECOP framework: technical, economic, commercial, organizational, and political risk.
- The 2026 Criteria provides a framework for developers, investors, and buyers to evaluate both project quality and delivery risk.
- This year's update draws on 170 new diligence reports from 2025 and the input of more than 60 subject matter experts, building on a foundation of six years of lessons from professional diligence across hundreds of real-world CDR projects.
The Criteria Create a Shared Standard for Credit Quality
Relae (formerly Carbon Direct) first launched the Criteria for High-Quality Carbon Dioxide Removal (the Criteria) in collaboration with Microsoft in 2021 to help rapidly and justly scale the development of high-quality carbon dioxide removal (CDR) credits. The market didn't yet have a shared definition of what "high-quality" meant, so we laid out transparent, science-based benchmarks that gave developers, investors, and buyers a common foundation to work from. Every year since, we have gone back and sharpened those benchmarks so that they keep pace with the quickly evolving industry.
But a shared definition of quality doesn't guarantee the delivery of credits as planned. The 2026 edition is the first to tackle that gap directly, pairing the Criteria's quality benchmarks with a new framework for evaluating delivery risk.
The Six Principles of High-Quality Carbon Removal
The Criteria defines six science-based principles that apply across engineered, hybrid, and nature-based CDR approaches:
- Social harms, benefits, and environmental justice: The extent to which the project prevents new social harms to people and communities, reduces existing harms, and provides meaningful benefits distribution.
- Environmental harms and benefits: The extent to which the project minimizes and mitigates environmental harms, as well as provides environmental benefits.
- Additionality and baselines: The evidence that the project’s carbon removal would not have occurred without carbon finance.
- Measurement, monitoring, reporting, and verification (MMRV): The ability to accurately quantify carbon removal in a repeatable and verifiable way, and to develop a plan for long-term monitoring of the project.
- Durability: The likelihood that removed carbon remains stored over time, with mechanisms in place to mitigate reversal risk.
- Leakage: The extent to which project activities cause increased emissions elsewhere.
These principles provide a consistent foundation for carbon removal procurement, evaluation, and project benchmarking.
[cta]
Supporting the Delivery of High-Quality CDR Credits
"Projects must work better operationally and be more commercial. Quality and delivery risk shape a project's risk profile at every point in its life, and this edition of the Criteria is the first to give buyers a way to judge both at once." Dr. Julio Friedmann, Chief Scientist, Relae
Designing projects to meet high-quality CDR criteria is only part of the challenge. Effective project planning, management, and execution are also essential to ensure that high-quality CDR tonnes successfully reach the market as planned. As discussed in CDR 2.0: Five Pillars of Successful Project Deployment and Delivery, managing delivery risk requires developers, investors, and buyers to understand the risks that can affect project success and align on how these risks are assessed and mitigated.
To support this alignment, the 2026 Criteria introduced a new Delivery Risk Appendix, which establishes a common framework and language for identifying and evaluating key delivery risks for the first time. Drawing on our broader observations of the carbon removal market and established approaches to project risk management, the appendix highlights common delivery risks across two broad CDR project types: open systems and closed systems. It organizes these risks into five categories: technical, economic, commercial, organizational, and political factors, also known as the TECOP framework.
The TECOP Framework for CDR Delivery Risk
- Technical delivery risks are associated with the technical feasibility of the project design, implementation, and long-term operation of the project
- Economic delivery risks are associated with the project’s financing structure, financial modeling assumptions, and expenditure profile
- Commercial delivery risk reflects the extent to which a project's purchase agreements, supply arrangements, and key contractual relationships are secured or well-advanced.
- Organizational delivery risks center on the project developer's capacity and capability to successfully plan, execute, and manage a project of the appropriate size and complexity.
- Political delivery risks are associated with governance, policies, and potential changes in regulatory environments, as well as the local communities’ perception of and willingness to participate in projects.
New Additions to the 2026 Criteria
Since publishing the 2025 Criteria, Relae has conducted an additional 170 diligence reports across established and emerging CDR pathways, ranging from reforestation and enhanced rock weathering (ERW) to direct air capture (DAC). To date, less than 10% of all 900+ projects the team has reviewed have met the bar for high-quality. These diligence efforts, together with insights from market analysis and ongoing synthesis of the latest scientific and technical literature, have deepened our understanding of how CDR project quality has evolved over the past year.
The 2026 Criteria leverage these insights and the expertise of more than 60 subject matter experts to reflect advances across the CDR industry and address key weaknesses that remain in the market across all pathways.
A few of the most significant updates to the Criteria include:
Addition of Direct Counterparty Considerations: Direct counterparties are the organizations that developers partner with, and are structurally dependent on, to generate credits. This can include:
- Primary feedstock providers (e.g., mines, biomass providers, tree nurseries)
- Major implementing partners (e.g., local implementation partners, base facilities, transportation and storage providers, major product offtakers)
- Land owners that make up a significant proportion of project land
To reflect the key role that direct counterparties play in high-quality credit generation, developers must conduct diligence and disclose on their direct counterparties to demonstrate that they are not causing social or environmental harm.
Increased Rigor for Enhanced Rock Weathering Projects: Over the past year, ERW’s presence in the CDR market has grown substantially, and so too has the market’s understanding of the corresponding scientific and technical rigor required to deliver high-quality tonnes. The 2026 Criteria raised the bar for how ERW projects:
- Measure and prove their carbon removal claims
- Mitigate risks related to potentially toxic elements (PTEs)
- Incorporate more sophisticated farmer protections and benefits
Projects now have to back up their numbers with multiple physical field measurements, not just computer models; and they must now track and account for every significant loss pathway, from plants taking up minerals to carbon escaping from rivers and oceans.
Use of Dynamic Baselines for ARR Projects: ARR projects are increasingly using dynamic baselines to provide a more accurate reflection of the counterfactual scenario (e.g., what would have happened in the absence of the project). This is reflected in the 2026 Criteria with a requirement that ARR projects, with the exception of agroforestry projects, use dynamic baselines with statistically matched controls.
What’s Next?
The 2026 Criteria create a clear, science-driven framework for both designing and delivering measurable, just, and durable carbon removal. However, the Criteria cannot ensure high-quality tonnes reach the market on its own; good criteria do not replace robust diligence. To put these criteria into practice, we encourage developers, standard-setting bodies, buyers, investors, and policymakers to consider how the Criteria can be used to inform their role in enabling the carbon market to deliver high-quality tonnes and to engage in deep diligence and ongoing monitoring over the life of a project.
This edition of the Criteria reflects what we have learned over the past year, but our work is not done. We will continue to update it so that it remains a living document that evolves with the science and the market. To do so effectively, it must be a collaborative effort; we welcome input from carbon market actors, academia, and communities.
Frequently Asked Questions
Who publishes the Criteria for High-Quality Carbon Dioxide Removal, and how often is it updated?
Relae (formerly Carbon Direct) first published the Criteria for High-Quality Carbon Dioxide Removal with Microsoft in 2021 and have updated it every year since. The 2026 edition reflects six years of lessons from real-world project diligence and advances in climate science.
What are the six principles of the Criteria for High-Quality Carbon Dioxide Removal?
The Criteria define six science-based principles that apply across all CDR pathways: social harms, benefits, and environmental justice; environmental harms and benefits; additionality and baselines; measurement, monitoring, reporting, and verification (MMRV); durability; and leakage.
What CDR pathways does the Criteria cover?
The Criteria include pathway-specific criteria across nine CDR pathways: afforestation, reforestation, and revegetation (ARR); mangrove forestation; improved forest management (IFM); soil carbon; enhanced rock weathering (ERW) in croplands; biomass carbon removal and storage (BiCRS); abiotic marine CDR; carbon mineralization; and direct air capture (DAC).
What is delivery risk in carbon removal?
Delivery risk is the likelihood that a project generates credits on the timeline and at the quantity committed to buyers. It's a distinct concern from credit quality: even a high-quality project can fail to deliver as planned because of technical, economic, commercial, organizational, or political risk, the five categories the Criteria's TECOP framework evaluates. The 2026 Criteria's new Delivery Risk Appendix gives developers, investors, and buyers a shared benchmark for identifying and managing these risks before they derail a project.
What's the relationship between carbon removal credit quality and delivery risk?
Credit quality and delivery risk are distinct but interrelated. A project that fails to deliver credits as planned reduces the availability of high-quality CDR tonnes in the market, and weaknesses in credit quality can themselves increase delivery risk by creating buyer uncertainty or limiting access to project financing. The 2026 Criteria provides a framework for evaluating both quality and delivery risk.
Carbon Removal, Reduction, and Avoidance Credits Explained
Key Takeaways
- Trust in carbon credits remains low. In part, this is because many mistakenly treat every credit type as interchangeable.
- Reduction, removal, and avoidance credits are verified against fundamentally different baselines, so credit quality must be judged based on type and project specifics, never with one blanket standard.
- The Integrity Council for the Voluntary Carbon Market's Core Carbon Principles now give buyers an independent bar to check against, including 44 methodologies approved across 13 eligible crediting programs, as of August 2026.
- Removal credits still make up only 5–6% of the market, even as compliance-driven demand accelerates, per our 2026 State of the Voluntary Carbon Market report.
Three Types of Carbon Credits: Reduction, Removal, and Avoidance
A carbon credit is a mechanism that allows one party to compensate another for their carbon mitigation activities. Based on their net emissions impact, there are three types of carbon credits: reduction, removal, and avoidance.
- Reduction credits reflect activities that decrease greenhouse gas emissions, compared to prior practices.
- Removal credits reflect activities that remove carbon dioxide already present in the atmosphere and oceans and lock it away for decades, centuries, or millennia.
- Avoidance credits reflect activities that prevent greenhouse gases from being emitted in the first place. For all three types, credits are assessed and issued by measuring or estimating how much carbon is reduced, removed, or avoided as a result of a credit purchase and its associated activities.
While credits are assessed in different ways depending on the type, one of the most important indicators of quality is a project's baseline - the emissions that would be present in a business-as-usual scenario, without action being taken to reduce, remove, or avoid them. Project developers use baselines as a means of comparison to assess the net emissions impact of a project.
- Baselines must be accurately set and data-driven.
- Emissions impacts of a project must be correctly calculated against its baseline.
Reduction, removal, and avoidance projects involve very different activities and, for some types of projects, it may be more challenging to establish an accurate baseline. However, without accurate baselines, climate impacts cannot be reliably determined.
Across the voluntary carbon market, Reduction credits represent roughly 20% of the purchases. Removal credits represent roughly 5% of the purchases. The remainder, roughly 75%, are avoidance credits.
Carbon Reduction Credits
Carbon reduction must drive the majority of our push to net zero, but translating carbon reduction activities into carbon credits that can be purchased is challenging. Examples of activities represented by carbon reduction credits include reducing fossil fuel use by improving fuel efficiency, or programs that reduce the methane that is generated from farms or municipal waste processing.
Reduction credits are measured and quantified against the baseline emissions of an existing technology or process. Some reduction credits are easy to track and measure, such as efficiency investments or destruction of fugitive methane. Other projects are more complex. For example, low-emission cookstove projects in developing regions rely on tracking patterns of cookstove use and quantifying emission factors for various fuel and stove combinations, both of which are hard to do. The result, as studies have shown, sometimes leads to overcrediting in reduction projects.
Superpollutant Credits
One class of reduction credit, superpollutant credits, has garnered recent attention. These credits involve the reduction of non-CO2 greenhouse gases with very strong radiative forcing, such as methane, nitrous oxides, or fluorinated gases like chlorofluorocarbons. These are not a substitute for CO2 removal, but can provide rapid and profound reductions at modest cost. Many different kinds of superpollutants exist in today’s market, worth roughly $60M today. Recent purchases by tech companies and others have highlighted the potential of these reduction credits.
Another class of reduction credit, transition credits, involves the deliberate early closure of emitting assets like coal-fired power plants or heavy manufacturing facilities. Early efforts by governments, banks, and companies around the world under the Just Energy Transition Partnership agreement jump-started transition credits as a concept at COP26. The Kinetic Coalition, in partnership with many groups including Relae, has launched work to bring transition credits to market with several pilot efforts, including closing a coal plant in the Philippines 10 years early.
Carbon Removal Credits
Projects that remove carbon come from a diverse set of solutions, from nature-based solutions like reforestation, to hybrid solutions like biochar, to engineered solutions such as direct air capture and storage. Roughly 5–6% of credits on the voluntary carbon market today are classified as removals, up from roughly 3% a few years ago.
Carbon removal baselines are determined differently depending on whether a project uses an engineered, hybrid, or nature-based solution. For engineered removals, the baseline is zero, because no carbon removal was occurring in the absence of the project. The credited removal will be the difference between the quantity of carbon removed and any emissions that occur to facilitate the removal (determined through a carbon credit life cycle assessment). Baselines for hybrid and nature-based removals can be more challenging. In natural systems, changes in carbon stocks created by removals must be measured and approximated over time, and creditable removals represent the additional carbon removed by the intervention relative to the baseline (e.g., fallow land versus a reforestation project).
Another important consideration for carbon removal credits is project durability, a measure of the likely duration of carbon storage. Stored carbon can re-enter the atmosphere either through deliberate actions (e.g., deforestation) or accidental ones (e.g., wildfires). Nature-based removals are especially vulnerable to being re-released and are usually considered less durable (i.e., stored for less than 50 years). In contrast, engineered solutions offer high durability (i.e., stored for hundreds to thousands of years), and hybrid removals also offer durability periods that are typically longer than those of nature-based removals.
While less durable, nature-based solutions are effective, cost-effective, and widely available today. They made up over 95% of all carbon removal credits issued in 2025. Engineered and hybrid solutions are more expensive and scarce but offer longer durability. Prices of engineered carbon removal are likely to fall with innovation and increased market participation, but are currently much higher than most nature-based credits. With SBTi's finalized Corporate Net-Zero Standard V2.0, this balance is likely to shift. Large companies must now purchase removal credits covering 1–100% of scope 1, scope 2, and scope 3 emissions between 2035 and their net-zero year, with an explicit focus on more durable CO2 removal credits.
Carbon Avoidance Credits
Examples of carbon avoidance include avoiding deforestation that would result in the release of carbon dioxide into the atmosphere or clean energy projects that avoid the release of emissions from burning fossil fuels in possible facilities. This can be confusing, since many avoided credits are called reduction credits, as is the case with projects under the Reducing Emissions from Deforestation and Forest Degradation (REDD+) framework. Avoidance credits make up roughly 75% of certified credits on the voluntary carbon market today - an overwhelming majority - in part due to high availability and low price.
Avoiding emissions is an important goal with numerous environmental, climate, community, and other benefits. Relae works with clients and customers across industries on developing and implementing strategies to avoid emissions within their value chain. However, there are significant challenges with the way that many carbon avoidance credits are created.
- Carbon avoidance credits are based on an estimate of the emissions that might have existed had a project not been funded. Because it is impossible to observe what might have happened in the absence of a project, carbon avoidance estimates are determined by considering historic data and contextual information. Statistical models can be used to create a presumed baseline that represents what would have happened in the absence of the project.
- Because the baseline is not observed in an avoided emissions project, there is uncertainty in calculating the number of carbon credits it produces. If the baseline is not set accurately, a project can overcredit. While the lack of a directly observed and measured baseline means avoidance credits will always have some degree of uncertainty, high-quality avoidance projects present compelling evidence to support their baselines, greatly reducing uncertainty.
New datasets, statistical techniques, and methodologies are providing opportunities for developing avoidance credits with more certainty. Three REDD+ methodologies have now cleared the Integrity Council for the Voluntary Carbon Market (ICVCM) assessment for its Core Carbon Principles (CCPs), a concrete sign that credit quality standards for avoidance projects are maturing.
Defining and Standardizing Quality in the Voluntary Carbon Market
Carbon credits are intended to reduce, remove, or avoid emissions. They pay for an environmental service that must be delivered. Companies working to generate climate benefits through credit purchases must grapple with the differences and uncertainties of credit quality to ensure that the intended benefits are realized.
While high-quality credits exist for all types of projects, a rich understanding of the differences in methodologies, geographies, physics, and ecology is required to identify high-quality projects and understand varied certainty, durability, and risk terms. Identifying high-quality carbon projects demands extensive and project-specific diligence beyond carbon market certification.
Our own diligence work reveals that high-quality projects can be hard to find. Fewer than 10% of the carbon removal projects we assessed for our 2026 State of the Voluntary Carbon Market report met our quality criteria. This diligence work now has an additional, independent backstop. As of August 2026, the ICVCM has approved 44 methodologies across 13 programs, as eligible for its CCP label, including ACR, Gold Standard, and VCS. For buyers, considering projects that are CCP-eligible should be used as a first filter—not a substitute for project-level diligence, but representing a legitimate floor.
While realized emissions impacts may be difficult to prove in some cases, it is important to remember that some projects provide additional co-benefits. REDD+ projects, for example, may have a positive impact on conservation and biodiversity, and cookstove projects may offer clear human health and social welfare benefits. However, these benefits should be assessed separately from carbon reduction, removal, or avoidance benefits.
Frequently Asked Questions
What's the difference between a carbon credit and a carbon offset?
A carbon credit represents one verified tonne of emissions reduced, removed, or avoided. A carbon offset describes how a buyer uses that credit, typically to counterbalance emissions it has not yet accounted for. The credit itself does not change type based on how it's claimed.
Which type of carbon credit—reduction, removal, or avoidance—is highest quality?
No single type is inherently highest quality. Each project, regardless of type, is verified against a defined baseline. Quality depends on how rigorously that specific baseline was set and how well the project meets other quality criteria. Removal credits from engineered sources have the most straightforward baseline (zero), and avoidance credits carry the most baseline uncertainty by design, but these are only one determinant of credit quality.
Do carbon removal credits automatically meet the ICVCM’s Core Carbon Principles?
No. The ICVCM assesses methodologies and programs, not individual projects. If a project uses a methodology that is eligible for the CCP label, this can be a useful floor but is not a guarantee of high quality.
How does SBTi's near-term removal mandate change which credits I should buy now?
SBTi's finalized Corporate Net-Zero Standard V2.0 doesn't require removal purchases until 2035, but it sets the ramp now (i.e., 1% of scope 1, scope 2, and scope 3 emissions in 2035, scaling to 100% by the net-zero year). This means the highest-durability removal supply that is scarcest and most in demand today is the same supply that many companies will need later. The SBTi guidelines are still changing, so buyers and project developers must track them closely.
US Wood Pellet Producers: The UK Market Is Contracting. Four Markets Are Beginning.
Key Takeaways
- The UK's new biomass Contracts for Difference framework will cut industrial wood pellet imports by slightly more than half starting in April 2027. As a result, US producers will be left competing for only 1.6 million GST, an 80% reduction in US-addressable volume, with no successor market locked in.
- US wood pellet producers who move now to upgrade sustainability credentials and build relationships in emerging markets will be best positioned to capture the next generation of demand; those who wait may find the most attractive offtake opportunities already structured around someone else's supply.
- Four domestic markets now present producers with new demand opportunities: cofiring, sustainable aviation fuel (SAF), low-carbon steel, and bioenergy with carbon capture and storage (BECCS). Of these, BECCS for data centers is the strongest structural fit: hyperscalers need clean firm power, pellet mills need offtakers, and the feedstock infrastructure is already in place.
The Demand Cliff Is Real, and the Timeline Is Short
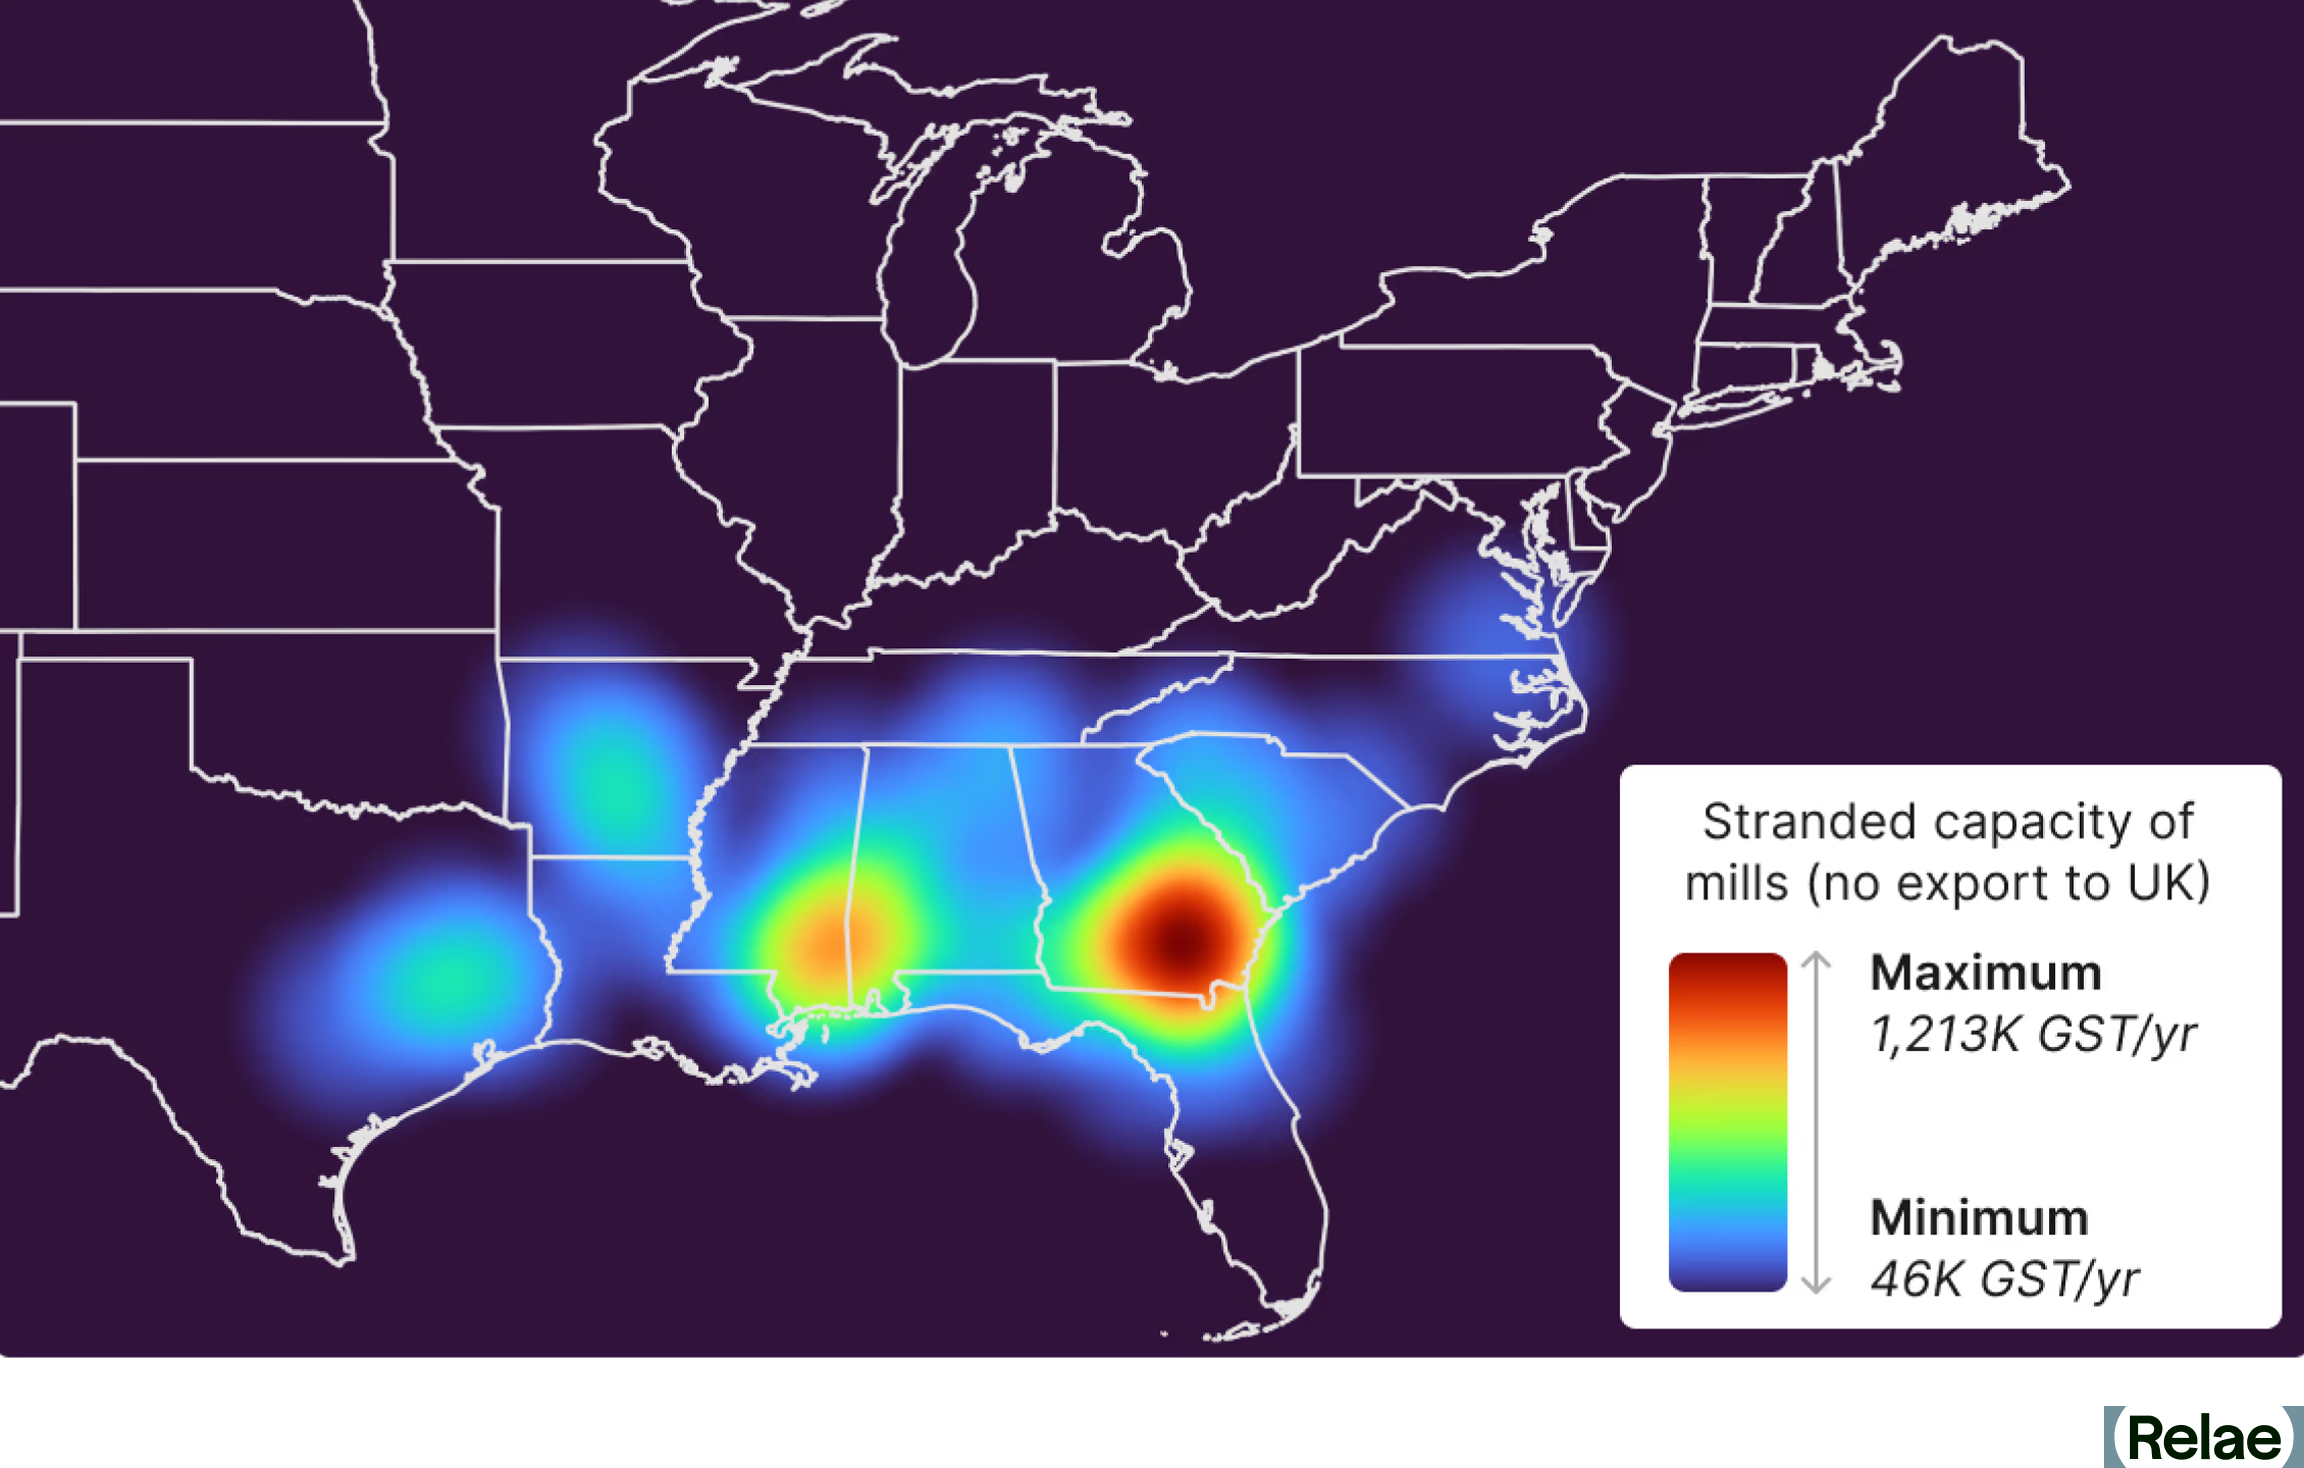
A pellet made in southern Mississippi this morning will be burned in a UK boiler about four weeks later. North America is on pace to ship more than 9 million green short tons (GST) of pellets to the UK each year—making the UK the world's largest consumer of wood pellets since 2018. The US Southeast is at the center of that supply chain: 28 large mills, 13.5 million GST of production capacity, rail spurs, export terminals, and bulk carriers, built almost entirely around UK demand.
However, the UK's new low-carbon Contracts for Difference (CfD) framework caps biomass power generators at a 27% annual capacity factor starting April 2027, down from roughly 64% today. When run hours fall by half, pellet demand follows. Existing subsidies expire in the first quarter of 2027, and the new CfD runs only to March 2031 with no commitment beyond that. Plant closures in Arkansas and Washington state, along with reduced output in Canada, are already early signals of supply chain contraction.
The Math of Who Gets Squeezed
The math is stark. By the second quarter of 2027, total annual UK pellet demand drops to 4.9 million GST. Of that:
- Approximately 2.3 million GST goes to captive, integrated UK supply chains.
- Approximately 1.0 million GST goes to Baltic suppliers, whose shipping times of one week or less become a decisive advantage as UK plants shift from baseload to dispatchable operation.
That leaves US producers competing for only 1.6 million GST. If Baltic suppliers capture more, US wood pellet exports to the UK could be effectively eliminated by 2031.
Sustainability qualification is also tightening. The new CfD cuts the supply-chain emissions ceiling from 55.6 grams of carbon dioxide equivalent per megajoule (gCO₂e/MJ) to 36.6 gCO₂e/MJ. The framework assesses compliance mill by mill, not on a portfolio average. A cleaner mill cannot carry a dirtier sibling through the door.
The producers who understand this math now have roughly 18 months to position themselves for what comes next.
From Stranded Supply to New Markets
The US Southeast's wood basket is robust: abundant inventory, strong growth-to-removal ratios, and more available residues than ever. The infrastructure is in place. The question is whether the next generation of markets can be developed quickly enough to redeploy this supply before the infrastructure sits idle.
Four pathways stand out as the strongest options for redeploying US pellet supply: BECCS for data centers, low-carbon steel, SAF, and domestic cofiring. We have rigorously assessed the logistics economics, sustainability cases, and project development for each.
BECCS for Data Centers: The Strongest Structural Fit
BECCS as a power source for data centers is the most compelling match for the situation pellet producers now face. The timing, feedstock requirements, and buyer characteristics align closely in a way that few other emerging markets can match.
Hyperscalers, the large data center operators driving an unprecedented surge in electricity demand, are signing deals for nuclear, geothermal, and small modular reactors alongside natural gas and renewables. They are doing this because annual Renewable Energy Certificates (RECs) are no longer sufficient to compensate for their scope 2 emissions, and they need clean, firm generation that can be matched to load on an hourly basis.
BECCS delivers exactly that. The Louisiana Green Fuels project—advanced by Strategic Biofuels and Relae (formerly Carbon Direct)—illustrates the model: regionally sourced forestry residues and sawmill waste generate 75 megawatts (MW) of firm electricity while sequestering over one million tonnes of CO₂ annually in deep saline formations. An ample supply of wood pellets creates a strategic opportunity for similar projects to move forward with certainty around feedstock processing, logistics, and costs.
The remaining commercial barrier is deal structure, not technology. No data center operator has yet signed an agreement to purchase both the electricity and carbon removal credits from a single BECCS plant. As scope 2 accounting tightens and domestic pellet supply becomes more readily available post-2027, the conditions for structuring the first such deal are improving fast.
"Pellet mills and data center developers have complementary problems: mills need offtakers, and data centers need local, dispatchable, clean power they can match to load on an hour-by-hour basis. BECCS is one of the few technologies that could solve both at once, and hyperscalers have shown they are willing to back early-stage clean firm power when the asset makes sense."
—Douglas Bryan, Senior Power and Energy Systems Modeler
Low-Carbon Steel: Certification Frameworks Are Arriving
Wood-derived biocarbon has a long-established niche in steelmaking. Brazil produces roughly 10% of its steel and 30% of its pig iron using charcoal from managed eucalyptus plantations—a proof of concept for biomass as a metallurgical input, if not a direct template for US producers. The plantations measurably lowered groundwater in producer regions of Minas Gerais, and charcoal's mechanical weakness relative to fossil coke has limited the model's reach beyond Brazil.
Current pilot projects use biomass in two roles. As a fuel, industrial trials have demonstrated 10% bio-coal co-injection without operational disruption, with reviews estimating that full replacement could cut blast-furnace CO₂ by around 27% per tonne of hot metal. As a reductant, biocoke is already being demonstrated at Outokumpu's pelletizing plant in Tornio, Finland. ArcelorMittal in Belgium and Tata Steel in India are running biomass pilots at tens of thousands of tonnes per year.
What makes this market worth serious attention now is the certification landscape. The Low Emission Steel Standard issued its first certifications in September 2025. The Global Steel Climate Council's Steel Climate Standard is under stakeholder review. In May 2025, Relae and Microsoft published Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors. These frameworks allow producers to internalize carbon price and environmental attribute certificate (EAC) values, closing the cost gap against fossil coke that has historically constrained biocarbon demand.
Relae worked with Eramet, a global metals company pursuing biogenic materials as a substitute for fossil coke at its Norwegian smelters, to assess high-quality carbon dioxide removal methodologies and chart a path to generating and selling carbon credits from their decarbonization projects. Producers who align their sustainability credentials to these emerging standards now will be better positioned for offtake as commercial-scale demand grows.
"Steelmaker pilots and the first low-carbon steel certifications are opening green-steel offtake to wood pellets, though commercial-scale demand remains limited. The producers that thrive in this market will be those that reliably deliver pellets aligned with high-quality sustainability standards."
—Louisa Brotherson, Hybrid Decarbonization Scientist
Sustainable Aviation Fuel: Mandates Create a Durable Demand Signal
Wood-based SAF is technically feasible via gasification to syngas, followed by Fischer-Tropsch upgrading, a proven chemistry for converting syngas to liquid hydrocarbons. Yet, the commercial challenges are substantial: the International Civil Aviation Organization estimates capital costs exceeding US$1 billion for large facilities, and production costs of US$11–48 per gallon to distillate.
The cautionary case is Fulcrum Bioenergy near Reno, Nevada, which attempted a Fischer-Tropsch process using municipal solid waste and appears to have failed due to a lack of rigorous pre-implementation testing and unrealistic timelines, a reminder that feedstock homogeneity matters enormously, and one area where pellets have a relative advantage.
Two structural dynamics make SAF worth serious attention despite those barriers. First, the European Union's (EU) SAF mandate, starting at 2% of jet fuel supply and ramping to 70% by 2050, carves out cellulosic biomass as the only qualifying feedstock once cooking oil supply is exhausted. The penalty structure in both the EU and UK creates strong demand regardless of SAF price: EU non-compliance penalties run roughly three times the price of SAF, and UK penalties can reach 13 times the cost of the fuel itself. Second, the alcohol-to-jet pathway offers a lower-capital entry point than Fischer-Tropsch, as demonstrated by Project Speedbird, a British Airways and LanzaJet collaboration targeting UK woody residues.
The near-term question is which routes have bankable offtake. Very few do yet, but the mandate structure suggests that window will shift rapidly.
"So far, facilities haven't scaled to the levels required to meet timeline demand. But the EU and UK mandate structures mean buyers are greatly incentivized to purchase SAF even at high prices, rather than pay non-compliance penalties."
—John Dees, Director, Fuels and Industrial Commodities
Domestic Cofiring: Achievable, but Not a Long-Term Anchor
Cofiring biomass with coal to produce electricity or heat is the most immediately achievable option. Most US coal-fired power plants could displace up to 10% of their input energy with raw or torrefied pellets, though plants would likely need fuel handling upgrades. Some state policies, such as Pennsylvania's Alternative Energy Portfolio Standards Act of 2004, support cofiring to meet renewable energy goals. However, there are no federal policies in the US that incentivize cofiring.
The case for cofiring as a long-term market is weak. The US coal fleet has contracted steadily for economic reasons—over 100 gigawatts (GW) of coal-fired capacity retired between 2015 and 2025—and biomass cofiring is unlikely to make a coal plant more cost-competitive. The Greenhouse Gas Protocol's scope 2 guidance does not permit buyers to procure a "strip" of electricity representing the biomass-fired fraction of output from a cofired plant; instead, buyers must accept the average total emissions from the plant in their scope 2 inventory, which limits the value proposition for corporate buyers seeking to demonstrate clean energy procurement.
The more interesting version of this pathway combines cofiring with carbon capture and storage (CCS), a combination that creates a deeper-abatement value proposition and the kind of firm, dispatchable power that corporate buyers increasingly need.
"Cofiring is a proven step toward modest emissions reductions from coal-fired electricity, but it's hard to make the economic case for it when compared to applications that command price premiums for deeper climate abatement."
—A.J. Simon, Director of Industrial Decarbonization
Sustainability Is Now the Qualification Gate
Each of these markets is more discerning about sustainable biomass sourcing than the UK power sector was a decade ago. That shift will not reverse.
US Southeast wood has real potential for high-integrity sustainability credentials, particularly in softwood residues. But it also carries downside risks when sourcing from natural stands. Through work with producers, buyers, and project developers across these markets, we have found that four questions now drive every serious procurement conversation:
- Does the supply chain have verifiable governance and chain-of-custody transparency?
- Does sourcing respect the rights of Indigenous Peoples and local communities?
- Is the wood coming from regions where forest carbon stocks are stable or growing, and not from protected areas or primary forest?
- Is sourced biomass a by-product of non-energy uses, and not the primary silviculture driver?
Producers who can answer yes to all four, and support those answers with data, are more likely to access these emerging markets. Those who cannot will find it harder to compete for offtake.
For a detailed framework on how these principles translate into contract language and certification requirements, see the 2025 Sustainable Forest Biomass Sourcing for CDR: A Buyer's Guide.
The Window Is Open, but Not Indefinitely
The US Southeast wood basket is well-positioned for the markets described here. The infrastructure is in place. What producers still need to build is the market positioning, sustainability documentation, and offtake relationships to go with it.
The producers who move now will have a meaningful head start. Those who wait for certainty may find that the most attractive offtake opportunities have already been structured around someone else's supply.
Learn more about Relae's work on SAF mandates, steel decarbonization, and sustainable biomass sourcing.
Frequently Asked Questions
What happens to US wood pellet exports when the UK's new biomass rules take effect?
Starting April 2027, the UK's signed Contracts for Difference agreement caps subsidized biomass generation at a 27% capacity factor, roughly half of today's levels. That's expected to cut total UK pellet demand to about 4.9 million GST a year, leaving only around 1.6 million GST available to US exporters.
Is BECCS for data centers a proven market, or still emerging?
The underlying technology is credible, and the Louisiana Green Fuels project already demonstrates it at commercial scale. However, the deal structure isn't yet proven. No hyperscaler has signed a single contract for both electricity and carbon removal credits from one BECCS plant, so this market is emerging rather than established.
How does low-carbon steel demand compare to sustainable aviation fuel as a market for pellet producers?
Steel offers nearer-term certification frameworks (the Low Emission Steel Standard began issuing certifications in 2025) but limited commercial-scale volume so far. SAF has a stronger long-run demand signal thanks to EU and UK blending mandates and steep non-compliance penalties, but requires far higher capital investment to enter.
What should a wood pellet producer look for when evaluating a new market?
The four sourcing questions that now gate access across all these markets are: verifiable chain-of-custody, respect for Indigenous and local community rights, sourcing from stable or growing forest carbon stocks (not primary forest), and biomass that's a by-product of non-energy uses rather than the primary driver of harvest.
GHG Protocol Releases New Land Sector and Removals Standard
Key Takeaways
- On January 30, 2026, the Greenhouse Gas Protocol (GHG Protocol) released its long-awaited Land Sector and Removals (LSR) Standard v1.0 following a 5-year consultation process. The LSR Standard is set to take effect on January 1, 2027.
- The release of the LSR Standard represents a notable development for companies in the food and agriculture sector looking to report on land-based GHG emissions in their annual GHG inventory, as well as companies that plan to report on carbon dioxide removals (both land-based and technological).
- The accompanying Land Sector and Removals Guidance, which will provide further direction on operationalizing and implementing the LSR Standard, is expected in Q2 of 2026. However, companies with significant land-based activities may want to begin assessing the impacts of the LSR Standard on their emissions accounting procedures and decarbonization strategies today.
Why the Land Sector and Removals Standard Matters Now
Emissions from agriculture and land use change account for roughly a quarter of global emissions. Yet, for years, food, fiber, and fuel companies have lacked a clear framework for accounting and reporting on GHG emissions and carbon dioxide removals from land use. This has significantly limited their ability to demonstrate progress toward climate targets within their operations and value chain. The GHG Protocol’s Land Sector and Removals (LSR) Standard, which was released on January 30, 2026, changes that, and in doing so raises a new set of questions.
The LSR Standard provides greater clarity on what is required of companies to transparently track and report against their emissions reduction and removal targets, and opens new pathways to report on supply chain decarbonization interventions. It also represents an important advancement for companies seeking to report on carbon dioxide removals within their emissions inventory, including both land management removals and technological removals with geologic storage.
While the LSR Standard contains notable new requirements compared to the draft released in 2022, companies still face a number of open questions related to implementation and the implications for their decarbonization strategies.
The GHG Protocol’s accompanying Land Sector and Removals Guidance, scheduled for Q2 2026, is expected to offer more practical direction for implementing the LSR Standard. However, companies with significant land-based activities that require sufficient lead time to prepare should consider assessing the impacts today.
Below, we provide an overview of the LSR Standard, key changes from the 2022 draft, and actionable next steps for food, fiber, and fuel companies considering the impacts on their target-setting and emissions reporting.
What Is the Land Sector and Removals Standard?
The LSR Standard, taking effect on January 1, 2027, sets requirements and recommendations for corporate GHG accounting that cover emissions and carbon removals from agricultural and land use activities. It builds on existing GHG Protocol standards for corporate carbon accounting. Notably, the LSR Standard does not cover the forestry sector, a key break from the 2022 draft. Forest carbon accounting guidance remains under development and will be the subject of a stakeholder consultation/request for information process expected later in 2026.
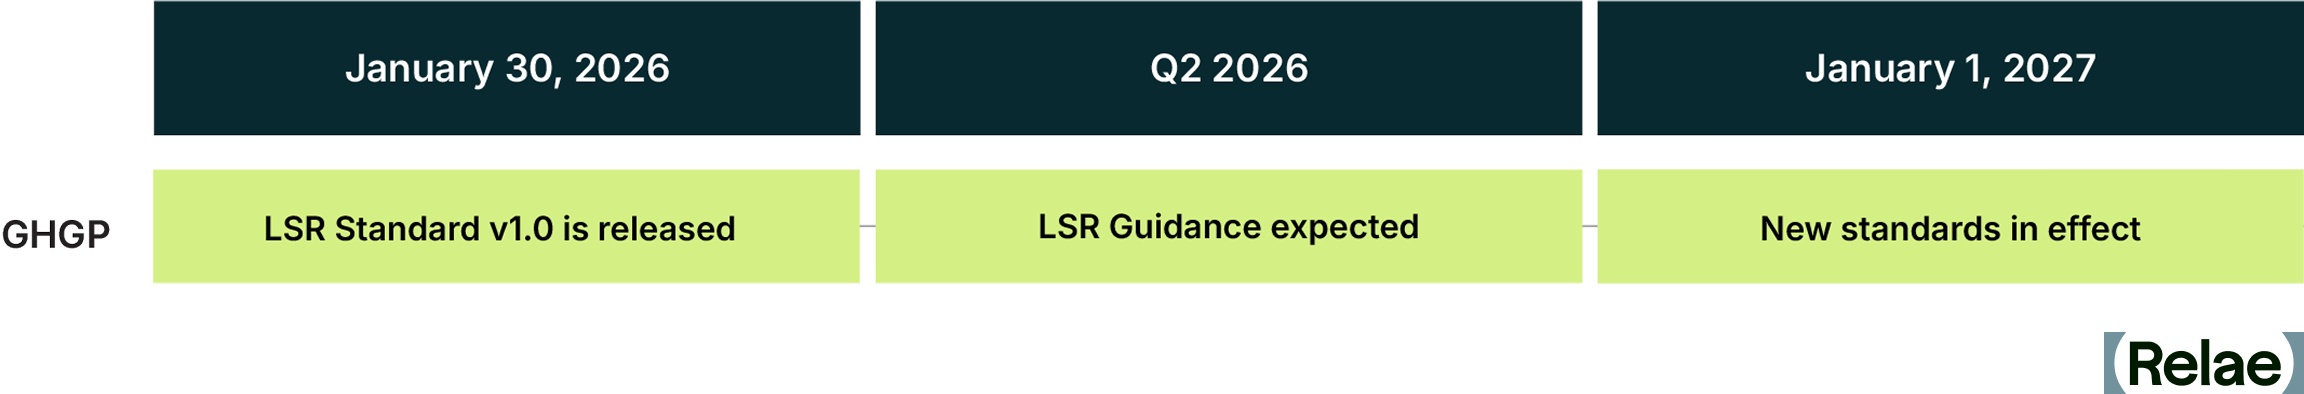
Land Sector and Removals Standard vs Land Sector and Removals Guidance
The LSR Standard establishes the core requirements companies must follow, while the accompanying Land Sector and Removals Guidance, expected in Q2 of 2026, will provide more detailed implementation support. In short, the LSR Standard sets the "what" while the Land Sector and Removals Guidance will explain the "how," helping companies put those requirements into practice.
Who Should Be Using the Land Sector and Removals Standard?
The LSR Standard applies to two groups of companies:
- Any company with significant1 land-sector activities within its own operations or value chain (most notably the food, feed, fiber, biofuel, and advanced biomaterials sector).
- Any company looking to report on carbon dioxide removals within their scope 1 and scope 3 inventories (including both land management removals or technological removals).
Land management carbon dioxide removals include those from carbon sequestration through farming practices, agroforestry, or silvopastural systems on productive agricultural land. Technological carbon dioxide removals, by contrast, refer to more engineered approaches such as direct air carbon capture and storage (DACCS) or bioenergy carbon capture and storage (BECCS).
What Changed From the 2022 Draft?
Among other provisions, the LSR Standard contains notable breaks from the 2022 draft, including specific changes related to traceability, carbon dioxide removals, leakage, and land use change.
Traceability: A New Approach
Under the LSR Standard, companies that account for scope 3 emissions, removals, and other metrics must apply a spatial boundary. This boundary is determined by the level of traceability they can establish to known lands or regions (from least to most granular): global, jurisdictional (e.g., country), sourcing region (e.g., supply shed), land management unit (LMU) (e.g., farm), or harvested area. For more granular spatial boundaries, such as sourcing region and LMU, companies are required to establish physical traceability, which can be demonstrated through various chain of custody models.
The LSR Standard defines sourcing regions as predefined, spatially-explicit land areas that supply a raw material to its first point of aggregation or first processing facility in the value chain. The GHG Protocol allows some flexibility in how these boundaries are drawn. They can be defined at a tier of the value chain that includes multiple first points of aggregation or first processing facilities whose supply areas overlap.
Alongside higher integrity chain of custody models such as identity preserved, segregated, and controlled blending, the LSR Standard opens to mass balance as a chain of custody model that can be used to demonstrate physical traceability at the sourcing region-level with appropriate safeguards.
This is notable because mass balance is the most common chain of custody model for large volume agricultural commodities, and physical traceability is required to report removals according to the LSR standard. While challenges for reporting removals at sourcing region spatial boundaries still exist, this change unlocks new opportunities to decarbonize commodities and report removals within non-segregated supply chains through insetting programs.
Carbon Dioxide Removals: Clarity on Spatial Boundaries
The draft LSR Standard introduces key principles for companies choosing to report land management carbon dioxide removals, including traceability, data quality, and permanence. Translating those principles into practice remains challenging given the dynamic nature of agricultural supply chains and limited farm-level traceability.
Among other requirements, the LSR Standard maintains that companies electing to report on removals must do so as a separate accounting category from emissions. They must also identify the specific lands where carbon is stored, and conduct ongoing storage monitoring to detect and report on reversals if and when they occur.
The LSR Standard does, however, resolve one of the more consequential open questions left by the 2022 draft: where companies are to draw the spatial boundary for reporting land management carbon dioxide removals. By formalizing and permitting traceability at the sourcing-region level (with appropriate safeguards), it offers a workable middle ground between farm-level precision and the broader supply chain realities that most food and agricultural companies face.
The LSR Standard also opens to using alternative approaches to traceability, such as impact traceability, which allows companies to trace removals back to the LMU through a pathway that is separate from the physical GHG inventory. This is notable as it provides companies with optionality for recognition of farm-level supply chain investments even when physical traceability cannot be established, and inventory recognition is therefore not feasible.
Land Use and Leakage: Stronger Requirements
Finally, the LSR Standard significantly strengthens land use and economic leakage requirements compared to the 2022 draft. While the draft gave companies flexibility to choose among land-tracking metrics, the LSR Standard mandates that all companies report land occupation for both scope 1 and scope 3 in hectares and quantify land carbon leakage whenever “high leakage risk activities”2 displace food or feed production. This includes companies developing crop-based biofuels and bio-based feedstocks.
Leakage must be quantified using the Carbon Opportunity Cost, a calculation aimed at capturing how much carbon could have been stored in the absence of land management activities.
What Should Companies Do Now?
For entities reporting in accordance with the GHG Protocol’s Corporate Standard and Scope 3 Standard, the new LSR Standard goes into effect on January 1, 2027. However, the GHG Protocol’s Land Sector and Removal Guidance is not set for publication until Q2 2026, leaving many open questions related to implementation amid a short data collection and reporting cycle
In the interim, companies may consider a continuous improvement approach, evolving and improving their internal measurement and reporting mechanisms to enable more granular accounting over time. Companies may also consider running analyses to assess the impact of new requirements on the design and cost of decarbonization strategies, with a specific focus on data collection and monitoring approaches.
Ultimately, while implementation of the LSR Standard may evolve over time, it need not delay action on value chain intervention. Companies that continue investing in supply chain decarbonization are building the data infrastructure, supplier relationships, and operational resilience that yield greater visibility into supply chain risk and drive long-term value, independent of reporting standards.
As the LSR Standard's requirements develop, companies that have already begun assessing their emissions footprint and strengthening supply chain traceability and data quality are likely to be better positioned to align their reporting procedures accordingly.
What Is Biochar? A Carbon Removal Solution Gaining Ground
Key Takeaways
- Concrete and steel contribute 13% of global CO2 emissions. These materials represent substantial scope 3 emissions for companies that are building new infrastructure, including data centers.
- Low-emission alternatives and production technologies are nascent and not yet widely deployed.
- Environmental attribute certificates (EACs) are an innovative solution that can stimulate manufacturing of sustainable commodity materials and overcome market barriers to direct physical procurement.
- Relae (formerly Carbon Direct) and Microsoft developed criteria to guide Microsoft’s high-quality EAC procurement, accelerate decarbonization, and catalyze market expansion for decarbonized materials across supply chains.
- These criteria cover seven key areas: qualifying conditions, social harms and benefits, environmental harms and benefits, additionality and baselines, catalytic impact, verifiability, and leakage.
A Vision for Low-Carbon Concrete and Steel
Concrete and steel are essential for modern construction, but are carbon-intensive. Combined, they account for approximately 13% of global carbon dioxide (CO2) emissions. As the demand for data centers and infrastructure development continues to grow, so do the embodied emissions from concrete and steel. There is an urgent need to decarbonize these sectors so that construction of new facilities remains consistent with climate commitments.
However, the markets for low-carbon concrete and steel are still in their infancy. Market barriers such as low production volumes, contracting complexity, geographic concentration of supplies, and long-distance transportation limit buyers’ ability to directly procure low-carbon building materials. As buyers and sellers overcome these barriers, the market for low-carbon building materials will mature, giving producers the confidence to invest in new manufacturing facilities and giving buyers access to decarbonized materials directly in their supply chain.
Environmental attribute certificates (EACs) represent the sustainability attributes of a material commodity, unbundled and transacted separately from the physical commodity. EACs are transacted at a price that reflects the additional cost of sustainably producing the material. While barriers to direct procurement of low-carbon materials persist, EACs can serve as a powerful tool to signal demand for low-carbon concrete and steel, catalyze market expansion, and accelerate decarbonization.
[cta]
Microsoft’s Approach to Emissions from Building Materials
To address embodied emissions and help achieve its ambitious 2030 carbon-negative goal, Microsoft aims to deeply reduce its scope 3 emissions, including from building materials, by more than half compared to a 2020 baseline. In 2023, scope 3 emissions made up over 96% of Microsoft’s total greenhouse gas footprint. To meet its 2030 target, Microsoft is focusing on addressing supply-chain emissions related to data center construction and the embodied carbon of the commodity materials used to build them. Microsoft is already working to decarbonize its building material supply chain using the following three tactics:
- Reduce the need for concrete and steel through innovative building design or the use of lower-carbon alternatives, such as sustainably sourced mass timber.
- Directly engage with suppliers to procure low-carbon alternatives to conventional concrete and steel.
- Invest in and help pilot new low-carbon production pathways.
EACs represent a fourth approach to decarbonization that can both reduce emissions and catalyze industry growth. Taken together with Microsoft’s design, procurement, and investment tactics, these actions underpin a comprehensive strategy for long-term decarbonization of the built environment.
High-Quality EACs Support Decarbonization
EACs offer a virtual, market-driven solution to decarbonize the built environment by allowing companies to support low-carbon material production when physical supply chain barriers impede direct procurement. EACs for concrete and steel function similarly to other market-based decarbonization mechanisms such as sustainable aviation fuel (SAF) certificates in the aviation sector and renewable energy certificates (RECs) in the energy sector.
These mechanisms work by decoupling the environmental benefits of low-carbon production from the physical materials themselves. EACs allow companies to claim the environmental benefits of physical low-carbon concrete or steel production, even if they do not directly or physically source those materials. EACs provide a verified claim that a purchaser has procured a product with lower emissions, enabling companies to meet climate targets and demonstrate their commitment to sustainability.
Due to their virtual nature, which limits physical oversight of the supply chain, EACs also exacerbate risks such as double counting, greenwashing, fraud, social harms, and environmental harms. Therefore, adhering to transparent, rigorous criteria is foundational to mitigating these risks.
New Criteria to Guide Procurement of High-Quality EACs
To support the integrity and effectiveness of EACs in these sectors, Relae and Microsoft have co-developed Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors. These robust criteria serve as a public resource for companies seeking credible and impactful EAC procurement pathways for low-carbon concrete and steel.
The criteria address seven key areas:
- Qualifying conditions: EACs must complement, not displace, direct procurement and represent significant emissions reductions.
- Social harms and benefits: EACs must not further social harms and should promote community engagement and social benefits such as meaningful workforce development opportunities and community climate resilience.
- Environmental harms and benefits: EACs must not perpetuate environmental harm, but instead should mitigate risks and, ideally, provide additional environmental benefits.
- Additionality and baselines: Projects funded by EACs must drive real, meaningful emissions reductions in terms of financial, regulatory, and common practice additionality.
- Catalytic impact: Prioritize transformative technologies with sector-wide decarbonization potential.
- Verifiability: Set a high bar for documentation, transparency, and independent auditing.
- Leakage: Address risks of emissions displacement to support net-positive outcomes.
These criteria provide a robust framework for companies and stakeholders to evaluate and implement commodity EACs effectively, supporting impactful change. They balance rigor with flexibility and acknowledge the nascent state of the markets for low-carbon concrete and steel. Sectoral decarbonization will advance over time, shifting the thresholds for what is considered significant, additional, and catalytic in EAC transactions. This science-driven framework can adapt to advancements in policy, industry practices, and technological readiness, ensuring EACs remain a relevant and impactful tool for years to come.
Sector-Specific Insights
In addition to providing overarching criteria and guidance on procuring EACs for the built environment, Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors also provides insights into the unique challenges and opportunities of decarbonizing concrete and steel.
Decarbonizing Concrete
EACs can support innovative decarbonization strategies for concrete, such as producing alternatives to clinker and cement, adopting supplementary cementitious materials (SCMs), and reducing emissions from cement kilns through electrification or integrating carbon capture and storage (CCS). Performance-based standards and evolving building codes may also unlock new opportunities for low-carbon concrete.
The Global Cement and Concrete Association (GCCA) publishes a rating system, Low Carbon Concrete (or Cement) Ratings, which defines eight separate low-carbon grades (AA through G). These grades correspond to the depth of decarbonization and are based on a sliding scale related to the material’s compressive strength. When developing these criteria, Microsoft considered grades AA through D to be eligible for consideration in its EAC procurements.
Decarbonizing Steel
EACs can support transformative technologies for decarbonizing steel, like direct reduced iron (DRI) with electric arc furnaces (EAF) powered by green or blue hydrogen. This support can enable the steel sector to move beyond incremental improvements and focus on capital-intensive solutions that have the potential to reshape the industry.
ResponsibleSteel, an independent standards and certification organization with membership that is broadly representative of the steel industry, publishes decarbonization progress levels, with four separate grades (PL1–PL4). These grades correspond to the depth of decarbonization and are based on a sliding scale related to the fraction of recycled scrap use in the steel manufacturing process. When developing these criteria, Microsoft included levels PL2 through PL4 for consideration in its EAC procurements.
A Blueprint for EAC Market Development
Relae and Microsoft crafted Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors as a public resource that can help shape the future of the commodity EAC market.
These criteria are designed to:
- Communicate intent: Communicate Microsoft's intent to support the decarbonization and scaling of physical commodity supply chains where they have been previously limited.
- Guide decision-making: Serve as a public guide for Microsoft's decision-making process, explaining the rationale behind pursuing or declining specific EAC pathways.
- Set high-integrity standards: Maintain high integrity for EACs at an early stage, ensuring they are used to enable future physical procurement by supporting market development.
- Stimulate partnership opportunities: Encourage potential partnerships and purchasing pipelines by clearly describing criteria for high-quality EACs.
- Publicly share detailed thinking: Build on previous work and publicly share detailed thinking, aiming to stimulate market development and guide procurement decisions.
Practical Recommendations for Implementing EACs
Whether you are a supplier, buyer, policymaker, or sustainability advocate, these new criteria offer actionable insights to help you navigate the complexities of EACs in the built environment. From setting significance thresholds to ensuring verifiability to avoiding double counting, the criteria provide clear guidance to maximize the impact of EAC-supported projects.
Beyond the technical aspects of EACs, these criteria aim to address their broader social and environmental implications. The criteria focus on the importance of community engagement, transparency, and equitable distribution of benefits in EAC project planning, ensuring that decarbonization efforts contribute to a more sustainable and just economy. The criteria are backed by extensive research, stakeholder consultations, and industry expertise.
[cta]
Meera Atreya, John Dees, David Madrid Garcia, Katherine Gomes, Grant Gutierrez, and A.J. Simon authored the Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors. We appreciate Julio Friedmann and Colin McCormick for their valuable technical insights. Adrianna Sutton, Molly Tucker, and Britt Warthen provided essential editorial and production support.
We are especially grateful to Julia Fidler and Brian Sifton, previously at Microsoft, for commissioning this report, providing detailed input, and engaging deeply with the Relae Science Team every step along the way. Special thanks to Katie Ross at Microsoft, whose leadership and coordination made the report possible.
We also extend our appreciation to the teams at RMI and Environmental Resources Management for their time, thoughtful feedback, and prior publications, which helped inform and complement this work.
Frequently Asked Questions
What is an environmental attribute certificate (EAC), and how does it differ from buying low-carbon concrete or steel directly?
An environmental attribute certificate represents the sustainability attributes of a commodity material such as concrete or steel, unbundled from the physical material and transacted separately from it. Direct procurement means a buyer purchases low-carbon concrete or steel and takes physical delivery of it for a specific project. An EAC purchase instead allows a buyer to fund and claim the environmental benefit of sustainably produced materials that are sold as typical commodities, and apply that benefit against conventional commodities in their own supply chain. EACs are priced to reflect the additional cost of producing the material sustainably, which sends a demand signal to producers. This makes EACs useful where market barriers—limited production volumes, geographic concentration of supply, or long-distance transportation—prevent buyers from sourcing low-carbon materials directly.
How do EACs for concrete and steel compare to renewable energy certificates (RECs) or sustainable aviation fuel (SAF) certificates?
Environmental attribute certificates for concrete and steel share a structure with renewable energy certificates and sustainable aviation fuel certificates: each decouples the environmental benefit of low-carbon production from the physical product, letting a buyer fund and claim that benefit without taking physical delivery. There are two key differences. First, conventional RECs represent electricity with a zero-emissions footprint, while every tonne of concrete or steel behind an EAC still carries embodied emissions — the certificate demonstrates reduction against a baseline, not a zero-emission product. Second, REC and SAF markets are established, while EACs for concrete and steel are nascent. Both differences are why rigorous criteria matter: quantifying the reduction credibly is harder, and the virtual structure carries risks of double counting, greenwashing, and fraud.
Will EACs let companies claim emissions reductions without actually reducing their built environment climate footprint?
An EAC purchase does not change the materials in a buyer's own buildings; it funds lower-emission production elsewhere in the market. Credible EAC frameworks therefore require that certificates complement rather than displace direct procurement, that they represent significant reductions against a defensible baseline, and that the funded project would not have proceeded without EAC revenue. The criteria published by Relae and Microsoft enable buyers to address these requirements directly in their procurement processes - addressing the climate and reputational risks of low-quality certificates. Used this way, EACs become an additional tool to address emissions from the built environment, supplementing design changes, direct procurement, and investment in new production pathways.
Who should use these criteria?
Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors, co-developed by Relae and Microsoft, is a public resource intended for four audiences. Buyers pursuing scope 3 reductions can use it to evaluate whether a given certificate represents a credible, additional emissions reduction. Suppliers and project developers can use it to understand what purchasers of high-quality certificates look for before bringing a project to market. Policymakers and standards bodies can draw on it while shaping rules for an emerging market. Sustainability practitioners and advocates can use it as a reference point for assessing claims made about low-carbon concrete and steel. The criteria are designed to evolve as these sectors decarbonize, and users may adapt them to meet their own levels of capability and ambition.
Key Trends in the 2026 Voluntary Carbon Market
Key Takeaways
- What's happening: The voluntary carbon market (VCM) stalled in 2025, with carbon credit retirements falling 7% despite a 227% surge in corporate climate commitments.
- Why it matters: Over 80% of high-durability carbon removal capacity is at risk of not being realized without additional offtake.
- The implication: For corporate buyers with 2030 climate targets, early movers will define market standards and secure the supply they need, while those who wait risk volatility and constrained access to high-quality credits.
Why the Voluntary Carbon Market Needs Action Now
The voluntary carbon market stands at a crossroads. Credit retirements in 2025 fell far below the billion-tonne-scale projections from earlier in the decade. There is a widening gulf between climate ambition and market action.
The VCM transacts credits that avoid, reduce, or remove emissions. Carbon dioxide removal (CDR), the process of removing and durably storing atmospheric CO₂, remains a small but critical segment, accounting for 5% of credits retired. Limiting overshoot of 1.5°C requires a rapid scale-up of CDR.
However, most organizations with 2030 climate goals have yet to engage in CDR procurement. Without clear market signals today, CDR supply will falter. What's missing isn't capability or knowledge, but the commitment to act. Early movers will define the market in its early stages, while latecomers may face volatility and uncertain supply.
Our latest analysis reveals both troubling trends and clear pathways forward for CDR buyers ready to move from commitment to execution.
[cta]
Five Years of Stagnation: The VCM Falls Short of Projections
For five consecutive years, muted growth and persistent oversupply of poor-quality credits have defined the market. In 2025, credit retirements—a proxy for spot-market demand—reached 157 million metric tonnes (Mt), down 7% from 2024.
This incremental growth is far below what market analysts anticipated earlier in the decade, when several projections expected demand to exceed 1 billion tonnes by 2030.
VCM Credit Trends: Concentrated in Avoidance and Reduction
The VCM has historically been concentrated in avoidance and reduction carbon projects, largely dominated by REDD+, renewable energy, and cookstove credits. 2025 marks the first year a new credit type has dominated, though: projects that reduce emissions of superpollutants now make up roughly 20% of all credits issued in the VCM. Superpollutant issuances increased by about 180% between 2020 and 2025, while retirements grew by roughly 150%.
CDR Remains a Small but Critical VCM Segment
In 2025, CDR credits accounted for only 5% of 2025 retirements, but have a more active forward offtake market—where buyers commit today to purchase credits that will be delivered in the future, providing crucial early-stage financing for projects.
Within the CDR category, high-quality credits are still hard to find. Applying our Criteria for High-Quality Carbon Dioxide Removal, we find that less than 10% of the CDR projects we review meet our high-quality threshold with minimal reservations.
Nature-Based CDR Dominates the Spot Market
Of the all CDR credits issued in the VCM in 2025, 95% originated from nature-based CDR pathways, while 5% represented high-durability CDR pathways such as biochar or bioenergy with carbon capture and storage (BECCS). This distribution reflects the mature role that nature-based CDR projects continue to play in the market, alongside the early stage of durable CDR deployment.
Within nature-based credits, supply and demand dynamics differed significantly between afforestation, reforestation, and revegetation (ARR) and improved forest management (IFM).
- For ARR credits, issuances and retirements have tracked closely at a roughly 1:1 ratio, with issuances remaining flat at around 7–8 Mt annually over the past four years, leaving little inventory available for spot purchasing.
- IFM credits, by contrast, have grown 2.5-fold since 2023, making them one of the largest sources of growth within nature-based credits, though high-quality CDR credits from IFM are in much lower supply.
For buyers, this means ARR credits are increasingly difficult to source on the spot market, while IFM credits are more readily available—though careful diligence is needed to identify high-quality projects.
Nature-based offtakes and commitments have expanded in recent years, with more than 90 Mt of future delivery now contracted or committed. The vast majority of these commitments are concentrated in ARR projects, highlighting both the supply constraints facing ARR today and buyers' foresight in securing the supply they will need in the near future.
High-Durability CDR Is Almost Entirely Forward-Looking
The spot market for high-durability CDR credits represents only 0.3% of activity in the VCM, but important dynamics are beginning to emerge as more high-durability CDR technologies reach the market.
From 2021 to 2025, roughly 80% of high-durability issuances and retirements came from biochar and geologic storage. However, the emergence of large-scale geologic CDR projects is beginning to shift the balance, with individual projects capable of delivering hundreds of thousands of tonnes annually. Early-stage methodologies such as enhanced rock weathering (ERW) and ocean alkalinity enhancement (OAE) issued their first credits in 2025, totaling roughly 12,000 tonnes.
While the spot market for high-durability CDR is growing and diversifying, forward offtake agreements continue to define the landscape. The ratio of high-durability spot retirements to volumes committed through forward offtake is 1:70—meaning for every tonne retired today, 70 tonnes have been committed for future delivery.
Forward Offtake Commitments Are Rising Across CDR Pathways
To date, forward offtake agreements, advanced market commitments (AMC), and large contracted deals with intermediaries cover more than 40 Mt of high-durability CDR, in addition to over 90 Mt of nature-based CDR. These cumulative volumes highlight the increasingly central role of forward purchasing in shaping future supply, particularly for capital-intensive, high-durability pathways.
However, the success of forward offtake strategies depends critically on careful due diligence. Without a rigorous assessment of technological readiness, project viability, and delivery risks, forward commitments risk financing projects that fail to deliver, undermining both individual investments and broader market confidence.
Market Concentration of Forward Offtake Remains High
A small group of companies continues to drive the majority of forward offtake activity. In 2025, Microsoft remained the clear market leader, accounting for roughly 60% of contracted nature-based CDR offtakes and more than 80% of high-durability offtakes with a named buyer announced to date. Other active buyers—including Google, JPMorgan Chase, Equinor, and Amazon—have expanded their commitments, but overall market concentration remains high.
This concentration reveals both opportunity and risk: while anchor buyers are proving the market model works, broader participation is needed to unlock the full scale of CDR deployment required.
Growing Gap Between Climate Ambition and Market Action
Corporate climate targets anchor most current VCM activity: All of the top-10 buyers in the market today participate based on either self-declared commitments or net-zero commitments aligned with the Science Based Targets initiative (SBTi).
Demand forecasts based on these future commitments project that total CDR demand could reach 46-110 Mt by 2030, a ~6-14x growth from today. Yet, how companies decide to implement their targets will ultimately affect the composition of CDR demand within the VCM.
Rather than relying solely on public commitments, we analyzed the behavior of companies that are actively purchasing CDR today. Should today's top buyers follow through on their stated CDR commitments, CDR demand could reach a minimum of 28 Mt by 2030, with 6.5 Mt of demand for high-durability CDR.
However, the discrepancy between observed demand and target-led scenarios shows a persistent gap between what companies say and what they do. SBTi reported a 227% surge in companies setting both near-term and net-zero targets in the 18 months leading up to mid-2025, while carbon credit retirements in the VCM fell 7% in 2025.
Shifting from intention to execution will ultimately determine whether the VCM evolves into a durable, functioning marketplace or stalls short of the scale required for credible, net-zero pathways.
Rising Trends of Greenhushing and Anonymity Obscure CDR Demand
In the broader VCM, 55% of tonnes retired on the spot market over the past three years have been anonymous, and that fraction has been increasing. A similar trend is true of high-durability CDR: nearly 40% of all offtake transactions made in 2025 did not disclose the participating buyer. This buyer behaviour could reflect the often-discussed greenhushing phenomenon.
When anonymous actors dominate, it becomes harder to track demand signals, verify corporate progress, and establish clear integrity benchmarks. This opacity creates systemic risk for the entire market.
Market Growth Tipping Points on the Horizon
Several pivotal events on the horizon could mitigate risk and unlock project development, tipping buyers into action after half a decade of limited market growth:
- Voluntary demand: SBTi's Corporate Net Zero Standard V2.0, published in June 2026, confirms credits still can’t count toward scope 1-3 targets, but introduces a voluntary recognition program starting in 2027 and mandatory removal purchasing for large companies from 2035, starting at 1% of footprint.
- Compliance demand: The UK's Emissions Trading Scheme (ETS) Authority has already committed to integrating carbon removals into the UK ETS by 2028 via an auction model. This is the first confirmed large-scale compliance pathway for CDR credits, though credit-type eligibility is still being worked out.
- Regulatory support: Publication of Article 6.4 methodologies under the Paris Agreement and loosening of CORSIA credit supply bottlenecks could expand eligible supply and boost buyer confidence.
These tipping points in policies, standards, and market structures are advancing with clear timelines, creating conditions to move CDR procurement from hesitation to activation.
CDR Supply Faces Critical Challenges
While buyer inaction poses one threat to market growth, the supply side faces its own critical challenges.
30%–220% More Investment Is Needed in Nature-Based CDR Supply
Nature-based CDR would require a 30%–220% increase in finance to support current corporate targets. Relae (formerly Carbon Direct) has identified US$18 billion in publicly committed funds for nature-based CDR announced from 2018 to 2025. If deployed immediately to generate high-quality CDR, this level of funding could translate into up to 32 Mt per year by 2030 and 290 Mt cumulatively through 2040.
This is sufficient to meet the conservative 28 Mt demand floor from today's active buyers—but falls well short of what would be needed if even a fraction of companies with 2030 targets begin executing on their stated commitments.
80% of High-Durability CDR Projects Are at Risk
The situation is more acute for high-durability CDR. We estimate that over 80% of the total 2030 credit supply pipeline is at risk, due to insufficient project offtake and financing agreements.
Without increased offtake and financing support, we expect that the landscape for capital-intensive, high-durability CDR may consolidate
CDR Buyers Will Determine Which Projects Get Built
The supply-side ecosystem features a sufficient number of high-quality CDR suppliers with the potential to scale. These suppliers face purchasing behavior insufficient to meet buyers' own stated climate goals. In this environment, every CDR procurement decision matters. Companies that delay procurement risk missing their own climate targets while also ceding competitive advantage to early movers who secure the limited supply of high-quality credits.
Five Actions to Strengthen the CDR Market
Buyers and investors can play a critical role in reducing project risk and strengthening the CDR market. Our full report details five essential actions:
- Use purchasing power wisely
- Prioritize project diligence
- Construct bankable contracts
- Support market data transparency and CDR goals
- Undertake project assurance
Each action addresses specific market failures and, when implemented strategically, can significantly improve the likelihood that high-quality CDR projects reach operation and deliver credits as contracted.
With 2030 only four years away, the window for action is rapidly closing. Early movers will secure supply and define market standards, while those who wait risk entering a crowded market with limited access to high-quality credits and escalating prices.
[cta]
Frequently Asked Questions
Why did the voluntary carbon market stall in 2025 despite rising corporate climate commitments?
Retirements fell 7% even as SBTi reported a 227% surge in companies setting near-term and net-zero targets. The gap reflects that most companies with 2030 goals haven't yet moved from setting targets to actually procuring credits.
Is carbon dioxide removal a proven market today, or still emerging?
CDR remains a small segment—about 5% of 2025 retirements—but it has an unusually active forward market, with buyers committing today to volumes delivered years from now. High-durability pathways like biochar and geologic storage are still early-stage relative to nature-based credits.
How does the new SBTi Net-Zero Standard affect corporate carbon credit strategy?
Under the new SBTi Net-Zero Standard, credits still can't be counted toward scope 1, 2, or 3 targets. But it introduces a voluntary recognition program starting in 2027, and requires large companies to begin purchasing carbon removals from 2035, starting at 1% of their footprint.
What should CDR buyers prioritize given current market conditions?
Given how concentrated forward offtake activity is today, buyers should prioritize rigorous project diligence and bankable contract structures over simply committing volume—the 2026 State of the Voluntary Carbon Market report details five recommended actions in more depth.
SBTi Emphasizes Near-Term Carbon Removal in Revised Corporate Standard Draft
Key Takeaways
- Near-term role for carbon removals: The revised Science-Based Targets Initiative (SBTi) Corporate Net Zero Standard (CNZS) v2.0 proposes requiring or recognizing interim carbon dioxide removal (CDR) targets before companies reach net zero. This shift aims to scale up the CDR industry in line with climate science and ensure companies address residual emissions earlier rather than deferring action until their net-zero target year.
- Revised target frameworks and increased accountability: The draft standard introduces key changes, including separate targets for scope 1 and 2 emissions, enhanced scope 3 target-setting guidelines, and the recognition of market-based mechanisms for indirect mitigation of scope 3 emissions. It also requires companies to publicly disclose transition plans and assess implementation progress against targets.
- Potential for stronger action on removals: While the proposed updates are a step forward, the final standard should make near-term CDR targets mandatory rather than optional and should expand to include those for projected scope 3 residual emissions, not just scope 1. Without these stronger mandates, demand for early-stage CDR investments may remain limited, potentially slowing progress toward net-zero goals.
- Companies should prepare now: Businesses should start integrating CDR into their climate strategies now so they are equipped to navigate procurement of high-quality removal credits in the voluntary carbon market. Preparing ahead of the final CNZS v2.0 release will help companies align with science-based decarbonization pathways and demonstrate climate leadership.
What the Latest SBTi Update Means for Corporate Climate Action
On 18 March, 2025, the Science Based Targets Initiative (SBTi) released its draft Corporate Net Zero Standard (CNZS) v2.0, significantly updating its framework for corporate net-zero target setting for the first time since 2021. The draft proposes new approaches for companies to support carbon dioxide removal (CDR) in the transition to net-zero emissions, a move that could help scale the nascent CDR industry.
This release is part of a broader revision, with key proposed updates including:
- Requiring public disclosure of transition plans after companies set targets.
- Separating targets for scope 1 and 2 emissions.
- Enhancing the scope 3 target-setting framework using an impact-based prioritization process.
- Recognizing indirect mitigation (e.g., book-and-claim commodity certificates) for hard-to-trace scope 3 emissions.
- Defining a role for emissions removals in the transition to net zero.
- Providing options to recognize company leadership in beyond value chain mitigation (BVCM).
- Assessing corporate progress against targets to bolster accountability.
While formal recognition of removals in the transition to net zero is a positive step, stronger incentives will be needed in the final CNZS to ensure companies take meaningful early action on CDR. The draft standard is open for the first of two public consultations until 1 June, 2025, with a finalized version expected to launch in 2026.
What Remains the Same From the Current Standard?
SBTi’s framework remains focused on three core requirements for companies:
- Reducing emissions year-on-year to reach an approved science-based target (SBT) by 2050 or earlier.
- Investing in beyond value chain mitigation (BVCM) in the transition to net zero to support near-term global decarbonization efforts.
- Neutralizing remaining emissions from the net-zero year (achieved after at least 90% emissions reductions) and onwards with high-quality, permanent carbon removal.
Carbon credits representing emissions reductions and removals remain ineligible for meeting reduction targets within a company’s value chain (SBTs).
What’s New in CNZS v2.0 for Carbon Removals?
Until now, the SBTi encouraged companies to invest in CDR through mechanisms such as BVCM, but has not proposed requiring removal before their target net-zero year. As a result, organizations had little clarity or incentive to invest in CDR ahead of their net-zero target date, dampening near-term demand for carbon removal and delaying the industry's growth.
The new draft changes this by proposing three options for the V2.0 Standard that address the impact of residual emissions during the transition to net zero:
- Option 1 (requirement): Companies are required to set near- and long-term removal targets, including interim CDR milestones,¹ to address projected residual emissions.
- Option 2 (optional with recognition): Companies can set and receive recognition for removal targets to address projected residual emissions.
- Option 3 (flexibility of mechanism): Companies have the flexibility to address expected residual emissions either entirely through additional emissions reductions within their value chain, entirely through removals, or via a combination of both.
Notably, all three approaches apply only to residual scope 1 emissions.
On top of these approaches, SBTi has suggested two options for the minimum durability threshold of CDR purchases in their draft standard. Removals will either need to follow a ‘like for like’ approach,² where CDR storage must match the atmospheric lifetime of residual emissions, or a gradual transition approach, where carbon storage durability increases over time.
Why Mandating CDR Matters
Mandating near-term CDR reinforces the need for immediate climate action, ensuring that carbon removals complement emissions reductions rather than being deferred until the net-zero target year. The urgency of early CDR investment is clear:
- Limiting global warming to well below 2°C above pre-industrial levels requires removing billions of tonnes (gigatonnes) of carbon dioxide annually by mid-century.
- The CDR industry is in its early stages and requires sustained investment today to scale in time.
- If companies wait until their net-zero year to purchase CDR, the supply of high-quality removal credits is unlikely to be sufficient.
As part of the proposed removal targets in Option 1 (above), the CNZS v2.0 would require companies to gradually increase CDR purchases over time, ramping up to 100% of a company’s projected residual scope 1 emissions in the net-zero target year (<10% of baseline year emissions).³
What More Can Be Done?
The potential introduction of required removal targets would be a significant and welcomed step, reinforcing the importance of near-term CDR investment to support industry maturation and climate goals. However, mandatory near-term CDR targets represent only one of three potential pathways for the V2.0 standard. Moreover, neutralization of residual emissions on the path to net zero is only proposed for scope 1 emissions. While the SBTi provides clear rationale for this,⁴ SBTi should not let the complexity of projecting scope 3 emissions be a barrier to climate change mitigation. Scope 3 emissions represent the majority of emissions from SBTi-aligned companies. Furthermore, companies with high scope 3 emissions typically have a higher ability to pay compared to their industrial counterparts with high scope 1 emissions.
If interim removal targets are made optional, and scope 3 emissions remain excluded, the demand signal for near-term CDR will be limited. The public consultation (and advice of Expert Working Groups that SBTi is convening) will be essential in determining which proposed guidance matures into the final standard; consultation feedback can be provided here prior to June 1, 2025.
How Businesses Can Prepare for CNZS v2.0
Companies aligning with SBTi’s evolving guidance should begin to integrate CDR into their climate strategy now. This means:
- Understanding their residual emissions forecast and planning early investments.
- Developing a company-specific climate strategy to incorporate CDR into their sustainability roadmaps in tandem with plans to reduce value-chain emissions.
- Engaging early in the voluntary carbon market to implement these strategies and develop procurement processes to support high-quality removal projects.
- Ensuring credibility by selecting removal projects aligned with scientific best practices.
Conclusion: A Step in the Right Direction, But More Certainty Is Needed
The CNZS v2.0 draft represents a critical turning point for corporate climate action with options to formalize the role of early CDR investment through interim removal targets for signatories. However, SBTi must take a stronger stance in the final version of the revised standard by choosing to adopt requirements for near-term neutralization (rather than leaving this optional), including projected residual scope 3 emissions in near-term CDR targets, aligning durability requirements with climate science, and defining removal quality standards to ensure these efforts drive meaningful climate impact. Organizations seeking to align with this guidance should prepare by developing a comprehensive climate strategy that accounts for science-based decarbonization pathways and recognizes the role of early-stage investment in CDR solutions.