



The Relae Blog
Original insights from the Relae team on the forces reshaping power systems, GHG emissions, environmental markets, nature, and the capital and policies behind them.
US Wood Pellet Producers: The UK Market Is Contracting. Four Markets Are Beginning.
Key Takeaways
- The UK's new biomass Contracts for Difference framework will cut industrial wood pellet imports by slightly more than half starting in April 2027. As a result, US producers will be left competing for only 1.6 million GST, an 80% reduction in US-addressable volume, with no successor market locked in.
- US wood pellet producers who move now to upgrade sustainability credentials and build relationships in emerging markets will be best positioned to capture the next generation of demand; those who wait may find the most attractive offtake opportunities already structured around someone else's supply.
- Four domestic markets now present producers with new demand opportunities: cofiring, sustainable aviation fuel (SAF), low-carbon steel, and bioenergy with carbon capture and storage (BECCS). Of these, BECCS for data centers is the strongest structural fit: hyperscalers need clean firm power, pellet mills need offtakers, and the feedstock infrastructure is already in place.
The Demand Cliff Is Real, and the Timeline Is Short
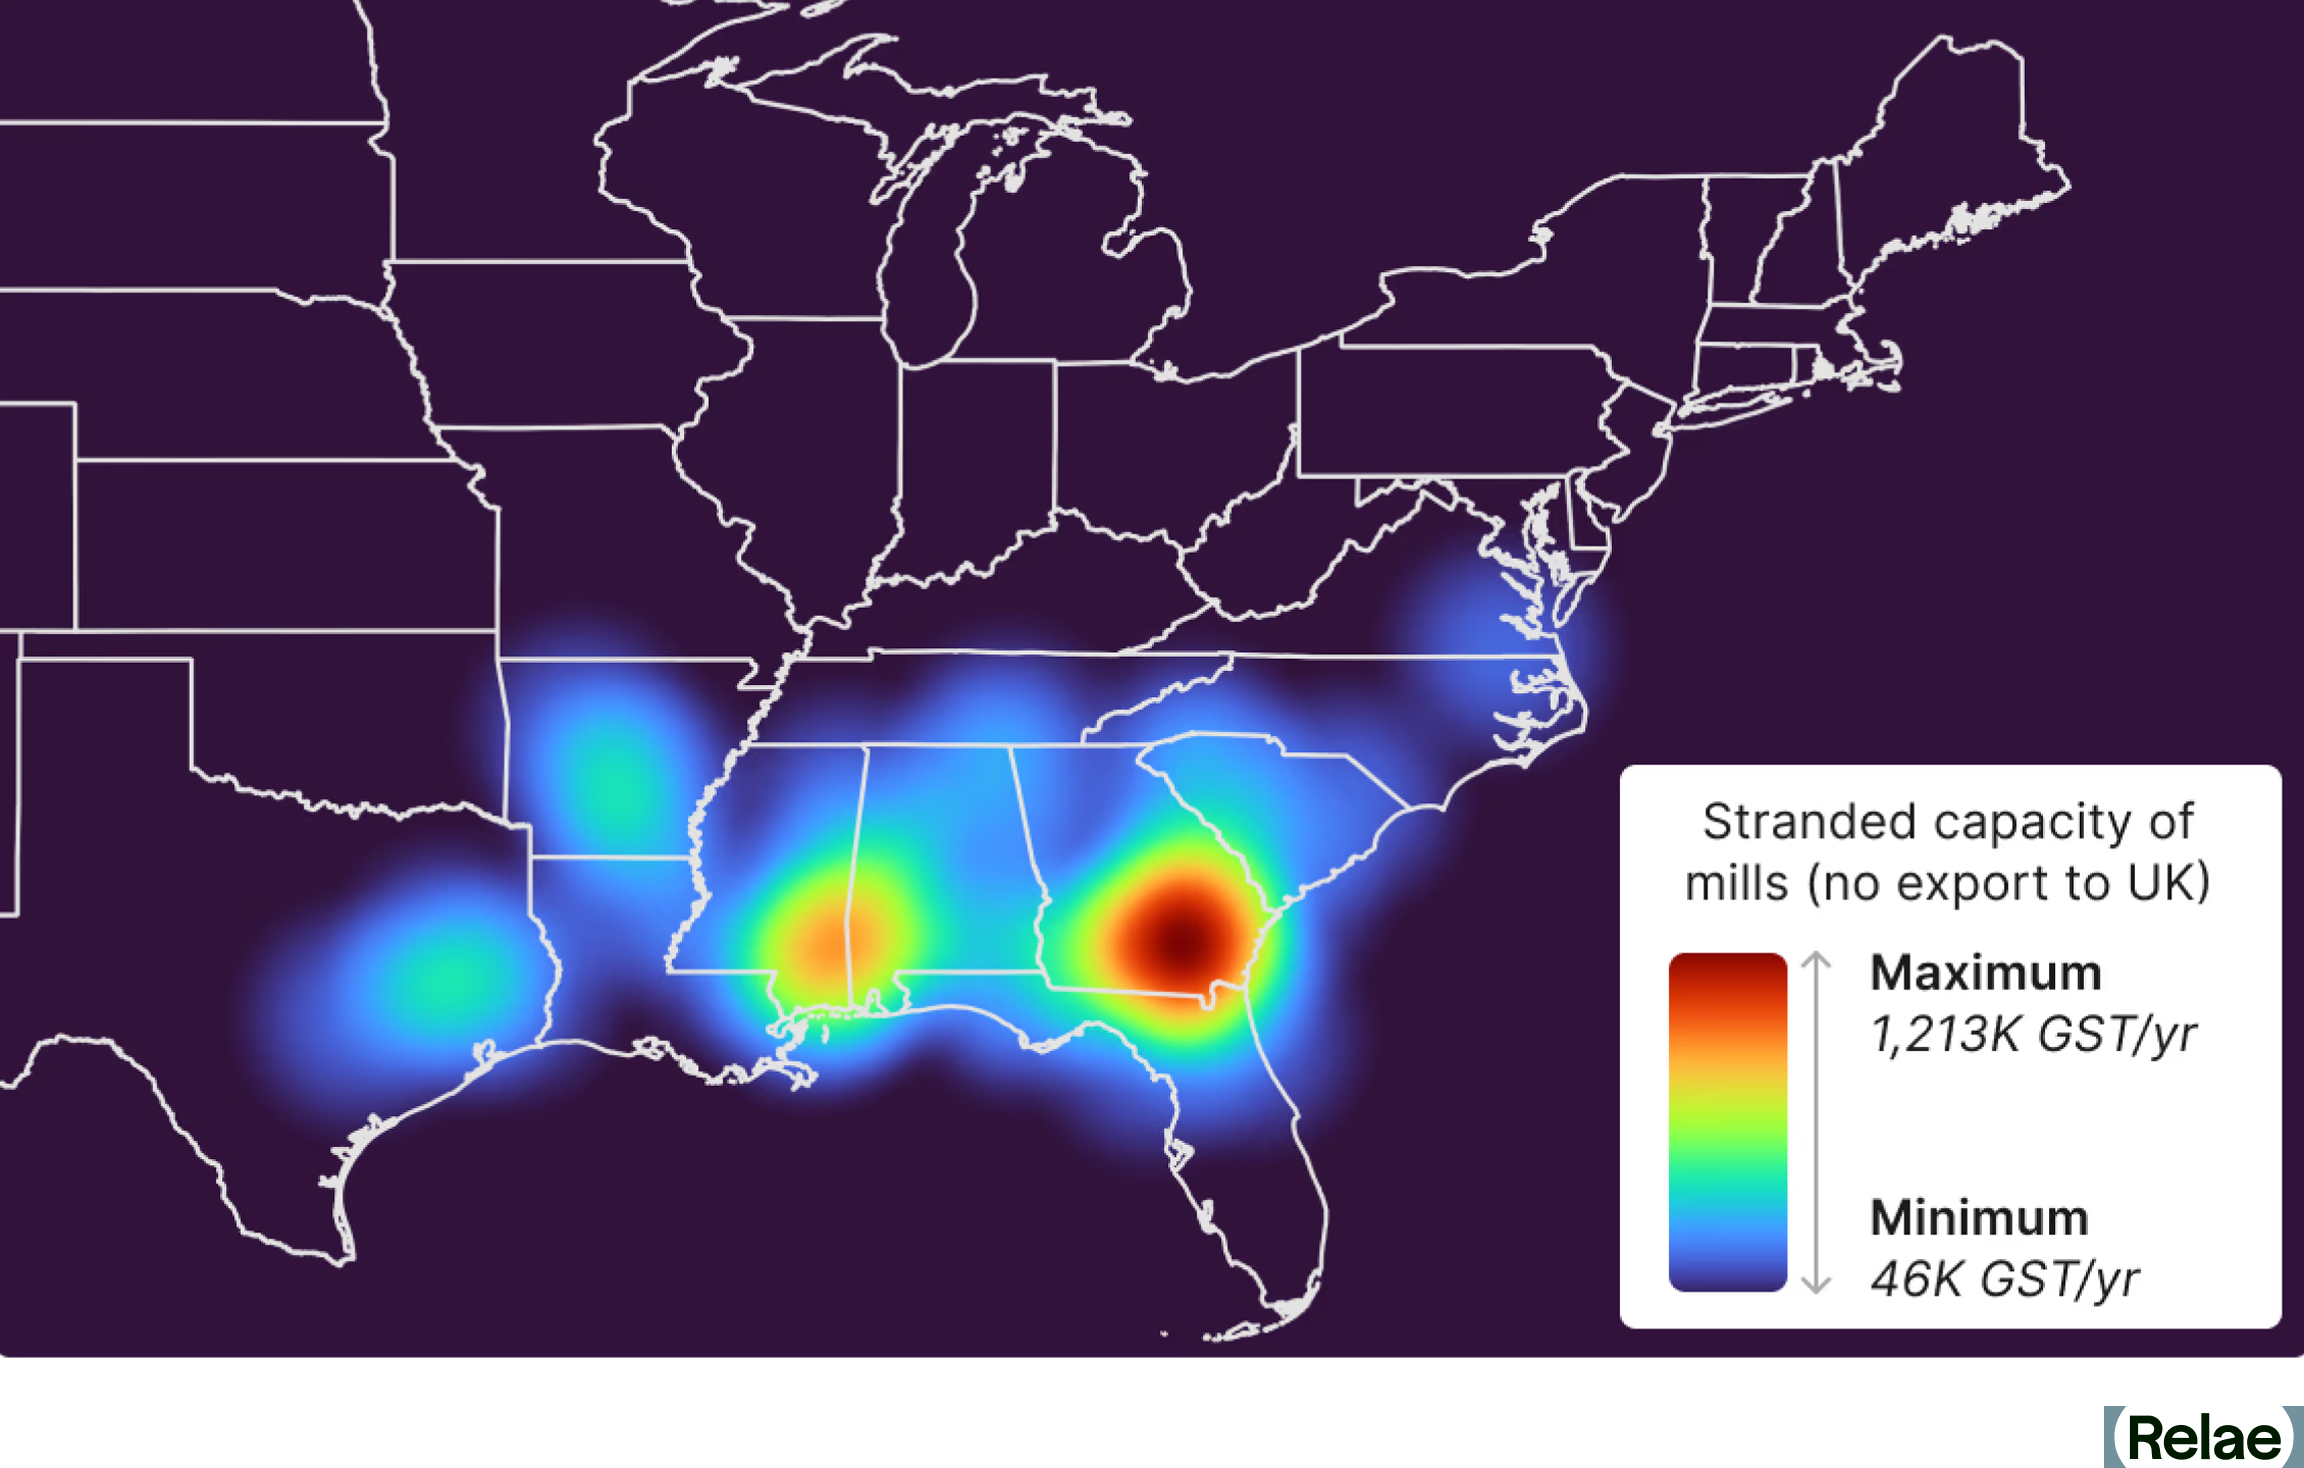
A pellet made in southern Mississippi this morning will be burned in a UK boiler about four weeks later. North America is on pace to ship more than 9 million green short tons (GST) of pellets to the UK each year—making the UK the world's largest consumer of wood pellets since 2018. The US Southeast is at the center of that supply chain: 28 large mills, 13.5 million GST of production capacity, rail spurs, export terminals, and bulk carriers, built almost entirely around UK demand.
However, the UK's new low-carbon Contracts for Difference (CfD) framework caps biomass power generators at a 27% annual capacity factor starting April 2027, down from roughly 64% today. When run hours fall by half, pellet demand follows. Existing subsidies expire in the first quarter of 2027, and the new CfD runs only to March 2031 with no commitment beyond that. Plant closures in Arkansas and Washington state, along with reduced output in Canada, are already early signals of supply chain contraction.
The Math of Who Gets Squeezed
The math is stark. By the second quarter of 2027, total annual UK pellet demand drops to 4.9 million GST. Of that:
- Approximately 2.3 million GST goes to captive, integrated UK supply chains.
- Approximately 1.0 million GST goes to Baltic suppliers, whose shipping times of one week or less become a decisive advantage as UK plants shift from baseload to dispatchable operation.
That leaves US producers competing for only 1.6 million GST. If Baltic suppliers capture more, US wood pellet exports to the UK could be effectively eliminated by 2031.
Sustainability qualification is also tightening. The new CfD cuts the supply-chain emissions ceiling from 55.6 grams of carbon dioxide equivalent per megajoule (gCO₂e/MJ) to 36.6 gCO₂e/MJ. The framework assesses compliance mill by mill, not on a portfolio average. A cleaner mill cannot carry a dirtier sibling through the door.
The producers who understand this math now have roughly 18 months to position themselves for what comes next.
From Stranded Supply to New Markets
The US Southeast's wood basket is robust: abundant inventory, strong growth-to-removal ratios, and more available residues than ever. The infrastructure is in place. The question is whether the next generation of markets can be developed quickly enough to redeploy this supply before the infrastructure sits idle.
Four pathways stand out as the strongest options for redeploying US pellet supply: BECCS for data centers, low-carbon steel, SAF, and domestic cofiring. We have rigorously assessed the logistics economics, sustainability cases, and project development for each.
BECCS for Data Centers: The Strongest Structural Fit
BECCS as a power source for data centers is the most compelling match for the situation pellet producers now face. The timing, feedstock requirements, and buyer characteristics align closely in a way that few other emerging markets can match.
Hyperscalers, the large data center operators driving an unprecedented surge in electricity demand, are signing deals for nuclear, geothermal, and small modular reactors alongside natural gas and renewables. They are doing this because annual Renewable Energy Certificates (RECs) are no longer sufficient to compensate for their scope 2 emissions, and they need clean, firm generation that can be matched to load on an hourly basis.
BECCS delivers exactly that. The Louisiana Green Fuels project—advanced by Strategic Biofuels and Relae (formerly Carbon Direct)—illustrates the model: regionally sourced forestry residues and sawmill waste generate 75 megawatts (MW) of firm electricity while sequestering over one million tonnes of CO₂ annually in deep saline formations. An ample supply of wood pellets creates a strategic opportunity for similar projects to move forward with certainty around feedstock processing, logistics, and costs.
The remaining commercial barrier is deal structure, not technology. No data center operator has yet signed an agreement to purchase both the electricity and carbon removal credits from a single BECCS plant. As scope 2 accounting tightens and domestic pellet supply becomes more readily available post-2027, the conditions for structuring the first such deal are improving fast.
"Pellet mills and data center developers have complementary problems: mills need offtakers, and data centers need local, dispatchable, clean power they can match to load on an hour-by-hour basis. BECCS is one of the few technologies that could solve both at once, and hyperscalers have shown they are willing to back early-stage clean firm power when the asset makes sense."
—Douglas Bryan, Senior Power and Energy Systems Modeler
Low-Carbon Steel: Certification Frameworks Are Arriving
Wood-derived biocarbon has a long-established niche in steelmaking. Brazil produces roughly 10% of its steel and 30% of its pig iron using charcoal from managed eucalyptus plantations—a proof of concept for biomass as a metallurgical input, if not a direct template for US producers. The plantations measurably lowered groundwater in producer regions of Minas Gerais, and charcoal's mechanical weakness relative to fossil coke has limited the model's reach beyond Brazil.
Current pilot projects use biomass in two roles. As a fuel, industrial trials have demonstrated 10% bio-coal co-injection without operational disruption, with reviews estimating that full replacement could cut blast-furnace CO₂ by around 27% per tonne of hot metal. As a reductant, biocoke is already being demonstrated at Outokumpu's pelletizing plant in Tornio, Finland. ArcelorMittal in Belgium and Tata Steel in India are running biomass pilots at tens of thousands of tonnes per year.
What makes this market worth serious attention now is the certification landscape. The Low Emission Steel Standard issued its first certifications in September 2025. The Global Steel Climate Council's Steel Climate Standard is under stakeholder review. In May 2025, Relae and Microsoft published Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors. These frameworks allow producers to internalize carbon price and environmental attribute certificate (EAC) values, closing the cost gap against fossil coke that has historically constrained biocarbon demand.
Relae worked with Eramet, a global metals company pursuing biogenic materials as a substitute for fossil coke at its Norwegian smelters, to assess high-quality carbon dioxide removal methodologies and chart a path to generating and selling carbon credits from their decarbonization projects. Producers who align their sustainability credentials to these emerging standards now will be better positioned for offtake as commercial-scale demand grows.
"Steelmaker pilots and the first low-carbon steel certifications are opening green-steel offtake to wood pellets, though commercial-scale demand remains limited. The producers that thrive in this market will be those that reliably deliver pellets aligned with high-quality sustainability standards."
—Louisa Brotherson, Hybrid Decarbonization Scientist
Sustainable Aviation Fuel: Mandates Create a Durable Demand Signal
Wood-based SAF is technically feasible via gasification to syngas, followed by Fischer-Tropsch upgrading, a proven chemistry for converting syngas to liquid hydrocarbons. Yet, the commercial challenges are substantial: the International Civil Aviation Organization estimates capital costs exceeding US$1 billion for large facilities, and production costs of US$11–48 per gallon to distillate.
The cautionary case is Fulcrum Bioenergy near Reno, Nevada, which attempted a Fischer-Tropsch process using municipal solid waste and appears to have failed due to a lack of rigorous pre-implementation testing and unrealistic timelines, a reminder that feedstock homogeneity matters enormously, and one area where pellets have a relative advantage.
Two structural dynamics make SAF worth serious attention despite those barriers. First, the European Union's (EU) SAF mandate, starting at 2% of jet fuel supply and ramping to 70% by 2050, carves out cellulosic biomass as the only qualifying feedstock once cooking oil supply is exhausted. The penalty structure in both the EU and UK creates strong demand regardless of SAF price: EU non-compliance penalties run roughly three times the price of SAF, and UK penalties can reach 13 times the cost of the fuel itself. Second, the alcohol-to-jet pathway offers a lower-capital entry point than Fischer-Tropsch, as demonstrated by Project Speedbird, a British Airways and LanzaJet collaboration targeting UK woody residues.
The near-term question is which routes have bankable offtake. Very few do yet, but the mandate structure suggests that window will shift rapidly.
"So far, facilities haven't scaled to the levels required to meet timeline demand. But the EU and UK mandate structures mean buyers are greatly incentivized to purchase SAF even at high prices, rather than pay non-compliance penalties."
—John Dees, Director, Fuels and Industrial Commodities
Domestic Cofiring: Achievable, but Not a Long-Term Anchor
Cofiring biomass with coal to produce electricity or heat is the most immediately achievable option. Most US coal-fired power plants could displace up to 10% of their input energy with raw or torrefied pellets, though plants would likely need fuel handling upgrades. Some state policies, such as Pennsylvania's Alternative Energy Portfolio Standards Act of 2004, support cofiring to meet renewable energy goals. However, there are no federal policies in the US that incentivize cofiring.
The case for cofiring as a long-term market is weak. The US coal fleet has contracted steadily for economic reasons—over 100 gigawatts (GW) of coal-fired capacity retired between 2015 and 2025—and biomass cofiring is unlikely to make a coal plant more cost-competitive. The Greenhouse Gas Protocol's scope 2 guidance does not permit buyers to procure a "strip" of electricity representing the biomass-fired fraction of output from a cofired plant; instead, buyers must accept the average total emissions from the plant in their scope 2 inventory, which limits the value proposition for corporate buyers seeking to demonstrate clean energy procurement.
The more interesting version of this pathway combines cofiring with carbon capture and storage (CCS), a combination that creates a deeper-abatement value proposition and the kind of firm, dispatchable power that corporate buyers increasingly need.
"Cofiring is a proven step toward modest emissions reductions from coal-fired electricity, but it's hard to make the economic case for it when compared to applications that command price premiums for deeper climate abatement."
—A.J. Simon, Director of Industrial Decarbonization
Sustainability Is Now the Qualification Gate
Each of these markets is more discerning about sustainable biomass sourcing than the UK power sector was a decade ago. That shift will not reverse.
US Southeast wood has real potential for high-integrity sustainability credentials, particularly in softwood residues. But it also carries downside risks when sourcing from natural stands. Through work with producers, buyers, and project developers across these markets, we have found that four questions now drive every serious procurement conversation:
- Does the supply chain have verifiable governance and chain-of-custody transparency?
- Does sourcing respect the rights of Indigenous Peoples and local communities?
- Is the wood coming from regions where forest carbon stocks are stable or growing, and not from protected areas or primary forest?
- Is sourced biomass a by-product of non-energy uses, and not the primary silviculture driver?
Producers who can answer yes to all four, and support those answers with data, are more likely to access these emerging markets. Those who cannot will find it harder to compete for offtake.
For a detailed framework on how these principles translate into contract language and certification requirements, see the 2025 Sustainable Forest Biomass Sourcing for CDR: A Buyer's Guide.
The Window Is Open, but Not Indefinitely
The US Southeast wood basket is well-positioned for the markets described here. The infrastructure is in place. What producers still need to build is the market positioning, sustainability documentation, and offtake relationships to go with it.
The producers who move now will have a meaningful head start. Those who wait for certainty may find that the most attractive offtake opportunities have already been structured around someone else's supply.
Learn more about Relae's work on SAF mandates, steel decarbonization, and sustainable biomass sourcing.
Frequently Asked Questions
What happens to US wood pellet exports when the UK's new biomass rules take effect?
Starting April 2027, the UK's signed Contracts for Difference agreement caps subsidized biomass generation at a 27% capacity factor, roughly half of today's levels. That's expected to cut total UK pellet demand to about 4.9 million GST a year, leaving only around 1.6 million GST available to US exporters.
Is BECCS for data centers a proven market, or still emerging?
The underlying technology is credible, and the Louisiana Green Fuels project already demonstrates it at commercial scale. However, the deal structure isn't yet proven. No hyperscaler has signed a single contract for both electricity and carbon removal credits from one BECCS plant, so this market is emerging rather than established.
How does low-carbon steel demand compare to sustainable aviation fuel as a market for pellet producers?
Steel offers nearer-term certification frameworks (the Low Emission Steel Standard began issuing certifications in 2025) but limited commercial-scale volume so far. SAF has a stronger long-run demand signal thanks to EU and UK blending mandates and steep non-compliance penalties, but requires far higher capital investment to enter.
What should a wood pellet producer look for when evaluating a new market?
The four sourcing questions that now gate access across all these markets are: verifiable chain-of-custody, respect for Indigenous and local community rights, sourcing from stable or growing forest carbon stocks (not primary forest), and biomass that's a by-product of non-energy uses rather than the primary driver of harvest.
The Sustainable Aviation Fuel Cost Premium Is Permanent
Key Takeaways
- Sustainable aviation fuel (SAF) will not reach price parity with fossil jet fuel under any realistic near-term scenario. The cost premium is structural—rooted in the chemistry of feedstocks—not a temporary artifact of early-stage markets.
- Neither airlines nor corporate buyers are purchasing SAF for its energy content. Both are buying sustainability claims: airlines for regulatory compliance and scope 1 credentials, corporates for scope 3 emissions reporting and social license to operate. The fuel is incidental to both transactions.
- Corporate offtakes can play a genuine role in building the SAF industry, but only if they create capacity that would not otherwise exist. Additionality is not a technicality; it is the entire value proposition.
- High-integrity SAF procurement requires evaluating not just carbon reduction, but feedstock sourcing, leakage, and social and environmental harms. The newly released Criteria for High-Quality Low Carbon Fuels from Relae (formerly Carbon Direct) provides a framework for doing this rigorously.
A Major Deal Illustrates How the SAF Market Really Works
On June 5, 2026, Google and American Airlines announced a three-year agreement under which Google will purchase sustainable aviation fuel (SAF) certificates (SAFc) associated with 35 million gallons of SAF. American will take physical delivery of the fuel at Chicago O'Hare. Google receives the emissions attributes. The arrangement relies on book-and-claim accounting, in which the physical fuel and the environmental attribute are legally separated and transferred to different parties.
The deal is a window into how the SAF market works, and what every company in the value chain needs to understand before entering it.
The SAF Cost Premium Is Structural, Not a Market Inefficiency
There is a persistent hope in the aviation industry that SAF will eventually reach price parity with fossil jet fuel. This will not happen, at least not through any mechanism that currently exists or is credibly in development.
The economics are the product of thermodynamics. Petroleum is pre-deoxygenated; over millions of years, heat and pressure stripped oxygen from biological material, concentrating energy into the hydrocarbons we pump out of the ground today. Bio-based SAF feedstocks, e.g., vegetable oils, agricultural residues, and other biomass, are oxygen-rich (carbohydrates, not hydrocarbons). Power-to-liquid e-fuels start from captured CO₂, which is fully oxidized.
Either way, every SAF production pathway must pay an energy debt to remove or chemically reduce that oxygen, in the form of hydrogen deoxygenation, energy inputs, and processing costs. This is not a manufacturing inefficiency that scale will solve. It is a constraint baked into the feedstocks themselves.
The numbers reflect this. According to the European Union Aviation Safety Agency (EASA), the average market price of SAF in 2025 was approximately €1,925 per tonne, roughly three times the €640 per tonne average for conventional jet fuel.
The cheapest pathway, hydroprocessed esters and fatty acids (HEFA), produced from waste oils like used cooking oil or tallow, represents almost all current SAF supply and sits at the lower end of the SAF cost range. Costlier cellulosic and e-fuel pathways push it higher. EASA estimates 2025 production costs for power-to-liquid e-fuels at €7,520 per tonne, more than ten times the cost of conventional kerosene. While these costs can and will come down, none are expected to approach price parity.
The feedstock ceiling compounds this. HEFA from waste oils is the cheapest SAF pathway, but waste oil supply is finite and competes with renewable diesel, which typically offers better margins for producers. As mandates push SAF volumes beyond what HEFA can supply, the industry must move to cellulosic biomass or power-to-liquid pathways, at progressively higher cost. Scaling the SAF industry does not automatically bring prices down. In the near term, it pushes them up.
Policy Determines Who Absorbs the Cost
If price parity is not coming, the cost premium lands somewhere. Two policy philosophies have emerged to answer that question.
Europe has largely adopted the polluter-pays principle: SAF mandates place the cost burden on fuel suppliers and, by extension, on airlines and their passengers. The EU's ReFuelEU Aviation regulation and the UK's SAF mandate both carry steep penalties for non-compliance. As Relae has documented, in the UK, those penalties range from three to 13 times the cost of compliance, depending on the obligation type and year, signaling that regulators are serious about pushing aviation toward sustainable fuels.
The United States approached the problem differently, leaning on taxpayer subsidies.The Inflation Reduction Act (IRA) 45Z Clean Fuel Production Credit and its predecessor, the 40B Sustainable Aviation Fuel Credit sought to socialize much of the cost premium. The appeal of this approach was that it made SAF economics viable without raising ticket prices. Its vulnerability was political: when the IRA's incentive landscape was revised, the project pipelines that had formed around those credits evaporated quickly. US taxpayer-funded support proved politically less durable than the UK and EU’s mandated compliance obligations.
Neither model works in isolation. Mandates without bankable project finance generate demand signals but no new supply. Incentives without policy durability attract project interest but cannot get facilities to final investment decisions. The deals that have actually moved capital combine a stable policy floor, whether mandate or incentive, with long-term private commitments that provide the revenue certainty project finance requires.
The Google-American Airlines deal illustrates the incentives-plus-private-commitment structure. The deal explicitly credits the Illinois SAF tax credit as the enabling policy lever. HEFA SAF of this type is eligible to generate Renewable Fuel Standard credits (RINs), and fuel produced from 2025 onward qualifies for the IRA's 45Z Clean Fuel Production Credit. This stack provides additional floor economics. The corporate offtake completes the structure by delivering the revenue certainty that volatile policy credits alone cannot. Remove any one of those elements and the deal's economics likely do not hold.
Nobody in this Market Is Buying SAF for its Energy Content
This is the key to understanding how the SAF market works. Neither airlines nor corporate buyers purchase SAF for its energy content. Airports have kerosene. Airlines do not need SAF to keep planes in the air. Corporate buyers, like Google, have minimal operational use for aviation fuel at all. While recent global disruptions in crude oil supply have highlighted SAF in the context of energy security, the industry as it exists today does not represent a realistic hedge against conventional fuel volatility.
What all parties are buying is the sustainability attribute attached to the fuel. For airlines, the relevant claim is a scope 1 emissions reduction: the right to report lower lifecycle carbon intensity for their flight operations. For corporate buyers, the relevant claim is a scope 3 reduction, a documented abatement of the emissions associated with their employees' business travel. Book-and-claim accounting makes this architecture explicit: it legally severs the physical fuel from the environmental attribute, allowing each to be transferred to the party that values it. The fuel is the delivery mechanism for the claim.
This distinction matters for assessing the market. Airlines operate on among the lowest margins of any major industry. They cannot absorb the cost premium voluntarily without fundamentally compromising their finances. They participate in SAF markets when required to by mandate, or when a corporate partner subsidizes the premium by purchasing certificates downstream. The cost premium does not disappear; it shifts. Understanding where it lands is the starting point for any serious procurement decision.
Corporate climate programs have finite budgets. SAF competes with renewable electricity procurement, fleet electrification, CO2 removal, and supply chain decarbonization for the same dollars. Buyers who want their sustainability claims to match the actual sources of their emissions (rather than offsetting aviation with unrelated activities elsewhere) have a genuine reason to prefer SAF.
A SAF Claim Is Only as Strong as the Quality Behind it
SAF buyers and sellers trade sustainability claims. The quality of those claims is the entire value proposition, and the reputational liability travels with them. The companies with the greatest willingness to pay for SAF certificates tend to be those with the most brand exposure: high-profile technology companies, professional services firms, and financial institutions. These are also the companies most likely to face scrutiny from regulators, NGOs, and investors if a claim does not hold up. Buying a certificate does not protect a company from that scrutiny. It transfers the liability along with the attribute.
That means a rigorous buyer needs to answer at least three distinct questions before relying on a SAF claim.
- Does this fuel actually reduce lifecycle emissions?
SAF's climate case rests on a carbon cycle argument: the feedstock absorbs CO₂ from the atmosphere as it grows, so when that carbon is released during combustion, the net addition to the atmosphere is theoretically near zero. But that logic holds only if upstream production is clean, and it often is not.
Indirect land use change (when demand for a feedstock crop displaces food agriculture elsewhere, triggering clearing of forests or grasslands) can generate substantial emissions elsewhere in the global land and food system, eroding or eliminating the lifecycle benefit. Even waste-based feedstocks are not automatically clean: used cooking oil and tallow have existing market uses, and diverting them without careful accounting can displace those uses, alter commodity markets, and create emissions leakage elsewhere.
- Is the purchase additional?
Additionality asks whether the procurement caused SAF to exist that otherwise would not have. This is a harder question than it appears, especially in markets where multiple policy support mechanisms are already active. For the Google-American Airlines deal, one critical variable for financial additionality—the SAFc price—has not been disclosed. If Illinois credits and federal RINs already cover most of the HEFA cost premium, then the question of what Google's purchase actually caused to happen is genuinely open. However, American Airlines has stated publicly that the long-term nature of the agreement enabled them to secure a new SAF offtake with Valero Marketing and Supply Company. The supply arrangement that may not have been bankable on the basis of volatile RIN markets and changeable policy alone. That is a real additionality argument. But it requires transparency to evaluate. The undisclosed SAF credit price is a current market liability, not just in this deal, but across the voluntary SAF market broadly.
Long-term offtakes do something that policy credits cannot: they provide stable, bankable revenue certainty. RIN prices fluctuate. Tax credits change with administrations. Neither can reliably anchor a final investment decision at the project level. A multi-year, creditworthy offtake agreement can. This is the distinctive and genuinely valuable role that corporate buyers play in this market: not paying the cost premium per gallon, but reducing the financial risk premium that keeps capital on the sidelines.
- Is the full supply chain sound?
Carbon claims are not the only dimension of sustainability that matters to a buyer's reputation. Companies making claims about their SAF procurement are implicitly making claims about their supply chains. That means labor practices, community impacts, Indigenous rights, feedstock sourcing integrity, and market leakage from displaced uses all fall within the scope of what a rigorous buyer should evaluate. A SAF supply chain that displaces food crops, harms a proximate community, or causes deforestation through indirect land use change creates a reputational problem that no certificate can fix.
What High-Integrity SAF Procurement Looks Like
The voluntary SAF market is still early, and the transparency it requires does not yet exist consistently. Relae recently released the Criteria for High-Quality Low Carbon Fuels, a comprehensive, publicly available framework designed to help close that gap.
The criteria address six principles across the full supply chain: carbon accounting, additionality, feedstock sourcing, leakage, environmental harms, and social harms and environmental justice. They are designed as a practical reference for what a credible SAF claim requires, and where existing certifications may leave gaps that require additional diligence.
At the transaction level, five questions should have clear answers before any buyer signs an offtake:
- Is the certificate linked to a specific project or supply agreement?
- Is that project financially dependent on the offtake, after accounting for all policy support already in the stack?
- Is the lifecycle emissions profile documented across the full well-to-wheel boundary, including indirect effects?
- Are the feedstock sourcing and supply chain risks assessed and disclosed?
- Has the producer evaluated leakage and community impacts?
The Google-American Airlines deal demonstrates what serious voluntary SAF procurement can look like. The Criteria for High-Quality Low Carbon Fuels provides the framework buyers need to evaluate deals like this one rigorously.
Low-Carbon Fuels Get a Market-Based Reporting Home
Key Takeaways
- The Greenhouse Gas (GHG) Protocol’s Actions and Market Instruments (AMI) proposal would formally recognize market-based instruments across emissions scopes for the first time, within Statement 2.
- The proposal substantially expands opportunities for companies to report lower emissions from purchasing market-based instruments for low-carbon fuels (LCF), such as book-and-claim environmental attribute certificates (EACs) for sustainable aviation fuel (SAF) and renewable natural gas (RNG).
- Companies purchasing or already holding market-based instruments for SAF, RNG, and other low-carbon fuels should begin mapping those instruments to the AMI’s proposed reporting structure now, before the standard is finalized.
The Current Reporting Problem With Low-Carbon Fuels
A low-carbon fuel is defined as a fuel whose lifecycle greenhouse gas (GHG) emissions are lower than those of a relevant, use-case-specific fossil fuel baseline. Most LCFs used today are created from biogenic sources like agricultural residues, used cooking oil, or landfill gas, and their use often results in reduced GHG emissions due to the fact that the CO2 they release during use is biogenic and not fossil.
Consumers of LCFs face a reportability problem. Many buyers track LCF purchases through market-based instruments such as book-and-claim and mass balance EACs. These instruments unbundle environmental claims from physical molecules to facilitate investment in LCFs when direct provision of the molecule is infeasible. However, the current GHG Protocol only permits the use of market-based tools for electricity-based emissions.
Currently, companies cannot recognize the emissions benefit of an LCF purchase unless they physically receive and combust the fuel. Given that sustainable aviation fuel, renewable natural gas, and other LCFs typically flow into shared pipeline and distribution infrastructure rather than being delivered to buyers as distinct physical molecules, direct delivery is often not achievable in practice. This limitation constrains demand growth in the voluntary market.
The value of LCFs to voluntary buyers is the sustainability claim attached to the molecule, not the molecule itself. Without a credible reporting framework for market-based instruments, buyers struggle to justify LCF procurement. Producers, in turn, may face a market where buyer reluctance limits commercial opportunities for scale-up. Non-reportability inhibits one of the few available levers to incentivize voluntary investment in climate solutions.
[cta]
How Does the AMI Proposal Address Non-Reportability?
The Actions and Market Instruments (AMI) proposal introduces a four-statement reporting framework, with all four statements relevant to elements of LCFs. Together, these statements give organizations across the LCF value chain a standardized way to account for LCF procurements in their sustainability reports, whether those procurements are physical or through market-based instruments.
- Statement 1 covers the physical GHG inventory and is the traditional GHG Protocol inventory as it exists today. Companies that physically receive and combust LCFs recognize the lower GHG emissions here.
- Statement 2 proposes a market-based GHG inventory for all emissions scopes. For the first time, this will allow companies to report the carbon intensities of book-and-claim and mass balance EACs for LCFs within a GHG Protocol-aligned inventory. This is a shift from the current framework, which relegates market-based instruments for LCFs and other products, along with carbon credits, to a supplemental section outside of the core emissions inventory. By bringing these purchases into the inventory itself, Statement 2 puts market-based LCF claims on a more equal footing with the emissions companies already report.
- Statement 3 covers beyond value chain interventions as well as GHG emissions reductions/avoidance reported relative to a baseline counterfactual (e.g., the domain of carbon credits). Avoided methane emissions upstream from RNG use is one LCF-relevant example that might live here.
- Statement 4 captures non-GHG indicators and could include things such as the quantity of an LCF procured or produced. This rounds out the story an organization tells about how LCFs fit within their operations and value chain.
How the AMI Proposal Applies to Specific Fuel Types
Two important LCFs are impacted by the current GHG Protocol guidance and offer an example of the significance of the AMI proposal.
- SAF is a biobased or synthetic drop-in substitute for conventional jet fuel.
- RNG, generally produced from organic wastes, is a drop-in substitute for conventional natural gas.
Both are typically delivered through existing infrastructure. SAF is typically blended into a common fuel supply. RNG is often injected into the broader gas network. The buyer typically does not have a direct physical link to the molecule’s consumption, but rather an indirect claim on molecules injected into a common system.
Current GHG Protocol guidance disallows using and reporting market-based LCF emissions factors within corporate scope inventories. If finalized as proposed, the AMI proposal’s Statement 2 would open the aperture for companies to report the lower emissions from purchasing SAF or RNG market-based instruments. Here’s how that might work.
SAF: Reporting Across the Value Chain
When an airline physically receives and burns SAF in its aircraft, the lower combustion emissions are reflected in its Statement 1, scope 1 emissions inventory. This is reported the same way as conventional jet fuel.
The picture changes when airlines use market-based instruments. Many airlines purchase scope 1 SAF certificates that are decoupled from the physical fuel and tracked via book-and-claim or mass balance EACs. Under the AMI proposal, the lower emissions factors of these instrument purchases would be reflected in an airline’s Statement 2, scope 1 emissions inventory.
Corporate buyers face a parallel situation. Companies that purchase scope 3 EACs from SAF suppliers or through airline programs to address employee travel would reflect these lower emissions factors in their Statement 2, scope 3, category 6 emissions. Legitimate Statement 2 claims provide additional incentive for corporate climate action to address travel emissions.
RNG: Reporting Across the Value Chain
As with SAF, an organization that physically receives and combusts RNG can reflect the lower emissions in its Statement 1, scope 1 emissions inventory.
More often, RNG is injected into the shared gas network and claimed by users through book-and-claim or mass balance certificates rather than physical delivery. Statement 2 introduces a reporting opportunity for RNG EAC purchasers to report lower scope 1 emissions. Lower emissions from RNG consumption could also be passed through as reduced scope 3 emissions for consumers of products associated with RNG consumption.
RNG carries an additional nuance. Some RNG projects may also claim to have avoided methane emissions (e.g., dairy manure methane emissions avoided by way of diversion to RNG). This type of methane avoidance attribute, typically tracked in the realm of carbon credits, would have a home within Statement 3, subject to additional disclosure requirements. Companies evaluating RNG certificates should understand which claims belong in which statement.
Application to Other LCFs and Market-Based Instruments
While SAF and RNG are two of the more prominent examples, the AMI proposal is relevant to all LCFs including renewable diesel and marine fuels. The emissions associated with market-based instrument purchases for these fuels would belong in Statement 2.
The proposed framework may also cover market-based instruments aimed at lower emissions conventional fuels, e.g., natural gas production that has taken measures to reduce fugitive methane emissions far below industry averages. Companies purchasing certificates of this type would theoretically report the reduced upstream natural gas emissions rates in Statement 2, scope 3, category 3.
Three Steps Companies Can Take Now to Prepare
The AMI proposal is still in development. A public request for information on the initial white paper recently closed. A draft standard is in development, with a formal public consultation planned in Q3 2027. Companies that act early will be better positioned when the standard takes effect. Steps will vary depending on where in the fuels value chain an organization sits, but could include:
- Map exposure. Identify where the organization sits in the LCFs value chain and what fuels it is currently procuring and consuming. This will help to better understand where the largest fuels-related emissions hot spots are in the current GHG inventory.
- Record current instruments and assess quality. Catalog the instruments the company is currently producing or procuring. Understand where these instruments may sit within the AMI’s proposed four-statement framework and assess their quality against emerging eligibility criteria.
- Engage with the process. The GHG Protocol is still defining eligibility and quality criteria for LCF instruments. Organizations can monitor interim developments from the AMI Technical Working Group. Companies with active programs have a real stake in how those criteria are written.
Frequently Asked Questions
How would the AMI proposal change the way low-carbon fuels get reported?
The core shift is the introduction of Statement 2, a new market-based GHG inventory. For the first time, companies would be able to report the lower emissions from purchasing market-based LCF instruments, including book-and-claim and mass balance EACs, within a GHG Protocol-aligned inventory. This applies to all LCFs, including SAF and RNG, and can be reflected in scope 1 or scope 3 inventories depending on where the organization sits in the LCF value chain.
Is the AMI proposal finalized, and what should companies do now?
No, the proposal is still in development. A public request for information on the initial white paper recently closed. A draft standard is in development, with a formal public consultation planned in Q3 2027. In the meantime, companies holding SAF, RNG, or other LCF instruments should map their exposure across the value chain, catalog existing instruments against the proposed four-statement framework, assess quality against emerging eligibility criteria, and monitor GHG Protocol AMI updates.
What should a company look for when evaluating a SAF or RNG certificate?
Buyers should confirm which claim a certificate actually conveys and where it would sit in the AMI’s proposed framework. For example, a lower-emissions carbon intensity claim belongs in Statement 2 whereas an avoided-methane claim falls under Statement 3. Buyers should also assess the instrument against the AMI's emerging eligibility and quality criteria to reduce the risk that a purchase won't qualify under the final standard. Relae (formerly Carbon Direct) has published a comprehensive set of criteria for high-quality low-carbon fuels that buyers can use as a starting point, until AMI’s eligibility and quality criteria are finalized.
Steel Decarbonization: How EACs Scale Low-Carbon Production by 2030
Key Takeaways
- Decarbonizing steel is key to meeting ambitious climate targets in the face of rapidly expanding AI infrastructure as well as broader infrastructure growth.
- The gap between corporate climate ambitions and near-term commercial reality is widening. Despite strong demand signals from hyperscalers and other major buyers, leading producers have recently canceled or delayed flagship green steel projects, citing high energy costs, slow hydrogen market development, and unfavorable policy environments.
- Bridging this gap requires significant capital investment and supporting mechanisms to scale low-carbon technologies. Environmental attribute certificates offer an effective mechanism to channel capital toward transformative, low-carbon steel projects, supporting technology scale-up, as well as providing a way for buyers to meet their emissions reduction targets.
- To protect the credibility of environmental attribute certificates as a market mechanism for decarbonization, projects should seek to meet rigorous quality criteria such as additionality, verifiability, and catalytic impact.
Forging New Climate Ambitions for Steel Production
Decarbonizing steel production is essential to meet global climate targets. Steel production accounts for approximately 7–9% of global CO2 emissions. This is driven chiefly by coal-based primary steelmaking, which still accounts for the majority of global production. Globally, at least 1.8 billion tonnes of crude steel were produced in 2025 to serve a broad array of industries including real estate, infrastructure, automotive, and data center construction.
As hyperscalers race to build the infrastructure underpinning the AI revolution, steel demand for data center construction, and associated energy infrastructure, is increasing. While the relative share of data center demand for steel versus global steel demand is small, the need for approximately 20,000 tonnes of steel per data center has a material impact on hyperscaler’s public climate commitments. Microsoft, Meta, and other large technology companies have set ambitious 2030 climate targets that include their scope 3 emissions. The embodied carbon of the steel used to build their data centers sits squarely in scope 3.
Hyperscaler’s climate commitments have generated sector-specific demand for decarbonized steel, presenting an opportunity to affect steel decarbonization more broadly. Despite this demand, the supply of low-carbon steel remains limited. The industry faces significant scale-up challenges due to the diffuse nature of demand and the nascent market. Catalyzing growth in decarbonized steel production will require market innovations and new production pathways designed to overcome these challenges. Credible environmental attribute certificates can help bridge the gap between today’s market and tomorrow’s low-carbon steel sector.
What is an Environmental Attribute Certificate?
An environmental attribute certificate (EAC) represents the environmental attributes of a product that can be unbundled and transacted separately from the underlying physical commodity. The most widely used EACs today are renewable energy certificates (RECs), which track the environmental attributes of renewable electricity. The same concept can also be applied to steel and iron, as well as to materials such as cement and concrete.
In a book and claim model, a steel producer can implement a verified emissions reduction intervention, quantify the resulting lowered carbon intensity per tonne of steel produced, and convert that into tradeable certificates. Buyers can then purchase those certificates to support the deployment of low-carbon steelmaking capacity in cases where direct procurement of low-carbon steel is currently impractical due to geographic, contracting, or scheduling incompatibilities.
EACs are distinct from carbon credits. They do not represent emissions reduced or avoided relative to a counterfactual; they represent the intrinsic carbon intensity of the material produced, measured through a life cycle assessment.
Decarbonizing Steel Requires Significant Capital and Infrastructure Deployment
Steel Production Today
Steel is currently made via three main production routes. About 71% of the world’s steel is produced through the blast furnace–basic oxygen furnace (BF-BOF) route, which emits an average of 2.33 tonnes of carbon dioxide (tCO2) per tonne of crude steel. A further 24% is produced using scrap-based electric arc furnaces (EAFs), which emit 0.68 tCO2 per tonne on average—far lower, but still dependent on the carbon intensity of grid electricity. The remaining roughly 5% uses direct reduced iron combined with an EAF (DRI-EAF), typically using natural gas, emitting 1.37 tCO₂ per tonne on average.
While increasing scrap-based production is a critical decarbonization lever, scrap availability is limited. Primary steel production, which uses iron ore as the main feedstock rather than recycled scrap, will remain necessary at large volumes through 2050. This makes it essential to decarbonize ore-based pathways, especially ironmaking: the step where iron ore is reduced to iron and where most emissions occur.
Decarbonizing ore-based steel production requires one of three fundamental interventions: (1) replacing coal and natural gas with low-carbon fuels such as hydrogen or bio-coke, (2) electrifying ironmaking directly, or (3) capturing and storing the CO2 generated from fossil-fuel-based processes. All three involve significant capital expenditure and dependencies on infrastructure that is not yet in place at the necessary scale. As a result, the energy and cost challenge is substantial.
Low-Carbon Steel: Emerging Pathways
A range of transformative technological pathways are currently in development to overcome these barriers, offering the potential to deliver deep decarbonization to the steel industry exceeding 90% by 2050:
- Hydrogen-based DRI-EAF: Using green hydrogen instead of natural gas within the DRI process provides a pathway to significantly lower the carbon intensity of ironmaking. Producers such as Stegra are deploying commercial-scale facilities designed to utilize 100% green hydrogen to reduce iron ore.
- Electrifying ironmaking:
- Molten oxide electrolysis: Boston Metal is commercializing a process that uses electricity to directly convert iron ore to molten metal through electrolysis at high temperature, eliminating the need for hydrogen or carbon reductants entirely.
- Low-temperature electrowinning: Colorado-based startup Electra uses renewable electricity to extract iron from ore via an aqueous electrochemical process that operates at near-ambient temperature.
- Carbon capture and storage (CCS): For blast furnaces and DRI plants with long remaining lifetimes, retrofitting with CCS technology can significantly reduce emissions. With new high-emitting capacity still being built, and assets expected to operate for decades, integrating CCS will be essential to avoid long-term carbon lock-in and to decarbonize these facilities over time. To date, commercial-scale deployment remains limited. The Al Reyadah facility at Emirates Steel is the only project currently capturing CO2 from a DRI process at scale, though a handful of other large-scale projects have entered the development pipeline.
Progress and Setbacks: A Mixed Picture
The past year sent contradictory signals about the pace of steel decarbonization. On the demand side, technology companies with ambitious climate targets are actively signaling their intent to procure near-zero steel and support its development.
In September 2025, Microsoft and Stegra announced a landmark agreement that combines a physical supply deal for low-carbon steel with a separate EAC purchase agreement. Around the same time, Meta announced an agreement with Electra to purchase EACs tied to the startup’s clean iron production, becoming one of the first buyers to use the EAC model for an entirely novel, pre-commercial ironmaking technology. Nucor, the largest US steelmaker, also entered into a physical iron purchase agreement with Electra.
Despite these demand signals, the industry has experienced significant setbacks. A series of low-carbon steel project cancellations and delays has raised questions about the pace and viability of the steel transition, especially due to the high costs associated with green hydrogen production.
At present, the green premium for most low-carbon steel remains too high for buyers. A combination of sustained policy support, long-term demand signals from buyers willing to pay more, and scaling of supporting industries, such as green hydrogen production, is necessary for the low-carbon steel industry to be successful in the long run.
How EACs Can Bridge the Funding Gap in Steel
EACs unbundle low-carbon steel attributes from the physical material, reducing the friction between buyers who are willing to pay a green premium and geographic or logistical constraints that may inhibit physical offtake. Buyers, such as hyperscalers procuring conventional steel for data center construction in locations where low-carbon steel is not yet available, can purchase these certificates to support the development of low-carbon capacity, attribute lower-carbon production to their steel use via a market-based mechanism, and advance toward their scope 3 targets.
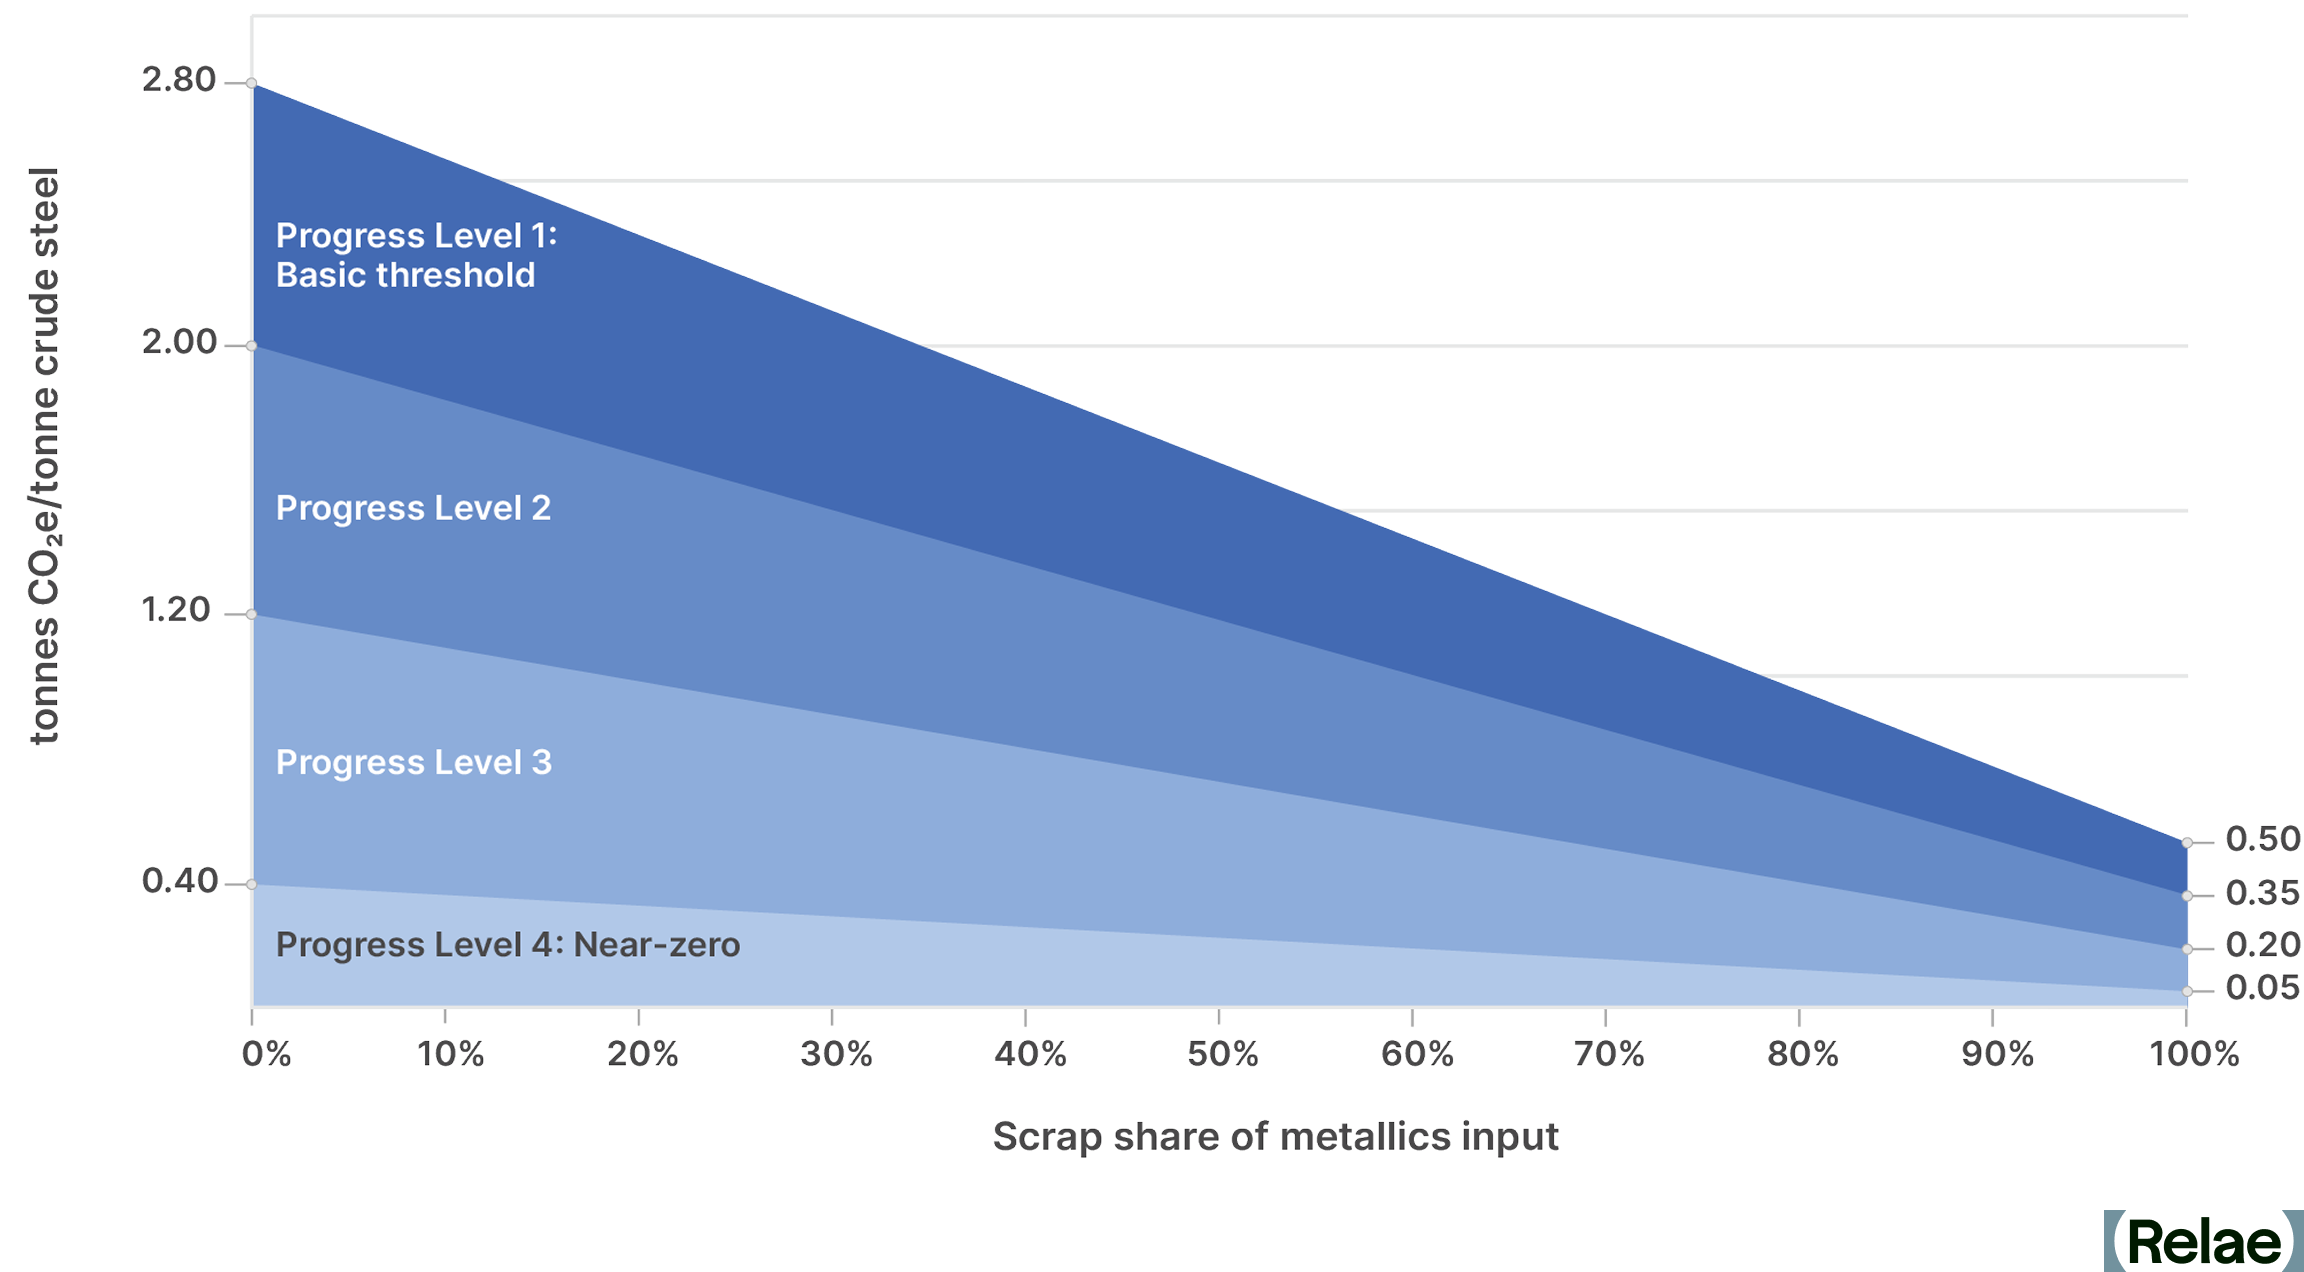
A primary objective of the Criteria for High-Quality Environmental Attribute Certificates in the Concrete and Steel Sectors, jointly developed by Relae (formerly Carbon Direct) and Microsoft, is to establish high-integrity standards for the EAC market in these sectors. For steel EACs, that means demonstrating significant emissions reduction performance by reaching at least Progress Level 2 in the ResponsibleSteel Decarbonization Progress Levels framework, and aiming to achieve Progress Level 3 by 2030. ResponsibleSteel’s scrap-variable benchmark provides a technology-neutral mechanism to evaluate emissions reduction performance by accounting for the specific proportion of scrap used.
EACs for steel are designed to be catalytic. Rather than supporting incremental improvements that are already becoming cost-competitive, they should target transformative capital changes, such as replacing BF-BOF routes with DRI-EAF, adopting low-carbon hydrogen in DRI processes, or deploying novel ironmaking technologies. Multi-year purchase agreements are particularly powerful because they provide the investment certainty that first-of-a-kind projects need to access capital at a lower cost.
What this Means for Buyers and Suppliers of Low-Carbon Steel
Whether you are producing or procuring steel, EACs are only one part of a broader decarbonization strategy. For buyers with significant emissions from steel, and other building materials such as cement and concrete, EACs can be a powerful tool to help advance scope 3 reduction goals where supply for physical low-carbon materials is limited. Suppliers can complement commercialization strategies for low-carbon materials by using EACs to monetize emissions reductions, generate additional revenue to support decarbonization investments, and help scale markets for low-carbon materials. Navigating the steel market requires decisions at the intersection of technical feasibility, greenhouse gas accounting, and capital strategy. Key considerations include:
- Greenhouse gas accounting and reportability: Cradle-to-gate emissions for steel production must be tracked using life cycle assessments and should strive for interoperability with environmental product declarations (EPDs). EAC transactions must be reported transparently, especially given the absence of formal market standards at this stage.
- Additionality and catalytic impact: EAC purchases must demonstrably support projects that would not proceed without financial support from the EAC market mechanism, and projects should have a credible pathway toward the near-zero (Progress Level 4) threshold on the ResponsibleSteel framework.
- Avoiding double counting: EAC buyers must verify that the environmental attributes they purchase are not also being claimed by the physical product buyer via an EPD.
FAQs
What is an environmental attribute certificate (EAC) for steel?
An EAC represents the environmental attributes of low-carbon steel, unbundled from the physical material itself, so a producer can quantify a verified reduction in carbon intensity per tonne and sell that value as a separate, tradeable certificate. Buyers can purchase EACs to support low-carbon steel production while still working toward their own emissions targets.
How is an EAC different from a carbon credit?
An EAC reflects the intrinsic carbon intensity of the material itself, measured through a life cycle assessment. That's different from a carbon credit, which represents carbon dioxide actively avoided, reduced or removed from the atmosphere relative to a baseline.
How are AI data centers impacting the demand for low-carbon steel?
Data centers use roughly 20,000 tonnes of steel each, and as hyperscalers build out AI infrastructure, that steel use counts toward their scope 3 emissions and public climate targets. That's turned data center construction into a meaningful driver of demand for low-carbon steel, even though supply remains limited.
What makes an EAC credible enough to count toward a company's emissions goals?
A credible steel EAC needs to meet criteria like additionality (the project wouldn't happen without the EAC revenue), verifiability through life cycle assessment, and catalytic impact toward transformative technology rather than incremental gains. Relae (formerly Carbon Direct) and Microsoft jointly developed criteria for high-quality EACs in the steel and concrete sectors, which set a threshold of at least Progress Level 2 on the ResponsibleSteel Decarbonization framework today, rising to Progress Level 3 by 2030.
Can a producer sell an EAC and also get credit for the physical steel elsewhere?
No. EAC producers need to confirm the environmental attributes they're selling aren't also being claimed by whoever buys the physical steel through an environmental product declaration; otherwise the same emissions reduction gets counted twice.
CORSIA Phase 1: Credits, Compliance, and What Comes Next
Key Takeaways
- CORSIA, the program intended to address international aviation emissions, is currently the world’s largest international compliance carbon market, with approximately 200 million tonnes of eligible emissions units (EEUs) expected to be retired for Phase 1 (2024-2026) compliance.
- Airlines have already begun retiring significant volumes of credits (clean cookstoves and jurisdictional REDD+) toward their Phase 1 obligations ahead of the January 2028 compliance deadline, signaling that the industry is treating CORSIA as a binding policy mandate.
- In addition to the four already approved, a record 25 carbon standards have applied for eligibility to supply credits under Phase 2 (2027–2035), pointing to a diversifying pipeline of credits.
- Legal enforcement of CORSIA at the national level remains uneven. A handful of jurisdictions, including the EU, Japan, Brazil, New Zealand, and Canada, have established compliance regimes, but it is unclear whether other major aviation markets will implement domestic enforcement requirements by 2027.
- As CORSIA matures alongside other compliance and voluntary frameworks, strategic engagement increasingly depends on understanding where eligibility overlaps and where the most value can be found.
Introduction to CORSIA
The Carbon Offsetting and Reduction Scheme for International Aviation (CORSIA) was established and is managed by the International Civil Aviation Organization (ICAO)—a specialized agency of the UN—and provides a compliance mechanism to reduce emissions from international aviation that do not fall within a single country’s contributions to the Paris Agreement. For years, CORSIA generated more commentary than activity—airlines weren’t required to offset a single tonne of CO2 emissions (tCO2) during the pilot phase (2021–2023). That is changing; in early 2026, Singapore Airlines and Japan Airlines retired significant volumes of carbon credits against their Phase 1 (2024–2026) obligations. Increasing authorization announcements showcase the eligible supply steadily entering the market, and 25 carbon standards have applied for Phase 2 (2027–2035) eligibility. As CORSIA becomes an active compliance market, this article explains how the program works, what is driving the current trends, and what to watch as Phase 1 draws to a close.
Who is Covered by CORSIA Phase 1 and Phase 2?
Because emissions from international aviation are not tied to any individual nation, the International Civil Aviation Organization (ICAO) adopted CORSIA in 2016 to complement the Paris Agreement framework and address these emissions. CORSIA applies to international airlines operating flights registered between participating countries.
- During Phase 1, offsetting obligations apply only to routes between the 130 countries that have voluntarily opted in.
- From Phase 2, participation becomes mandatory for all 193 ICAO member states, except for those below the aviation activity threshold or classified as Least Developed Countries, Small Island Developing States, or Landlocked Developing Countries—although they can voluntarily participate.
Several major aviation markets, including China, that are not participating in Phase 1 will be required to do so from 2027.
Offsetting Obligations
Airlines are required to offset the portion of their emissions that exceeds the program’s baseline on routes subject to offsetting. The key input is the annual Sectoral Growth Factor (SGF), which reflects how much annual emissions on covered routes have grown above the baseline (set at 85% of 2019 emissions). In simple terms, each airline's offsetting obligation is calculated by multiplying its CORSIA-regulated emissions by the SGF.
For example, an airline that emits 1 million tCO2 on covered routes in a year when the SGF is 10%, would have an offsetting obligation of 100,000 tCO2. An airline that emits 500,000 tCO2 in the same year would have an obligation of 50,000 tCO2. The actual 2024 SGF was 15.4%, exceeding the baseline and triggering offsetting obligations for the first time since the COVID-induced reduction in international aviation activity.
Beginning in 2033, CORSIA’s offsetting formula combined the SGF with an individual component that accounts for each airline's own emissions growth. The individual weighting starts at 15% in 2033 (with an SGF weighting of 85%) and rises to 45% by 2035 (SGF 55%). This progressively ties each airline’s obligations to its own emissions trajectory rather than sector-wide trends alone.
Airlines can also reduce their obligations by reporting the use of CORSIA Eligible Fuel (CEF). In order to qualify as CEF, Sustainable Aviation Fuel (SAF) must meet ICAO’s certification criteria. Offsetting remains a lower-cost option than sustainable fuel procurement, and CORSIA obligations are currently not influential drivers of CEF/SAF uptake compared to supply mandates, such as ReFuelEU Aviation. However, these dynamics will evolve as CORSIA matures and SAF prices continue to fall.
CORSIA Eligible Carbon Credits: Phase 1 and Phase 2
To determine the eligibility of carbon crediting standards and credits issued under those standards, ICAO's Technical Advisory Body (TAB) reviews applications and recommends approval to the ICAO Council, subject to restrictions on methodologies, vintages, and more granular project elements. Currently, no standard is approved without exclusions. Credits eligible for use under CORSIA are known as Eligible Emissions Units (EEUs).
TAB broadly excludes some project types across standards, including large-scale grid-connected renewable energy projects and most project-level REDD+ activities. The exclusions reflect TAB's assessments of baselines, safeguards, and quantification gaps. However, these assessments are not static; ICAO updates its determinations as the evidence base improves. For example, in 2025, TAB approved certain direct air capture (DAC) and biochar pathways for the first time.
A record 25 carbon standards—certifying projects from emissions avoidance to engineered carbon dioxide removal (CDR)—have applied for Phase 2 eligibility in the 2026 assessment cycle, reflecting the scale of the opportunity. The International Air Transportation Association (IATA) projected a demand of 170–236 million EEUs for Phase 1 alone; developers are eager to serve this growing market. Assessment results are expected in October 2026.
Article 6 and Corresponding Adjustments
The biggest bottleneck for eligible supply has been requirements relating to Article 6.2 of the Paris Agreement. CORSIA requires that EEUs carry a host country Letter of Authorization (LoA) confirming that the host country will not count the underlying mitigation toward its Nationally Determined Contribution (NDC). This prevents double counting between CORSIA and national emission inventories, but it also means eligible supply depends on host country authorization, not just meeting methodological requirements. Authorized credits are called Internationally Transferred Mitigation Outcomes (ITMOs).
To manage the risk that a host country fails to apply the promised corresponding adjustment, projects must secure legally enforceable insurance policies that either provide replacement EEUs or funds to secure them. Several providers have been approved to insure EEUs registered by Gold Standard and Verra.
Insurance requirements do not apply when the host country has already confirmed the corresponding adjustments in its mandatory Paris Agreement reporting. For example, in March 2026, Madagascar submitted a Biennial Transparency Report (BTR) and annual information report that reflect the application of corresponding adjustments to CORSIA-eligible clean cookstoves credits listed on the Verra registry. According to Verra, BTR accounting is the “highest level of assurance” that ITMOs will not be double counted.
The Enforcement Challenge
With the authorization bottleneck loosening, market attention is turning to demand. Critically, ICAO has no direct enforcement power; for CORSIA to work, participating countries must pass laws requiring airlines to comply with its requirements. Under CORSIA rules, airlines must retire their Phase 1 EEUs by January 2028, but most are not yet subject to legal sanctions for failing to comply. Where regulations do exist, it remains unclear whether penalties will be stringent enough to matter, or whether they will be enforced at all.
Where legal enforcement of offsetting requirements does exist, it varies by design. For example, in Brazil, failure to comply attracts a penalty of BRL 50/tCO2 (US$10/tCO2) and an administrative fine. Meanwhile, the Canadian Aviation Regulations impose administrative fines capped at CAD 25,000 (US$18,000) per infraction, but there is no specific fine for each tCO2 not offset. However, the absence of a statutory penalty framework does not necessarily mean compliance will not be enforced. For example, New Zealand manages CORSIA participation through an administrative Memorandum of Understanding with Air New Zealand, rather than a dedicated legal regime (though this will change from 2027). Similar informal arrangements may be more common than the legislative record suggests.
According to 2024 data, US-based airlines account for around 15% of CORSIA-covered emissions. However, there is no indication that the federal government will implement CORSIA penalties under the current administration. It is unclear how non-compliance by a major economy will impact market confidence or enforcement by other governments, but uncertainty about US participation in multilateral climate programs is not new.
What to Watch
- Global enforcement: As Phase 2 approaches, the prospects for CORSIA enforcement in key aviation markets will become clearer. China, which has not participated in the voluntary phase and has raised objections to CORSIA’s design on grounds of fairness, presents an uncertain picture for domestic transposition. The UK government has consulted on a draft legal amendment that would penalise non-compliance for UK airlines at £100/tCO2 (US$130/tCO2), but has not published updates since February 2025.
- EU Emissions Trading Scheme (ETS) update: In July 2026, the European Commission proposed to expand the ETS to address emissions from flights departing the European Economic Area (EEA) to destinations within 5,000 km. To avoid double charging emissions also regulated under CORSIA, the Commission proposed to deduct CORSIA costs from airlines’ ETS obligations. While the Commission flagged concern about the stringency of CORSIA eligibility criteria, the proposed rules would not impact demand for Phase 1 EEUs. Still, it is worth watching for future restrictions on which credits EU airlines can use for CORSIA, whether in Phase 1 or 2.
- Supply financing vehicles: The LEAF Coalition—which purchases credits verified under the CORSIA-eligible ART TREES standard—has signed over US$1.5 billion worth of purchase agreements with host countries. The Forest Carbon Partnership Facility (FCPF) and BioCarbon Fund Initiative for Sustainable Forest Landscapes (ISFL), both CORSIA-approved for Phase 1 in early 2026, have built jurisdictional REDD+ pipelines across dozens of countries. As projects mature, it will be worth watching how issued credits are marketed across compliance and voluntary channels.
Strategic Considerations
Avoided emissions credits dominate early CORSIA supply—and consequently demand—principally from avoided deforestation and clean cooking projects. As there is no regulatory premium for higher-cost CDR, this is not surprising. But as the market matures and supply diversifies, airlines are likely to begin differentiating on geography, co-benefits, and environmental performance. Corporate interest is growing in projects that abate non-CO2 superpollutants, due to their outsized near-term climate impact. As many of these projects are based in countries actively issuing LoAs, this may soon translate into a supply of superpollutant EEUs. Some airlines are reluctant to procure aggressively now, anticipating the upcoming availability of higher-quality credits.
Credits that hold value across multiple frameworks could carry a strategic premium. A credit also eligible for Singapore's carbon tax, Switzerland's CO2 Act, or SBTi claims may offer more durable demand than one tied to a single use case. While specific requirements vary significantly, we are beginning to see convergence around broad principles, such as the need for Article 6 authorization for credits used in compliance markets tied to NDCs. Procurement and project development strategies could begin to favour credits that confer wider market optionality.
The precondition for all of this is policy stability. Longer-term offtake agreements, portfolio strategies, and meaningful investment in project development depend on confidence that CORSIA rules will hold. Efforts to soften emissions regulations in response to energy price shocks are now testing this confidence, from proposed changes to soften the EU ETS to Singapore's deferral of its SAF levy. Tracking price signals, enforcement developments, and authorization trends will be essential for identifying firm demand and where the opportunities lie.
Conclusion
Effective engagement with CORSIA requires more than developing quality projects. It means understanding methodological eligibility requirements, navigating Article 6.2 authorization processes, tracking a network of overlapping national regulations, and staying ahead of a rapidly evolving market landscape. Relae (formerly Carbon Direct) brings together policy, market, and scientific expertise to help clients on all of these fronts.
Frequently Asked Questions
Which carbon credits can airlines use for CORSIA compliance?
CORSIA Eligible Emissions Units (EEUs) must be issued by crediting standards approved by ICAO's Technical Advisory Body. Every approved standard currently has exclusions on certain methodologies and project types, so eligibility is granular rather than blanket. EEUs must also have a host country Letter of Authorization confirming a corresponding adjustment under Article 6.2 of the Paris Agreement.
Is CORSIA actually enforceable?
In all phases, CORSIA obligations are legally binding when a country writes them into domestic law. Countries participating in Phase 1 are expected to do this, but not all have, and enforcement remains uncertain in several key aviation markets (e.g., the United States). Even where enforcement exists, penalty regimes vary significantly in stringency and design.
How does the July 2026 EU ETS proposal affect CORSIA?
The European Commission's proposal to expand ETS coverage to more flights does not reduce demand for CORSIA credits. While it would lead to overlap between flights covered under CORSIA and the ETS, as proposed, airlines could have CORSIA costs effectively deducted from their ETS allowance obligations. However, the Commission has signalled continued scrutiny of CORSIA's effectiveness, which could shape future limits on the credits EU airlines are allowed to use.
The AI Bubble Debate Misses the Point: The Bottleneck Is Physical
Key Takeaways
- Agentic inference has changed the economics of AI. Tokens are becoming units of work and the economic driver is now the work produced, not token generation. Per-token costs are falling and the willingness to pay for work produced is rising; these two trends compound. This tailwind enhances AI economics and has spillover impacts on all layers of the AI stack.
- The AI infrastructure question has shifted from whether demand will show up to whether the physical stack can scale quickly enough. That stack includes power generation, grid capacity, interconnection, compute, memory, networking, cooling, siting, and community acceptance.
- Carbon Direct Capital and Relae (formerly Carbon Direct Inc.) have a differentiated view because the two entities work across both sides of the constraint: Relae advises hyperscalers and energy buyers on power and grid bottlenecks, while Carbon Direct Capital invests in the technologies that relieve those bottlenecks.
- Carbon Direct Capital sees better risk-adjusted returns investing in the physical foundations of AI, including clean firm power, energy system efficiency, data center efficiency, and inference-optimized compute, rather than chasing late-stage AI application valuations.
A Better Question Than "Is AI a Bubble?"
The most important development in AI economics is agentic AI turning tokens into work, a shift that reframes the bubble debate which dominated investor conversations, sell-side notes, and Chief Information Officer surveys through early 2026. Hyperscalers spent approximately US$380 billion on capital expenditure (capex) in 2025 and have guided to approximately US$720 billion of capex in 2026.¹ Carbon Direct Capital and Relae have worked together to build project-level models for both training and inference facilities to demystify the numbers and understand financial and technical sensitivities. The core finding was that the assets could be bankable using standard assumptions and that the binding constraints were physical, not financial. That conclusion has been reinforced in recent months by new developments.
Concretely, AI is moving from single prompts and answers to multi-step workflows that plan, reason, call tools, verify outputs, and keep state. This shift to inference is the structural successor to training in the initial AI capex cycle; it changes power requirements, time to power, and compute architectures all at once. Goldman Sachs estimates that agentic AI could drive a 24-fold increase, relative to a 2026 baseline, to roughly 120 quadrillion tokens per month globally by 2030 as per-token costs continue to fall. SemiAnalysis makes the same point from another angle: the value of frontier tokens has risen as agentic workflows become useful, while hardware and software improvements have reduced the cost of producing each token.
This does not mean every AI company is attractive, every data center project works, or every valuation is justified. It means the easy bubble framing is missing the more investable question. If token demand is compounding and the unit value of work produced is rising, the scarce resource is not abstract enthusiasm. It is the physical infrastructure required to turn that demand into work produced.
The Data Center Model Still Matters, But the Box is not a Black Box
Our internal modeling for an illustrative 167-megawatt inference data center using Nvidia Blackwell graphics processing unit (GPU) servers suggests the potential for high-teens percent equity returns under a defined set of assumptions.² We built a bottom-up underwriting, beginning with the number of users served per inference data center, assuming approximately how many tokens they will demand daily, and translating that token demand into compute needed based on industry-standard quantization and utilization rates. We then inferred the number of GPUs and servers needed to achieve the desired compute, which ultimately drove the total invested capital and power demand based on assumed thermal power designs and power usage effectiveness (PUE). On the revenue side, we used GPU-as-a-service rental rates as one proxy for the market value of compute capacity. A hyperscaler would not rent scarce compute externally if it had higher-value internal demand for that same capacity. As we will detail below, GPU rental prices have been steadily increasing on the back of inflecting inference demand.
This model is not the entire argument; it is the starting point. An important lesson is that power cost alone does not break data center economics. Electricity is slightly over 10% of total costs in our model: a 50% increase in power price reduces equity-level returns by less than 2%. Access to power, speed of interconnection, and equipment availability matter more. In other words, the economics of the model facility are workable, but only if the facility can be built and powered on the timeline customers need.
That is where most AI commentary remains too superficial. It treats the data center as a black box: capex goes in, tokens come out. That misses the bottlenecks inside and around the box. AI racks are moving far beyond traditional cloud power density. Cooling is shifting from air to liquid and two-phase systems. Networking and high-bandwidth memory become binding constraints in inference architectures. Grid interconnection queue wait times stretch to years. Communities can and do block projects. The technical, physical, and political constraints are increasingly the drivers of potential returns.
Inference Makes the Constraint Structural
While training is episodic, inference is recurring. A training run can be delayed, accelerated, or redesigned. Inference happens every time a user asks a question, a developer runs an agent, a business automates a workflow, or an application calls a model in the background. Agentic inference multiplies that load because one user action can become many model calls, validation loops, and memory reads; industry benchmarks show that agentic systems consume 5–30 times more tokens than a standard chat interaction.
Inference demand is also resilient in both directions. If efficiency gains lower the cost per token, more workflows become economic and total token consumption rises - the classic Jevons Paradox. However, token prices do not necessarily need to fall for inference spend to grow. As the economic unit shifts from tokens generated to work produced, customers may pay more per token when an agent delivers work produced that is worth more than the inference cost. Regardless of token price, tokens must all route through the same physical bottlenecks and we are seeing an increase in inference demand.
The architecture of inference is also changing. Some workloads will prioritize low-latency answers. Others, especially agentic work without a human waiting on every token, will prioritize memory, state, context, and cost per completed task. That means the AI infrastructure stack will become more heterogeneous, not less: XPUs (specialized AI accelerator chips), custom silicon, photonics, memory hierarchies, and edge or regional deployment models will all matter. The pricing data shows demand for more AI infrastructure overall: on-demand GPU rental capacity is effectively sold out across all chip generations in early 2026, with one-year Hopper H100 contract pricing rising 15–20% month-on-month through March 2026 and Blackwell B200 rental rates up 23% in March alone. When rental rates rise into a wave of new chip supply, supply is not catching up to demand.
Power Is Not One Constraint, It Is Several
Saying "AI is power constrained" is true, but not specific enough. The real problem has several layers. First, data centers need more electricity than many local grids can deliver on hyperscalers' timelines. Crucially, some grids can supply sufficient power but not continuously for 8,760 hours per year, conflicting with traditional assumptions about service reliability and leading to novel strategies around flexibility and intermittent self-supply. Second, the grid must be able to absorb large, fast-moving computational loads without creating reliability risks. Third, customers need energy procurement strategies that satisfy cost, reliability, climate, and public-acceptance requirements. Fourth, projects must get built in real communities, through real interconnection processes and real permitting fights. Power is not simply a commodity to purchase. It is an infrastructure development problem.
This is where Relae is directly relevant. Relae has assembled a team of scientific, engineering, and market experts to support a paying power and energy advisory practice serving hyperscalers, energy buyers, and power producers. Its work answers the questions customers are asking before the market prices them: how to get more capacity out of existing physical grid infrastructure; how to assess the costs and value of load flexibility through advanced modeling capabilities; how to make clean firm generation bankable; how to reduce data center energy intensity; how to validate "bring your own power" and "bring your own compute" structures; and how to build projects that communities will accept.
In the last twelve months alone, Relae has supported hyperscalers on bankability assessments for next-generation geothermal, scoped load-flexibility programs for multi-hundred-megawatt, single-customer sites, and modeled the carbon and reliability profile of "bring your own power" configurations against grid-tied baselines. Carbon Direct Capital leverages our network of technical experts at Relae, including power engineers, geologists, and electrochemists, to conduct credible technical diligence and to gain insights into early stage market trends and emerging preferences.
What Carbon Direct Capital Is Investing Behind
Our investment focus follows the bottlenecks. On the power side, we are investing in technologies that can deliver reliable power on AI timelines. Sage Geosystems is a next-generation geothermal platform with hyperscaler buy-in; Carbon Direct Capital co-led its US$97 million Series B with Ormat Technologies. We could not have made this investment without the deep expertise of the Relae research team which analyzed Sage's technical results to date to help underwrite future project feasibility. ION Clean Energy is a company that retrofits carbon capture technology onto natural gas combined cycle plants to create "blue electrons"; Relae is in active dialogue with multiple large power users on this topic. Carbon Direct Capital is also actively evaluating the enabling picks and shovels around geothermal, nuclear, fuel cells, and more.
On the data center efficiency side, we are investing in technologies that reduce the amount of power required for a unit of AI work. While it is encouraging to see incremental annual gains in chip efficiency, these are scaling far more slowly than compute demand, driving the need for more innovative technological solutions. As one example, a team at Relae helped us understand the fundamental energy consumption requirements of a standard complementary metal-oxide-semiconductor (CMOS) chip, and the potential of all-optical computing as an alternative. This led to Carbon Direct Capital investing in Neurophos, a photonic compute company targeting step-function gains in energy efficiency per chip that are beyond those achievable by existing GPUs. Carbon Direct Capital joined the company's US$110 million Series A alongside Gates Frontier, Microsoft's M12, Aramco Ventures, Bosch Ventures, and others. More broadly, we are studying other layers of the data center technology stack including networking, memory, cooling, and inference-optimized architectures because the next phase of AI infrastructure will not be solved by simply buying more of yesterday's hardware.
The Bear Case Deserves to Be Taken Seriously
There are real risks to the AI boom: Hyperscaler free cash flow can compress if capex grows faster than revenue. Model efficiency gains can reduce the amount of compute required for a given task. Training demand may be more episodic than the market assumes. Local opposition can slow or cancel data center and power projects. Some new data center capacity could become expensive cloud infrastructure competing on price if AI revenue disappoints.
Those risks are why Carbon Direct Capital frames this as an investment in constraints, not in AI enthusiasm. If efficiency improves, inference use cases expand and the bottleneck shifts to deployment, memory, power, and cost per unit of work produced. If training demand slows, inference and enterprise agents still require recurring capacity. If local grids cannot absorb load, technologies that unlock power, reduce energy intensity, or improve flexibility become more valuable. If some AI applications or model developers fail, the upstream physical bottlenecks remain for the rest.
The Investment Conclusion
The AI infrastructure opportunity sits at the intersection of frontier technology risk, project-finance economics, and energy-system engineering. Underwriting this opportunity well requires addressing all three at once; Carbon Direct Capital is built to do just that. The technical team at Relae has a pulse on emerging stakeholder preferences and scientific breakthroughs, understands novel technologies deeply, and is highly experienced in conducting detailed technical diligence to ensure that projects are viable and scalable. Carbon Direct Capital combines these market and technical insights with our commercial underwriting to facilitate new investments. We are not picking AI winners. We are not picking pure energy assets. We are investing in the companies and technologies that have to exist for AI to sustainably scale.
Frequently Asked Questions
Is the AI capex boom a bubble? While valuations vary, token demand and physical infrastructure needs are real and compounding. The correct question to ask is not whether AI is a bubble, but what the binding constraints are. Our modeling shows that constraints are physical, not financial.
What are the real constraints on AI infrastructure growth right now? AI infrastructure growth is constrained by power availability, grid capacity, and interconnection speed, not capital availability.
Why does inference matter more than training for long-term AI power demand? Inference is recurring and grows with AI usage, it is not episodic like training runs.
What is Carbon Direct Capital investing in, and why? We are investing in clean firm power, energy system efficiency, data center efficiency, and inference-optimized compute—the physical bottlenecks rather than application-layer valuations.
Disclaimer
Carbon Direct Capital Management LLC is an investment adviser registered with the US Securities and Exchange Commission (SEC). Registration as an investment adviser does not imply any particular level of skill or training. Additional information about Carbon Direct Capital Management LLC, including our Form ADV Part 2A Brochure, is available on the SEC's website at adviserinfo.sec.gov.
This content is provided for informational purposes only and should not be construed as or relied upon as investment, legal, tax, or other advice. You should consult your own advisers regarding legal, business, tax, and other matters related to any investment. Any projections, estimates, forecasts, targets, prospects, or opinions expressed are subject to change without notice and may differ from opinions expressed by other employees of Carbon Direct Capital Management LLC, its affiliates, investors, portfolio companies and other individuals, groups or entities. Certain information contained herein may have been obtained from third-party sources believed to be reliable; however, Carbon Direct Capital Management LLC makes no representations about the accuracy or completeness of any such information or its appropriateness for any given situation. Any investments or portfolio companies mentioned are not representative of all investments made by funds managed by Carbon Direct Capital Management LLC, and there can be no assurance that any investment will be profitable or that future investments will have similar characteristics or results. Past performance is not indicative of future results. The content speaks only as of the date indicated. This content does not constitute an offer to sell or a solicitation of an offer to buy any security. Any such offering will be made only pursuant to formal offering documents.
Every Climate Action Counts: GHG Protocol's AMI Proposal Explained
Key Takeaways
- The GHG Protocol's Actions and Market Instruments (AMI) proposal introduces a four-statement reporting framework that will give companies an official place to report carbon dioxide removal (CDR), book-and-claim environmental attribute certificates (EACs), and financed reductions, actions that cannot currently count toward scope 1, 2, or 3 emissions reporting.
- The AMI proposal’s four-statement framework will put current emissions and mitigation efforts side by side in the same report, in the same units, giving sustainability teams a clear, defensible way to make a business case for every major decarbonization investment.
- A full draft standard is expected in 2027/2028. Companies that audit their portfolios against emerging quality criteria and engage now will have time to identify gaps and be best positioned when the standard takes effect.
What Problem Does the AMI Proposal Solve?
Companies that have purchased carbon dioxide removal (CDR) credits, invested in book-and-claim environmental attribute certificates (EACs) for low-carbon materials, or funded a carbon capture and storage (CCS) project outside of their value chain have probably heard some version of the same question from their board, employees, or investors: "Where does this show up in our GHG Protocol Scopes?" Until now, the answer has been: it doesn’t.
The current GHG Protocol Corporate Standard was built around a single organization’s emissions inventory. It has no recognized home for CDR, EACs for materials, or financed reductions that occur outside of a company’s operational boundaries (they must be “reported separately”). Companies making real climate investments, therefore, have had no standard way to show it within the Corporate Standard.
The GHG Protocol's Actions and Market Instruments (AMI) proposal aims to fundamentally change that.
What Is the AMI Proposal's Four-Statement Framework?
The GHG Protocol's AMI proposal will replace the single corporate inventory with four distinct Statements, all housed within a single GHG Report:
- Statement 1: A company’s traditional GHG inventory, including operational emissions across scope 1, scope 2 (location-based only), and scope 3.
- Statement 2: Market-based emissions accounting across scopes 1, 2, and 3 using EACs for energy, materials, and other purchased goods. While this is well established for electricity, it will be the first time that similar book-and-claim arrangements for low-carbon steel, concrete, sustainable aviation fuel (SAF), and renewable natural gas can be directly recognized.
- Statement 3: Beyond-value-chain mitigation and CDR. This is the reporting home for CDR credits, superpollutant credits, and financed reductions that mitigate emissions outside a company’s value chain.
- Statement 4: Co-benefits and additional climate impacts, capturing non-GHG benefits arising from corporate action and value that do not fit neatly into emissions accounting.
This change is more than just a rearrangement of reporting - it’s a fundamental expansion of scope. The introduction of Statements 2 and 3 will allow companies to report their mitigation activities in tonnes of CO2e - the same unit as their emissions. For the first time, a company will be able to show its emissions and its climate investments side by side, in the same language, in the same report.
Why Does This Matter Now?
Today, companies investing in CDR, book-and-claim EACs (other than electricity), and financed emissions reductions face a persistent credibility gap. The investments are real. The climate impact is real. However, since no recognized reporting framework captures them, they are functionally invisible within corporate disclosures. This makes it harder to justify the spend internally and harder to communicate the value externally.
The AMI framework will remove that barrier across every major decarbonization category:
- A company purchasing a book-and-claim EAC for the low-carbon attribute of low-carbon concrete or steel would report the carbon intensity benefit in Statement 2 under scope 3.1. Statement 2 is the appropriate reporting location, rather than Statement 1, because the physical low-carbon concrete/steel product is not actually used by the company.
- An airline or corporate traveler using SAF via a book-and-claim arrangement could report the emissions benefit in Statement 2. Similarly, the airline could now report biogenic emissions from SAF if applicable in Statement 2, scope 1. Corporate travelers would report improvements in Statement 2, scope 3, category 6. Since the SAF does not physically enter the airline’s planes, the benefit is reportable only in everyone’s Statement 2 reports. If the airline can prove physical delivery of SAF onto its airplanes, then the benefits are shifted into everyone’s Statement 1 reports.
- A technology company funding a third-party carbon capture and storage project that receives verified reduction credits would report them in Statement 3, because the CCS project is outside of the technology company’s value chain and the technology company is not buying any goods or services from the CCS project. The third party that operates the CCS project would report lower scope 1 emissions in Statement 1 than they did pre-CCS, since the project impacts their direct emissions.
- A company buying CDR credits from CDR projects outside of their own value chain would report the removals in Statement 3, directly alongside the company’s Statement 1 and 2 emissions. This differs from the previous example because the company is not funding a project; it is buying a service - a CDR credit.
The practical effect will be significant. When clients ask whether a given investment "counts" under the GHG Protocol, the answer will shift from "probably not" to "yes, and here is which statement it belongs in."
What Does This Mean for Hard-to-Abate Sectors?
For sectors like cement, steel, chemicals, shipping, and aviation—where full decarbonization will be extremely challenging—the AMI proposal’s framework offers something that has not previously existed: a multi-faceted reporting strategy.
Companies in these sectors will be able to combine Statement 2 (EAC-based carbon intensity swaps for purchased goods) with Statement 3 (financed reduction credits) to demonstrate near-term progress, while long-term abatement technology matures. A cement buyer, for example, would procure low-carbon cement EACs under a book-and-claim arrangement and report the emissions benefit in Statement 2, while simultaneously funding a CCS project and reporting the resulting reduction credits in Statement 3.
For data centers and large power consumers, the framework adds a new layer to existing scope 2 electricity strategies: the ability to report the embodied carbon benefits of low-carbon materials used in construction and infrastructure, via Statement 2. Lower-carbon natural gas for power procured with EACs would also now be reportable in Statement 2.
For financial institutions and asset managers, the new statements create a richer disclosure environment for both internal reporting and structuring sustainability-linked financial products tied to Statement 2 and 3 performance.
How to Prepare Now
A full draft standard is expected in 2027/2028. Between now and then, the GHG Protocol will define the eligibility and quality guardrails that determine what activities qualify for Statements 2 and 3. Those criteria will matter enormously: they will shape which CDR credits, EAC programs, and financed reduction projects meet the bar for official reporting recognition.
Companies should not wait for final rules to begin preparing. Here are the most important steps to take now:
- Review existing portfolios against the emerging quality criteria for Statements 2 and 3. Not every credit or EAC program will qualify, and identifying the gaps early creates time to act.
- Map current decarbonization investments to the four statements. This exercise alone will reveal reporting opportunities and gaps that are not visible under the current single-inventory framework.
Frequently Asked Questions
What is the AMI proposal, and how does it work?
The GHG Protocol’s Actions and Market Instruments (AMI) proposal would allow organizations to report: their emissions (statement 1); their market-based emissions across all scopes (statement 2); GHG emissions reductions, avoidance, and removals resulting from their actions (statement 3); and other relevant metrics (statement 4).
How does AMI compare to the TCAT and/or AIM framework?
The AMI proposal is very similar to the Task Force for Corporate Action Transparency (TCAT) Mitigation Action Accounting and Reporting Guidance and the Advanced and Indirect Mitigation (AIM) Standard & Guidance. The AMI standard is not finalized, but many concepts from TCAT and AIM (including sector association tests) could be included in the final standard.
Can any climate action really count for the AMI proposal?
As of September 2026, the AMI standard is not finalized. However, if the final standard adopts the proposed structure, then any verified, high-quality climate action is reportable. Look for guidance from the GHG Protocol to determine verification and quality requirements.
Shifting Playbook for Corporate Power Procurement
Key Takeaways
- The Greenhouse Gas (GHG) Protocol’s proposed scope 2 revisions would shift many large power buyers from annual renewable energy certificate (REC) accounting to 24/7 hourly matching and reveal a larger emissions gap than most inventories currently report.
- Of all the US grid regions modeled, the emissions gap between annual and 24/7 hourly matching is widest in PJM Interconnection (PJM) and the Electric Reliability Council of Texas (ERCOT), the markets where data center load is growing fastest.
- Relae's modeling quantifies the shift from annual to 24/7 hourly matching: serving a 4-gigawatt (GW) data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM, a roughly 800-megawatt premium in PJM that translates directly into cost and siting strategy.
- Closing that gap requires investments in clean, firm generation technologies, like natural gas with carbon capture and storage (CCS), battery storage, and geothermal. The optimal mix varies by market and load profile, which means modeling current and future emissions positions under 24/7 accounting to understand the best procurement options for a specific portfolio.
Annual REC Accounting No Longer Holds at Data Center Scale
For years, large corporate energy buyers have relied on a straightforward approach: purchase renewable energy certificates (RECs) or sign virtual power purchase agreements (VPPAs) to offset market-based scope 2 emissions. Under the current GHG Protocol guidance, these instruments allow companies to claim low or zero emissions regardless of when or where clean energy is actually generated. When corporate clean energy demand was modest, this fueled new renewable project development while aggregate grid emissions were trending down.
That approach worked, until now. Energy demand from data centers and hyperscalers is surging. The Federal Energy Regulatory Commission (FERC) reported more than 50 GW of data center capacity operating in the US at the end of 2025, much of it concentrated in regions where local clean generation cannot keep pace. When corporate clean energy demand was modest, the gap between contractual claims and physical generation was small enough that few questioned this argument. At hyperscaler levels, with load concentrated in a handful of grids, that gap is becoming too large to ignore.
From a climate perspective, well-designed renewable procurement has created real impact by channeling corporate capital into new clean generation, and reducing CO2 emissions anywhere to benefit the climate everywhere. From a grid perspective, power consumption and generation must balance in real time, and the flow of electricity is constrained by the physics of the transmission system. Some regulators, investors, and standard-setters argue that corporate clean energy claims should be grounded in this second, engineering perspective rather than the first. The GHG Protocol's proposed revisions reflect that view, and would force buyers to defend their claims against it.
Relae’s modeling of this 24/7 framework in PJM and ERCOT helps quantify its costs and emissions implications in the markets where the stakes are highest.
What Does 24/7 Hourly Matching Mean for Scope 2 Accounting?
The biggest proposed change to the GHG Protocol’s current Scope 2 Guidance is the move from annual power reporting and matching to a 24/7 approach. Instead of calculating emissions with an annual emissions factor (EF) based on their independent system operator (ISO) or eGRID region for each megawatt-hour (MWh) consumed, companies would need to use hourly-specific EFs.
Companies would still be able to retire RECs to reduce their market-based emissions. However, companies would need to show that these RECs came from clean energy that was generated on the same grid, in the same hour as their facilities consumed power. This makes annual, location-agnostic REC retirement, currently the dominant practice, insufficient for 24/7 market-based accounting.
Both the time restriction (hourly matching) and the location restriction (generation on the same grid as consumption) will make it more difficult for companies to retire RECs. For example, because today's methodology is location-agnostic, a New York-based company can retire RECs from a Texas wind farm (purchased unbundled or via a VPPA) to reduce its reported market-based scope 2 value. This has allowed renewable development to follow the best resource sites rather than the load. Similarly, the time of day that the wind farm generates energy is irrelevant, as long as it is approximately in the same calendar year.
Under the proposed revisions, retiring these RECs would no longer be acceptable for the New York company, since they would fail both location- and hourly-matching requirements. As a result, companies with large REC portfolios today may no longer be able to retire them in order to reduce their market-based scope 2 emissions, if the proposed revisions take effect. These companies may face significant unmatched consumption under 24/7 accounting, especially during evening peaks or grid stress events when fossil-based generation fills the gap.
Annual Matching vs 24/7 Hourly Matching
The figure below illustrates the gap between what a representative large buyer reports under the current annual location- and market-based methodologies, versus what an hourly 24/7 analysis reveals.
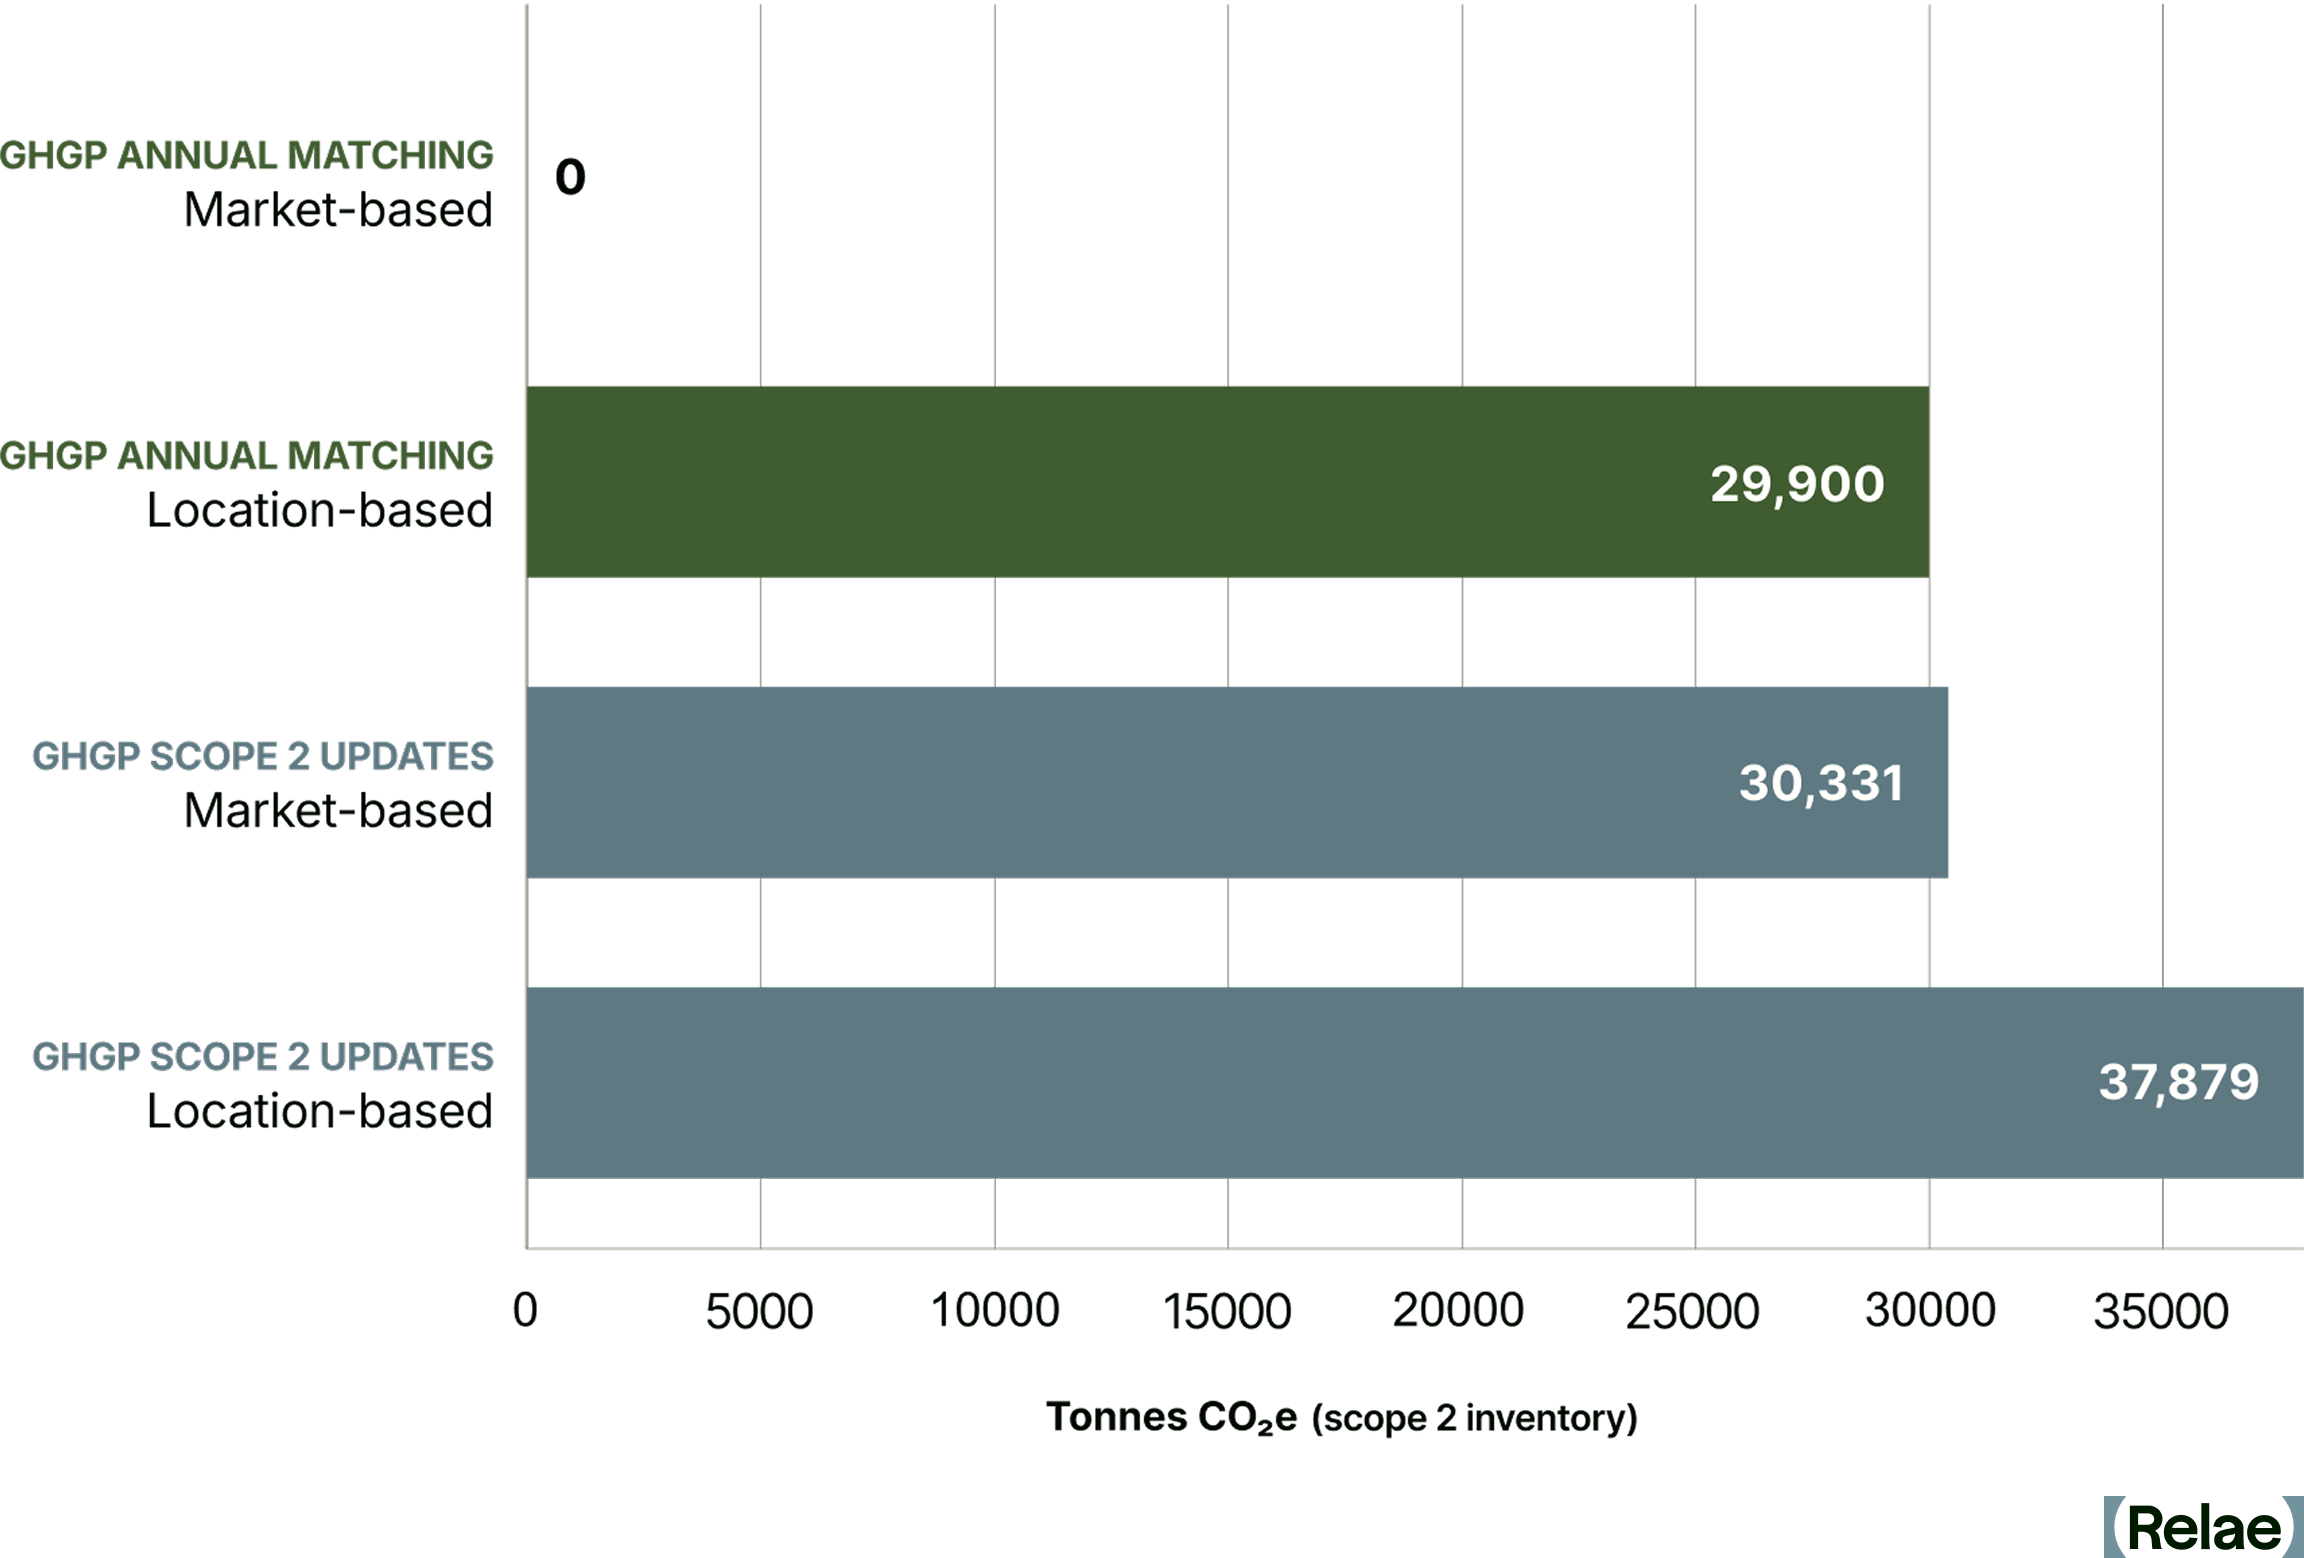
Understanding this emissions gap is the essential first step for buyers to make informed decisions about which instruments to retain, which contracts to renegotiate, and where new investment will matter most. If the proposed scope 2 revisions are enacted, companies procuring clean energy will be disincentivized from buying RECs sourced from variable renewables in distant locations, and instead will find it more favorable to invest in same-grid clean, firm generation, such as geothermal, nuclear, and renewables plus storage. RECs from these projects would qualify to be retired against market-based scope 2 emissions under the proposed revisions, where today's distant-wind or off-peak-solar RECs would not.
Where Pressure Is the Highest: ERCOT and PJM
Two markets stand out for projected hyperscaler load growth: PJM, which covers the extended mid-Atlantic region, and ERCOT in Texas. Both are on track to absorb massive increases in data center demand over the next decade, and both expose the limits of annual REC accounting in ways that will be hard to ignore under the new proposed framework.
PJM: 60% Fossil Generation Means High Marginal Emissions
PJM is one of the largest and most complex wholesale electricity markets in the world. Its generation mix still includes 60% coal and natural gas, which means hourly emissions intensity remains high, particularly during evening peaks and grid stress events when fossil generation dominates the dispatch stack.
Buyers relying solely on annual REC retirement may show low market-based scope 2 emissions today, but a 24/7 analysis tells a different story. For PJM-based buyers, this means hourly matching gaps will be largest during evening and overnight hours, when nuclear and storage become disproportionately valuable relative to additional solar.
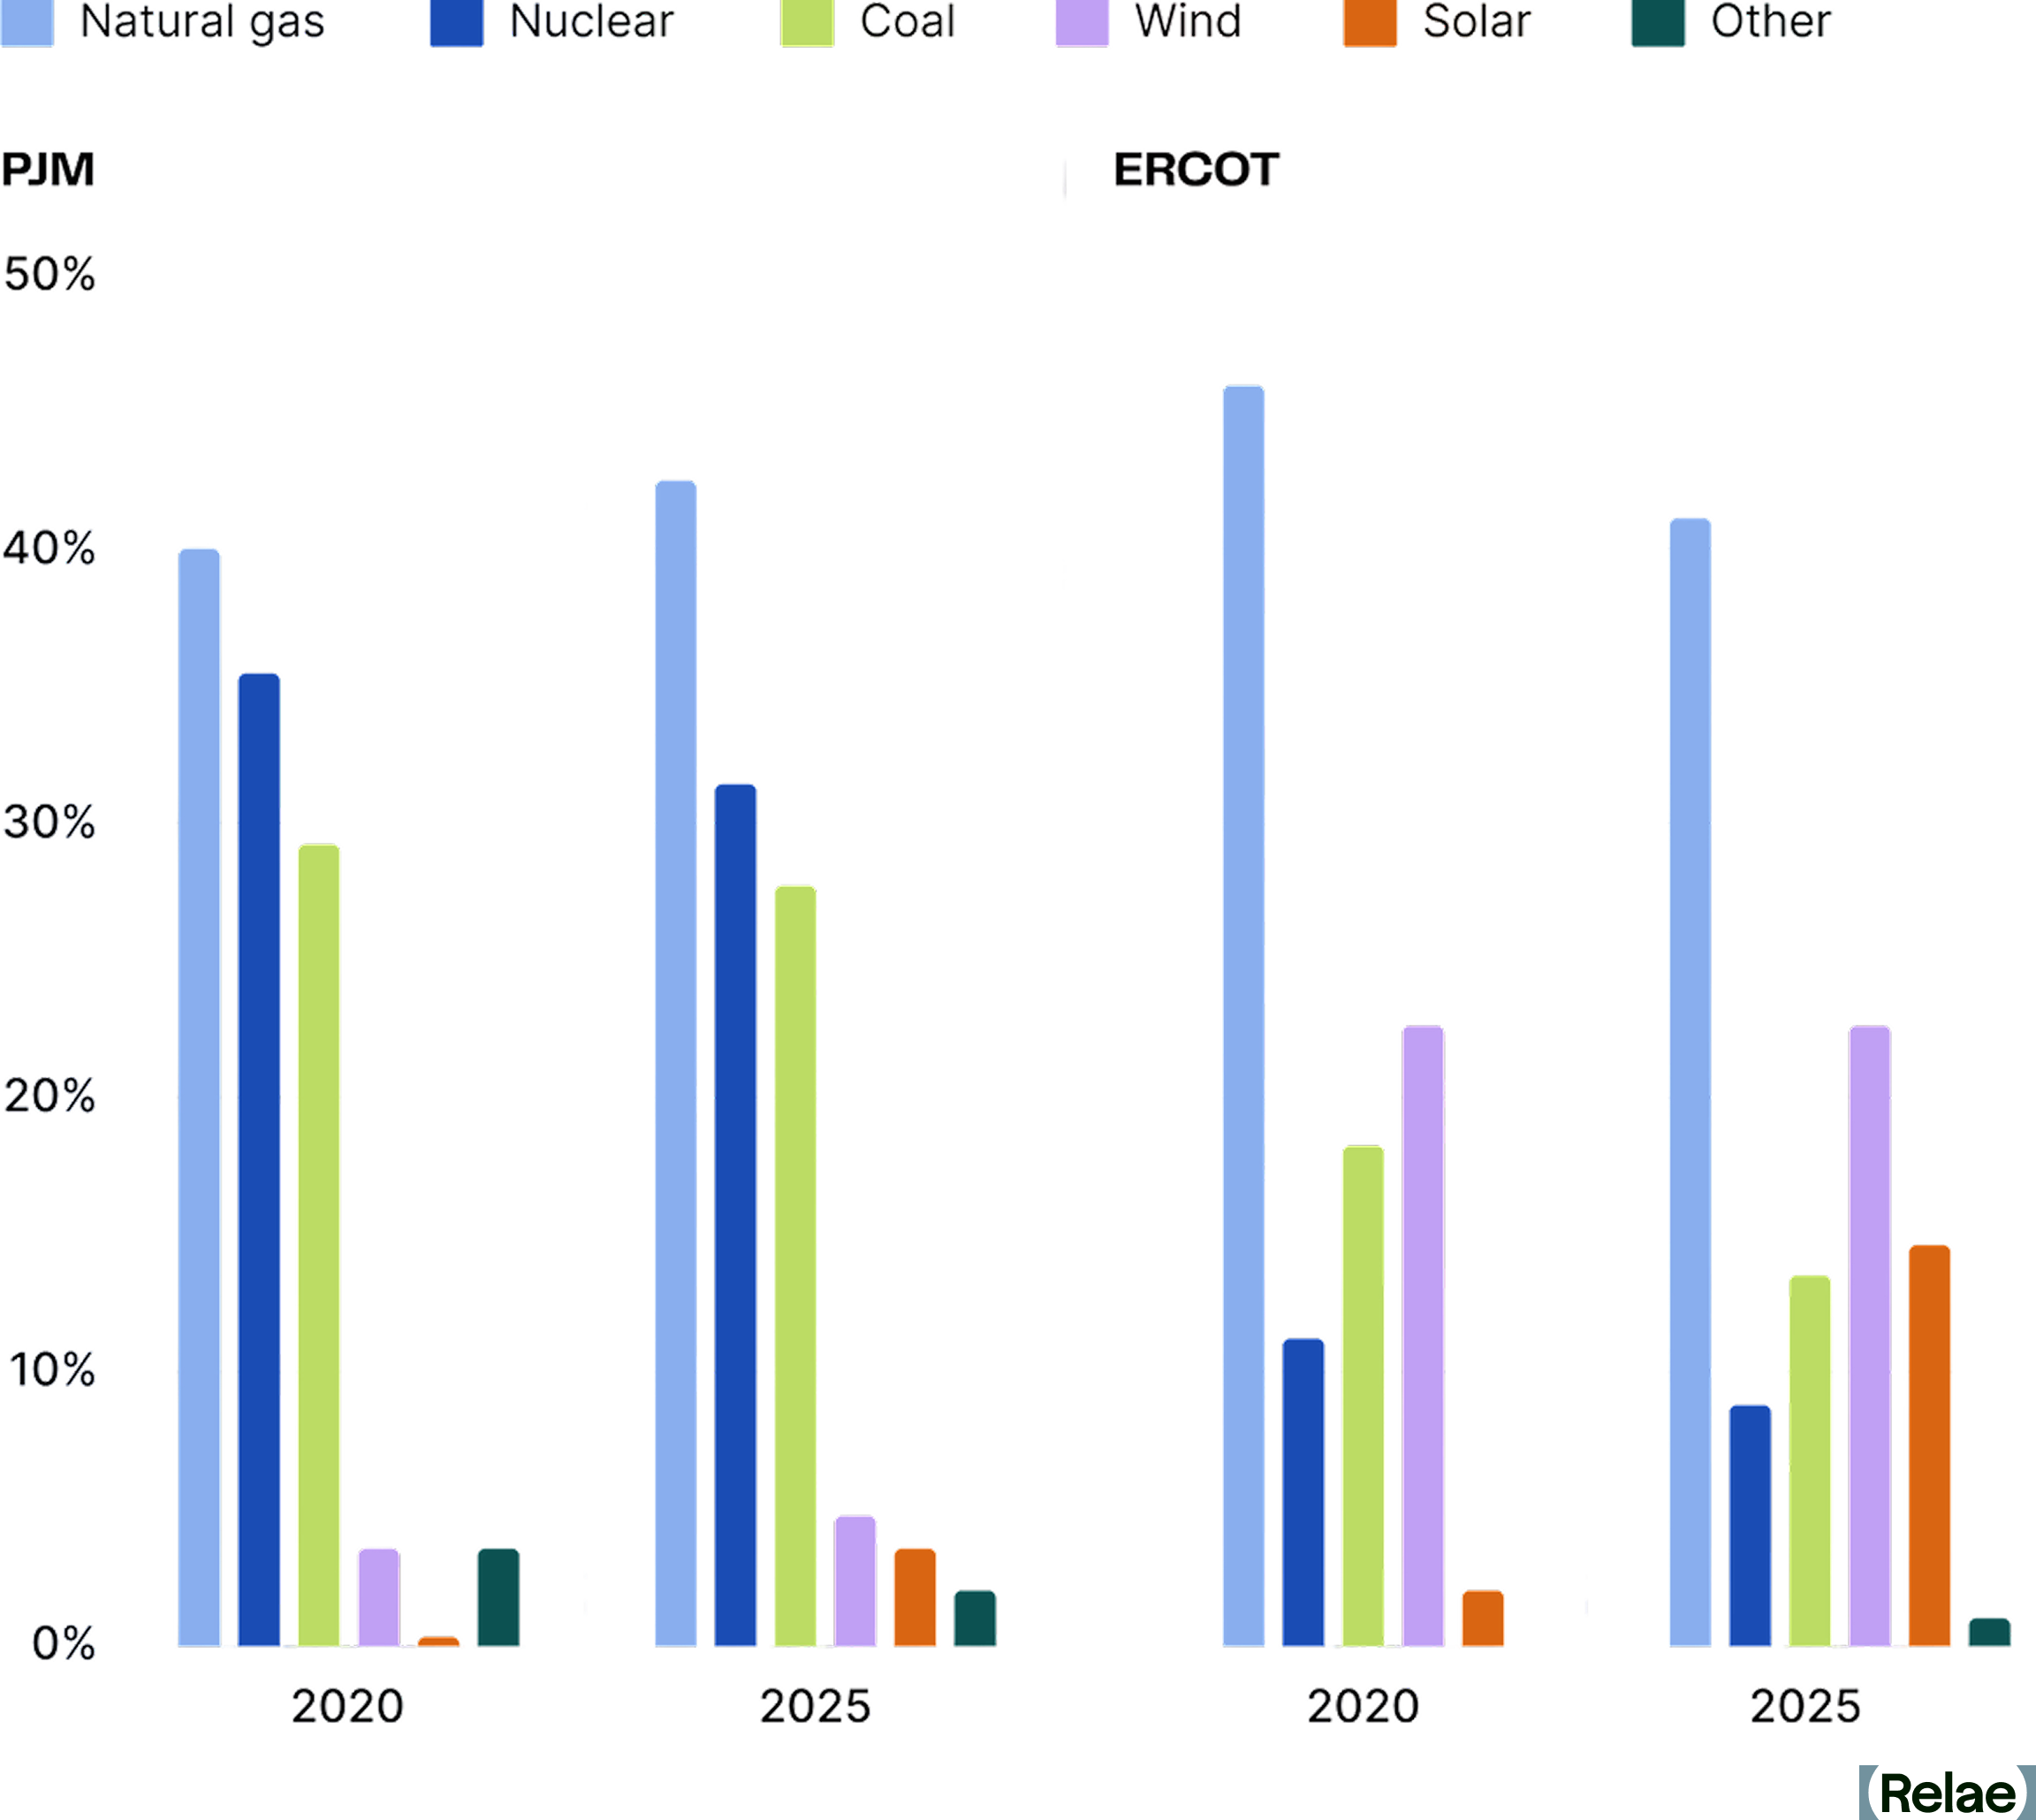
ERCOT: Solar and Wind Don’t Peak When Demand Does
Texas has abundant wind and solar, with solar generation growing nearly 7x since 2020, but those resources don’t always run when demand peaks. While fossil-based generation has declined since 2020, it still comprises more than half of ERCOT’s generation. Solar dominates midday, wind peaks in the evening, and natural gas fills the gaps, especially during high-demand evenings or extreme weather events.
Buyers with large ERCOT footprints may find that VPPA portfolios, which generate most of their clean energy in off-peak hours, already satisfy the proposed location-based test but fail on hourly matching. Battery storage and demand flexibility could help bridge the gap.
Figure 3 below quantifies that gap in both markets by showcasing the carbon-free energy (CFE) score in ERCOT and PJM, as well as the additional capacity required for a 4 GW load to achieve a 100% CFE target. The CFE score is the share of grid-supplied electricity in a given hour that comes from carbon-free sources, and is the metric the proposed scope 2 revisions would use to evaluate hourly matching. A 100% CFE target means electricity consumption is matched to carbon-free generation in every hour of the year.
In the left panel, a representation1 of each market's 2030 hours are sorted by grid (CFE) score, from the dirtiest hour on the left to the cleanest on the right. Neither grid approaches 100% carbon-free on its own, and the shaded areas represent the unmatched hours a buyer claiming 100% clean energy through annual instruments would actually carry under 24/7 accounting. The gap is the maximum unmatched hours a buyer might be exposed to, as some RECs procured through annual matching may qualify under the new rules, if satisfying the locational and hourly requirements.
The right panel translates that gap into action. The additional co-located clean generation and storage required to serve a representative 4 GW load (roughly 5% of the forecast 2030 C&I load in ERCOT and 4% in PJM) at a 100% hourly CFE target, on top of what the underlying grid already provides.
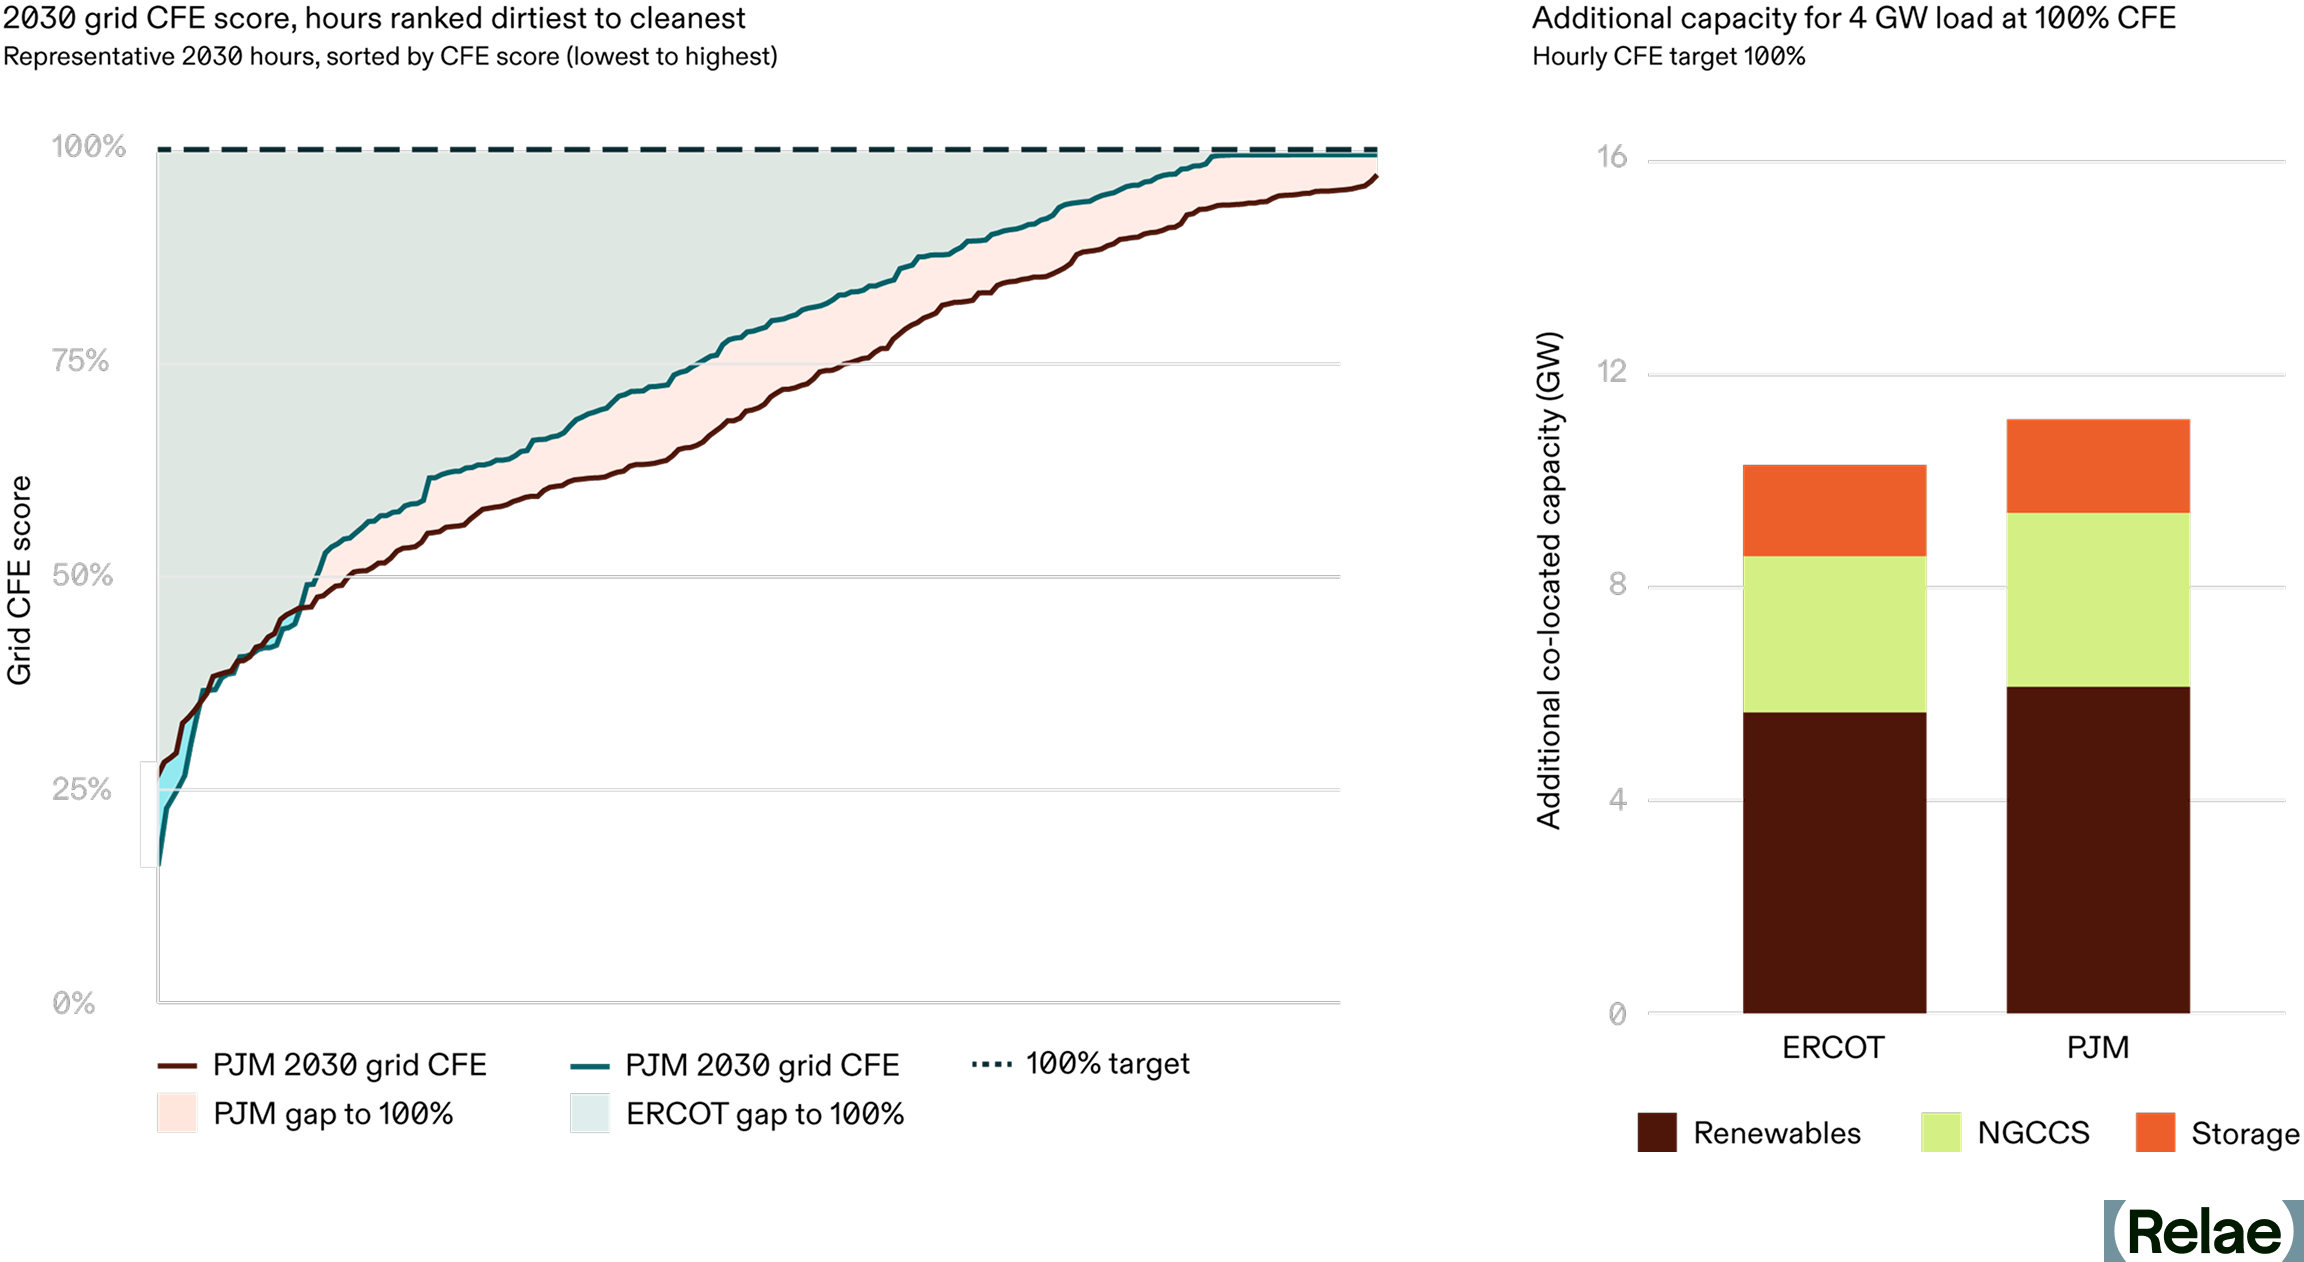
A few patterns are worth highlighting. First, the left panel confirms that PJM’s grid will still spend materially more hours below 100% carbon-free than ERCOT’s in 2030, a direct consequence of the coal- and gas-heavy generation mix described above. Notably, ERCOT's curve reaches 100% in a meaningful share of hours (windows when the grid is running entirely on carbon-free resources), while PJM's never does, meaning some fossil generation is dispatched in every hour.
Second, the ISO a buyer operates in drives a meaningful difference in build-out: hitting 100% hourly CFE for a 4 GW load takes 9.6 GW of additional capacity in ERCOT and closer to 10.5 GW in PJM. This indicates the advantage of achieving hourly and locational matching in already clean grids, which may influence a buyer choosing where to site new workloads.
Renewables have the largest share of the additional capacity in both markets (5-6 GW), paired with significant long-duration energy storage (~2 GW), while natural gas with CCS provides meaningful clean, firm capacity (~3 GW). ERCOT’s storage share of capacity is slightly larger, reflecting the midday-solar/evening-load mismatch, while PJM leans a bit more on natural gas with CCS, where clean, firm generation does more of the heavy lifting due to lower wind speeds and solar irradiance than Texas.
The right panel also illustrates why clean, firm technologies (natural gas with CCS, advanced nuclear, and enhanced geothermal) are likely to be included alongside renewables and batteries in any serious 24/7 portfolio. With only renewables and batteries, hitting the same target requires about double the total generation and storage capacity. In both markets, targets that look achievable today on an annual REC basis will require materially more capital and a different mix of resources, under 24/7 accounting.
Top Questions Large Power Buyers Need to Model Before the Rules Change
The GHG Protocol revisions are not finalized, and the timing of any mandate remains uncertain, which is exactly why modeling cannot wait.
A useful self-test for any large power buyer is: can your team answer the following today with defensible numbers?
- What is your hourly CFE score across your largest load centers, and how far does it sit from your reported market-based emissions?
- Which of your existing VPPAs and REC contracts hold value under 24/7 accounting, and which become effectively stranded?
- What mix of resources delivers the incremental clean, firm capacity that closes your gap in PJM, ERCOT, or wherever your load is concentrated at the lowest cost?
- If your next gigawatt of load were sited in a different ISO, how would your emissions position change?
Clean firm projects do not appear off the shelf. Advanced nuclear, enhanced geothermal, and natural gas with CCS all carry multi-year development timelines, and corporate offtake agreements are often what get these projects financed in the first place. Buyers who engage now help shape the project pipeline that will be available in their target markets in 2030, and can lock in offtake terms before competition for the most valuable sites tightens. Buyers who wait until the methodology is final will be working with shorter lead times, fewer development partners, and less leverage to specify projects that fit their load profiles and hourly matching needs.
Frequently Asked Questions
What is 24/7 hourly matching, and how does it differ from today's REC accounting?
Today's scope 2 accounting lets companies retire renewable energy certificates (RECs) from any grid, at any time of year, to offset their emissions. The GHG Protocol's proposed 24/7 hourly matching would require RECs to come from clean generation on the same grid, in the same hour a facility consumes power, making most of today's location-agnostic RECs ineligible for market-based accounting.
Why are PJM and ERCOT under the most pressure from this shift?
Both markets are absorbing the fastest-growing data center load in the country, and both still lean on fossil generation to meet demand outside peak renewable hours. PJM's generation mix is 60% coal and gas, while ERCOT's solar and wind often don't peak when demand does, so buyers in these markets face the largest gaps between their annual REC claims and their actual hourly carbon-free energy score.
How much additional clean capacity does it take to close the gap?
Relae's modeling finds that serving a 4 GW data center load at 100% hourly carbon-free energy requires 9.6 GW of additional clean capacity in ERCOT and 10.5 GW in PJM. That capacity mix leans on renewables and long-duration storage in both markets, with natural gas with CCS playing a larger role in PJM, where wind and solar resources are weaker.
What should power buyers do before the GHG Protocol revisions are finalized?
Start modeling now. Buyers should know their hourly carbon-free energy score, understand which existing VPPAs and REC contracts hold value under 24/7 accounting, and identify the lowest-cost mix of clean, firm resources that closes their gap. Clean firm projects like advanced nuclear, enhanced geothermal, and natural gas with CCS take years to develop, so buyers who engage early have more influence over the project pipeline and better offtake terms.
Modeling the 24/7 Emissions Gap with Relae
For large power buyers assessing what the proposed GHG Protocol revisions mean for their power procurement portfolio, Relae's Advanced Power Emissions Analysis solution models the gap between current market-based reporting and what 24/7 accounting would reveal—by market, load profile, and technology stack.